
 Food Waste Management Market | 2026-2036
Food Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Food Waste Management Market Intelligence
Food manufacturers and municipal governments is reorganizing procurement priorities away from landfill-dependent disposal toward circular recovery models. Veolia Environment leverages its integrated treatment infrastructure across European urban centers. Waste Management, Inc. anchors North American collection networks with dense route density. Republic Services, Inc. specializes in landfill-gas-to-energy co-location, competing on operational efficiency rather than technology premium.
Food waste management encompasses the systematic collection, transport, treatment, and valorization of organic discards from commercial, industrial, and residential sources, typically processed through composting, anaerobic digestion, or thermal treatment to recover energy, nutrients, or soil amendments. The primary industrial purpose centers on reducing methane emissions from decomposing organics while generating biogas, compost, or other secondary products. Collection services dominate revenue volume due to recurring route contracts and tipping-fee structures, though anaerobic digestion commands margin premiums through renewable natural gas offtake agreements. Composting technology remains mature and cost-competitive for lower-moisture feedstocks, while fermentation pathways gain share in regions with established biorefinery infrastructure.
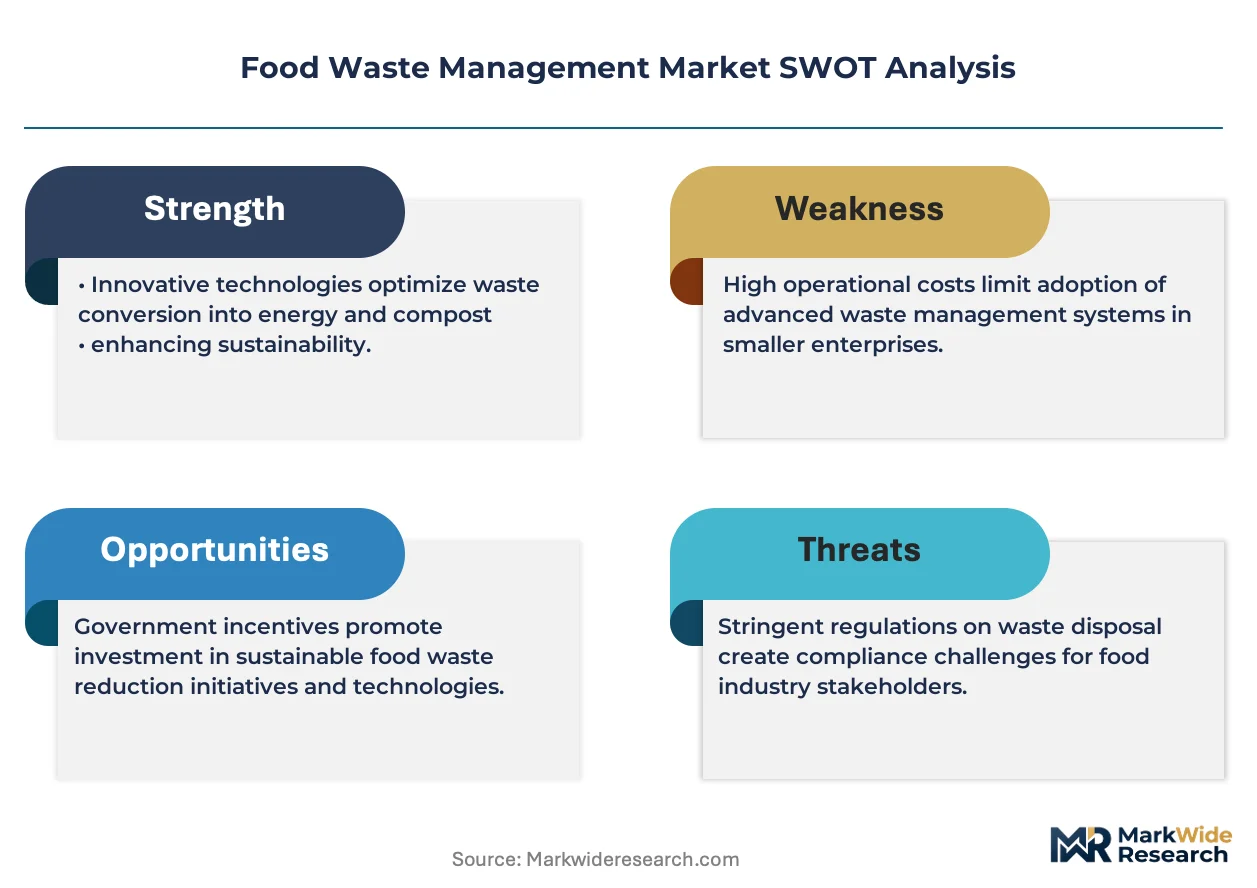
The EPA landfill methane regulations and EU Green Deal organic recovery targets shape compliance-driven investment in collection infrastructure and treatment capacity. California's SB 1383 and France's anti-waste law AGEC extend producer responsibility frameworks to commercial generators, tightening disposal alternatives. Stakeholders must monitor evolving state-level organic waste bans and biogas interconnection standards to align capital deployment with policy-enforced demand shifts.
Market Dynamics
Landfill diversion mandates are compressing disposal economics while anaerobic digestion infrastructure attracts capital seeking renewable energy credit arbitrage. Municipal procurement now prioritizes collection-to-energy integration over standalone hauling contracts.
Growth Catalysts
- EU Green Deal organic recovery targets:Member states must achieve 65% municipal waste recycling by 2035, forcing cities to expand separate organic collection routes and build local composting capacity.
- California SB 1383:This state mandate requires 75% organic waste diversion by 2025 and establishes procurement quotas for recovered organic products, creating guaranteed offtake for compost and biogas.
- Anaerobic digestion with RNG upgrading:Food manufacturers are installing on-site digesters to capture biogas, clean it to pipeline-quality renewable natural gas, and monetize carbon credits through voluntary markets.
Market Restraints
- High capex intensity for digester construction:Steel, specialized membranes, and gas upgrading equipment require substantial upfront investment, limiting deployment to large generators or municipal consortia.
- Feedstock contamination:Plastic bags, cutlery, and packaging fragments disrupt digester biology and increase preprocessing costs, degrading project returns for facilities accepting mixed commercial waste.
- Limited interconnection standards:Biogas injection into natural gas pipelines faces varying technical requirements across utility territories, creating permitting delays and revenue recognition uncertainty.
Strategic Opportunities
- France AGEC anti-waste law:Extended producer responsibility for commercial food waste creates service contracts for industrial caterers and large retailers seeking compliance outsourcing.
- Black soldier fly larvae processing:This biotechnology converts food scraps to insect protein for animal feed, opening valorization pathways for waste streams too contaminated for anaerobic digestion.
- Smart bin sensor networks:IoT-enabled fill-level monitoring optimizes collection routing, reducing diesel consumption and enabling dynamic pricing models for generator pay-by-weight contracts.
Industry Challenges
- Skilled technician scarcity:Anaerobic digester operation requires microbiology expertise and mechanical troubleshooting that vocational programs have not scaled to match facility construction.
- Contamination detection at scale:Automated sorting systems struggle to identify and remove non-organic materials from high-speed commercial waste streams without manual intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Waste Management Market |
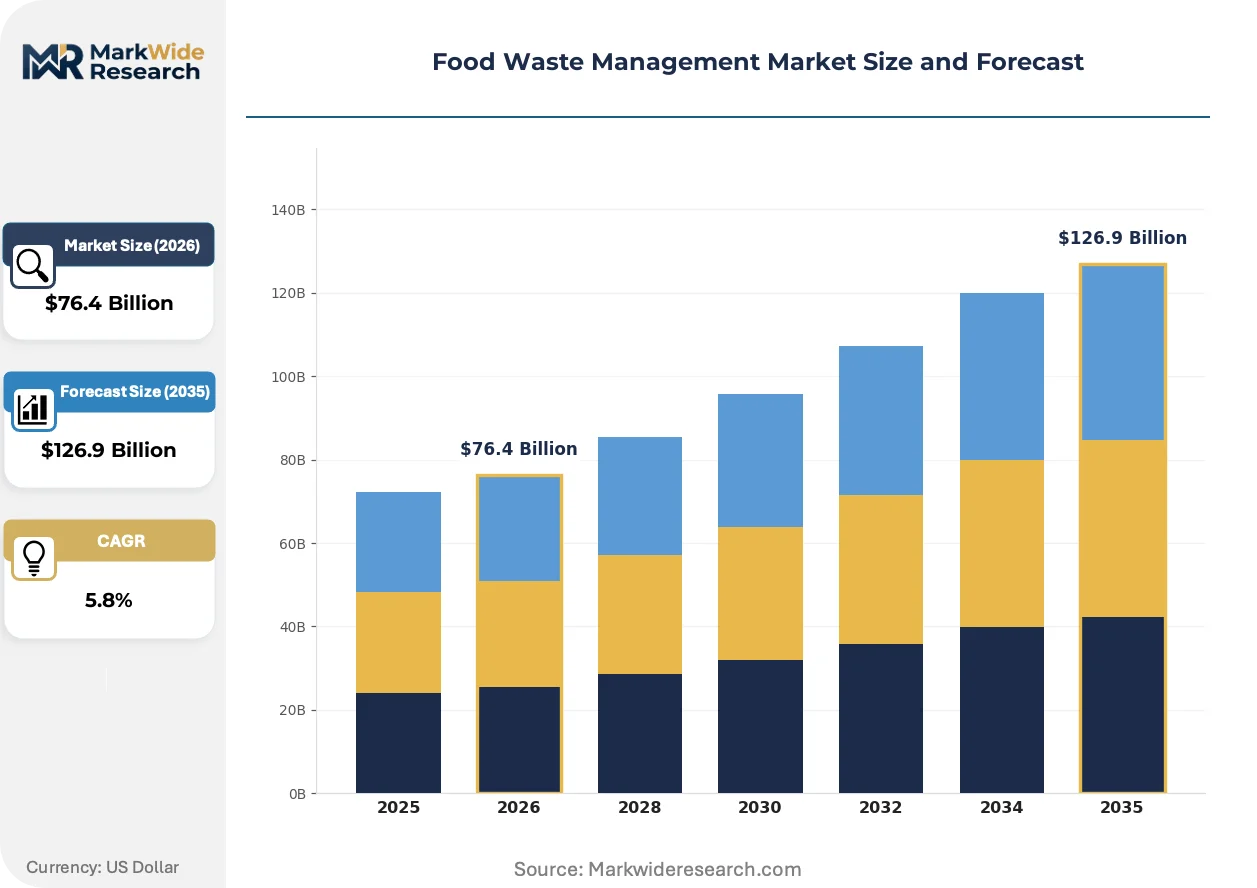
| Market Size in 2026 | $76.4 Billion |
| Market Size in 2035 | $126.9 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Recycling, Anaerobic Digestion End User: Restaurants, Supermarkets, Households, Food Manufacturers Technology: Composting, Incineration, Fermentation, Biodegradation Use Case: Composting Initiatives, Waste Reduction Programs, Nutrient Recovery, Policy Compliance |
| Companies Covered | Republic Services, Inc., Andritz AG, Veolia Environment, Stericycle, Inc., Covanta Holding Corporation, Waste Management, Inc., Clean Harbors, Inc., Waste Connections, Inc., SUEZ Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Waste Management Market Strategic Shifts & Innovations
Wet anaerobic digestion and dry fermentation systems are diverging into distinct competitive arenas based on feedstock moisture content and scale economics. Equipment suppliers are specializing rather than pursuing universal platform strategies.
Dry anaerobic digestion technology is bifurcating the market for high-solids organic waste. Food manufacturers with packaged goods rejects and bakery waste are adopting garage-style batch digesters that operate without wastewater discharge permits. This technology is compressing the addressable market for traditional wet digestion systems in the 5-50 ton per day range, forcing incumbent engineering firms to abandon mid-scale projects or acquire dry fermentation intellectual property.
EPA landfill methane regulations are tightening surface emission monitoring requirements and accelerating closure timelines for uncontrolled dumps. Operators must install gas collection systems or face penalties, diverting capital toward alternative treatment infrastructure. California and New York facilities face the most stringent compliance schedules, with many counties now prohibiting organic waste disposal entirely.
Retail grocery chains are consolidating waste service contracts from regional haulers to national providers offering guaranteed landfill diversion reporting. Kroger and Albertsons have shifted procurement toward integrated collection-to-compost agreements that deliver verified tonnage data for ESG disclosures. This concentration is visible across the US Midwest and Southeast, where single-source contracts now cover hundreds of store locations previously served by fragmented local operators.
Food Waste Management Market Segmentation
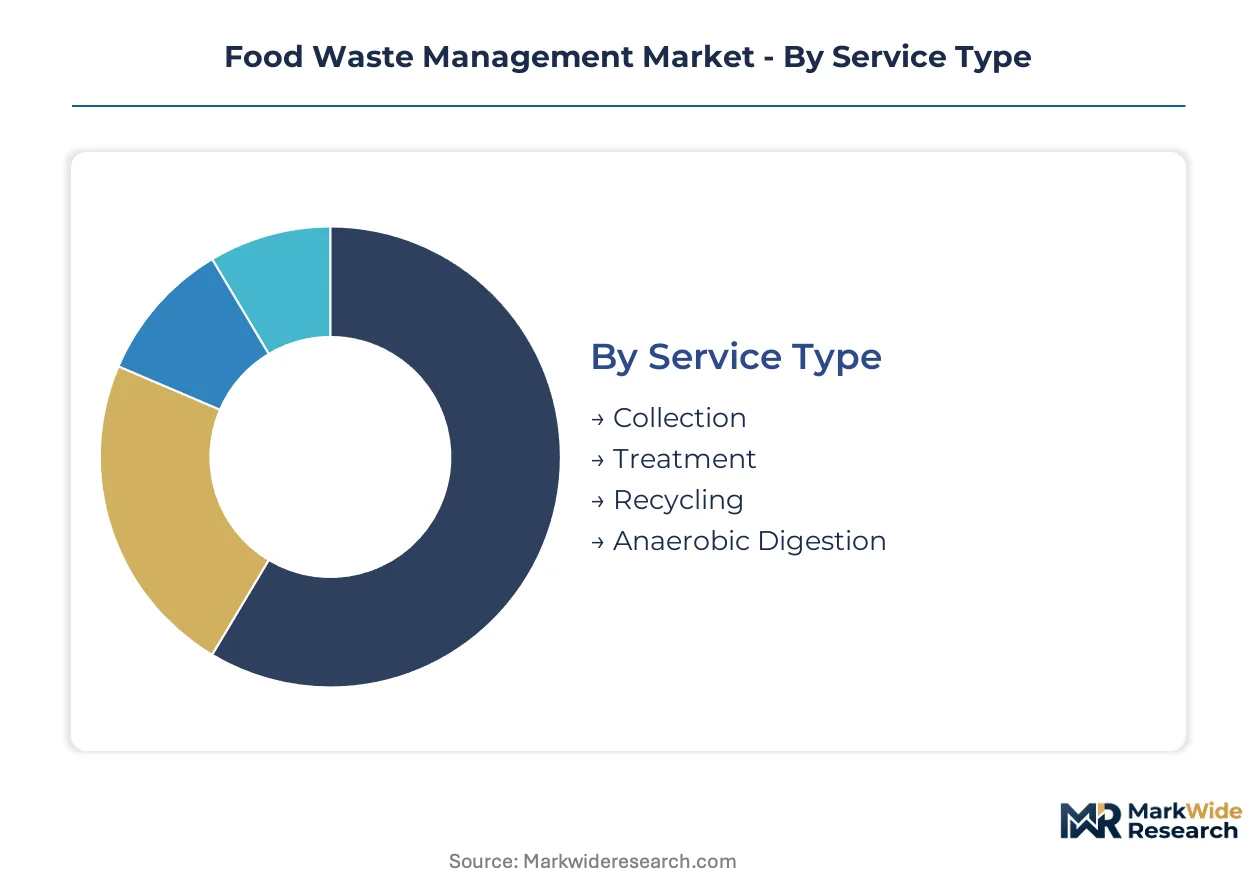
Food waste management procurement flows through distinct service channels shaped by generator scale and regulatory pressure. Municipal contracts favor collection-heavy integrated providers, while industrial generators self-source treatment capacity to capture renewable energy credits.
Service Type:
Collection routes anchor recurring revenue through tipping-fee structures, while treatment services command project-based margins tied to technology performance.
- Collection:Dense urban route networks generate predictable cash flows through municipal contracts with per-ton tipping fees. Demand concentrates in United States metropolitan areas where SB 1383 mandates separate organic waste pickup, forcing cities to expand fleet capacity and frequency.
- Treatment:Centralized composting and digestion facilities process aggregated feedstock from multiple generators under long-term service agreements. Germany's mechanical-biological treatment plants face capacity constraints as EU Green Deal targets accelerate organic diversion, pushing investment toward facility expansion.
- Recycling:Sorting and preprocessing operations recover packaging materials and contaminants from mixed commercial waste streams. France's AGEC anti-waste law creates service demand from large retailers seeking compliance outsourcing for packaging separation.
- Anaerobic Digestion:Biogas capture and upgrading to pipeline-quality renewable natural gas monetizes carbon credits through voluntary markets. California and New York project pipelines dominate deployment as landfill bans tighten and interconnection standards mature.
Collection dominates installed base. Anaerobic digestion is where expansion concentrates.
End User:
Generator scale determines service configuration, with large commercial accounts self-sourcing treatment and smaller generators relying on municipal collection infrastructure.
- Restaurants:High-frequency, low-volume waste streams with high moisture content favor collection-dependent service models. Dense urban clusters in United States and German cities drive route optimization investment for daily pickup schedules.
- Supermarkets:Mixed organic and packaging waste requiring preprocessing creates demand for integrated collection-sorting contracts. Kroger and Albertsons procurement consolidation across United States Midwest and Southeast favors national providers with verified diversion reporting.
- Households:Curbside organic bins and drop-off programs generate volume through municipal subsidy. China's pilot city programs for kitchen waste separation in Shanghai and Beijing are expanding collection infrastructure.
- Food Manufacturers:Large-volume, consistent feedstock quality enables on-site digester installation with direct biogas offtake. Bakery and packaged goods rejects in United States and Germany are shifting toward dry fermentation systems to avoid wastewater discharge permits.
Food manufacturers command premium pricing for integrated solutions. Households represent the steepest expansion trajectory as municipal programs scale.
Technology:
Maturity curves diverge sharply, with composting and incineration at cost parity while fermentation and biodegradation pathways compete on valorization upside.
- Composting:Aerobic decomposition of organic matter to soil amendments operates at lowest unit cost for low-moisture feedstocks. United States and Germany maintain the largest installed base of windrow and in-vessel systems serving municipal contracts.
- Incineration:Thermal treatment with energy recovery faces permitting constraints but handles contaminated waste streams unsuitable for biological processing. Japan's waste-to-energy facilities integrate food waste into mixed municipal solid waste combustion.
- Fermentation:Bioconversion to ethanol or organic acids requires refined feedstock streams and proximity to biorefinery infrastructure. China's industrial biotechnology clusters are developing dedicated food waste fermentation capacity.
- Biodegradation:Black soldier fly larvae and other biological agents convert waste to insect protein for animal feed. France and Netherlands pilot facilities are scaling to handle contaminated streams excluded from anaerobic digestion.
Composting dominates installed base. Biodegradation is where expansion concentrates.
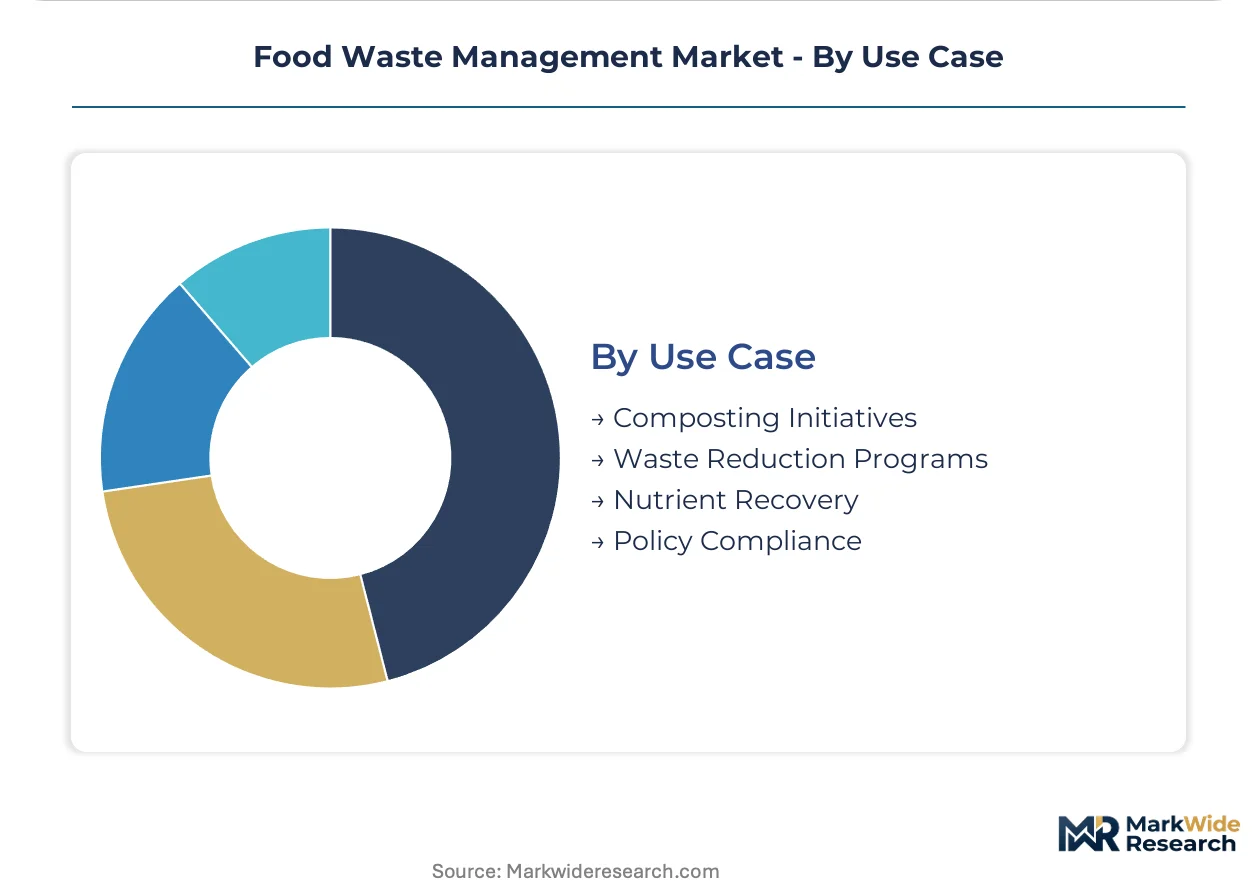
Use Case:
Procurement priorities shift from disposal cost minimization toward compliance verification and circular product recovery.
- Composting Initiatives:Soil amendment production for agricultural and landscaping applications creates local offtake markets. California's SB 1383 procurement quotas guarantee demand for municipal compost output.
- Waste Reduction Programs:Source reduction and donation coordination services for edible food rescue. France's AGEC law mandates commercial food waste audits, creating consulting and tracking service demand.
- Nutrient Recovery:Phosphorus and nitrogen extraction from digestate for fertilizer production. Germany's circular economy strategy targets nutrient recycling from organic waste streams.
- Policy Compliance:Verified diversion reporting and documentation for regulatory submissions and ESG disclosures. United States and EU mandatory reporting frameworks are standardizing data requirements across jurisdictions.
Policy compliance dominates installed base. Nutrient recovery is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports biogas upgrading equipment and dry fermentation systems to food manufacturers in France and the Netherlands. United States technology licensors supply anaerobic digestion process designs to Canadian municipal utilities expanding organic waste infrastructure.
United States
EPA landfill methane regulations and state-level organic waste bans drive infrastructure investment. California's SB 1383 mandates 75% organic diversion by 2025 with procurement quotas for recovered products. The Central Valley hosts expanding composting clusters serving agricultural offtake markets.
Germany
Mechanical-biological treatment plants face capacity constraints from EU Green Deal organic recovery targets. The country's national environmental regulator enforces strict biogas quality standards for grid injection. Bavaria's industrial biogas corridor concentrates dry fermentation adoption among bakery and packaged goods manufacturers.
France
AGEC anti-waste law extends producer responsibility to commercial food waste generators. The national environmental agency oversees compliance frameworks for industrial caterers and large retailers. The Paris metropolitan area contracts integrated collection-sorting services for supermarket chains seeking verified diversion reporting.
China
Shanghai and Beijing pilot city programs mandate household kitchen waste separation with expanding collection infrastructure. The Ministry of Ecology and Environment sets municipal organic waste diversion targets for tier-one cities. Yangtze River Delta biorefinery clusters develop dedicated food waste fermentation capacity for industrial biotechnology feedstocks.
Netherlands
Black soldier fly larvae processing facilities scale to handle contaminated streams excluded from anaerobic digestion. The national environmental regulator permits insect protein production for animal feed applications. The Randstad urban corridor deploys smart bin sensor networks optimizing collection routing for dense commercial waste generators.
Food Waste Management Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base splits between integrated waste conglomerates with collection route density and equipment-focused engineering firms licensing proprietary digester designs. Three archetypes dominate: municipal contract aggregators, on-site treatment specialists, and industrial biotechnology licensors. Consolidation concentrates in collection route acquisitions while technology partnerships proliferate in digester upgrading and RNG interconnection.
Among North American waste service providers, Waste Management, Inc., Republic Services, Inc., and Waste Connections, Inc. exemplify the municipal contract aggregator archetype through dense route networks and tipping-fee revenue structures. Veolia Environment represents European integrated infrastructure positioning across urban treatment centers. Andritz AG occupies the equipment licensing tier supplying dry and wet digestion systems to project developers.
| Leading Market Players |
|---|
| Republic Services, Inc. |
| Andritz AG |
| Veolia Environment |
| Stericycle, Inc. |
| Covanta Holding Corporation |
| Waste Management, Inc. |
| Clean Harbors, Inc. |
| Waste Connections, Inc. |
| SUEZ Group |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for renewable natural gas lock in feedstock supply visibility and price predictability for anaerobic digestion operators, binding California and New York project developers to fixed-price arrangements with utilities seeking carbon credit arbitrage.
Pricing Analysis
Current-generation wet anaerobic digestion systems command 15-25% price premiums over dry fermentation alternatives due to higher biogas yields and established RNG upgrading pathways. Wet digestion pricing stratifies across premium, standard, and economy tiers based on feedstock contamination tolerance and gas quality certification. Cost compression in standard-tier equipment is intensifying because Chinese engineering firms are exporting modular digester packages at reduced engineering margins. Food manufacturers with consistent bakery waste streams exhibit lowest price sensitivity, while municipal procurement officers in mid-sized United States cities remain most responsive to per-ton tipping fee differentials.
Supply Chain Analysis
Strategic stockpiling of specialized steel alloys and membrane materials characterizes digester construction procurement, with European project developers maintaining 6-9 month component buffers against supply volatility. Manufacturing concentration centers on Germany, China, and Denmark for biogas upgrading equipment and gas cleaning membranes. Raw material dependencies include high-grade stainless steel for digester vessels, specialized polymer membranes for CO2 separation, and platinum-group catalysts for hydrogen sulfide removal. Tariff exposure on Chinese steel imports threatens project cost structures for North American developers. Distribution runs through engineering-procurement-construction contractors with regional fabrication partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of anaerobic digester operators with microbiology expertise and mechanical troubleshooting capability constrains facility utilization rates and creates bottlenecks for project developers seeking to scale capacity.
For Market Incumbents: Compound route density advantages through acquisition of municipal collection contracts in United States states with pending organic waste bans, while investing in dry fermentation intellectual property to defend against garage-style batch digester substitutes displacing mid-scale wet systems. California's SB 1383 procurement quotas for recovered organic products represent the priority lever for locking in long-term offtake agreements. For New Entrants and Emerging Players: EPA landfill methane compliance certification fast-tracks market entry for operators offering verified diversion reporting to retail grocery chains consolidating procurement from regional haulers. White-space targets include black soldier fly larvae processing for contaminated waste streams excluded from anaerobic digestion, and smart bin sensor network deployment in dense United States urban clusters. A direct-to-generator pay-by-weight pricing model with IoT-enabled dynamic routing offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward equipment-focused engineering firms with proprietary dry fermentation designs, given the technology bifurcation compressing addressable markets for traditional wet digestion systems. Long-term viability rests on positioning for RNG interconnection standard maturation and carbon credit market deepening. The signal to watch is biogas pipeline injection permit approval velocity in New York and California utility territories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Waste Management anchors North American route density through municipal contract aggregation. |
| Technology Licensing for Dry Fermentation | Andritz AG supplies garage-style batch digesters to bakery manufacturers avoiding wastewater permits. |
| RNG Interconnection Partnership | Project developers secure pipeline injection agreements with California utilities for carbon credit monetization. |
| Smart Sensor Network Deployment | Netherlands operators optimize collection routing for dense commercial generators in the Randstad corridor. |
| Insect Protein Processing Scale-Up | France and Netherlands facilities handle contaminated streams excluded from anaerobic digestion pathways. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with municipal solid waste directors, anaerobic digester facility managers, RNG offtake contract negotiators, and food manufacturer sustainability officers. Secondary validation drew from EPA enforcement databases, EU Green Deal implementation reports, California SB 1383 compliance filings, and German biogas quality standard documentation. Bottom-up project pipeline tracking triangulated against top-down regulatory mandate modeling.
Across the analysis window, the forecasting framework models service type segmentation, technology maturity curves, and end-user scale economics alongside regional regulatory enforcement intensity. CAGRs derive from facility capacity buildout trajectories, RNG interconnection permit issuance rates, and municipal contract award velocity. Industry-specific inputs include feedstock contamination rates affecting digester uptime and carbon credit price volatility in voluntary markets.
Decision-makers should treat outputs as directional under assumptions of continued landfill diversion mandate enforcement and stable carbon credit demand; material deviation would warrant model refresh. Forecasts reflect base-case regulatory implementation timelines and commodity price assumptions. Revision becomes warranted when biogas interconnection standard fragmentation crosses thresholds that delay project revenue recognition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Medical Waste Management System Market