
 India Bio-Medical Waste Management Market | 2026-2036
India Bio-Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
India Bio-Medical Waste Management Market Insights
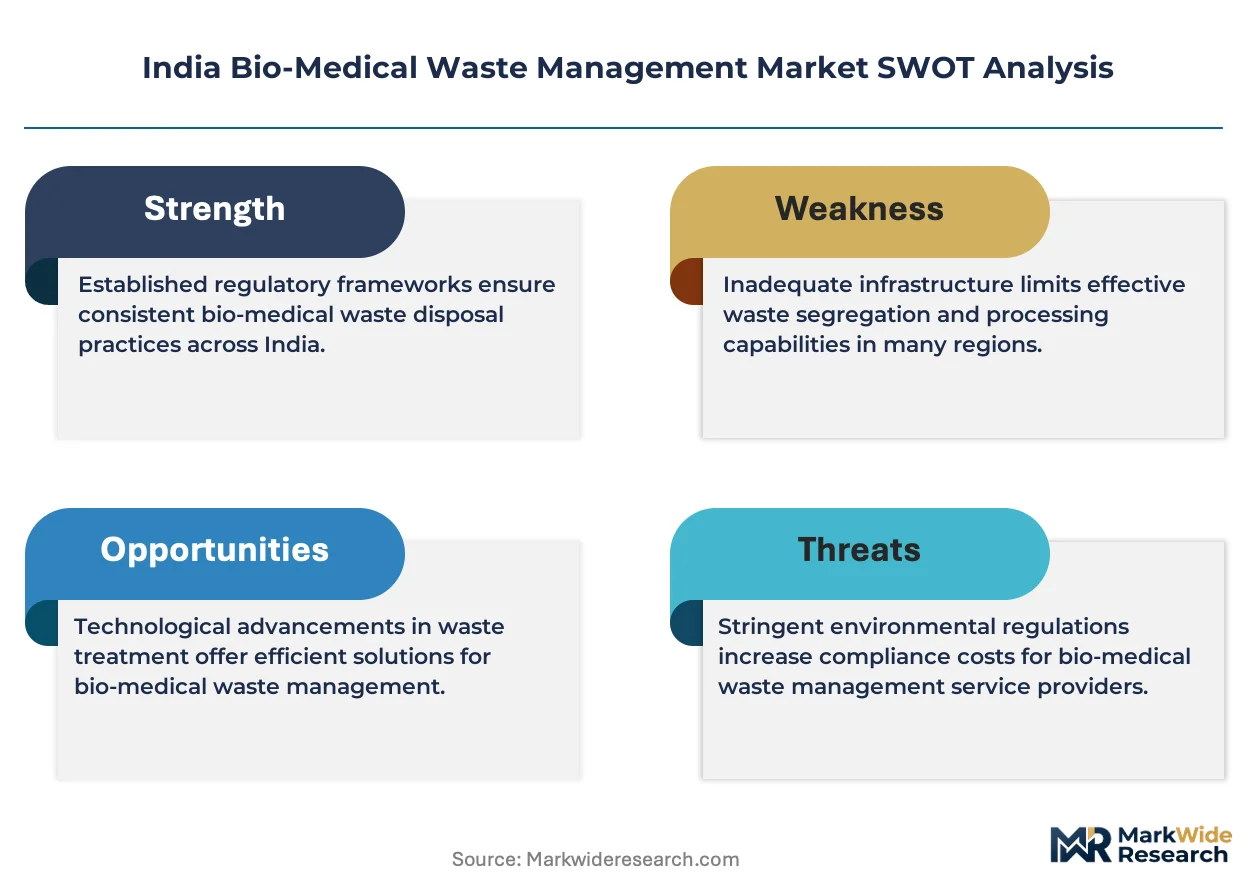
The Biomedical Waste Management Rules 2016 amendment is consolidating the cost-of-entry calculus for new operators across India. SMS Water Graca BMW Pvt. Ltd. leverages its western India plant network to sustain high utilization rates in Maharashtra and Gujarat. Veolia Environnement S.A. competes through technology leadership in automated segregation systems, while Biotic Waste Solution Pvt. Ltd. anchors its position in Delhi-NCR through municipal hospital contracts.
Bio-medical waste management encompasses the systematic collection, segregation, treatment, and final disposal of waste generated during diagnosis, treatment, or immunization of humans and animals, requiring autoclaving at 121°C for 60 minutes or incineration at 1100°C to achieve pathogen inactivation. Its primary purpose is preventing nosocomial infections, environmental contamination, and occupational exposure among healthcare workers. Sharps and containers dominate product-type revenue due to mandatory single-use mandates, while treatment services extract the deepest margin pools given capital intensity and licensing scarcity. Hospitals remain the anchor end-user segment, though diagnostic labs represent the fastest-growing demand source as point-of-care testing expands.
CPCB enforcement actions and State Pollution Control Board licensing protocols shape operational viability, with BIS standards for autoclave performance creating product-level compliance gates. The PLI scheme for medical device manufacturing indirectly amplifies waste generation volumes, tightening collection frequency requirements. Stakeholders must monitor emerging state-level mandates for real-time tracking of waste consignments from generator to disposal endpoint.
Market Dynamics
CPCB enforcement intensity is compressing operational margins for unlicensed collectors while accelerating consolidation toward centralized common biomedical waste treatment facilities in Maharashtra, Karnataka, and Gujarat.
Growth Catalysts
- Biomedical Waste Management Rules 2016 Amendment:Stricter segregation mandates at generator sites are expanding serviceable addressable market for licensed treatment operators across tier-I and tier-II hospital networks.
- Point-of-Care Testing Expansion:Diagnostic laboratories in western and southern India are multiplying waste generation nodes beyond traditional hospital settings, fragmenting collection logistics into higher-margin micro-routes.
- Autoclave Technology Upgrades:BIS performance standards for steam sterilization equipment are retiring thermal inefficiencies and opening replacement cycles for 121°C/60-minute compliant systems.
Market Restraints
- Diesel Price Volatility:Collection fleet operators absorb fuel cost swings that comprise 35-40% of per-kilometer logistics economics, compressing route profitability in low-density rural catchments.
- Incinerator Ash Disposal Bottlenecks:Hazardous landfill capacity scarcity in Delhi-NCR and Mumbai metropolitan regions forces intermediate storage, extending liability exposure for treatment facility operators.
- Plastic PPE Substitution Pressures:Biodegradable alternative materials for sharps containers and collection bags remain incompatible with existing autoclave sterilization protocols, locking generators into petroleum-based supply chains.
Strategic Opportunities
- Real-Time Tracking Mandates:Emerging state-level requirements for GPS-enabled waste consignment monitoring from generator to disposal endpoint create software-integrated service bundling potential.
- Tier-III Hospital Penetration:Underpenetrated nursing homes and primary health centers in Bihar, Odisha, and northeastern states represent captive volume aggregation opportunities ahead of regulatory enforcement waves.
- PLI Scheme Spillover:Production-linked incentives for domestic medical device manufacturing amplify procedural waste generation volumes, tightening collection frequency requirements for sterilization wrap and single-use instruments.
Industry Challenges
- Autoclave Technician Scarcity:Certified boiler operators capable of maintaining 121°C/15 psi steam parameters remain concentrated in western India, constraining facility expansion timelines in emerging markets.
- CPCB Licensing Timelines:Common biomedical waste treatment facility permits require 18-24 month environmental clearance cycles, freezing capital deployment during regulatory review windows.
- Legacy Incinerator Retrofits:Existing 850°C dual-chamber systems require secondary combustion zone upgrades to meet 1100°C pathogen inactivation standards, stranding pre-2016 capital investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bio-Medical Waste Management Market |
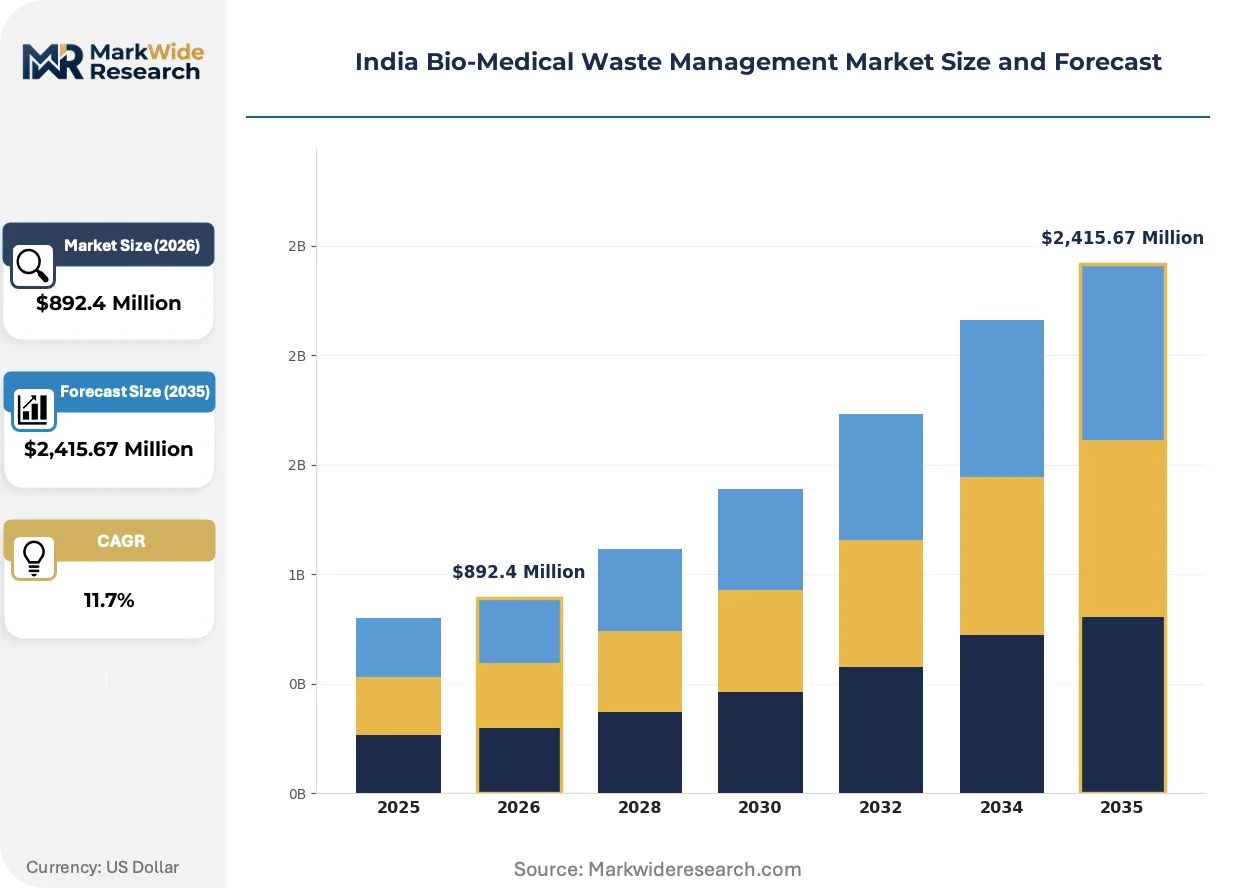
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,415.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sharps, Disposal Bags, Containers, Medical Equipment End User: Hospitals, Clinics, Diagnostic Labs, Research Facilities Service Type: Collection, Treatment, Recycling, Disposal Application: Infectious Waste, Non-Infectious Waste, Hazardous Waste, Pharmaceutical Waste |
| Companies Covered | SMS Water Graca BMW Pvt. Ltd., Veolia Environnement S.A., Biotic Waste Solution Pvt. Ltd, Clean Harbors, Inc., SUEZ SA, Mumbai Waste Management Ltd., GreenTech Environ Management Pvt. Ltd., REMONDIS SE & Co. KG, Synergy Waste Management Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bio-Medical Waste Management Market Trends and Innovations
Digital traceability infrastructure is displacing paper-based manifest systems while microwave-based disinfection technologies challenge steam autoclave dominance in low-volume generator segments.
Radio-frequency identification tagging is unifying generator-registration, transporter-licensing, and treatment-facility-approval databases under unified CPCB digital platforms. Tier-II hospitals in Pune and Ahmedabad are piloting RFID-integrated weighing scales at segregation points, capturing real-time waste category data. This unifying architecture is compressing documentation lag from 72 hours to instantaneous regulatory visibility, enabling dynamic route optimization for collection fleet operators.
The Biomedical Waste Management Rules 2016 amendment mandates barcoding or QR-coding of pre-treated waste bags before interstate transport, tightening chain-of-custody documentation. State Pollution Control Boards in Maharashtra and Karnataka are deploying mobile inspection applications cross-referenced against centralized databases, accelerating enforcement action cycles. Sharps containers and red-bag biomedical waste categories face the steepest compliance verification intensity, driving generator preference for licensed common treatment facilities over captive infrastructure.
Aggregator platforms are consolidating fragmented diagnostic laboratory generators into scheduled collection pools, displacing ad-hoc individual service contracts. Reference laboratories in Bengaluru and Hyderabad are outsourcing entire waste management functions to integrated service providers, bundling segregation training, PPE supply, and treatment documentation. This consolidation pattern concentrates procurement leverage in southern India where diagnostic chain density enables route economics that standalone hospitals cannot replicate internally.
India Bio-Medical Waste Management Market Segmentation
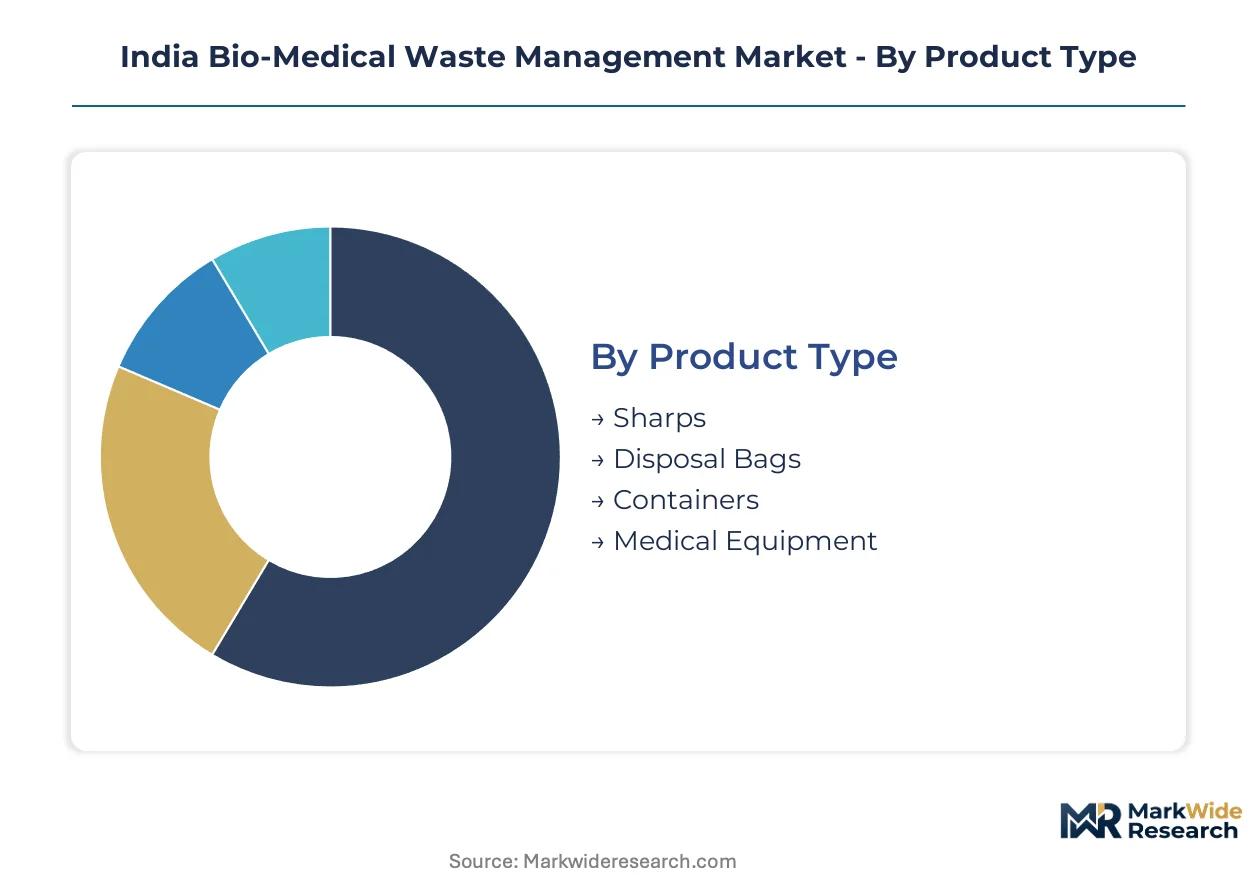
Segmentation in India's bio-medical waste management market reveals how regulatory pressure and technology specifications fragment procurement decisions across generator types. Each axis exposes distinct margin structures and compliance burdens that shape operator positioning.
Product Type:
Thermal resistance specifications and single-use mandates define product differentiation across this category.
- Sharps:Needles, syringes, and lancets requiring puncture-proof containment with polypropylene construction rated for 121°C autoclave cycles. Demand concentrates in Maharashtra and Karnataka multi-specialty hospitals where mandatory single-use protocols generate highest per-bed volumes. CPCB's color-coding enforcement tightens procurement to BIS-certified suppliers.
- Containers:Rigid color-coded bins for anatomical and soiled waste with UV-stabilized polyethylene walls. Western India diagnostic chains drive replacement cycles as point-of-care testing expands beyond hospital campuses. Real-time tracking mandates favor RFID-integrated container procurement.
- Disposal Bags:LDPE/HDPE red and yellow bags with 50-micron minimum thickness for leak-proof transport. Municipal hospital contracts in Delhi-NCR standardize bulk procurement.
- Medical Equipment:Autoclaves, shredders, and needle destroyers for captive treatment infrastructure. Tier-II hospital expansion in Gujarat accelerates capital equipment deployment.
Mature deployment sits with Sharps. Newer deployment is concentrated in Medical Equipment as captive infrastructure expands under stricter CPCB norms.
End User:
Volume scale and regulatory scrutiny intensity separate procurement behaviors across generator categories.
- Hospitals:Multi-bed facilities generating 1-2 kg per bed daily with mandatory common biomedical waste treatment facility tie-ups. Western and southern India tier-I networks sustain highest collection frequency contracts. Autoclave technology upgrades at generator sites drive integrated service bundling.
- Diagnostic Labs:Fragmented point-of-care testing nodes multiplying waste generation beyond traditional hospital catchments. Bengaluru and Hyderabad reference laboratory chains outsource entire waste management functions. Aggregator platforms consolidate scheduled collection pools displacing ad-hoc contracts.
- Clinics:Smaller generators with intermittent waste volumes served by micro-route logistics. Bihar and Odisha nursing homes represent underpenetrated volume aggregation ahead of enforcement waves.
- Research Facilities:Specialized pathological and biotechnological waste streams requiring extended autoclave dwell times. Academic medical centers in Pune and Ahmedabad pilot RFID-integrated segregation systems.
Procurement leverage concentrates in Hospitals. Diagnostic Labs are climbing the fastest as point-of-care testing fragments collection economics.
Service Type:
Capital intensity and licensing scarcity create tiered margin pools across the value chain.
- Collection:Fleet-based logistics absorbing 35-40% fuel cost exposure in per-kilometer economics. Route density in Maharashtra and Gujarat sustains operator profitability against diesel price volatility.
- Treatment:Autoclaving at 121°C/60 minutes and incineration at 1100°C requiring certified boiler operators concentrated in western India. Licensing scarcity and 18-24 month environmental clearance cycles protect incumbent margins.
- Recycling:Post-autoclave plastic recovery for non-hazardous waste streams. Biodegradable PPE substitution pressures lock generators into petroleum-based supply chains.
- Disposal:Hazardous landfill placement for incinerator ash and anatomical waste. Delhi-NCR and Mumbai metropolitan regions face capacity scarcity forcing intermediate storage liability.
Margin depth sits with Treatment. Technology substitution is concentrated in Collection as digital traceability displaces paper-based manifest systems.
Application:
Infectious risk classification determines handling protocols and treatment technology selection.
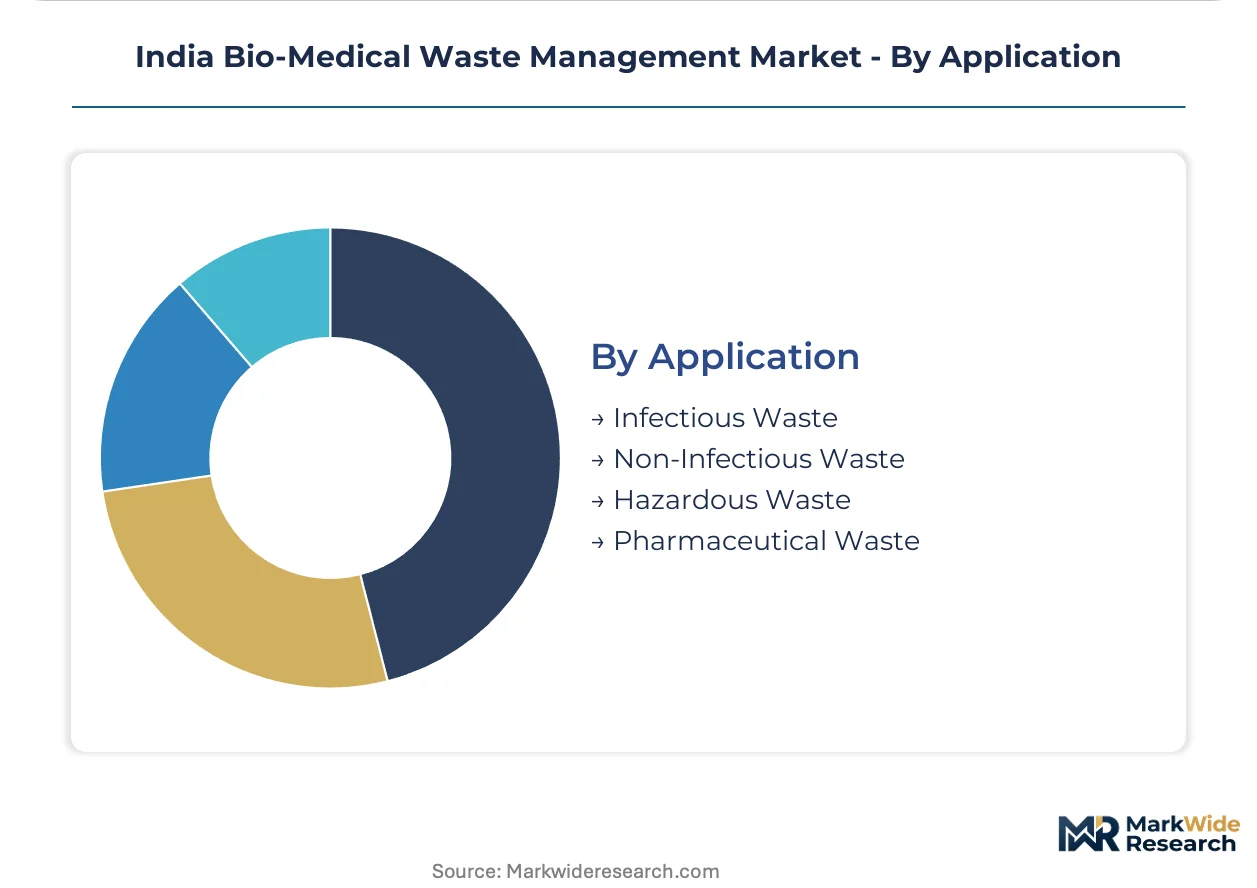
- Infectious Waste:Cultures, swabs, and pathological specimens mandating autoclave or incineration endpoint. Sharps and red-bag categories face steepest CPCB compliance verification intensity.
- Hazardous Waste:Chemicals, heavy metals, and cytotoxic drugs requiring specialized landfill disposal. Mumbai and Delhi-NCR treatment operators extend liability exposure through intermediate storage.
- Pharmaceutical Waste:Expired drugs and vaccine remnants with controlled substance destruction protocols. PLI scheme medical device manufacturing amplifies procedural waste generation volumes.
- Non-Infectious Waste:General soiled materials and packaging segregated for municipal disposal. Lowest compliance burden permits cost-minimized handling.
Regulatory attention concentrates in Infectious Waste. Pharmaceutical Waste is gaining share fastest from production-linked incentive spillover into domestic device manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in western India concentrate captive treatment infrastructure investment under stricter CPCB norms. Maharashtra and Gujarat host the densest common biomedical waste treatment facility networks. Karnataka and Tamil Nadu anchor southern expansion as diagnostic laboratory chains multiply waste generation nodes.
Maharashtra
Mumbai and Pune multi-specialty hospitals generate 1-2 kg per bed daily, sustaining highest collection frequency contracts. The Maharashtra Pollution Control Board enforces real-time GPS tracking mandates from generator to disposal endpoint. SMS Water Graca BMW leverages its western India plant network to sustain high utilization rates across Mumbai metropolitan and Pune industrial clusters.
Gujarat
Tier-II hospital expansion in Ahmedabad and Surat accelerates capital equipment deployment for captive autoclave infrastructure. Gujarat Pollution Control Board licensing protocols compress operational timelines for centralized facility permits. The state's pharmaceutical manufacturing belt amplifies procedural waste generation volumes from PLI scheme medical device production.
Karnataka
Bengaluru diagnostic laboratory chains outsource entire waste management functions to integrated service providers. The Karnataka State Pollution Control Board deploys mobile inspection applications cross-referenced against centralized CPCB databases. Point-of-care testing fragments collection economics into higher-margin micro-routes across Hyderabad-Bengaluru corridor nodes.
Delhi-NCR
Municipal hospital contracts in Delhi standardize bulk procurement of LDPE/HDPE disposal bags. The Central Pollution Control Board enforcement actions compress margins for unlicensed collectors. Hazardous landfill capacity scarcity forces intermediate storage liability extension for treatment operators serving NCR metropolitan catchments.
Tamil Nadu
Chennai academic medical centers pilot RFID-integrated segregation systems for infectious waste categories. The Tamil Nadu Pollution Control Board mandates barcoding of pre-treated waste bags before interstate transport. Southern India nursing homes in underpenetrated districts represent volume aggregation opportunities ahead of regulatory enforcement waves.
India Bio-Medical Waste Management Market Competitive Landscape
Western India producers anchor the high-utilization tier; Delhi-NCR specialists hold municipal contract positions. The vendor base concentrates around three strategic archetypes: integrated facility operators with captive plant networks, technology-led automated segregation providers, and municipal-contract-anchored regional specialists. Consolidation accelerates toward centralized common biomedical waste treatment facilities as CPCB enforcement retires unlicensed collectors. Licensing scarcity and 18-24 month environmental clearance cycles protect incumbent margins against new entrant disruption.
Within the integrated facility tier, SMS Water Graca BMW Pvt. Ltd. and Veolia Environnement S.A. occupy positions reflecting scale-driven route economics and technology leadership respectively. Biotic Waste Solution Pvt. Ltd. exemplifies the municipal-contract archetype through its Delhi-NCR hospital network concentration. SMS Water Graca anchors western India utilization rates; Veolia represents automated segregation system capabilities; Biotic Waste Solution demonstrates regional contract density strategies.
| Leading Market Players |
|---|
| SMS Water Graca BMW Pvt. Ltd. |
| Veolia Environnement S.A. |
| Biotic Waste Solution Pvt. Ltd |
| Clean Harbors, Inc. |
| SUEZ SA |
| Mumbai Waste Management Ltd. |
| GreenTech Environ Management Pvt. Ltd. |
| REMONDIS SE & Co. KG |
| Synergy Waste Management Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Autoclave technology upgrades to 121°C/60-minute BIS-compliant systems are simultaneously elevating capital recovery requirements for treatment operators and concentrating procurement leverage among western India equipment suppliers. This dual compression of cost economics and vendor concentration shapes how service contracts are priced and how supply chains configure across the biomedical waste value chain.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as CPCB licensing timelines stretch 18-24 months for new common biomedical waste treatment facility permits. Three-tier pricing structure across premium, standard, and economy levels separates integrated service bundling from standalone collection-only contracts, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy-tier collection services is intensifying because diesel price volatility erodes per-kilometer route economics. Municipal hospital networks in Delhi-NCR exhibit highest price sensitivity, while multi-specialty hospital chains in Maharashtra demonstrate lowest sensitivity due to regulatory compliance priority.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for medical device manufacturing are redirecting procurement toward India-based sterilization wrap and single-use instrument suppliers. Geographic supply concentration centers on India for autoclave fabrication and captive treatment infrastructure, China for specialized LDPE/HDPE bag polymers, and Germany for precision boiler control systems. Raw material dependencies rest on steam-grade stainless steel, medical-grade polypropylene, and RFID-integrated weighing scale components. Single-source vulnerability concentrates in certified boiler operator labor pools anchored in western India. Distribution runs through state-pollution-control-board-licensed common treatment facility networks with mandated GPS tracking documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's biomedical waste management market functions as a supply-constrained environment where 18-24 month CPCB environmental clearance cycles for new treatment facilities prop incumbent pricing power and protect established operator margins.
For Market Incumbents: Lock in route density advantages across Maharashtra and Gujarat by acquiring underutilized captive infrastructure from tier-II hospital networks facing CPCB compliance cost pressures. Expand certified boiler operator training pipelines to preempt technician scarcity constraints that threaten facility expansion timelines. Prioritize backward integration into RFID-integrated container manufacturing to capture hardware margins from emerging real-time tracking mandates. For New Entrants and Emerging Players: Launch via aggregator platforms consolidating fragmented diagnostic laboratory generators in Bengaluru and Hyderabad into scheduled collection pools. Target tier-III nursing homes and primary health centers in Bihar, Odisha, and northeastern states as the most penetrable geography ahead of enforcement wave arrival. Pursue municipal hospital contract anchoring in underpenetrated state capitals as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated waste management conglomerates seeking western India plant network density. Long-term viability across the projection horizon hinges on licensing scarcity persistence and regulatory enforcement intensity maintenance. Acquisition target archetype: regional specialists with state-pollution-control-board permits in tier-II city clusters. Monitor Karnataka and Tamil Nadu mobile inspection application deployment velocity as the signal to watch for enforcement inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| CPCB Permit Acquisition | 18-24 month clearance cycles create scarcity value for licensed operators in Maharashtra and Karnataka. |
| RFID-Integrated Container Deployment | Real-time tracking mandates from state pollution control boards drive hardware-software bundling opportunities. |
| Certified Technician Training Programs | Boiler operator scarcity in emerging markets constrains facility expansion without proactive workforce development. |
| Diagnostic Lab Aggregator Platform Launch | Point-of-care testing fragmentation in southern India enables micro-route economics that standalone hospitals cannot replicate. |
| Tier-III Geography Pre-Enforcement Positioning | Bihar and Odisha nursing home volume aggregation ahead of regulatory waves captures first-mover licensing advantage. |
Research Methodology
Document review covered CPCB enforcement action records, state pollution control board licensing protocols, and BIS autoclave performance standards, complemented by interviews with common biomedical waste treatment facility operators, hospital biomedical engineers, diagnostic laboratory procurement managers, and state regulatory affairs officers. Secondary validation drew from CDSCO medical device manufacturing disclosures, PLI scheme administrative data, and municipal hospital contract documentation. Bottom-up generator volume estimates triangulated against top-down treatment facility capacity utilization data.
Segmentation outputs across product type, end user, service type, and application dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions. Industry-specific forecast inputs incorporated diesel price volatility coefficients and CPCB enforcement intensity indices by state jurisdiction.
The model assumes a particular technology adoption path; alternative pathways for microwave-based disinfection would alter the outlook if steam autoclave standards are relaxed. Forecasts reflect assumptions regarding regulatory enforcement persistence and licensing timeline stability. Alternative scenarios involving accelerated biodegradable PPE substitution or hazardous landfill capacity expansion in Delhi-NCR and Mumbai would necessitate forecast revision. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market