
 India Commercial Food Waste Decomposer Market | 2026-2036
India Commercial Food Waste Decomposer Market Size, Share, and Industry Trends Forecast 2026-2036
India Commercial Food Waste Decomposer Market Insights
The Solid Waste Management Rules 2016 amendment is expanding compliance obligations for bulk waste generators across Indian metros. Zigma Machinery & Equipment Solutions leverages its engineering pedigree to dominate the aerobic system segment in western India. Kings Industries anchors its position through sustained R&D on thermal decomposition cycles. Riteways Enviro Pvt Ltd specializes in compact anaerobic digesters tailored for hotel kitchen footprints.
India commercial food waste decomposers are electromechanical or bioreactor systems designed to break down organic kitchen refuse through controlled microbial, thermal, or mechanical action, typically processing 50 kg to 5,000 kg daily into stabilised compost or biogas precursors. Aerobic technology leads installed capacity due to lower capital requirements and faster cycle times, while anaerobic configurations capture expanding interest from food manufacturers seeking biogas output. The restaurant end-user segment currently occupies the largest share of unit deployments, though catering services represent the fastest-growing procurement channel as event-scale waste liability sharpens.
BIS certification requirements for electrical composting equipment and state-level plastic waste management enforcement under SWM Rules shape product design and market access for domestic manufacturers. The central electricity regulator CEA and state pollution control boards coordinate on biogas-to-energy incentives that redirect manufacturer R&D priorities. Stakeholders must monitor how municipal corporation tender specifications evolve toward output quality standards rather than mere capacity metrics.
Market Dynamics
Municipal organic waste mandates across Maharashtra and Karnataka are compressing procurement cycles for on-site decomposition units as hotel chains race to demonstrate compliance before state-level enforcement deadlines.
Growth Catalysts
- Solid Waste Management Rules 2016 amendments:The central framework now obligates bulk waste generators across Indian metros to process refuse on-site, triggering unit deployments in Bangalore's restaurant clusters.
- FSSAI food waste management guidelines:Food safety protocols now embed waste liability into operational audits, forcing commercial kitchens to document decomposition capacity.
- BIS certification requirements:Electrical composting equipment standards are filtering out unqualified suppliers and consolidating procurement toward tested aerobic systems.
Market Restraints
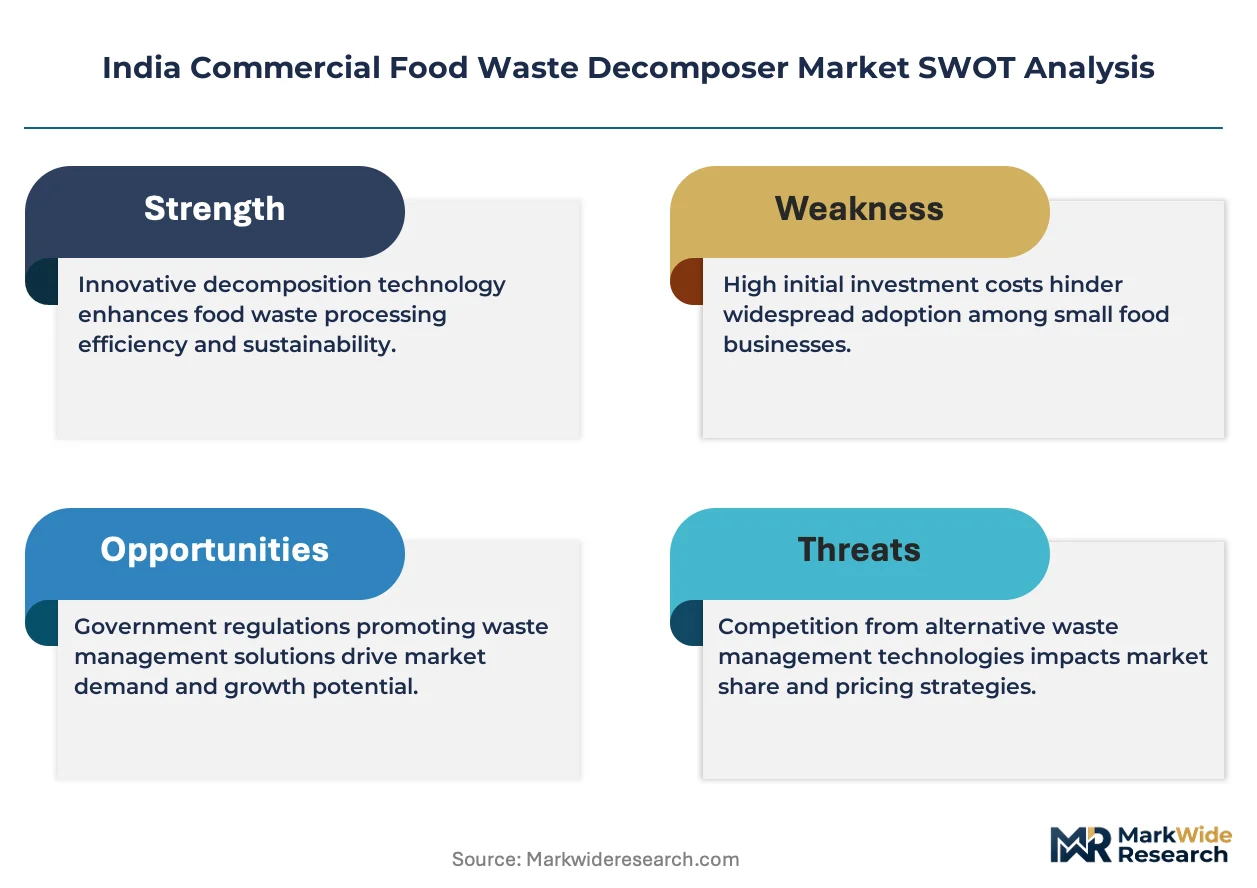
- Capital intensity for anaerobic configurations:Bioreactor systems require 3-4x the upfront investment of aerobic units, restricting adoption to large food manufacturers with captive biogas offtake.
- Microbial culture supply concentration:Starter inoculum production clusters in western India, creating logistics friction for Gujarat-based processors seeking rapid commissioning.
- Power reliability variance:Thermal decomposition cycles depend on grid stability that remains uneven across tier-2 municipal corporations.
Strategic Opportunities
- Catering services procurement channel:Event-scale waste liability is sharpening demand for compact rental units at temporary venues across Delhi-NCR and Mumbai.
- CEA biogas-to-energy incentives:Central electricity regulator coordination with state pollution control boards redirects manufacturer R&D toward anaerobic output quality.
- IoT-enabled remote monitoring:Sensor integration with decomposition cycles is converging with municipal corporation tender specifications that now weight output quality metrics over capacity alone.
Industry Challenges
- Commissioning timeline compression:BIS electrical certification and state pollution control board approvals now overlap, stretching technical documentation teams at domestic manufacturers.
- Integration with legacy kitchen workflows:Existing waste segregation practices at hotel chains require retraining before decomposition units achieve rated throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Commercial Food Waste Decomposer Market |
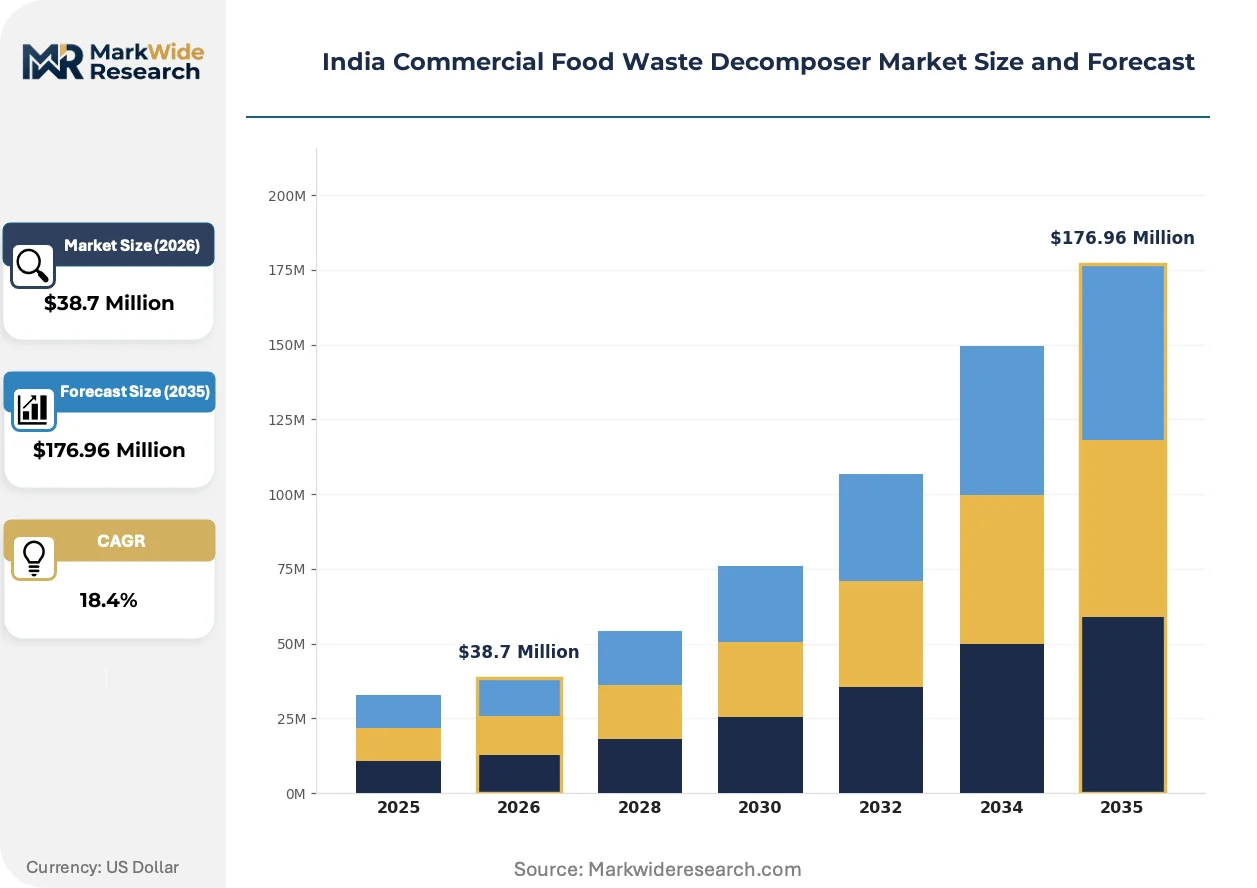
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $176.96 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Aerobic, Anaerobic, Mechanical, Thermal End User: Restaurants, Hotels, Catering Services, Food Manufacturers Application: Organic Waste Management, Composting, Biogas Production, Soil Amendment Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Zigma Machinery & Equipment Solutions, Kings Industries, Gurukrupa Enterprises, Riteways Enviro Pvt Ltd, Envipure Solution, Vakratund Invention India Private Limited, Reva Engineering Enterprises, Ecopollutech Engineers, Greenrich Grow India Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Commercial Food Waste Decomposer Market Trends and Innovations
Aerobic and anaerobic technology paths are diverging based on end-use biogas requirements, while municipal tender design is pivoting from capacity specifications toward compost quality verification.
Electrochemical oxidation pre-treatment is converging with traditional microbial decomposition to accelerate cycle times for high-fat kitchen refuse. Large-format hotel kitchens in Maharashtra are piloting hybrid systems that combine electrochemical cells with aerobic drums, compressing processing windows from 24 hours to under 12 hours for grease-heavy loads. This convergence is enabling smaller footprint units to replace larger conventional installations in space-constrained urban properties.
FSSAI's integration of waste management into food safety audits is reshaping procurement documentation requirements. Commercial kitchens must now maintain decomposition logs alongside hygiene records, forcing equipment suppliers to bundle digital tracking interfaces with hardware sales. Restaurant clusters in Bangalore are responding fastest, with several mandating cloud-connected units that stream compliance data directly to municipal corporations.
Event-scale waste liability is compressing rental procurement cycles for temporary decomposition capacity. Catering operators previously reliant on municipal collection now face direct fines for unsegregated refuse, driving same-day equipment deployment contracts. Gujarat's food processing corridors exhibit the most visible shift, with festival-season rental volumes now matching permanent installations in annual unit-hours deployed.
India Commercial Food Waste Decomposer Market Segmentation
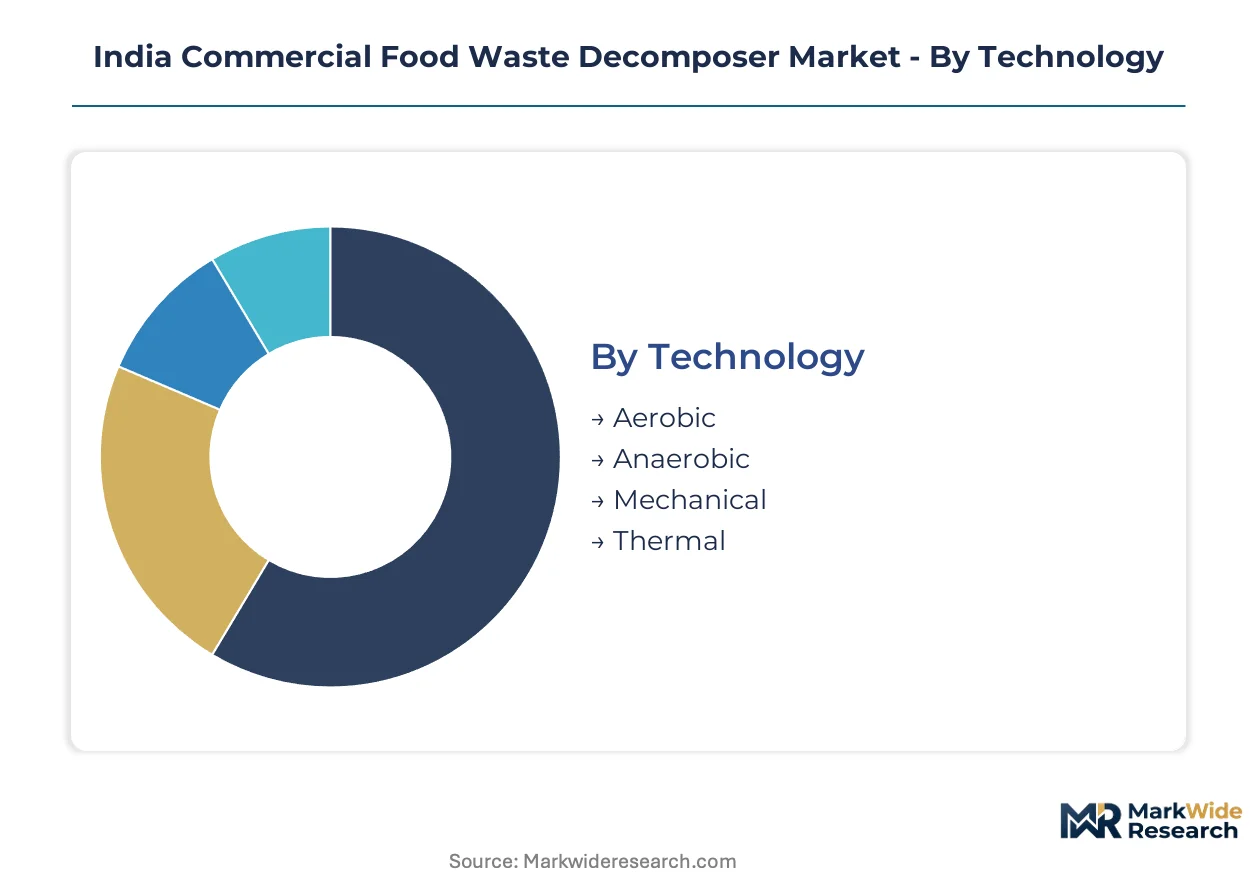
Technology choices in India's commercial food waste decomposer market determine capital recovery timelines and regulatory compliance pathways. End-user procurement patterns diverge sharply between permanent installations and rental deployments across Maharashtra and Karnataka enforcement zones.
Technology:
Upgrade cycles accelerate where BIS certification deadlines compress equipment replacement decisions for bulk waste generators.
- Aerobic:Electromechanical systems deploy oxygen-fed microbial cultures to decompose organic refuse within 24-hour cycles. Hotel chains across Bangalore's restaurant clusters favor these units for lower capital outlay and faster commissioning timelines under municipal mandates.
- Anaerobic:Sealed bioreactor configurations capture methane precursors through oxygen-excluded bacterial digestion. Food manufacturers in Gujarat's processing corridors prioritize this technology where CEA biogas-to-energy incentives improve project economics.
- Mechanical:Physical pulverization systems reduce waste volume without biological stabilization, serving temporary catering deployments where immediate volume reduction satisfies event-scale compliance.
- Thermal:Heat-accelerated decomposition units process grease-heavy kitchen loads in under 12 hours, commanding premium positioning in Maharashtra's space-constrained urban hotel properties.
Aerobic systems sit at the top of the volume ranking, with anaerobic configurations climbing the fastest.
End User:
Procurement scale varies dramatically between single-unit restaurant deployments and multi-site corporate rollouts across state enforcement corridors.
- Restaurants:Independent and chain establishments in Bangalore's dense commercial districts drive baseline demand for compact 50-500 kg daily capacity units. FSSAI audit documentation requirements now mandate decomposition logs alongside hygiene records, forcing hardware upgrades with integrated digital tracking.
- Hotels:Large-format properties across Maharashtra install on-site systems to meet bulk generator obligations under amended SWM Rules. Space constraints in Mumbai and Pune properties favor hybrid electrochemical-aerobic configurations with reduced footprints.
- Catering Services:Event operators in Delhi-NCR and Mumbai procure rental units for temporary venues where same-day deployment contracts now match permanent installations in annual unit-hours.
- Food Manufacturers:Processing facilities in Gujarat's corridors deploy industrial-scale anaerobic digesters with captive biogas offtake, though 3-4x capital intensity restricts adoption to larger operators.
Restaurants dominate current deployment volumes, while catering services expand most quickly.
Application:
Output specifications determine municipal tender eligibility and downstream revenue streams from compost or biogas sales.
- Organic Waste Management:Core compliance function addressing SWM Rules mandates for bulk generators, with output quality metrics now weighted over capacity in corporation tender specifications.
- Composting:Stabilized soil amendment production serves agricultural offtake agreements in peri-urban zones surrounding Bangalore and Pune.
- Biogas Production:Methane capture for energy conversion attracts CEA-coordinated incentives, redirecting manufacturer R&D priorities toward anaerobic output quality.
- Soil Amendment:Refined compost products meeting BIS quality standards command premium positioning in commercial horticulture supply chains.
Organic waste management commands the largest installed base, with biogas production gaining share fastest.
Distribution Channel:
Channel selection reflects customer technical sophistication and urgency of compliance deadlines across state enforcement schedules.
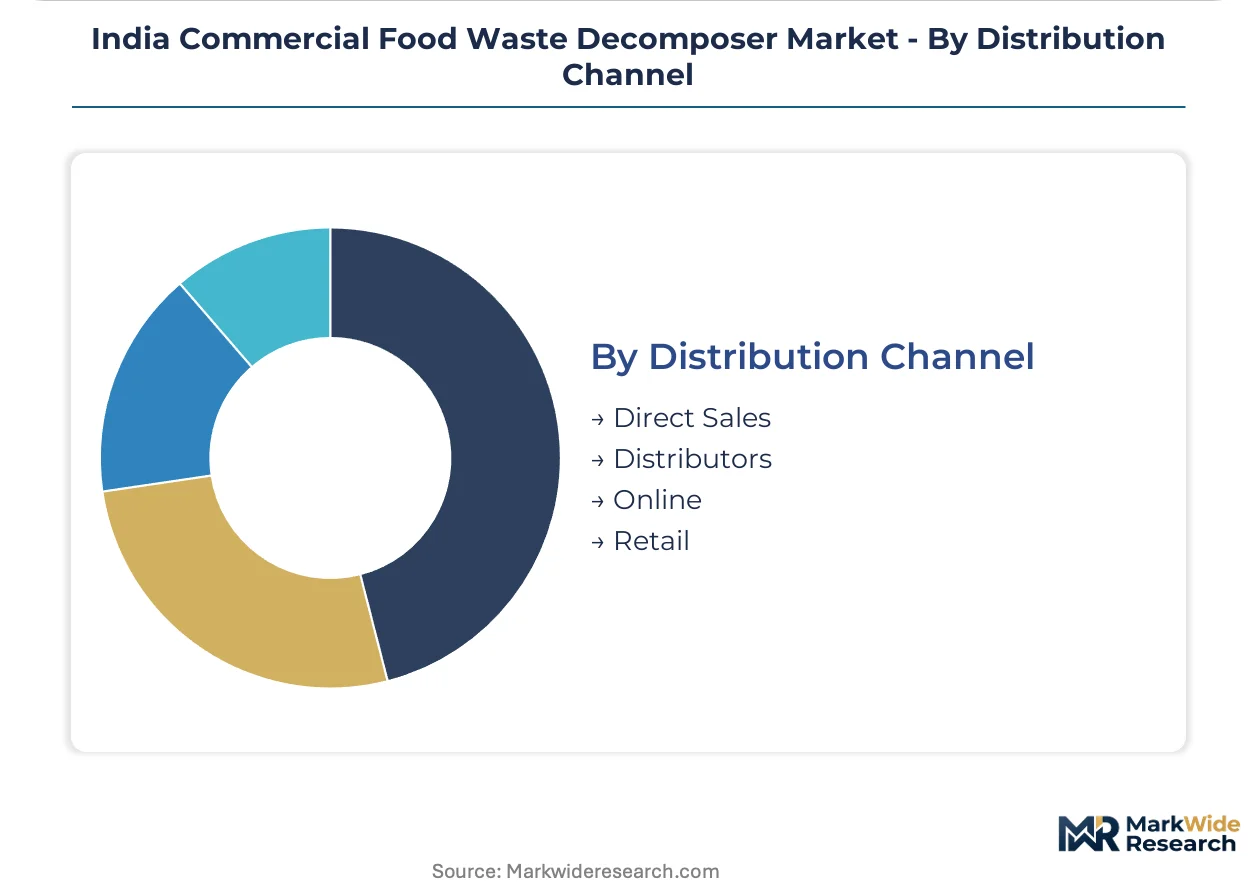
- Direct Sales:Manufacturer-led engagements dominate large hotel chain and food manufacturer procurements requiring customized integration with legacy kitchen workflows.
- Distributors:Regional equipment networks serve mid-scale restaurant clusters with standardized aerobic units and localized commissioning support.
- Online:Digital procurement channels expand for compact rental units and replacement microbial culture supplies, particularly in tier-2 municipal corporations.
- Retail:Limited presence through specialized commercial kitchen equipment dealers, concentrated in Bangalore and Mumbai metropolitan supply hubs.
Direct sales lead transaction value, with online channels expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Maharashtra and Karnataka anchor India's commercial food waste decomposer manufacturing and deployment networks. State-level enforcement corridors concentrate procurement activity where municipal mandates bite hardest.
Maharashtra
Mumbai and Pune hotel chains drive bulk generator compliance under amended SWM Rules. The Maharashtra Pollution Control Board coordinates with municipal corporations on tender specifications that now weight output quality metrics. Space-constrained urban properties in Mumbai favor compact hybrid electrochemical-aerobic configurations with reduced footprints.
Karnataka
Bangalore's dense restaurant clusters deploy baseline aerobic units for 50-500 kg daily capacity processing. The Karnataka State Pollution Control Board enforces bulk waste generator obligations with documented decomposition logs. FSSAI audit integration forces hardware upgrades with cloud-connected digital tracking interfaces in Koramangala and Indiranagar commercial districts.
Gujarat
Food processing corridors in Ahmedabad and Vadodara prioritize industrial-scale anaerobic digesters with captive biogas offtake. CEA-coordinated biogas-to-energy incentives redirect manufacturer R&D priorities toward output quality verification. Festival-season rental volumes now match permanent installations in annual unit-hours deployed across the state's processing zones.
Delhi-NCR
Catering operators in Gurgaon and Noida procure rental units for temporary venues where same-day deployment contracts dominate. The Delhi Pollution Control Committee enforces direct fines for unsegregated refuse at event-scale operations. Microbial culture supply logistics from western India create commissioning friction for rapid equipment activation.
Tamil Nadu
Chennai's commercial kitchen equipment dealers serve mid-scale restaurant clusters with standardized aerobic units and localized commissioning support. State pollution control board approvals overlap with BIS electrical certification, stretching technical documentation timelines. Tier-2 municipal corporations in Coimbatore exhibit expanding digital procurement channels for compact rental units.
India Commercial Food Waste Decomposer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across India's commercial food waste decomposer market. The vendor base clusters around engineering fabricators with legacy machining capabilities and specialized environmental technology firms with bioreactor expertise. Three archetypes dominate: western India-based aerobic system specialists, thermal decomposition R&D anchors, and compact anaerobic digester designers for hospitality footprints. Consolidation pressures favor manufacturers with integrated BIS certification capabilities and state pollution control board liaison networks.
Among western India-based engineering specialists, Zigma Machinery & Equipment Solutions occupies a position exemplifying the aerobic system segment's engineering pedigree. Kings Industries anchors the thermal decomposition archetype through sustained R&D cycle development. Riteways Enviro Pvt Ltd represents the compact anaerobic digester specialization tailored for hotel kitchen constraints. These three fabricators illustrate how geographic concentration in Maharashtra and Karnataka shapes competitive positioning around municipal enforcement proximity and microbial culture supply chain access.
| Leading Market Players |
|---|
| Zigma Machinery & Equipment Solutions |
| Kings Industries |
| Gurukrupa Enterprises |
| Riteways Enviro Pvt Ltd |
| Envipure Solution |
| Vakratund Invention India Private Limited |
| Reva Engineering Enterprises |
| Ecopollutech Engineers |
| Greenrich Grow India Private Limited |
| Others |
Pricing and Supply Chain Analysis
Hybrid electrochemical-aerobic configurations are compressing manufacturing cycle times while concentrating component sourcing around Maharashtra and Karnataka engineering clusters, simultaneously lowering per-unit production costs and tightening supplier bargaining power for domestic fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with thermal and anaerobic systems commanding premium positioning against baseline aerobic units. Price differentiation rests on BIS certification grade and bundled commissioning support, with catering operators exhibiting highest sensitivity while food manufacturers prioritize biogas output quality over capital outlay. Cost compression in standard-tier aerobic configurations is intensifying because microbial culture suppliers compete on volume contracts.
Supply Chain Analysis
Regional distribution centers in Mumbai, Bangalore, and Ahmedabad operate hub-and-spoke patterns that feed tier-2 municipal corporations. Manufacturing concentrates in India, with stainless steel fabrication and electrochemical cell components drawing from Gujarat and Tamil Nadu supplier bases. Single-source vulnerability around proprietary microbial inoculum strains creates commissioning delays for rapid-deployment contracts. Distribution runs through direct manufacturer channels for large hotel chains and specialized equipment distributors for mid-scale restaurant clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as municipal enforcement timelines harden compliance obligations across Indian metros, embedding decomposition capacity into commercial kitchen operating licenses.
For Market Incumbents: Deepen backward integration into microbial culture production to secure supply chain control against western India concentration risks. Expand BIS certification capabilities to filter unqualified competitors from municipal tender pools. Prioritize R&D investment in IoT-enabled output verification interfaces as corporation specifications pivot toward quality metrics. For New Entrants and Emerging Players: Tier-2 municipal corporations in Coimbatore and Vadodara represent underserved procurement channels with compressed compliance deadlines and limited distributor presence. Target rental deployment contracts for festival-season catering operators in Gujarat seeking same-day equipment activation. Pursue digital-first go-to-market positioning through online procurement platforms for compact unit sales. For Investors and Strategic Acquirers: Valuations sit cheapest among engineering fabricators lacking integrated certification capabilities and state pollution control board liaison networks. Long-term viability favors manufacturers with captive biogas-to-energy project development expertise aligned with CEA incentive coordination. Watch municipal tender specification evolution toward compost quality verification as the inflection signal for technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Filters unqualified suppliers from Maharashtra and Karnataka municipal tender pools. |
| Microbial Culture Supply Integration | Secures commissioning timelines against western India logistics friction. |
| IoT-Enabled Output Verification | Aligns equipment specifications with evolving corporation quality metrics. |
| Anaerobic Biogas Quality R&D | Captures CEA-coordinated energy conversion incentives in Gujarat corridors. |
| Rental Fleet Expansion | Matches festival-season catering demand in Delhi-NCR and Mumbai. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hotel operations directors, municipal corporation sanitation engineers, food manufacturer plant heads, and equipment distributor principals alongside secondary validation through BIS certification databases, state pollution control board filings, FSSAI audit protocols, and municipal tender documentation. Bottom-up unit deployment counts triangulated against top-down market sizing from engineering fabricator capacity disclosures.
Comparable historical periods anchored the projection horizon to pre-enforcement and post-amendment regulatory phases across the modeling period. Segmentation dimensions modeled include technology pathway, end-user archetype, application output type, and distribution channel structure. CAGRs derived from fitted growth curves incorporating enforcement timeline acceleration, procurement cycle compression, and rental channel expansion rates.
Underlying measurement precision varies by segment; aerobic system deployments carry tighter precision than anaerobic configurations given standardization and reporting consistency. Forecasts reflect assumptions around municipal enforcement adherence and state-level plastic waste rule implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Vietnam Waste Management Market