
 Metal Recycling Baler Market | 2026-2036
Metal Recycling Baler Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Recycling Baler Market Analytics
Aftermarket service revenue is rewriting profit distribution across the metal recycling baler landscape. LEFORT anchors its European installed base through long-term maintenance contracts and spare parts logistics. Sierra International Machinery leverages its North American dealer network to control aftermarket touchpoints across scrap yard customers. Danieli Centro Recycling competes on technical service intensity, embedding field engineers at large industrial manufacturer sites.
A metal recycling baler compresses ferrous and non-ferrous scrap into dense, furnace-ready bales using hydraulic, pneumatic, or electric drive systems exerting hundreds of tons of force. Horizontal balers dominate volume throughput in high-capacity scrap yards where continuous feed streams require automated processing. Two-ram balers command premium positioning for mixed-material flexibility, while electric drive technology is displacing conventional hydraulic systems in facilities facing carbon accounting pressures.
The EPA enforces scrap metal handling standards that shape baler emission profiles and hydraulic fluid containment protocols across US installations. REACH and the EU Green Deal mandate traceable metal recovery rates that push European scrap yards toward auto-tie balers with integrated weighing and material identification. Stakeholders must monitor how China's dual carbon goals and GB standards evolve to determine whether electric and hybrid baler architectures gain regulatory preference over legacy hydraulic platforms.
Market Dynamics
The metal recycling baler market pivots on the electrification of drive systems as carbon accounting pressures force scrap processors to abandon hydraulic architectures. This technology transition compresses operating costs while raising upfront capital requirements across yard and industrial installations.
Growth Catalysts
- EU Green Deal mandates:Binding metal recovery targets in Germany and France accelerate fleet replacements toward auto-tie balers with integrated weighing systems.
- Industrial manufacturing integration:Chinese steel mills and aluminum smelters deploy onsite baling to cut logistics spend and guarantee furnace-ready feedstock quality.
- Scrap yard consolidation:Volume concentration across North American metal recyclers drives continuous-feed horizontal baler demand for automated high-throughput processing.
Market Restraints
- Steel price volatility:Feedstock cost swings compress processor margins and delay capital commitments on new baler installations.
- Hydraulic fluid containment costs:EPA spill prevention regulations impose ongoing compliance expenditure on legacy hydraulic system operators.
- Electric drive component scarcity:Permanent magnet motor supply concentrates among East Asian suppliers, creating procurement bottlenecks for European and North American OEMs.
Strategic Opportunities
- India's informal sector formalization:BIS certification requirements and urban mining initiatives open addressable market space for mid-capacity baler deployments.
- Hybrid drive architectures:Convergence of servo-electric precision with hydraulic force density targets carbon-intensive yards unable to full-electrify.
- Auto-tie system retrofits:REACH documentation pressures create aftermarket demand for material identification and weighing module upgrades on existing installed base.
Industry Challenges
- Hydraulic-to-electric technician retraining:Field service workforce lacks competency in high-voltage drive diagnostics and permanent magnet motor maintenance.
- Legacy control system integration:Proprietary PLC architectures from 1990s-era balers resist interoperability with modern IoT-enabled monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Recycling Baler Market |
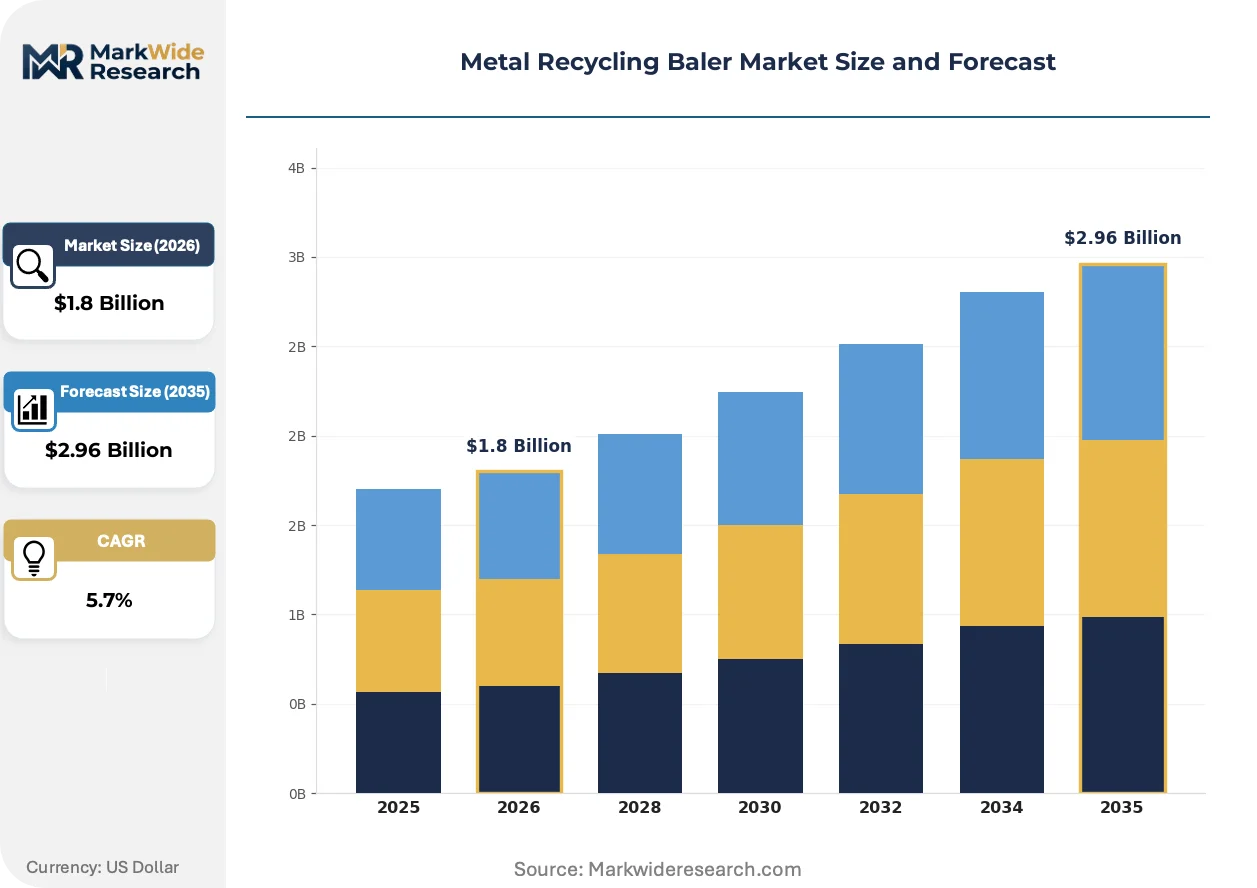
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Baler, Vertical Baler, Two-Ram Baler, Auto-Tie Baler Technology: Hydraulic, Pneumatic, Electric, Hybrid End User: Scrap Yards, Industrial Manufacturers, Waste Management Companies, Retailers Deployment: Onsite, Offsite, Mobile, Permanent Installation |
| Companies Covered | American Baler Company, LEFORT, IMABE IBERICA, JMC Recycling Ltd, Sierra International Machinery, Advance Hydrau Tech Pvt Ltd, Danieli Centro Recycling, Bronneberg, Marathon Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Recycling Baler Market Evolving Landscape
Sensor fusion and machine learning architectures are penetrating baler control systems, transforming compression force optimization from operator judgment to algorithmic execution. This shift compresses energy consumption per bale while reducing material-dependent setup times.
Machine vision is digitizing feedstock classification at the baler infeed. Scrap yards in the US and Germany deploy spectral cameras to distinguish aluminum grades and coated steels before compression. The technology enables real-time bale tagging that satisfies REACH traceability mandates without manual sorting labor.
The EPA's tightened hydraulic fluid containment standards are forcing control architecture redesigns across US installations. Secondary containment and leak detection systems now require integration with baler PLCs, raising engineering complexity for OEMs serving American scrap processors. California and Texas yards face the steepest compliance curves due to state-level groundwater protection overlays.
Service contract unbundling is fragmenting how scrap yards procure baler support. Large German recyclers now separate preventive maintenance, spare parts logistics, and emergency response into discrete supplier relationships. This purchasing pattern shift pressures OEMs like LEFORT and Sierra International Machinery to defend attachment rates through predictive maintenance software rather than bundled service packages.
Metal Recycling Baler Market Segmentation
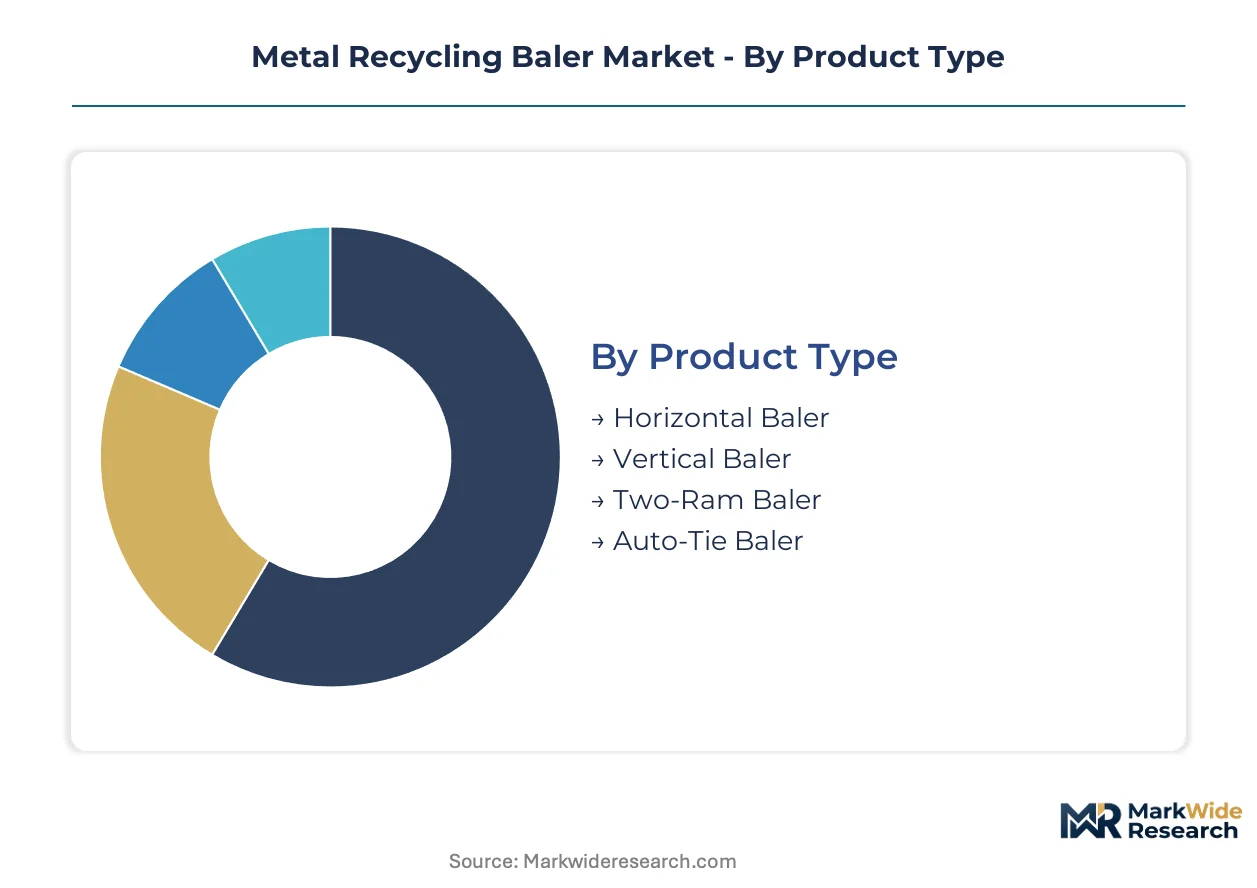
Segmentation in the metal recycling baler market reveals how technology maturity, operational scale, and regulatory pressure fragment equipment demand. Each dimension exposes distinct procurement patterns across scrap processors and industrial operators.
Product Type:
Mature horizontal architectures dominate high-volume installations, while emerging auto-tie configurations capture regulatory-driven replacement cycles.
- Horizontal Baler:Continuous-feed designs process aluminum and steel streams without operator intervention. Demand concentrates across German scrap yards expanding fleet capacity under EU Green Deal metal recovery mandates.
- Vertical Baler:Space-constrained operations favor these compact units for lower throughput applications. Retailers and small waste management companies in urban clusters deploy them for preliminary volume reduction before offsite transport.
- Two-Ram Baler:Dual-compression chambers enable mixed-material flexibility without manual presorting. Industrial manufacturers integrating onsite baling specify these for handling diverse production scrap grades.
- Auto-Tie Baler:Automated wire-tying systems integrate weighing modules and material identification sensors. REACH traceability requirements in France and Germany accelerate adoption across yards replacing legacy manual-tie equipment.
Horizontal balers retain volume leadership; auto-tie balers hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy hydraulic investments from premium electric and hybrid architectures commanding carbon-accounting premiums.
- Hydraulic:Established force-density platforms face escalating compliance costs under EPA spill prevention regulations. Legacy installed bases in Texas and California absorb secondary containment retrofit expenditures.
- Pneumatic:Compressed-air drive systems occupy niche mid-capacity applications with moderate force requirements. Food and beverage sector scrap processors specify these for clean-environment installations.
- Electric:Permanent magnet motors eliminate hydraulic fluid containment liabilities and cut energy consumption per bale. Supply concentration among East Asian motor manufacturers creates procurement bottlenecks for European OEMs.
- Hybrid:Servo-electric precision converges with hydraulic force density for carbon-intensive yards unable to full-electrify. Chinese steel mills evaluate these architectures against dual carbon goal compliance timelines.
Hydraulic systems retain installed base dominance; electric drives gain share fastest among new installations.
End User:
Application intensity varies sharply between external scrap processors and captive industrial operations with divergent logistics economics.
- Scrap Yards:Independent metal recyclers deploy high-throughput horizontal and two-ram configurations for commodity-grade output. North American yard consolidation drives automated continuous-feed demand.
- Industrial Manufacturers:Steel mills and aluminum smelters integrate onsite baling to eliminate third-party logistics costs and guarantee furnace-ready feedstock quality. Chinese industrial deployment concentrates in coastal manufacturing clusters.
- Waste Management Companies:Municipal and commercial waste streams require flexible baling for mixed metal recovery. These operators prioritize mobile and offsite deployment models.
- Retailers:Distribution centers and big-box chains deploy compact vertical units for packaging and fixture scrap. Volume constraints limit specification to entry-capacity equipment.
Scrap yards retain volume leadership; industrial manufacturers hold the steepest expansion curve.
Deployment:
Customer type and mobility requirements dictate capital allocation between fixed infrastructure and flexible equipment positioning.
- Onsite:Permanent installation at generation points eliminates transport costs for high-volume producers. Industrial manufacturers and large scrap yards standardize on this model.
- Offsite:Centralized processing facilities serve dispersed scrap collection networks. Waste management companies operate these configurations for aggregated municipal and commercial feedstock.
- Mobile:Trailer-mounted balers relocate to demolition sites and temporary collection events. Construction scrap recovery and disaster debris operations specify these units.
- Permanent Installation:Foundation-anchored systems maximize throughput and automation integration. Greenfield scrap yard developments in Germany and France specify permanent horizontal and auto-tie architectures.
Permanent installations retain volume leadership; mobile deployment holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German scrap yards absorb premium pricing for auto-tie systems under regulatory pressure, while Indian informal processors remain acutely price-sensitive to capital outlays.
Germany
Scrap yards in the Ruhr Valley and Bavaria expand horizontal baler fleets to process rising aluminum and steel volumes. The EU Green Deal mandates binding metal recovery targets that accelerate replacement of manual-tie equipment. Hamburg and Stuttgart industrial clusters drive specification of integrated weighing and material identification systems.
United States
EPA spill prevention regulations impose secondary containment costs on legacy hydraulic installations across Texas and California scrap processors. Yard consolidation in the Southeast and Midwest concentrates volume throughput demand for continuous-feed horizontal architectures. Houston and Chicago metal recyclers prioritize automated processing to reduce labor dependency.
China
Coastal manufacturing clusters in Jiangsu and Zhejiang provinces integrate onsite baling to eliminate third-party logistics costs for steel mills and aluminum smelters. GB standards and dual carbon goals push evaluation of electric drive architectures against legacy hydraulic platforms. Shanghai and Ningbo industrial zones concentrate captive processing demand.
India
BIS certification requirements and urban mining initiatives in Maharashtra and Gujarat formalize previously informal scrap collection networks. Price-sensitive mid-capacity deployments dominate as processors balance compliance costs against capital constraints. Mumbai and Ahmedabad metal recovery operations drive gradual fleet modernization.
France
REACH traceability mandates accelerate auto-tie baler adoption across scrap yards in Île-de-France and Hauts-de-France. Paris and Lyon industrial recyclers specify material identification sensors to satisfy documentation requirements for furnace-ready output. The EU Green Deal reinforces national circular economy targets for metal recovery rates.
Metal Recycling Baler Market Competitive Landscape
Capability concentration sits with European and North American engineering specialists; scale advantage sits with Asian fabricators serving cost-sensitive emerging markets. The vendor base separates into three strategic archetypes: premium-tier European OEMs with embedded service networks, mid-market specialists competing on customization flexibility, and volume-focused Asian producers optimizing production economics. Dominant competitive moves include aftermarket service contract unbundling and predictive maintenance software deployment to defend attachment rates.
Among European engineering specialists, LEFORT and Danieli Centro Recycling occupy positions emphasizing technical service intensity and long-term maintenance relationships. Sierra International Machinery anchors the North American premium tier through dealer network control of aftermarket touchpoints. These three exemplify how geographic origin and organizational structure shape competitive positioning without requiring identical capability investments.
| Leading Market Players |
|---|
| American Baler Company |
| LEFORT |
| IMABE IBERICA |
| JMC Recycling Ltd |
| Sierra International Machinery |
| Advance Hydrau Tech Pvt Ltd |
| Danieli Centro Recycling |
| Bronneberg |
| Marathon Equipment |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese hydraulic component manufacturing is compressing OEM margins while forcing European and North American suppliers toward premium electric drive positioning. This utilization imbalance creates divergent pricing postures across legacy and next-generation baler architectures.
Pricing Analysis
Aftermarket service contracts now generate the dominant share of lifetime value across installed baler fleets. Three-tier pricing structure across premium, standard, and economy levels separates OEMs with embedded field engineering from regional assemblers competing on capital cost. Price differentiation rests on certification grade and geographic delivery cost, with EU Green Deal compliance premiums widening spreads between REACH-certified and non-certified equipment. Cost compression in mid-capacity hydraulic tiers is intensifying because Chinese fabricators are absorbing margin to maintain volume. Scrap yards in India and Southeast Asia exhibit acute price sensitivity, while German industrial recyclers prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Contract manufacturing for permanent magnet motors concentrates among East Asian foundries, with Chinese and South Korean suppliers holding dominant capacity. Component sourcing draws from Germany for precision hydraulics, China for structural steel frames, and Japan for high-voltage drive controllers. Supply chain risk centers on single-source vulnerability for rare-earth magnet procurement. Distribution runs through OEM-direct channels for large industrial accounts and authorized dealer networks for scrap yard customers across North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal recycling baler demand is tracking a cyclical recovery anchored to steel price stabilization and resumed capital expenditure across European scrap processors.
For Market Incumbents: Pre-empt electric drive component scarcity by securing long-term offtake agreements with East Asian motor suppliers before procurement bottlenecks tighten. Deepen backward integration into predictive maintenance software to defend attachment rates as German recyclers unbundle service contracts. Capacity addition in India addresses the formalization wave without exposing core European margins to price-sensitive competition. For New Entrants and Emerging Players: Pursue mobile baler deployment as the most penetrable white space, where construction scrap recovery and disaster debris operations lack established supplier relationships. Target India's mid-capacity segment through BIS-certified equipment priced below European OEM tiers. Channel partnerships with local fabrication shops accelerate geographic coverage without captive field service investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European OEMs with long-term maintenance contracts and spare parts logistics embedded at large scrap yard accounts. Acquisition targets with installed base density in Germany and France offer superior cash flow visibility across a five-to-ten-year window. Monitor steel price futures and EU carbon border adjustment implementation as inflection signals for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive Platform Migration | Eliminates EPA hydraulic fluid containment liabilities while cutting energy consumption per bale processed. |
| Auto-Tie System Retrofit Program | Captures REACH-driven upgrade demand across legacy installed base in France and Germany. |
| Predictive Maintenance Software Launch | Defends service attachment rates as large German recyclers unbundle procurement relationships. |
| India Distribution Partnership | Addresses BIS certification requirements without direct capital exposure to price-sensitive segments. |
| Hybrid Drive Architecture Development | Targets carbon-intensive Chinese steel mills unable to full-electrify under dual carbon timelines. |
Research Methodology
Initial hypotheses were tested against primary input from scrap yard operations managers, industrial maintenance directors, OEM aftermarket service heads, and hydraulic component procurement leads and refined through secondary validation. Primary fieldwork combined structured interviews with equipment end-users and channel partners across Germany, the United States, China, and India. Secondary sources included customs trade data for baler import flows, EPA enforcement records for hydraulic spill incidents, EU ETS carbon accounting disclosures, and SEC filings from listed metal recycling operators. Bottom-up unit economics triangulated against top-down market sizing from national scrap processing capacity registries.
Demand-supply balance modeling across the projection horizon incorporated feedstock volume forecasts by metal category, fleet replacement cycles tied to regulatory compliance deadlines, and industrial captive processing adoption rates. Segmentation dimensions included product architecture, drive technology tier, end-user application intensity, and deployment model. CAGRs were derived from installed base growth projections and average selling price evolution by technology tier. Industry-specific inputs captured steel price volatility bands and carbon accounting cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in steel price indices, industrial production cycles, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution elasticities. Quarterly review of scrap metal futures, OEM order backlogs, and REACH documentation compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
North America Solid Waste Management Market