
 Waste Paper Recycling Market | 2026-2036
Waste Paper Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Paper Recycling Market Intelligence
The substitution of virgin wood pulp with recycled fiber in packaging materials is consolidating the value of clean, sorted waste paper streams. Integrated producers like Pratt Industries operate closed-loop systems, turning collected paper directly into new packaging. Waste Management leverages its vast collection network to secure feedstock, while Veolia Environment differentiates through advanced sorting technologies to maximize recovery rates from mixed streams.
Waste paper recycling is the process of converting paper-based waste into new pulp through sorting, cleaning, and pulping. A critical step is deinking, which uses chemical and mechanical actions to remove contaminants and produce a viable secondary fiber. Cardboard remains the largest volume segment due to e-commerce packaging, supplying feedstock directly to Pulp & Paper Manufacturers. Higher-margin opportunities exist in recycling office paper, which yields premium-quality pulp for new graphic and tissue paper production.
Regulatory frameworks create the primary market conditions for recycling. The EU Green Deal mandates circular economy principles and recycled content targets, while US EPA guidelines influence municipal collection programs. China's stringent import quality standards have fundamentally altered trade flows for recovered paper. Future investment decisions will hinge on securing access to high-quality, uncontaminated feedstock and navigating regional variations in recycled content mandates.
Market Dynamics
The central force governing the waste paper recycling market is the global realignment of supply chains. National import restrictions, particularly China's stringent quality standards, are compelling waste-exporting countries to develop domestic processing infrastructure and seek new end markets in Southeast Asia.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and its Circular Economy Action Plan compel manufacturers to use more recycled content in packaging, creating a stable, policy-driven demand for recovered paper pulp.
- E-commerce Expansion:Sustained growth in the e-commerce sector generates a massive and consistent supply of used corrugated containers (UCC), which serve as the primary feedstock for containerboard and packaging production.
- Deinking Technology:Advances in flotation deinking and washing processes enable the removal of inks and contaminants more efficiently, producing higher-quality recycled pulp suitable for graphic papers and tissue.
Market Restraints
- Feedstock Contamination:The presence of plastics, food residue, and other non-paper materials in municipal collection streams degrades fiber quality, increases processing costs, and lowers the yield of usable pulp.
- Collection Rate Volatility:Recovered paper supply is subject to fluctuations based on municipal budgets, public participation in recycling programs, and overall economic activity, creating input cost instability for recyclers.
- Virgin Fiber Competition:In certain packaging applications and geographic markets, virgin wood pulp remains a cost-competitive alternative, particularly when sustainability is not the primary procurement driver for end-users.
Strategic Opportunities
- Processing Hub Development:Investment in new recycling and pulping facilities in countries like Vietnam, India, and Malaysia can capture regional demand from manufacturing industries and process materials previously exported to China.
- High-Grade Pulp Production:Focusing on sorted office paper (SOP) and other high-quality grades presents an opportunity to produce premium pulp for tissue, printing, and writing paper, which command higher margins.
- EPR Legislation:The adoption of Extended Producer Responsibility (EPR) schemes in various US states and Canadian provinces provides a new, consistent funding mechanism to upgrade collection and sorting infrastructure.
Industry Challenges
- Capital Investment Hurdles:The construction of modern recycling mills equipped with advanced sorting, pulping, and deinking systems requires significant upfront capital expenditure, posing a barrier to new entrants.
- Logistical Reconfiguration:Shifting trade flows necessitates the establishment of new shipping routes, warehousing, and supply chain partnerships, adding complexity and cost for collectors and brokers.
- Advanced Sorting Expertise:A shortage of technicians trained to operate and maintain sophisticated optical sorters and robotic separation systems can limit the efficiency and throughput of modern material recovery facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Paper Recycling Market |
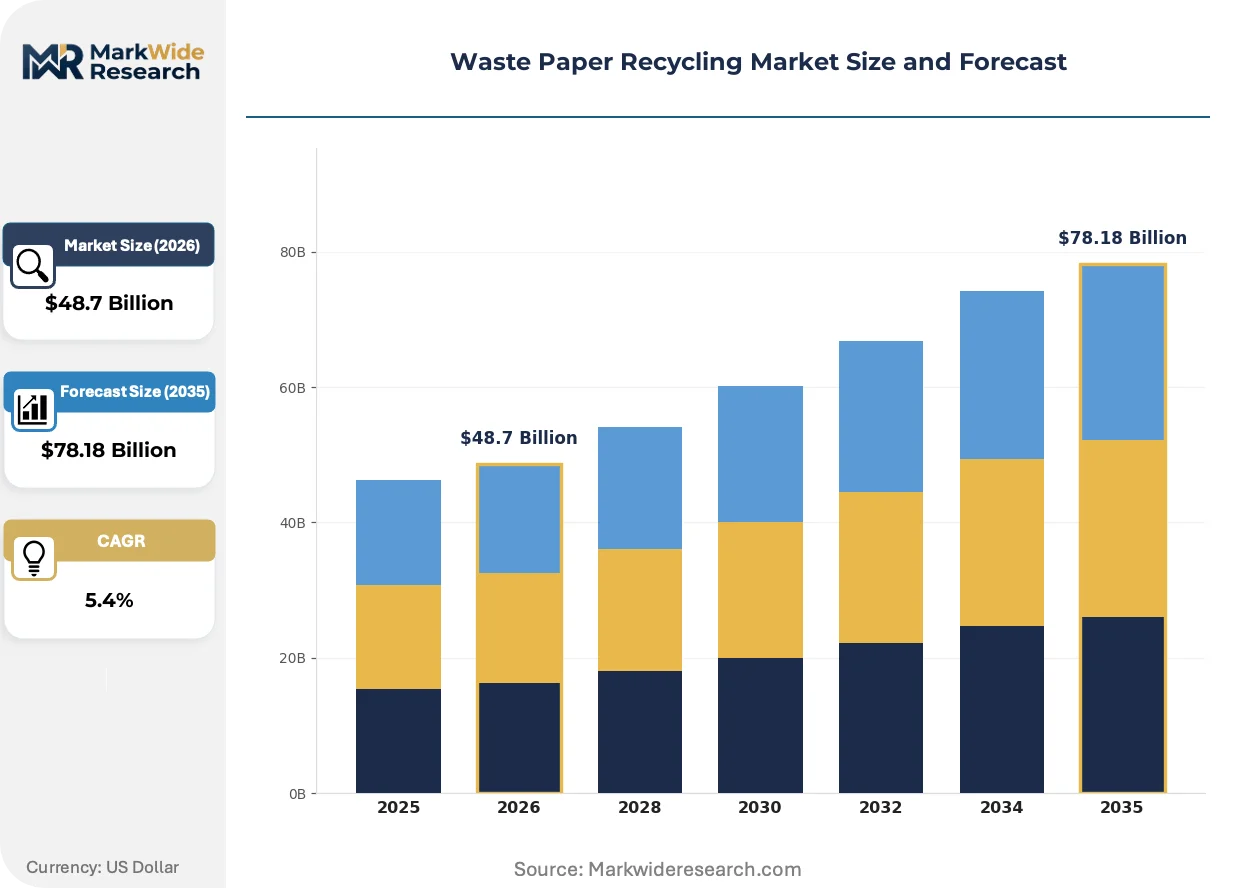
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $78.18 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Office Paper, Newspaper, Cardboard, Mixed Paper, Kraft Paper Technology: Mechanical Recycling, Chemical Recycling, Thermal Treatment, Deinking, Sorting Automation End User: Pulp & Paper Manufacturers, Packaging Companies, Printing Firms, Textile Producers Distribution Channel: Direct Sales, Wholesalers, Online Marketplaces, Recycling Centers |
| Companies Covered | Sonoco Recycling, ST Paper Resources, Waste Management, Hanna Paper Recycling, Cascades Recovery, Republic Services, Remondis, Pratt Industries, Veolia Environment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Paper Recycling Market Strategic Shifts & Innovations
The market's evolution is defined by a technological push toward automation and purity, transforming waste paper from a low-cost commodity into a specified industrial input. This shift is reinforced by regulations that mandate circularity and corporate sustainability goals that require verifiable recycled content.
Advanced optical sorting, often enhanced with artificial intelligence, identifies and separates different paper grades and contaminants with high precision. Material recovery facilities (MRFs) are adopting this technology to improve the quality of their output bales. This automation is consolidating the value of specific waste streams, enabling processors to produce cleaner feedstock that meets the stringent requirements of paper mills.
China's "National Sword" policy, which imposed strict contamination limits on imported recyclables, has had a profound impact. It effectively closed a primary export market, forcing waste-generating regions like North America and Europe to either landfill more material or invest heavily in domestic processing capabilities. The containerboard and mixed paper segments were most affected, spurring the development of new mills in the US and new export destinations in Southeast Asia.
A notable behavioral shift is occurring as major consumer packaged goods companies and retailers make public commitments to recycled content targets. This changes procurement from a purely cost-based decision to one driven by sustainability verification, creating demand for certified recycled fiber. This trend is most pronounced in the European and North American food, beverage, and personal care packaging sectors.
Waste Paper Recycling Market Segmentation
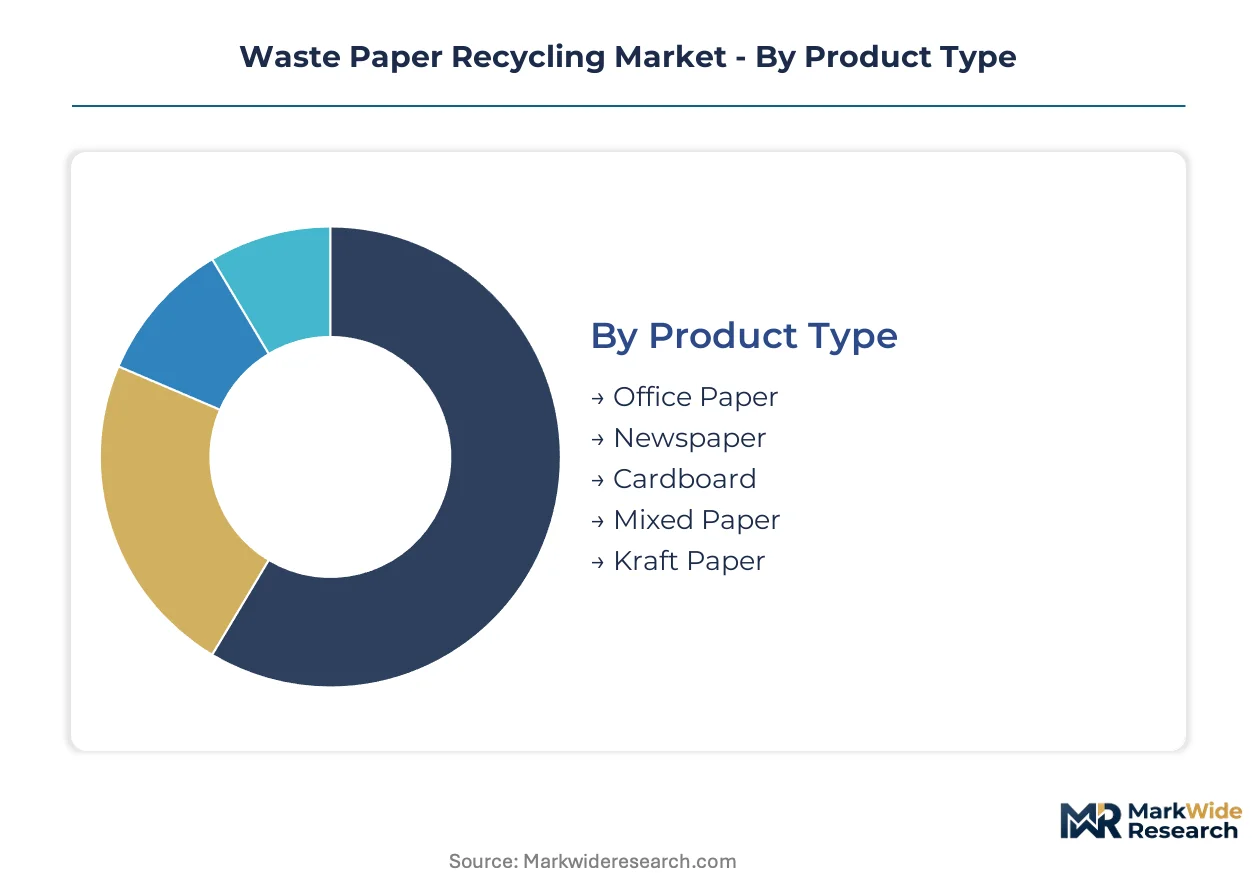
The waste paper recycling market segments reflect diverse material characteristics, processing technologies, and end-user demands. Understanding these distinctions is critical for allocating capital investment efficiently and optimizing recovery infrastructure. Each segment possesses unique requirements for collection, sorting, and conversion into viable secondary fiber.
Product Type:
Capital investment in processing infrastructure often prioritizes product types that offer high volume or premium quality. The varying fiber lengths and contamination levels across paper grades dictate the specific machinery and deinking capacity required for effective recycling.
- Cardboard:This segment comprises corrugated containers and paperboard, characterized by long, strong fibers suitable for new packaging. E-commerce expansion drives consistent, high-volume demand from containerboard manufacturers globally, especially in North America and Southeast Asia.
- Office Paper:Consisting of high-quality, short-fiber paper, this stream yields premium pulp suitable for graphic and tissue paper production. Demand concentrates in regions with robust printing industries and high consumer tissue consumption, driven by the need for brightness and cleanliness.
- Newspaper:Primarily groundwood pulp, this material has shorter fibers and higher ink content, making it suitable for newsprint and some tissue applications. Municipal collection programs provide a steady supply, though demand fluctuates with the decline of print media.
- Mixed Paper:This category includes various low-grade paper types, often with higher contamination levels, requiring extensive sorting and cleaning. It serves as a feedstock for lower-grade paper products, particularly in markets with less stringent quality requirements.
- Kraft Paper:Known for its strength, unbleached kraft paper is valued for packaging applications, including grocery bags and multiwall sacks. Its long fibers make it desirable for applications where strength and durability are paramount.
Cardboard absorbs the bulk of installed capacity; Office Paper is expanding most quickly.
Technology:
Technological advancements drive efficiency and purity across the recycling value chain. Each technology requires specific capital outlays and operational expertise, with newer methods focusing on maximizing material recovery and minimizing environmental impact.
- Deinking:This chemical and mechanical process removes inks, coatings, and contaminants from recovered paper, producing brighter, cleaner pulp. Investment in advanced flotation and washing deinking systems is critical for producing high-quality graphic and tissue papers.
- Sorting Automation:Utilizing optical sensors, artificial intelligence, and robotics, this technology identifies and separates different paper grades and contaminants. Modern material recovery facilities increasingly deploy automated sorting to improve output quality and reduce labor costs.
- Mechanical Recycling:This involves physically breaking down paper fibers into pulp through shredding, pulping, and screening without significant chemical alteration. It is a fundamental process for most waste paper streams, particularly for corrugated cardboard.
- Chemical Recycling:Emerging technologies in this segment involve using solvents or other chemical processes to break down paper fibers at a molecular level. This method targets highly contaminated or mixed paper streams, converting them into new cellulose-based products.
- Thermal Treatment:While less common for direct paper recycling, thermal processes like gasification can convert non-recyclable paper waste into energy or chemical feedstocks. This serves as an end-of-life solution for residual materials, particularly in regions lacking other disposal options.
The market for advanced sorting automation is expanding, driven by stringent quality standards. Deinking technology is a critical investment for producing premium recycled pulp.
End User:
The end-user segments dictate the quality specifications and volume requirements for recycled paper pulp, influencing investment decisions in upstream processing. Each industry integrates recycled fiber differently based on product standards and cost structures.
- Pulp & Paper Manufacturers:These companies convert recycled fiber into various paper products, including containerboard, newsprint, and printing and writing papers. They represent the largest demand segment, requiring consistent, high-quality feedstock to maintain production cycles.
- Packaging Companies:This segment uses recycled paper to produce corrugated boxes, folding cartons, and other protective packaging solutions. Demand is strong due to corporate sustainability goals and consumer preference for eco-friendly packaging materials.
- Printing Firms:These businesses utilize recycled content in graphic papers for magazines, brochures, and other printed materials. They seek high-brightness, deinked pulp to ensure print quality and meet environmental certifications.
- Textile Producers:A niche but growing application, recycled cellulose fibers from paper can be processed into textile fibers. This innovative use case offers a circular solution for paper waste, particularly in the fashion industry.
Pulp & Paper Manufacturers represent the primary off-takers for recycled pulp. Demand from Packaging Companies is significantly influencing feedstock quality requirements.
Distribution Channel:
The distribution channels determine the flow of recovered paper from generation points to processing facilities. Investment in logistics and collection infrastructure is crucial for securing a consistent and cost-effective supply of raw materials.
- Recycling Centers:These facilities serve as collection points for residential and commercial waste paper, sorting and baling materials for further processing. Municipal programs and private operators manage these centers, which are fundamental to the supply chain.
- Direct Sales:Integrated producers and large collectors often sell recovered paper directly to paper mills or processing plants, bypassing intermediaries. This channel emphasizes long-term contracts and consistent supply partnerships.
- Wholesalers:These intermediaries aggregate smaller volumes of recovered paper from various sources and sell them to larger mills or exporters. Wholesalers play a critical role in consolidating supply and managing logistics across fragmented collection networks.
- Online Marketplaces:Digital platforms facilitate the buying and selling of recovered paper, connecting suppliers and buyers more efficiently. These marketplaces introduce greater transparency and price discovery into the trade of recycled materials.
Recycling Centers form the backbone of local collection infrastructure. Direct Sales are increasingly favored by large-scale producers seeking supply chain control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Southeast Asia, such as those in Vietnam and India, are becoming focal points for new waste paper processing investments. These zones attract capital due to favorable trade policies and a growing regional demand for recycled fiber. This concentration of capacity is reshaping global supply chains for recovered paper.
United States
Demand for containerboard from e-commerce drives significant collection of used corrugated containers. US EPA guidelines influence municipal collection programs and recycling standards. New paper mills are expanding capacity across states like Georgia and Wisconsin to process domestic feedstock.
Germany
The EU Green Deal mandates recycled content targets for packaging materials, stimulating demand for recovered paper pulp. Germany's robust circular economy policies promote high collection and sorting rates. The Rhine-Ruhr region, a major industrial cluster, houses advanced deinking and pulping facilities.
India
Packaging industry expansion creates strong demand for sustainable inputs, particularly corrugated cardboard. India's PLI scheme and other industrial policies support domestic manufacturing and recycling infrastructure. Gujarat and Maharashtra are emerging as key processing hubs for waste paper.
Vietnam
Manufacturing industries require consistent recycled fiber supply, attracting foreign investment in processing. The Vietnamese government provides incentives for green investments and sustainable industrial development. Ho Chi Minh City and its surrounding provinces are witnessing the establishment of new paper recycling plants.
China
Domestic demand for recycled content is increasing following stringent import quality standards. China's dual carbon goals and environmental protection policies drive investments in local processing. The Yangtze River Delta region, with its dense industrial base, focuses on high-quality domestic paper recycling.
Waste Paper Recycling Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the waste paper recycling market. The industry exhibits a tiered structure, from large integrated waste management companies to smaller, specialized processors. Strategic archetypes include vertically integrated fiber producers, pure-play recycling technology providers, and regional collection network operators. Companies are pursuing geographic expansion and advanced sorting technology investments to secure feedstock and enhance output quality.
Within the integrated waste management sector, Waste Management exemplifies a model leveraging extensive collection networks to secure consistent feedstock volumes across North America. Veolia Environment, a French multinational, occupies a position focused on advanced sorting technologies and resource optimization to maximize recovery rates from complex mixed streams globally. Pratt Industries, an Australian-owned company with significant US operations, represents a vertically integrated, closed-loop system, directly converting collected paper into new corrugated packaging materials for regional markets. These entities anchor different aspects of the recycling value chain, from raw material aggregation to finished product manufacturing.
| Leading Market Players |
|---|
| Sonoco Recycling |
| ST Paper Resources |
| Waste Management |
| Hanna Paper Recycling |
| Cascades Recovery |
| Republic Services |
| Remondis |
| Pratt Industries |
| Veolia Environment |
| Others |
Cost & Logistics Intelligence
Advanced optical sorting, a key technology shift, simultaneously reshapes cost economics by reducing manual labor and concentrates supply by enabling higher-purity output from specific material recovery facilities.
Pricing Analysis
Volume-based contracts for mixed paper often yield lower margins, while premium-grade sorted office paper commands higher prices. Pricing models largely involve commodity spot pricing for lower grades and contract-based long-term offtake for high-volume, consistent streams. Price differentiation stems from fiber quality, such as brightness for graphic papers, and geographic delivery costs. Pricing softness reflects competition from virgin wood pulp in some packaging applications. Packaging companies are highly price-sensitive for bulk corrugated, while tissue manufacturers prioritize quality.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns define the logistical flow of recovered paper from collection to processing facilities. Geographic supply concentration is shifting from China to emerging hubs like India and Vietnam. The market depends on consistent supplies of used corrugated containers and sorted office paper. Regulatory restrictions, such as import bans, represent a significant structural risk. Direct sales and wholesalers form the dominant downstream distribution structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
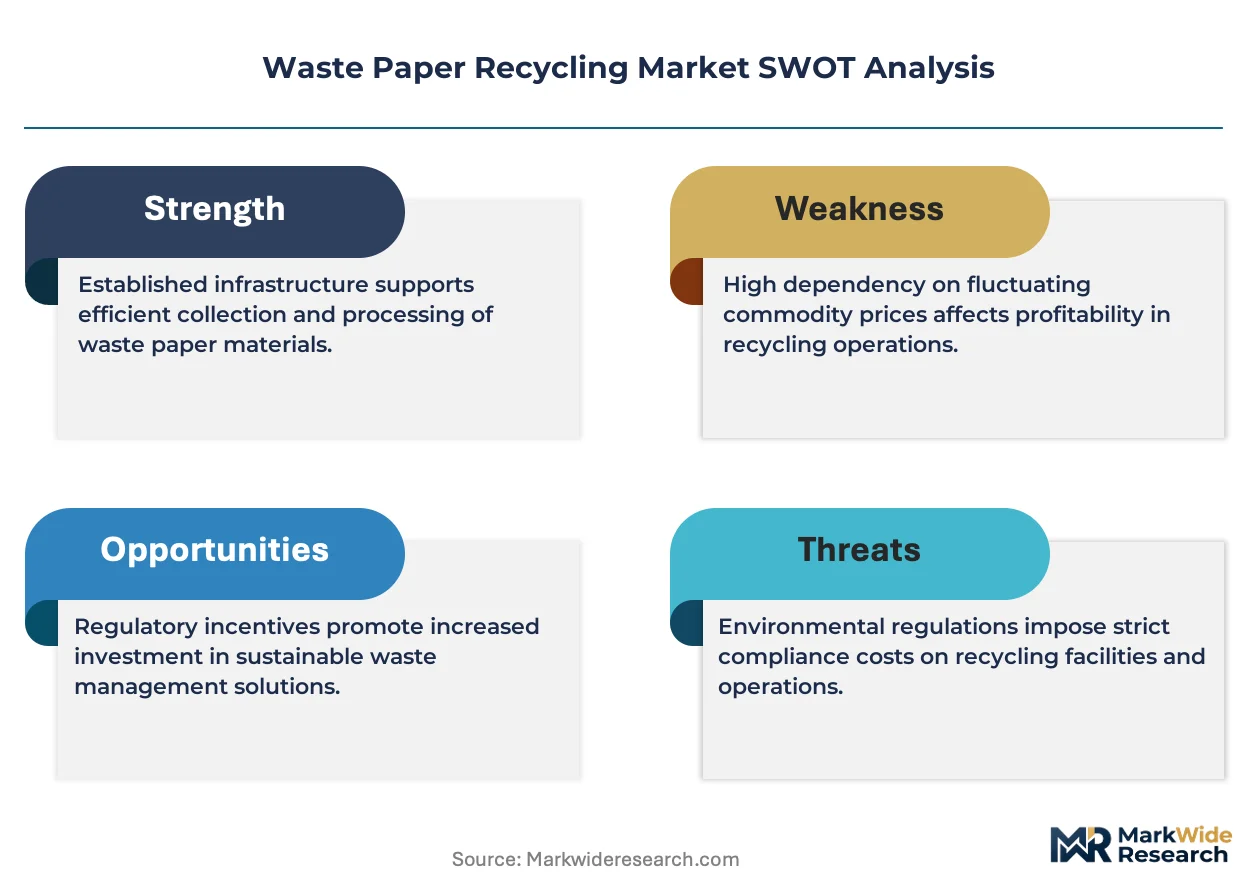
The waste paper recycling market presents a supply-constrained narrative, with limited advanced deinking capacity in emerging regions propping up pricing for premium pulp.
For Market Incumbents: Extend collection networks into new municipal and commercial streams to secure consistent feedstock volumes. Invest in advanced sorting technologies to mitigate feedstock contamination, a persistent threat to fiber quality. Pursue capacity additions in Southeast Asia to leverage growing regional manufacturing demand. Backward integration into packaging production offers a lever for supply chain control.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for new entrants focusing on high-recycled content packaging solutions. Target unaddressed regional demand for high-grade pulp in countries like India, establishing processing hubs. Focus on chemical recycling technologies for mixed paper streams, a highly penetrable segment. A go-to-market angle involves offering certified, traceable recycled fiber to sustainability-conscious brands.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated processors that control both feedstock sourcing and advanced pulping capacity. Long-term viability hinges on sustained demand for circular economy inputs over the next decade. Acquisition targets include specialized technology providers in optical sorting and deinking. A signal to watch is the widespread adoption of Extended Producer Responsibility legislation in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Optical Sorting | Improves fiber purity and recovery rates from mixed waste streams. |
| Expand Processing Capacity in Southeast Asia | Captures growing regional demand and reconfigures global trade flows. |
| Develop High-Grade Deinking Facilities | Enables production of premium pulp for graphic and tissue papers. |
| Secure Long-Term Feedstock Contracts | Ensures consistent supply and mitigates collection rate volatility for mills. |
| Form Strategic Partnerships with E-commerce Giants | Guarantees a steady supply of used corrugated containers for recycling. |
Research Approach
US EPA guidelines, EU Green Deal mandates, and national trade statistics formed the secondary backbone for market sizing and trend analysis. This analysis combined insights from primary interviews with recycling facility managers, pulp & paper procurement leads, and regulatory affairs specialists. Bottom-up data aggregation and top-down market validation ensured comprehensive coverage across the value chain.
Historical trendline analysis established baseline market performance and informed projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, end user, and regional processing capacity. Compound annual growth rates were derived from a multi-factor regression model incorporating e-commerce growth rates and recycled content targets.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling would alter the outlook for mixed paper streams. Forecasts reflect assumptions regarding geopolitical trade policies and virgin fiber price volatility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Household Composters Market