
 Landfill Gas Market | 2026-2036
Landfill Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Landfill Gas Market Analysis
High-BTU upgrading to pipeline-quality biomethane is bifurcating project economics between electricity-only and renewable natural gas pathways. Waste Management Inc leverages its vertically integrated landfill portfolio to control feedstock access across North American sites. Veolia Environnement S.A. sustains operational scale through long-term municipal contracts in France and the United Kingdom. Republic Services Inc anchors its competitive position by specializing in landfill gas collection infrastructure at closed and active sites.
Landfill gas consists of methane and carbon dioxide produced by anaerobic decomposition of organic waste, typically containing 45-55% methane by volume with balance CO2, nitrogen, and trace compounds. Gas utilization technology dominates installed capacity, while combined heat and power configurations capture margin pools through dual revenue streams from electricity and thermal offtake. Electrical generation applications lead deployment volumes, though vehicle fuel and cogeneration segments are expanding as renewable natural gas infrastructure matures.
The EPA enforces New Source Performance Standards under the Clean Air Act, mandating landfill gas collection and control systems at designated facilities, while state renewable portfolio standards create compliance-driven offtake demand. OSHA and state environmental agencies regulate worker exposure and emissions monitoring protocols, shaping operational cost structures. Stakeholders must monitor evolving renewable natural gas certification standards and interstate pipeline injection rules to assess project bankability.
Market Dynamics
EPA New Source Performance Standards mandate landfill gas collection at municipal facilities, compressing compliance timelines and forcing capital deployment into collection infrastructure across the United States. This regulatory pressure is restructuring project economics toward high-BTU upgrading pathways.
Growth Catalysts
- Renewable Portfolio Standards:State-level mandates in California, New York, and Texas create guaranteed offtake demand for landfill gas-derived electricity, securing long-term revenue visibility for project developers.
- Pipeline Injection Rules:FERC Order 636 and interstate pipeline tariff reforms enable biomethane producers to access wholesale natural gas markets, expanding revenue potential beyond captive electricity sales.
- Baseload Renewable Supply:Power generation utilities prioritize landfill gas for grid stability, as its continuous output contrasts with intermittent solar and wind resources.
Market Restraints
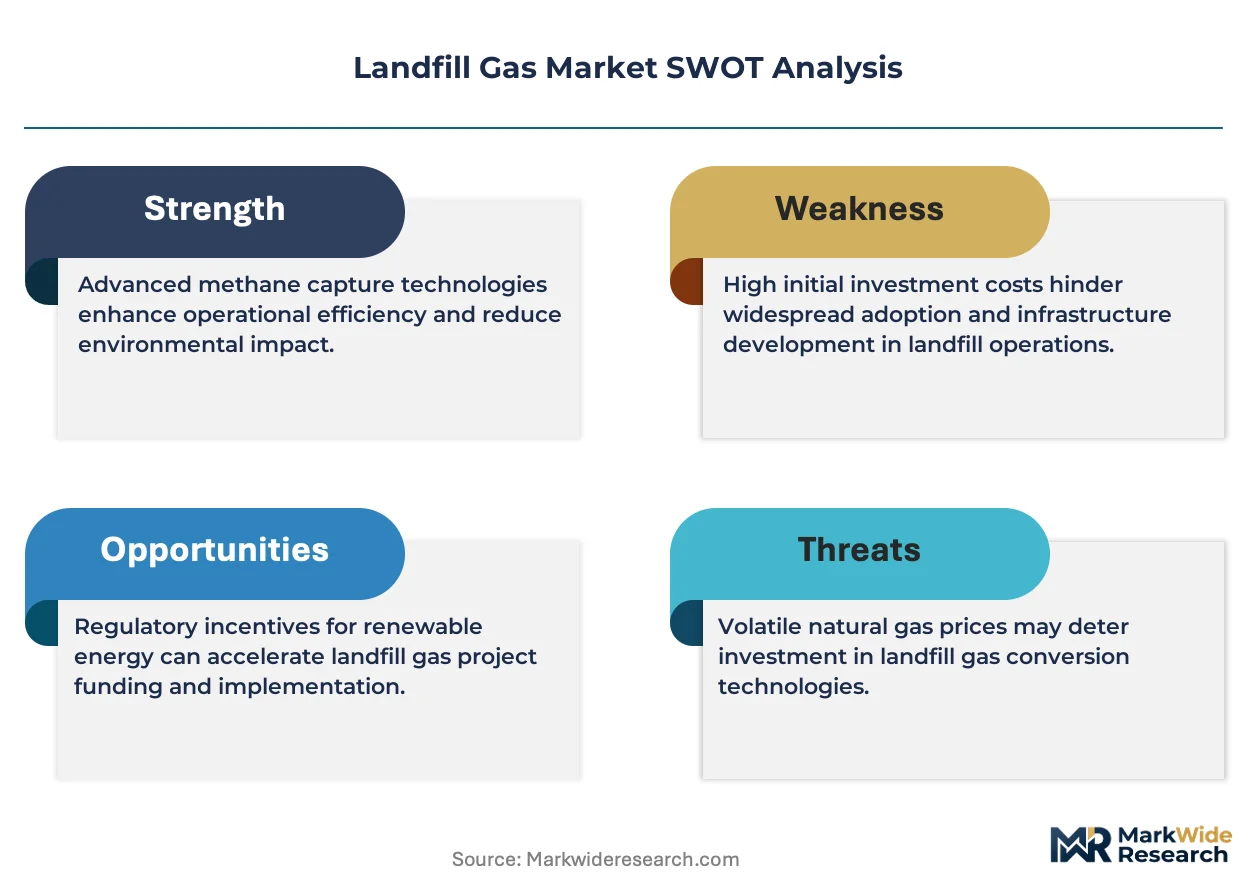
- Siloxane Contamination:Trace silicon compounds in landfill gas degrade combustion equipment, requiring costly pretreatment systems that erode project returns at smaller-scale facilities.
- Feedstock Concentration:Waste Management Inc and Republic Services Inc control access to the majority of high-volume United States landfill sites, limiting independent developer entry.
- Natural Gas Price Volatility:Henry Hub price fluctuations compress biomethane upgrading margins when pipeline-quality gas benchmarks drop below production breakevens.
Strategic Opportunities
- RNG Vehicle Fuel:California Low Carbon Fuel Standard credits create premium pricing for biomethane dispensed at compressed natural gas stations serving heavy-duty trucking fleets.
- Closed Landfill Rehabilitation:Post-closure care obligations at United States Superfund and state-regulated sites create public-private partnership structures for gas-to-energy retrofits.
- Combined Heat and Power:Industrial thermal offtake agreements with food processing and district heating systems capture dual revenue streams unavailable to electricity-only configurations.
Industry Challenges
- Emissions Monitoring Expertise:Continuous methane leak detection and reporting requirements under EPA Greenhouse Gas Reporting Program strain technical staffing at smaller operators.
- Interconnection Queues:Utility grid upgrade timelines delay project energization, extending capital deployment periods and financing costs for independent power producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landfill Gas Market |
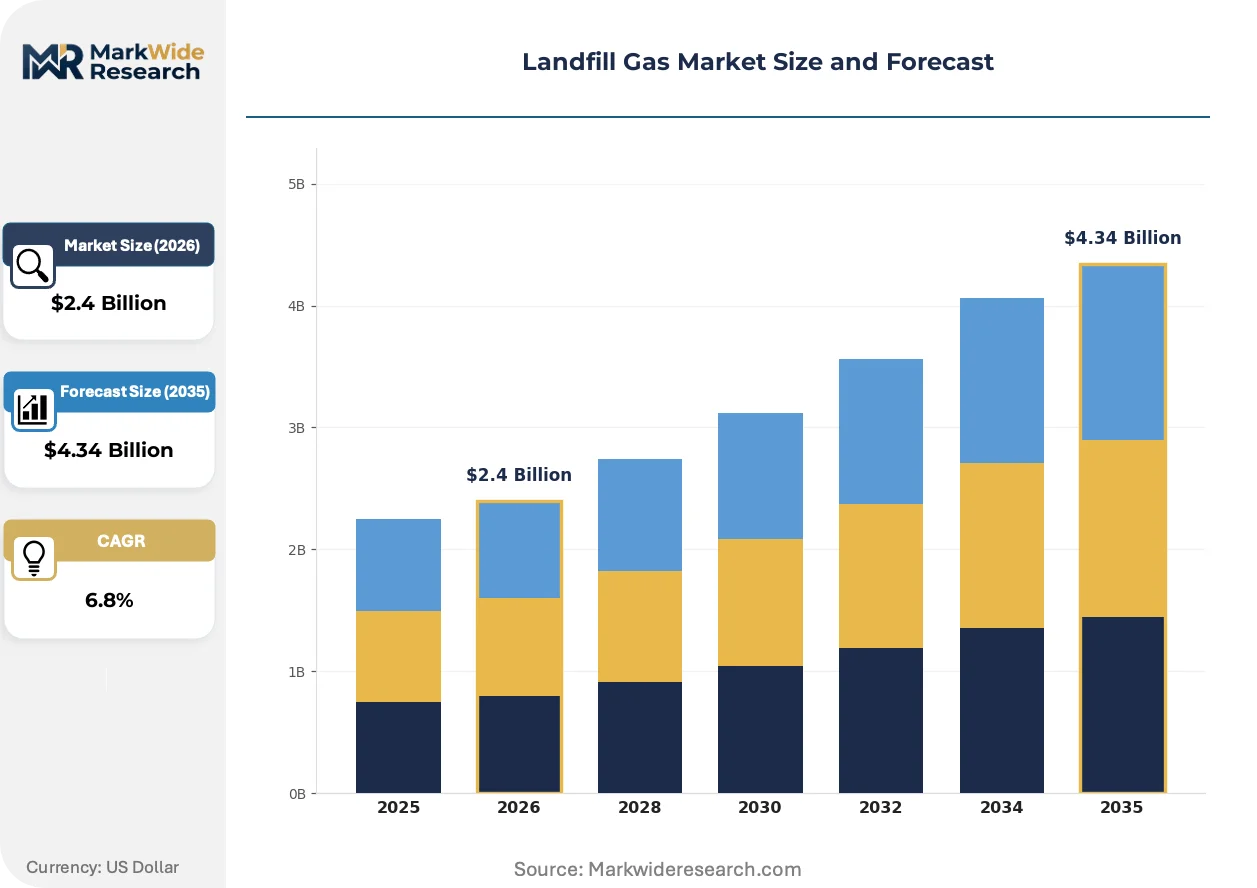
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Utilization, Flare System, Combined Heat and Power, Landfill Gas Collection End User: Power Generation, Industrial Heating, Renewable Energy Projects, Waste Management Facilities Deployment: On-site Generation, Utility Supply, Off-site Processing, Remote Monitoring Application: Electrical Generation, Thermal Energy, Vehicle Fuel, Cogeneration |
| Companies Covered | Waste Management Inc, Veolia Environnement S.A., SUEZ SA, Covanta Holding Corporation, Pennon Group Plc, Aria Energy Corp, Biffa Plc, Republic Services Inc, Energy Developments Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landfill Gas Market Emerging Trajectories
Membrane separation technology is displacing pressure swing adsorption as the dominant landfill gas upgrading method, reducing energy intensity and capital requirements for biomethane production. This shift is compressing project payback periods and expanding economically viable site scales.
Pressure swing adsorption systems historically dominated high-BTU upgrading, using molecular sieves to separate methane from carbon dioxide. Mid-scale landfill gas developers in the United States are now adopting hollow-fiber membrane modules for their modular footprint and lower maintenance burden. Membrane separation is displacing legacy upgrading hardware across projects below five million standard cubic feet per day capacity, enabling distributed RNG production at previously subeconomic sites.
The EPA's Renewable Fuel Standard pathway qualification process for landfill gas-derived cellulosic biofuel is tightening documentation requirements for feedstock traceability and lifecycle emissions accounting. This regulatory evolution forces project developers to implement blockchain or centralized database tracking systems for gas origin verification. California and Oregon clean fuel programs are most affected, as their credit markets require RFS-compliant certification for interstate biomethane transfers.
Long-term offtake contracting is replacing merchant power sales as the dominant revenue model for landfill gas-to-energy projects. Independent power producers now prioritize 15-20 year power purchase agreements with investment-grade utilities over spot market exposure. This preference shift is most visible in Texas and the PJM Interconnection, where renewable energy credit banking rules favor contracted capacity over speculative development.
Landfill Gas Market Segmentation
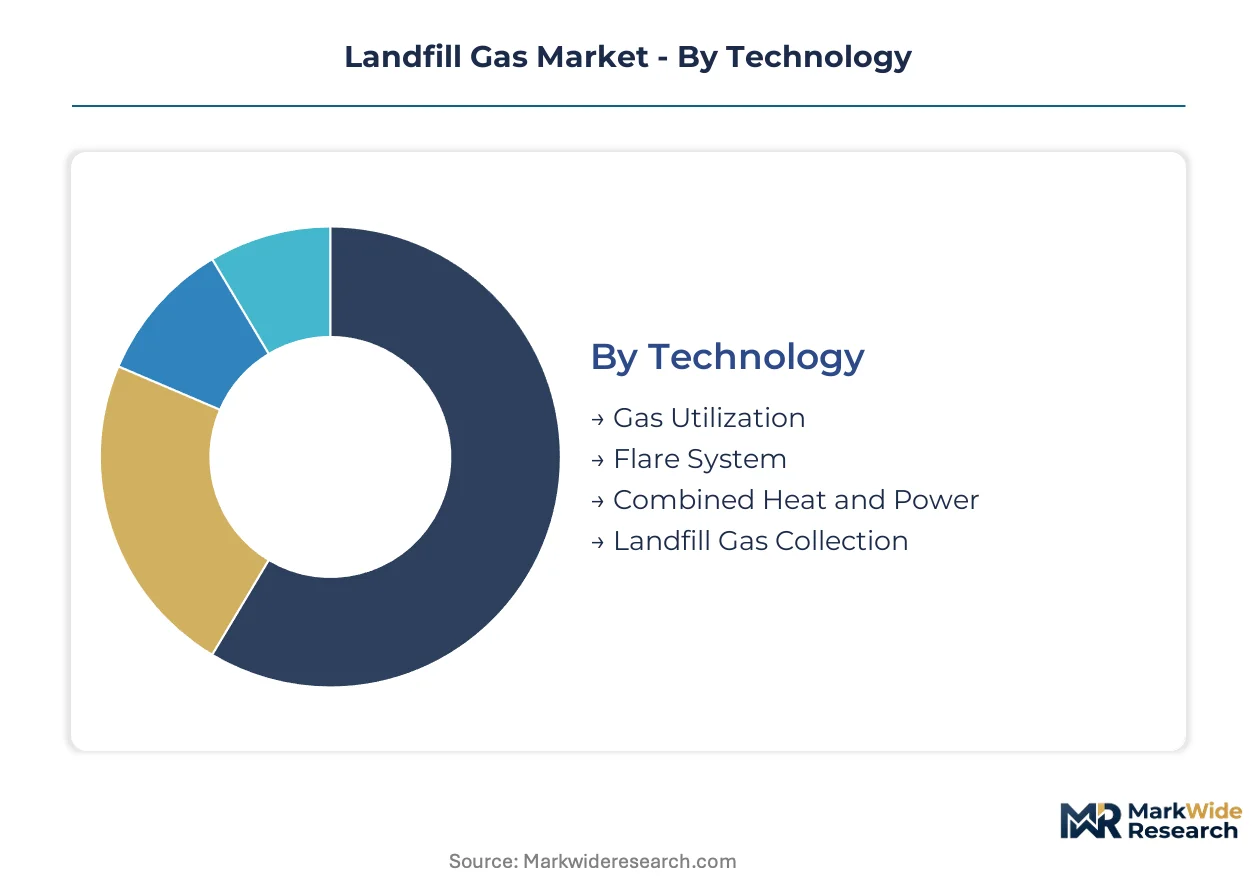
Technology pathways diverge sharply in capital intensity and revenue potential across landfill gas markets. End-use applications face distinct competitive pressures from solar, wind, and grid-scale battery storage alternatives.
Technology:
Gas Utilization and Combined Heat and Power configurations face mounting substitution pressure from standalone solar-plus-storage hybrids that undercut baseload pricing in deregulated markets.
- Gas Utilization:Systems combust landfill gas in internal combustion engines or turbines to generate electricity, typically achieving 25-35% electrical conversion efficiency. Demand concentrates at United States municipal landfills serving baseload power purchase agreements with regional utilities, driven by EPA New Source Performance Standards compliance mandates that require active gas destruction or beneficial use.
- Combined Heat and Power:Cogeneration configurations capture waste thermal energy for industrial process heat or district heating, pushing total system efficiency above 80%. Deployment clusters near food processing plants and institutional heating loads in the Upper Midwest, where thermal offtake agreements provide revenue stability unavailable to electricity-only projects.
- Flare System:Open-flare and enclosed-flare systems destroy methane without energy recovery, serving compliance-only installations where power grid interconnection proves economically unviable.
- Landfill Gas Collection:Wellfield infrastructure and blower stations extract gas from waste mass, representing the foundational capital layer upon which all downstream utilization depends.
Gas Utilization retains volume leadership; Combined Heat and Power holds the steepest expansion curve as industrial thermal offtake markets mature.
End User:
Cost tier differentiation separates premium renewable energy credit-eligible offtake from baseline compliance-driven demand.
- Power Generation:Investor-owned utilities and independent power producers purchase landfill gas-derived electricity under long-term contracts, prioritizing capacity factors above 90% to offset renewable portfolio standard obligations. Procurement concentrates with California and Texas utilities facing aggressive decarbonization timelines.
- Industrial Heating:Food processors, cement manufacturers, and district heating operators purchase thermal energy or pipeline-injected biomethane, capturing carbon intensity reductions for product certification and export compliance.
- Renewable Energy Projects:Developer-led initiatives aggregate multiple revenue streams—electricity sales, renewable thermal certificates, and low-carbon fuel standard credits—at greenfield landfill gas-to-energy installations.
- Waste Management Facilities:Landfill operators self-consume gas for site power and leachate evaporation, reducing operational expenditures and regulatory exposure at closed and active disposal sites.
Power Generation commands the largest installed base; Industrial Heating is climbing the fastest as thermal electrification accelerates manufacturing decarbonization mandates.
Deployment:
Application maturity dictates whether projects anchor at source or pursue distributed processing economics.
- On-site Generation:Electricity production at landfill boundary minimizes interconnection costs and land use conflicts, dominating the United States project pipeline where transmission queue delays stretch 3-5 years.
- Utility Supply:Pipeline-quality biomethane injection requires high-BTU upgrading and compressor stations, unlocking wholesale natural gas market access but demanding capital commitments above $10 million per project.
- Off-site Processing:Mobile upgrading units and virtual pipeline deliveries serve dispersed landfill clusters, aggregating subeconomic gas volumes into truckable compressed natural gas for vehicle fuel markets.
- Remote Monitoring:SCADA and IoT sensor networks enable predictive maintenance and emissions leak detection, reducing labor intensity at geographically isolated wellfields.
On-site Generation maintains dominant deployment share; Utility Supply is gaining share fastest as interstate pipeline injection rules standardize across FERC jurisdictions.
Application:
Customer type fragmentation separates mass-market electricity from premium transportation fuel segments.
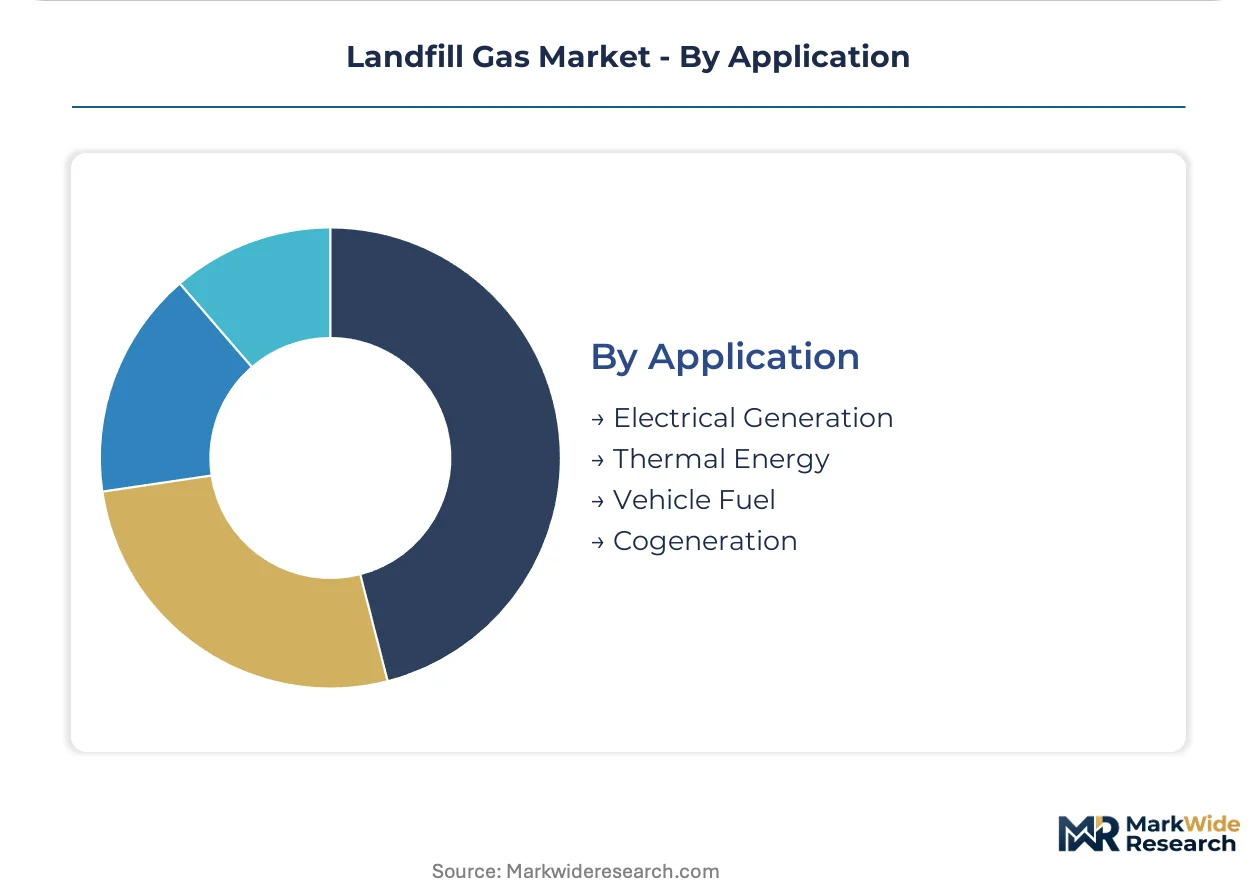
- Electrical Generation:Baseload power sales to grid operators constitute the foundational revenue model, with project returns tied to regional power purchase agreement pricing and renewable energy credit markets.
- Thermal Energy:Direct combustion for industrial process heat bypasses electrical conversion losses, serving energy-intensive manufacturers with combined heat and power configurations or dedicated thermal offtake contracts.
- Vehicle Fuel:Compressed and liquefied natural gas dispensing for heavy-duty trucking fleets commands California Low Carbon Fuel Standard credit premiums, with pricing indexed to diesel and gasoline carbon intensity benchmarks.
- Cogeneration:Simultaneous electricity and thermal production maximizes energy extraction efficiency, anchoring project economics at landfills proximate to industrial parks and district heating infrastructure.
Electrical Generation holds installed capacity leadership; Vehicle Fuel commands the steepest expansion trajectory as renewable natural gas infrastructure scales to serve freight decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in landfill gas-to-energy capacity, exporting biomethane certification expertise and upgrading technology while importing European membrane separation systems. Trade flows concentrate equipment and engineering services rather than physical gas molecules.
United States
EPA New Source Performance Standards mandate gas collection at municipal facilities, compressing compliance timelines and forcing capital deployment into collection infrastructure. State renewable portfolio standards in California and Texas create guaranteed offtake demand for landfill gas-derived electricity. The Midwest industrial corridor hosts dense clusters of combined heat and power installations serving food processing thermal loads.
Germany
The country's national environmental regulator enforces strict landfill closure and post-closure care obligations, extending gas extraction timelines at historical disposal sites. The EEG renewable energy tariff system guarantees feed-in premiums for landfill gas electricity, stabilizing project returns. The Ruhr industrial region rehabilitates closed municipal landfills through public-private partnerships for district heating integration.
United Kingdom
Ofgem's renewable obligation certificate mechanism sustains offtake demand from landfill gas generators facing grid parity pressure. The Environment Agency mandates methane destruction at active and closed landfill sites under pollution prevention and control permits. Greater Manchester and West Midlands urban clusters concentrate operational gas-to-energy capacity at legacy municipal waste sites.
France
ADEME subsidizes high-BTU upgrading installations through its biomethane injection support scheme, expanding pipeline-quality renewable natural gas production. The country's national environmental regulator enforces strict emissions monitoring at landfill facilities under industrial environmental classification rules. The Île-de-France region anchors demand through district heating network integration and compressed natural gas vehicle fueling infrastructure.
China
The Ministry of Ecology and Environment implements methane emission control action plans targeting municipal solid waste disposal sites in major urban agglomerations. Provincial carbon intensity reduction targets incentivize landfill gas capture for power generation at megacity waste facilities. The Yangtze River Delta and Pearl River Delta concentrate project development at high-volume sanitary landfills serving Shanghai, Jiangsu, and Guangdong municipal waste streams.
Landfill Gas Market Vendor Landscape
Concentration sits with vertically integrated waste management conglomerates that control feedstock access across captive landfill portfolios. Three strategic archetypes define competitive positioning: integrated waste-to-energy operators leveraging site ownership, independent gas-to-energy developers securing long-term offtake contracts, and technology providers licensing upgrading and collection systems. Dominant competitive moves include portfolio diversification into renewable natural gas pathways and strategic partnerships with utility offtakers to secure interconnection priority.
Among North American integrated operators, Waste Management Inc and Republic Services Inc exemplify the site-control archetype through captive landfill portfolios that internalize feedstock economics. Veolia Environnement S.A. occupies a position representing the European municipal contract model, anchoring operational scale through long-term public waste management agreements. These three entities sit within distinct geographic footprints—United States domestic concentration versus European transnational coverage—yet converge on the same strategic imperative: converting regulatory compliance obligations into energy revenue streams.
| Leading Market Players |
|---|
| Waste Management Inc |
| Veolia Environnement S.A. |
| SUEZ SA |
| Covanta Holding Corporation |
| Pennon Group Plc |
| Aria Energy Corp |
| Biffa Plc |
| Republic Services Inc |
| Energy Developments Ltd |
| Others |
Supply Flow & Price Mechanics
Collection infrastructure scale economies at United States municipal landfills compress per-unit gas extraction costs below thresholds viable for independent developers, concentrating supply-side pricing power with vertically integrated waste management operators while establishing price floors tied to EPA compliance equipment depreciation schedules.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contracting as the dominant pricing structure, with contract-based power purchase agreements spanning 15-20 years replacing merchant power sales. Price differentiation separates pipeline-quality biomethane from electricity-only pathways, with California Low Carbon Fuel Standard credits and renewable thermal certificates commanding premiums over baseline compliance-driven electricity. Cost compression in smaller-scale upgrading installations is intensifying because membrane separation technology reduces capital intensity for sub-five-million-scfd projects. Municipal utilities facing renewable portfolio standard obligations demonstrate lowest price sensitivity, while independent power producers in deregulated Texas and PJM markets face highest spot-price exposure.
Supply Chain Analysis
Container availability constraints across Asia-Pacific trade lanes elevate inbound logistics costs for hollow-fiber membrane modules manufactured in Japan and South Korea. Manufacturing concentration for landfill gas upgrading equipment centers on Germany, the United States, and China, with European membrane separation systems dominating high-BTU installations. Raw material dependencies include specialized polymer membranes, corrosion-resistant wellhead casings, and precision blower assemblies. Single-source vulnerability concentrates in siloxane removal media suppliers serving pretreatment systems. Distribution runs through engineering-procurement-construction contractors integrating wellfield construction with utility interconnection management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operations and maintenance service contracts represent the fastest-expanding recurring revenue layer, outpacing equipment sales as landfill operators outsource continuous emissions monitoring and predictive wellfield maintenance to specialized vendors.
For Market Incumbents: Fortify captive landfill portfolio control through exclusive gas rights agreements at closed sites facing post-closure care obligations, while deepening backward integration into membrane upgrading manufacturing to capture margin pools threatened by technology commoditization. Prioritize certification investment for EPA Renewable Fuel Standard pathway qualification to secure California and Oregon clean fuel program access. For New Entrants and Emerging Players: Lead with mobile upgrading units and virtual pipeline aggregation serving dispersed landfill clusters below utility interconnection scale, targeting the vehicle fuel segment where California LCFS credit banking creates pricing premiums unavailable to electricity-only competitors. Pursue public-private partnership structures at Superfund-listed closed landfills where rehabilitation obligations offset site access costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors project developers with contracted offtake portfolios and operational scale rather than pure-play technology licensors exposed to equipment margin compression. Five-to-ten-year viability hinges on renewable natural gas infrastructure maturation and interstate pipeline injection rule standardization. Monitor FERC Order 636 tariff reform implementation as the critical inflection signal for biomethane market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| High-BTU Upgrading Capacity Buildout | Pipeline injection access unlocks wholesale natural gas market participation beyond captive electricity sales. |
| Long-term Power Purchase Agreement | Investment-grade utility contracts provide revenue visibility securing project finance at favorable terms. |
| Technology Licensing Partnership | Membrane separation system providers expand addressable market through modular distributed deployment models. |
| Backward Integration into Wellfield Services | Captive operations and maintenance capabilities reduce third-party service dependence and margin leakage. |
| Green Certification Program | EPA RFS pathway qualification enables California LCFS credit monetization for interstate biomethane transfers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with landfill gas project developers, utility power procurement officers, waste management facility directors, and environmental compliance consultants. Secondary validation drew from EPA Greenhouse Gas Reporting Program filings, EIA power generation databases, FERC interstate pipeline tariff records, and state renewable portfolio standard compliance reports. Bottom-up project pipeline aggregation was triangulated against top-down market sizing derived from installed capacity estimates and capacity factor assumptions.
Across the analysis window, volume and value outputs were modeled through segmentation by technology pathway, end-use application, and deployment configuration, with additional dimensioning by state regulatory framework cluster. CAGRs were computed from year-over-year growth rate progression rather than endpoint averaging. Forecast inputs incorporated EPA New Source Performance Standards compliance timeline acceleration, membrane separation technology adoption curves, and renewable natural gas pipeline injection capacity expansion.
Underlying assumptions cover stable federal environmental enforcement continuity and state renewable portfolio standard maintenance, with deviation risk concentrated in natural gas price volatility at Henry Hub and interconnection queue delay extensions beyond current utility timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
Waste Paper Management Market