
 United States Waste to Energy Market | 2026-2036
United States Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United States Waste to Energy Market Analytics
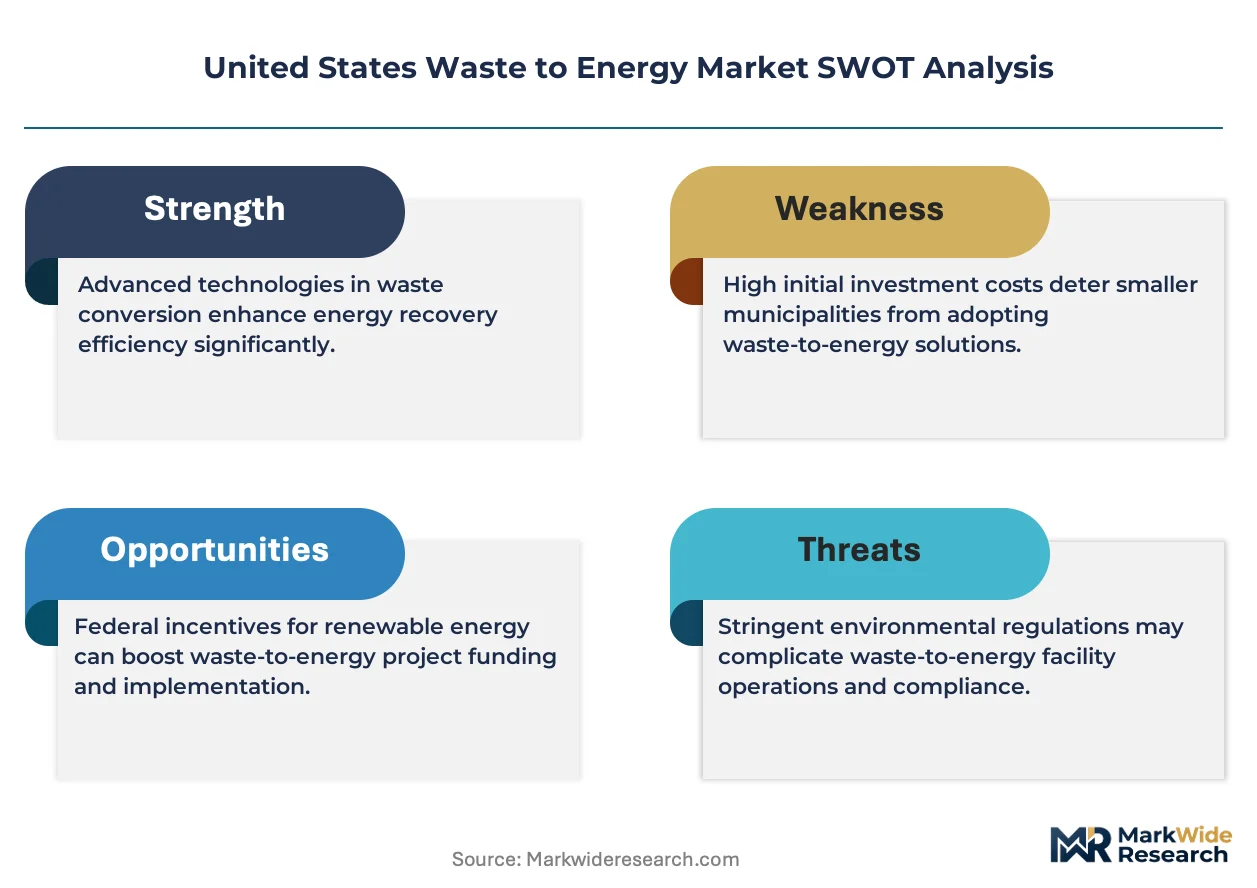
The Inflation Reduction Act is expanding investment eligibility for waste-to-energy infrastructure through enhanced tax credit structures. Covanta Holding Corp leverages its integrated fleet of mass-burn facilities across the Northeast to sustain long-term offtake contracts with municipal buyers. Wheelabrator Technologies Inc anchors its competitive position through specialized energy-from-waste plants serving mid-Atlantic population centers. WIN Waste Innovations differentiates via vertical control over collection-to-generation logistics in New England markets.
Waste to energy encompasses thermal and biological processes that convert municipal solid waste, industrial refuse, and agricultural residues into electricity, heat, or synthetic fuels through controlled combustion, gasification, or anaerobic decomposition at temperatures typically exceeding 850 degrees Celsius for incineration pathways. The primary purpose centers on simultaneous volume reduction of landfill-bound material and dispatchable baseload power generation for grid-connected utilities. Incineration dominates installed capacity due to decades of operational maturity and established emissions control protocols, while anaerobic digestion captures accelerating interest from agricultural feedstock aggregators seeking biogas upgrading pathways. Gasification occupies a specialized niche where industrial waste streams with consistent calorific value support syngas-to-energy configurations.
EPA emissions standards under the Clean Air Act, state-level renewable portfolio standards in California and New York, and OSHA workplace safety protocols collectively shape facility permitting timelines, technology selection, and operational compliance costs for developers. The Department of Energy's research funding for advanced conversion pathways further influences technology migration timelines across the project pipeline. Stakeholders must monitor interconnection queue dynamics and evolving state-level clean energy procurement mandates to align development timelines with offtake opportunities.
Market Dynamics
Landfill diversion mandates in the Great Lakes corridor are forcing municipal utilities to accelerate thermal conversion procurement, while aging coal plant retirements release interconnection-ready sites for waste-to-energy developers.
Growth Catalysts
- EPA Landfill Methane Regulations:The EPA's updated methane emissions rules are compelling waste managers to divert organic material from landfills toward controlled combustion pathways, creating guaranteed feedstock flows for new facilities.
- State Renewable Portfolio Standards:California and New York classify waste-derived power as renewable generation, enabling developers to secure long-term offtake contracts with utilities under mandated procurement schedules.
- Interconnection Queue Priority:Projects sited at retired coal plants in Ohio and Pennsylvania leverage existing transmission infrastructure, bypassing the multi-year queue delays facing greenfield renewable developments.
Market Restraints
- Feedstock Calorific Volatility:Single-stream recycling contamination and seasonal organic waste variation destabilize plant thermal efficiency, requiring costly preprocessing equipment at Midwest facilities.
- Specialized Equipment Concentration:European suppliers dominate combustion grate and emissions control system manufacturing, exposing US developers to euro-denominated procurement risk and extended lead times.
- Air Quality Permitting Friction:The Clean Air Act's Maximum Achievable Control Technology standards impose multi-year approval timelines in non-attainment zones, particularly around Chicago and Detroit metropolitan areas.
Strategic Opportunities
- Agricultural Biogas Upgrading:Dairy operations in Wisconsin and Minnesota are deploying anaerobic digestion with pipeline injection, accessing renewable natural gas premiums through EPA's Renewable Fuel Standard pathway.
- Industrial Waste Syngas:Consistent calorific value from manufacturing byproducts in Texas and Louisiana supports plasma gasification configurations producing hydrogen for regional petrochemical demand.
- Inflation Reduction Act Tax Credits:The IRA's enhanced investment tax credit structure now covers waste-to-energy infrastructure, improving project IRRs for developers targeting 2026-2030 construction windows.
Industry Challenges
- Combustion Engineering Talent Scarcity:Mass-burn facility operators face acute shortages of boiler specialists and emissions control technicians as the skilled trades workforce ages out in the Northeast.
- Legacy SCADA Integration:Retrofitting 1990s-era distributed control systems with modern digital monitoring platforms requires extended outage windows, disrupting baseload power delivery commitments to municipal buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Waste to Energy Market |
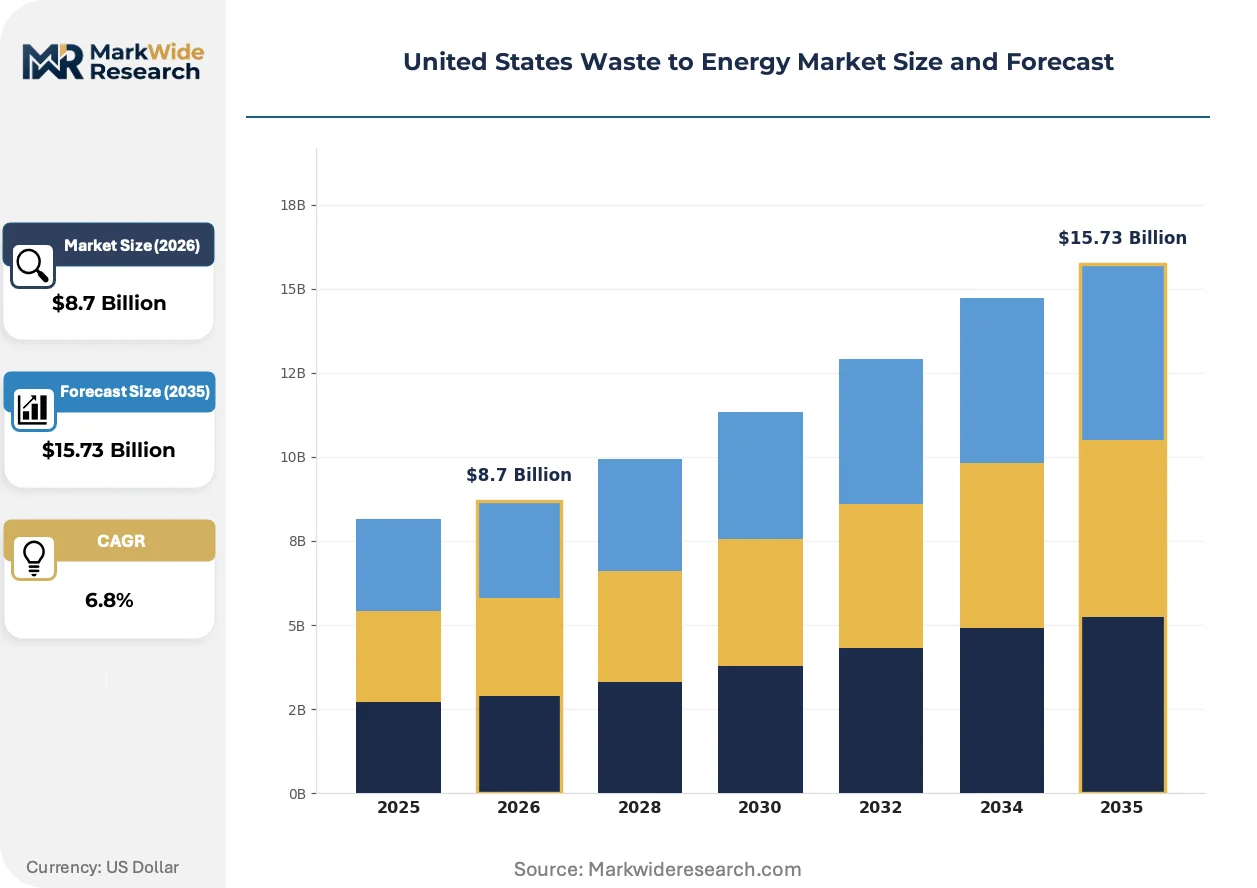
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Gasification, Anaerobic Digestion, Pyrolysis Feedstock Type: Municipal Solid Waste, Agricultural Residues, Industrial Waste, Wood Waste End User: Utilities, Waste Management Companies, Government Agencies, Industrial Facilities Conversion Method: Thermal, Biological, Mechanical, Chemical |
| Companies Covered | Covanta Holding Corp, Wheelabrator Technologies Inc, WIN Waste Innovations, Veolia North America, Waste Management Inc, Montenay International, Babcock & Wilcox Enterprises, Hitachi Zosen Inova, Fulcrum BioEnergy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Waste to Energy Market Evolving Landscape
Advanced conversion technologies are compressing the capital cost gap between incineration and gasification, while digital monitoring platforms enable predictive maintenance that reduces unplanned downtime at thermal facilities.
Plasma gasification is unifying waste destruction with syngas production in a single reactor vessel, eliminating the ash residue volumes typical of grate combustion. Industrial processors in chemical manufacturing corridors are piloting these systems for hazardous waste streams. The technology is compressing permitting timelines by demonstrating near-zero residual waste output to state environmental agencies.
The Inflation Reduction Act's technology-neutral clean electricity tax credit is reclassifying waste-to-energy eligibility alongside solar and wind, altering developer capital stack calculations. Treasury Department guidance on domestic content bonuses is steering equipment procurement toward US-manufactured combustion components. Developers in the mid-Atlantic are restructuring project finance to capture the full 30% investment tax credit before statutory phase-down triggers.
Municipal procurement offices are consolidating waste disposal and power purchase agreements into unified 20-25 year contracts, replacing the historical separation of tipping fee negotiations from energy offtake terms. This bundling is compressing vendor selection cycles and favoring vertically integrated operators with in-house collection fleets. The pattern is most visible in New England, where Hartford and Providence have issued combined RFPs covering waste collection through electricity delivery.
United States Waste to Energy Market Segmentation
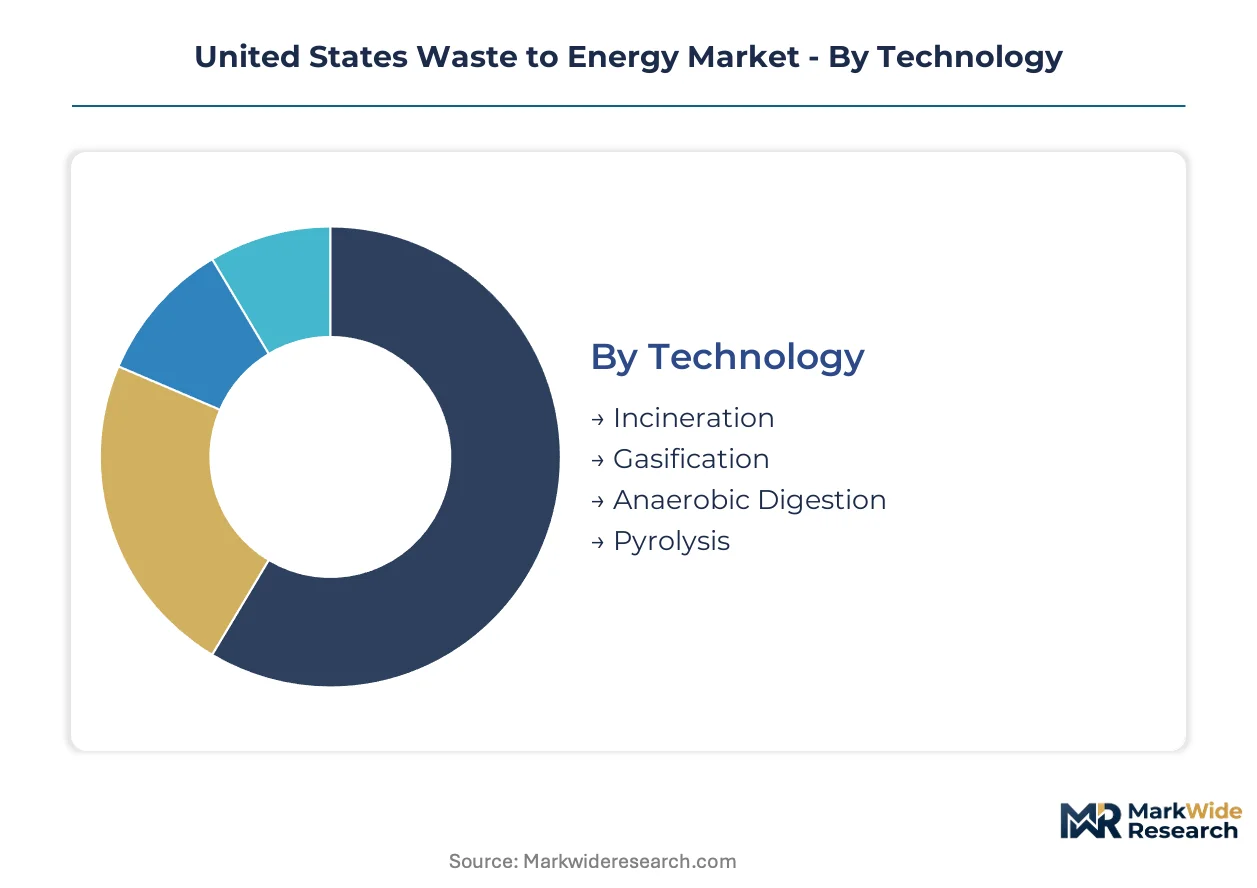
Waste-to-energy developers select technology pathways based on feedstock calorific consistency, permitting complexity, and interconnection readiness. Segmentation reveals how thermal conversion dominates baseload utility contracts while biological processes capture agricultural and distributed generation opportunities.
Technology:
EPA Maximum Achievable Control Technology standards and state air quality permits create divergent compliance burdens across thermal and biological pathways, with incineration facing the most stringent stack monitoring requirements.
- Incineration:Mass-burn facilities combust unsorted municipal solid waste at temperatures exceeding 850 degrees Celsius, generating steam for turbine electricity production. Demand concentrates in the Great Lakes corridor where retired coal plants offer interconnection-ready sites, though Chicago and Detroit non-attainment zones impose multi-year permitting timelines.
- Anaerobic Digestion:Biological decomposition of organic feedstock in oxygen-free digesters produces biogas for upgrading to pipeline-quality renewable natural gas. Wisconsin and Minnesota dairy operations are deploying these systems to access EPA Renewable Fuel Standard premiums, bypassing the air permitting friction facing thermal alternatives.
- Gasification:Partial oxidation converts carbonaceous material into synthetic gas at controlled temperatures, enabling higher electrical efficiency than direct combustion. Industrial waste streams in Texas and Louisiana with consistent calorific value support plasma gasification configurations targeting hydrogen production for regional petrochemical demand.
- Pyrolysis:Thermal decomposition in oxygen-limited environments produces liquid bio-oil, syngas, and char from woody biomass and plastic waste. Pilot facilities in the Northeast are testing residue-free outputs to compress state environmental approval timelines.
Leading the category by volume: Incineration. Expanding most quickly: Anaerobic Digestion.
Feedstock Type:
Calorific consistency and contamination levels determine preprocessing capital requirements and plant thermal efficiency across feedstock categories.
- Municipal Solid Waste:Mixed household and commercial refuse with variable moisture and non-combustible content requires magnetic separation and shredding before thermal conversion. Northeast municipal utilities under landfill diversion mandates are securing long-term supply contracts with guaranteed minimum tonnage commitments.
- Agricultural Residues:Dairy manure, crop residues, and food processing waste with high moisture content suit biological conversion pathways. Minnesota and Wisconsin operations are aggregating feedstock across multi-farm cooperatives to achieve digester scale economies.
- Industrial Waste:Manufacturing byproducts including paper sludge, textile offcuts, and chemical residues offer predictable calorific value. Texas Gulf Coast petrochemical corridors are sourcing consistent streams for syngas-to-hydrogen configurations.
- Wood Waste:Sawmill residues, forest thinnings, and construction debris provide low-moisture, high-BTU feedstock for combustion and pyrolysis. Pacific Northwest timber operations are integrating on-site power generation to offset grid electricity purchases.
Dominant by tonnage processed: Municipal Solid Waste. Gaining share fastest: Agricultural Residues.
End User:
Procurement sophistication and contract duration vary sharply between regulated utilities and decentralized industrial offtakers.
- Utilities:Investor-owned and municipal electric companies under state renewable portfolio standards procure baseload power through 20-25 year power purchase agreements. New England and mid-Atlantic utilities are bundling waste disposal and electricity offtake into unified procurement vehicles.
- Waste Management Companies:Integrated haulers seek vertical control over collection-to-generation logistics to secure tipping fee revenue and avoid landfill capital expenditures. Hartford and Providence have issued combined RFPs covering collection through electricity delivery to favor vertically integrated bidders.
- Government Agencies:Federal, state, and municipal entities prioritize landfill diversion compliance over power revenue maximization. Defense installations and correctional facilities are piloting on-site digestion for food waste streams.
- Industrial Facilities:Energy-intensive manufacturers including cement, steel, and chemical producers pursue captive power generation and process heat applications. Louisiana petrochemical complexes are evaluating syngas integration for hydrogen feedstock substitution.
Contract volume leader: Utilities. Procurement innovation center: Waste Management Companies.
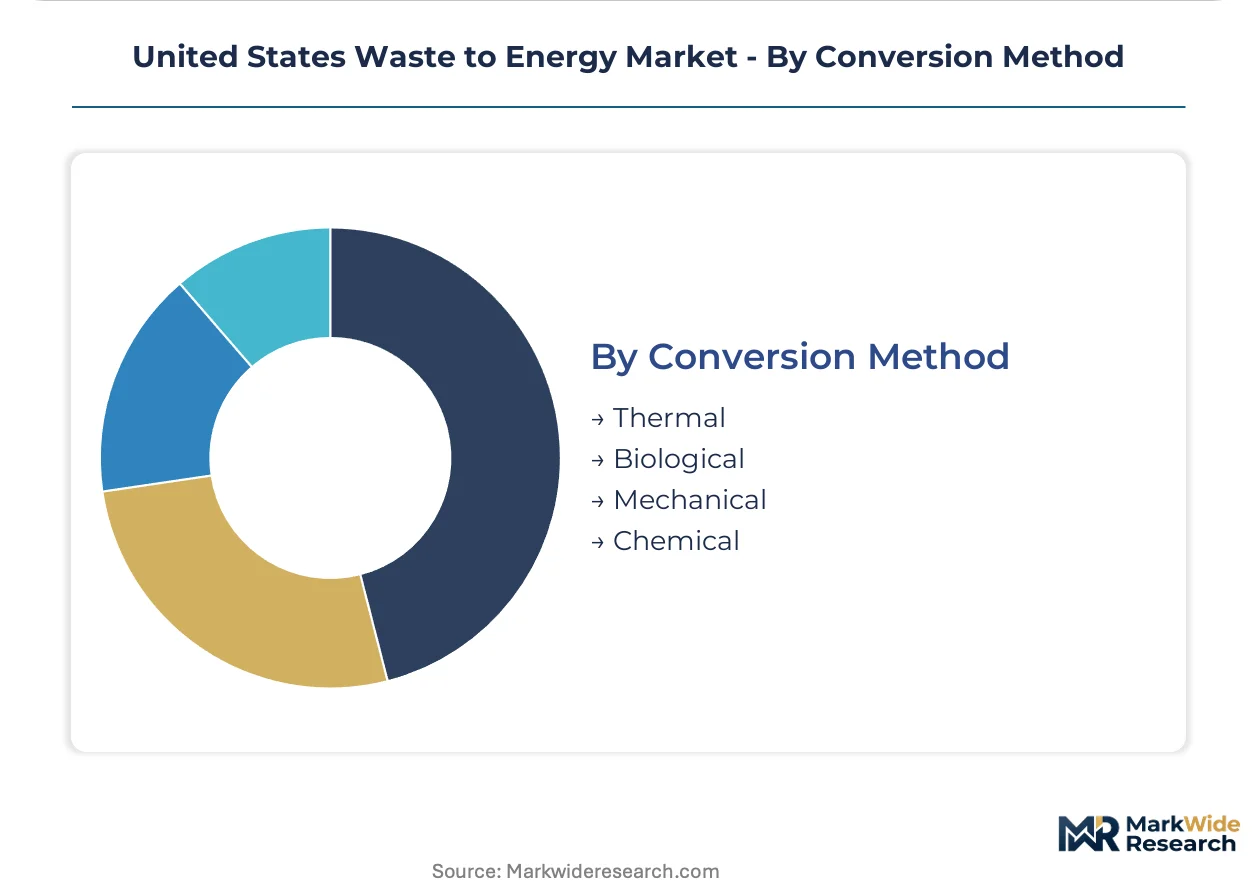
Conversion Method:
Capital intensity and operational complexity stratify across conversion approaches, with thermal methods requiring the highest upfront engineering investment.
- Thermal:Combustion, gasification, and pyrolysis pathways require refractory-lined reactors, emissions control trains, and steam turbine infrastructure. Ohio and Pennsylvania developers leverage existing coal plant balance-of-plant equipment to reduce greenfield capital requirements.
- Biological:Anaerobic digestion and fermentation processes operate at lower temperatures with simpler mechanical systems but require longer residence times and feedstock preprocessing. Wisconsin dairy cooperatives are deploying covered lagoon digesters with pipeline injection infrastructure.
- Mechanical:Densification, sorting, and refuse-derived fuel preparation upgrade waste streams for co-firing or export. Midwest material recovery facilities are expanding RDF production lines to supply cement kiln co-firing contracts.
- Chemical:Solvent extraction, hydrothermal liquefaction, and catalytic upgrading convert waste into liquid fuels and chemical precursors. Research funding from the Department of Energy is accelerating pilot-scale deployment of advanced chemical pathways.
Installed capacity leader: Thermal. Steepest expansion trajectory: Biological.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the Great Lakes corridor and Northeast, while demand concentrates in coastal population centers with landfill diversion mandates. The Midwest generates surplus waste-derived power for export to mid-Atlantic grids.
Great Lakes Corridor
Retired coal plants in Ohio and Michigan provide interconnection-ready sites for thermal conversion projects. EPA landfill methane regulations compel waste managers in Illinois and Indiana to divert organic material toward controlled combustion. Detroit and Cleveland metropolitan areas host aging mass-burn facilities undergoing emissions control upgrades.
Northeast Seaboard
Landfill scarcity in Massachusetts and Connecticut drives procurement of waste-to-energy under state renewable portfolio standards. New York classifies waste-derived power as Tier 1 renewable generation, enabling long-term utility contracts. Hartford and Providence have issued unified RFPs bundling collection and electricity delivery.
Mid-Atlantic
New Jersey and Pennsylvania utilities seek baseload power to replace retiring nuclear capacity. The Inflation Reduction Act's enhanced investment tax credit steers developers toward 2026-2030 construction windows. Philadelphia and Baltimore waste authorities negotiate tipping fee structures tied to wholesale electricity prices.
Southeast
Florida and Georgia municipal utilities pilot anaerobic digestion for food waste streams under emerging state diversion targets. Defense installations evaluate on-site thermal processing for installation resilience. Atlanta and Miami metropolitan areas lack legacy waste-to-energy infrastructure, creating greenfield development opportunities.
Pacific Coast
California's renewable portfolio standard mandates procurement from waste-derived sources, though air quality permitting friction delays new thermal projects. Oregon and Washington timber operations integrate wood waste combustion for captive power generation. Los Angeles and San Francisco waste districts prioritize biological conversion pathways to avoid non-attainment zone complications.
United States Waste to Energy Market Competitive Landscape
The competitive structure tilts toward integrated operators with captive waste collection networks. Three tiers define the landscape: mass-burn facility specialists with decades of operational maturity, biological conversion entrants targeting agricultural feedstock aggregation, and industrial waste processors leveraging consistent calorific streams. Dominant competitive moves include vertical integration into collection logistics and strategic positioning at retired coal plant interconnection sites.
Within the integrated operator tier, Covanta Holding Corp, Wheelabrator Technologies Inc, and WIN Waste Innovations exemplify distinct geographic anchoring strategies. Covanta occupies a position across Northeast mass-burn infrastructure. Wheelabrator Technologies Inc represents mid-Atlantic concentration. WIN Waste Innovations sits within New England markets with collection-to-generation control. These three operators collectively illustrate how municipal procurement bundling favors vertically integrated players with in-house fleet capabilities.
| Leading Market Players |
|---|
| Covanta Holding Corp |
| Wheelabrator Technologies Inc |
| WIN Waste Innovations |
| Veolia North America |
| Waste Management Inc |
| Montenay International |
| Babcock & Wilcox Enterprises |
| Hitachi Zosen Inova |
| Fulcrum BioEnergy |
| Others |
Value Network & Pricing Analysis
EPA landfill methane regulations gate both qualified feedstock supply and premium-tier pricing access for thermal conversion facilities, as compliance-certified operators command tipping fee premiums while non-compliant landfills face diversion mandates that concentrate feedstock flows toward permitted plants.
Pricing Analysis
Long-term power purchase agreement structures anchor pricing to baseload electricity output and guaranteed waste throughput volumes. Three-tier pricing structure across premium, standard, and economy levels separates facilities with advanced emissions control and renewable portfolio standard eligibility from basic compliance-tier operations. Pricing pressure stems from single-stream recycling contamination raising preprocessing costs at Midwest mass-burn plants. Municipal utilities show highest price sensitivity due to ratepayer scrutiny, while industrial captive generators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Refurbishment flows for aging combustion grates and emissions control systems create reverse-logistics demand toward European specialist manufacturers in Germany, Denmark, and the Netherlands. US developers draw from euro-denominated procurement for refractory materials, boiler components, and SCADA control systems. Single-source vulnerability concentrates in combustion grate engineering expertise held by Hitachi Zosen Inova and Babcock & Wilcox. Distribution runs through engineering-procurement-construction contractors with established EPA permitting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock supply constraints from tightening landfill diversion timelines prop pricing power for permitted thermal conversion capacity, creating durable margin structures for qualified operators.
For Market Incumbents: Deepen backward integration into municipal waste collection contracts to lock in guaranteed feedstock tonnage against emerging anaerobic digestion competitors. Secure interconnection queue positions at retired coal plant sites in Ohio and Pennsylvania before greenfield renewable projects crowd transmission access. Prioritize SCADA modernization to reduce unplanned outage penalties in power purchase agreements.
For New Entrants and Emerging Players: Begin with agricultural biogas upgrading in Wisconsin and Minnesota dairy corridors, where EPA Renewable Fuel Standard premiums and lower air permitting friction create faster deployment timelines than thermal alternatives. Target industrial waste syngas configurations in Texas petrochemical corridors with consistent calorific feedstock. Lead with pipeline injection infrastructure partnerships to access renewable natural gas offtake premiums.
For Investors and Strategic Acquirers: Treasury Department guidance on domestic content bonuses for Inflation Reduction Act tax credits is the leading indicator that US-manufactured combustion component suppliers will command acquisition premiums. Long-term viability centers on vertically integrated operators with captive collection fleets and 20-year municipal contracts. Monitor state renewable portfolio standard expansion announcements for demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Supply Contract Consolidation | Long-term municipal tipping agreements with guaranteed tonnage commitments secure baseload economics for thermal facilities. |
| Coal Plant Site Repurposing | Interconnection-ready infrastructure in Ohio and Pennsylvania bypasses multi-year queue delays facing greenfield developments. |
| Emissions Control Technology Upgrade | EPA Maximum Achievable Control Technology compliance enables renewable portfolio standard eligibility in California and New York. |
| Anaerobic Digestion Scale-Up | Wisconsin and Minnesota dairy cooperatives access EPA Renewable Fuel Standard premiums through pipeline injection infrastructure. |
| Digital SCADA Platform Integration | Predictive maintenance capabilities reduce unplanned downtime penalties in 20-year utility power purchase agreements. |
Research Methodology
Multi-period observation of EPA enforcement actions, state renewable portfolio standard adoptions, and interconnection queue dynamics anchored the trend analysis, supplemented by interviews with utility planning officers, waste authority procurement directors, EPC contractors, and emissions control system engineers. Secondary validation drew from EIA power plant databases, FERC interconnection filings, EPA enforcement and compliance history records, and state environmental agency permit tracking systems. Bottom-up facility-level capacity modeling triangulated against top-down state-level procurement mandate aggregation.
Input-output matrices mapped feedstock availability, conversion technology capital requirements, and offtake contract structures across the projection horizon. Segmentation dimensions modeled include technology pathway, feedstock calorific tier, end-user procurement sophistication, and regional grid interconnection status. CAGRs were derived from facility deployment pipeline analysis and state mandate compliance timelines. Key forecast inputs incorporated EPA landfill methane rule implementation schedules and Treasury Department tax credit guidance interpretations.
Underlying measurement precision varies by segment; thermal conversion capacity and utility offtake volumes carry tighter precision than emerging biological pathway deployment. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and interconnection queue processing rates. Practitioners should monitor state legislative sessions for renewable portfolio standard expansion and EPA regional office enforcement prioritization for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market