
 Hydrogen-Bromine Flow Battery Market | 2026-2036
Hydrogen-Bromine Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen-Bromine Flow Battery Market Insights
The performance gap between premium integrated systems and commodity component supply is broadening as electrolyzer efficiency and control software complexity separate high-reliability installations from basic hardware packages. JenaBatteries GmbH leverages its proprietary membrane technology to sustain manufacturing precision at scale. Elestor anchors its position through integrated system architectures that dominate European utility pilot programs. Bosch competes across the component layer with industrial-grade pump and power conversion systems drawn from adjacent hydrogen infrastructure portfolios.
Hydrogen-bromine flow batteries store electrical energy through reversible electrochemical reactions between hydrogen and bromine species, typically operating at ambient temperatures with aqueous electrolytes and achieving round-trip efficiencies exceeding 70 percent for multi-hour discharge durations. Their primary purpose centers on grid-scale energy arbitrage, renewable firming, and industrial backup power where lithium-ion limitations in duration and degradation create functional gaps. Standalone systems currently lead installed capacity as early adopters prioritize decoupled power and energy scaling, while hybrid configurations integrating solid-state buffers represent the fastest-growing technology segment as developers seek faster response dynamics. Utility-scale end users command the dominant margin pool given procurement scale and performance guarantee requirements, though commercial applications show accelerating interest behind on-site renewable pairing mandates.
The EU Green Deal and F-Gas Regulation shape product design requirements for long-duration storage systems deployed across European member states, with REACH compliance governing bromine handling and membrane material safety across the supply chain. Germany's KBA and national energy regulator enforce grid interconnection standards that dictate power conversion system certification thresholds for utility-connected installations. Stakeholders must monitor evolving CE marking protocols for electrochemical storage and assess how bromine supply chain concentration affects project delivery timelines.
Market Dynamics
The EU Green Deal's tightening carbon intensity benchmarks for long-duration energy storage are compressing procurement timelines across European utility-scale grid operators. This regulatory pressure accelerates pilot-to-deployment transitions while amplifying the performance gap between integrated system suppliers and commodity component vendors.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in thermal management systems push grid operators toward ambient-temperature electrochemical alternatives that eliminate synthetic coolant dependencies.
- Renewable firming mandates:Wind and solar penetration thresholds in national energy plans create functional demand for multi-hour discharge duration beyond lithium-ion degradation limits.
- Bromine supply chain concentration:Dead Sea and Arkansas production clusters enable predictable raw material sourcing for membrane-electrolyte stack manufacturing at scale.
Market Restraints
- Membrane material cost volatility:Perfluorinated ionomer prices fluctuate with fluorochemical feedstock markets, compressing margin structures for system integrators dependent on proprietary separator technologies.
- Power conversion system certification thresholds:Germany's KBA interconnection standards impose lengthy type-approval processes that extend project delivery timelines for utility-connected installations.
- Lithium-ion substitution pressure:Declining lithium iron phosphate pack costs and established recycling infrastructure create competitive displacement risk for emerging flow battery chemistries in sub-4-hour applications.
Strategic Opportunities
- Industrial backup power in the Netherlands:Chemical processing clusters near Rotterdam seek island-capable storage to hedge grid instability without diesel generator dependencies.
- Hybrid solid-state buffer integration:Coupling hydrogen-bromine stacks with supercapacitor or lithium titanate buffers enables sub-second frequency response capabilities that unlock ancillary services revenue streams.
- CE marking protocol evolution:Anticipated harmonized electrochemical storage standards create first-mover certification advantages for manufacturers with established EU notified body relationships.
Industry Challenges
- Electrochemical systems engineering talent scarcity:The intersection of bromine chemistry, hydrogen safety, and power electronics control requires specialized expertise concentrated in limited European research clusters.
- Stack manufacturing precision at scale:Maintaining membrane thickness tolerances and electrolyte flow distribution uniformity across megawatt-class production volumes demands capital-intensive metrology infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen-Bromine Flow Battery Market |
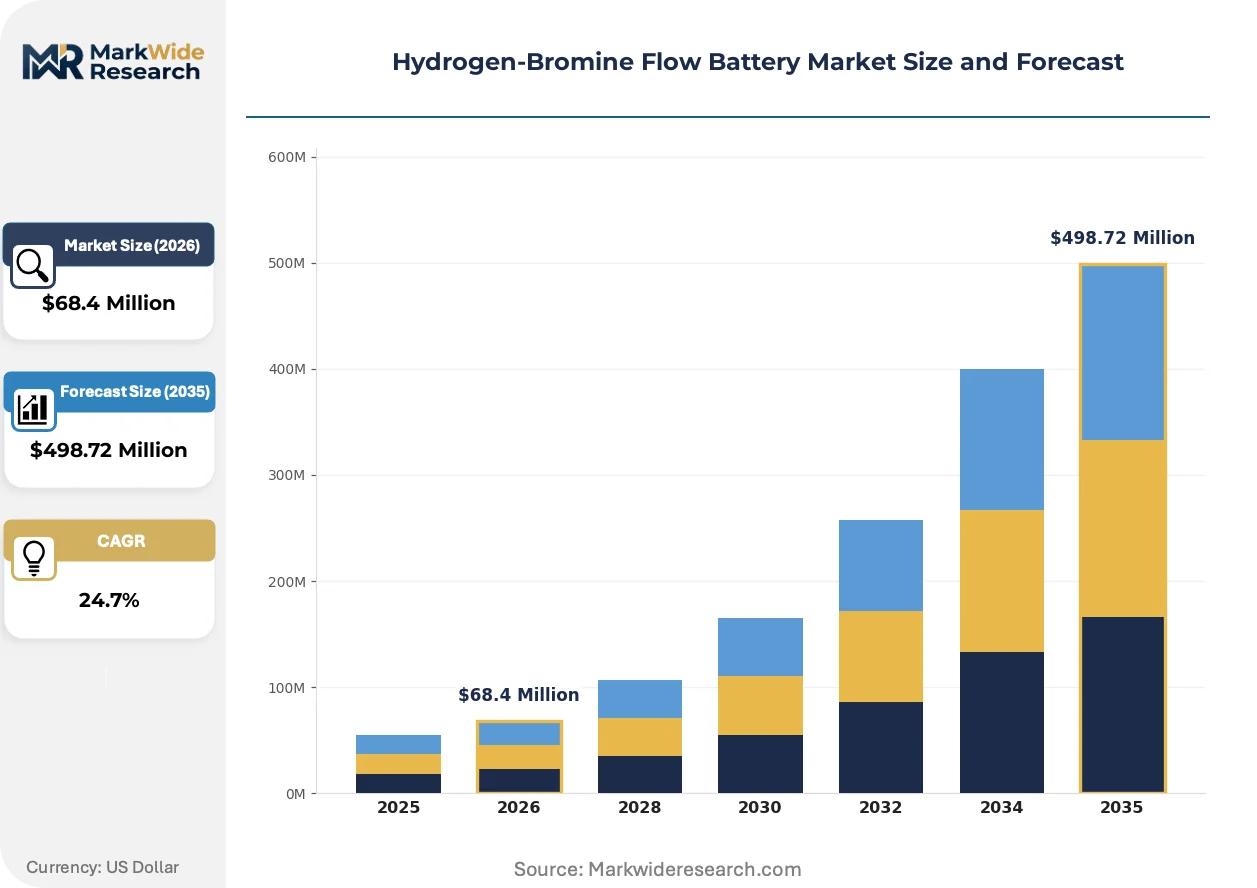
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $498.72 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hybrid Systems, Standalone Systems, Integration Technologies, Control Systems End User: Commercial Applications, Industrial Applications, Utility-Scale, Research Institutions Component: Electrolyzers, Storage Tanks, Pumps, Power Conversion Systems Installation: On-site, Off-site, Retrofitting, Modular Systems |
| Companies Covered | JenaBatteries GmbH, Siemens Energy, Bosch, Elestor, Schaeffler AG, MAN Energy Solutions, SMA Solar Technology AG, Sunfire GmbH, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen-Bromine Flow Battery Market Trends and Innovations
Technology maturation and regulatory harmonization are compressing the gap between laboratory performance and field-proven reliability for long-duration storage systems. These converging forces reshape competitive positioning around integrated architectures versus component specialization.
Membrane-electrolyte interface engineering is consolidating around thin-film composite structures that reduce ionic resistance while maintaining bromine species containment. Utility procurement teams now specify round-trip efficiency guarantees above seventy percent for eight-hour discharge profiles. This performance threshold is consolidating supplier tiers, marginalizing early-stage developers lacking validated degradation curves across multi-year operational datasets.
The EU Green Deal's carbon intensity benchmarking framework now extends to embodied emissions in energy storage manufacturing. REACH compliance obligations for bromine handling and membrane precursor chemicals impose documentation burdens that favor established chemical process operators with existing substance registration portfolios. German grid operators respond by embedding lifecycle carbon thresholds directly into tender evaluation matrices.
Power purchase agreement structures increasingly unbundle energy arbitrage from capacity services, enabling hybrid storage configurations that optimize revenue stacking. Industrial offtakers in chemical processing and data center verticals now procure long-duration storage through energy-as-a-service contracts rather than capital expenditure models. This financing rotation is most visible in the Netherlands where Elestor's operational megawatt installations demonstrate bankable performance track records for project finance pools.
Hydrogen-Bromine Flow Battery Market Segmentation
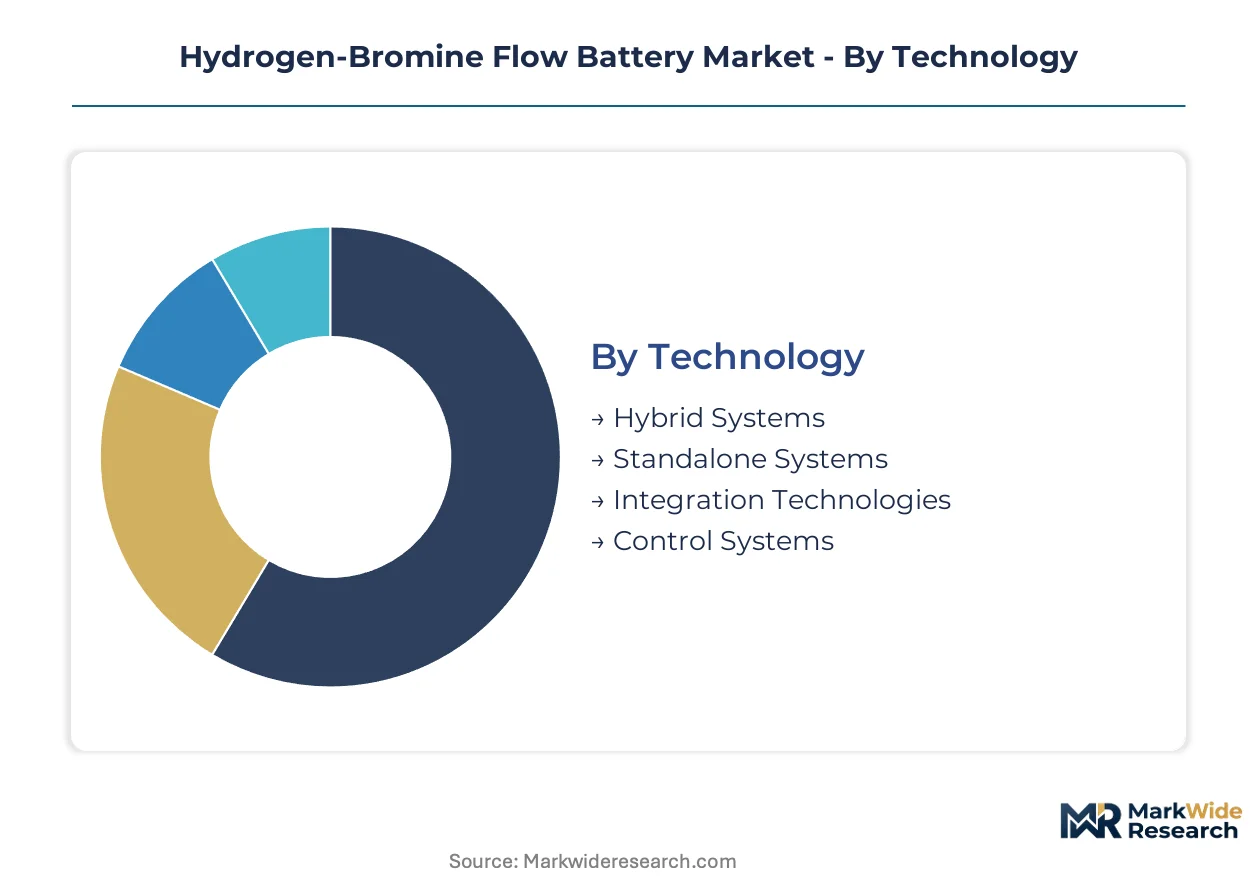
Hydrogen-bromine flow battery deployments fragment across distinct technology architectures and procurement models. Each segment carries unique upgrade cycles and replacement timelines that reshape vendor positioning and customer switching costs.
Technology:
Upgrade cycles vary sharply by system complexity, with integrated architectures demanding longer validation periods before field replacement.
- Hybrid Systems:These configurations couple hydrogen-bromine electrochemical stacks with solid-state buffers such as supercapacitors or lithium titanate cells. Dutch chemical processing clusters near Rotterdam prioritize hybrid architectures for island-capable backup that eliminates diesel dependencies while meeting sub-second frequency response requirements.
- Standalone Systems:Decoupled power and energy scaling define these installations, with membrane-electrolyte stacks operating independently of auxiliary storage. German utility-scale grid operators favor standalone configurations for renewable firming applications where eight-hour discharge profiles and seventy-plus percent round-trip efficiency guarantees dominate procurement specifications.
- Integration Technologies:Middleware layers enabling stack-to-grid connectivity.
- Control Systems:Proprietary software managing electrolyte flow distribution and power conversion optimization.
Volume placements concentrate in Standalone Systems; the faster expansion belongs to Hybrid Systems.
End User:
Customer type dictates performance guarantee requirements and financing structures, with capital availability separating procurement approaches.
- Utility-Scale:Grid-connected installations exceeding ten megawatts dominate margin pools through scale economics and long-term power purchase agreements. Germany's KBA interconnection standards and national energy regulator certification thresholds create procurement barriers that favor established integrators with validated degradation curves across multi-year operational datasets.
- Commercial Applications:On-site renewable pairing mandates drive demand from data centers and manufacturing facilities seeking energy-as-a-service contracts rather than capital expenditure models. Netherlands-based installations demonstrate bankable performance track records that unlock project finance pools for this customer segment.
- Industrial Applications:Chemical processing and heavy manufacturing seeking island-capable storage.
- Research Institutions:Pilot-scale deployments validating membrane-electrolyte interface engineering advances.
Revenue concentration sits with Utility-Scale deployments; Commercial Applications show the steepest expansion trajectory.
Component:
Supply chain configuration determines margin capture, with proprietary technologies commanding premium positioning against commodity hardware.
- Electrolyzers:Ambient-temperature electrochemical reactors enabling reversible hydrogen-bromine reactions. EU F-Gas Regulation restrictions on fluorinated greenhouse gases push grid operators toward these ambient-temperature alternatives that eliminate synthetic coolant dependencies in thermal management systems.
- Power Conversion Systems:Industrial-grade inverters and rectifiers managing AC-DC transformation for grid interconnection. Bosch leverages adjacent hydrogen infrastructure portfolios to compete across this component layer with systems drawn from established industrial automation supply chains.
- Storage Tanks:Aqueous electrolyte containment vessels with bromine species corrosion resistance.
- Pumps:Electrolyte circulation hardware maintaining flow distribution uniformity across megawatt-class stack assemblies.
Procurement volume clusters on Electrolyzers; Power Conversion Systems are climbing the fastest.
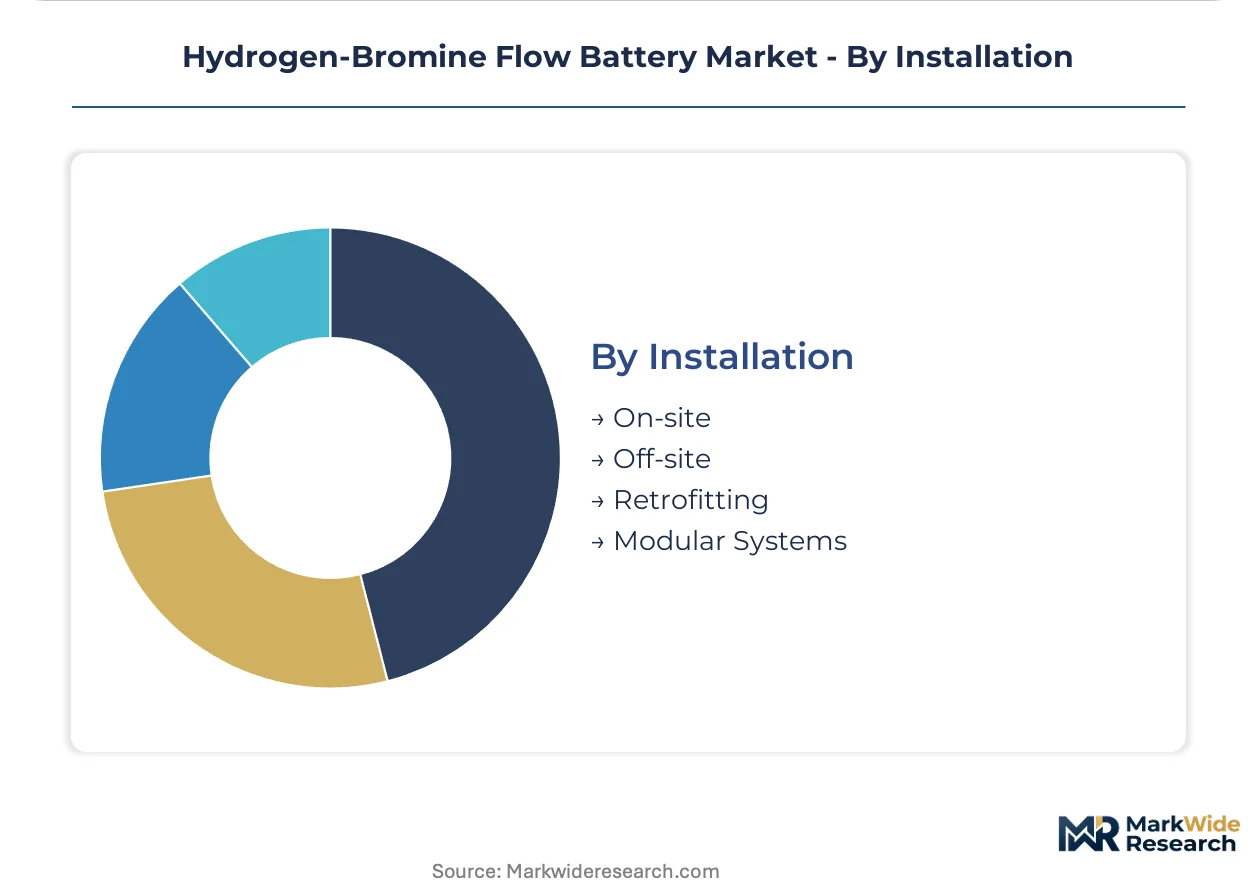
Installation:
Deployment modality shapes project delivery timelines and capital structure, with retrofit economics competing against greenfield modular approaches.
- Modular Systems:Factory-integrated skid-mounted units enabling rapid field assembly and capacity scaling through containerized replication. Elestor's operational megawatt-class installations in the Netherlands demonstrate bankable modular architectures that compress commissioning timelines for utility pilot programs.
- Retrofitting:Integration of hydrogen-bromine stacks into existing electrical infrastructure and civil works. German grid operators expanding pilot deployments face extended delivery timelines from KBA type-approval processes for utility-connected retrofit installations.
- On-site:Greenfield construction at point-of-use locations with dedicated civil infrastructure.
- Off-site:Centralized manufacturing with subsequent transportation to operational locations.
Deployment volume favors Modular Systems; Retrofitting is gaining share fastest among brownfield expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's chemical processing corridor anchors European hydrogen-bromine flow battery deployment, with Elestor's megawatt installations demonstrating bankable performance for project finance pools. The EU Green Deal's carbon intensity benchmarks compress procurement timelines across utility-scale grid operators from the Netherlands to Germany.
Germany
Utility-scale grid storage operators in North Rhine-Westphalia and Bavaria expand pilot deployments as the KBA enforces lengthy type-approval processes for utility-connected installations. The national energy regulator embeds lifecycle carbon thresholds directly into tender evaluation matrices. Berlin-Brandenburg research clusters concentrate electrochemical systems engineering talent at the intersection of bromine chemistry and hydrogen safety.
Netherlands
Chemical processing clusters near Rotterdam seek island-capable storage to hedge grid instability without diesel generator dependencies. The Dutch national framework for renewable firming mandates drives on-site renewable pairing requirements for data centers and manufacturing facilities. Elestor's operational megawatt-class installations in the Randstad demonstrate modular architectures that compress commissioning timelines.
United States
Industrial offtakers in Texas and California procure long-duration storage through energy-as-a-service contracts rather than capital expenditure models. FERC interconnection standards and state-level renewable portfolio standards create procurement barriers that favor established integrators. The Pacific Northwest hosts research institutions validating membrane-electrolyte interface engineering advances for next-generation stack designs.
China
Dual carbon goals and provincial renewable penetration targets create functional demand for multi-hour discharge duration beyond lithium-ion degradation limits. The MIIT governs electrochemical storage manufacturing standards while GB standards dictate power conversion system certification thresholds. Yangtze River Delta industrial zones concentrate bromine supply chain infrastructure for membrane-electrolyte stack manufacturing at scale.
Hydrogen-Bromine Flow Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated system architectures versus component supply layers. The vendor base stratifies into three tiers: proprietary membrane technology specialists, industrial-grade power conversion system suppliers, and modular system integrators. Two strategic moves dominate competitive dynamics: backward integration into bromine supply chains and technology licensing partnerships that accelerate CE marking certification.
Within the integrated system tier, Elestor anchors Dutch deployment activity through megawatt-class installations. JenaBatteries GmbH exemplifies the membrane technology archetype with proprietary separator expertise. Bosch occupies a position across the component layer, leveraging adjacent hydrogen infrastructure portfolios for industrial-grade pump and power conversion systems.
| Leading Market Players |
|---|
| JenaBatteries GmbH |
| Siemens Energy |
| Bosch |
| Elestor |
| Schaeffler AG |
| MAN Energy Solutions |
| SMA Solar Technology AG |
| Sunfire GmbH |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Electrochemical systems engineering talent scarcity in Berlin-Brandenburg research clusters widens labor-cost differentials between premium integrated system suppliers and commodity component vendors, compressing margin structures for stack manufacturers lacking proprietary membrane technologies.
Pricing Analysis
Value-based pricing anchored to round-trip efficiency guarantees above seventy percent for eight-hour discharge profiles separates premium integrated system suppliers from commodity hardware packagers. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—CE marking for utility-connected installations versus industrial-grade specifications—and by volume scale for megawatt-class procurement. Pricing pressure stems from declining lithium iron phosphate pack costs in sub-4-hour applications. Utility-scale grid operators demonstrate lowest price sensitivity given performance guarantee requirements and long-term power purchase agreement structures.
Supply Chain Analysis
Membrane-electrolyte stack refurbishment and remanufacturing flows remain underdeveloped, limiting secondary material recovery and extending replacement cycles for perfluorinated ionomer separators. Manufacturing concentrates in Germany, the Netherlands, and China, with Dead Sea and Arkansas bromine production clusters feeding membrane-electrolyte stack assembly. Raw material dependencies center on fluorochemical feedstocks for ionomer membranes, industrial-grade pumps from adjacent hydrogen infrastructure portfolios, and power conversion system components. Single-source vulnerability in perfluorinated ionomer supply creates procurement risk. Distribution runs through EPC contractors and direct utility procurement channels for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where proprietary membrane technology and captive bromine supply chains determine margin capture against commodity component competitors.
For Market Incumbents: Cement position through backward integration into bromine supply chains and proprietary membrane-electrolyte interface engineering. Lithium-ion substitution pressure in sub-4-hour applications threatens stack manufacturers lacking validated degradation curves across multi-year operational datasets. Capacity addition in Yangtze River Delta industrial zones secures raw material sourcing proximity.
For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for ambient-temperature electrochemical alternatives eliminating synthetic coolant dependencies. Commercial applications in data center and manufacturing verticals show penetrable white space behind energy-as-a-service contract structures. Hybrid solid-state buffer integration represents the fastest-expanding technology segment for ancillary services revenue capture.
For Investors and Strategic Acquirers: Re-rating potential sits with proprietary membrane technology specialists given REACH compliance documentation burdens favoring established chemical process operators. Long-term viability hinges on bankable performance track records unlocking project finance pools. Monitor CE marking protocol harmonization for electrochemical storage as inflection indicator for first-mover certification advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Supply | Captive sourcing from Dead Sea and Arkansas production clusters reduces membrane-electrolyte stack cost volatility. |
| Hybrid Solid-State Buffer Integration | Coupling with supercapacitors unlocks sub-second frequency response revenue streams for Dutch chemical processors. |
| CE Marking Certification Investment | First-mover advantages emerge from harmonized electrochemical storage standards under EU Green Deal frameworks. |
| Energy-as-a-Service Contract Structures | Financing rotation from capital expenditure models accelerates commercial segment penetration in Netherlands data centers. |
| Membrane-Electrolyte Interface Engineering | Thin-film composite structures reduce ionic resistance while maintaining bromine containment for German utility specifications. |
Research Methodology
Document review covered FERC filings, EIA data, IEA reports, and project development databases, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork with hydrogen-bromine flow battery system integrators and membrane technology specialists was validated against secondary sources including SEC filings from adjacent hydrogen infrastructure portfolios and customs data on fluorochemical feedstock trade flows. Bottom-up installation capacity modeling was triangulated against top-down market sizing from regulatory mandate analysis.
Installed capacity and revenue outputs were generated through segmentation across technology architecture, end-user category, component layer, and installation modality, with CAGRs derived from regulatory mandate timelines and pilot-to-deployment transition rates. The analytical framework incorporated round-trip efficiency degradation curves, membrane replacement cycles, and power conversion system certification thresholds as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path favoring standalone systems for renewable firming; alternative pathways for hybrid configurations with solid-state buffers would alter the outlook for ancillary services revenue capture. Forecasts reflect assumptions on EU Green Deal implementation pacing, bromine supply chain concentration stability, and lithium-ion cost trajectories. Practitioners should monitor KBA type-approval process durations, perfluorinated ionomer price volatility, and CE marking protocol finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Solar Storage System Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Power Bank Market
Energy Storage
South America Energy Storage Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Hybrid Solar Wind Energy Storage Market