
 Asia-Pacific Real Estate Brokerage Market | 2026-2036
Asia-Pacific Real Estate Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Real Estate Brokerage Market Insights
Luxury residential buyers is repositioning toward cross-border investment advisory as wealth migration accelerates from mainland China to Singapore and Australia. CBRE Group leverages its Asia-Pacific platform dominance to capture ultra-high-net-worth flows across multiple jurisdictions. JLL sustains competitive tension through technology leadership in commercial asset valuation tools. Colliers International anchors its regional position through deep tenant representation networks in Tier-1 office markets.
Asia-Pacific real estate brokerage encompasses intermediary services that match property buyers, sellers, and lessees through licensed agents operating under jurisdiction-specific fiduciary standards, with commission structures typically ranging from one to three percent of transaction value depending on asset class and local convention. The primary commercial purpose centers on reducing information asymmetry in opaque property markets while managing due diligence, negotiation, and contractual execution. Residential brokerage occupies the largest revenue pool across the region, though investment brokerage commands superior margins per transaction due to complexity premiums on cross-border capital deployment. Online platforms within the technology segment are expanding fastest as PropTech integration displaces traditional walk-in client acquisition models across urban Southeast Asia.
Singapore's Monetary Authority of Singapore and Australia's Australian Securities and Investments Commission enforce anti-money laundering protocols that tighten customer due diligence requirements for cross-border property transactions. China's National Development and Reform Commission and India's Real Estate Regulatory Authority impose foreign investment caps and project escrow mandates that reshape market access conditions for international brokerages. Thailand's Land Department and Vietnam's Ministry of Construction maintain title registration systems with varying degrees of digital transparency, creating operational complexity for regional operators. Stakeholders must monitor regulatory divergence across ASEAN member states as digital transaction standards proliferate at uneven speeds.
Market Dynamics
Digital transaction mandates from Australia's financial regulator and Singapore's monetary authority are compressing settlement timelines across the Asia-Pacific real estate brokerage market, forcing traditional intermediaries to rebuild operational infrastructure around PropTech platforms or surrender market position to digitally native competitors.
Growth Catalysts
- Cross-border wealth migration:Ultra-high-net-worth individuals from mainland China are accelerating property acquisitions in Singapore and Australia, generating sustained demand for multi-jurisdictional advisory services and premium commission structures.
- Anti-money laundering protocol enforcement:Singapore's Monetary Authority of Singapore and Australia's Australian Securities and Investments Commission have tightened customer due diligence requirements, creating competitive advantage for brokerages with compliant digital verification systems.
- PropTech platform integration:Virtual property tours and AI-powered valuation tools are reducing information asymmetry in opaque Southeast Asian markets, expanding addressable transaction volumes for technology-enabled intermediaries.
Market Restraints
- Foreign investment caps:China's National Development and Reform Commission maintains strict capital controls on outbound real estate investment, constraining brokerage revenue from mainland-sourced cross-border transactions.
- Title registration opacity:Thailand's Land Department and Vietnam's Ministry of Construction operate paper-based title systems with limited digital transparency, elevating due diligence costs and extending transaction timelines for regional operators.
- Escrow mandate fragmentation:India's Real Estate Regulatory Authority imposes project-specific escrow requirements that vary by state, complicating standardized brokerage workflows across subnational jurisdictions.
Strategic Opportunities
- Underpenetrated secondary cities:Vietnam's Da Nang and Indonesia's Surabaya exhibit rising middle-class property demand with limited professional brokerage presence, offering first-mover positioning for platform-enabled entrants.
- Technology convergence:Blockchain-based smart contracts integrated with digital identity verification are enabling self-executing settlement processes that reduce intermediary friction in Singapore's luxury residential segment.
- Channel innovation:Social commerce platforms popular in Southeast Asian consumer markets are emerging as property discovery channels, allowing brokerages to acquire clients outside traditional walk-in and referral models.
Industry Challenges
- Licensed agent scarcity:Qualified professionals capable of navigating multi-jurisdictional regulatory frameworks remain concentrated in Sydney, Melbourne, and Singapore, limiting expansion capacity for regional brokerages.
- Legacy system integration:Established brokerages with decades of paper-based transaction records face substantial capital requirements to migrate client data and workflow processes onto compliant digital platforms.
- Certification timeline compression:Australia's financial regulator and Singapore's monetary authority are accelerating compliance deadlines faster than brokerages can retrain staff and recertify operational procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Real Estate Brokerage Market |
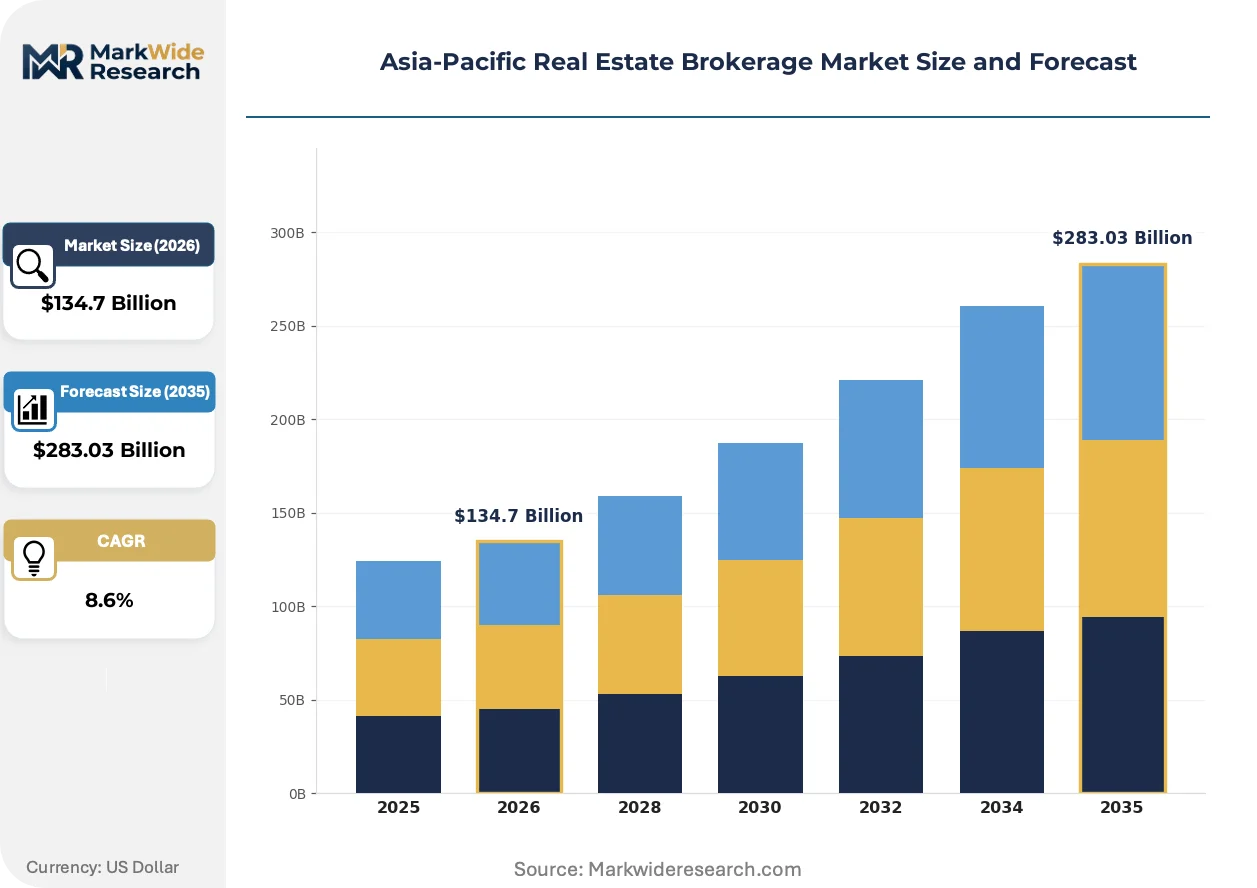
| Market Size in 2026 | $134.7 Billion |
| Market Size in 2035 | $283.03 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Brokerage, Commercial Brokerage, Investment Brokerage, Leasing Services Customer Type: First-Time Buyers, Real Estate Investors, Corporations, Property Developers Transaction Size: Small Transactions, Medium Transactions, Large Transactions, Mega Deals Technology: Online Platforms, Mobile Applications, CRM Software, Virtual Tours |
| Companies Covered | CBRE Group, JLL, Colliers International, Knight Frank, Savills, Cushman & Wakefield, Century 21 Real Estate, PropNex Ltd., Centaline Property Agency Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Real Estate Brokerage Market Trends and Innovations
PropTech integration is fundamentally restructuring how property transactions originate, execute, and settle across the Asia-Pacific region, with three interconnected developments reshaping competitive positioning among established and emerging intermediaries.
Artificial intelligence-powered valuation engines are overtaking traditional comparable-sales methodologies in Australia's metropolitan corridor from Sydney to Melbourne. Institutional investors and luxury residential buyers now expect real-time price estimates derived from machine learning models processing thousands of micro-market variables. This compression of valuation timelines is enabling same-day offer generation that was previously impossible under manual appraisal workflows.
Singapore's Monetary Authority of Singapore and Australia's Australian Securities and Investments Commission have implemented digital transaction reporting mandates that require real-time submission of cross-border property settlements. Brokerages must now maintain API-connected compliance infrastructure that automatically flags suspicious activity patterns to regulators. The investment brokerage segment faces the steepest adaptation costs, as complex capital structures require more sophisticated data architecture than residential transactions.
Wealthy buyers from mainland China are consolidating property searches through centralized cross-border advisory platforms rather than engaging multiple single-market agents. This behavioral shift concentrates commission flows toward brokerages with licensed presence in both origin and destination jurisdictions. Singapore and Australia have emerged as the primary destination markets where this platform consolidation is most visible, with buyers prioritizing single-relationship execution over fragmented local representation.
Asia-Pacific Real Estate Brokerage Market Segmentation
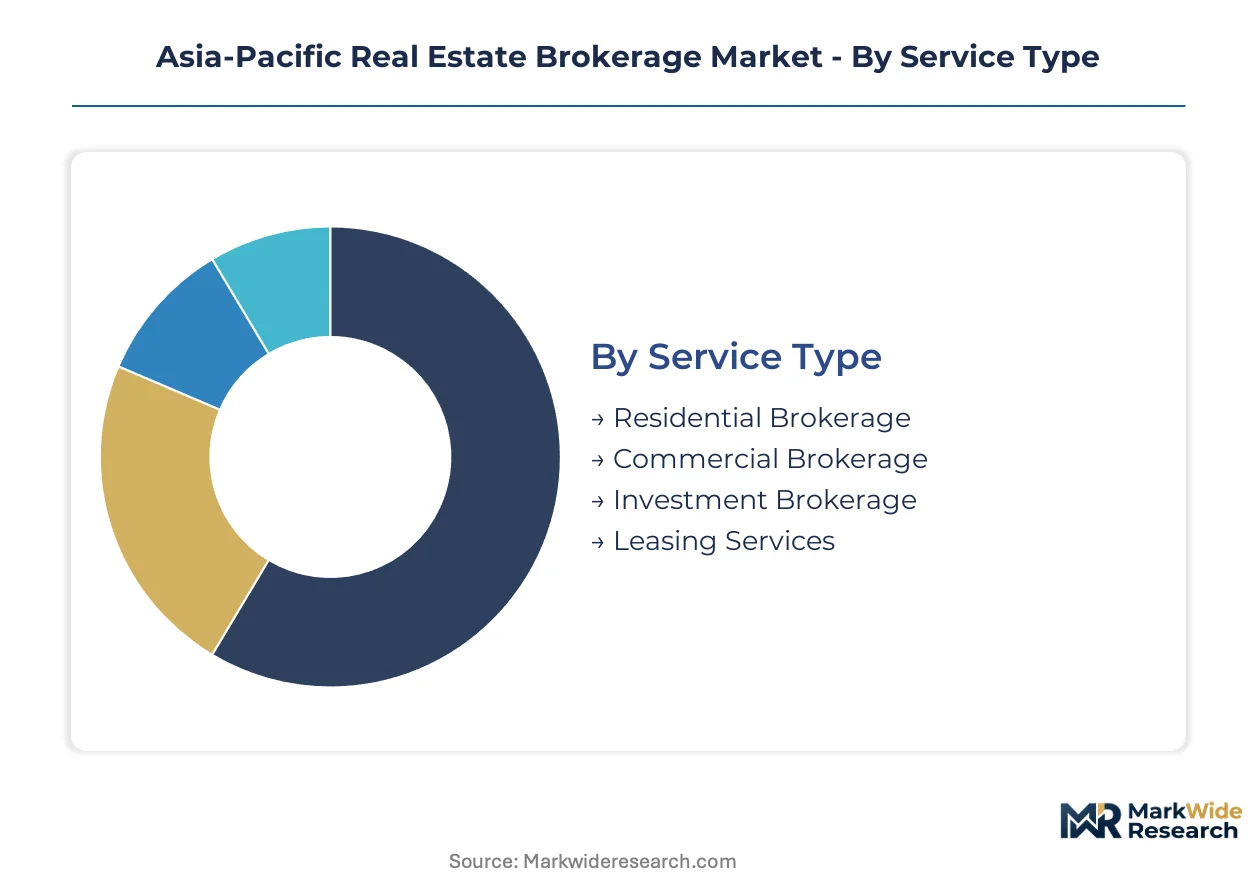
Brokerage revenue pools fragment sharply across service lines and client profiles, with commission structures and operational requirements diverging substantially between residential walk-in traffic and institutional capital deployment. Understanding these segment boundaries reveals where technology investments yield the highest returns and where regulatory compliance costs concentrate.
Service Type:
Supply-side capability concentrates in metropolitan hubs where licensed agents cluster around high-velocity transaction corridors, creating uneven coverage across secondary geographies.
- Residential Brokerage:Matches individual buyers and sellers of single-family homes, condominiums, and apartment units through commission-based representation. Australia's Sydney-to-Melbourne corridor generates sustained transaction velocity as urban density intensifies and intergenerational wealth transfers accelerate property turnover.
- Commercial Brokerage:Facilitates office, retail, and industrial asset transactions between institutional owners and corporate occupiers. Singapore's Grade-A office market commands premium advisory fees as multinational corporations consolidate Asia-Pacific headquarters and require complex lease restructuring expertise.
- Investment Brokerage:Cross-border capital placement services for ultra-high-net-worth individuals and sovereign wealth vehicles navigating foreign ownership restrictions.
- Leasing Services:Tenant representation and landlord advisory for multi-year occupancy contracts without title transfer.
Residential brokerage absorbs the bulk of installed capacity; investment brokerage is expanding most quickly.
Customer Type:
Commission economics vary dramatically by client sophistication, with first-time buyers requiring intensive education while institutional clients demand multi-jurisdictional execution capabilities.
- First-Time Buyers:Entry-level purchasers navigating mortgage qualification, deposit structures, and regulatory compliance for initial property acquisition. Vietnam's emerging middle class in Da Nang and Ho Chi Minh City drives demand for guided purchase processes as condominium ownership norms displace generational family housing.
- Real Estate Investors:Portfolio builders seeking yield optimization across multiple properties and markets. Australia's negative gearing tax treatment and Singapore's stable currency anchor attract mainland Chinese capital seeking diversification beyond domestic property restrictions.
- Corporations:Occupiers requiring lease negotiation, expansion planning, and workplace strategy advisory.
- Property Developers:Project sponsors needing pre-sales marketing, bulk disposal, and joint venture structuring.
Real estate investors command the highest commission rates per transaction hour; first-time buyers represent the largest addressable population.
Transaction Size:
Operational infrastructure requirements scale non-linearly with deal magnitude, as mega deals demand specialized legal structuring and cross-border regulatory navigation.
- Small Transactions:Sub-million-dollar residential purchases and short-term leases executed through standardized workflows. Indonesia's Surabaya and Bandung markets exhibit dense small-transaction activity where platform-enabled matching reduces agent time investment per closing.
- Medium Transactions:Mid-market commercial assets and premium residential acquisitions requiring due diligence coordination. Thailand's Bangkok condominium resale market concentrates medium-transaction volume as foreign quota restrictions create complex ownership structuring needs.
- Large Transactions:Institutional-grade assets and portfolio disposals exceeding national reporting thresholds.
- Mega Deals:Landmark trophy assets and cross-border platform acquisitions involving multiple regulatory jurisdictions.
Medium transactions absorb the bulk of agent labor hours; mega deals deliver the steepest expansion trajectory for specialized advisory practices.
Technology:
Capital deployment into digital infrastructure separates scaled operators from fragmented local competitors, with API connectivity to regulatory systems becoming a licensure requirement.
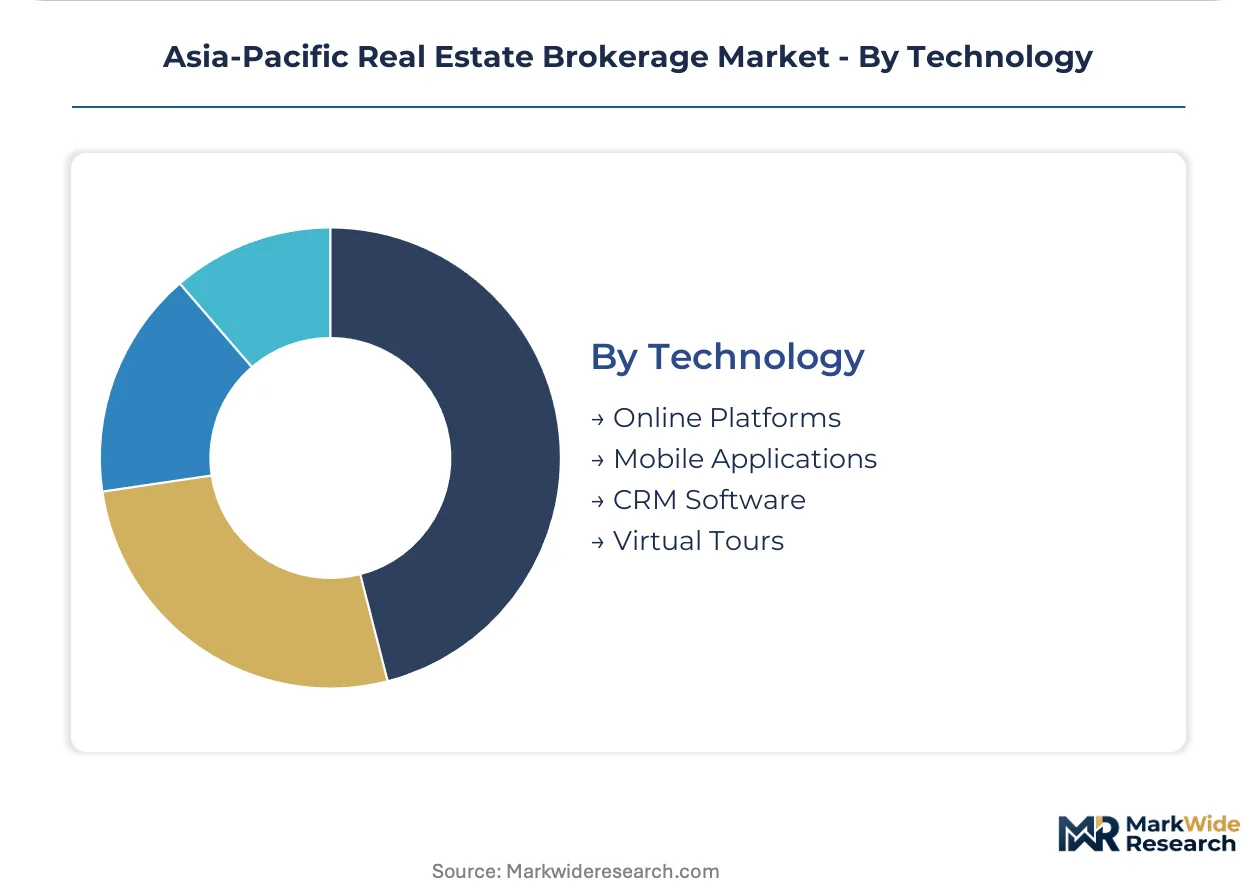
- Online Platforms:Web-based property discovery and transaction initiation portals aggregating listings across multiple brokerages. Singapore's PropertyGuru and Australia's REA Group dominate consumer search behavior, forcing traditional agents to purchase premium placement or surrender lead generation control.
- Mobile Applications:Smartphone-native interfaces enabling instant notification, document upload, and biometric identity verification. Southeast Asian markets with high mobile-first internet penetration show the fastest app adoption curves as consumers bypass desktop search entirely.
- CRM Software:Client relationship management systems tracking interaction history, preference profiles, and pipeline stages.
- Virtual Tours:Immersive digital property inspections reducing physical viewing requirements for distant buyers.
Online platforms capture the majority of consumer attention; mobile applications are climbing the fastest as smartphone penetration deepens across emerging Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Foreign Investment Review Board framework channels offshore capital into designated metropolitan zones, compressing transaction timelines for compliant intermediaries. Singapore's Qualifying Domestic Entity scheme accelerates cross-border settlement velocity through digital verification mandates. China's Hainan Free Trade Port pilot program is testing relaxed property ownership rules for foreign nationals.
Australia
Sydney-to-Melbourne corridor transaction velocity intensifies as intergenerational wealth transfers accelerate property turnover. Australia's Foreign Investment Review Board enforces strict non-resident acquisition screening, elevating compliance costs for brokerages serving offshore buyers. Melbourne's inner-ring suburbs concentrate luxury residential advisory activity as ultra-high-net-worth mainland Chinese buyers consolidate representation.
Singapore
Grade-A office lease restructuring generates sustained demand for tenant representation expertise as multinational corporations consolidate Asia-Pacific headquarters. Singapore's Monetary Authority of Singapore mandates real-time digital transaction reporting for cross-border settlements, forcing API infrastructure investments. Marina Bay and Orchard Road districts anchor premium residential brokerage activity as wealth migration from mainland China concentrates.
China
Outbound capital controls constrain brokerage revenue from cross-border transactions originating in Tier-1 cities. China's National Development and Reform Commission maintains strict approval thresholds for foreign real estate investment, redirecting flows through Hong Kong intermediaries. Shanghai's Lujiazui financial district retains domestic investment brokerage density despite regulatory compression on international deployment.
Thailand
Bangkok condominium resale volume concentrates medium-transaction activity as foreign quota restrictions create complex ownership structuring needs. Thailand's Land Department operates paper-based title registration with limited digital transparency, extending due diligence timelines for regional operators. Sukhumvit and Silom corridors attract cross-border advisory presence targeting Southeast Asian investor diversification.
Vietnam
Da Nang and Ho Chi Minh City exhibit rising middle-class property demand with limited professional brokerage presence, offering first-mover positioning. Vietnam's Ministry of Construction maintains project escrow mandates that vary by province, complicating standardized workflows. District 2 in Ho Chi Minh City and the An Thuong beach zone in Da Nang concentrate emerging luxury residential development activity.
Asia-Pacific Real Estate Brokerage Market Competitive Landscape
Top-tier vendors anchor the premium advisory segment, while mid-scale operators compete on transaction velocity in standardized residential markets. The vendor base stratifies across three distinct tiers: global platform conglomerates with multi-jurisdictional licensing, regional specialists with deep tenant representation networks, and technology-enabled challengers acquiring clients through social commerce channels. Competitive tension centers on M&A activity consolidating licensed agent pools and strategic partnerships embedding PropTech platforms into regulatory compliance workflows.
Among global platform conglomerates, CBRE Group and JLL exemplify the multi-jurisdictional archetype with presence spanning origin and destination markets for cross-border capital flows. Colliers International occupies a position within the tenant representation specialist tier, anchoring regional market share through deep corporate occupier relationships. These three entities collectively represent the competitive frontier where technology licensing agreements and compliance infrastructure investments determine relative positioning.
| Leading Market Players |
|---|
| CBRE Group |
| JLL |
| Colliers International |
| Knight Frank |
| Savills |
| Cushman & Wakefield |
| Century 21 Real Estate |
| PropNex Ltd. |
| Centaline Property Agency Limited |
| Others |
Pricing and Supply Chain Analysis
Singapore's Monetary Authority of Singapore digital transaction reporting mandate gates both qualified supply and premium-tier pricing access, as brokerages lacking API-connected compliance infrastructure face exclusion from cross-border advisory while compliant operators capture complexity premiums on ultra-high-net-worth flows.
Pricing Analysis
Short lead-time execution commands premium pricing in Australia's Sydney-to-Melbourne corridor, where same-day offer generation enabled by AI-powered valuation engines justifies elevated commission structures. Pricing stratifies across premium, standard, and economy tiers based on regulatory compliance certification and cross-border jurisdictional coverage depth. Cost compression in the standard tier is intensifying because digitally native platforms displace traditional walk-in acquisition models. First-time buyers in Vietnam's emerging markets exhibit highest price sensitivity, while mainland Chinese ultra-high-net-worth individuals in Singapore and Australia demonstrate lowest sensitivity due to single-relationship execution preferences.
Supply Chain Analysis
Dual-sourcing requirements from institutional investors mandate multi-brokerage qualification across both origin and destination jurisdictions, elevating operational complexity for regional operators. Licensed agent pools concentrate in Australia, Singapore, and Hong Kong, while technology infrastructure draws from India and Malaysia for back-office PropTech development. Supply chain risk centers on single-source vulnerability where qualified professionals capable of navigating multi-jurisdictional regulatory frameworks remain geographically concentrated. Distribution runs through centralized cross-border advisory platforms rather than fragmented local agent networks, concentrating commission flows toward scaled operators with compliant digital infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where Singapore's Monetary Authority of Singapore real-time digital transaction reporting mandate creates a barrier-to-entry moat favoring brokerages with pre-built API infrastructure and certified operational procedures.
For Market Incumbents: Anticipate regulatory timeline compression by accelerating staff retraining and recertification ahead of Australian Securities and Investments Commission deadlines. Consolidate licensed agent pools through targeted acquisition in Sydney and Melbourne to defend against digitally native competitors capturing cross-border wealth migration flows. Vertical integration into proprietary AI valuation engines offers margin protection as machine learning models displace traditional comparable-sales methodologies. For New Entrants and Emerging Players: Begin with Vietnam's Da Nang and Indonesia's Surabaya secondary cities where rising middle-class property demand meets limited professional brokerage presence. Social commerce platforms popular in Southeast Asian consumer markets provide the most penetrable client acquisition channel outside traditional walk-in and referral models. Partner with established PropTech infrastructure providers to bypass legacy system migration costs and accelerate compliance certification timelines. For Investors and Strategic Acquirers: Australia's Foreign Investment Review Board enforcement intensification is the leading indicator that compliance-ready brokerages will command acquisition premiums over the medium-term horizon. Target regional specialists with deep tenant representation networks in Tier-1 office markets and existing API connectivity to monetary authority reporting systems. Watch for Singapore's Qualifying Domestic Entity scheme expansion as the signal that cross-border settlement velocity acceleration is unlocking scalable revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| PropTech Platform Integration | API-connected compliance infrastructure satisfies Singapore's Monetary Authority of Singapore real-time reporting mandates. |
| Licensed Agent Pool Acquisition | Consolidation in Sydney and Melbourne addresses scarcity of multi-jurisdictional regulatory navigation capability. |
| AI-Powered Valuation Engine Deployment | Machine learning models processing micro-market variables enable same-day offer generation in Australia's metropolitan corridor. |
| Cross-Border Advisory Platform Expansion | Single-relationship execution captures consolidating commission flows from mainland Chinese ultra-high-net-worth buyers. |
| Social Commerce Channel Development | Smartphone-native property discovery bypasses traditional walk-in client acquisition in Southeast Asian emerging markets. |
Research Methodology
Multi-period observation of transaction velocity indicators, regulatory compliance deadline acceleration, and PropTech platform adoption rates anchored the trend analysis, supplemented by interviews with licensed brokerage principals, regulatory affairs officers at monetary authorities, PropTech platform engineers, and institutional investor real estate allocation heads. Secondary validation drew from Australian Securities and Investments Commission enforcement bulletins, Singapore's Monetary Authority of Singapore circulars, Real Estate Regulatory Authority state-level filings, and customs data on cross-border capital flows. Bottom-up transaction volume aggregation and top-down macroeconomic driver assessment provided triangulation.
Input-output matrices modeled relationships between regulatory mandate implementation timelines, licensed agent supply constraints, and technology adoption curves across the projection horizon. Segmentation dimensions included service type, customer sophistication tier, transaction magnitude bracket, and technology deployment level. CAGRs were derived from regression analysis against historical transaction velocity patterns and forward-looking regulatory compliance cost assumptions. Forecast inputs incorporated monetary authority digital mandate rollout schedules and intergenerational wealth transfer acceleration indicators.
Regulatory enforcement intensity shifts, cross-border capital control relaxation or tightening, and PropTech platform failure rates are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about continued monetary authority digital transaction mandate proliferation and sustained mainland Chinese wealth migration velocity. A model refresh is warranted upon material change in Singapore's Qualifying Domestic Entity scheme scope or Australia's Foreign Investment Review Board screening threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Lease Management Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Green Lease Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
US Home Service Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Egypt Real Estate Brokerage Market