
 Egypt Real Estate Brokerage Market | 2026-2036
Egypt Real Estate Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Real Estate Brokerage Market Insights
Licensed property agent talent is rotating toward digital-first platforms as traditional foot-traffic models lose ground in secondary cities. Coldwell Banker Egypt leverages its franchise network to sustain brand recognition across Alexandria and Cairo corridors. RE/MAX Egypt anchors its growth through independent agent recruitment that competes with localized boutique firms. AqarMap differentiates by controlling online listing aggregation that extends reach into emerging compounds.
Egypt real estate brokerage encompasses intermediary services that match property buyers, sellers, and tenants through valuation, marketing, negotiation, and closing facilitation, typically operating on commission structures tied to transaction value. The sector functions as the primary liquidity mechanism for Egypt's predominantly private-ownership housing stock and commercial asset base. Residential brokerage dominates transaction volume as Egypt's urban population expansion and new city satellite developments create sustained listing flow. Commercial brokerage captures premium commission rates per transaction despite lower deal frequency, particularly in Cairo's administrative and retail districts. Investment brokerage is gaining structural importance as Gulf capital and domestic institutional buyers seek portfolio allocation into income-generating assets.
The Financial Regulatory Authority governs mortgage brokerage licensing and consumer protection standards, while the Egyptian Real Estate Registry enforces title verification and transfer documentation requirements that shape transaction timelines. Egypt's building codes and new city development authority approvals create compliance layers that brokerage firms must navigate to list properties in state-planned zones. Stakeholders should monitor how regulatory digitization of land records and electronic notarization reshape speed-to-close metrics and commission structures.
Market Dynamics
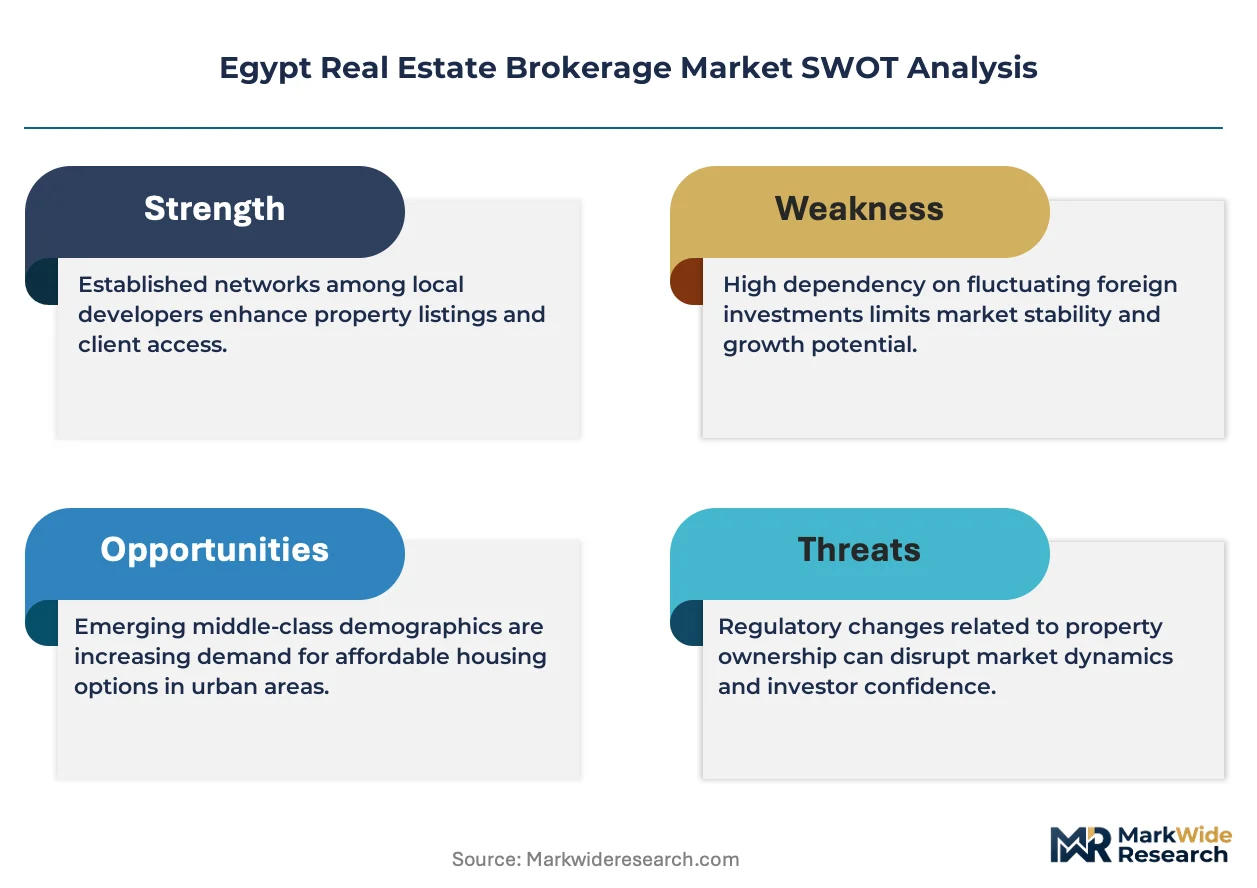
Egypt's Financial Regulatory Authority mortgage reforms are compressing transaction timelines and forcing traditional brokerage models toward digital verification workflows. This regulatory pressure is redistributing competitive advantage toward firms with integrated fintech capabilities.
Growth Catalysts
- New Administrative City pipeline:State-planned urban corridors outside Cairo are generating sustained listing inventory as government relocation mandates activate demand clusters.
- Mortgage finance liberalization:Central Bank of Egypt interest rate adjustments and FRA licensing frameworks are expanding credit-accessible buyer pools beyond cash-dominant segments.
- PropTech integration:Virtual property tours and blockchain-anchored title verification are reducing due diligence friction for remote investors.
Market Restraints
- Title registry fragmentation:Egyptian Real Estate Registry documentation gaps in informal settlements create legal exposure that delays closings and elevates escrow costs.
- Agent commission compression:Digital platform fee structures are squeezing traditional percentage-based remuneration models.
- Gulf capital flow volatility:Regional geopolitical risk and currency fluctuation dampen institutional investment brokerage volumes.
Strategic Opportunities
- Red Sea coastal corridor:Tourism and second-home demand in Hurghada and Marsa Alam remain underpenetrated by organized brokerage networks.
- Sharia-compliant financing:Islamic mortgage product development opens segments previously excluded from conventional interest-bearing instruments.
- AI-powered valuation engines:Machine learning appraisal tools are converging with satellite imagery to accelerate pricing accuracy in emerging compounds.
Industry Challenges
- Licensed agent scarcity:FRA certification requirements and examination pass rates constrain talent pipeline expansion.
- Legacy system integration:Electronic notarization platforms must interface with decades-old paper-based registry archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Real Estate Brokerage Market |
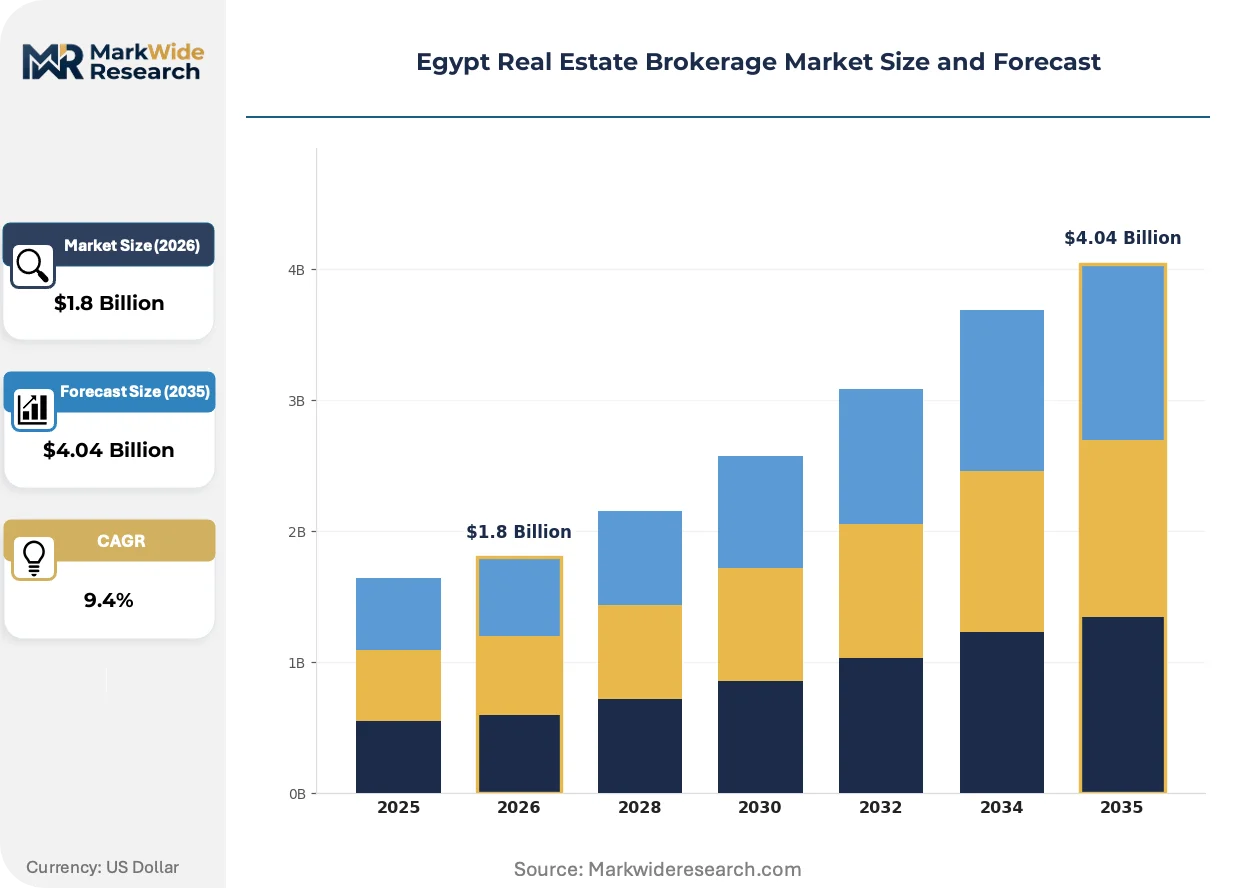
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Brokerage, Commercial Brokerage, Industrial Brokerage, Investment Brokerage Client Type: First-Time Buyers, Investors, Sellers, Renters Transaction Type: Buy, Sell, Lease, Rent Property Type: Residential, Commercial, Mixed-Use, Land |
| Companies Covered | The Address Investments, Coldwell Banker Egypt, Egypt Best Properties, Elbayt, RE/MAX Egypt, ERA Real Estate Egypt, Platinum Properties, New Avenue Real Estate, AqarMap, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Real Estate Brokerage Market Trends and Innovations
Digital infrastructure is reconfiguring how Egyptian buyers discover, evaluate, and close property transactions. Three distinct movements are compressing traditional brokerage functions while elevating data transparency expectations.
Blockchain-anchored smart contracts are displacing paper-based escrow processes in Greater Cairo luxury segments. High-net-worth buyers and Gulf institutional investors are adopting these instruments for New Administrative City acquisitions. The technology is displacing notary-dependent verification timelines that previously extended closings by weeks.
Financial Regulatory Authority electronic mortgage origination mandates are forcing lender-brokerage data interoperability. Origination platforms must now interface directly with FRA-supervised credit bureaus. Commercial brokerage in Cairo's administrative districts faces the steepest compliance recalibration as documentation standards tighten.
First-time buyer cohorts are bypassing traditional agent relationships through direct-developer digital portals. New Cairo and 6th of October City compounds are capturing inquiry traffic that previously filtered through intermediaries. This channel rotation is most pronounced among under-35 demographic clusters in satellite city developments.
Egypt Real Estate Brokerage Market Segmentation
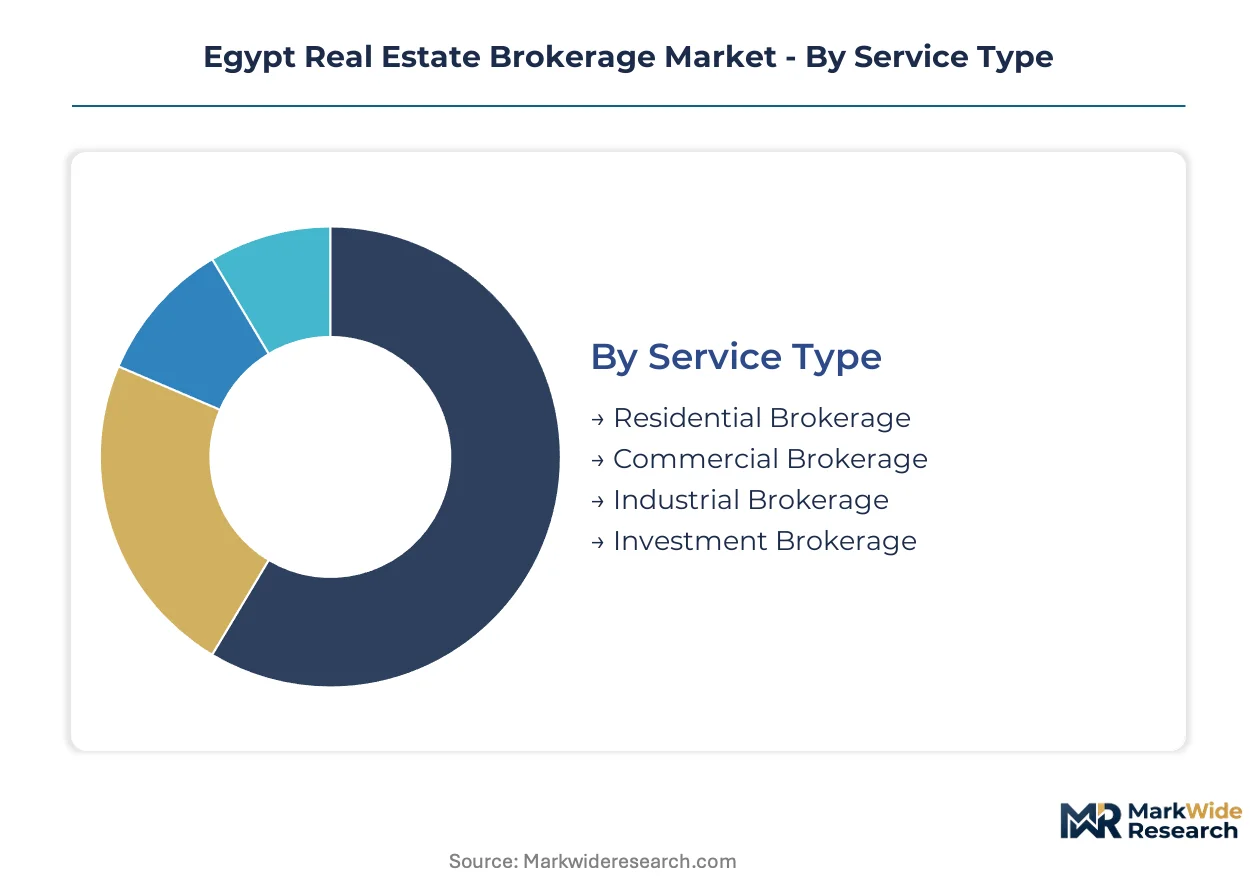
Segmentation reveals how Egypt's brokerage landscape fragments across service models, client profiles, and transaction mechanisms. Each dimension carries distinct commission structures, regulatory exposure, and technology substitution risk that reshape competitive positioning.
Service Type:
Residential brokerage faces the steepest substitution pressure as direct-developer portals and PropTech platforms disintermediate traditional agent relationships in Greater Cairo satellite cities.
- Residential Brokerage:Intermediary services connecting individual buyers and sellers of apartments, villas, and compounds. Demand concentrates in New Administrative City developments as government relocation mandates activate first-time buyer clusters facing mortgage finance liberalization.
- Commercial Brokerage:Office, retail, and hospitality asset transactions with premium commission structures. Cairo's administrative districts anchor deal flow, though Financial Regulatory Authority electronic origination mandates are compressing traditional valuation timelines.
- Industrial Brokerage:Warehouse, factory, and logistics facility transactions. Specialized agents navigate Egyptian Real Estate Registry documentation gaps that elevate escrow complexity.
- Investment Brokerage:Portfolio allocation services for income-generating assets and development projects. Gulf capital volatility constrains deal frequency despite higher per-transaction fees.
Residential brokerage anchors the volume base while investment brokerage gains share at the steepest rate as institutional capital seeks structured exposure.
Client Type:
Commission compression is most severe in the renter segment where digital platforms have commodified matching services across Alexandria and secondary urban corridors.
- First-Time Buyers:Young professionals and families entering formal ownership through mortgage-financed purchases. New Cairo and 6th of October City compounds capture this cohort through integrated developer-broker partnerships.
- Investors:Domestic and Gulf-based buyers seeking rental yield or capital appreciation. Red Sea coastal corridors remain underpenetrated by organized networks serving this segment.
- Sellers:Property owners liquidating assets for relocation, estate settlement, or portfolio rebalancing. Listing velocity fluctuates with Central Bank of Egypt interest rate cycles.
- Renters:Short and medium-term lease seekers in urban employment centers. Platform fee structures have displaced traditional percentage-based representation in this category.
First-time buyers generate the highest transaction frequency while investors command the largest average commission per closing.
Transaction Type:
Lease transactions carry the lowest margin per unit of effort as standardized documentation and recurring renewals reduce broker differentiation.
- Buy:Acquisition transactions involving title transfer, financing coordination, and regulatory compliance. Blockchain-anchored smart contracts are displacing paper-based escrow in luxury Greater Cairo segments.
- Sell:Disposition services encompassing valuation, marketing, negotiation, and closing facilitation. Electronic notarization platforms are compressing timelines for state-planned zone approvals.
- Lease:Commercial and residential tenancy arrangements with recurring revenue potential. AI-powered valuation engines are converging with satellite imagery to accelerate pricing accuracy.
- Rent:Short-term residential arrangements with high volume but compressed fees. Direct-developer portals capture inquiry traffic that previously filtered through intermediaries.
Buy transactions generate the deepest fee pools while lease arrangements deliver the most predictable recurring revenue streams.
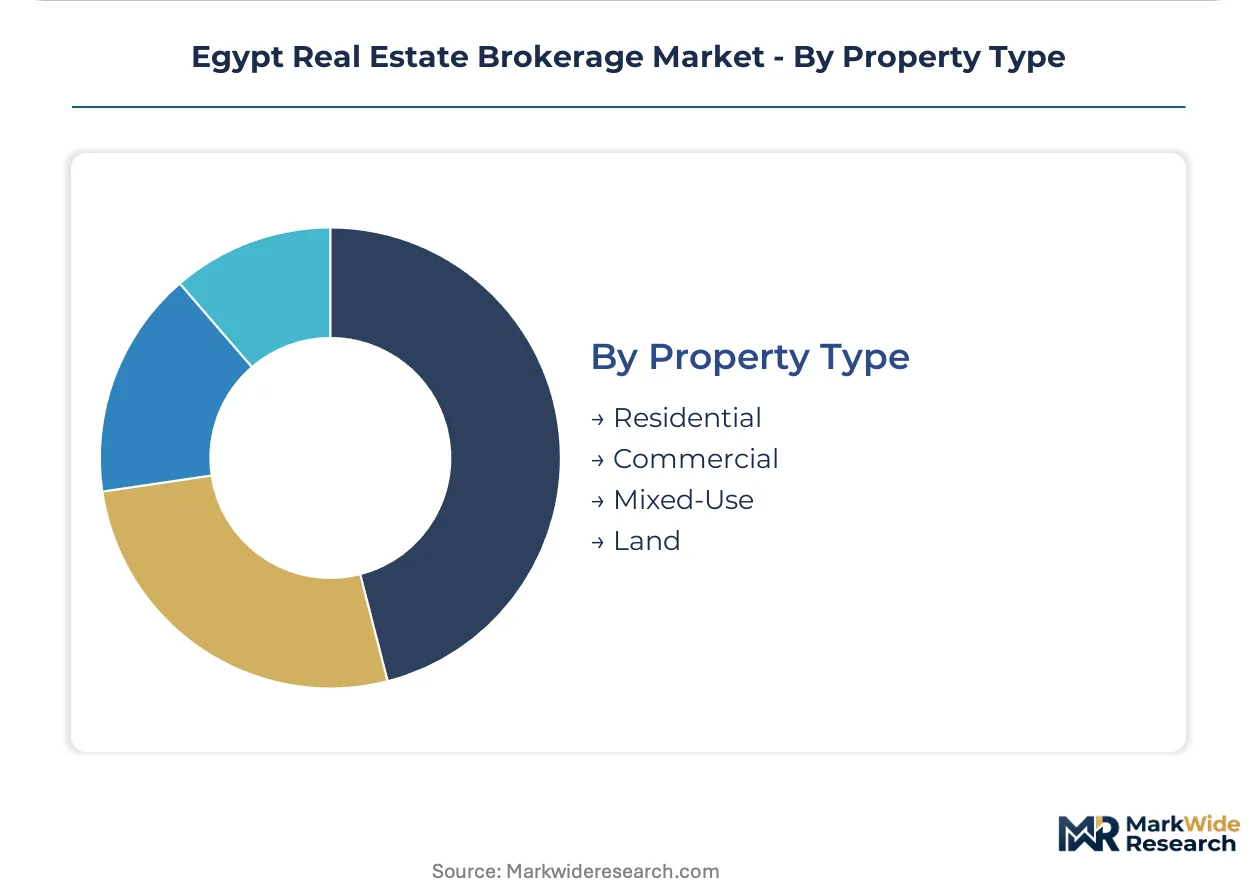
Property Type:
Mixed-use developments face the steepest regulatory complexity as Egyptian building codes and new city development authority approvals create layered compliance requirements.
- Residential:Single-family homes, apartments, and compounds for owner-occupation or rental. Satellite city population expansion sustains listing inventory across Greater Cairo periphery.
- Commercial:Office buildings, retail centers, and hospitality assets. Cairo's administrative districts concentrate premium commission opportunities despite lower deal frequency.
- Mixed-Use:Integrated developments combining residential, commercial, and retail functions. State-planned urban corridors outside Cairo generate sustained inventory as master plans activate.
- Land:Undeveloped parcels for future construction or speculation. Title registry fragmentation in informal settlements creates legal exposure that delays closings.
Residential property dominates transaction volume while mixed-use developments command the highest commission rates per square meter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brokerage service consumption patterns diverge sharply across Egypt's urban hierarchy, with Greater Cairo demanding full-stack transaction support while Red Sea and secondary cities favor lean digital matching platforms.
Greater Cairo
New Administrative City relocations and mortgage finance liberalization are activating first-time buyer clusters across Cairo's eastern periphery. The Financial Regulatory Authority's electronic origination mandates compress closing timelines for satellite city compounds. New Cairo and 6th of October City master-planned developments concentrate listing inventory as government employee housing programs expand.
Alexandria
Coastal property turnover and second-home investment sustain brokerage activity along Alexandria's Mediterranean corridor. Egyptian Real Estate Registry documentation requirements shape transaction velocity in historic districts with fragmented title histories. Smouha and Borg El Arab industrial zones anchor commercial brokerage demand from manufacturing tenants.
Red Sea Coastal Corridor
Tourism property cycles and foreign ownership regulations create volatile but high-margin brokerage opportunities in Hurghada and Marsa Alam. Central Bank of Egypt currency controls influence Gulf investor participation in resort developments. Organized brokerage networks remain underpenetrated relative to organic broker activity in beachfront compounds.
Suez Canal Economic Zone
Industrial logistics demand and port-adjacent warehousing are generating specialized commercial brokerage requirements around Ismailia and Port Said. New city development authority approvals create compliance layers for state-planned zone listings. East Port Said industrial clusters attract tenant representation mandates from multinational facility operators.
Upper Egypt Urban Centers
Informal settlement density and limited mortgage penetration constrain formal brokerage development in Assiut and Sohag. Cash-dominant transactions predominate as FRA-supervised credit bureau coverage remains thin. Localized broker networks operate outside licensed franchise systems with minimal PropTech platform penetration.
Egypt Real Estate Brokerage Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Egypt's brokerage hierarchy. Franchise-anchored networks and digital-first platforms occupy distinct competitive positions, with traditional independent operators filling gaps in secondary cities. Three archetypes dominate: global brand licensees leveraging international recognition, domestic PropTech aggregators controlling listing flow, and boutique specialists serving high-net-worth segments. Competitive moves center on agent recruitment intensification and developer portal partnerships that bypass traditional intermediation.
Among franchise-anchored networks, Coldwell Banker Egypt and RE/MAX Egypt exemplify the global-brand archetype, sustaining cross-Cairo and Alexandria presence through independent agent recruitment. AqarMap occupies a distinct position within the digital aggregation tier, controlling online listing infrastructure that extends reach into emerging compounds. These three represent the primary competitive anchors around which market structure organizes.
| Leading Market Players |
|---|
| The Address Investments |
| Coldwell Banker Egypt |
| Egypt Best Properties |
| Elbayt |
| RE/MAX Egypt |
| ERA Real Estate Egypt |
| Platinum Properties |
| New Avenue Real Estate |
| AqarMap |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day closing timelines in Greater Cairo luxury segments compress commission extraction windows and force brokerage networks toward digital workflow investments that reshape cost structures across agent tiers.
Pricing Analysis
Project-based commission structures dominate Egypt's brokerage landscape, with percentage-based fees scaling from residential lease arrangements through commercial asset dispositions. Price differentiation rests on transaction complexity and regulatory navigation depth, where New Administrative City approvals command premium facilitation fees. Pricing pressure stems from direct-developer portal proliferation that bypasses traditional intermediation in satellite city compounds. First-time buyer segments exhibit acute price sensitivity, while Gulf institutional investors prioritize execution certainty over fee minimization.
Supply Chain Analysis
Financial Regulatory Authority licensing chokepoints constrain agent talent pipelines and elevate recruitment costs for franchise networks across Cairo and Alexandria corridors. Licensed capacity concentrates in Greater Cairo and Alexandria, with secondary cities drawing from informal broker pools that operate outside certified systems. Technology infrastructure dependencies span cloud hosting providers, payment gateway operators, and satellite imagery vendors for valuation engines. Single-source vulnerability sits with Egyptian Real Estate Registry digitization timelines that determine transaction velocity. Distribution runs through hybrid digital-physical channels where online listing aggregation feeds offline closing facilitation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's real estate brokerage sector exhibits cyclical recovery characteristics as Central Bank of Egypt interest rate adjustments reactivate mortgage-accessible buyer pools following contractionary periods.
For Market Incumbents: Consolidate agent networks through FRA certification sponsorship programs that lock talent away from digital-first competitors. Deepen developer portal partnerships in New Administrative City corridors where government relocation mandates sustain listing flow. Anchor defensive positioning against commission compression by controlling exclusive inventory access in master-planned compounds. For New Entrants and Emerging Players: Differentiate on Sharia-compliant financing advisory capabilities that incumbent networks have underdeveloped. Target Red Sea coastal corridors where organized brokerage penetration lags organic broker activity in Hurghada and Marsa Alam resort compounds. Pursue AI-powered valuation engine licensing as the primary go-to-market wedge against traditional appraisal dependencies. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned boutique firms in Alexandria and secondary cities where succession transitions create liquidity events. Long-term viability hinges on digital infrastructure ownership rather than agent headcount accumulation. Monitor Financial Regulatory Authority electronic notarization rollout velocity as the critical inflection signal for transaction timeline compression and commission structure stability.| Strategic Initiative | Industry Significance |
|---|---|
| FRA Licensing Infrastructure Investment | Certified agent pipeline expansion accelerates network scaling in regulatory-compliant segments. |
| Developer Portal Partnership | Exclusive New Administrative City inventory access secures first-time buyer transaction flow. |
| PropTech Platform Integration | Blockchain-anchored smart contracts displace paper-based escrow in luxury Greater Cairo closings. |
| Sharia-Compliant Product Development | Islamic mortgage advisory opens segments excluded from conventional interest-bearing instruments. |
| Red Sea Geographic Expansion | Hurghada and Marsa Alam corridor penetration captures underorganized tourism property cycles. |
Research Methodology
Initial hypotheses were tested against primary input from licensed property agents, Financial Regulatory Authority compliance officers, mortgage finance executives, and new city development authority planners and refined through secondary validation against Egyptian Real Estate Registry documentation protocols, Central Bank of Egypt monetary policy circulars, FRA licensing frameworks, and satellite city master plan disclosures. Bottom-up transaction volume estimates triangulated against top-down market sizing derived from commission rate structures and deal frequency observations.
Variance decomposition across service type, client profile, transaction mechanism, and property category dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling that incorporated mortgage penetration elasticity, government relocation mandate timelines, and PropTech adoption velocity. Industry-specific forecast inputs encompassed FRA electronic origination mandate implementation schedules and Egyptian Real Estate Registry digitization milestone assumptions.
Material uncertainties — regulatory enforcement intensity shifts, Gulf capital flow volatility, and currency fluctuation amplitude — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision triggers including Central Bank of Egypt policy reversals and new city development authority approval process changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
United States Self Storage Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
Lease Management Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Home Warranty Service Market