
 Germany Real Estate Services Market | 2026-2036
Germany Real Estate Services Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Real Estate Services Market Foresight
Bavaria is reshaping commercial property management standards through stringent energy retrofit mandates. Vonovia SE leverages its scale to dominate multifamily portfolio operations across Germany's top urban centers. CBRE Germany competes on cross-border investment advisory strength, while JLL anchors its position through technology-driven valuation platforms.
Germany Real Estate Services encompasses the full spectrum of professional activities supporting property ownership, operation, and transacting, including lease administration, asset valuation, capital markets placement, and integrated building operations. Property management commands the largest revenue pool due to recurring fee structures on Germany's substantial rental housing stock, while facility management shows the fastest structural expansion as corporate occupiers outsource non-core building operations. Residential property types sustain the deepest client base among individual investors and family offices, whereas portfolio deals above €10 million concentrate margin capture for institutional advisory specialists.
KBA oversight of commercial vehicle fleet logistics intersects with industrial property compliance, while the federal Building Energy Act and KfW subsidy frameworks reshape retrofit demand across existing stock. The EU Green Deal's building performance standards tighten operational requirements for service providers. Stakeholders must monitor how Berlin's federal-state regulatory friction over housing policy reshapes investment allocation between Germany's eastern and western metropolitan corridors.
Market Dynamics
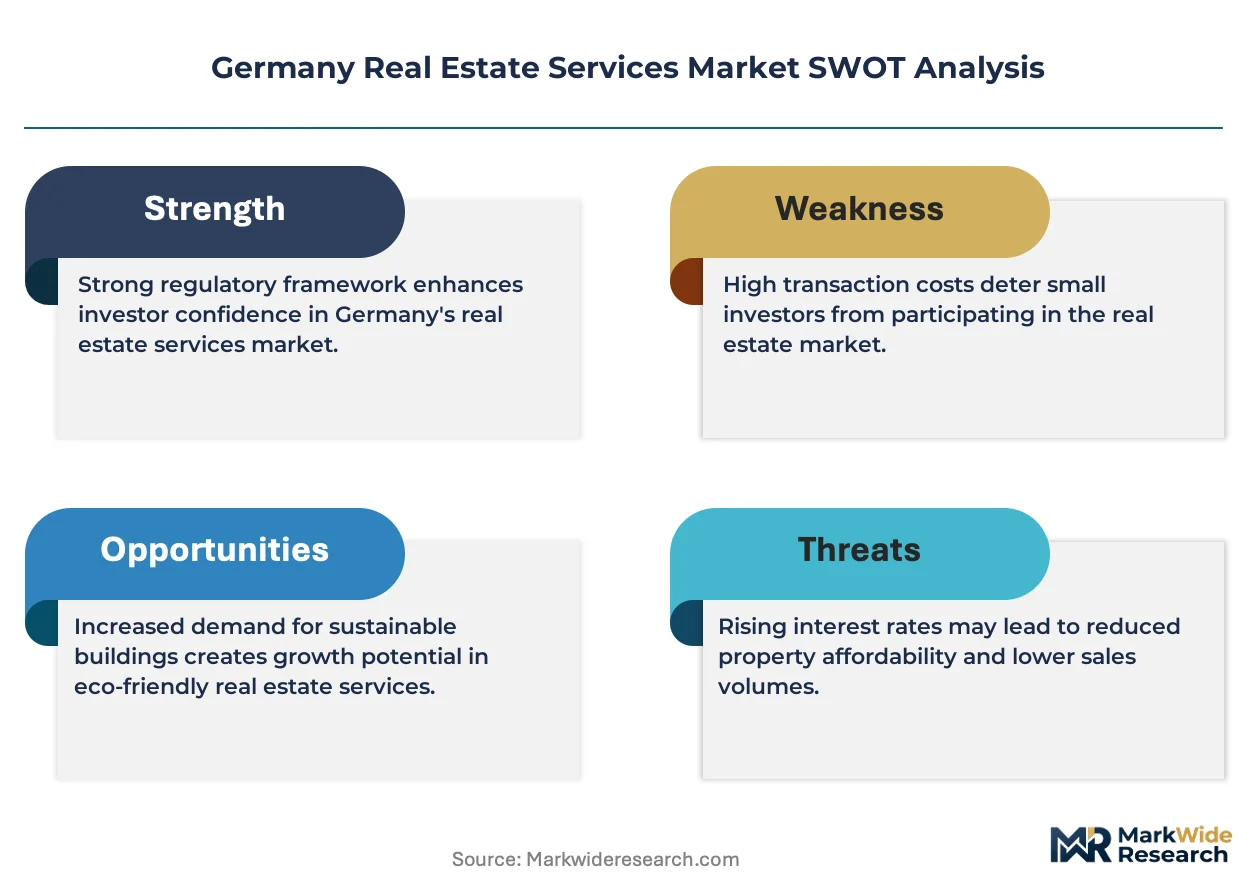
The federal Building Energy Act mandates sweeping thermal efficiency upgrades across Germany's existing building stock, forcing property managers to restructure service portfolios around energy auditing, retrofit coordination, and subsidy navigation. This regulatory pressure concentrates investment into technical capabilities that traditional lease administration providers lack.
Growth Catalysts
- EU Green Deal building performance standards:The tightening operational requirements create mandatory compliance workstreams for energy certification and carbon disclosure across commercial portfolios.
- Corporate occupiers in Frankfurt and Munich:These entities are consolidating vendor relationships into integrated facility management contracts that bundle hard services, soft services, and energy management under single providers.
- KfW subsidy frameworks:The accessible financing mechanisms for building retrofits are accelerating property owner willingness to commission energy audits and execute improvement measures.
Market Restraints
- Skilled technician scarcity:The shortage of certified energy auditors and HVAC retrofit specialists in eastern German states limits execution capacity for mandated building upgrades.
- Regulatory friction between Berlin and federal authorities:The repeated federal-state conflicts over rent control legislation create investment uncertainty that freezes capital allocation decisions in the capital region.
- Construction material cost volatility:Fluctuating prices for insulation systems and heat pump components compress margin predictability on fixed-price retrofit contracts.
Strategic Opportunities
- Underpenetrated small multifamily stock in Saxony and Thuringia:The fragmented ownership structures in these eastern states present aggregation opportunities for portfolio management platforms.
- Convergence of building automation and energy management software:The integration of IoT sensor networks with predictive maintenance algorithms enables new subscription-based service tiers.
- Bavarian commercial energy retrofit mandates:The state's accelerated timeline for non-residential building efficiency creates concentrated demand for project management and compliance documentation services.
Industry Challenges
- Data interoperability across legacy property management systems:The fragmentation of tenant billing, maintenance records, and energy consumption data across incompatible platforms complicates integrated reporting for institutional clients.
- Certification timeline compression for energy auditors:The surge in demand for Building Energy Act compliance documentation outpaces the training pipeline for qualified assessors, creating bottlenecks in service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Real Estate Services Market |
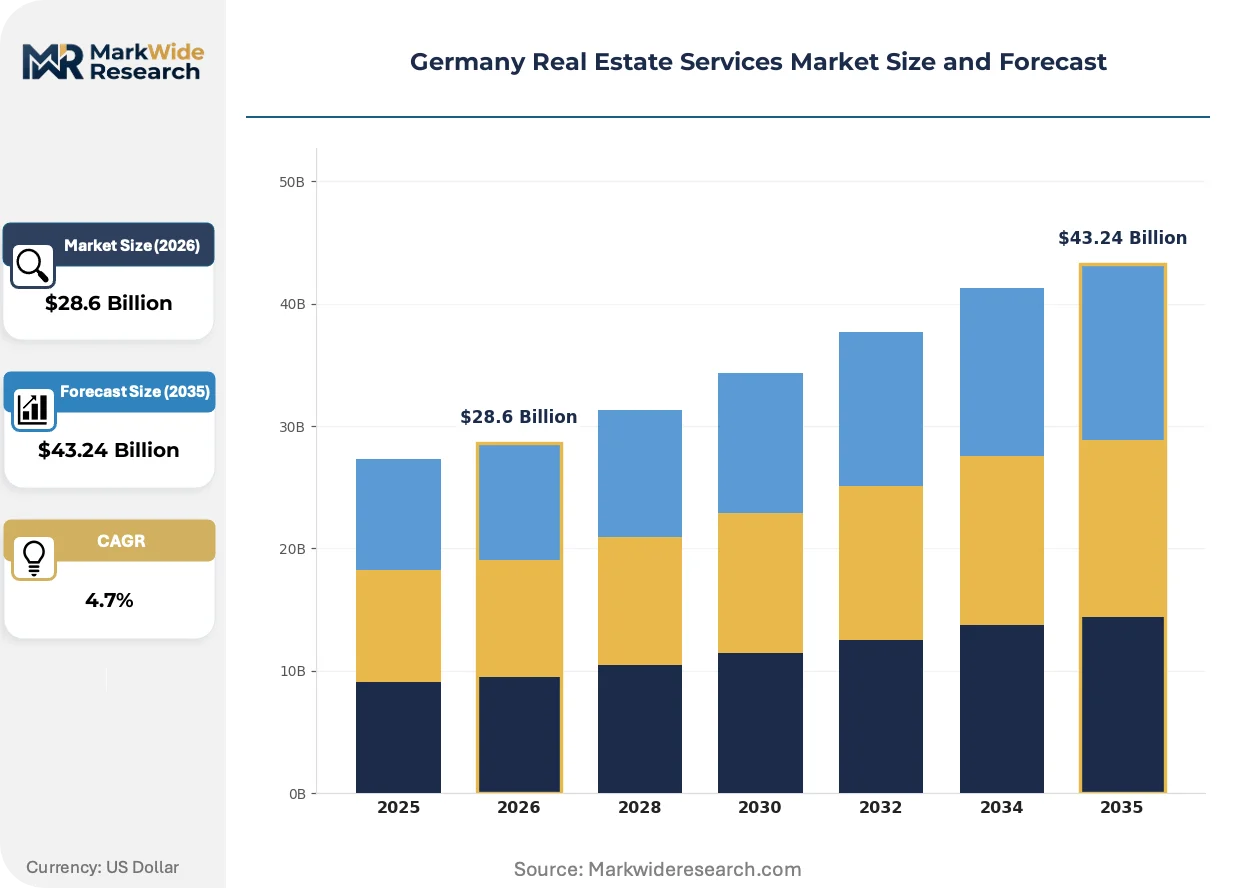
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Property Management, Brokerage, Consultancy, Valuation, Facility Management, Investment Advisory Client Type: Individual Investors, Corporate Entities, Real Estate Developers, Institutional Investors, Family Offices Property Type: Residential, Commercial, Industrial, Retail, Hospitality, Mixed-Use Transaction Size: Below €1 Million, €1 Million - €10 Million, Above €10 Million, Portfolio Deals |
| Companies Covered | Vonovia SE, Deutsche Wohnen SE, Apleona, LEG Immobilien SE, Scout24 SE, CBRE Germany, Cushman & Wakefield, Savills, Jones Lang LaSalle (JLL), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Real Estate Services Market Shifts & Advancements
Digital twin technology and predictive analytics are restructuring how German property managers monitor building performance and anticipate capital needs. These tools compress decision cycles and shift fee structures toward outcome-based arrangements.
Building information modeling integrated with IoT sensor networks is collapsing the traditional separation between design-phase documentation and operational-phase facility management. Mid-size property operators in Hamburg and Stuttgart are adopting these platforms fastest, attracted by reduced insurance premiums and accelerated tenant issue resolution. The technology is collapsing the information asymmetry between asset owners and service providers, forcing transparency on maintenance backlogs and energy performance gaps.
The federal Building Energy Act and its implementing ordinances are mandating granular energy consumption disclosure for commercial buildings above specific floor area thresholds. Property managers must now maintain continuous monitoring infrastructure and report standardized metrics to regulatory databases. The commercial office segment in Frankfurt Rhine-Main is most affected, with landlords retrofitting metering systems and renegotiating lease clauses to pass through compliance costs.
Corporate real estate directors are consolidating previously fragmented service contracts into comprehensive facility management partnerships that embed key performance indicators for uptime, energy intensity, and occupant satisfaction. Traditional hourly-rate maintenance arrangements are yielding to fixed-fee outcome guarantees in Düsseldorf and Cologne corporate campuses. This restructuring is most visible among pharmaceutical and financial services occupiers with large contiguous footprints and regulatory exposure to workplace certification standards.
Germany Real Estate Services Market Segmentation
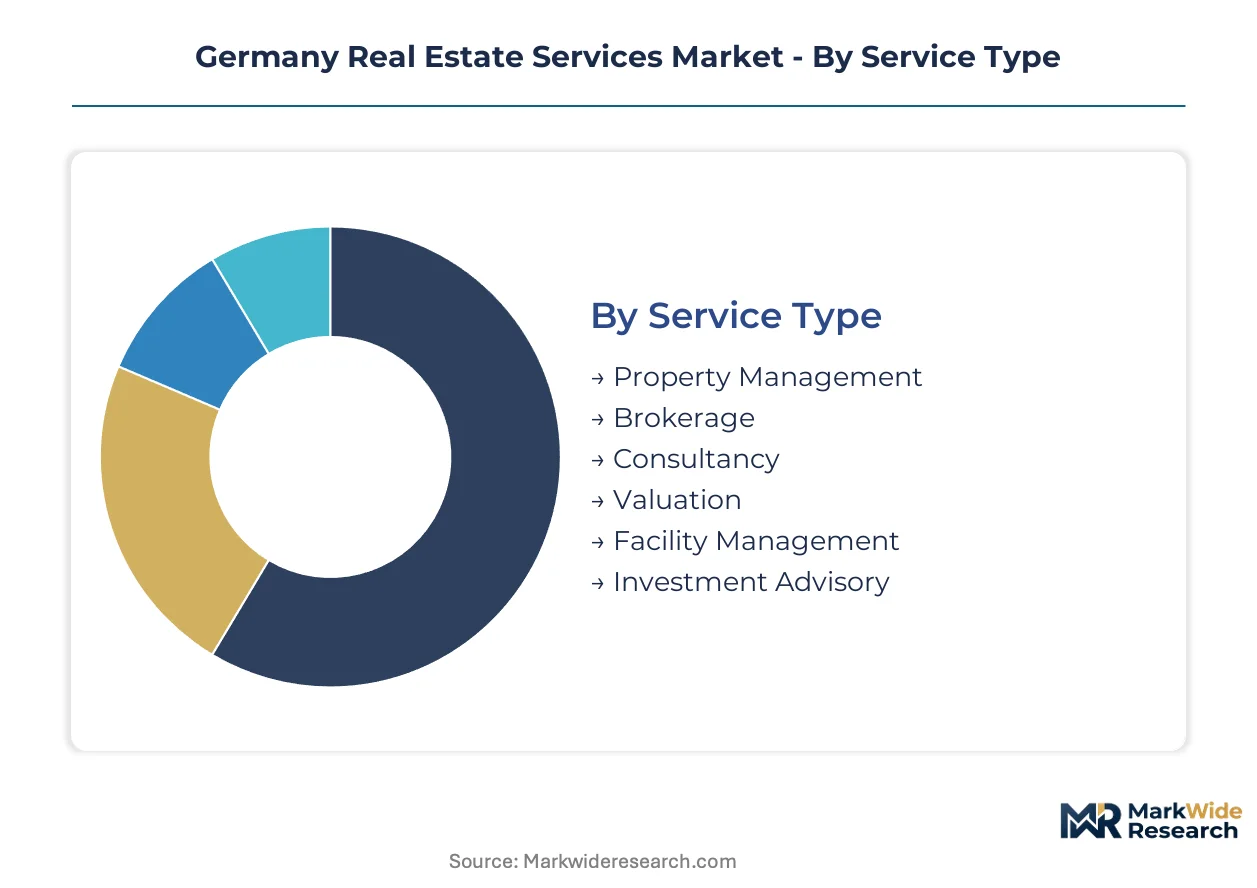
Germany's real estate services market fragments across service maturity, client sophistication, and transaction scale. Each dimension carries distinct margin profiles and capability requirements that reshape competitive positioning.
Service Type:
Mature fee-for-service models dominate recurring revenue streams, while emerging technology-enabled offerings capture expansion capital.
- Property Management:Encompasses lease administration, tenant relations, rent collection, and maintenance coordination across residential and commercial portfolios. Bavaria's energy retrofit mandates concentrate demand for technical property managers who can navigate subsidy frameworks and contractor procurement. This segment handles the majority of throughput.
- Facility Management:Integrates hard services, soft services, and energy management under unified operational contracts. Corporate occupiers in Frankfurt and Munich consolidate vendor relationships here, driven by workplace certification standards and carbon disclosure requirements. This segment is the fastest mover on share.
- Brokerage:Transactional matching of buyers and sellers with commission structures tied to deal closure.
- Consultancy:Strategic advisory on portfolio allocation, development feasibility, and market entry timing.
- Valuation:Asset appraisal for financing, reporting, and regulatory compliance purposes.
- Investment Advisory:Capital placement guidance for institutional allocations into German real estate.
Property management commands the deepest revenue base; facility management shows the steepest expansion trajectory.
Client Type:
Cost tier stratification separates high-touch institutional relationships from standardized retail service delivery.
- Institutional Investors:Pension funds, insurance companies, and sovereign wealth vehicles deploying capital into German multifamily and logistics portfolios. These clients demand integrated reporting, ESG compliance documentation, and cross-border transaction execution capabilities concentrated in Berlin and Frankfurt.
- Corporate Entities:Occupiers seeking integrated facility management partnerships with embedded performance guarantees. Pharmaceutical and financial services firms in Düsseldorf and Cologne drive consolidation of previously fragmented service contracts.
- Individual Investors:Small-scale landlords requiring basic lease administration and maintenance coordination.
- Real Estate Developers:Project sponsors needing pre-leasing, marketing, and post-completion management handover.
- Family Offices:Private wealth vehicles with hybrid needs spanning direct property oversight and portfolio-level advisory.
Institutional investors anchor fee concentration; corporate entities are expanding most quickly as outsourcing deepens.
Property Type:
Application-driven segmentation separates regulated residential stock from yield-focused commercial assets.
- Residential:Multifamily rental housing subject to federal and state-level tenancy protections. Berlin's rent control turbulence and the Building Energy Act retrofit mandates reshape service requirements across eastern and western metropolitan corridors.
- Commercial:Office properties facing granular energy consumption disclosure requirements under federal implementing ordinances. Frankfurt Rhine-Main landlords retrofit metering systems and renegotiate lease clauses to pass through compliance costs.
- Industrial:Logistics and manufacturing facilities with KBA fleet compliance intersections.
- Retail:High-street and shopping center assets adapting to footfall measurement and tenant mix optimization.
- Hospitality:Hotels and serviced apartments requiring operational intensity and brand standard enforcement.
- Mixed-Use:Developments combining residential, commercial, and retail components with complex governance structures.
Residential sustains the broadest client base; commercial office is gaining share fastest on regulatory compliance spend.
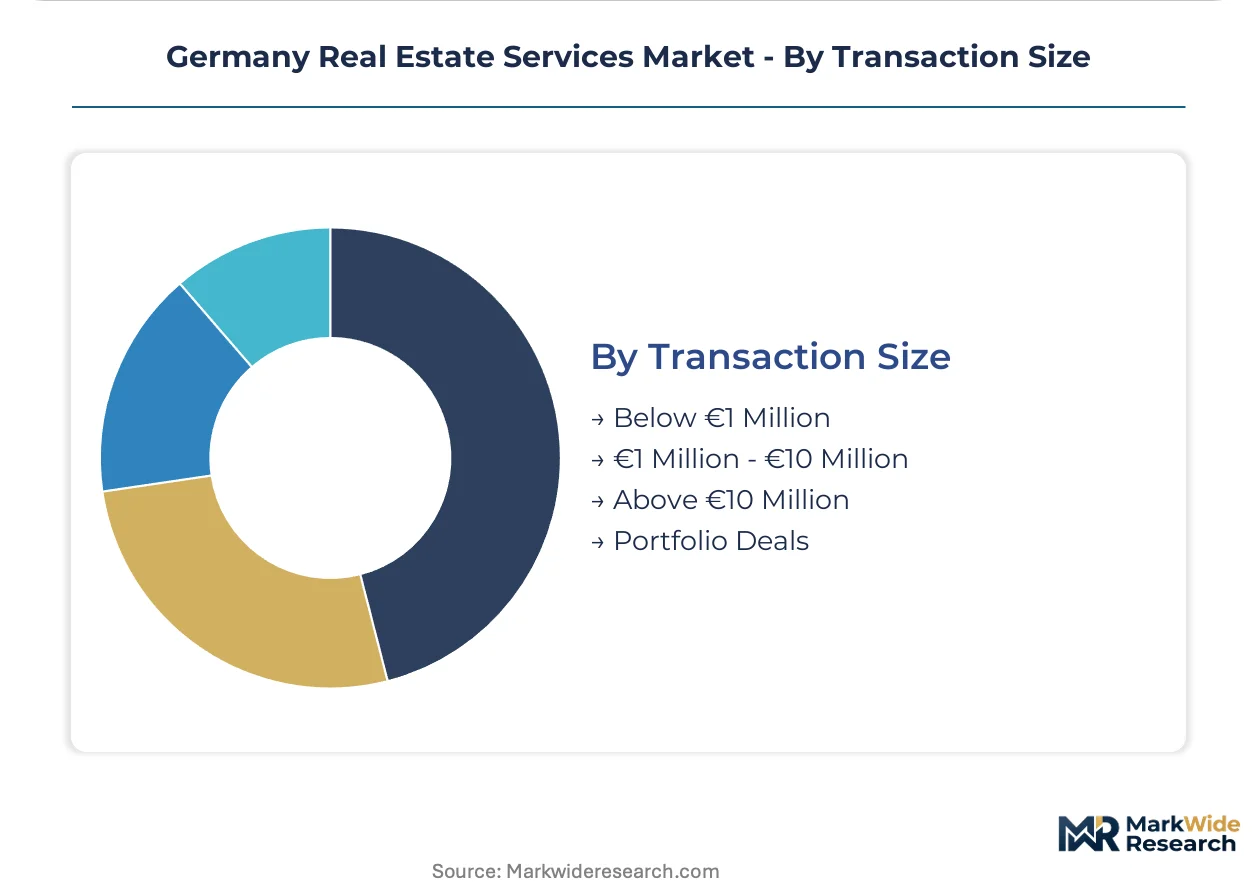
Transaction Size:
Volume concentration determines margin capture, with scale thresholds separating retail brokerage from institutional advisory specialization.
- Portfolio Deals:Multi-asset transactions above €10 million concentrating margin capture for advisory specialists. Vonovia SE and comparable platforms aggregate fragmented eastern German stock in Saxony and Thuringia through these channels.
- Above €10 Million:Single-asset institutional trades requiring due diligence coordination and financing arrangement.
- €1 Million - €10 Million:Mid-market transactions serving family offices and wealth advisors.
- Below €1 Million:Retail-scale deals with standardized processes and compressed fee margins.
Portfolio deals concentrate premium advisory economics; the €1-10 million bracket is climbing the fastest on family office activation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider networks cluster around Germany's metropolitan corridors where transaction velocity and regulatory complexity concentrate demand. The federal system delegates building energy enforcement to state authorities, creating differentiated compliance environments across sub-regions.
Bavaria
Commercial property managers navigate accelerated energy retrofit mandates for non-residential stock. The state's building authority enforces stricter timelines than federal minimums. Munich's corporate campus concentration drives integrated facility management contract consolidation among pharmaceutical and technology occupiers.
North Rhine-Westphalia
Industrial logistics corridors generate facility management demand at the intersection of KBA fleet compliance and property operations. The state's building energy office administers KfW subsidy distribution for retrofit projects. Düsseldorf and Cologne host pharmaceutical headquarters outsourcing building operations under performance-guarantee structures.
Hesse
Frankfurt's financial services density concentrates demand for energy disclosure compliance and carbon reporting infrastructure. The regional energy agency implements federal Building Energy Act ordinances for commercial buildings above floor area thresholds. Frankfurt Rhine-Main landlords retrofit metering systems and renegotiate lease pass-through clauses.
Berlin-Brandenburg
Multifamily portfolio operators adjust to federal-state regulatory friction over tenancy legislation. The capital region's rent control turbulence freezes capital allocation timing for institutional investors. Berlin's eastern boroughs present aggregation opportunities for fragmented small-landlord stock under professional management platforms.
Baden-Württemberg
Mid-size property operators adopt digital twin and IoT-enabled building automation fastest. The state's technical university network feeds engineering talent into energy auditing and HVAC retrofit specializations. Stuttgart's automotive supplier headquarters demand workplace certification compliance and integrated service bundles.
Germany Real Estate Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The market structures around scale-driven residential portfolio operators, cross-border investment advisory networks, and technology-enabled valuation platforms. Three archetypes dominate: integrated facility management providers, multifamily portfolio aggregators, and transaction-focused brokerage-advisory hybrids. Competitive moves concentrate on energy retrofit capability acquisition and building automation software integration.
Among residential portfolio specialists, Vonovia SE and LEG Immobilien SE exemplify scale-driven operators leveraging unit concentration to standardize property management workflows. Deutsche Wohnen SE occupies a position within the same archetype, representing consolidation strategies targeting eastern German multifamily stock. Within the advisory tier, CBRE Germany and JLL anchor cross-border investment placement and technology-driven valuation services respectively. Apleona sits within the integrated facility management segment, exemplifying bundled hard and soft service delivery for corporate occupiers.
| Leading Market Players |
|---|
| Vonovia SE |
| Deutsche Wohnen SE |
| Apleona |
| LEG Immobilien SE |
| Scout24 SE |
| CBRE Germany |
| Cushman & Wakefield |
| Savills |
| Jones Lang LaSalle (JLL) |
| Others |
Supply & Pricing Matrix
Skilled technician scarcity in eastern German states determines both pricing tier spreads and supply chain shape, compressing margins on fixed-price retrofit contracts while forcing service providers to restructure procurement around certified energy auditor availability and HVAC specialist networks.
Pricing Analysis
The federal Building Energy Act dictates the pricing tier structure across property management services. Three-tier pricing separates premium advisory bundles from standard compliance packages from economy maintenance retainers. Price differentiation rests on certification level for energy auditors and volume scale of portfolio contracts. Pricing pressure stems from construction material cost volatility in insulation systems and heat pump components. Small multifamily landlords in Saxony and Thuringia exhibit highest price sensitivity; institutional investors in Frankfurt and Munich demonstrate lowest sensitivity due to embedded ESG compliance requirements.
Supply Chain Analysis
Single-source vulnerability in certified energy auditor training pipelines dominates supply chain risk for compliance documentation services. Geographic supply concentration centers on Germany, Austria, and Switzerland for HVAC retrofit equipment and building automation systems. Raw material dependencies include mineral wool insulation, heat pump refrigerants, and IoT sensor hardware. Distribution runs through regional contractor networks coordinated by property management platforms, with KfW subsidy administration acting as a procurement chokepoint for retrofit project financing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across small multifamily ownership in eastern German states creates aggregation opportunities, as the Building Energy Act retrofit mandates force professionalization of previously informal landlord operations.
For Market Incumbents: Build regulatory compliance moats through vertical integration into energy auditing certification programs. Acquire HVAC retrofit specialists in Saxony and Thuringia to secure execution capacity. Invest in building automation software platforms to capture subscription revenue from outcome-based service tiers. The threat of data interoperability failures across legacy systems demands proprietary integration layers as defensive infrastructure. For New Entrants and Emerging Players: Eastern German small multifamily stock offers the most penetrable geography for portfolio management platforms. Target Berlin-Brandenburg's fragmented ownership structures with subsidy navigation services bundled into property management retainers. Pursue white-space in Bavarian commercial energy retrofit project management, where accelerated state timelines outpace incumbent capacity. A go-to-market angle anchored in KfW financing expertise differentiates against established lease administration providers. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors technical capability aggregators over traditional brokerage-advisory hybrids. Long-term viability over the next decade hinges on energy retrofit execution capacity and building automation software integration. Acquisition targets should demonstrate certified auditor pipelines and IoT-enabled predictive maintenance platforms. Monitor Berlin federal-state regulatory friction resolution as the signal for capital allocation timing normalization in the capital region.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Auditor Certification Pipeline Investment | Builds captive compliance capacity as the federal Building Energy Act documentation surge outpaces training output. |
| Building Automation Platform Integration | Enables subscription-based service tiers through IoT sensor networks and predictive maintenance algorithms. |
| Eastern German Portfolio Aggregation | Captures fragmented small-landlord stock in Saxony and Thuringia under professional management platforms. |
| KfW Subsidy Navigation Service Layer | Accelerates property owner willingness to commission retrofits through accessible financing mechanism expertise. |
| Integrated Facility Management Partnership Consolidation | Captures corporate occupier demand in Frankfurt and Munich for bundled hard services, soft services, and energy management. |
Research Methodology
Cross-validation between primary interviews with property management executives, facility management procurement leads, energy auditing specialists, and KfW program administrators and secondary validation through federal Building Energy Act implementing ordinances, KBA commercial vehicle fleet compliance documentation, EU Green Deal building performance standards, and Vonovia SE and LEG Immobilien SE regulatory filings anchors the qualitative findings. Bottom-up service provider capacity assessments and top-down investment flow analysis triangulate market sizing.
Calibration against historical retrofit completion rates and subsidy disbursement velocity informs the analytical framework across the projection horizon. Segmentation dimensions modeled include service type maturity, client sophistication tier, property type regulatory exposure, transaction scale threshold, and regional enforcement intensity. CAGRs derive from trend extrapolation adjusted for regulatory implementation timelines. Forecast inputs incorporate certified auditor training pipeline capacity and construction material cost volatility indices.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and construction labor availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and subsidy program continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
United States Self Storage Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Green Lease Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Global Home Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Property Tax Services Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
US Home Service Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Relocation Management Service Market