
 Global Self Storage Market | 2026-2036
Global Self Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self Storage Market Foresight
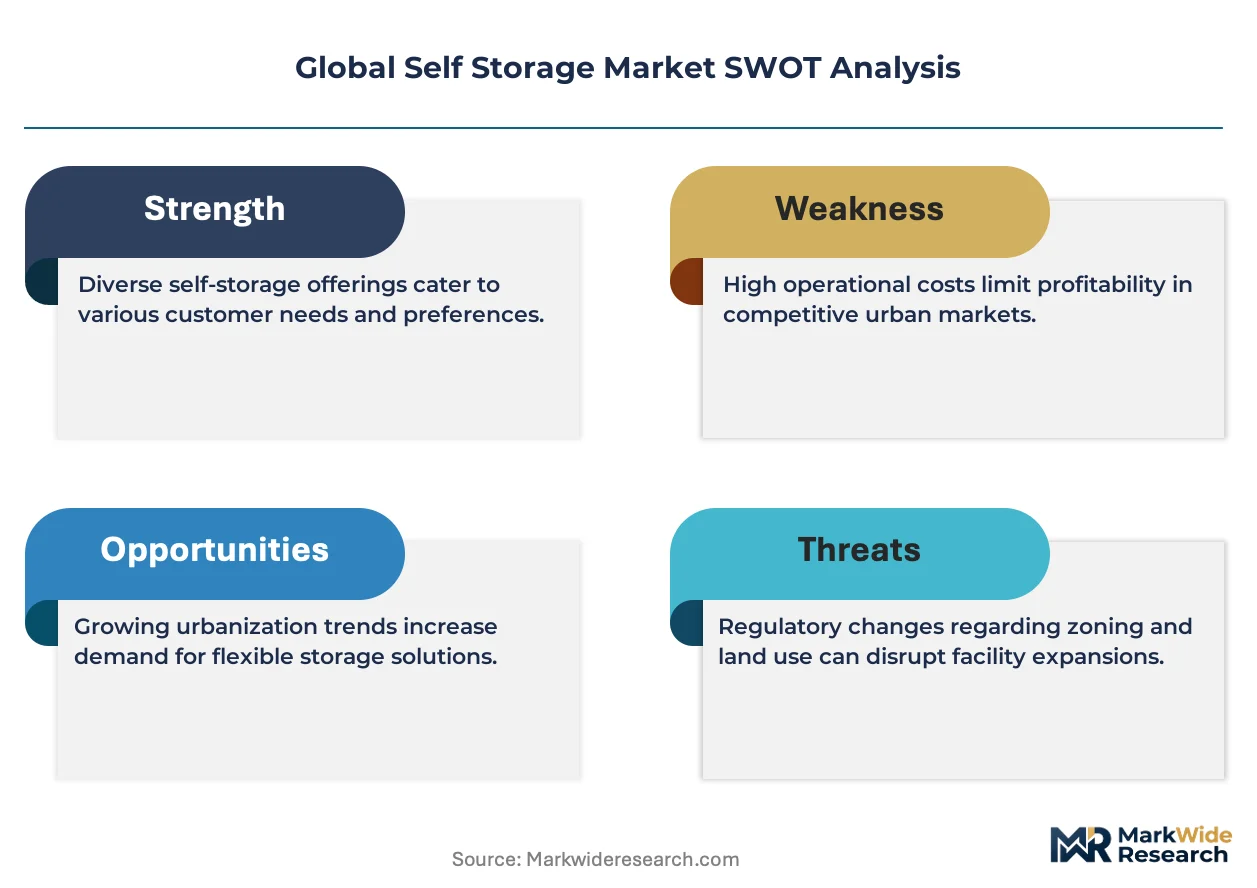
Climate-controlled service tiers is realigning how operators package and price storage offerings. Public Storage leverages its extensive nationwide footprint to anchor premium positioning in major metropolitan corridors. Extra Space Storage competes through technology-integrated property management platforms that sustain operational efficiency across diverse markets. CubeSmart specializes in third-party management services, extending its revenue model beyond owned assets.
Self storage denotes a commercial real estate category providing leased, enclosed space for temporary goods retention, typically featuring roll-up doors, concrete or steel construction, and perimeter security systems designed for individual access control. The primary commercial purpose centers on monetizing underutilized land or structures through recurring rental income from consumers and businesses requiring flexible, short-to-medium duration storage without long-term lease obligations. Climate-controlled facilities capture disproportionate margin pools as humidity-sensitive goods storage commands sustained premium pricing, while mobile storage services represent the fastest-growing service type as urban consumers prioritize doorstep collection and delivery over traditional facility visits. Individual customers dominate current occupancy volumes, though business customer segments exhibit accelerated expansion as e-commerce sellers and contractors seek distributed inventory solutions.
The US Department of Housing and Urban Development's zoning frameworks and local municipal land-use codes shape facility development timelines and permissible locations across American markets, while the EPA's stormwater management requirements influence site engineering standards for outdoor storage configurations. European operators navigate REACH chemical safety protocols and national building energy codes that constrain climate-controlled facility design specifications. Stakeholders must monitor evolving municipal restrictions on self storage construction in residential-adjacent zones and assess automation capital deployment against labor cost trajectories in target markets.
Market Dynamics
Smart access technologies and automated gate systems are compressing operational labor requirements while repositioning facility economics toward technology-enabled service tiers.
Growth Catalysts
- Small business inventory decentralization:E-commerce sellers and contractors across the United States are expanding distributed storage footprints to reduce last-mile fulfillment costs.
- REACH chemical safety protocols:European climate-controlled facility specifications are tightening, creating compliant capacity scarcity that sustains premium pricing power for certified operators.
- Mobile storage doorstep logistics:Urban consumers in dense metropolitan corridors are substituting facility visits with container collection and delivery services.
Market Restraints
- Land-use code fragmentation:Municipal zoning restrictions in residential-adjacent zones across American markets are extending development timelines and limiting permissible facility locations.
- Stormwater engineering compliance:EPA management requirements for outdoor storage configurations are elevating site preparation costs and constraining expansion in flood-prone geographies.
- Climate system energy intensity:Humidity-controlled environments face sustained electricity cost pressure, compressing margins on non-premium service tiers.
Strategic Opportunities
- Third-party management services:Asset-light revenue models extending beyond owned properties are capturing institutional capital seeking operational expertise without real estate exposure.
- India urban storage penetration:Tier-1 city housing transitions and SME inventory growth are creating whitespace for organized self storage development in underpenetrated South Asian markets.
- ISO 27001 data security certification:Smart facility platforms integrating tenant access logs and payment systems can differentiate through information security credentials.
Industry Challenges
- Automation capital deployment timing:Facility operators face execution risk in matching technology investment cycles against local labor cost trajectories.
- Legacy access system integration:Retrofitting biometric and mobile credentialing into existing perimeter security infrastructure creates operational downtime and tenant friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self Storage Market |
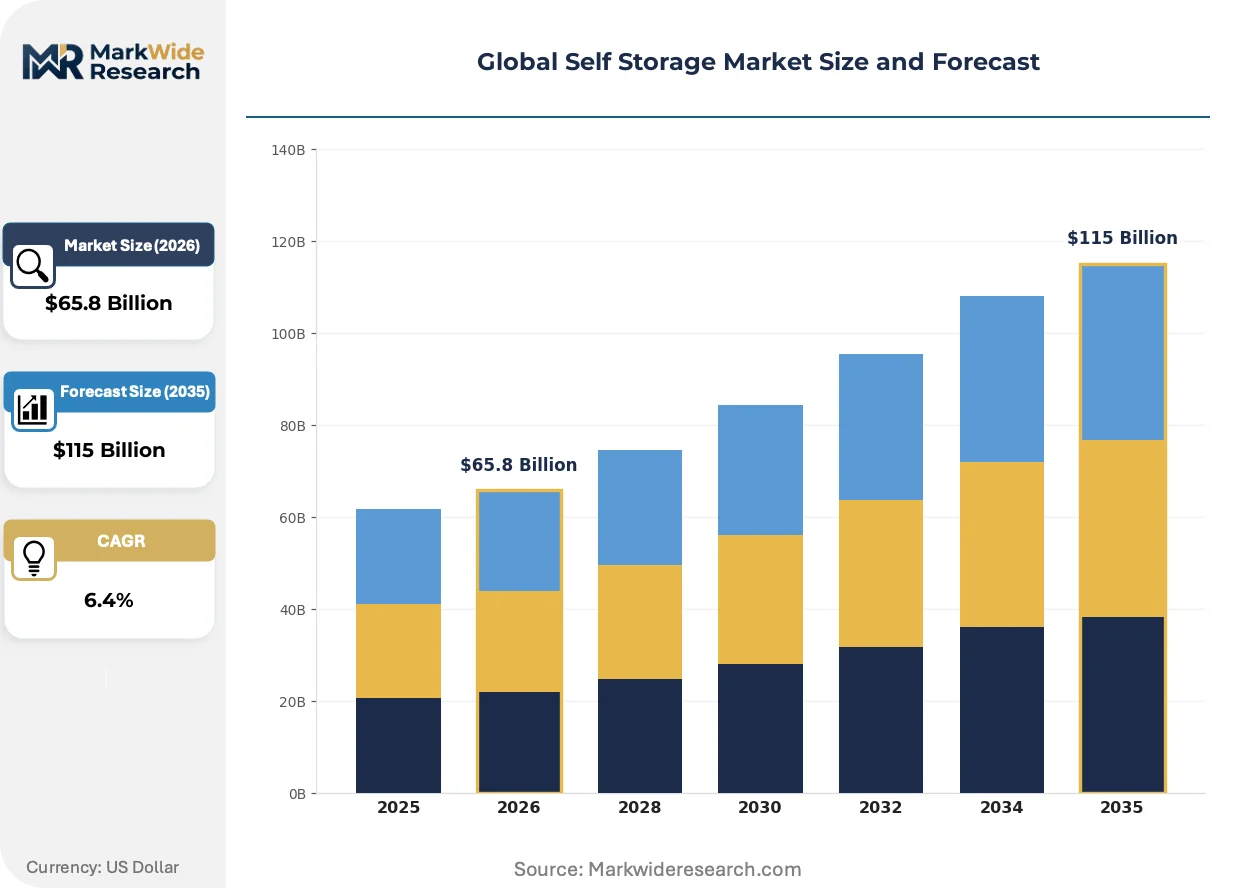
| Market Size in 2026 | $65.8 Billion |
| Market Size in 2035 | $115 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor, Outdoor, Climate-Controlled, Vehicle Storage Unit Size: Small, Medium, Large, Extra Large Customer Type: Individual, Business, Student, Military Service Type: Self-Service, Full-Service, Mobile Storage, Remote Access |
| Companies Covered | Public Storage, Extra Space Storage, CubeSmart, U-Haul International, National Storage Affiliates, Life Storage, Safestore, Big Yellow Self Storage, Shurgard Self Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self Storage Market Shifts & Advancements
Facility operations are pivoting from passive space rental toward technology-mediated service experiences that compress customer acquisition costs and extend lease duration.
Biometric entry systems and smartphone credentialing are rewriting tenant access protocols across major metropolitan facilities. Urban consumers and business account holders are adopting mobile-first entry at accelerating rates. This credentialing shift is enabling dynamic unit pricing and real-time availability management that compresses traditional front-desk staffing models.
EPA stormwater management requirements are tightening engineering standards for outdoor storage configurations in American markets. Industrial consequences include elevated site preparation costs and extended permitting timelines for ground-up developments. Facility operators in coastal and flood-prone geographies are responding with elevated concrete pad specifications and enhanced drainage infrastructure.
Subscription-based storage models are displacing traditional month-to-month leasing in urban consumer segments. Digital-native platforms are bundling pickup, transport, and inventory management services that disintermediate conventional facility visits. This behavioral pivot is most visible in dense housing markets across the United States and Western Europe where space constraints and convenience premiums align.
Global Self Storage Market Segmentation
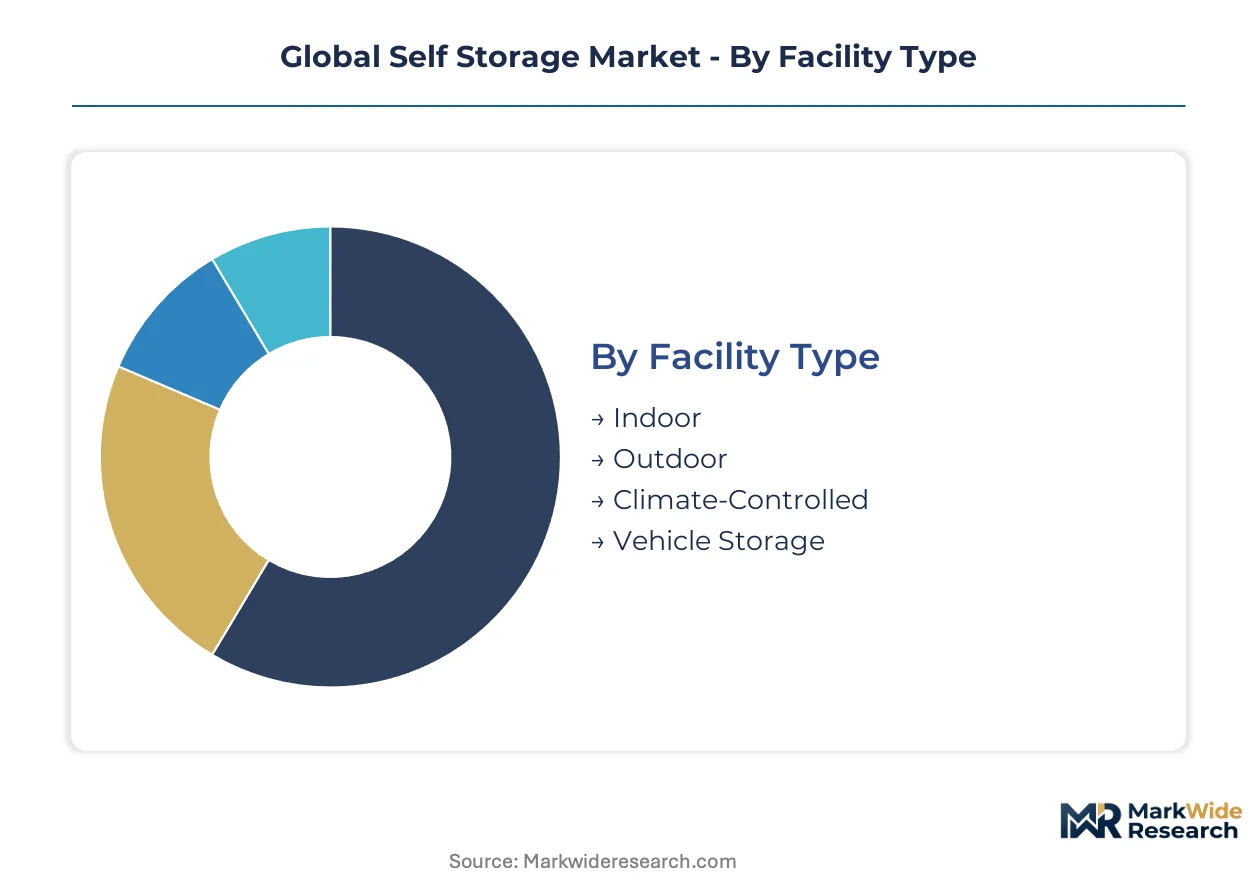
Segmentation in self storage reveals divergent capital requirements and margin profiles across facility configurations. Understanding these structural differences enables operators to align development budgets with local demand density and competitive positioning.
Facility Type:
Capital intensity varies dramatically across facility configurations, with climate infrastructure and specialized construction driving upfront investment tiers.
- Indoor:Multi-story steel or concrete structures with elevator systems and interior corridors. Demand concentrates in dense northeastern US corridors and Japanese metropolitan wards where land scarcity forces vertical development and tenants prioritize security over drive-up access.
- Outdoor:Single-story drive-up units on paved surfaces with minimal building envelope. Texas and Florida operators favor this format for its lower construction cost per square foot, though stormwater management compliance elevates site preparation expenses in flood-prone submarkets.
- Climate-Controlled:Humidity and temperature regulation systems maintaining 55-80°F ranges year-round. European REACH protocols and US EPA energy standards constrain equipment specifications.
- Vehicle Storage:Covered or uncovered bays accommodating RVs, boats, and commercial fleets. Australian coastal markets and US Sun Belt retirement corridors sustain premium pricing for enclosed vehicle bays.
Most installed capacity flows through Outdoor configurations. Expansion is steepest in Climate-Controlled as humidity-sensitive inventory storage commands sustained premium pricing.
Unit Size:
Revenue per square foot and lease duration patterns diverge across unit dimensions, with smaller formats capturing urban convenience premiums.
- Small:Lockers and compact units under 50 square feet for document storage and seasonal items. Manhattan, London, and Singapore operators command per-square-foot premiums that offset higher customer acquisition costs in hyperdense housing markets.
- Medium:Standard 5x10 to 10x10 configurations serving household transitions. Suburban US markets and German Mittelstand business districts sustain stable occupancy through residential mobility and small inventory decentralization.
- Large:10x15 to 10x20 units accommodating full household contents. Canadian prairie cities and Australian suburban corridors favor this format for family relocation storage.
- Extra Large:Warehouse-scale spaces exceeding 300 square feet for commercial inventory and equipment. Indian Tier-1 SME clusters and US e-commerce fulfillment nodes are expanding distributed storage footprints in this category.
Medium units dominate current revenue contribution. Small formats are climbing the fastest as urban density intensifies space constraints in major metropolitan housing markets.
Customer Type:
Contract structures and lifetime value profiles shift markedly across tenant categories, with business accounts exhibiting longer retention and lower price sensitivity.
- Individual:Residential tenants storing household goods during life transitions. US Sun Belt migration corridors and UK property chains sustain demand through divorce, death, and downsizing events.
- Business:E-commerce sellers, contractors, and service firms requiring distributed inventory positioning. Amazon third-party sellers across Germany and construction subcontractors in UAE free zones are accelerating contract volume in this segment.
- Student:Seasonal storage demand aligned with academic calendars. University towns in Massachusetts, Oxford, and Melbourne experience predictable summer vacancy cycles that compress annual yield.
- Military:Government-contracted or personally procured storage during deployment rotations. San Diego, Norfolk, and Kaiserslautern facility clusters benefit from permanent military presence and PCS mobility patterns.
Individual contracts represent the largest installed base. Business accounts are gaining share fastest as SME inventory decentralization accelerates across developed markets.
Service Type:
Operational labor intensity and technology infrastructure requirements define competitive positioning across service tiers.
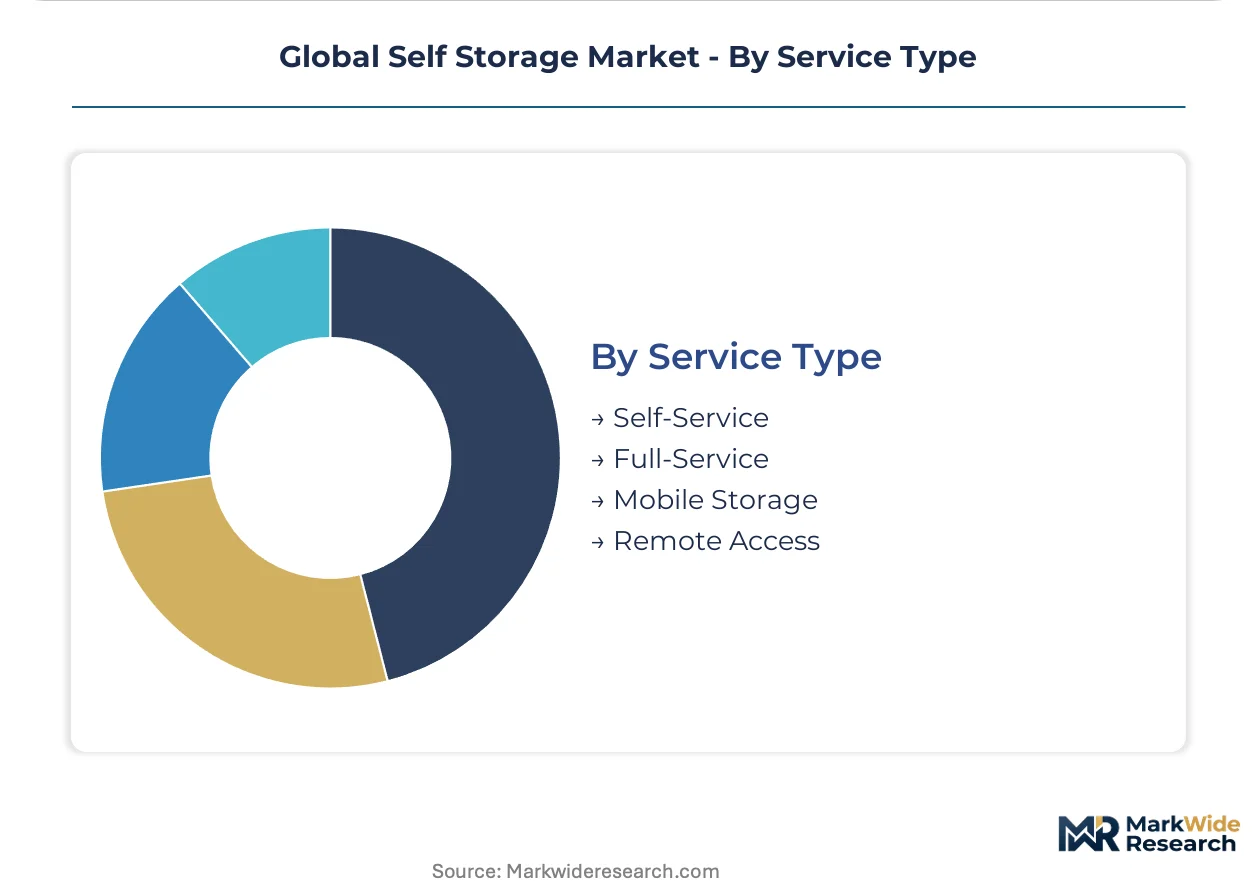
- Self-Service:Traditional facility access with minimal staff presence. US secondary markets and French provincial cities sustain this model through lower rent structures and established tenant self-sufficiency.
- Full-Service:Staffed facilities with moving assistance, packing supplies, and concierge support. High-income Tokyo wards and Manhattan corridors justify labor costs through premium pricing and extended lease duration.
- Mobile Storage:Doorstep container delivery and retrieval logistics. London, Amsterdam, and San Francisco consumers are substituting facility visits with collection services that compress total storage friction.
- Remote Access:Smartphone credentialing and automated entry without on-site staff. South Korean smart city developments and Nordic automation-forward markets favor this capital-intensive, labor-light configuration.
Self-Service capacity retains the largest footprint. Mobile Storage is expanding most quickly as urban convenience premiums reshape consumer expectations in dense metropolitan corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting facility development capital toward jurisdictions with streamlined permitting and lighter environmental compliance burdens. Operators in lower-regulation markets compress development timelines while peers in restrictive geographies absorb extended approval cycles and elevated site preparation costs.
United States
Urban density in Manhattan, San Francisco, and Seattle sustains premium pricing for climate-controlled units as housing transitions accelerate. The EPA's stormwater management requirements elevate engineering standards for outdoor configurations in flood-prone coastal submarkets. Houston and Phoenix operators favor single-story drive-up formats for their lower construction cost per square foot.
Germany
Mittelstand inventory decentralization drives demand for medium-format units in business districts across Munich, Hamburg, and Frankfurt. REACH chemical safety protocols constrain climate-controlled facility specifications, creating compliant capacity scarcity. Berlin's housing stock constraints and rental market friction sustain individual tenant segments through life transition events.
United Kingdom
Property chain delays and downsizing trends in London, Oxford, and Cambridge generate consistent household storage demand. GDPR compliance requirements shape smart facility platform development for tenant data protection. Manchester and Birmingham logistics corridors attract business accounts from e-commerce sellers seeking distributed inventory positioning.
Australia
Retirement corridor migration along the Gold Coast and Sunshine Coast sustains premium vehicle storage pricing for enclosed RV and boat bays. The country's national building energy codes influence climate system specifications for humidity-controlled environments. Sydney and Melbourne operators face land scarcity pressures that favor vertical indoor formats over expansive outdoor configurations.
India
Tier-1 city housing transitions in Mumbai, Bangalore, and Delhi-NCR create whitespace for organized self storage development among underpenetrated SME clusters. The country's central bank monetary policy affects commercial real estate financing availability for ground-up developments. Hyderabad and Pune technology corridors exhibit accelerating business account adoption as contract manufacturers and e-commerce sellers expand distributed footprints.
Global Self Storage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with facility ownership concentration varying by market maturity. The United States exhibits the highest ownership consolidation among REIT-structured operators, while European and Asian markets retain greater fragmentation among regional independents. Three archetypes dominate: vertically integrated REITs controlling development and operations, third-party management specialists monetizing operational expertise without asset ownership, and technology-enabled platforms disrupting traditional facility economics. Competitive intensity centers on portfolio scale expansion through acquisition and automation capital deployment to compress labor intensity.
Among North American REIT-structured operators, Public Storage and Extra Space Storage exemplify the vertically integrated archetype with extensive metropolitan corridor footprints. CubeSmart occupies a position within the third-party management tier, extending revenue capture beyond owned assets through operational contracts. Safestore represents European market consolidation dynamics among London-listed storage specialists.
| Leading Market Players |
|---|
| Public Storage |
| Extra Space Storage |
| CubeSmart |
| U-Haul International |
| National Storage Affiliates |
| Life Storage |
| Safestore |
| Big Yellow Self Storage |
| Shurgard Self Storage |
| Others |
Supply & Pricing Matrix
Climate-controlled premium tiers command sustained pricing power through humidity-sensitive inventory demand, while outdoor drive-up formats compete on land acquisition cost efficiency and construction speed across Texas and Florida submarkets. This bifurcation channels capital toward technology-enabled service tiers in dense metropolitan corridors and toward low-labor configurations in secondary American markets, with supply chain decisions pivoting on local zoning permissiveness and stormwater compliance burdens.
Pricing Analysis
Direct-to-consumer channels capture margin premiums through subscription-based storage models that displace traditional month-to-month leasing in urban consumer segments. Three-tier pricing structure across premium, standard, and economy levels separates climate-controlled humidity regulation from basic outdoor units and mobile container services. Cost compression in non-premium outdoor tiers intensifies as municipal land scarcity elevates site acquisition expenses in residential-adjacent zones. Small business accounts exhibit lowest price sensitivity due to inventory decentralization imperatives, while individual residential tenants in secondary markets demonstrate highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale logistics and construction contractor demand through bulk unit leasing arrangements and enterprise contract structures. Manufacturing concentration for climate system equipment centers on Germany, Japan, and the United States, while steel building components and automated gate systems source predominantly from Chinese and South Korean fabrication facilities. Supply chain risk manifests in single-source vulnerability for specialized HVAC compressors meeting REACH and EPA energy specifications. Distribution runs through third-party management specialists and vertically integrated REITs with metropolitan corridor footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in self storage rest on automation capital deployment compressing labor intensity and climate-controlled tier premiums widening against commodity outdoor formats.
For Market Incumbents: Extend technology-enabled service tiers through biometric entry systems and smartphone credentialing platforms that compress customer acquisition costs. Defend against mobile storage disruptors by integrating doorstep logistics into owned service portfolios. Prioritize vertical integration into third-party management contracts to capture institutional capital seeking operational expertise without real estate exposure. For New Entrants and Emerging Players: Begin with underpenetrated Indian Tier-1 cities where SME inventory growth and housing transitions create whitespace for organized self storage development. Target Hyderabad and Pune technology corridors for business account acquisition through contract manufacturer relationships. Pursue ISO 27001 certification as a differentiated entry credential for smart facility platforms handling tenant access and payment data. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional independents lack capital for automation retrofitting and climate system compliance investments. Long-term viability favors operators with scalable third-party management revenue streams and technology-integrated property platforms. Watch municipal zoning liberalization in residential-adjacent zones as the inflection signal for accelerated development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Capital Deployment | Biometric and mobile credentialing systems compress labor costs and extend lease duration in metropolitan facilities. |
| Third-Party Management Expansion | Asset-light revenue models capture institutional capital seeking operational expertise without direct real estate exposure. |
| Climate-Controlled Capacity Addition | REACH and EPA compliant humidity regulation systems command sustained premium pricing in European and American markets. |
| Mobile Storage Service Integration | Doorstep container logistics disintermediate traditional facility visits in dense London, Amsterdam, and San Francisco corridors. |
| ISO 27001 Certification Investment | Information security credentials differentiate smart facility platforms integrating tenant access logs and payment systems. |
Research Methodology
Direct dialogue with self storage facility operators, real estate investment trust portfolio managers, municipal zoning officials, and construction contractors grounded the qualitative foundation of this analysis. Secondary validation drew from EPA stormwater management filings, HUD zoning framework documentation, European REACH protocol submissions, and SEC 10-K disclosures from REIT-structured operators. Bottom-up unit economics modeling triangulated against top-down market sizing across facility type, customer segment, and service tier dimensions.
Segmented outputs across indoor, outdoor, climate-controlled, and vehicle storage configurations combined with individual, business, student, and military customer categories. CAGRs derived from historical absorption rates, development pipeline tracking, and demographic mobility pattern analysis. Forecast inputs incorporated small business inventory decentralization trends and smart access technology adoption curves without specifying implementation timelines.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on household mobility, abrupt municipal zoning liberalization or restriction shifts, and energy cost volatility affecting climate-controlled facility margins. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Green Lease Market
Real Estate Services
Lease Management Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
US Home Service Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Thailand Real Estate Market