
 Volatile Organic Compounds (VOC) Concentrator Market | 2026-2036
Volatile Organic Compounds (VOC) Concentrator Market Size, Share, and Industry Trends Forecast 2026-2036
Volatile Organic Compounds (VOC) Concentrator Market Analytics
Zeolite is decoupling from activated carbon as the dominant adsorbent in high-humidity industrial applications, compressing lifecycle costs for end users. Munters leverages its rotor manufacturing scale to anchor European supply chains for solvent recovery installations. Seibu Giken Co. Ltd. specializes in honeycomb zeolite concentrators that dominate Asia-Pacific automotive paint shop retrofits. CECO Environmental competes through integrated thermal oxidizer pairings that extend its equipment value proposition beyond standalone concentration units.
A volatile organic compounds concentrator is an air pollution control device that captures dilute VOC-laden airstreams—typically at concentrations below 500 parts per million—onto adsorbent media before desorbing them into a concentrated stream for destruction or recovery. The system operates on a continuous rotary wheel or fixed-bed architecture with regeneration temperatures between 150 and 200 degrees Celsius, serving primarily to reduce exhaust volumes sent to downstream thermal oxidizers and cut fuel consumption. Activated carbon systems occupy the mature, cost-sensitive tier of the product landscape, while zeolite-based concentrators represent the fastest-growing segment driven by automotive coating line expansions. Thermal oxidizer pairings command the deepest margin pools because they lock in captive aftermarket service contracts and compliance monitoring revenues.
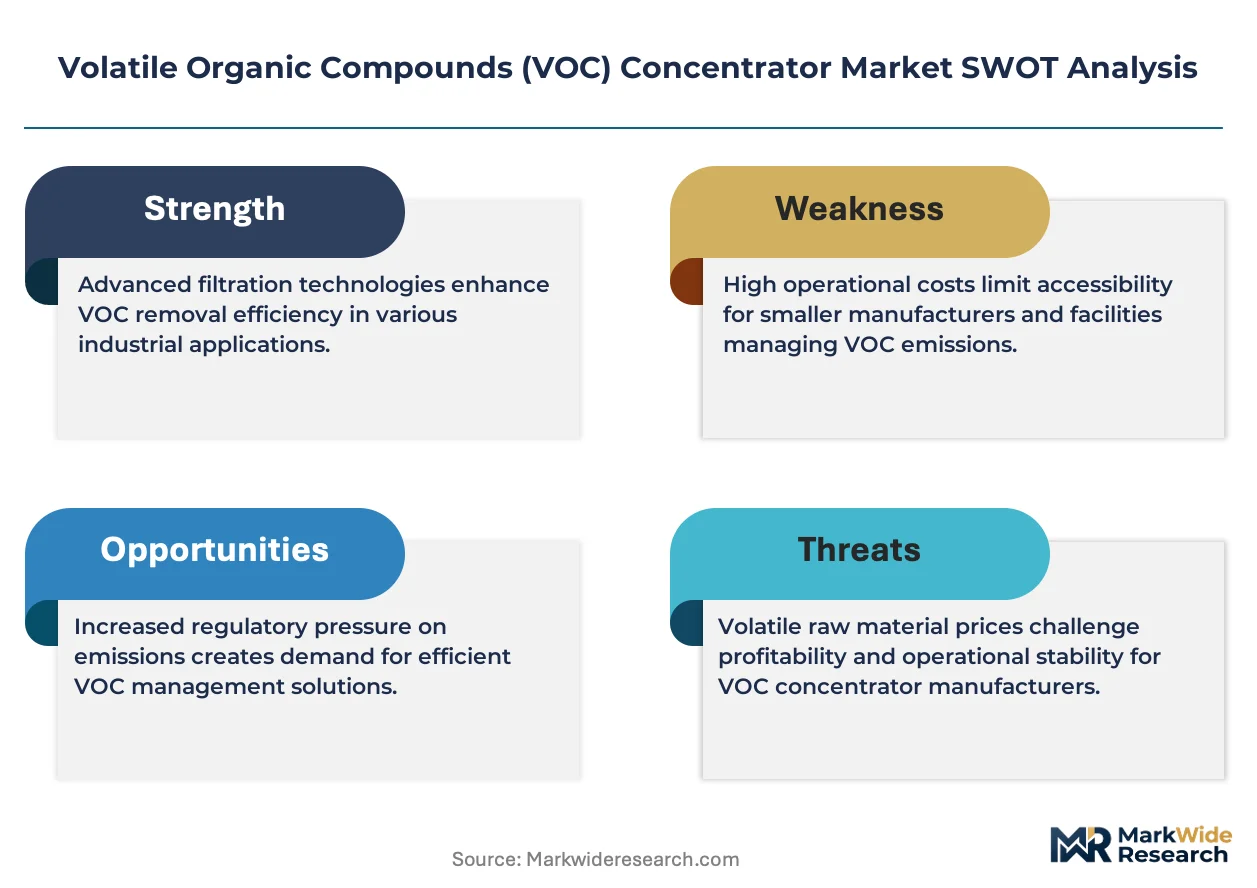
The US EPA enforces Maximum Achievable Control Technology standards under NESHAP that mandate VOC capture efficiencies above 95 percent at major source facilities, directly driving concentrator procurement timelines. The EU Industrial Emissions Directive and F-Gas Regulation compound compliance complexity by restricting certain solvent chemistries and requiring continuous emissions monitoring at chemical and coating plants. China's MEE enforces increasingly stringent GB standards for volatile organic compound emissions from industrial sectors, reshaping equipment specifications for multinational manufacturers operating in the region. Stakeholders must weigh zeolite supply security against activated carbon price stability when committing to multi-year concentrator fleet deployments.

Market Dynamics
Zeolite rotor technology is compressing the total cost of ownership gap against activated carbon systems in high-humidity industrial corridors, forcing incumbent suppliers to recalibrate their aftermarket service architectures around desiccant replacement cycles rather than carbon bed swaps.
Growth Catalysts
- EPA NESHAP MACT Standards:The US EPA mandates 95 percent VOC capture efficiency at major source facilities, compelling automotive paint shops and chemical plants to install concentrator-thermal oxidizer pairings ahead of compliance deadlines.
- Automotive Coating Line Expansions:OEMs in Michigan, Alabama, and South Carolina are retrofitting solvent-based spray booths with zeolite concentrators to handle increased throughput without expanding oxidizer capacity.
- Honeycomb Zeolite Manufacturing Scale:Japanese and South Korean producers have achieved production densities that slash rotor replacement costs by half versus legacy fixed-bed designs.
Market Restraints
- Zeolite Supply Concentration:High-purity synthetic zeolite production clusters in Japan and select Chinese provinces, exposing buyers to geopolitical friction and shipping bottlenecks.
- Activated Carbon Price Volatility:Bituminous coal and coconut shell feedstock costs swing with energy markets, squeezing margins for cost-sensitive municipal and small industrial adopters.
- Desorption Temperature Limitations:Zeolite media degrades above 220 degrees Celsius, restricting applicability to high-boiling-point solvent streams that require alternative recovery methods.
Strategic Opportunities
- India Chemical Corridor Buildout:Gujarat and Maharashtra state industrial zones lack installed VOC control infrastructure, creating first-mover advantages for concentrator-oxidizer integrators.
- Battery Manufacturing Solvent Recovery:Lithium-ion electrode coating operations in Nevada and Arizona generate dilute N-methyl-2-pyrrolidone streams ideal for concentrator capture and closed-loop solvent return.
- EU F-Gas Regulation Alignment:The phase-down of hydrofluorocarbon solvents under F-Gas is accelerating migration to non-fluorinated chemistries that pair efficiently with zeolite adsorption systems.
Industry Challenges
- Rotor Regeneration Expertise Gap:Maintenance technicians skilled in honeycomb media thermal cycling and seal replacement remain scarce outside Japan and Germany.
- Legacy Oxidizer Integration Complexity:Retrofitting concentrators onto existing thermal oxidizers requires custom ductwork and control system harmonization that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volatile Organic Compounds (VOC) Concentrator Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Membrane, Biofilter, Thermal Oxidizer End User: Industrial Manufacturing, Automotive, Paints & Coatings, Pharmaceuticals Technology: Adsorption, Condensation, Biological Treatment, Desorption Application: Air Quality Control, Odor Removal, Solvent Recovery, Hazardous Waste Treatment |
| Companies Covered | Anguil Environmental, TKS Industrial Company, Seibu Giken Co. Ltd., Cycle Therm, LLC, The CMM Group, LLC, Munters, CECO Environmental, Gulf Coast Environmental Systems, Nichias Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volatile Organic Compounds (VOC) Concentrator Market Evolving Landscape
Equipment architectures are converging around continuous rotary wheels with embedded temperature monitoring, displacing batch-mode fixed beds across high-volume processing environments. This shift is compressing capital deployment cycles and rewiring vendor revenue models toward performance-based service contracts.
Electrified desorption is electrifying the concentrator segment by replacing natural gas-fired regeneration with resistive heating elements. Automotive OEMs in Stuttgart and Detroit are piloting all-electric rotor systems to eliminate Scope 1 emissions from paint shop operations. The technology is electrifying site permitting by removing combustion sources from regulatory scrutiny and enabling installation in urban manufacturing zones with strict fire codes.
The EU Industrial Emissions Directive now mandates continuous emissions monitoring at chemical and coating plants above threshold solvent consumption levels. German regulators in Ludwigshafen and Leverkusen are enforcing real-time data transmission to regional environmental agencies. Zeolite-based concentrators with integrated sensor arrays are capturing preference share as they simplify compliance documentation and reduce third-party verification costs.
Buyers are consolidating procurement authority at the corporate sustainability office rather than plant engineering departments. Multinational chemical manufacturers in Basel and Houston now mandate fleet-standard concentrator specifications across all facilities to simplify spare parts logistics and training. This concentration is visible most acutely in the pharmaceutical sector, where Merck and Roche have issued global framework agreements with single-source rotor suppliers.
Volatile Organic Compounds (VOC) Concentrator Market Segmentation
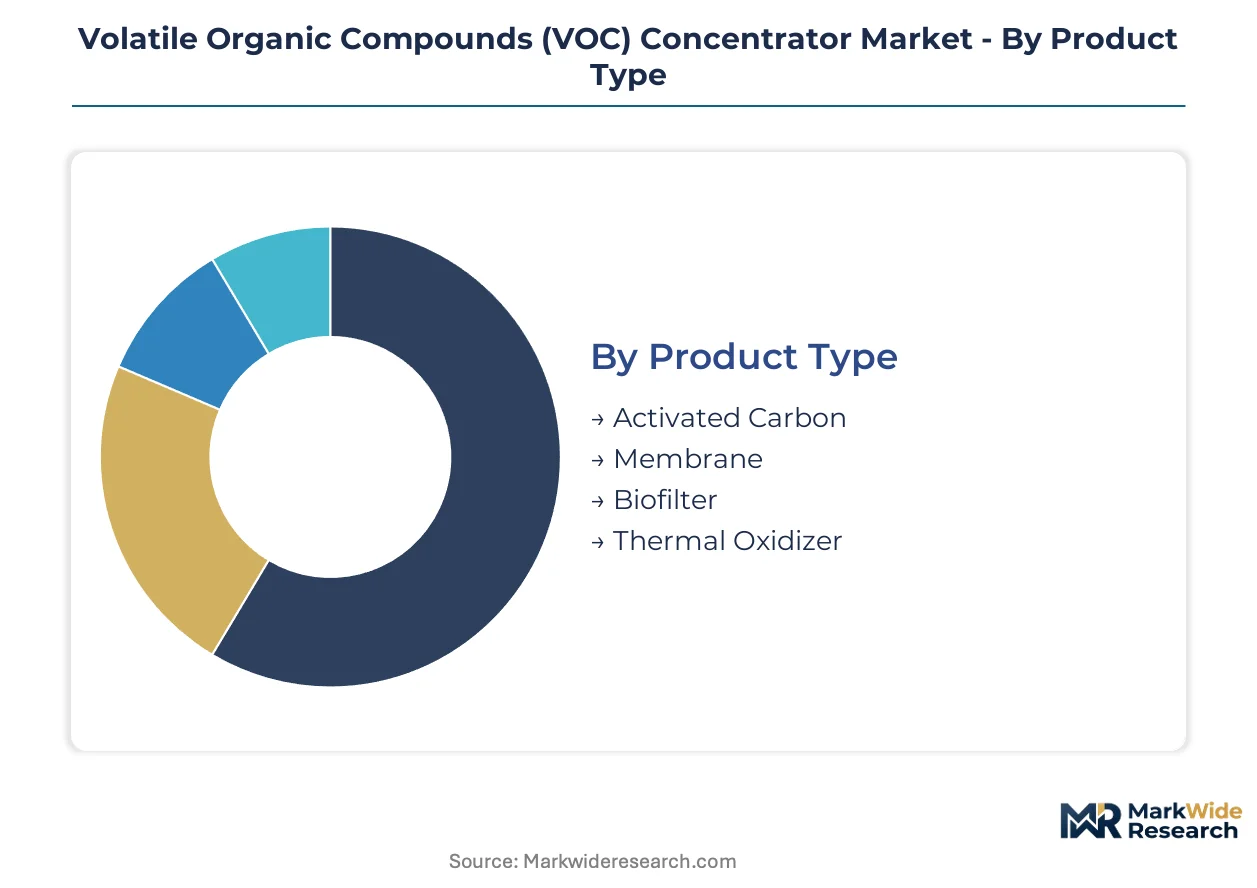
VOC concentrator procurement cycles track distinct upgrade timelines across adsorbent media, thermal integration architectures, and end-use compliance pressures. Segment boundaries blur where hybrid systems combine multiple treatment stages into single-vendor packages.
Product Type:
Replacement cycles diverge sharply between media-based systems requiring periodic rotor or bed swaps and permanent equipment installations with decades-long depreciation schedules.
- Activated Carbon:Bituminous and coconut shell formulations dominate cost-sensitive municipal installations. Price volatility in coal feedstock squeezes margins for small industrial adopters in the US Southeast.
- Membrane:Polymeric separation layers enable solvent recovery without thermal regeneration, cutting energy costs for high-value chemical streams. German chemical clusters around Ludwigshafen anchor European demand for pervaporation-integrated concentrators.
- Biofilter:Microbial oxidation beds treat low-concentration odorous streams at food processing and wastewater facilities. Humidity sensitivity restricts deployment to temperate climate zones with stable operating conditions.
- Thermal Oxidizer:Direct flame and catalytic variants destroy concentrated VOC streams above 95 percent efficiency. Automotive OEMs in Michigan and Alabama pair these with upstream zeolite concentrators to meet EPA NESHAP MACT standards.
Activated Carbon sits at the top of the volume ranking, with Membrane climbing the fastest as solvent recovery economics improve.
End User:
Compliance urgency varies by sector exposure to EPA, EU Industrial Emissions Directive, and China's MEE enforcement timelines.
- Industrial Manufacturing:Chemical plants and petrochemical complexes generate the largest airstream volumes requiring concentration before destruction. US Gulf Coast facilities face compressed procurement timelines ahead of NESHAP compliance deadlines.
- Automotive:Paint shop retrofits and new coating line installations drive zeolite rotor demand. OEMs in Stuttgart, Detroit, and Toyota City standardize on honeycomb concentrators to handle increased throughput without oxidizer expansion.
- Paints & Coatings:Solvent-based spray booths emit dilute VOC streams ideal for adsorption concentration. EU F-Gas Regulation phase-down accelerates migration to non-fluorinated chemistries compatible with zeolite systems.
- Pharmaceuticals:Batch processing operations require flexible concentrator sizing for campaign-based production. Basel and Houston headquarters mandate fleet-standard specifications across global manufacturing networks.
Industrial Manufacturing commands the largest installed base, with Automotive expanding most quickly on coating line investment cycles.
Technology:
Process selection hinges on stream composition, humidity levels, and downstream recovery or destruction objectives.
- Adsorption:Zeolite and activated carbon media capture dilute VOCs onto solid substrates for subsequent concentration. High-humidity industrial corridors favor hydrophobic zeolite formulations that resist moisture competition.
- Condensation:Cryogenic and mechanical cooling recover high-boiling-point solvents as liquid products. German automotive suppliers deploy these for paint gun cleaning solvent return.
- Biological Treatment:Biofilters and biotrickling filters oxidize biodegradable compounds at ambient temperatures. Operating cost advantages erode where land constraints prevent large footprint installations.
- Desorption:Thermal swing and pressure swing methods regenerate saturated media. Electrified resistive heating pilots in Stuttgart and Detroit eliminate natural gas combustion from paint shop operations.
Adsorption anchors the technology mix, with Desorption gaining share fastest on electrification and energy cost pressures.
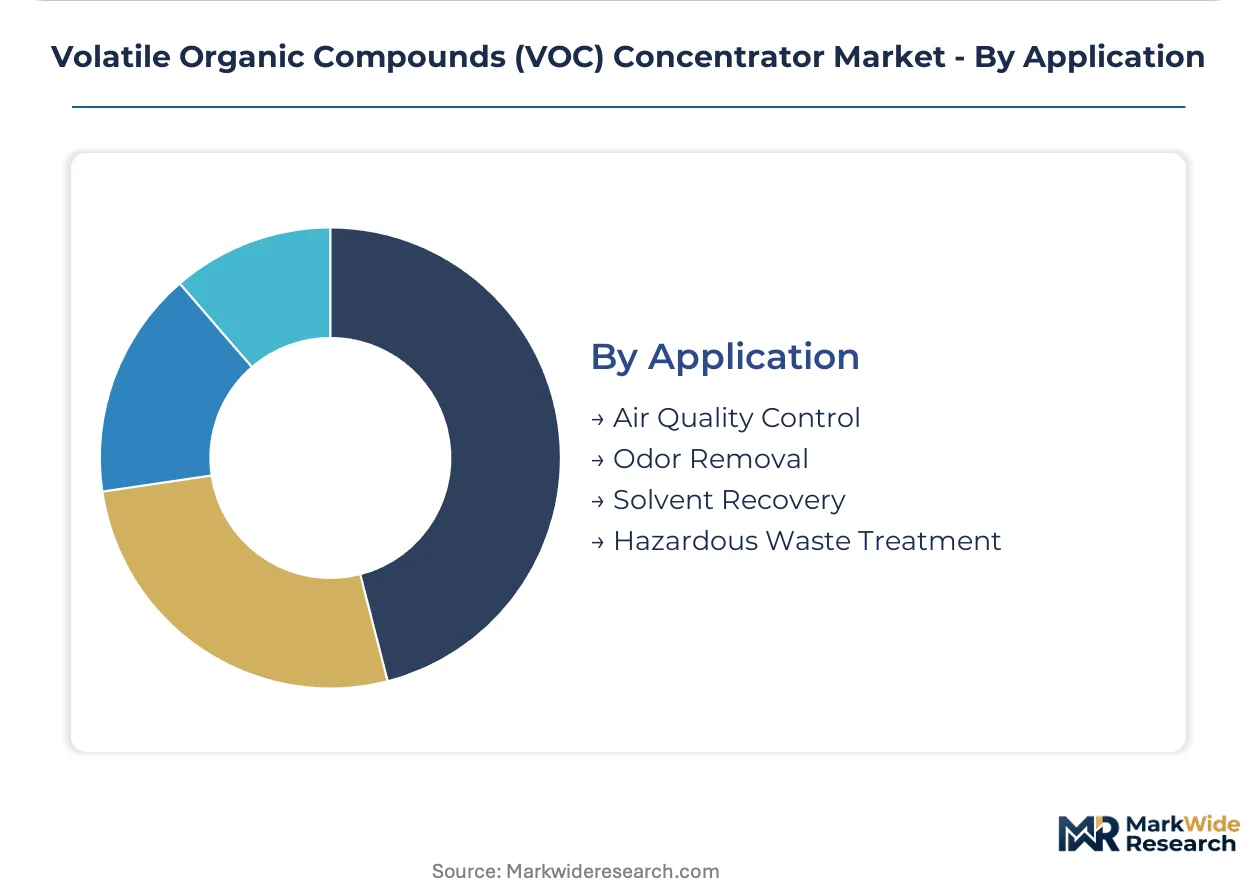
Application:
Functional requirements split between regulatory compliance mandates and operational efficiency improvements.
- Air Quality Control:Continuous emissions reduction at major source facilities satisfies EPA, EU, and Chinese regulatory thresholds. Integrated sensor arrays simplify documentation and cut third-party verification costs.
- Odor Removal:Biofilters and adsorption systems treat nuisance emissions from food processing, rendering, and wastewater operations. Proximity to residential zones drives premium system specifications.
- Solvent Recovery:Closed-loop return of captured organics reduces virgin solvent purchases and waste disposal costs. Nevada and Arizona lithium-ion battery electrode coating operations generate ideal N-methyl-2-pyrrolidone streams for concentrator capture.
- Hazardous Waste Treatment:Concentration reduces exhaust volumes sent to high-destruction-efficiency thermal oxidizers. Fuel consumption savings justify capital investment at chemical plants with stable, high-volume waste streams.
Air Quality Control leads by installed capacity, with Solvent Recovery posting the steepest expansion trajectory on circular economy economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen's chemical corridor anchors global concentrator demand through BASF's sprawling manufacturing complex and the dense cluster of specialty chemical producers feeding European automotive supply chains.
United States
Automotive paint shops in Michigan and Alabama drive zeolite rotor procurement ahead of EPA NESHAP MACT compliance deadlines. The EPA mandates 95 percent VOC capture efficiency at major source facilities. Gulf Coast petrochemical complexes in Texas and Louisiana retrofit solvent recovery systems to handle expanded ethylene cracker output.
Germany
Automotive OEMs in Stuttgart and Wolfsburg standardize on honeycomb concentrators for coating line expansions without oxidizer capacity upgrades. The EU F-Gas Regulation accelerates migration to non-fluorinated solvent chemistries compatible with zeolite adsorption. The Ludwigshafen-Leverkusen chemical corridor concentrates activated carbon rotor demand for continuous emissions monitoring compliance.
China
Multinational manufacturers in Shanghai and Guangdong reshape equipment specifications under tightening GB standards enforced by the MEE. The Yangtze River Delta battery manufacturing corridor generates dilute N-methyl-2-pyrrolidone streams ideal for concentrator capture. Jiangsu province chemical parks face compressed procurement timelines for integrated thermal oxidizer pairings.
Japan
Toyota City automotive clusters and Osaka industrial zones sustain demand for honeycomb zeolite manufacturing at production densities that halve rotor replacement costs. METI industrial efficiency programs subsidize electrified desorption pilots eliminating natural gas combustion. Yokkaichi chemical producers anchor Asia-Pacific supply security for high-purity synthetic zeolite media.
India
Gujarat and Maharashtra state industrial zones lack installed VOC control infrastructure, creating first-mover advantages for concentrator-oxidizer integrators. The country's national environmental regulator enforces increasingly stringent emissions standards across chemical and coating operations. Dahej and Mundra petrochemical corridors attract equipment vendors establishing localized service networks.
Volatile Organic Compounds (VOC) Concentrator Market Competitive Landscape
Global majors compete with regional champions across rotor manufacturing scale and thermal oxidizer integration depth. The vendor base splits between European engineering conglomerates with captive adsorbent production and Asian specialists concentrating honeycomb zeolite fabrication. Three archetypes dominate: integrated environmental systems houses, dedicated rotor manufacturers, and thermal oxidizer specialists extending upstream into concentration. Competitive dynamics center on strategic partnerships for geographic coverage and technology licensing for media formulations.
Within the integrated systems tier, CECO Environmental and Munters exemplify equipment-oxidizer pairing strategies that lock in captive aftermarket revenues. Seibu Giken Co. Ltd. occupies a specialist position representing Japanese honeycomb zeolite manufacturing density. These three anchors illustrate how competitive positioning splits between margin capture through thermal integration and cost leadership through rotor production scale.
| Leading Market Players |
|---|
| Anguil Environmental |
| TKS Industrial Company |
| Seibu Giken Co. Ltd. |
| Cycle Therm, LLC |
| The CMM Group, LLC |
| Munters |
| CECO Environmental |
| Gulf Coast Environmental Systems |
| Nichias Corporation |
| Others |
Value Network & Pricing Analysis
Zeolite media costs cascade through three distinct pricing tiers as synthetic zeolite from Yokkaichi and select Chinese provinces feeds into rotor manufacturing, with bituminous coal and coconut shell feedstock volatility compressing margins for activated carbon systems serving cost-sensitive municipal buyers in the US Southeast.
Pricing Analysis
Input-cost pass-through from synthetic zeolite and activated carbon feedstocks shapes tiered pricing across premium honeycomb rotors, standard fixed-bed systems, and economy carbon-bed configurations. Price differentiation hinges on adsorbent purity grades and EPA NESHAP compliance certification tiers, with automotive OEMs in Stuttgart and Detroit showing lowest sensitivity due to regulatory deadline pressure. Pricing pressure intensifies in the activated carbon tier as coal feedstock costs swing with energy markets, squeezing small industrial adopters and municipal operators most acutely.
Supply Chain Analysis
ISO 9001 and EPA certification gating restricts rotor supply to qualified fabricators, with high-purity synthetic zeolite production anchoring in Japan and Jiangsu province while activated carbon sourcing draws from bituminous coal mines in Appalachia and coconut shell processors in Southeast Asia. Raw material dependencies center on zeolite precursors, carbon feedstocks, and honeycomb substrate aluminum. Single-source vulnerability concentrates in Japanese zeolite supply for automotive-grade rotors. Distribution runs through OEM-direct contracts for large installations and regional environmental systems integrators for mid-market retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VOC concentrator market functions as a regulatory compounder where EPA NESHAP MACT standards mandating 95 percent capture efficiency at major source facilities create irreversible procurement timelines across automotive and chemical sectors.
For Market Incumbents: Anchor market position by securing captive zeolite supply agreements with Yokkaichi chemical producers to insulate against geopolitical friction, while expanding electrified desorption R&D to meet automotive OEM Scope 1 elimination targets in Stuttgart and Detroit. Threat substitution from membrane separation technologies in German chemical clusters demands accelerated thermal oxidizer integration depth to lock in aftermarket service revenues.
For New Entrants and Emerging Players: The premium-economy price-point gap in India's Gujarat and Maharashtra chemical corridors offers first-mover positioning before installed base saturation, targeting concentrator-oxidizer integrator partnerships with Dahej and Mundra petrochemical developers. White-space concentration in battery manufacturing solvent recovery across Nevada and Arizona lithium-ion corridors supports N-methyl-2-pyrrolidone capture specialization as the most penetrable application segment.
For Investors and Strategic Acquirers: Consolidation pressure builds where honeycomb zeolite manufacturing scale concentrates among Japanese specialists with irreplaceable production density advantages. Long-term viability over the mid-term horizon favors targets with captive rotor fabrication and thermal oxidizer pairing capabilities. The signal to watch is electrified desorption adoption velocity among automotive OEMs as an inflection indicator for technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Media | Yokkaichi supply security insulates margin structure against shipping bottlenecks and geopolitical friction. |
| Electrified Desorption Pilot Deployment | Stuttgart and Detroit automotive OEMs eliminate Scope 1 emissions from paint shop regulatory scrutiny. |
| India Service Network Localization | Gujarat and Maharashtra first-mover positioning captures chemical corridor buildout before competitor saturation. |
| Battery Manufacturing Solvent Recovery Specialization | Nevada and Arizona lithium-ion electrode coating generates ideal N-methyl-2-pyrrolidone concentrator applications. |
| Thermal Oxidizer Pairing Integration | CECO Environmental and Munters demonstrate captive aftermarket service contract depth beyond standalone units. |
Research Methodology
Direct dialogue with plant engineers at automotive OEMs, procurement leads at chemical manufacturers, aftermarket service directors, and regulatory compliance officers grounded qualitative findings, cross-referenced with EPA enforcement databases, EU ETS emissions registries, SEC 10-K equipment disclosures, and customs import records for zeolite and activated carbon media. Bottom-up installation tracking and top-down emissions compliance modeling triangulated market sizing across adsorbent media types, thermal integration architectures, and end-use compliance pressures.
Bottom-up volume modeling tracked individual concentrator installations at major source facilities against EPA NESHAP compliance deadlines, while top-down analysis scaled from regional emissions inventory data and thermal oxidizer pairing rates. Segmentation dimensions spanned adsorbent media chemistry, rotor versus fixed-bed architecture, automotive versus chemical end-use, and geographic regulatory cluster intensity. CAGRs derived from installation run-rate projections and replacement cycle analysis, with electrified desorption adoption curves and F-Gas Regulation phase-down timelines as industry-specific forecast inputs across the projection horizon.
Caveats apply where EPA enforcement discretion, zeolite supply disruptions, or accelerated electrification pilots could materially shift the outlook. Forecasts embed assumptions regarding NESHAP compliance timeline adherence and honeycomb manufacturing scale expansion. A model refresh is warranted upon material change in EPA MACT standard stringency or Japanese zeolite export policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Foam Market