
 Tallow Fatty Acid Market | 2026-2036
Tallow Fatty Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Tallow Fatty Acid Market Analysis
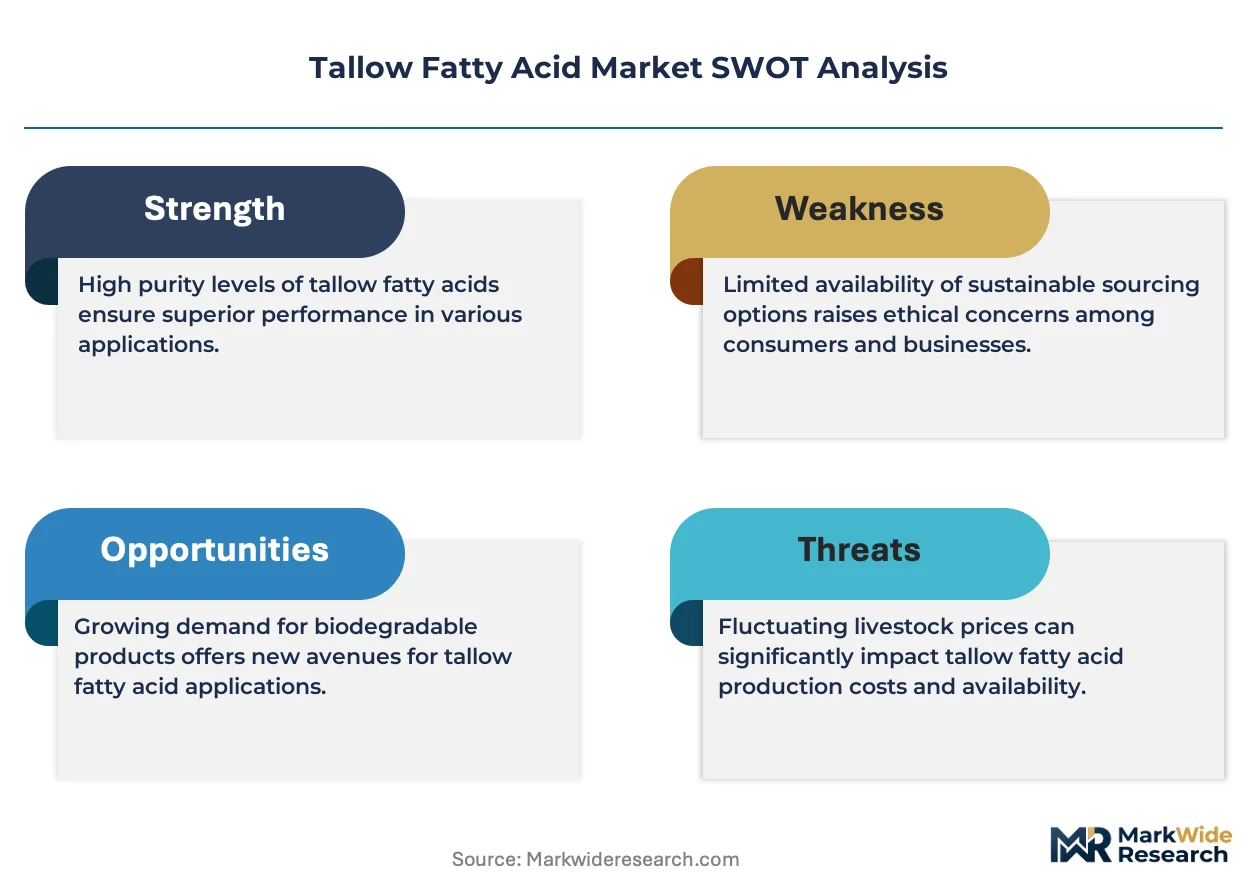
The split between pharmaceutical-grade and industrial-grade tallow fatty acids is rebalancing as cosmetic compounders tighten purity specifications while biodiesel blenders absorb lower-grade offtake. BASF SE leverages its integrated oleochemical network to secure consistent tallow feedstock access across European personal care markets. KLK Oleo anchors its position through backward integration into palm and tallow splitting operations in Southeast Asia. Emery Oleochemicals specializes in high-iodine-value unsaturated fractions for lubricant ester production.
Tallow fatty acids are triglyceride-derived C16-C18 carboxylic acids obtained through fat splitting, hydrogenation, and fractional distillation of bovine or ovine adipose tissue, with stearic acid and oleic acid representing the dominant fractions for soap, surfactant, and lubricant base stock applications. Saturated fatty acids occupy the largest volume share due to entrenched demand from bar soap and rubber processing industries, while pharmaceutical-grade fractions command the deepest margin pools owing to USP-NF certification requirements and limited qualified supply. Unsaturated fatty acids represent the fastest-expanding product category as automotive lubricant formulators substitute petroleum-derived base oils with bio-based esters.
FDA food-contact substance notifications and EPA renewable fuel standard pathways govern US market access for tallow-derived inputs, while REACH registration dossiers and ECHA SVHC screening determine European commercial viability. USDA FSIS facility inspection requirements for rendering operations constrain North American supply elasticity. Stakeholders must monitor evolving EU Green Deal methane-reduction mandates and their downstream impact on livestock sector output and tallow availability.
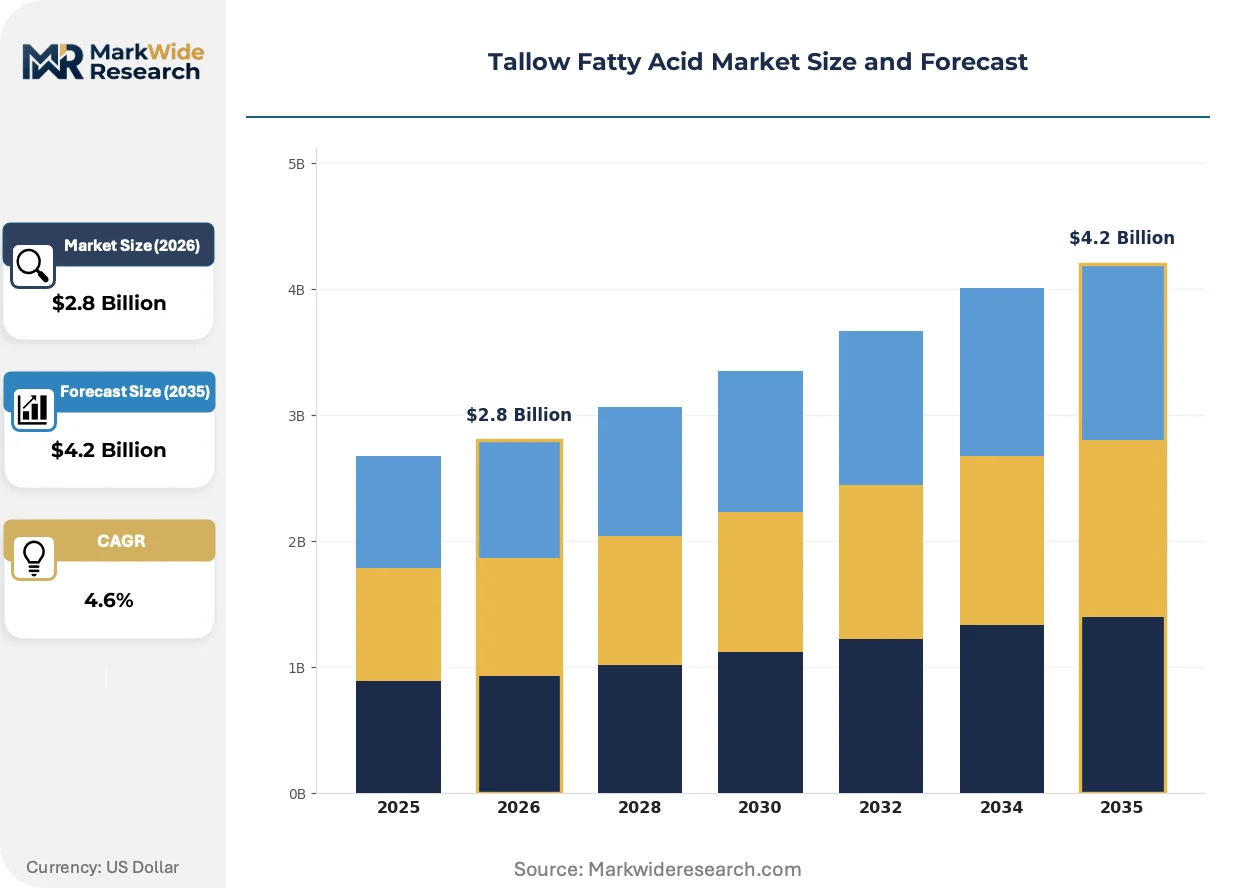
Market Dynamics
Pharmaceutical-grade purity specifications are compressing industrial-grade margins while biodiesel blenders absorb residual offtake, creating a bifurcated supply structure where certification tier determines commercial viability more than volume scale.
Growth Catalysts
- REACH bio-based classifications:ECHA documentation requirements redirect European formulators toward animal-derived feedstocks with verified chain-of-custody credentials.
- Lubricant ester substitution:Automotive formulators replace petroleum base oils with high-iodine-value unsaturated fractions for biodegradable hydraulic fluids.
- Oleochemical cluster density:Hamburg and Frankfurt concentration enables just-in-time delivery to cosmetic compounders, reducing working capital requirements.
Market Restraints
- Livestock output volatility:EU Green Deal methane-reduction mandates constrain bovine herd sizes, tightening tallow raw material availability.
- Rendering facility inspection rigor:USDA FSIS protocols limit North American supply elasticity during demand spikes.
- Palm fatty acid substitution:Southeast Asian palm-derived alternatives compete on price in surfactant applications lacking certification requirements.
Strategic Opportunities
- Pharmaceutical-grade capacity expansion:USP-NF certification scarcity creates margin pools for qualified producers in Germany and the Netherlands.
- Biodegradable lubricant mandates:EPA renewable fuel standard pathways incentivize bio-based ester adoption in heavy equipment fleets.
- Direct compounder relationships:Personal care manufacturers seek bypass of traditional distributors for supply security.
Industry Challenges
- Fractional distillation expertise scarcity:Specialized technicians for C16-C18 separation are concentrated among legacy European operators.
- Multi-jurisdiction dossier maintenance:Simultaneous FDA food-contact notifications and REACH registrations strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tallow Fatty Acid Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saturated Fatty Acids, Unsaturated Fatty Acids, Mono-unsaturated Fatty Acids, Poly-unsaturated Fatty Acids Application: Cosmetics, Biofuels, Lubricants, Animal Feed End User: Personal Care Manufacturers, Automotive Industry, Food Industry, Agriculture Sector Grade: Food Grade, Industrial Grade, Technical Grade, Pharmaceutical Grade |
| Companies Covered | KLK Oleo, BASF SE, Cargill, Incorporated, Oleon NV, AkzoNobel, Godrej Industries, Emery Oleochemicals, Vantage Specialty Chemicals, Wilmar International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tallow Fatty Acid Market Emerging Trajectories
Continuous hydrogenation reactor designs and molecular distillation advances are reshaping yield economics, while sustainability verification platforms alter how procurement teams evaluate supplier credentials.
Membrane filtration technology is integrating into traditional fat splitting workflows to reduce thermal degradation of heat-sensitive unsaturated fractions. Cosmetic compounders in Germany adopt these hybrid systems to preserve oleic acid integrity for premium emollient formulations. The process is integrating quality control directly into production, compressing batch release timelines.
ECHA SVHC screening expansion under REACH is forcing reformulation of personal care products containing trace contaminants. Industrial consequence includes accelerated migration toward pharmaceutical-grade feedstocks even in non-pharmaceutical applications. German surfactant manufacturers bear the highest compliance burden, redirecting R&D spending toward purification technology.
Compounders now demand chain-of-custody documentation extending to rendering source. Direct supplier relationships replace spot-market purchasing among large personal care manufacturers. This pattern concentrates procurement volume with integrated oleochemical producers holding captive rendering operations.
Tallow Fatty Acid Market Segmentation
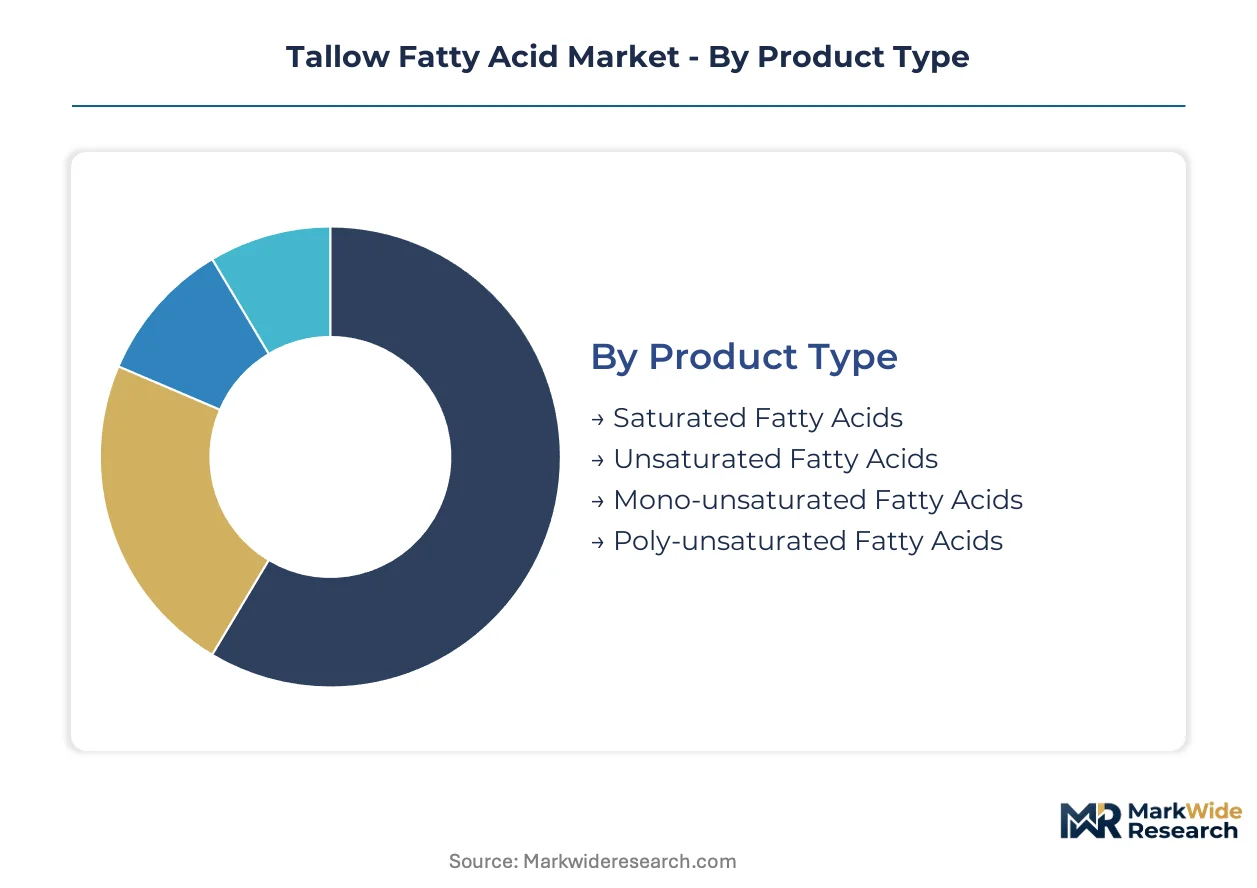
Segmentation in tallow fatty acids separates commodity volume from premium margin pools. Product chemistry and certification tiers create distinct investment profiles and customer access requirements.
Product Type:
Capital intensity varies sharply across hydrogenation and fractionation requirements for each chemical class.
- Saturated Fatty Acids:Stearic and palmitic acid fractions dominate bar soap and rubber processing formulations. German oleochemical clusters around Hamburg concentrate hydrogenation capacity for this segment, serving established personal care compounders with consistent offtake.
- Unsaturated Fatty Acids:High-iodine-value oleic acid fractions require controlled thermal processing to preserve double-bond integrity. Automotive lubricant formulators in Germany and the Netherlands substitute these bio-based esters for petroleum-derived base oils under EPA renewable fuel standard pathways.
- Mono-unsaturated Fatty Acids:Purified oleic acid streams command cosmetic-grade premiums through molecular distillation investments.
- Poly-unsaturated Fatty Acids:Linoleic acid fractions serve specialized coating applications with limited qualified supply.
Saturated fatty acids absorb the bulk of installed capacity; unsaturated fatty acids are expanding most quickly.
Application:
End-use diversification spreads risk across cyclical and defensive demand patterns.
- Cosmetics:Surfactant and emollient formulations demand pharmaceutical-grade purity with USP-NF certification. REACH SVHC screening under ECHA jurisdiction forces German compounders toward verified chain-of-custody feedstocks.
- Lubricants:Biodegradable hydraulic fluids require high-iodine-value unsaturated fractions. EPA renewable fuel standard pathways incentivize bio-based ester adoption in heavy equipment fleets.
- Biofuels:Biodiesel blenders absorb lower-grade tallow offtake, creating residual demand for industrial-grade fractions.
- Animal Feed:Fatty acid calcium soaps serve ruminant nutrition with lower purity thresholds.
Cosmetics commands the deepest margin pools; lubricants is gaining share fastest.
End User:
Procurement sophistication separates direct compounder relationships from distributor-mediated supply.
- Personal Care Manufacturers:Food-grade and pharmaceutical-grade specifications dominate procurement. German surfactant manufacturers bear the highest REACH compliance burden, redirecting R&D spending toward purification technology.
- Automotive Industry:Lubricant formulators seek high-iodine-value unsaturated fractions for biodegradable hydraulic fluids.
- Food Industry:FDA food-contact substance notifications govern market access for tallow-derived inputs.
- Agriculture Sector:Animal feed applications tolerate lower-grade fractions with reduced certification overhead.
Personal care manufacturers concentrate premium procurement; automotive is climbing the fastest.
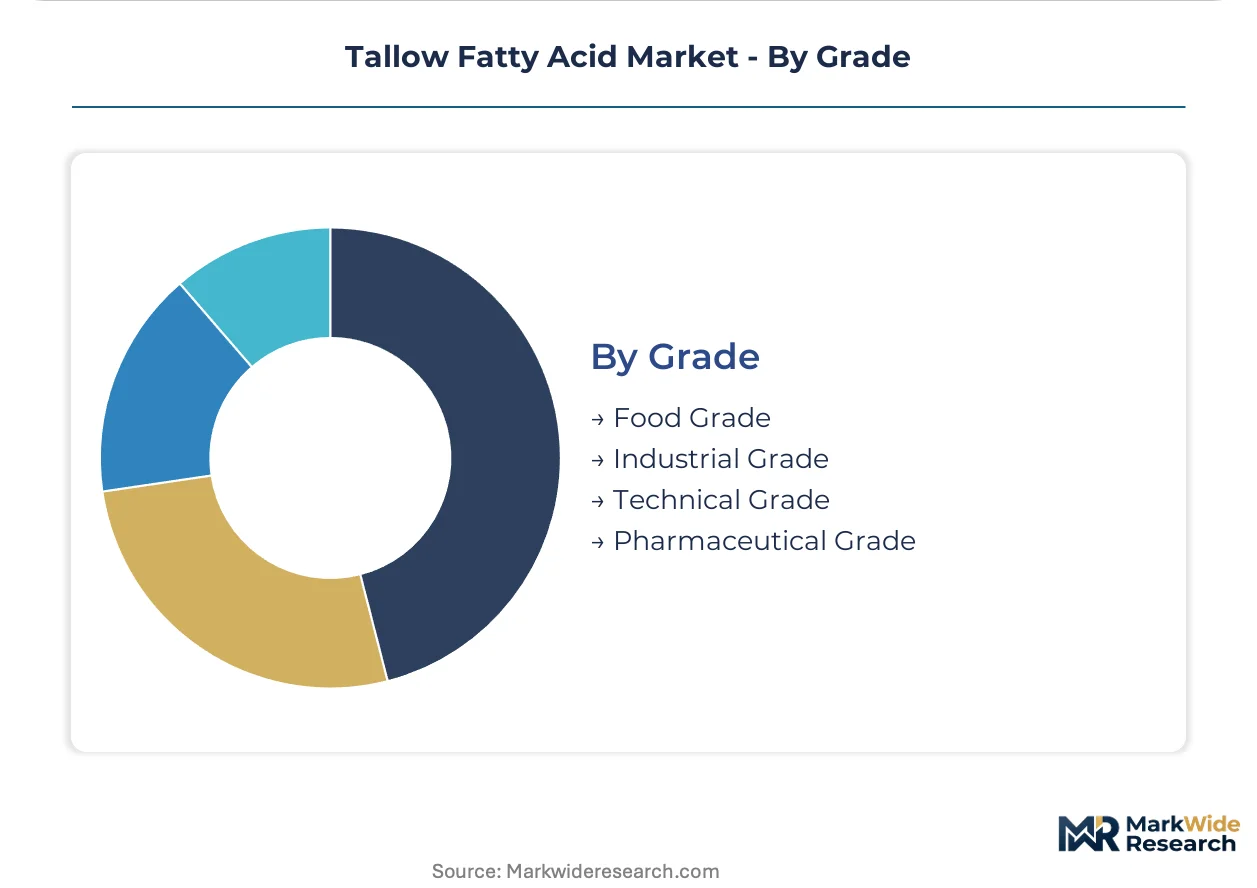
Grade:
Certification tier determines commercial viability more than production volume.
- Pharmaceutical Grade:USP-NF certification requirements and limited qualified supply create scarcity-driven margin pools. German and Dutch producers concentrate capacity expansion here.
- Food Grade:FDA food-contact substance notifications and EFSA safety assessments govern European and North American market access.
- Industrial Grade:Biodiesel blenders absorb residual offtake as cosmetic compounders tighten purity specifications.
- Technical Grade:Rubber processing and general industrial applications tolerate broader specification ranges.
Pharmaceutical grade captures the steepest margin trajectory; food grade maintains the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European oleochemical processing for tallow fatty acids, with integrated rendering and fractionation facilities supplying cosmetic compounders across the continent. The city's port infrastructure enables just-in-time delivery to German surfactant manufacturers and lubricant formulators in the Netherlands. This concentration pattern repeats across three additional markets where regulatory frameworks and industrial clustering shape competitive positioning.
United States
Personal care manufacturers in New Jersey and California drive food-grade tallow fatty acid procurement for surfactant formulations. FDA food-contact substance notifications govern market access, with USDA FSIS facility inspection requirements constraining supply elasticity during demand spikes. Rendering operations concentrate in the Midwest, supplying oleochemical processors along the Gulf Coast.
Germany
REACH and ECHA bio-based chemical classifications redirect formulators toward animal-derived feedstocks with verified chain-of-custody documentation. The country's national chemical regulator enforces SVHC screening that accelerates migration toward pharmaceutical-grade inputs. Frankfurt and Hamburg clusters supply cosmetic and lubricant compounders with hydrogenation and fractional distillation capacity.
Netherlands
Automotive lubricant formulators in Rotterdam and Amsterdam substitute high-iodine-value unsaturated fractions for petroleum-derived base oils. EFSA safety assessments govern food-grade applications alongside REACH registration requirements. The Port of Rotterdam enables integrated tallow splitting operations serving European biodegradable hydraulic fluid markets.
Malaysia
KLK Oleo anchors Southeast Asian supply through backward integration into palm and tallow splitting operations. The country's national standards body enforces quality specifications for oleochemical exports. Port Klang concentration enables dual-feedstock flexibility between palm and tallow derivatives for surfactant manufacturers.
Brazil
Biodiesel blenders absorb lower-grade tallow offtake from rendering operations in São Paulo state. ANVISA regulates pharmaceutical-grade applications while agricultural demand for fatty acid calcium soaps supports rural processing facilities. Campinas industrial corridor hosts fractionation capacity serving domestic personal care compounders.
Tallow Fatty Acid Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with USP-NF qualification creating scarcity-driven positioning. The vendor base stratifies into integrated oleochemical majors, regional rendering specialists, and distributor-mediated traders. Three archetypes dominate: backward-integrated producers with captive rendering, technology-focused fractionators with molecular distillation expertise, and scale-driven commodity suppliers. Competitive moves concentrate on pharmaceutical-grade capacity expansion and direct compounder relationship formation.
Within the integrated major tier, BASF SE and KLK Oleo exemplify divergent geographic anchoring strategies. BASF SE represents European network integration across personal care markets, while KLK Oleo occupies a position in Southeast Asian dual-feedstock flexibility. Emery Oleochemicals sits within the specialization archetype, with company naming indicating oleochemical focus rather than diversified chemical portfolio breadth.
| Leading Market Players |
|---|
| KLK Oleo |
| BASF SE |
| Cargill, Incorporated |
| Oleon NV |
| AkzoNobel |
| Godrej Industries |
| Emery Oleochemicals |
| Vantage Specialty Chemicals |
| Wilmar International Ltd |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification scarcity creates a steep value ladder that simultaneously concentrates pricing power with USP-NF qualified producers and fragments supply chain control across rendering, splitting, and fractionation stages. German compounders pay substantial premiums for verified chain-of-custody documentation under ECHA bio-based classifications, while biodiesel blenders absorb residual industrial-grade volume at compressed margins.
Pricing Analysis
Yield-based pricing anchors contract structures, with cosmetic compounders paying premiums tied to oleic acid purity preservation through membrane filtration integration. USP-NF certification tier and REACH registration completeness drive price differentiation between German pharmaceutical-grade suppliers and commodity biodiesel feedstock vendors. Pricing pressure stems from palm fatty acid substitution in surfactant applications lacking certification requirements. Biodiesel blenders exhibit highest price sensitivity; personal care manufacturers demonstrate lowest sensitivity due to formulation lock-in.
Supply Chain Analysis
Freight cost sensitivity shapes procurement geography, with Hamburg and Rotterdam port concentration enabling just-in-time delivery that offsets higher unit costs for cosmetic compounders. Supply concentrates in Germany, the Netherlands, and Malaysia, with raw material dependencies on bovine herd output, rendering facility throughput, and hydrogenation catalyst availability. EU Green Deal methane-reduction mandates create livestock output volatility as a structural supply risk. Distribution runs through integrated oleochemical majors with captive rendering operations rather than spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is displacing thermal processing for unsaturated fraction preservation, creating a technology-transition window where legacy hydrogenation reactor operators face yield compression against hybrid system adopters.
For Market Incumbents: Anchor pharmaceutical-grade capacity expansion in Germany and the Netherlands to defend margin pools against palm-derived substitution in surfactant applications. Prioritize backward integration into rendering operations to secure chain-of-custody documentation demanded by REACH-compliant formulators. Invest in molecular distillation expertise retention as specialized C16-C18 separation technicians concentrate among legacy European operators.
For New Entrants and Emerging Players: Begin with biodegradable lubricant ester supply to automotive formulators in Rotterdam and Amsterdam, where EPA renewable fuel standard pathways incentivize bio-based base oil substitution. Target direct compounder relationships with mid-tier personal care manufacturers seeking bypass of traditional distributors for supply security. Pursue USP-NF certification as the primary go-to-market credential rather than competing on industrial-grade volume.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated oleochemical producers holding captive rendering operations given ECHA SVHC screening expansion forcing migration toward verified feedstock sourcing. Long-term viability favors operators with simultaneous FDA food-contact notification and REACH registration dossier capabilities. Monitor EU Green Deal methane-reduction mandate implementation as the inflection signal for tallow raw material availability tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Capacity Expansion | USP-NF certification scarcity creates defendable margin pools for qualified German and Dutch producers. |
| Backward Integration into Rendering | Captive tallow sourcing secures chain-of-custody documentation required by ECHA bio-based classifications. |
| Membrane Filtration Technology Adoption | Hybrid processing preserves oleic acid integrity for premium cosmetic emollient formulations in Hamburg clusters. |
| Direct Compounder Relationship Formation | Bypass of traditional distributors reduces working capital requirements for personal care manufacturers. |
| Biodegradable Lubricant Ester Supply Agreement | EPA renewable fuel standard pathways incentivize bio-based hydraulic fluid adoption in heavy equipment fleets. |
Methodological Framework
Document review covered customs/trade data, SEC 10-K filings, and ECHA registration dossiers, complemented by interviews with oleochemical plant managers, procurement leads at personal care OEMs, distribution channel partners, and technical R&D directors. Secondary validation drew from Cefic reports, USDA FSIS facility records, and EPA renewable fuel standard pathway documentation. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Segment-level outputs across the projection horizon reflect modeling by product chemistry, certification tier, end-use industry, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating livestock output forecasts and lubricant ester substitution rates. Industry-specific inputs included hydrogenation capacity utilization rates and pharmaceutical-grade yield differentials.
Underlying measurement precision varies by segment; pharmaceutical-grade and food-grade categories carry tighter precision than industrial-grade and technical-grade applications due to certification documentation density. Forecasts reflect assumptions about EU Green Deal implementation pace and biodiesel blending mandate stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Global Substrate Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Sulfur Recovery Technology Market