
 Foam Market | 2026-2036
Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Market Intelligence
The shift toward bio-based and recycled feedstocks for polyol and isocyanate production is fragmenting the traditionally petrochemical-dependent supply chain. Global chemical giant BASF SE leverages its extensive portfolio to develop sustainable foam solutions. Dow Inc. competes on its massive manufacturing scale and global distribution networks for polyurethane systems. Meanwhile, Covestro AG specializes in high-performance polymer materials for demanding automotive and electronics applications.
Foam is a material formed by trapping gas bubbles in a liquid or solid polymer matrix, creating a lightweight structure with distinct thermal, acoustic, and mechanical properties. Its primary industrial purpose is insulation, cushioning, and structural support, achieved by precisely controlling cell structure and density during polymerization. Polyurethane foam dominates the market, with flexible foam variants leading in bedding and furniture applications. Rigid foam, however, shows significant application growth in construction insulation due to its superior R-value and thermal resistance.
Regulations such as the European Union's REACH framework and the U.S. EPA's rules on blowing agents dictate chemical composition and manufacturing processes. Concurrently, national building codes in countries like Germany, Japan, and Canada mandate specific thermal performance standards, influencing foam selection in construction. Supplier selection will increasingly hinge on the ability to provide materials that meet evolving environmental regulations and circular economy principles.
Market Dynamics
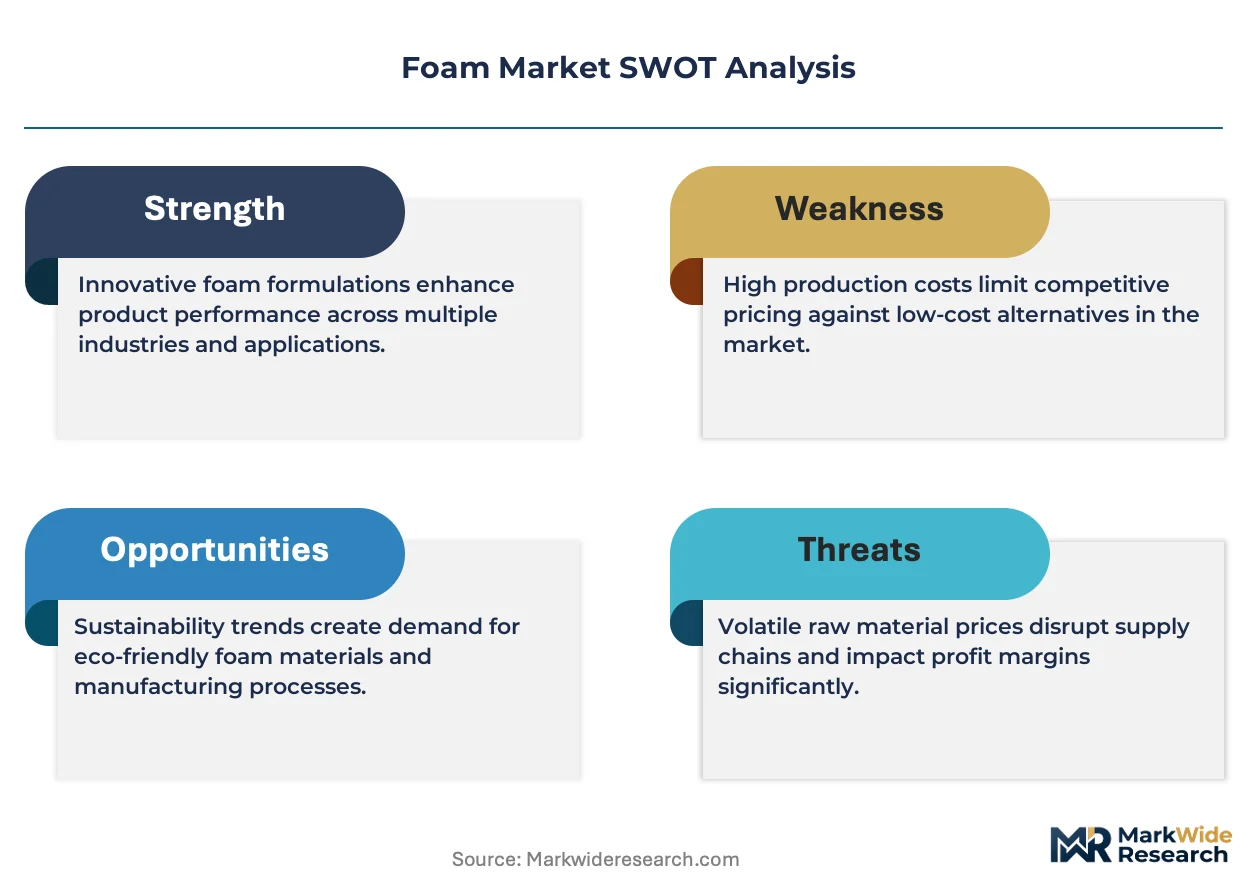
The foam market's structure is defined by the push for circularity in polymer science. Strict regulations on chemical inputs and end-of-life management are forcing a shift from petrochemical dependence toward bio-based polyols and advanced recycling technologies, reshaping material selection criteria across core end-use sectors.
Growth Catalysts
- Building Energy Codes:Strict thermal performance mandates in Germany and Canada compel the use of high-R-value rigid foams for insulation, boosting consumption in construction.
- Automotive Lightweighting:The automotive industry's pursuit of fuel efficiency and EV range drives demand for lightweight polyurethane foams in seating, interior panels, and sound dampening.
- Bio-based Polyols:Development of polyols from renewable sources like soy oil creates material options that meet sustainability goals in consumer goods like furniture and bedding.
Market Restraints
- Petrochemical Volatility:Dependence on petrochemicals like TDI and MDI exposes the supply chain to oil and gas price volatility, impacting production costs.
- Blowing Agent Restrictions:The phase-out of HFCs under the EU F-Gas Regulation and EPA rules necessitates costly reformulation and requalification of foam systems.
- Natural Fiber Competition:In packaging and cushioning, foam faces substitution from materials like molded pulp and wool due to their perceived environmental benefits.
Strategic Opportunities
- Cold Chain Logistics:Expanding pharmaceutical and food supply chains creates opportunities for high-performance rigid foams in temperature-controlled packaging and transport.
- Indian Infrastructure:Large-scale infrastructure projects in India present a growth opportunity for foam insulation in commercial buildings, transportation, and industrial facilities.
- Additive Manufacturing:Using foamable polymers in 3D printing enables creation of customized, lightweight components with complex geometries for aerospace and medical devices.
Industry Challenges
- Recycling Infrastructure Gap:A lack of scaled, economically viable collection and chemical recycling for post-consumer thermoset foams like polyurethane hinders circularity goals.
- Chemical Compliance Complexity:Navigating fragmented substance regulations, such as the EU's REACH and China's GB standards, requires significant investment in testing and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Market |
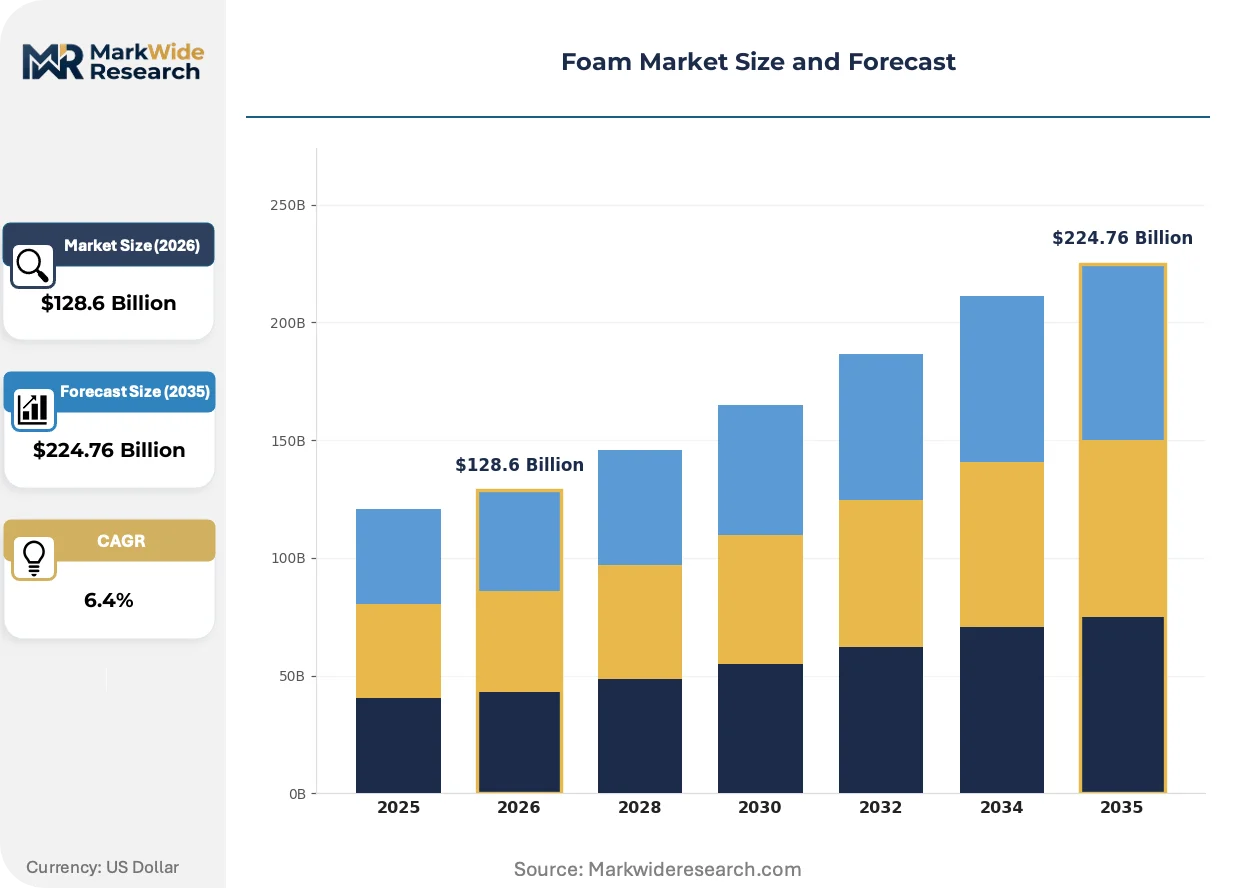
| Market Size in 2026 | $128.6 Billion |
| Market Size in 2035 | $224.76 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polystyrene Foam, Polyethylene Foam, Phenolic Foam, Melamine Foam Form: Rigid Foam, Flexible Foam, Spray Foam, Molded Foam, Extruded Foam Application: Construction Insulation, Bedding & Furniture, Packaging Solutions, Automotive Components, Sports Equipment End User Industry: Building & Construction Firms, Furniture Manufacturers, Consumer Electronics, Aerospace Manufacturers, Sports Goods Producers |
| Companies Covered | Covestro AG, Recticel NV/SA, BASF SE, Armacell International S.A., Sekisui Chemical Co., Ltd., Dow Inc., Rogers Corporation, Trelleborg AB, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Market Strategic Shifts & Innovations
Material innovation in the foam sector is accelerating through the integration of digital tools with polymer chemistry. This convergence allows for faster development of sustainable materials that meet increasingly stringent performance and regulatory criteria across multiple end-use industries.
Digital twinning and simulation software enables predictive modeling of foam polymerization and cell structure. Material scientists in the automotive and aerospace sectors are adopting this to design custom foam properties without extensive physical trials. This technology is virtualizing the prototyping process, reducing development timelines and material waste for new formulations.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure of environmental impacts throughout the supply chain. This regulation forces foam producers to quantify and report on the carbon footprint, recyclability, and chemical composition of their products. Building material and automotive component suppliers are most affected, now competing on verified sustainability data.
End-users in construction and electronics are specifying foam based on third-party certifications rather than just supplier datasheets. This trend elevates the importance of standards like UL Greenguard for air quality or FM Approvals for fire resistance. This certification-driven procurement is most prominent in North American commercial construction and the global electronics industry.
Foam Market Segmentation
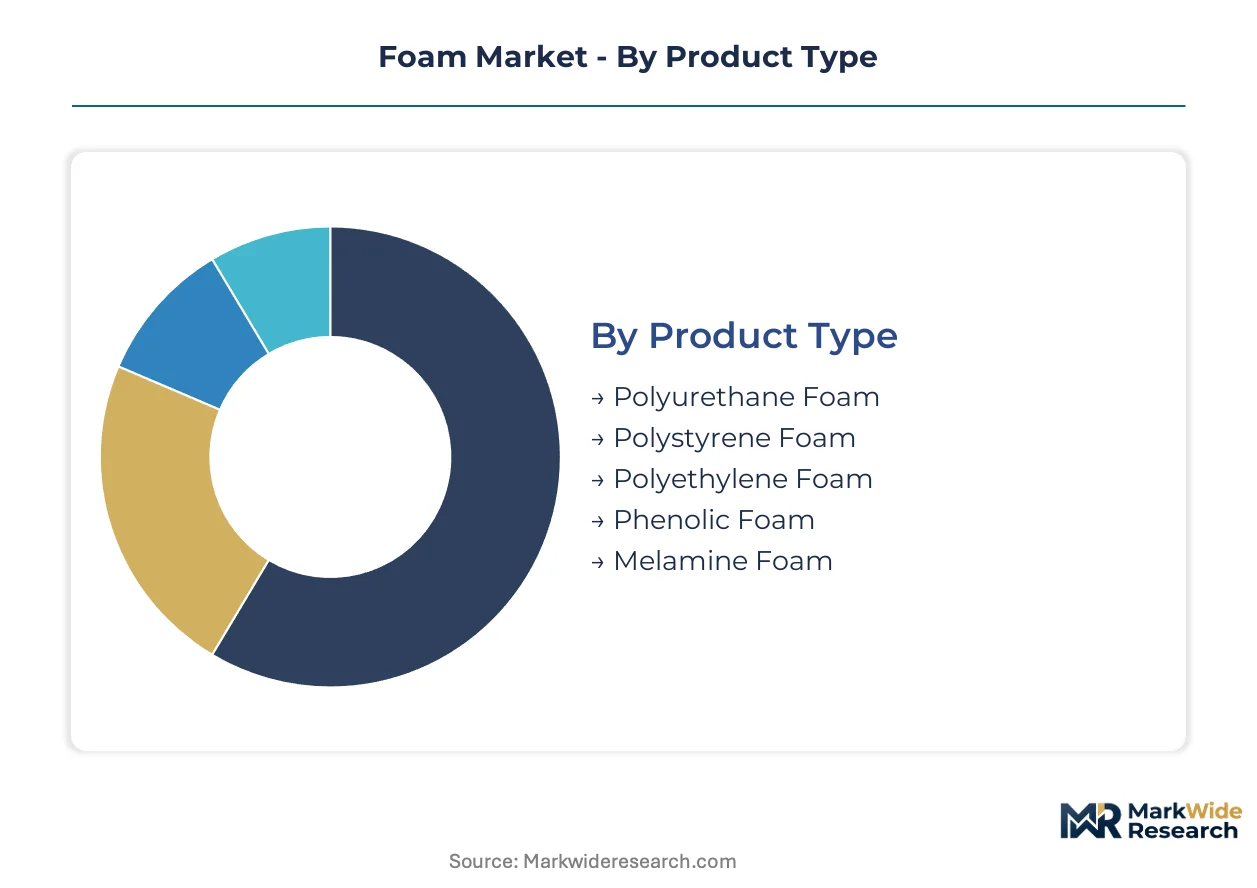
The Foam Market segmentation provides a granular view of product diversity and application-specific demands. This detailed breakdown highlights how material science innovations and end-user requirements influence market dynamics across various industrial and consumer sectors.
Product Type:
The product type segmentation reveals varying development cycles, with some formulations evolving rapidly to meet new performance demands while others maintain established production methods.
- Polyurethane Foam:This versatile polymer offers excellent thermal insulation and cushioning properties. Strong demand concentrates within construction insulation and automotive lightweighting applications.
- Polystyrene Foam:Known for its lightweight, closed-cell structure, this foam provides superior thermal insulation and impact absorption. Significant demand is observed in packaging and building envelope applications.
- Polyethylene Foam:Flexible and shock-absorbing, used in protective packaging and sports equipment.
- Phenolic Foam:Offers high fire resistance and low smoke emission, utilized in specialized construction and aerospace.
- Melamine Foam:Open-cell structure provides high sound absorption, primarily for acoustic insulation.
Polyurethane Foam dominates the installed base across diverse applications. Polystyrene Foam is where expansion concentrates due to its broad utility in construction and packaging.
Form:
The form segmentation differentiates foam products by their manufacturing complexity and material input costs, impacting their overall price point and market accessibility.
- Rigid Foam:Its closed-cell structure delivers high thermal resistance, making it essential for energy-efficient building insulation and cold chain logistics.
- Flexible Foam:Characterized by an open-cell structure, it offers superior cushioning and comfort. This form is widely used in furniture, bedding, and automotive seating.
- Spray Foam:Applied as a liquid, it expands and hardens in place, providing seamless insulation in construction.
- Molded Foam:Produced by injecting polymers into molds, common for intricate automotive components.
- Extruded Foam:Continuously produced in sheets or boards, used for insulation and protective packaging.
Flexible Foam holds substantial market volume due to consumer goods applications. Rigid Foam exhibits the steepest expansion trajectory driven by construction mandates.
Application:
The application segmentation highlights diverse end-use requirements, ranging from thermal management to structural support and comfort, each demanding specific foam properties.
- Construction Insulation:This application utilizes rigid foams for superior thermal performance. It is driven by strict building energy codes in Germany and Canada.
- Bedding & Furniture:This segment primarily uses flexible polyurethane foams. It is driven by consumer demand for comfort and durability in home furnishings.
- Packaging Solutions:Employs lightweight foams for cushioning and protection, essential for safe transport of goods.
- Automotive Components:Incorporates foams for lightweighting, NVH reduction, and seating, critical for fuel efficiency.
- Sports Equipment:Uses foams for impact absorption and lightweight design in protective gear.
Construction Insulation represents a significant revenue generator due to its high-performance requirements. Automotive Components are gaining share rapidly, propelled by lightweighting initiatives.
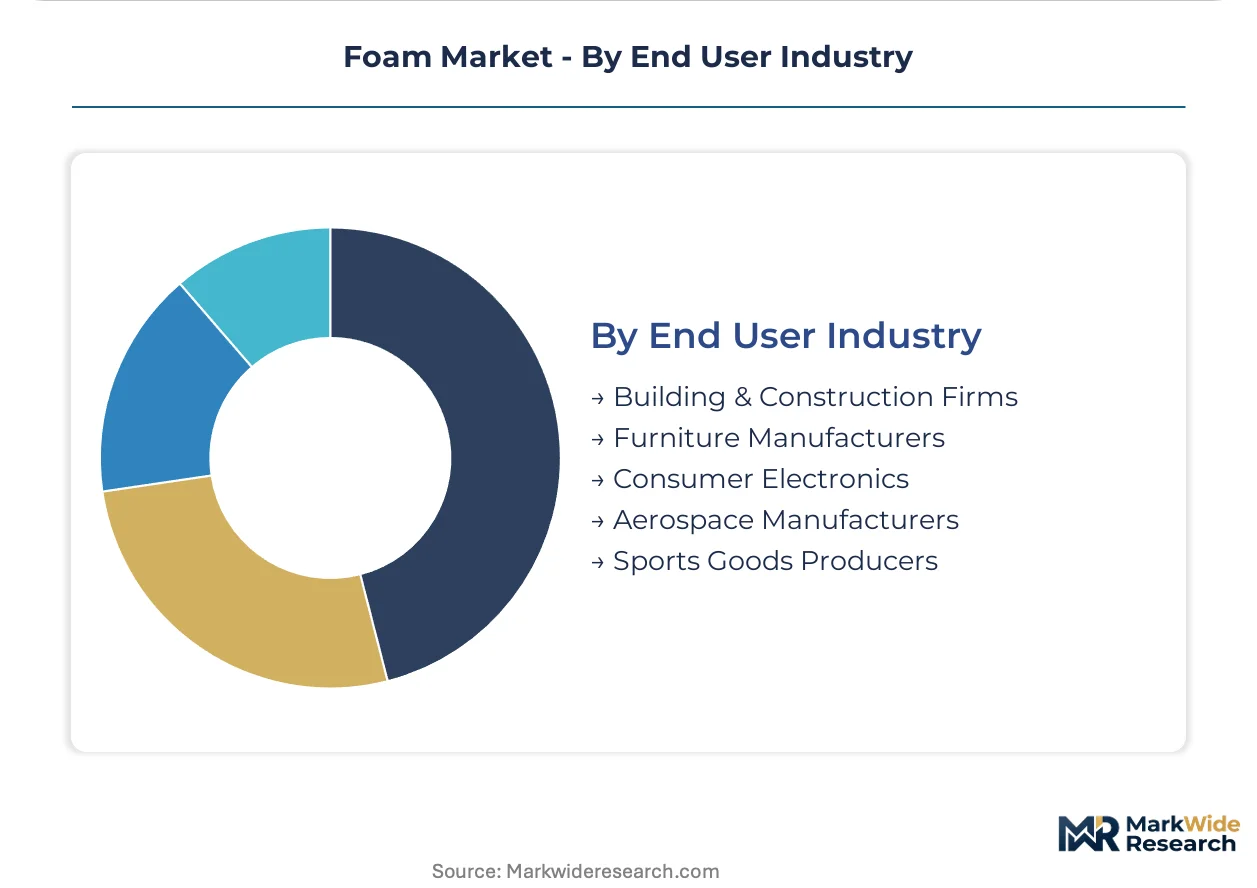
End User Industry:
The end-user industry segmentation reflects distinct procurement patterns and material specification needs, influenced by sector-specific regulations and consumer trends.
- Building & Construction Firms:These firms procure rigid and spray foams for insulation and structural integrity. They are influenced by national building codes and energy efficiency mandates.
- Furniture Manufacturers:These manufacturers require flexible foams for cushioning and upholstery. Their procurement is driven by design trends and sustainability goals for bio-based materials.
- Consumer Electronics:Utilizes foams for packaging, vibration dampening, and internal component protection.
- Aerospace Manufacturers:Specify high-performance, lightweight foams for structural components and insulation.
- Sports Goods Producers:Integrate foams for impact protection, comfort, and weight reduction in equipment.
Building & Construction Firms drive substantial foam volume globally. Aerospace Manufacturers are a growing segment for specialized, high-margin foam solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global foam market dynamics reflect a complex interplay of regional production capabilities and consumption patterns. Significant trade flows occur in specialized foam materials and end-products. This balance shapes localized manufacturing strategies and supply chain resilience across continents.
China
China's expansive manufacturing and construction industries drive substantial demand for polystyrene and polyurethane foams. The country's GB standards dictate material specifications, particularly for fire safety and environmental performance. The Yangtze River Delta region, a major industrial hub, concentrates production of foams for consumer electronics and automotive parts.
Germany
Germany's stringent building energy codes compel the use of high-R-value rigid foams for insulation, boosting construction sector consumption. The EU F-Gas Regulation necessitates costly reformulation of blowing agents, impacting foam system development. Bavaria's automotive cluster drives demand for specialized polyurethane foams in lightweighting and noise-vibration-harshness applications.
United States
United States construction and packaging sectors generate significant demand for rigid and flexible foams. EPA rules on blowing agents influence chemical composition, particularly for insulation products. The Gulf Coast region, a major petrochemical hub, supports large-scale production of key foam precursors, driving innovation in sustainable alternatives.
India
India's large-scale infrastructure projects and expanding automotive industry create substantial demand for foam insulation and seating components. BIS standards for building materials influence foam selection for thermal performance and fire resistance. The Delhi-NCR region, a major commercial center, experiences growth in cold chain logistics and specialized packaging foam applications.
Canada
Canada's national building codes mandate specific thermal performance standards, driving consumption of rigid foam insulation. Health Canada regulations influence chemical safety aspects for foams used in consumer products and construction. Ontario's manufacturing base, especially near Toronto, integrates specialized foams into automotive components and high-performance sports equipment.
Foam Market Key Industry Players
On the supply side, the industry is characterized by a mix of chemical giants with extensive portfolios and specialized foam manufacturers. This market structure exhibits elements of both consolidation among raw material suppliers and fragmentation among downstream foam converters. Integrated chemical producers often leverage economies of scale in feedstock procurement and polymer synthesis. Strategic archetypes include integrated chemical producers, dedicated foam specialists, and niche solution providers. Dominant competitive moves involve capacity expansion to meet demand and strategic partnerships for sustainable material development.
Integrated chemical producers, leveraging their broad material science expertise, represent a significant segment of the market by supplying foundational components. Germany-based BASF SE and United States-based Dow Inc. exemplify this archetype, offering a wide range of polyols, isocyanates, and complete polyurethane systems globally. Germany-based Covestro AG, specializing in high-performance polymer materials, occupies a position at the premium end, focusing on demanding applications in automotive, electronics, and construction sectors, driving material innovation.
| Leading Market Players |
|---|
| Covestro AG |
| Recticel NV/SA |
| BASF SE |
| Armacell International S.A. |
| Sekisui Chemical Co., Ltd. |
| Dow Inc. |
| Rogers Corporation |
| Trelleborg AB |
| Huntsman Corporation |
Cost & Logistics Intelligence
Petrochemical volatility, particularly for TDI and MDI, determines both pricing tier spreads and the geographic concentration of foam precursor production. This commodity price exposure directly influences final product costs and supply chain resilience.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake for specialized foams, while commodity spot pricing applies to basic grades. Price differentiation stems from performance specifications like R-value and specific third-party certifications such as UL Greenguard. Pricing softness stems from intense competition in standard foam grades, particularly for packaging applications. Construction firms are highly price-sensitive for insulation, balancing cost with thermal performance, whereas aerospace manufacturers prioritize performance over cost.
Supply Chain Analysis
Major integrated chemical producers like BASF SE and Dow Inc. hold significant capacity for foam precursors, concentrating supply in key industrial regions. Geographic supply concentration for polyols and isocyanates is notable in China, Germany, and the United States. Raw material dependencies on petrochemicals like MDI and TDI introduce commodity price volatility and regulatory restrictions on blowing agents, such as the EU F-Gas Regulation, create a structural compliance risk. Distribution runs through direct sales channels to large industrial end-users and specialized distributors for smaller volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Foam Market presents a compelling service-attach opportunity, with material lifecycle management and advanced recycling services expanding faster than primary material sales. This shift reflects increasing demand for circularity and end-of-life solutions.
For Market Incumbents: Insulate core market share by accelerating investment in bio-based polyols and advanced chemical recycling technologies. This counters the threat from natural fiber competition and addresses stricter environmental regulations like REACH. Pursue certification investment in standards such as UL Greenguard to differentiate products. Consolidate supply chain control through strategic capacity additions in high-growth regions like India.
For New Entrants and Emerging Players: Establish a beachhead in niche, high-value applications like additive manufacturing of customized foam components for medical devices. Target the cold chain logistics segment with high-performance rigid foams, leveraging unmet demand. The most penetrable segment is specialized aerospace components, where performance requirements allow for premium pricing. A go-to-market angle focused on digital twinning and rapid prototyping for custom foam properties offers differentiation.
For Investors and Strategic Acquirers: The EU Corporate Sustainability Reporting Directive (CSRD) reshapes the acquisition landscape, prioritizing companies with verifiable sustainability data and circular economy solutions. Over the long term, demand for sustainable, high-performance foam materials remains robust. Target mid-cap specialists possessing patented bio-based polyol technologies or economically viable chemical recycling processes for thermoset foams. An increase in strategic partnerships between chemical giants and advanced recycling startups is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia-Pacific | Meets growing construction and automotive demand in India and China. |
| Bio-based Polyol R&D Investment | Addresses sustainability mandates and reduces petrochemical dependency. |
| Chemical Recycling Technology Acquisition | Enables circularity for thermoset foams, a key industry challenge. |
| Digital Twinning Platform Integration | Accelerates custom foam design and reduces physical prototyping waste. |
| Third-Party Certification Pursuit | Differentiates products based on verified performance and environmental standards. |
Research Approach
Initial hypotheses were tested against primary input from polymer scientists, procurement managers at automotive OEMs, and construction material specifiers, then refined. This involved synthesizing insights from in-depth interviews with secondary validation from customs trade data and national building codes. Bottom-up volumetric data was triangulated with top-down market sizing from chemical industry association reports. This rigorous approach ensured a comprehensive understanding of market dynamics.
A demand-supply balance model underpins the quantitative framework, projecting market evolution across the analysis window. Segmentation dimensions included product type, foam form, application, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth trends and projected technological shifts. Forecast inputs included evolving building energy codes and bio-based material adoption rates.
Macroeconomic conditions sit as an overlay; deviation in global construction spending or oil & gas prices would shift the trajectory. Geopolitical instability and supply chain disruptions represent additional risk factors for this market. Quarterly review of raw material prices and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Vacuum Degreasers Market