
 Asia-Pacific Bio Transformer Oil Market | 2026-2036
Asia-Pacific Bio Transformer Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bio Transformer Oil Market Outlook
Utility procurement channels across Southeast Asia and eastern China are reconfiguring as grid operators phase out mineral oil in favor of biodegradable alternatives. Cargill Incorporated leverages its global agricultural supply base to secure feedstock cost advantages for natural ester production. Sinopec anchors domestic distribution through its extensive refinery and chemical logistics network across China. Eaton competes on technical service density, embedding field engineering teams directly with power utility customers.
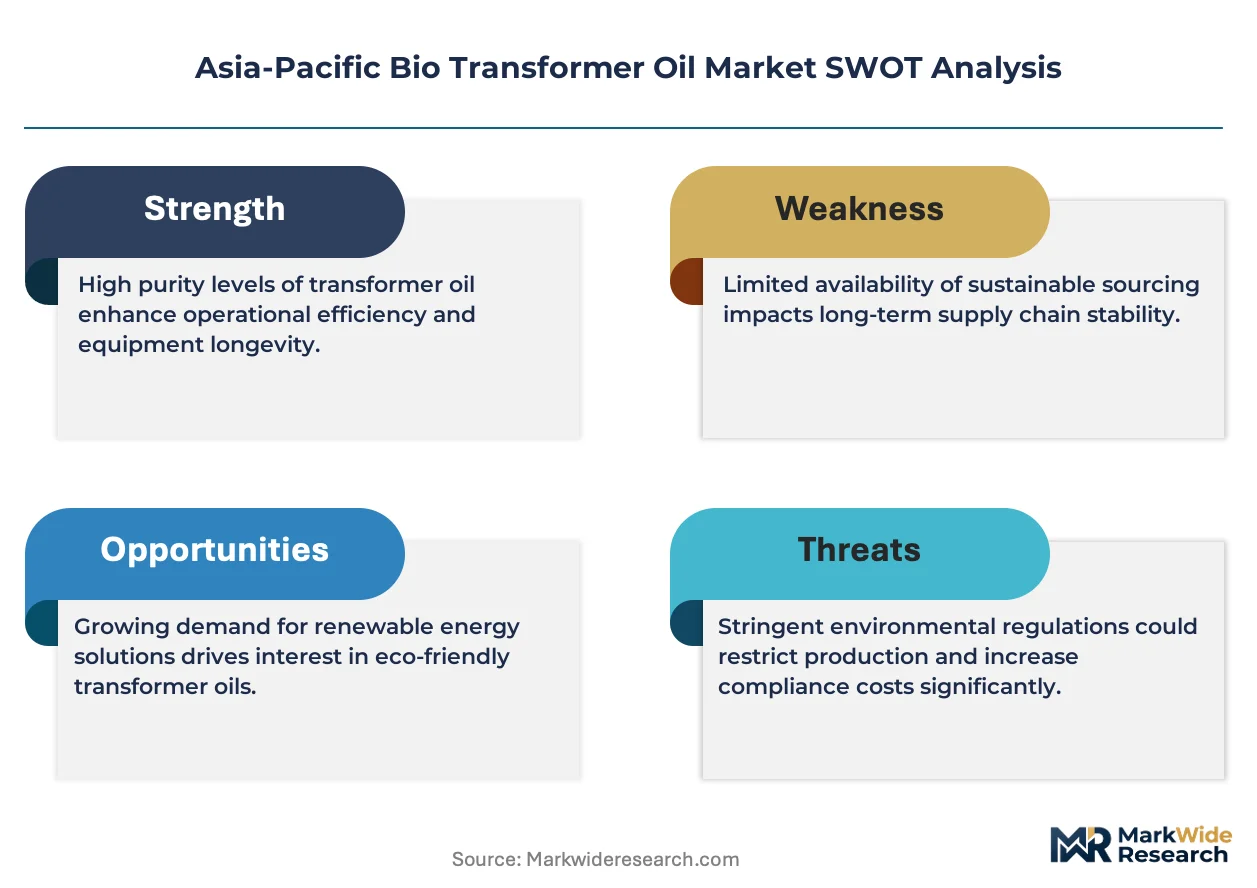
Asia-Pacific bio transformer oil comprises biodegradable dielectric fluids derived from vegetable oils or synthetic esters, formulated with oxidation inhibitors and pour-point depressants to achieve fire points above 300°C and biodegradability exceeding 90% in standardized tests. These fluids insulate and cool transformer windings while reducing environmental liability from spills. Natural ester products lead current volume due to mature supply chains in palm and soybean oil feedstocks, though synthetic ester formulations command premium positioning for high-temperature and compact transformer designs. Power transformers represent the dominant application segment given unit volumes and fluid capacity per installation, while renewable energy end users represent the fastest-expanding demand pool as wind and solar farms require environmentally compliant grid connection assets.
China's SAMR enforces GB standards for transformer fluid fire safety and environmental compatibility, while India's BIS mandates testing protocols that increasingly favor biodegradable alternatives over conventional mineral oil. METI in Japan promotes bio-based insulating fluids through efficiency and carbon-reduction procurement guidelines for utilities. Stakeholders must monitor how rapidly national regulators align fire safety classifications with carbon accounting frameworks to anticipate which fluid chemistries gain preferential grid access.
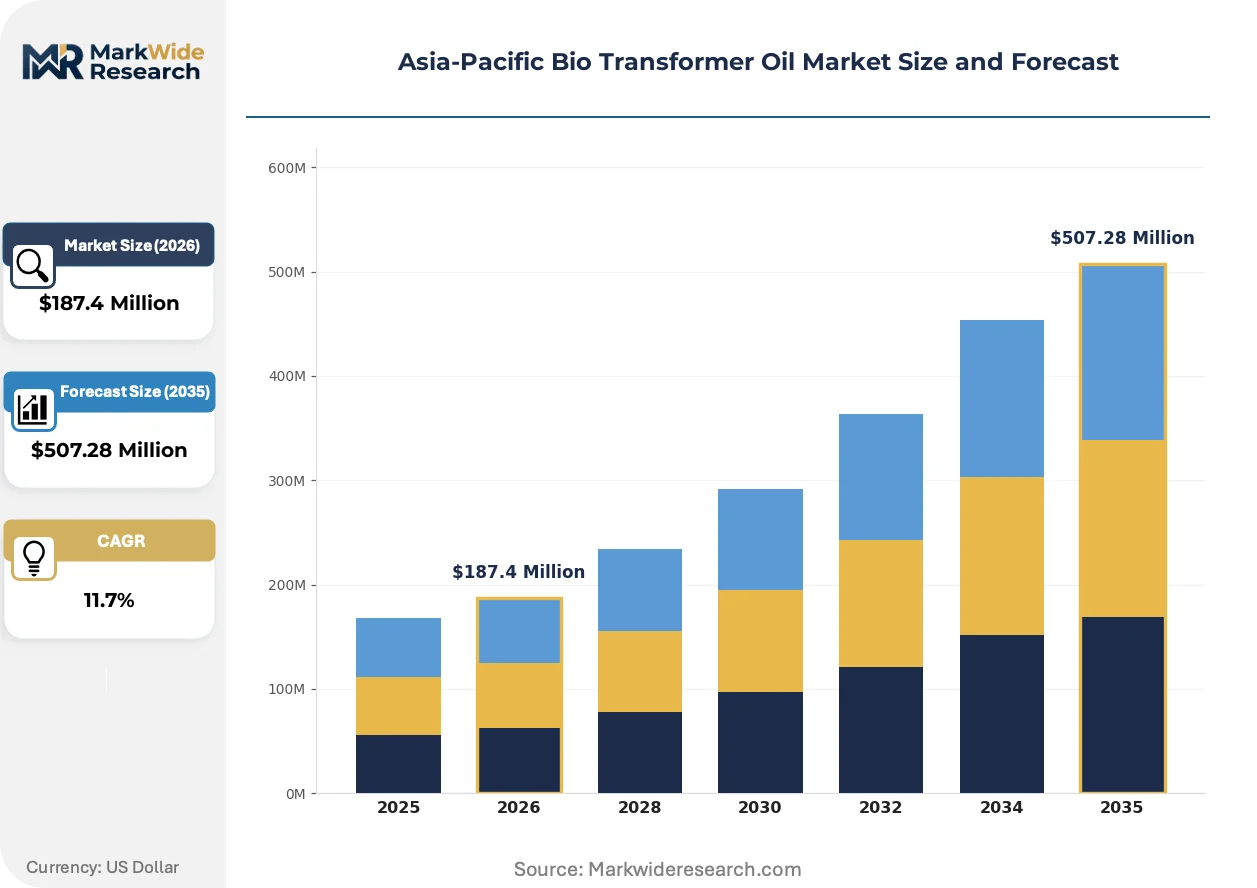
Market Dynamics
China's dual carbon goals and India's BIS standards are structurally accelerating substitution from mineral oil to biodegradable insulating fluids across utility procurement channels. Feedstock supply chains in palm and soybean oils are concentrating competitive advantage among agricultural-anchored producers.
Growth Catalysts
- India's BIS standards:Testing protocols increasingly favor biodegradable alternatives over conventional mineral oil in power transformer installations. Utilities in India's western power corridors are expanding procurement mandates.
- Wind and solar farms:Renewable energy end users require environmentally compliant grid connection assets with fire points above 300°C. This segment represents the fastest-expanding demand pool for natural ester formulations.
- China's SAMR enforcement:GB standards for transformer fluid fire safety and environmental compatibility are compelling grid operators to phase out mineral oil in eastern China.
Market Restraints
- Palm oil price volatility:Natural ester production depends on agricultural commodity markets subject to weather and trade policy disruptions. Feedstock cost swings compress margin predictability for producers lacking captive supply.
- Southeast Asian supply concentration:Biodegradable fluid manufacturing clusters in Malaysia and Indonesia create geographic risk exposure. Logistics disruptions in the Strait of Malacca corridor threaten just-in-time utility procurement.
- Mineral oil residual infrastructure:Existing transformer fleets with decades of remaining service life limit near-term replacement velocity. Utilities face stranded asset calculations when evaluating fluid conversion economics.
Strategic Opportunities
- Vietnam and Philippines power corridors:Underpenetrated utility markets lack established bio-fluid supply relationships. First-mover distributors can anchor long-term procurement contracts as grid expansion accelerates.
- Synthetic ester premium positioning:High-temperature and compact transformer designs command pricing advantages. Formulations with enhanced oxidation stability address data center and urban substation constraints.
- Japan's METI procurement guidelines:Carbon-reduction incentives for utilities create preferential market access for bio-based insulating fluids. Efficiency mandates align with product performance attributes.
Industry Challenges
- Field engineering skill gaps:Transformer maintenance technicians require retraining on bio-fluid handling protocols. Pour-point depressant formulations demand different cold-weather operational procedures than mineral oil.
- BIS certification timelines:Extended testing protocols for biodegradable alternatives delay product market entry. Laboratory capacity constraints in India create queue bottlenecks for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bio Transformer Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Ester, Synthetic Ester, Mineral Oil, Biodegradable Oil Application: Power Transformers, Distribution Transformers, Generator Transformers, Special Transformers End User: Utilities, Industrial Facilities, Commercial Buildings, Renewable Energy Installation: Indoor, Outdoor, Onshore, Offshore |
| Companies Covered | Cargill Incorporated, Eaton, Nynas AB, Sinopec, M&I Materials Ltd, ABBA S.p.A, PSP Specialities Public Company Limited, Savita Oil, Shell Plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bio Transformer Oil Market Strategic Shifts
Advanced synthetic ester formulations with tailored molecular structures are compressing the performance gap with mineral oil while maintaining biodegradability advantages. Manufacturers are embedding oxidation inhibitors that extend fluid service intervals.
Synthetic ester chemistry with customized pour-point and viscosity profiles is rendering obsolete the temperature-performance trade-offs that previously limited bio-fluid adoption in cold-climate installations. Grid operators in northern China are piloting these formulations for winter-peaking substations. The technology is compressing the addressable market gap between premium synthetic and economy natural ester segments.
China's SAMR is tightening GB standard enforcement for transformer fluid fire safety classifications. Manufacturers must now document environmental compatibility alongside thermal performance in product registrations. Eastern Chinese utilities are pre-qualifying suppliers based on dual carbon goal alignment, reshaping competitive access.
Utility procurement departments are consolidating supplier relationships around technical service density rather than commodity pricing alone. Power operators in India and China are embedding field engineering requirements into tender specifications. This behavior shift favors producers with direct service presence over trading-house intermediaries in high-stakes transformer contracts.
Asia-Pacific Bio Transformer Oil Market Segmentation
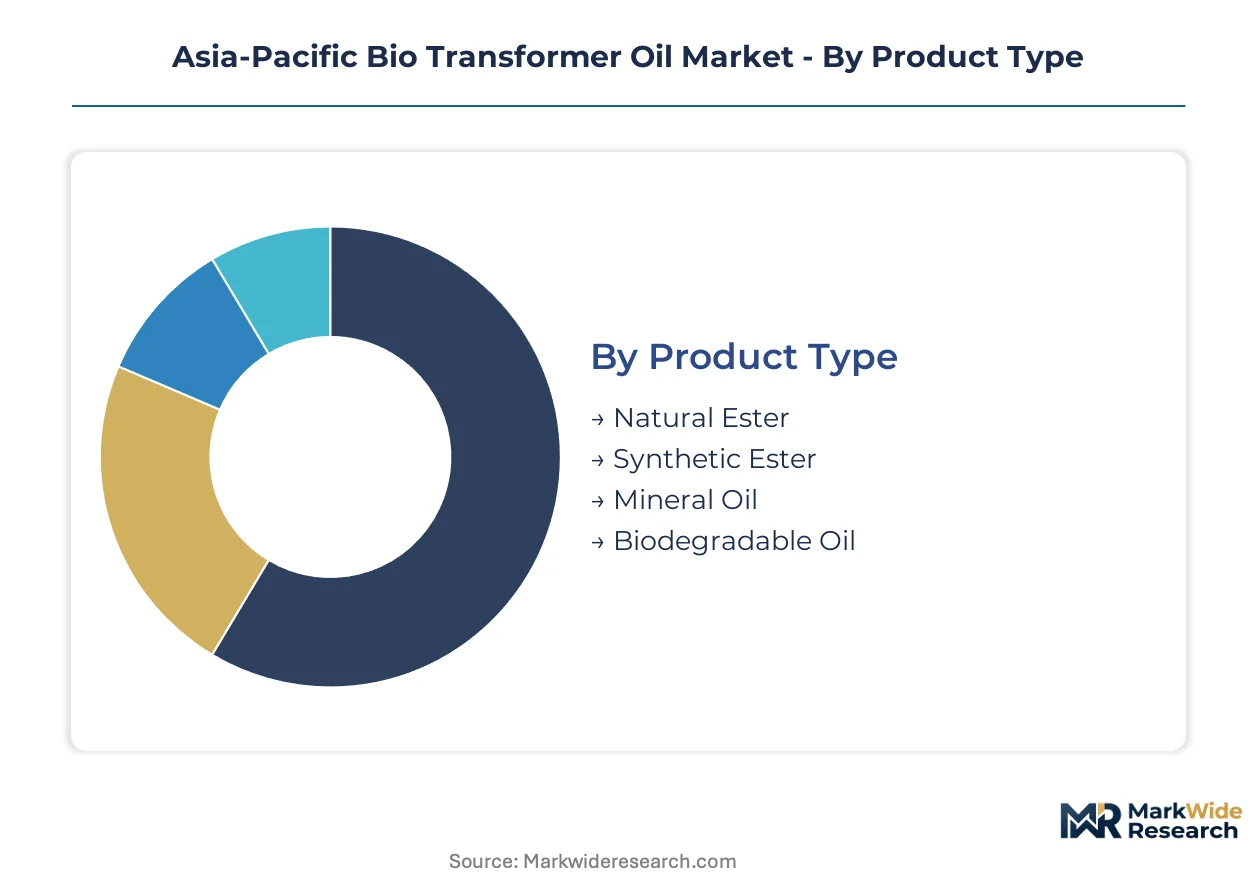
Segmentation in the Asia-Pacific bio transformer oil market exposes divergent replacement cycles across product chemistries and transformer asset classes. Procurement patterns vary sharply between utility fleet operators with decades-long asset horizons and renewable developers with shorter project lifecycles. Understanding these temporal dynamics guides inventory positioning and technical service resource allocation.
Product Type:
Replacement velocity separates these fluid categories, with natural ester formulations cycling through maintenance intervals faster than synthetic alternatives due to oxidation characteristics and feedstock variability.
- Natural Ester:Derived from palm and soybean oil feedstocks with fire points exceeding 300°C and biodegradability above 90% in standardized tests. Procurement concentrates in eastern China and Malaysia where agricultural supply chains anchor production economics. India's western power corridors are expanding procurement mandates under BIS standards that favor biodegradable alternatives.
- Synthetic Ester:Formulated with tailored molecular structures for high-temperature and compact transformer designs. Demand clusters around data center substations and urban grid infrastructure in Japan where METI procurement guidelines reward carbon-reduction performance. Premium positioning commands pricing advantages for oxidation-stable formulations.
- Mineral Oil:Conventional petroleum-derived insulating fluid with established supply infrastructure but declining share under regulatory pressure.
- Biodegradable Oil:Blended formulations targeting specific environmental compliance thresholds without full ester conversion.
Natural ester anchors the volume base while synthetic ester gains share at the steepest rate.
Application:
Unit fluid capacity and asset criticality create a cost tier structure, with power transformers commanding premium service contracts and distribution transformers driving volume throughput.
- Power Transformers:Large-capacity grid assets with fluid volumes exceeding 50,000 liters per unit. Procurement in China's eastern provinces emphasizes fire safety certification under SAMR-enforced GB standards. Technical service density requirements favor suppliers with embedded field engineering teams.
- Distribution Transformers:Smaller units deployed across rural electrification programs and urban densification projects. Volume concentration in India's western corridors supports economy-tier natural ester procurement.
- Generator Transformers:Power plant interconnection assets with specialized thermal cycling requirements.
- Special Transformers:Custom designs for industrial process loads and traction power systems.
Power transformers concentrate margin contribution while distribution transformers expand most quickly across Southeast Asian procurement channels.
End User:
Customer type determines specification stringency, with utilities enforcing legacy compatibility protocols and renewable developers accepting next-generation formulations without retrofit constraints.
- Utilities:Grid operators across China, India, and Southeast Asia with phased mineral oil substitution programs. BIS testing protocols and SAMR fire safety classifications drive qualification timelines. Stranded asset calculations complicate conversion economics for fleets with remaining service life.
- Renewable Energy:Wind and solar farm developers requiring environmentally compliant grid connection assets. This segment climbs the fastest as project finance structures mandate spill liability reduction.
- Industrial Facilities:Manufacturing complexes with captive substations and process-critical power requirements.
- Commercial Buildings:Urban developments with space-constrained transformer installations and fire code sensitivity.
Utilities anchor current procurement volume while renewable energy developers show the steepest expansion trajectory.
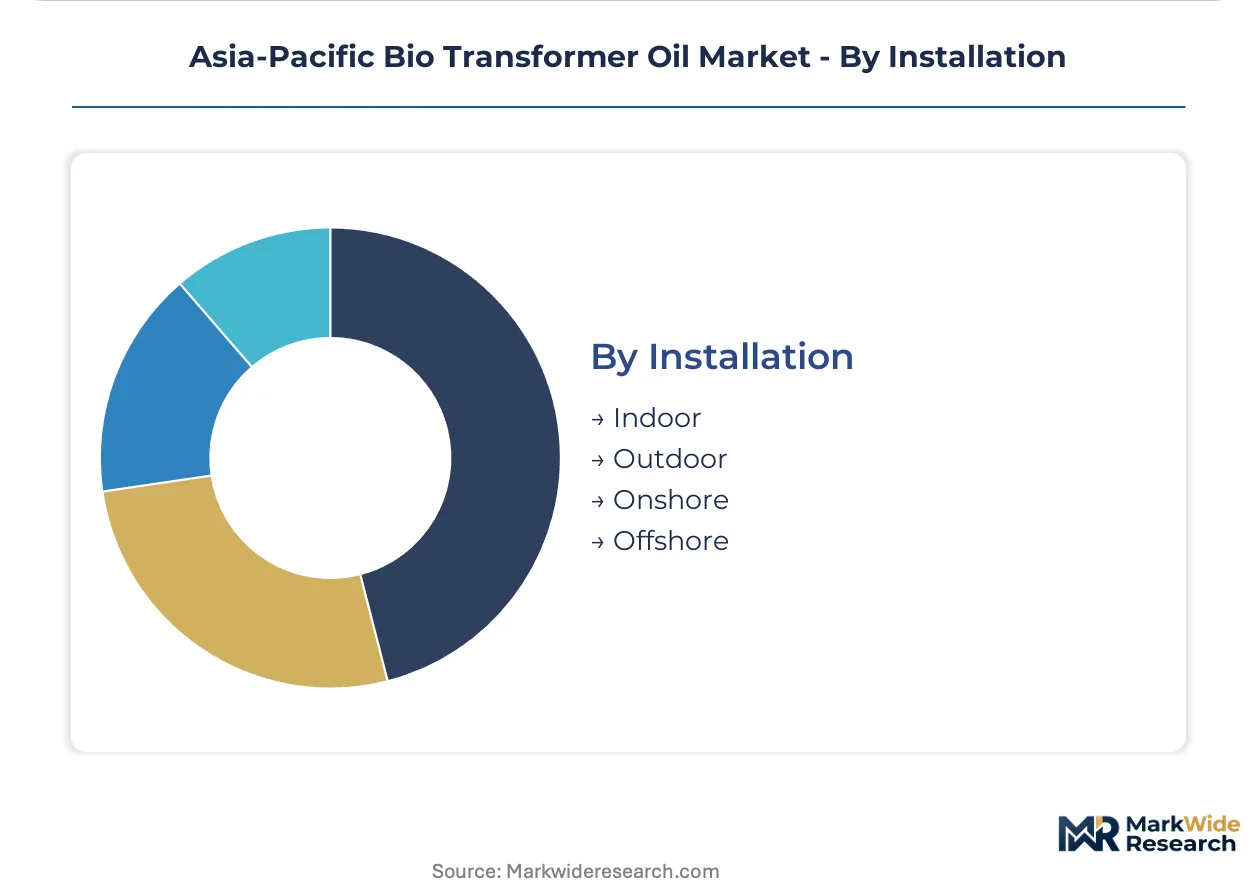
Installation:
Environmental exposure conditions segment the market by operational risk profile, with offshore and outdoor installations demanding enhanced oxidation stability and cold-flow performance.
- Outdoor:Exposed substations across tropical Southeast Asia and temperate northern China. Synthetic ester formulations with customized pour-point profiles address winter-peaking requirements in Hebei and Liaoning provinces.
- Indoor:Space-constrained urban installations where fire point requirements exceed mineral oil capabilities. Data center clusters in Singapore and Tokyo drive specification tightening.
- Onshore:Conventional grid infrastructure with standard environmental protection.
- Offshore:Coastal and marine installations with salt spray exposure and spill sensitivity.
Outdoor installations dominate current deployment while indoor applications gain share fastest on urban densification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Strait of Malacca corridor underwrites Southeast Asia's bio transformer oil logistics, connecting Malaysian and Indonesian feedstock clusters to utility procurement channels across the region. Eastern China's coastal grid infrastructure anchors import throughput for natural ester formulations. India's western power transmission corridors concentrate domestic blending capacity.
China
Eastern provinces including Jiangsu and Zhejiang drive procurement volume as grid operators phase out mineral oil under SAMR-enforced GB standards. The dual carbon goals compel state-owned utilities to pre-qualify suppliers based on environmental compatibility documentation. Northern provinces pilot synthetic ester formulations for winter-peaking substations.
India
Western power corridors spanning Gujarat and Maharashtra expand procurement mandates under BIS testing protocols favoring biodegradable alternatives. Stranded asset calculations complicate conversion economics for utility fleets with remaining service life. Laboratory capacity constraints in Mumbai and Delhi create certification queue bottlenecks.
Japan
Urban substation densification in Tokyo and Osaka drives specification tightening for fire-point performance. METI procurement guidelines reward carbon-reduction alignment in utility tender evaluations. Data center clusters in the Kanto region anchor premium synthetic ester demand.
Vietnam
Rural electrification programs and grid expansion projects create first-mover opportunities for bio-fluid distributors lacking established supply relationships. The underpenetrated utility market lacks incumbent procurement partnerships. Coastal wind farm developments mandate environmentally compliant grid connection assets.
Malaysia
Palm oil feedstock concentration anchors natural ester production economics for export markets. Manufacturing clusters in Penang and Selangor supply biodegradable fluids to Southeast Asian utilities. Geographic concentration creates logistics risk exposure through the Strait of Malacca corridor.
Asia-Pacific Bio Transformer Oil Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on feedstock and formulation technology. The vendor base stratifies across agricultural-anchored producers, petrochemical distributors, and technical service specialists. Three archetypes dominate: global agribusiness operators with captive vegetable oil supply, integrated energy majors leveraging refinery logistics, and electrical equipment specialists embedding field engineering with utility customers. Competitive moves concentrate on backward integration into feedstock sourcing and geographic expansion through distributor partnerships.
Within the agricultural-anchored tier, Cargill Incorporated occupies a position exemplifying global supply base leverage for natural ester production. Sinopec anchors the petrochemical distributor archetype through domestic refinery and chemical logistics networks across China. Eaton represents the technical service specialist model, embedding field engineering density directly with power utility customers. These three players illustrate the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Eaton |
| Nynas AB |
| Sinopec |
| M&I Materials Ltd |
| ABBA S.p.A |
| PSP Specialities Public Company Limited |
| Savita Oil |
| Shell Plc |
| Others |
Value Chain & Pricing Dynamics
Palm oil price volatility determines both the spread between natural and synthetic ester pricing tiers and the geographic clustering of blending capacity around Malaysian and Indonesian feedstock sources. Buyers in eastern China and India's western power corridors face divergent landed costs based on Strait of Malacca logistics exposure and domestic tariff treatment of agricultural imports.
Pricing Analysis
Volume-discount tiering structures separate utility procurement contracts from spot purchases by renewable developers and industrial facilities. Pricing stratifies across premium synthetic ester, standard natural ester, and economy blended formulations based on fire point certification under SAMR-enforced GB standards and BIS testing protocols. Cost compression in the natural ester tier is intensifying because Malaysian palm oil supply swings compress margin predictability for producers lacking captive agricultural supply. State-owned utilities in China exhibit the lowest price sensitivity due to dual carbon goal procurement mandates, while rural electrification programs in Vietnam and the Philippines drive aggressive economy-tier negotiation.
Supply Chain Analysis
Export-control regimes on advanced synthetic ester catalysts and oxidation inhibitor chemistries limit technology transfer to unlicensed blending facilities in Southeast Asia. Manufacturing gravity centers on Malaysia, Indonesia, and eastern China where palm oil feedstock, refinery logistics infrastructure, and utility demand clusters overlap. Raw material dependencies include palm and soybean oil agricultural supply, specialty chemical additives for pour-point depression, and fire-retardant base stocks from petrochemical streams. Single-source vulnerability concentrates in the Strait of Malacca corridor where maritime disruption threatens just-in-time delivery to eastern Chinese grid operators. Distribution runs through integrated energy majors with captive refinery networks and agricultural-anchored producers with direct utility contracting arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility procurement consolidation across China and India concentrates buyer power among state-owned grid operators with multi-year tender frameworks. This consolidation fragments pricing leverage for smaller producers dependent on spot market sales.
For Market Incumbents: Insulate margin position through backward integration into Malaysian and Indonesian palm oil supply chains before feedstock cost swings destabilize natural ester economics. Secure BIS certification queue priority in Mumbai and Delhi laboratory networks to accelerate product entry ahead of mineral oil substitution deadlines. Anchor long-term offtake contracts with eastern Chinese utilities under SAMR-enforced GB standard pre-qualification requirements. For New Entrants and Emerging Players: Mid-market commercial buildings and data center substations in Southeast Asia represent the most penetrable entry point given fire code sensitivity and absence of incumbent technical service relationships. Coastal wind farm developments in Vietnam and the Philippines offer white-space procurement channels without established bio-fluid supply partnerships. Lead with synthetic ester formulations targeting indoor installation specifications where premium positioning offsets volume disadvantages. For Investors and Strategic Acquirers: India's BIS standards alignment with carbon accounting frameworks reshapes the acquisition landscape toward certified formulation capabilities. Five-to-ten year viability favors targets with laboratory testing relationships and field engineering density in utility customer accounts. The signal to watch is queue clearance velocity at BIS certification facilities as a leading indicator of product pipeline conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill's agricultural supply base anchors natural ester cost advantages against palm oil volatility. |
| Field Engineering Density Expansion | Eaton's embedded technical teams secure utility tender wins through service-level differentiation. |
| Synthetic Ester Capacity Buildout | High-temperature formulations address data center substation constraints in Tokyo and Singapore. |
| Long-term Utility Supply Agreement | Sinopec's refinery network locks in eastern Chinese grid operator procurement under dual carbon mandates. |
| Certification Fast-track Investment | Laboratory capacity expansion in Mumbai and Delhi reduces BIS queue bottlenecks for new entrants. |
Study Parameters
Cross-validation between primary interviews with utility procurement officers, transformer OEM technical directors, and agricultural commodity traders anchors the qualitative findings against secondary trade flow data and regulatory filing analysis. Bottom-up triangulation combined transformer installation databases with fluid consumption estimates across power and distribution asset classes. Top-down validation referenced SAMR GB standard enforcement timelines and METI procurement guideline implementation schedules.
Calibration against historical substitution velocity in European bio transformer oil markets informed adoption curve assumptions across the projection horizon. Segmentation modeling spanned product chemistry tiers, transformer capacity classes, end-user procurement structures, and installation environment risk profiles. CAGRs were derived from utility capital expenditure trajectories, renewable energy interconnection mandates, and mineral oil fleet replacement economics. Industry-specific inputs included palm oil futures curve shapes and BIS laboratory capacity expansion plans.
Stress conditions across palm oil price bands, Strait of Malacca logistics disruption scenarios, and BIS certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and utility fleet replacement willingness. Material shifts in India's BIS standards implementation pace or China's dual carbon goal acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Hydrogen Sulphide Market
Industrial Chemicals
Regenerative Thermal Oxidizer Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market