
 Electronic Grade Trimethylindium Market | 2026-2036
Electronic Grade Trimethylindium Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Grade Trimethylindium Market Insights
SEMI S2 equipment safety qualification is collapsing the supplier base for electronic grade trimethylindium, as only firms with certified cleanroom production lines can serve leading semiconductor foundries. Tosoh Finechem leverages its integrated fine chemical infrastructure to sustain high-volume output of ultra-high-purity metalorganics. Albemarle anchors North American supply through its specialty chemicals network, while Vital Materials dominates indium raw material refining and backward integration into precursor synthesis.
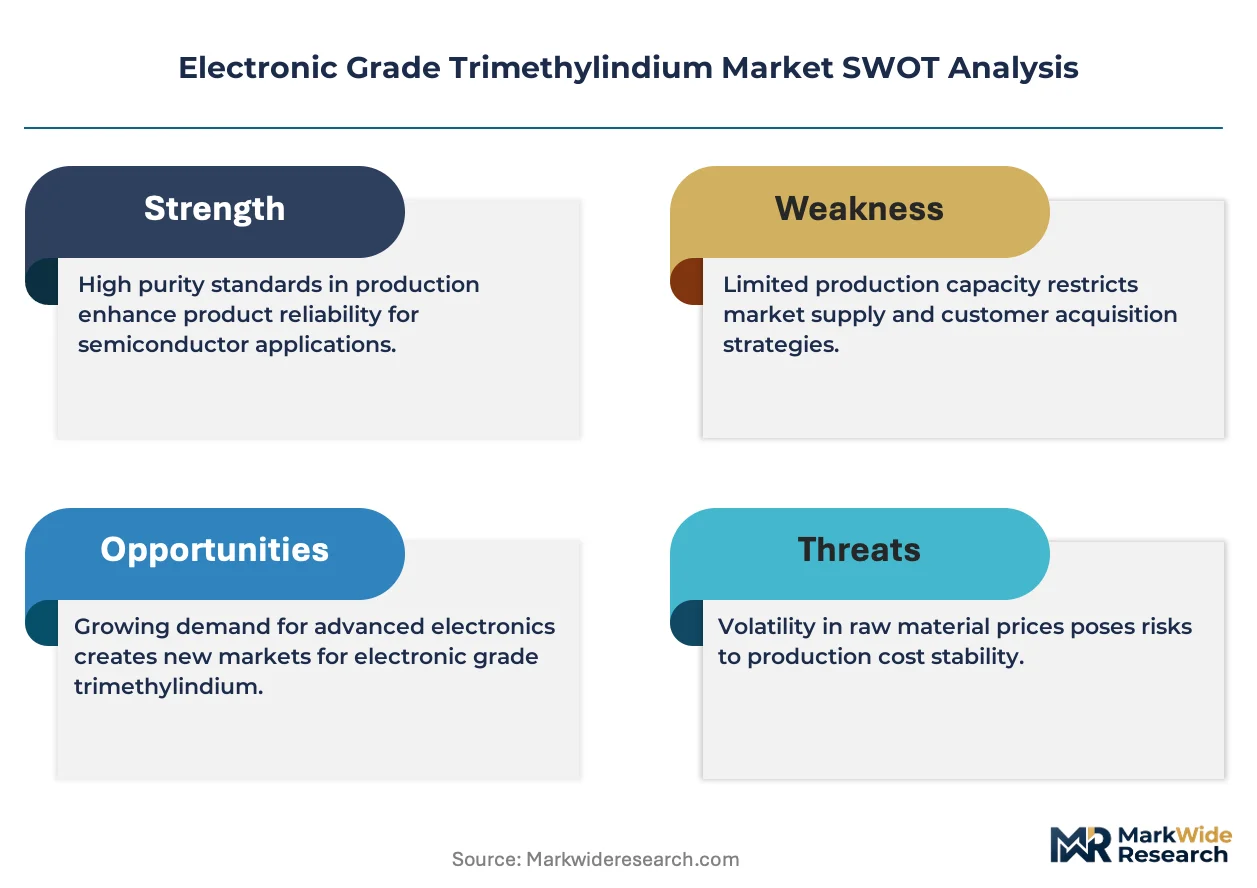
Electronic grade trimethylindium is an organometallic compound with the formula In(CH₃)₃, typically manufactured at 6N+ purity (99.9999%) through direct synthesis of metallic indium with methyl halides followed by distillation and sublimation, serving as a critical precursor for metal-organic chemical vapor deposition of indium-containing III-V semiconductor layers. High-purity product grades command the dominant margin pool due to stringent particle and metal-impurity specifications for advanced node logic chips. Semiconductor fabrication plants represent the fastest-growing end user category as EUV-based 3nm and 2nm processes expand indium phosphide and indium gallium arsenide epitaxy steps.
EPA hazardous air pollutant standards and OSHA process safety management requirements govern trimethylindium handling, storage, and transport in the United States, while REACH registration and CLP classification in Europe mandate extensive toxicological documentation that elevates compliance costs for non-European exporters. China's MEE enforces dual carbon goals through emissions intensity caps on organometallic synthesis facilities, pushing producers toward closed-loop manufacturing. Stakeholders must monitor evolving semiconductor export control lists and precursor chemical dual-use regulations that could abruptly reshape qualified supplier rosters and regional sourcing obligations.
Market Dynamics
SEMI S2 cleanroom certification requirements are compressing the qualified supplier base for electronic grade trimethylindium, as only facilities meeting equipment safety and particle contamination standards can serve advanced semiconductor foundries producing sub-7nm logic chips.
Growth Catalysts
- EUV lithography expansion:3nm and 2nm logic node ramps at Taiwan Semiconductor Manufacturing and Samsung Foundry are multiplying metal-organic chemical vapor deposition steps for indium phosphide and indium gallium arsenide epitaxy layers.
- REACH substance registration:ECHA's phased compliance deadlines for organometallic precursors are locking in established European suppliers with completed toxicological dossiers while elevating barriers for new market entrants.
- Memory chip fabrication:South Korea's concentration of DRAM and NAND flash facilities in Pyeongtaek and Icheon corridors is sustaining concentrated demand for ultra-high-purity indium precursors.
Market Restraints
- Indium metal supply concentration:Primary indium refining capacity clusters in Chinese smelters, exposing precursor manufacturers to export quota volatility and geopolitical supply disruptions.
- Pyrophoric handling infrastructure:OSHA process safety management mandates for air-sensitive organometallics require specialized glovebox systems and inert atmosphere transport vessels that inflate capital intensity.
- Alternative precursor development:Research into indium amidinate and indium cyclopentadienyl complexes threatens long-term displacement of trimethylindium in select atomic layer deposition applications.
Strategic Opportunities
- India semiconductor manufacturing:Micron Technology's planned assembly and test facility in Gujarat and Tata Group's proposed fab in Dholera create virgin demand territory for qualified precursor suppliers.
- Closed-loop synthesis systems:China's MEE emissions intensity caps are incentivizing producers to invest in solvent recovery and waste minimization technologies that yield operational cost advantages.
- Silicon photonics integration:Convergence of indium phosphide lasers with silicon waveguides in datacenter optical transceivers is opening specialized epitaxy service markets outside traditional logic foundries.
Industry Challenges
- 6N+ purity certification timelines:Qualification cycles for new trimethylindium batches at leading foundries extend 12-18 months, freezing supplier switching and amplifying customer concentration risk.
- Organometallic chemist scarcity:The specialized synthesis expertise required for air-free manipulation of indium alkyls is concentrating at a handful of academic programs and industrial training centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Grade Trimethylindium Market |
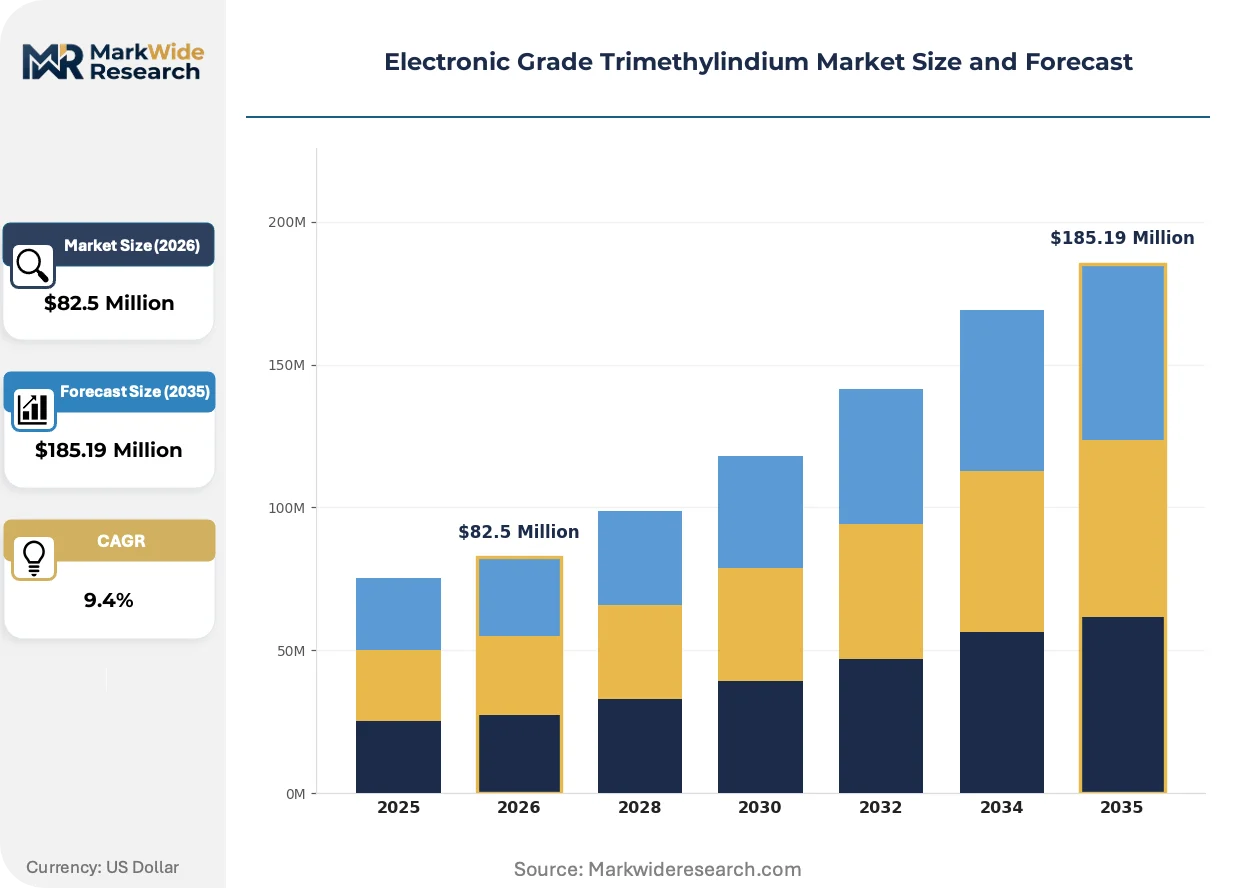
| Market Size in 2026 | $82.5 Million |
| Market Size in 2035 | $185.19 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity, Standard Grade, Technical Grade, Specialty Grade Application: LED, Solar Cells, Semiconductors, Thin-Film Transistors End User: Electronics Manufacturers, Research Institutions, Solar Energy Providers, Semiconductor Fabrication Plants Packaging Type: Drums, Cylinders, Bags, Containers |
| Companies Covered | Jiangsu Nata Opto, ARGOSUN, Tosoh Finechem, Vital Materials, Albemarle, Merck KGaA, Nouryon, Lake Materials, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Grade Trimethylindium Market Trends and Innovations
Advanced node semiconductor manufacturing is fragmenting precursor specifications across customer tiers, as leading-edge foundries demand custom purity profiles while mature-node producers accept standardized grades. This divergence is reshaping R&D allocation and production line configuration across the supply base.
Point-of-use purification is fragmenting traditional bulk precursor supply models. Leading memory chip manufacturers in South Korea now specify trimethylindium delivery through vessel-integrated filtration systems that remove particulates immediately before injection into metal-organic chemical vapor deposition reactors. This architecture is compressing the addressable market for conventional bulk chemical suppliers while expanding service contracts for integrated gas and chemical delivery specialists.
REACH authorization requirements for substances of very high concern are fragmenting import pathways into European Union member states. ECHA's 2024 updates to organometallic substance classification have triggered re-registration obligations for trimethylindium and related indium alkyls, forcing non-European producers to establish EU-based legal entities or exclusive distributor relationships. German chemical distributors with existing ECHA liaison infrastructure are capturing expanded margin share from direct Asian exporters.
Dual-source procurement mandates are fragmenting long-term supply agreements at major semiconductor fabricators. Taiwan Semiconductor Manufacturing and Intel have both instituted vendor qualification requirements that obligate minimum two approved suppliers for all critical metal-organic precursors, including electronic grade trimethylindium. This policy is compressing contract durations from five-year frameworks toward rolling annual agreements with price renegotiation clauses, elevating working capital requirements for qualified producers.
Electronic Grade Trimethylindium Market Segmentation
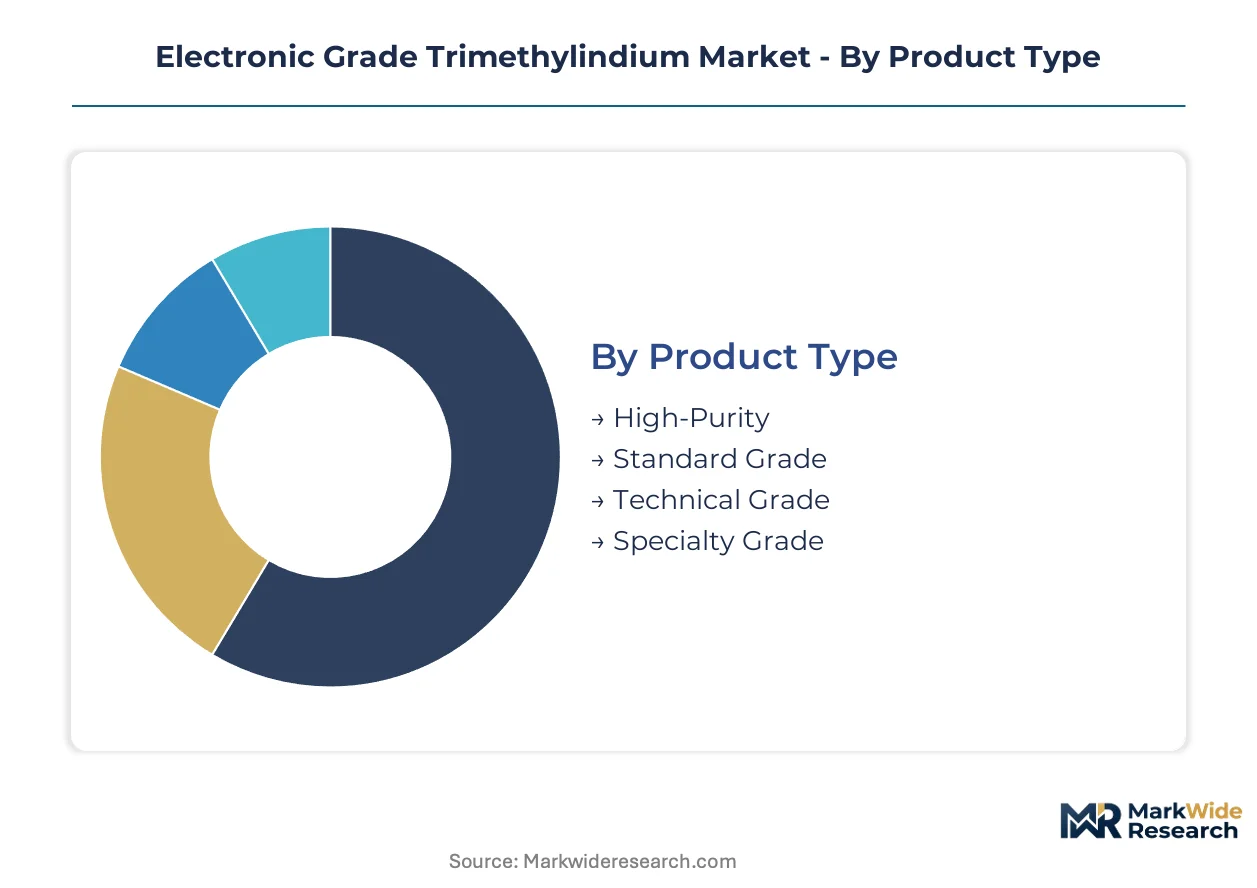
Electronic grade trimethylindium procurement channels diverge sharply across purity tiers and end-use applications. Semiconductor fabrication plants demand certified supply chains with point-of-use purification, while research institutions and solar energy providers accept conventional bulk packaging with simpler logistics.
Product Type:
High-purity grades flow through semiconductor foundry-qualified channels with SEMI S2 certification, while standard and technical grades serve industrial research and compound semiconductor prototyping through distributor networks.
- High-Purity:Manufactured at 6N+ purity (99.9999%) through multi-stage distillation and sublimation. Taiwan Semiconductor Manufacturing and Samsung Foundry concentrate orders here for EUV-based 3nm and 2nm indium phosphide epitaxy steps.
- Standard Grade:Typically 5N purity (99.999%) serving mature-node logic and analog chip production. South Korea's display manufacturing corridors in Gumi and Paju sustain concentrated offtake for LED and thin-film transistor applications.
- Technical Grade:4N purity specifications for academic research and materials characterization. University cleanroom facilities in Germany and Japan represent the primary demand nodes.
- Specialty Grade:Custom-formulated variants with modified alkyl chain lengths or solvent complexes. Niche demand concentrates at national laboratory systems requiring project-specific precursor properties.
High-Purity dominates installed base. Standard Grade is where expansion concentrates.
Application:
Cost tier stratification separates premium epitaxy applications from commodity deposition processes, with purity premiums widening between semiconductor-grade and industrial-grade end uses.
- Semiconductors:Metal-organic chemical vapor deposition of indium gallium arsenide and indium phosphide layers for advanced node logic and RF devices. Taiwan and South Korea fabrication clusters drive volume.
- LED:Blue and white LED epitaxy on sapphire and silicon carbide substrates. China's dual carbon goals are accelerating MOCVD reactor deployment for solid-state lighting manufacturing.
- Solar Cells:Copper indium gallium selenide thin-film photovoltaic deposition. European solar module assembly plants in Germany and the Netherlands sustain residual demand.
- Thin-Film Transistors:Indium gallium zinc oxide backplane deposition for OLED displays. Japanese display panel manufacturers in Osaka and Hiroshima prefectures anchor procurement.
Semiconductors command margin concentration. LED is climbing the fastest.
End User:
Customer type determines packaging specifications, with semiconductor fabrication plants requiring vessel-integrated filtration systems while research institutions accept standard cylinders.
- Semiconductor Fabrication Plants:Sub-7nm foundries specify point-of-use purification with inert atmosphere delivery. Intel and Taiwan Semiconductor Manufacturing dual-source procurement mandates are fragmenting supplier contracts.
- Electronics Manufacturers:Display panel and optoelectronic device producers with intermediate purity requirements. South Korean chaebol-affiliated chemical distributors capture consolidated procurement.
- Research Institutions:University and national laboratory systems with small-batch, high-frequency ordering patterns. German Max Planck Institutes and Japanese RIKEN centers represent stable demand.
- Solar Energy Providers:Thin-film photovoltaic manufacturers with price-sensitive procurement. Chinese state-owned energy conglomerates dominate this segment.
Semiconductor Fabrication Plants dominate installed base. Electronics Manufacturers is where expansion concentrates.
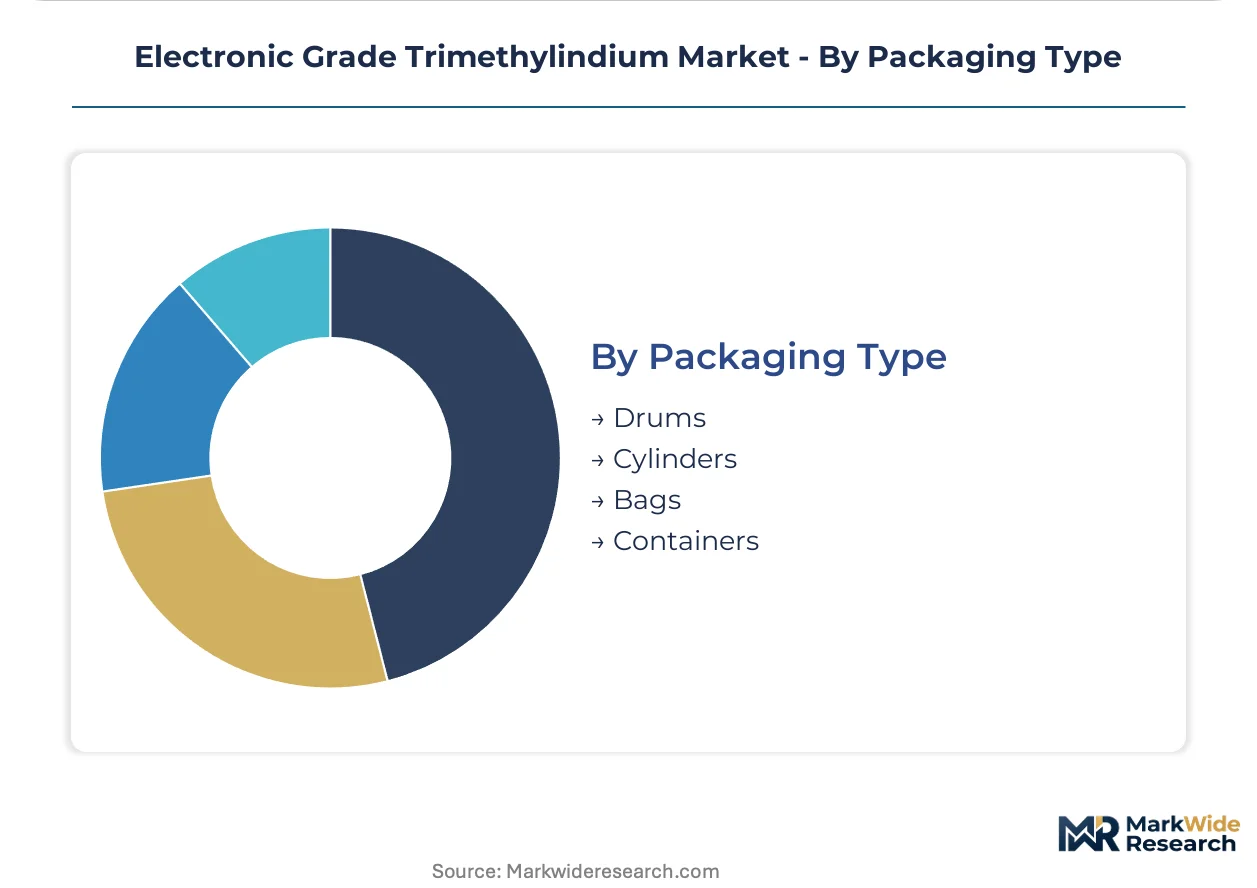
Packaging Type:
Supply concentration in pyrophoric handling infrastructure shapes packaging selection, with cylinders and specialized containers commanding premium positioning over conventional drums.
- Cylinders:Stainless steel vessels with dip-tube delivery for inert atmosphere transfer. Semiconductor foundries specify cylinder-integrated filtration for particle removal at point of use.
- Containers:Sealed aluminum vessels for moderate-volume precursor delivery. Electronics manufacturers in Japan and South Korea prefer container-based logistics for multi-site distribution.
- Drums:Industrial-scale packaging for technical grade and research quantities. Academic institutions and solar cell producers accept drum-based supply with simplified handling protocols.
- Bags:Flexible intermediate bulk containers for specialty grade custom formulations. Limited adoption due to air sensitivity and inerting challenges.
Cylinders dominate installed base. Containers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and South Korea's semiconductor subsidies are accelerating metal-organic precursor deployment across East Asian fabrication corridors. Regulatory frameworks in Germany and the United States are tightening purity benchmarks while expanding qualified supplier pools.
South Korea
Samsung Foundry and SK Hynix are expanding EUV-based 3nm production in Pyeongtaek and Icheon, multiplying orders for 6N+ trimethylindium. The Ministry of Trade, Industry and Energy offers tax credits for domestic precursor localization. Seoul Capital Area fabrication clusters now require dual-source procurement for all critical metal-organics.
China
Yangtze Memory Technologies and Hua Hong Semiconductor are ramping indium phosphide epitaxy for RF and power devices. The Ministry of Ecology and Environment enforces emissions intensity caps on organometallic synthesis facilities through its dual carbon implementation framework. Jiangsu and Zhejiang province chemical parks are consolidating precursor production under state-affiliated conglomerates.
United States
Intel's Arizona and Ohio fab investments are qualifying new trimethylindium suppliers for advanced node production. OSHA process safety management mandates govern pyrophoric handling infrastructure requirements. The CHIPS and Science Act directs federal funding toward domestic semiconductor chemical supply chain resilience.
Germany
Infineon Technologies and Bosch are expanding silicon carbide and gallium nitride foundry capacity in Dresden and Reutlingen. ECHA REACH registration requirements for organometallic precursors mandate completed toxicological dossiers for market access. Bavaria's chemical industry cluster hosts specialized distributors with existing ECHA liaison infrastructure.
Japan
Tokyo Electron and Shin-Etsu Chemical are integrating indium-based III-V layers into silicon photonics platforms. METI's semiconductor revitalization strategy prioritizes precursor supply chain security for advanced packaging. Osaka and Hiroshima prefectures concentrate display panel manufacturing with concentrated demand for indium gallium zinc oxide precursors.
Electronic Grade Trimethylindium Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification timelines, creating a tiered structure where public chemical conglomerates anchor volume contracts while private refiners capture margin on ultra-high-purity grades. Three archetypes dominate: integrated fine chemical houses with backward control over indium metal supply, specialty gas distributors with point-of-use purification integration, and regional smelter-affiliated producers serving captive domestic demand. Competitive moves concentrate on dual-source qualification racing and closed-loop synthesis system deployment.
Within the integrated fine chemical tier, Tosoh Finechem and Albemarle exemplify archetypes of scale-driven producers with certified cleanroom infrastructure. Vital Materials anchors the raw material refining vector. Merck KGaA and Nouryon occupy positions bridging specialty chemical distribution with semiconductor-qualified logistics networks.
| Leading Market Players |
|---|
| Jiangsu Nata Opto |
| ARGOSUN |
| Tosoh Finechem |
| Vital Materials |
| Albemarle |
| Merck KGaA |
| Nouryon |
| Lake Materials |
| LANXESS |
| Others |
Pricing and Supply Chain Analysis
Alternative precursor development displaces trimethylindium in select atomic layer deposition applications, simultaneously shifting procurement geography toward European research corridors and compressing pricing premiums for legacy 6N+ grades as buyers hedge qualification investments.
Pricing Analysis
Certification level creates the primary spread between 6N+ semiconductor-grade and 4N technical-grade products. Three-tier pricing structure across high-purity, standard, and technical levels dominates, with SEMI S2 qualification and REACH dossier completion driving premium capture. Pricing pressure stems from dual-source procurement mandates at Taiwan Semiconductor Manufacturing and Intel, which fragment contract durations and intensify annual renegotiation cycles. Solar energy providers exhibit highest price sensitivity due to commodity thin-film module economics, while sub-7nm foundries absorb premiums for particle-specified delivery systems.
Supply Chain Analysis
China and South Korea anchor primary indium metal refining and advanced precursor synthesis respectively. Raw material flows draw from Chinese smelter output, methyl halide feedstocks, and specialized stainless-steel vessel fabrication concentrated in Japan and Germany. Single-source vulnerability concentrates in Jiangsu and Zhejiang province chemical parks where state-affiliated conglomerates consolidate organometallic production. Distribution runs through semiconductor-qualified logistics networks with ECHA-registered German distributors capturing expanded margin share from direct Asian exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across purity tiers and point-of-use delivery models creates niche entry points as leading foundries diverge from standardized procurement toward custom-specified supply architectures.
For Market Incumbents: Fortify backward integration into indium metal refining to offset Chinese export quota volatility, while accelerating closed-loop synthesis system deployment to meet MEE emissions intensity caps. Dual-source qualification racing at Samsung Foundry and SK Hynix threatens customer concentration advantages; SEMI S2 certification renewal cycles offer defensive moat extension through 12-18 month qualification timelines that freeze supplier switching. For New Entrants and Emerging Players: Point-of-use purification service gaps in Indian semiconductor manufacturing corridors offer white-space penetration as Micron Technology's Gujarat facility and Tata Group's Dholera fab create virgin demand without incumbent vessel-integrated filtration contracts. Target research institution procurement through technical-grade bulk packaging with simplified logistics, leveraging shorter qualification cycles against foundry-tier certification barriers. Partner with German chemical distributors possessing existing ECHA liaison infrastructure to bypass REACH re-registration obligations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty gas distributors with point-of-use purification integration capabilities. Long-term viability centers on capture of silicon photonics epitaxy service markets outside traditional logic foundries, where indium phosphide laser convergence with silicon waveguides diversifies end-use concentration. Monitor ECHA authorization timelines for organometallic substances of very high concern as inflection indicators for import pathway restructuring and margin capture redistribution toward EU-based legal entities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Refining | Vital Materials and Albemarle anchor supply security against Chinese export quota volatility. |
| Closed-Loop Synthesis System Deployment | Tosoh Finechem leverages solvent recovery to meet MEE dual carbon emissions intensity caps. |
| Dual-Source Qualification Racing | Intel and Taiwan Semiconductor Manufacturing fragment contract structures toward rolling annual agreements. |
| Point-of-Use Purification Integration | South Korean memory manufacturers specify vessel-integrated filtration compressing conventional bulk supply. |
| ECHA Liaison Infrastructure Acquisition | German distributors capture margin share from direct Asian exporters facing REACH re-registration. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with precursor synthesis directors, semiconductor fab procurement leads, and organometallic chemists at academic training centers; and secondary validation through customs trade data, SEC chemical company filings, and ECHA registration databases. Bottom-up triangulation across purity tier shipment volumes and top-down cross-check against MOCVD reactor deployment disclosures ensured segmentation integrity.
Across the analysis window, the forecasting framework modeled grade tier stratification, end-use application concentration, packaging format evolution, and regional regulatory cluster differentiation. CAGRs were derived from installed base expansion at EUV-based 3nm and 2nm fabrication nodes and indium phosphide epitaxy step multiplication. Forecast inputs incorporated REACH authorization phase-in schedules and CHIPS Act funding disbursement patterns for domestic chemical supply chain resilience.
Underlying assumptions cover sustained EUV lithography ramp rates and stable indium metal export licensing from Chinese smelters, with deviation risk concentrated in semiconductor export control list expansions and precursor chemical dual-use regulation shifts. Recalibration cycles align with material shifts in ECHA substance classification updates and MEE emissions intensity enforcement actions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Desmutting Agent Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Pressure Filter Market