
 Hydro Fluorocarbon Market | 2026-2036
Hydro Fluorocarbon Market Size, Share, and Industry Trends Forecast 2026-2036
Hydro Fluorocarbon Market Foresight
Refrigerant reclamation and recovery services is hardening into a mandatory revenue layer rather than an optional add-on across the hydro fluorocarbon value chain. Honeywell International Inc. leverages its stewardship-certified reclamation network to lock in aftermarket relationships with commercial HVAC operators. Daikin Industries Ltd. anchors its position through captive collection infrastructure tied to equipment lease programs in Japan and Southeast Asia. The Chemours Company differentiates by bundling reclamation credits with virgin refrigerant sales to large industrial accounts.
Hydro fluorocarbons are synthetic organofluorine compounds containing hydrogen, fluorine, and carbon atoms, with global warming potentials ranging from hundreds to thousands of times that of carbon dioxide depending on specific molecular formulation; they function primarily as working fluids in vapor-compression refrigeration and air conditioning cycles. HFC-32 and HFC-125 are gaining structural prominence as blend components in R-410A and R-454B formulations, displacing higher-GWP pure HFC-134a in new equipment specifications. The automotive end-user segment retains the deepest profit pools for legacy HFC-134a supply, though commercial refrigeration applications are shifting fastest toward lower-GWP alternatives under regulatory pressure.
The US Environmental Protection Agency enforces phasedown allocations under the American Innovation and Manufacturing Act, while the European Union F-Gas Regulation mandates stepped reductions in HFC import quotas and equipment bans. China's Ministry of Ecology and Environment implements dual carbon goals that tighten HFC production allowances ahead of Kigali Amendment baselines. Stakeholders must track how national phase-down schedules diverge in stringency and timeline, as these gaps will determine where stranded HFC assets concentrate and where transitional blend demand persists longest.
Market Dynamics
The Kigali Amendment's phase-down schedules are compressing manufacturing timelines and forcing refrigerant formulators to accelerate lower-GWP blend development ahead of equipment replacement cycles. This regulatory pressure is restructuring capital allocation across the hydro fluorocarbon value chain.
Growth Catalysts
- Automotive air conditioning demand:Passenger vehicle production in China and India continues to pull HFC-134a volumes upward as climate control penetration deepens in mid-tier vehicle segments.
- EU F-Gas Regulation quotas:Stepped reductions in HFC import allowances are creating transitional demand for reclaimed refrigerants and lower-GWP retrofit blends across commercial refrigeration.
- HFC-32 adoption:This lower-GWP pure compound is gaining specification share in residential heat pumps and ductless mini-splits as original equipment manufacturers redesign compressor architectures.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in China and Mexico, exposing HFC producers to export license volatility and input cost spikes.
- Technical blending limitations:HFC-32's mild flammability restricts its deployment in centralized commercial chillers and certain industrial process cooling applications.
- Regulatory timeline misalignment:Divergent phase-down schedules between the US EPA's AIM Act and China's MEE allowances are fragmenting inventory management across multinational supply chains.
Strategic Opportunities
- India's cooling action plan:Room air conditioner stock growth under the India Cooling Action Plan is opening demand for HFC-32 and R-454B before full HFC phase-down implementation.
- Refrigerant-as-a-service models:Equipment lease programs with embedded reclamation obligations are creating recurring revenue streams tied to regulatory compliance mandates.
- Natural refrigerant convergence:CO2 transcritical systems paired with HFC-32 auxiliary circuits in hybrid supermarket architectures are opening retrofit pathways for existing installed bases.
Industry Challenges
- Fluorochemistry talent scarcity:Formulation chemists with expertise in low-GWP blend thermodynamics and lubricant compatibility are concentrated among a shrinking pool of specialized practitioners.
- Certification timeline compression:ASHRAE safety classification and ISO 817 flammability testing for new A2L refrigerants are extending product development cycles beyond equipment manufacturer refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydro Fluorocarbon Market |
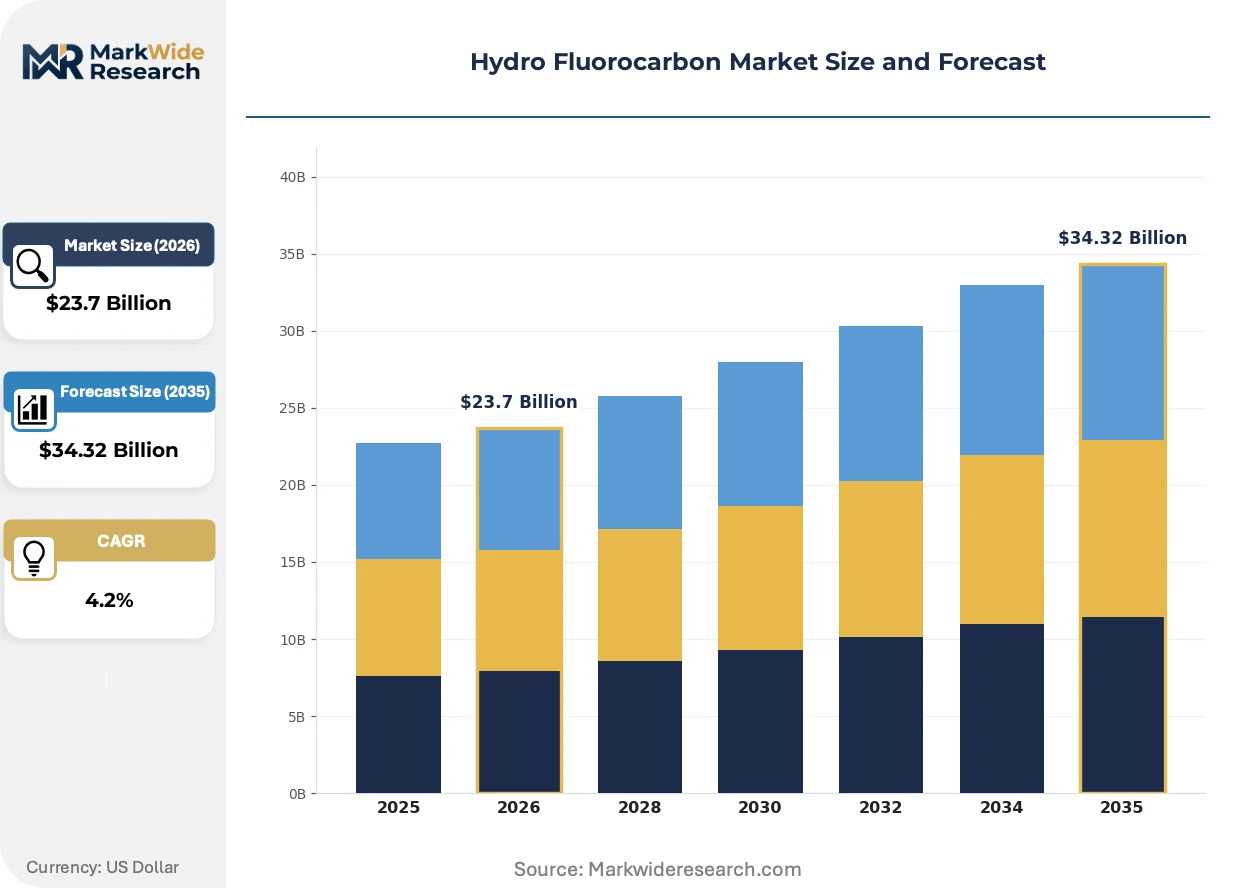
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $34.32 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HFC-134a, HFC-125, HFC-143a, HFC-32 Application: Refrigeration, Air Conditioning, Foam Blowing, Aerosol Propellant End User: Residential, Commercial, Industrial, Automotive Technology: Closed Loop, Open Loop, Hybrid, Natural Refrigerants |
| Companies Covered | Honeywell International Inc., Daikin Industries Ltd., The Chemours Company, Arkema S.A., Solvay S.A., Gujarat Fluorochemicals Limited, Linde plc, Sinochem Group, SRF Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydro Fluorocarbon Market Shifts & Advancements
Refrigerant chemistry is pivoting toward mildly flammable A2L classifications as equipment redesigns absorb safety system costs. Formulators, equipment makers, and service networks are simultaneously retooling around this thermodynamic inflection point.
HFO-1234yf is overtaking HFC-134a as the baseline automotive refrigerant. European and Japanese vehicle manufacturers specified this hydrofluoroolefin for new platforms beginning in the mid-2010s. US EPA SNAP program approvals accelerated North American adoption. The compound's 4 GWP versus HFC-134a's 1,430 GWP is compressing legacy refrigerant profit pools and forcing reclamation infrastructure investment.
China's Ministry of Ecology and Environment tightened production allowance baselines ahead of Kigali Amendment commitments. Domestic HFC manufacturers must now secure quota transfers or face forced capacity idling. Export-oriented formulators are redirecting volume toward lower-GWP blend components to preserve quota fungibility under the dual carbon goals framework.
Commercial HVAC operators are unbundling refrigerant supply from equipment procurement. Large facility managers in Germany and Japan now contract separately for virgin refrigerant, reclamation services, and leak detection monitoring. This purchasing pattern shift is compressing distributor margins while elevating stewardship-certified service providers to direct supplier status.
Hydro Fluorocarbon Market Segmentation
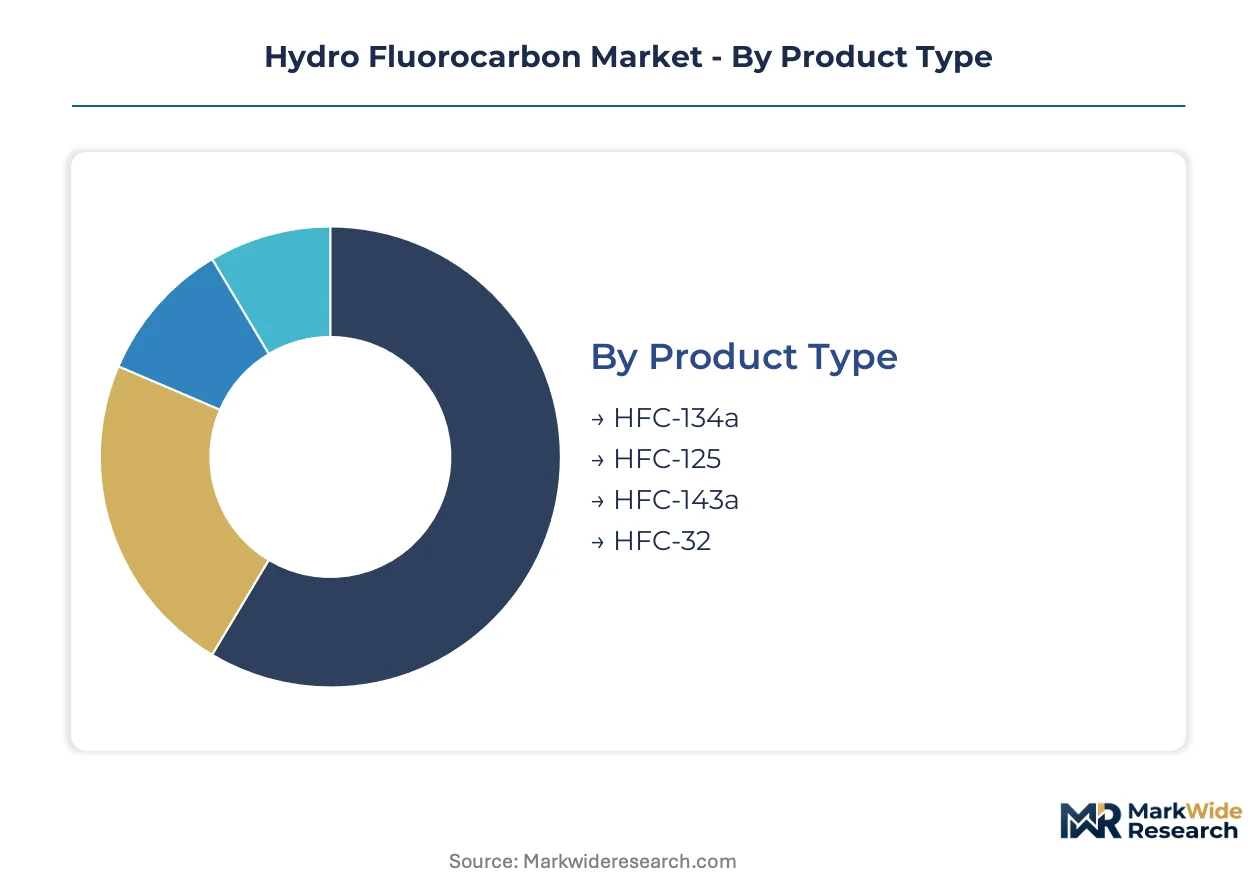
Segmentation reveals how regulatory phase-downs and equipment replacement cycles redistribute demand across molecular formulations and end-use applications. Manufacturers track these shifts to align production quotas with the fastest-converting customer segments.
Product Type:
Upgrade cycles in vapor-compression equipment are forcing rapid substitution between HFC chemistries as original equipment manufacturers redesign compressor architectures around thermodynamic and flammability constraints.
- HFC-134a:This pure compound maintains dominance in automotive air conditioning systems requiring non-flammable working fluids. Passenger vehicle production in China and India continues pulling volumes upward despite its 1,430 GWP drawing regulatory pressure under Kigali Amendment schedules.
- HFC-32:Lower GWP of 675 positions this molecule as the preferred replacement in residential heat pumps and ductless mini-splits. Japanese and South Korean equipment manufacturers have accelerated specification shifts toward this mildly flammable A2L refrigerant ahead of European F-Gas Regulation quota reductions.
- HFC-125:Blend component supplying fire suppression properties in R-410A and R-454B formulations.
- HFC-143a:Constituent in ternary blends serving commercial refrigeration retrofit markets.
Volume placements concentrate in HFC-134a; the faster expansion belongs to HFC-32.
Application:
Cost tier differentiation separates capital-intensive industrial process cooling from price-sensitive residential installations, with regulatory compliance mandates acting as the primary pricing determinant across tiers.
- Refrigeration:Commercial cold chain operators in Germany and Japan are unbundling refrigerant procurement from equipment leases. Supermarket retrofit demand for lower-GWP alternatives is climbing fastest under EU F-Gas Regulation stepped quota reductions.
- Air Conditioning:Room air conditioner stock growth under India's Cooling Action Plan is opening transitional demand for HFC-32 and R-454B before full phase-down implementation compresses pure HFC volumes.
- Foam Blowing:Insulation panel manufacturers in China face tightening MEE production allowances.
- Aerosol Propellant:Personal care and industrial spray applications requiring precise pressure characteristics.
Refrigeration commands the steepest compliance-driven pricing; air conditioning delivers the broadest volume base.
End User:
Customer type determines service model attachment, with commercial facility managers adopting refrigerant-as-a-service contracts while residential consumers remain transactional.
- Automotive:Vehicle manufacturers specified HFO-1234yf for European and Japanese platforms beginning in the mid-2010s, with US EPA SNAP approvals accelerating North American conversion. Legacy HFC-134a profit pools are compressing as reclamation infrastructure investments absorb stranded inventory risks.
- Commercial:Large facility managers now contract separately for virgin refrigerant, reclamation services, and leak detection monitoring. This purchasing pattern shift elevates stewardship-certified service providers to direct supplier status while compressing distributor margins.
- Residential:Heat pump adoption in cold-climate regions is expanding addressable equipment stock.
- Industrial:Process cooling applications with specialized thermodynamic requirements and extended replacement cycles.
Automotive leads technology transition speed; commercial drives service revenue attachment.
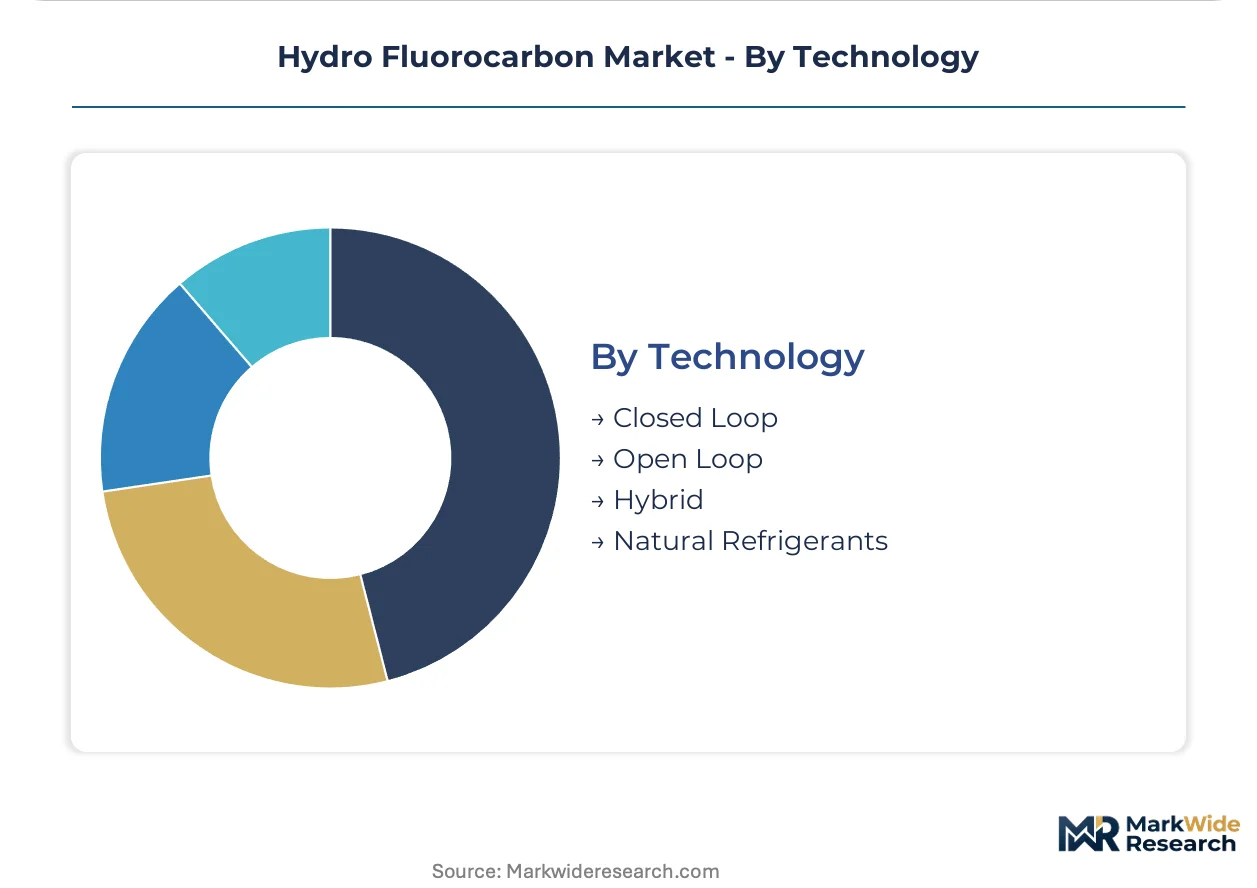
Technology:
Supply concentration in fluorspar mining shapes technology pathway economics, with acid-grade ore availability determining HFC versus natural refrigerant cost parity.
- Closed Loop:Sealed vapor-compression systems dominate residential and commercial installations. China's domestic HFC manufacturers must secure quota transfers or face forced capacity idling under tightened MEE baselines ahead of Kigali commitments.
- Hybrid:CO2 transcritical systems paired with HFC-32 auxiliary circuits are opening retrofit pathways for existing supermarket installed bases. German equipment makers pioneered these architectures to bridge regulatory compliance with capital cycle constraints.
- Open Loop:Direct expansion systems with higher leak rates facing stepped containment requirements.
- Natural Refrigerants:Ammonia and hydrocarbon alternatives displacing HFCs in industrial process cooling.
Closed Loop retains the largest installed base; Hybrid configurations are gaining specification share fastest in commercial retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates HFC production capacity while the United States and India absorb the largest consumption volumes. This geographic split creates quota arbitrage opportunities as national phase-down schedules diverge in stringency.
United States
Automotive air conditioning retrofit demand in the Southeast and Southwest drives HFC-134a consumption. The EPA enforces phasedown allocations under the AIM Act, tightening virgin refrigerant availability. Houston and the Gulf Coast concentrate reclamation infrastructure investment.
China
Domestic room air conditioner manufacturing pulls HFC-32 volumes upward. The Ministry of Ecology and Environment tightened production allowance baselines ahead of Kigali Amendment commitments. Zhejiang and Shandong provinces host the bulk of acid-grade fluorspar processing and HFC synthesis capacity.
Germany
Commercial refrigeration operators accelerate lower-GWP retrofits under stepped EU F-Gas Regulation quota reductions. The country's national implementation enforces equipment bans and leak detection mandates. The Rhine-Ruhr industrial corridor anchors CO2 transcritical system manufacturing.
India
Room air conditioner stock growth under the India Cooling Action Plan opens transitional HFC-32 demand. The Bureau of Energy Efficiency implements mandatory labeling and efficiency standards. Gujarat and Tamil Nadu concentrate compressor and heat pump assembly operations.
Japan
Residential heat pump adoption drives HFC-32 specification in ductless mini-splits. METI oversees refrigerant transition timelines aligned with Kigali commitments. The Chubu region around Nagoya hosts equipment manufacturers redesigning compressor architectures.
Hydro Fluorocarbon Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across the hydro fluorocarbon value chain. The market structure concentrates among integrated chemical conglomerates with captive fluorspar access and stewardship-certified reclamation networks. Three archetypes dominate: diversified industrials with refrigerant portfolios, specialized fluorochemical producers, and industrial gas distributors with blending capabilities. Capacity expansion and strategic quota transfers constitute the primary competitive moves as phase-down schedules compress manufacturing timelines.
Within the diversified industrial tier, Honeywell International Inc. and Daikin Industries Ltd. exemplify integrated players with captive reclamation infrastructure. The Chemours Company occupies a position among specialized fluorochemical producers with bundled credit offerings. These three entities anchor competitive positioning through distinct service model attachments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Daikin Industries Ltd. |
| The Chemours Company |
| Arkema S.A. |
| Solvay S.A. |
| Gujarat Fluorochemicals Limited |
| Linde plc |
| Sinochem Group |
| SRF Limited |
| Others |
Supply & Pricing Matrix
The transition from HFC-134a to HFC-32 and A2L blend formulations is simultaneously compressing manufacturing economics and redistributing supply power toward producers with captive fluorspar access and certified reclamation infrastructure. This molecular pivot forces capital retooling while China's Ministry of Ecology and Environment production allowances tighten feedstock availability for non-integrated players.
Pricing Analysis
Cost-down pressure on legacy HFC-134a accelerates because automotive OEMs are specifying HFO-1234yf for new platforms while reclamation infrastructure absorbs stranded inventory risks. Three-tier pricing structure across stewardship-certified premium, standard commercial, and economy spot tiers separates buyers by compliance documentation requirements and volume scale. Price differentiation hinges on quota fungibility under Kigali Amendment schedules and after-sales service bundling. Mid-tier commercial facility managers exhibit highest price sensitivity; automotive OEMs with long-term offtake agreements demonstrate lowest.
Supply Chain Analysis
China's domestic-content requirements for acid-grade fluorspar processing are reshaping sourcing patterns for multinational formulators. Geographic supply concentration centers on China, Mexico, and South Africa for acid-grade fluorspar ore; Germany and Japan for specialized compressor manufacturing. Raw material dependencies include acid-grade fluorspar, anhydrous hydrogen fluoride, and chlorinated intermediates. Single-source vulnerability from Chinese export license volatility poses structural risk. Distribution runs through stewardship-certified reclaimers and industrial gas distributors with blending capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
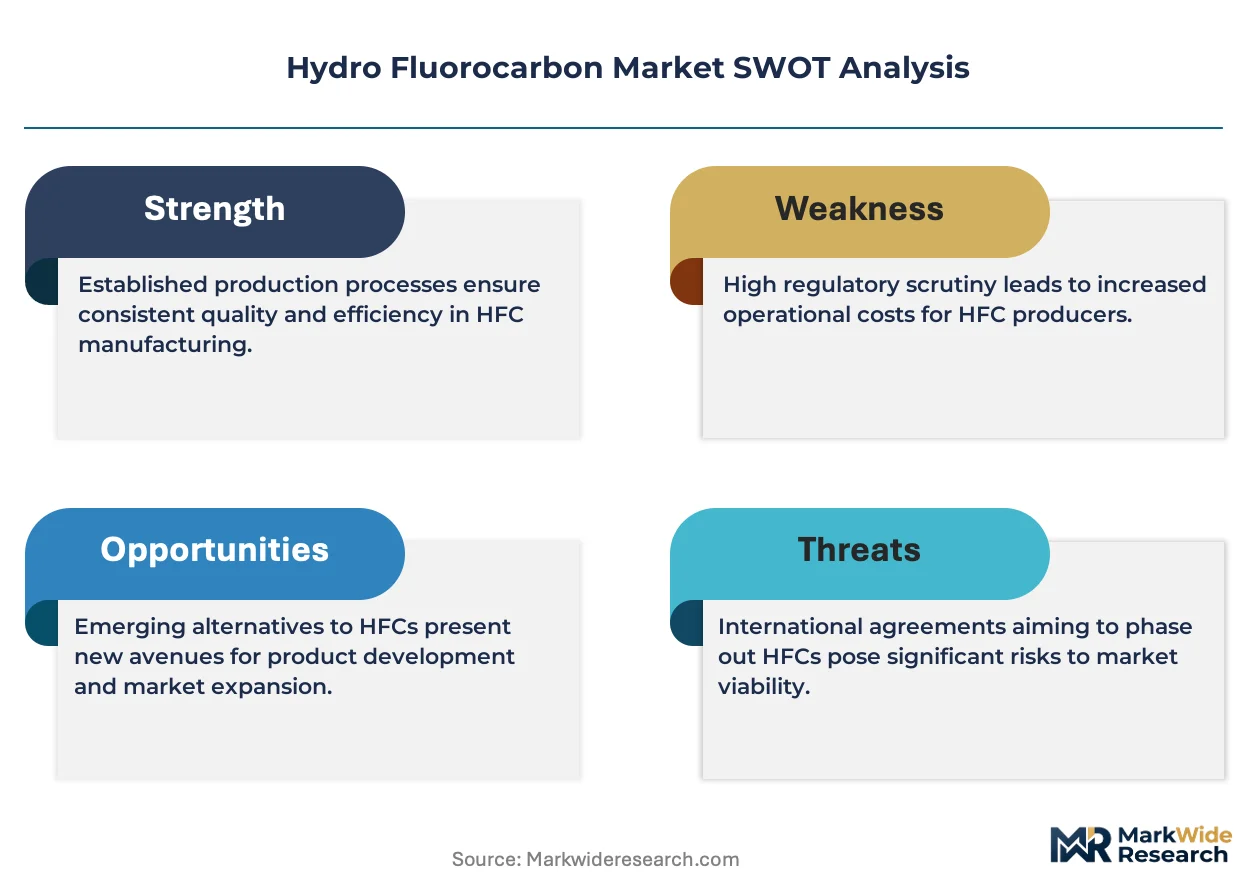
The hydro fluorocarbon market functions as a cost-of-compliance arena where the US EPA AIM Act phasedown allocations create a regulatory moat favoring incumbent producers with established quota positions and reclamation networks.
For Market Incumbents: To counter margin compression from HFC-134a demand destruction, accelerate backward integration into acid-grade fluorspar sourcing and secure quota transfers under China's MEE dual carbon framework. Prioritize certification investment for A2L refrigerant handling to capture commercial HVAC retrofit demand under EU F-Gas Regulation stepped reductions. For New Entrants and Emerging Players: Small-scale commercial refrigeration operators in India's Cooling Action Plan implementation zones represent an underserved buyer archetype with transitional demand for HFC-32 before full phase-down. Target facility managers seeking refrigerant-as-a-service contracts with embedded leak detection and reclamation obligations. Pursue equipment lease programs with captive collection infrastructure as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with specialized fluorochemical producers possessing stewardship-certified reclamation networks given accelerating regulatory mandates for circular refrigerant economies. Long-term viability favors assets with quota fungibility across US, EU, and Chinese regulatory frameworks. Monitor divergence between EPA AIM Act and MEE allowance timelines as the critical inflection signal for stranded asset risk concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar | Captive ore supply from Chinese or Mexican mining operations insulates against MEE export license volatility. |
| Stewardship Certification Investment | EPA and EU-recognized reclamation credentials unlock direct supplier status with commercial facility managers. |
| A2L Refrigerant Portfolio Expansion | HFC-32 and R-454B formulations align compressor redesign cycles with F-Gas Regulation quota reductions. |
| Refrigerant-as-a-Service Launch | Equipment lease programs with embedded reclamation obligations generate recurring revenue under compliance mandates. |
| Joint Venture in India | Cooling Action Plan room air conditioner growth opens transitional demand before full HFC phase-down implementation. |
Research Methodology
Trade databases, regulatory filing repositories, and chemical industry association reports formed the secondary backbone for this analysis. Primary interviews with plant managers at HFC synthesis facilities, procurement leads at automotive OEMs, distribution channel partners in commercial HVAC, and technical R&D directors at refrigerant formulators combined with secondary validation. Bottom-up volume modeling and top-down quota allocation analysis provided triangulation across data sources.
Historical trendline analysis of production allowance allocations, equipment shipment data, and refrigerant consumption patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular formulation grade, end-use application, equipment technology type, and regional regulatory cluster. CAGRs were derived from quota trajectory modeling and equipment replacement cycle timing. Industry-specific forecast inputs incorporated Kigali Amendment baseline calculations and F-Gas Regulation step-down schedules.
Revisions become necessary when regulatory timeline divergence between major economies accelerates, fluorspar export restrictions tighten beyond current baselines, or A2L refrigerant safety classification timelines compress equipment redesign schedules. Forecasts reflect documented assumptions regarding quota fungibility and reclamation infrastructure buildout rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Bleaching Clay Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Europe Bitumen Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Fluidized Bed Reactors Market