
 Screw Separators Market | 2026-2036
Screw Separators Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Separators Market Analytics
The widening performance gap between stainless-steel premium units and carbon-steel commodity models is repositioning procurement criteria across municipal and industrial buyers. Flottweg SE leverages its Bavarian manufacturing base to sustain high-margin custom engineering for European biogas operators. ANDRITZ AG anchors its position through captive foundry capacity that controls casting quality for large-diameter bowl separators. WAMGroup competes aggressively on standardized vertical units for agricultural slurry applications across Southern Europe.
Screw separators are continuous-solids-liquid separation devices employing Archimedean screw conveyors within cylindrical or conical housings, typically constructed from AISI 304/316 stainless steel or wear-resistant carbon steel with 0.5–3 mm screen slot openings and throughput capacities from 5 to 200 cubic meters per hour. These machines dewater organic sludges, recover oil from drilling muds, and clarify process streams by conveying solids against gravity while filtrate drains through perforated screens. Horizontal separators dominate installed base in European wastewater infrastructure where low-headroom retrofits predominate, while bowl separators command the fastest expansion in oilfield services due to superior handling of abrasive drilling fines. Mechanical technology leads unit shipments but hydraulic variants capture disproportionate margin pools in food processing where gentle product handling justifies premium pricing.
EU urban wastewater treatment directives enforced by national environmental agencies mandate tertiary solids reduction, directly stimulating replacement demand for higher-efficiency screw separator installations. EPA effluent limitation guidelines in the United States impose parallel nutrient-load constraints on municipal treatment works, while China's MEE enforces stricter discharge standards for industrial processors in the Yangtze River Economic Belt. Stakeholders must monitor evolving corrosion-resistance specifications and regional certification harmonization to avoid stranded capital in cross-border equipment procurement.
Market Dynamics
Tightening EU effluent standards are compressing replacement cycles for municipal wastewater infrastructure, forcing buyers to prioritize corrosion-resistant stainless-steel architectures over legacy carbon-steel units.
Growth Catalysts
- Urban Wastewater Treatment Directives:EU mandates for tertiary solids reduction are accelerating retrofit demand across German and French municipal plants.
- Biogas sector expansion:European anaerobic digestion facilities are specifying custom-engineered separators for digestate dewatering at scale.
- Yangtze River discharge enforcement:China's MEE standards are compelling industrial processors to upgrade hydraulic separator installations.
Market Restraints
- Nickel price volatility:AISI 316 stainless-steel input costs fluctuate with LME nickel futures, squeezing margin on premium units.
- Foundry capacity concentration:Large-diameter bowl casting expertise clusters in Central European supplier networks, creating supply bottlenecks.
- Centrifuge substitution:Decanter centrifuges retain cost advantages for high-throughput oilfield applications above 200 cubic meters per hour.
Strategic Opportunities
- Indian food processing corridors:Gentle-handling hydraulic variants face limited domestic competition in dairy and fruit-press applications.
- EU Green Deal biogas targets:National renewable energy incentives are expanding the addressable market for agricultural slurry separators.
- Predictive maintenance convergence:Vibration-sensor integration with cloud analytics enables service-contract revenue streams.
Industry Challenges
- Welding certification timelines:Pressure-vessel ASME and PED compliance documentation extends delivery schedules by 8-14 weeks.
- Legacy control system integration:Municipal SCADA architectures in older German plants require custom protocol adapters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Separators Market |
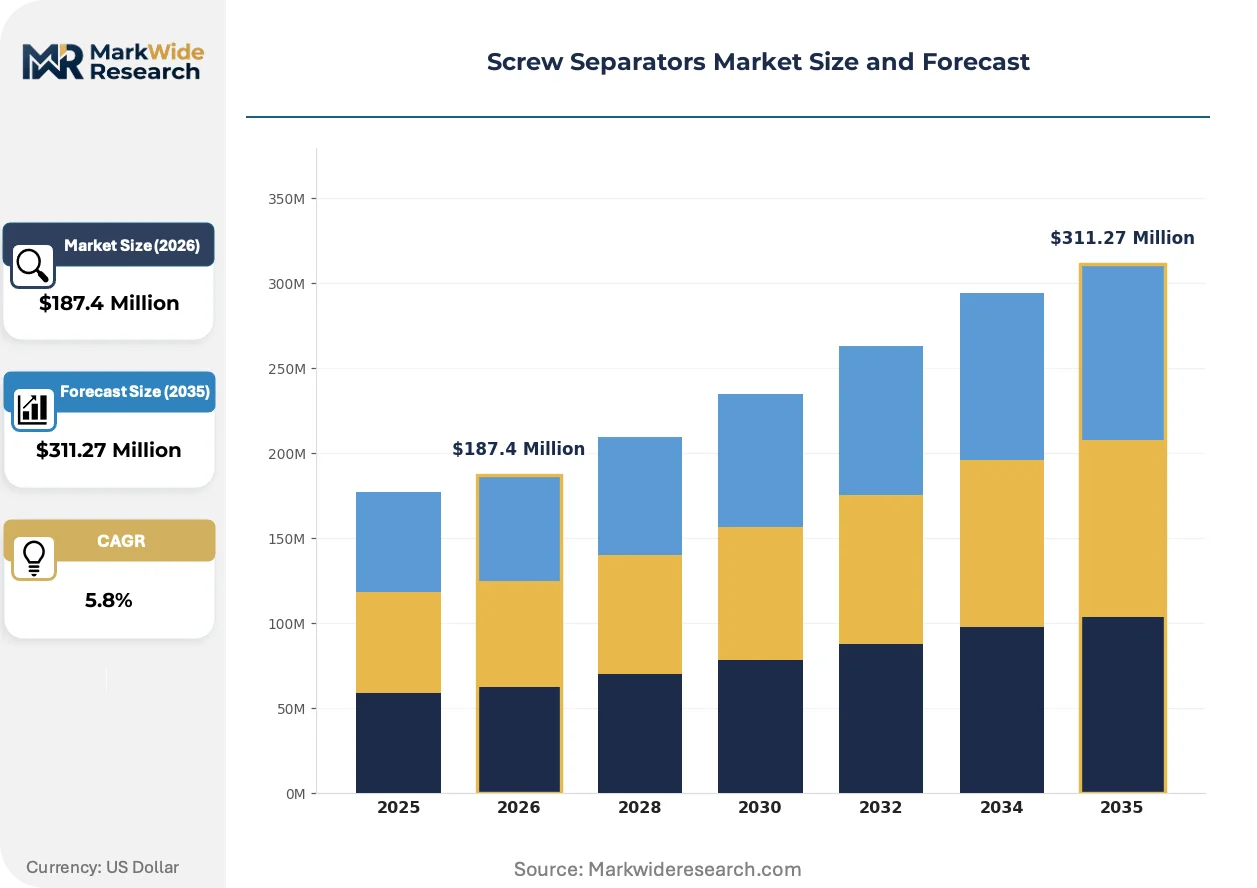
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Separator, Vertical Separator, Inclined Separator, Bowl Separator Application: Waste Management, Oil Recovery, Food Processing, Chemical Processing End User: Mining Industry, Oil & Gas, Agriculture, Manufacturing Technology: Mechanical, Thermal, Hydraulic, Pneumatic |
| Companies Covered | Flottweg SE, WAMGroup, ANDRITZ AG, GEA Group, CRI-MAN S.p.A., Huber SE, Vogelsang GmbH, Alfa Laval, FAN Separator, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Separators Market Evolving Landscape
Digital condition-monitoring and materials science advances are redefining equipment lifecycle economics, while regulatory enforcement patterns are compressing buyer decision horizons across municipal procurement.
Ceramic-lined screw conveyors are integrating tungsten carbide wear surfaces to extend service intervals in abrasive drilling-mud applications. Oilfield service contractors in the Permian Basin are specifying these retrofits to reduce unplanned downtime. The technology is integrating predictive replacement scheduling into asset-management platforms, compressing traditional maintenance outsourcing models.
REACH corrosion-resistance specifications are mandating hexavalent chromium elimination from surface treatments on equipment sold into EU wastewater markets. German environmental agencies are enforcing these material declarations through tender pre-qualification requirements. Stainless-steel passivation protocols are displacing legacy chromate conversion coatings across bowl separator production lines.
Performance-based service contracts are displacing traditional capital-purchase arrangements in French municipal water utilities. Maintenance cost certainty is replacing upfront equipment cost as the primary evaluation metric. This behavioral shift is most visible in Île-de-France regional procurement frameworks, where ten-year total-cost-of-ownership models dominate bid scoring.
Screw Separators Market Segmentation
Screw separator procurement decisions split sharply between retrofit compatibility in mature wastewater infrastructure and performance specifications for greenfield industrial installations. Buyers weigh corrosion resistance, throughput capacity, and integration complexity differently across municipal, agricultural, and extractive applications.
Product Type:
Retrofit constraints in aging European plants drive orientation preferences, while abrasive-handling requirements in oilfield services reshape bowl separator specifications.
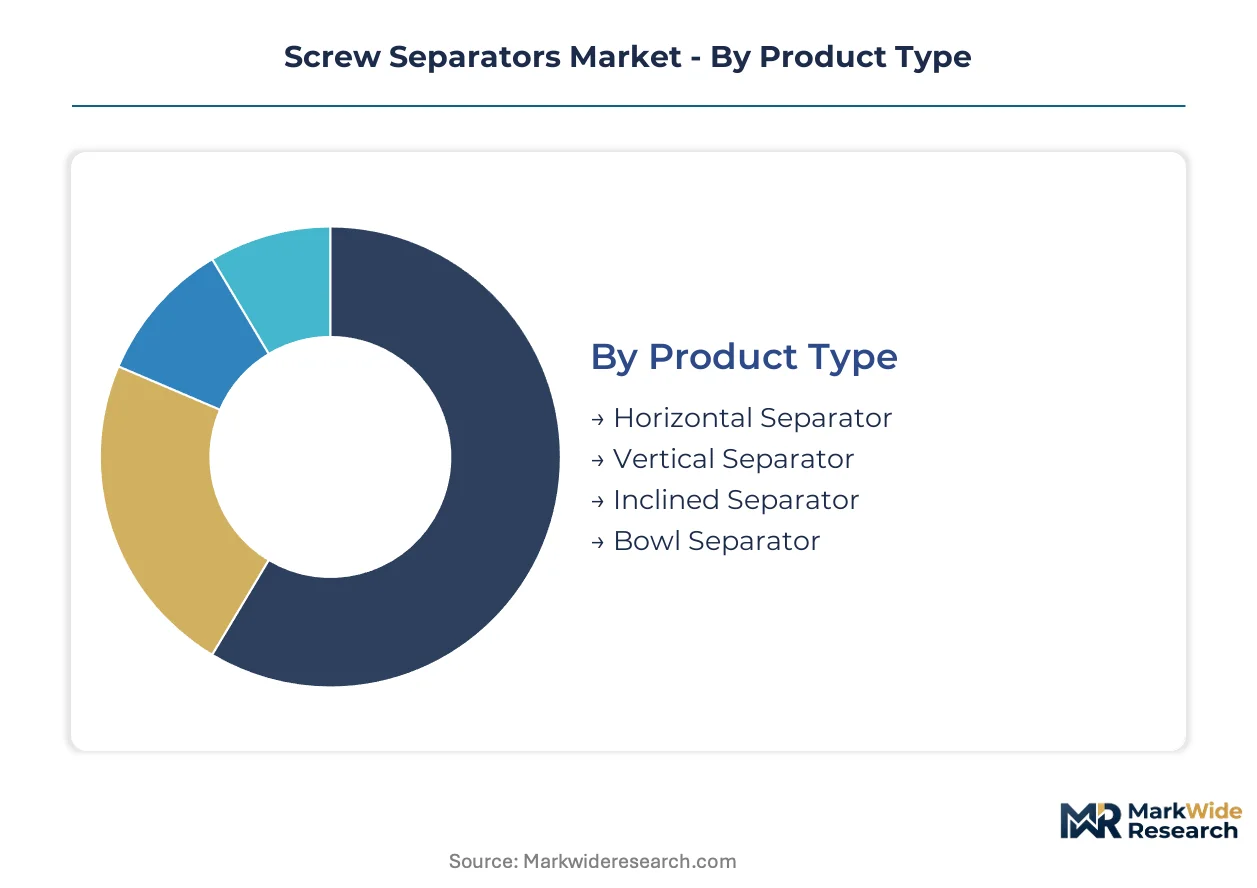
- Horizontal Separator:Low-headroom designs dominate German and French municipal retrofits where basement installations limit vertical clearance. Tightening EU tertiary solids mandates are accelerating replacement demand for stainless-steel horizontal units in legacy plants.
- Bowl Separator:Conical rotating bowls handle abrasive drilling fines at throughputs exceeding 200 cubic meters per hour in Permian Basin operations. Superior centrifugal force recovery justifies premium pricing against decanter centrifuge alternatives in oilfield services.
- Vertical Separator:Standardized footprint suits agricultural slurry applications across Southern European biogas facilities with limited floor space.
- Inclined Separator:Intermediate angle configurations serve niche food processing lines requiring gravity-assisted drainage without full vertical elevation.
Volume sits with horizontal configurations; growth tilts toward bowl separators.
Application:
Regulatory enforcement intensity varies by effluent stream, concentrating investment in sectors facing immediate discharge standard upgrades.
- Waste Management:Municipal wastewater plants in Germany specify AISI 316 stainless-steel architectures to meet REACH corrosion-resistance specifications without hexavalent chromium surface treatments. EPA effluent limitation guidelines in the United States impose parallel nutrient-load constraints on treatment works.
- Food Processing:Hydraulic separator variants capture premium margins in dairy and fruit-press operations where gentle product handling preserves yield quality. China's MEE discharge standards in the Yangtze River Economic Belt are compelling processor upgrades.
- Oil Recovery:Drilling mud clarification demands tungsten carbide wear surfaces in ceramic-lined screw conveyors for extended service intervals.
- Chemical Processing:Aggressive process streams require specialized alloy specifications beyond standard AISI grades.
Installed base concentrates in waste management; food processing offers the steepest expansion trajectory.
End User:
Capital intensity and operating environment severity differentiate procurement criteria across extractive and agricultural buyers.
- Oil & Gas:Oilfield service contractors specify bowl separators with predictive maintenance integration to minimize unplanned downtime in remote drilling operations.
- Agriculture:EU Green Deal biogas targets are expanding the addressable market for digestate dewatering equipment across anaerobic digestion facilities.
- Mining Industry:Abrasive slurry handling requires hardened wear components in tailings dewatering applications.
- Manufacturing:Process water recycling systems in industrial corridors drive standardized vertical unit demand.
Agriculture anchors current shipments; oil and gas commands the highest per-unit pricing.
Technology:
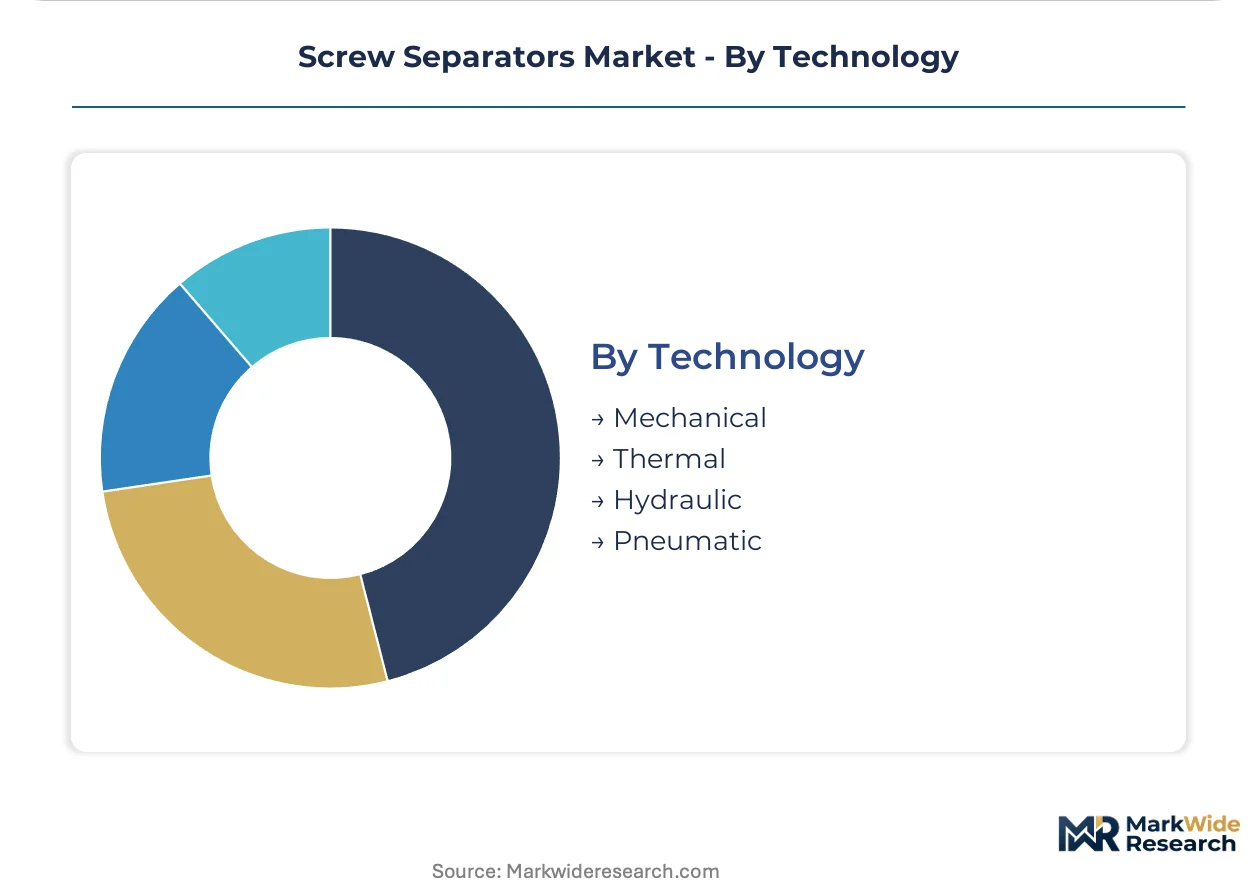
Energy intensity and product gentleness determine technology selection, with mechanical systems dominating volume and hydraulic systems capturing margin.
- Mechanical:Archimedean screw conveyors in cylindrical housings with 0.5–3 mm screen slot openings deliver the lowest capital cost per cubic meter of throughput. European wastewater infrastructure relies on mechanical systems for continuous solids-liquid separation.
- Hydraulic:Pressure-driven separation preserves cellular structure in dairy and fruit processing applications where shear sensitivity justifies premium energy consumption. Limited domestic competition in Indian food processing corridors creates expansion opportunities.
- Thermal:Evaporation-assisted dewatering serves specialized sludge reduction applications with high moisture content.
- Pneumatic:Air-driven systems occupy niche roles in explosive atmosphere environments requiring ignition-source elimination.
Mechanical technology dominates unit shipments; hydraulic variants are gaining share fastest in premium food applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor wastewater retrofits concentrate German procurement activity for horizontal separator replacements. Yangtze River Economic Belt discharge enforcement drives Chinese hydraulic unit upgrades. Permian Basin drilling operations anchor North American bowl separator demand.
Germany
Ruhr Valley municipal plants and Bavarian biogas facilities drive stainless-steel horizontal separator demand. EU urban wastewater treatment directives enforced by national environmental agencies mandate tertiary solids reduction. Flottweg SE's Bavarian manufacturing base supplies custom-engineered digestate dewatering units to anaerobic digestion operators.
China
Yangtze River Economic Belt industrial processors face MEE discharge standard upgrades for food and chemical operations. Stricter effluent enforcement compels hydraulic separator installations in dairy and fruit-press corridors. Shanghai and Jiangsu province manufacturing clusters concentrate domestic fabrication capacity for standardized vertical units.
United States
Permian Basin oilfield services demand bowl separators with tungsten carbide wear surfaces for abrasive drilling mud clarification. EPA effluent limitation guidelines impose nutrient-load constraints on municipal treatment works in Texas and California. Gulf Coast petrochemical processors specify corrosion-resistant architectures for aggressive process streams.
France
Île-de-France regional procurement frameworks prioritize ten-year total-cost-of-ownership models over upfront capital cost. EU Green Deal biogas targets expand agricultural slurry separator demand in Brittany and Normandy anaerobic digestion clusters. Performance-based service contracts displace traditional capital-purchase arrangements in Paris metropolitan water utilities.
India
Maharashtra and Gujarat food processing corridors present expansion opportunities for gentle-handling hydraulic variants with limited domestic competition. BIS certification requirements shape equipment import specifications for dairy and fruit-press applications. Pune and Ahmedabad industrial zones drive process water recycling system demand for manufacturing wastewater clarification.
Screw Separators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across corrosion-resistance specifications and custom engineering capabilities. The vendor base clusters around three strategic tiers: Bavarian custom-engineering specialists, Central European foundry-integrated manufacturers, and standardized agricultural equipment fabricators. Consolidation pressure intensifies as REACH compliance documentation and ASME welding certification timelines extend delivery schedules. Dominant competitive moves include captive foundry capacity expansion and predictive maintenance service contract bundling.
Among Central European manufacturers, ANDRITZ AG exemplifies foundry-integrated production control, while Flottweg SE occupies the custom-engineering tier for biogas applications. WAMGroup anchors the standardized equipment segment for agricultural slurry processing across Southern European markets. These three represent distinct competitive archetypes: upstream-integrated casting control, high-margin bespoke fabrication, and volume-driven standardized supply.
| Leading Market Players |
|---|
| Flottweg SE |
| WAMGroup |
| ANDRITZ AG |
| GEA Group |
| CRI-MAN S.p.A. |
| Huber SE |
| Vogelsang GmbH |
| Alfa Laval |
| FAN Separator |
| Others |
Value Network & Pricing Analysis
The performance gap between stainless-steel premium units and carbon-steel commodity models manifests in divergent pricing architectures and supply chain configurations across municipal and industrial buyer segments. Municipal procurement in Germany and France prioritizes corrosion-resistant architectures despite 40-60% unit cost premiums, while agricultural buyers in Southern Europe absorb standardized vertical units through distributor networks optimized for volume throughput.
Pricing Analysis
Value-based pricing anchors on throughput guarantees and maintenance cost certainty rather than capital expenditure alone. Three-tier pricing structure across premium, standard, and economy levels separates AISI 316 custom-engineered units from AISI 304 standardized models and carbon-steel commodity alternatives. Cost compression in carbon-steel tiers is intensifying because nickel price volatility squeezes stainless-steel margins and forces foundry-integrated manufacturers to absorb input cost swings. Municipal wastewater utilities exhibit lowest price sensitivity due to regulatory compliance mandates, while agricultural cooperatives in Southern Europe demonstrate highest elasticity to upfront capital outlays.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from oilfield service contractors, while distributor networks serve fragmented agricultural and municipal procurement. Supply concentrates in Germany, Austria, and Italy for large-diameter bowl casting and precision machining. Raw material dependencies include nickel-bearing stainless steel from European mills, tungsten carbide wear components from Central European suppliers, and specialized drive motors from German manufacturers. Single-source vulnerability in foundry capacity for bowl separators exceeding 500 millimeter diameter creates procurement bottlenecks. Distribution runs through manufacturer-direct relationships for custom-engineered units and regional equipment distributors for standardized agricultural applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints for large-diameter bowl castings prop pricing power among integrated manufacturers, creating supply-constrained conditions that favor incumbent margin defense over aggressive expansion.
For Market Incumbents: Lock in captive foundry capacity expansion in Bavaria and Upper Austria to defend against decanter centrifuge substitution in oilfield services above 200 cubic meters per hour. Prioritize ASME and PED welding certification investment to extend delivery schedule advantages over non-integrated competitors lacking pressure-vessel documentation capabilities. For New Entrants and Emerging Players: Enter via hydraulic separator specialization for Indian dairy and fruit-press corridors where limited domestic competition creates white-space opportunities. Target Maharashtra and Gujarat food processing clusters with gentle-handling variants. Pursue BIS certification partnerships with established European manufacturers to accelerate market access without full fabrication infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with foundry-integrated mid-cap specialists given REACH corrosion-resistance specification enforcement and hexavalent chromium elimination mandates. Long-term viability favors manufacturers controlling captive casting capacity and predictive maintenance service contract revenue streams. Monitor nickel LME futures volatility as inflection indicator for margin compression timing across stainless-steel premium tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Bavarian manufacturers secure bowl casting quality control for biogas digestate dewatering specifications. |
| Predictive Maintenance Service Contracts | Vibration-sensor integration with cloud analytics displaces traditional capital-purchase arrangements in French utilities. |
| Hydraulic Variant Localization | Indian food processing corridors present limited domestic competition for gentle-handling separator technology. |
| Ceramic-Lined Wear Surface Development | Tungsten carbide retrofits extend service intervals for Permian Basin drilling mud clarification applications. |
| REACH Compliance Documentation Investment | Hexavalent chromium elimination mandates reshape surface treatment protocols for EU wastewater market access. |
Research Methodology
Independent corroboration across equipment manufacturer sales data, municipal procurement databases, and foundry production records underwrites the qualitative findings in this study. Primary interviews with wastewater plant maintenance directors, OEM procurement teams at oilfield service contractors, agricultural biogas facility operators, and aftermarket service heads informed operational demand patterns. Secondary validation drew from EU urban wastewater treatment directive enforcement reports, EPA effluent limitation guideline updates, China MEE discharge standard publications, and customs trade data for separator equipment imports. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations across technology and application segments.
Comparable-period anchoring established baseline demand patterns from historical retrofit cycles and regulatory enforcement waves, then projected replacement intensity across the analysis window. Segmentation modeling incorporated product orientation, application sector, end-user industry, and technology type dimensions. CAGRs derived from regression analysis against industrial capital expenditure indices, wastewater infrastructure investment budgets, and oilfield service activity levels. Nickel price volatility coefficients and foundry capacity utilization rates served as industry-specific forecast sensitivity inputs.
Revisions become necessary when nickel LME futures exhibit sustained volatility above historical bands, when EU REACH specifications expand to additional surface treatment chemistries, or when China's MEE enforcement intensity shifts across provincial boundaries. Forecasts reflect documented assumptions regarding regulatory timeline adherence and industrial capital expenditure continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
India Acetic Acid Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Global Bio Based Isoprene Market