
 VOC Concentrator Market | 2026-2036
VOC Concentrator Market Size, Share, and Industry Trends Forecast 2026-2036
VOC Concentrator Market Analysis
EPA Maximum Achievable Control Technology standards for surface coating operations is recalibrating the cost-of-entry calculus for VOC abatement equipment across North American manufacturing. CECO Environmental leverages its integrated engineering-services model to anchor large-scale automotive installations. Munters competes through thermal technology specialization in European chemical processing corridors. Nichias Corporation dominates Asian supply channels with membrane-based concentrator systems tailored to semiconductor fabrication standards.
A VOC concentrator is an emission control device that captures volatile organic compounds from industrial exhaust streams through adsorption media—typically zeolite-impregnated honeycomb rotors—then desorbs and concentrates the captured VOCs into a smaller, treatable airstream for thermal oxidation or recovery. The unit operates at adsorption efficiencies exceeding 95% while reducing downstream destruction energy requirements by concentrating dilute inlet streams from 50-500 ppm to 5,000-50,000 ppm. Carbon adsorption product types occupy the largest installed base due to decades of proven performance in solvent recovery applications, though thermal concentrators represent the fastest-growing category as regenerative thermal oxidation technology achieves higher destruction efficiency thresholds at lower operating temperatures. Pharmaceutical applications command premium pricing due to batch-process variability and stringent purity requirements, while chemical manufacturing remains the volume anchor driven by continuous-process solvent loading.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants shapes product certification requirements and installation timelines across US manufacturing facilities. EU F-Gas Regulation and REACH compliance frameworks in Europe mandate material disclosure and phase-down schedules that influence adsorbent selection and rotor replacement protocols. China's MEE ambient air quality action plans impose regional emission caps that accelerate concentrator deployment in Yangtze River Delta chemical clusters. Stakeholders must monitor evolving thermal efficiency benchmarks and cross-border carbon border adjustment mechanisms to align capital deployment with regulatory trajectories.
Market Dynamics
Regenerative thermal oxidation retrofits are compressing payback periods for concentrator installations across solvent-intensive manufacturing, forcing equipment vendors to bundle thermal destruction units with adsorption systems rather than selling standalone concentrators.
Growth Catalysts
- EPA Maximum Achievable Control Technology:Surface coating operations in automotive paint shops face tightened emission ceilings, mandating 95%+ capture efficiency that only zeolite-impregnated rotor systems reliably deliver.
- Semiconductor fabrication:Membrane-based concentrator architectures tailored to cleanroom standards are penetrating wafer processing facilities as solvent loading variability increases batch-to-batch.
- Yangtze River Delta chemical clusters:China's MEE ambient air quality action plans impose regional emission caps that accelerate replacement of carbon adsorption systems with regenerative configurations.
Market Restraints
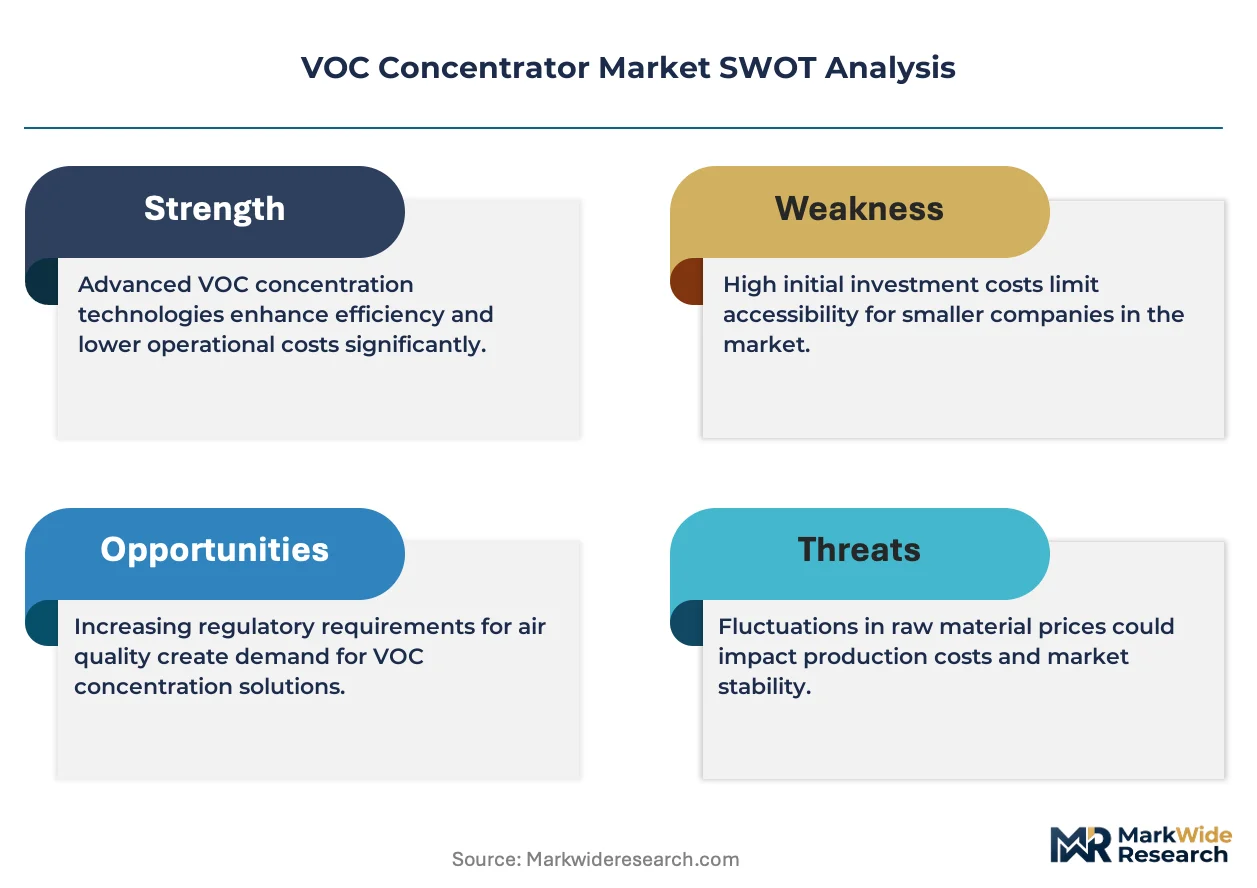
- Zeolite supply concentration:Synthetic zeolite production for honeycomb rotors concentrates among specialty chemical producers in Japan and Germany, exposing concentrator manufacturers to input cost volatility and allocation constraints.
- Carbon adsorption lock-in:Decades of installed base in solvent recovery applications create switching friction, as facilities amortize legacy activated carbon systems rather than adopting thermal concentrator architectures.
- EU F-Gas Regulation phase-down:Refrigerant-based cooling subsystems in concentrator desorption loops face material disclosure requirements and replacement protocols that extend procurement timelines.
Strategic Opportunities
- Pharmaceutical batch processing:Variable solvent loading and stringent purity requirements command premium pricing for concentrator-thermal oxidizer integrated systems that handle campaign-based production.
- India chemical corridor expansion:Gujarat and Maharashtra state pollution control mandates are creating first-mover advantage for vendors offering membrane-based systems with lower maintenance footprints than zeolite rotors.
- ISO 14001 certification convergence:Environmental management system audits are driving preference for concentrator technologies with verified destruction efficiency documentation, favoring vendors with third-party validated performance data.
Industry Challenges
- Rotor replacement skill scarcity:Zeolite-impregnated honeycomb rotor refurbishment requires specialized technicians trained in adsorbent handling and thermal cycling protocols, creating service bottlenecks in remote manufacturing locations.
- Legacy ductwork integration:Retrofitting concentrators into existing exhaust streams demands custom engineering to match pressure drops and flow profiles, extending installation timelines and requiring on-site fabrication capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VOC Concentrator Market |
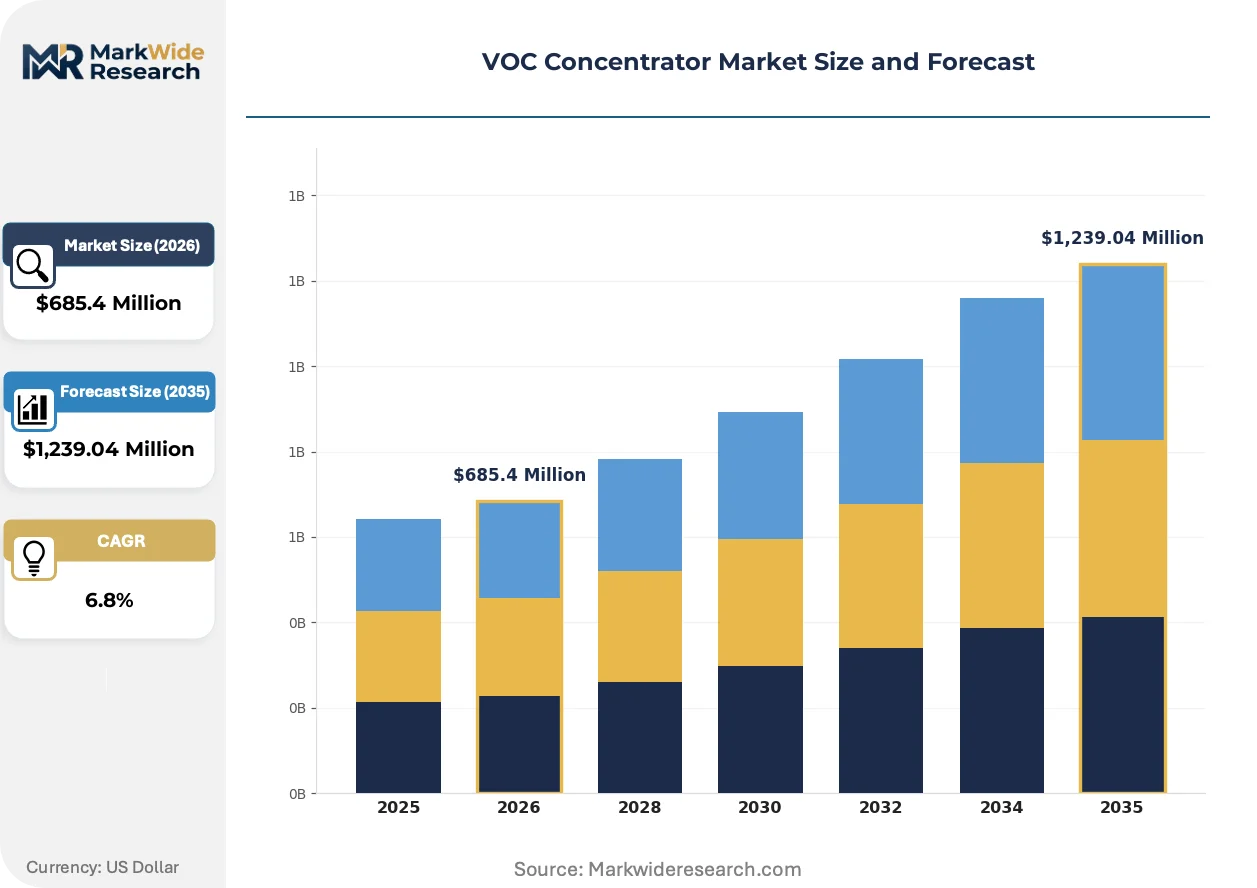
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Membrane, Carbon Adsorption, Biofiltration Application: Automotive, Pharmaceuticals, Chemical Manufacturing, Food Processing Technology: Regenerative Thermal Oxidation, Vapor Recovery, Cooling Condensation, Catalytic Oxidation End User: Industrial, Commercial, Residential, Research Facilities |
| Companies Covered | Seibu Giken Co. Ltd., Nichias Corporation, CECO Environmental, Anguil Environmental Systems, TKS Industrial Company, Munters, Dürr Aktiengesellschaft, Taikisha Ltd., Catalytic Products International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VOC Concentrator Market Emerging Trajectories
Modular concentrator architectures are fragmenting the traditional integrated-systems market, enabling point-source capture at individual process vessels rather than centralized exhaust treatment. This shift is compressing project scales and altering vendor competitive dynamics.
Membrane separation technology is decentralizing VOC capture from large centralized units to distributed point-source installations. Pharmaceutical manufacturers with multi-product facilities are adopting skid-mounted membrane concentrators at individual reactor vents. This architecture is enabling facility managers to isolate solvent-specific waste streams for recovery rather than commingled destruction.
China's MEE enforcement of ambient air quality action plans is mandating continuous emission monitoring systems on concentrator exhaust streams. Chemical plants in the Yangtze River Delta must install verified analyzers with data transmission to provincial environmental databases. Semiconductor fabrication facilities are responding by specifying concentrators with integrated monitoring subsystems to preempt regulatory inspection failures.
After-sales service unbundling is separating rotor replacement and thermal oxidizer maintenance from original equipment contracts. Automotive paint shops in Germany and the United States are negotiating standalone service agreements with third-party specialists rather than captive vendor relationships. This pattern is most visible in high-volume coating operations where downtime costs exceed premium service pricing.
VOC Concentrator Market Segmentation
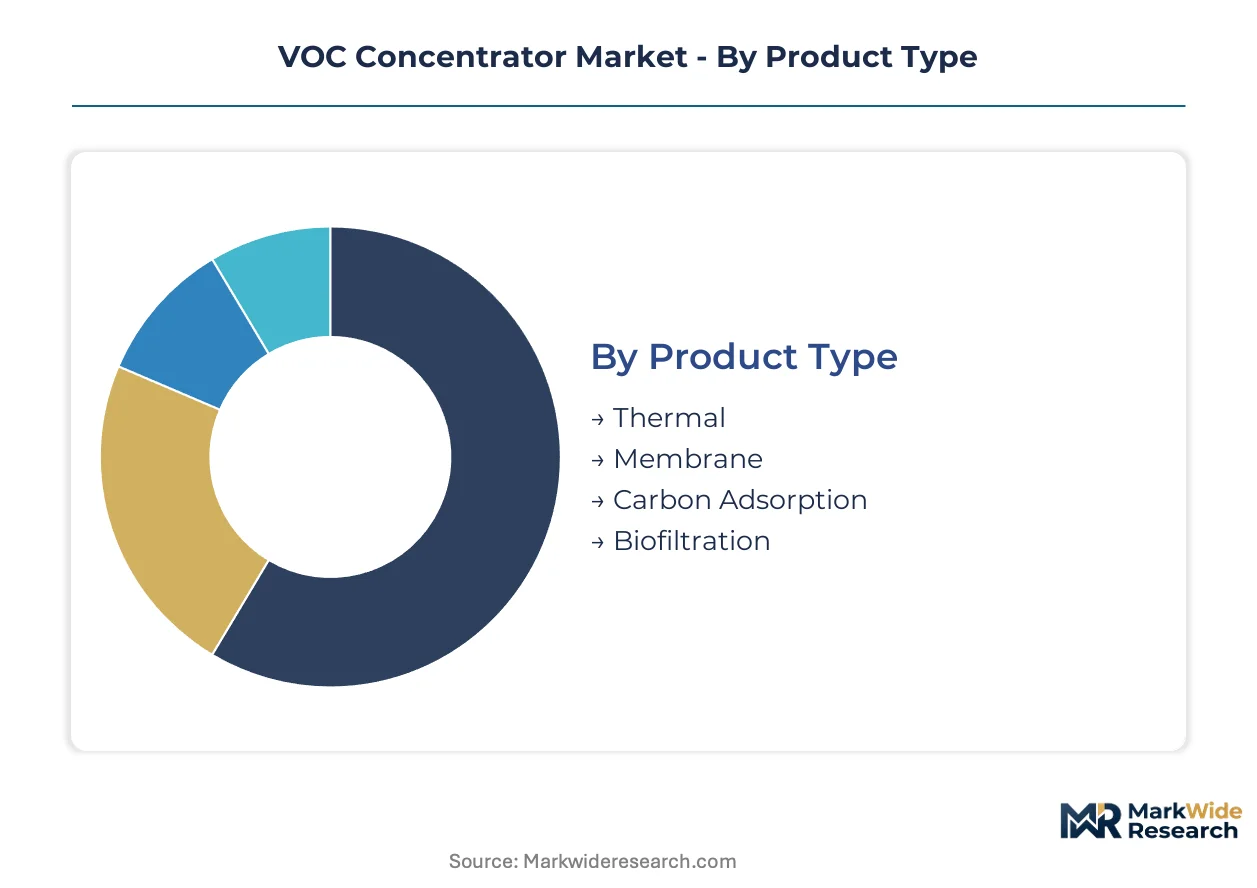
VOC concentrator procurement varies sharply across process intensity, emission variability, and regulatory exposure. Buyers in automotive paint shops prioritize thermal destruction efficiency, while pharmaceutical facilities demand membrane precision for batch-to-batch solvent fluctuations.
Product Type:
Cost tier separates buyers seeking capital efficiency from those prioritizing destruction certainty over decades-long amortization.
- Thermal:Zeolite-impregnated honeycomb rotors concentrate dilute inlet streams through thermal cycling, achieving 95%+ adsorption efficiency. German automotive paint shops facing EPA Maximum Achievable Control Technology mandates are retrofitting regenerative thermal oxidation bundles that compress payback periods below five years.
- Membrane:Polymeric separation layers tailored to semiconductor cleanroom standards isolate solvent-specific waste streams at individual reactor vents. Japanese wafer fabrication facilities under METI efficiency mandates specify skid-mounted architectures that enable point-source capture without centralized exhaust re-engineering.
- Carbon Adsorption:Decades of proven solvent recovery performance anchor the largest installed base despite higher energy intensity.
- Biofiltration:Microbial degradation pathways suit low-concentration, high-volume streams in food processing exhaust.
Carbon adsorption leads volumes today; thermal is gaining share fastest.
Application:
Volume concentration and margin profile diverge between continuous-process chemical corridors and campaign-based pharmaceutical operations.
- Chemical Manufacturing:Continuous solvent loading across Yangtze River Delta clusters drives demand for regenerative configurations with verified destruction efficiency documentation. China's MEE ambient air quality action plans impose regional emission caps that accelerate replacement of legacy carbon systems.
- Automotive:Surface coating operations in Germany and the United States face tightened EPA emission ceilings that mandate 95%+ capture efficiency only zeolite-impregnated rotor systems reliably deliver.
- Pharmaceuticals:Batch-process variability and stringent purity requirements command premium pricing for integrated concentrator-thermal oxidizer systems.
- Food Processing:Lower concentration thresholds and odor control priorities favor biofiltration or cooling condensation economics.
Chemical manufacturing anchors volume scale; pharmaceuticals commands the steepest pricing premiums.
Technology:
Maturity gradient separates proven thermal destruction from emerging recovery architectures that alter operating cost structures.
- Regenerative Thermal Oxidation:Ceramic heat recovery media achieve destruction efficiency thresholds above 99% at lower operating temperatures than recuperative designs. EU F-Gas Regulation phase-down schedules influence adsorbent selection and rotor replacement protocols across European chemical processing corridors.
- Vapor Recovery:Condensation and membrane hybrid systems enable solvent reclamation for resale rather than destruction, reshaping lifecycle economics for high-value organic compounds.
- Cooling Condensation:Refrigerant-based subsystems face material disclosure requirements that extend procurement timelines under REACH compliance frameworks.
- Catalytic Oxidation:Precious metal catalyst beds reduce operating temperatures for halogenated streams but impose higher capital intensity.
Regenerative thermal oxidation dominates installed capacity; vapor recovery is climbing the fastest.
End User:
Facility scale and regulatory scrutiny intensity create distinct procurement patterns across installation footprints.
- Industrial:Large-scale manufacturing plants in solvent-intensive sectors deploy centralized concentrator-oxidizer bundles with continuous emission monitoring systems. Germany's KBA enforcement and EPA National Emission Standards for Hazardous Air Pollutants shape certification requirements and installation timelines.
- Commercial:Printing, coating, and degreasing operations in mixed-use facilities favor modular point-source architectures that minimize ductwork re-engineering.
- Research Facilities:Laboratory fume hood exhaust with highly variable loading profiles drives demand for compact membrane units with rapid response characteristics.
- Residential:Negligible addressable market due to emission scale and regulatory exemption thresholds.
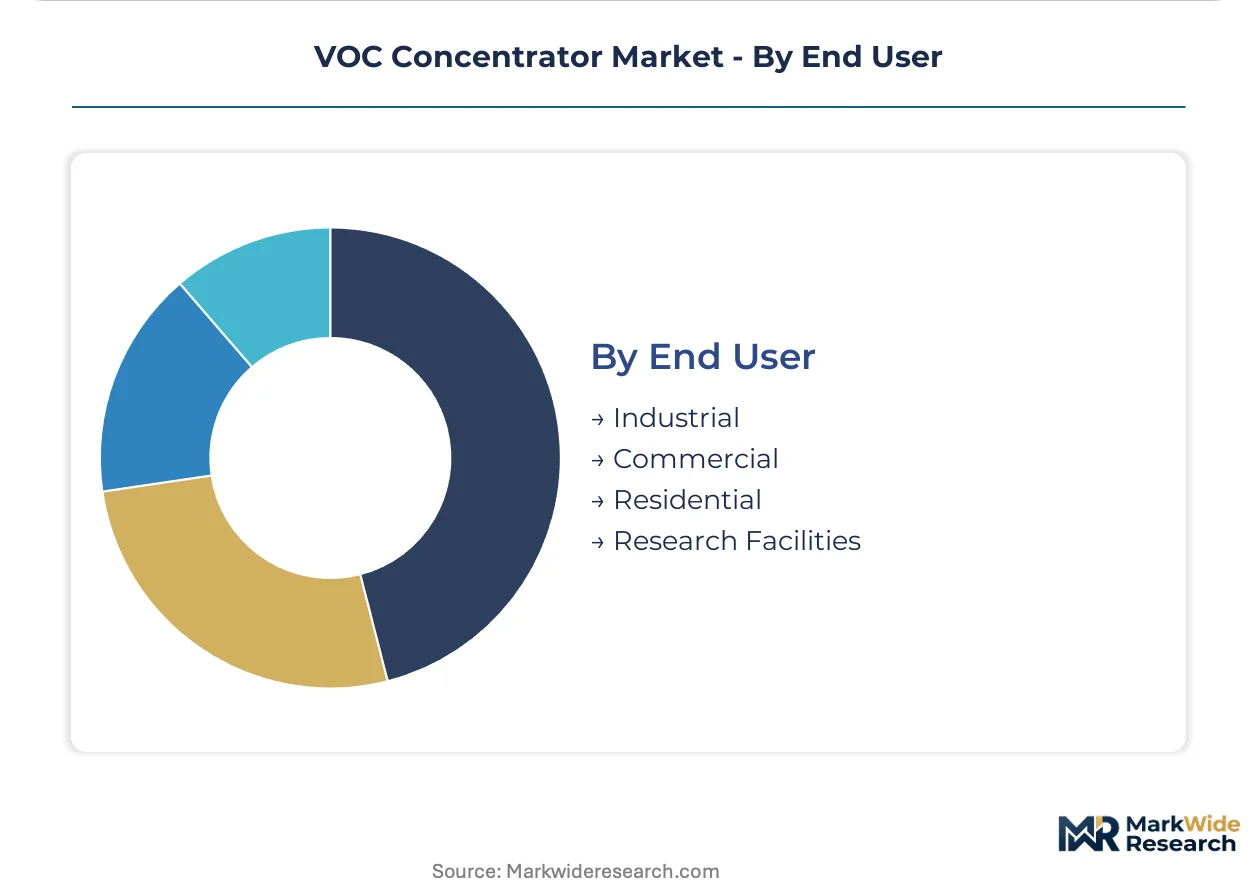
Industrial captures absolute volume; commercial installations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rotor fabrication technicians concentrate in Japan and Germany, creating regional service bottlenecks that shape deployment timelines across manufacturing corridors.
United States
Automotive paint shops in Michigan and Tennessee expand concentrator procurement as EPA Maximum Achievable Control Technology tightens emission ceilings for surface coating operations. The agency's National Emission Standards for Hazardous Air Pollutants reshape certification requirements and installation timelines. Chemical manufacturing clusters along the Gulf Coast retrofit carbon adsorption systems with regenerative thermal oxidation bundles.
Germany
KBA enforcement of EU F-Gas Regulation phase-down schedules extends procurement timelines for refrigerant-based cooling subsystems in concentrator desorption loops. The country's automotive OEMs in Bavaria and Baden-Württemberg negotiate standalone rotor replacement agreements with third-party specialists. REACH compliance frameworks mandate material disclosure that influences adsorbent selection protocols.
China
MEE ambient air quality action plans impose regional emission caps accelerating concentrator deployment across Yangtze River Delta chemical clusters. Synthetic zeolite supply concentration among Japanese and German specialty chemical producers exposes Chinese fabricators to input cost volatility. Semiconductor fabrication facilities in Shanghai specify integrated monitoring subsystems to preempt regulatory inspection failures.
Japan
METI efficiency mandates push chemical plants toward regenerative thermal oxidation retrofits with verified destruction efficiency documentation. Wafer fabrication facilities under cleanroom standards specify skid-mounted membrane architectures enabling point-source capture. Nichias Corporation anchors Asian supply channels with membrane-based systems tailored to semiconductor processing.
India
Gujarat and Maharashtra state pollution control mandates create first-mover advantage for vendors offering membrane-based systems with lower maintenance footprints. The country's pharmaceutical manufacturers with multi-product facilities adopt distributed point-source installations at individual reactor vents. Variable solvent loading in batch processing commands premium pricing for integrated concentrator-thermal oxidizer systems.
VOC Concentrator Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the VOC concentrator landscape. The market structure fragments across three tiers: integrated environmental engineering groups bundling thermal destruction with adsorption systems, thermal technology specialists concentrating on European chemical processing corridors, and membrane-based fabricators serving semiconductor cleanroom standards. Strategic moves center on geographic expansion into India's chemical corridor and technology licensing arrangements that compress payback periods below five years.
Within the integrated engineering tier, CECO Environmental and Dürr Aktiengesellschaft exemplify diversified conglomerates anchoring large-scale automotive installations through bundled service models. Seibu Giken Co. Ltd. occupies a position among specialized rotor fabricators where synthetic zeolite handling expertise creates service differentiation. Nichias Corporation represents the membrane-based specialist archetype, with geographic origin in Japan aligning with METI efficiency mandate enforcement and semiconductor fabrication demand concentration.
| Leading Market Players |
|---|
| Seibu Giken Co. Ltd. |
| Nichias Corporation |
| CECO Environmental |
| Anguil Environmental Systems |
| TKS Industrial Company |
| Munters |
| Dürr Aktiengesellschaft |
| Taikisha Ltd. |
| Catalytic Products International |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between EPA-certified thermal bundles and commodity carbon adsorption units manifests in both invoice structures and procurement routing. Premium configurations command bundled engineering-service contracts through CECO Environmental and Dürr Aktiengesellschaft, while standard-tier buyers source activated carbon systems through regional distributors with limited after-sales attachment.
Pricing Analysis
Bundled versus unbundled service splits now define contract economics across the VOC concentrator landscape. Project-based pricing dominates integrated thermal-oxidizer installations, with EPA Maximum Achievable Control Technology certification and verified destruction efficiency documentation driving premium tiers. Price differentiation stems from thermal efficiency benchmarks and rotor replacement service bundling. Cost compression in standard carbon adsorption tiers intensifies as facilities amortize legacy systems rather than upgrade. Automotive paint shops in Germany exhibit lowest price sensitivity due to downtime cost exposure, while commercial coating operations in mixed-use facilities prioritize capital efficiency.
Supply Chain Analysis
Freight cost escalation for honeycomb rotor imports from Japan and Germany is reshaping procurement timelines for concentrator fabricators in China and India. Synthetic zeolite production concentrates in Japanese and German specialty chemical corridors, with activated carbon feedstocks drawing from coconut shell processors in Southeast Asia and bituminous coal sources in North America. Single-source vulnerability in zeolite-impregnated rotor supply creates allocation risk during demand surges. Distribution runs through OEM-direct channels for large automotive installations and regional environmental equipment distributors for commercial retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge where EPA enforcement timelines in the United States lag EU F-Gas Regulation phase-down schedules by eighteen to twenty-four months, allowing vendors to redirect inventory and engineering capacity across Atlantic corridors.
For Market Incumbents: Deepen captive supply arrangements for synthetic zeolite feedstocks to offset Japanese and German producer allocation constraints. Secure rotor refurbishment technician certification programs in Yangtze River Delta and Gujarat manufacturing corridors before skill scarcity hardens into service bottlenecks. Vertical integration into thermal oxidizer fabrication compresses competitor access to bundled project economics. For New Entrants and Emerging Players: China's MEE ambient air quality action plans in the Yangtze River Delta open a window for membrane-based concentrator architectures with lower maintenance footprints than zeolite rotors. Target pharmaceutical batch processing facilities in India with skid-mounted point-source systems that isolate solvent-specific waste streams. Pursue technology licensing arrangements with established semiconductor fabrication equipment vendors to bypass direct sales channel development. For Investors and Strategic Acquirers: Consolidation pressure builds where synthetic zeolite handling expertise concentrates among fewer than five specialized rotor fabricators with demonstrated cleanroom certification. Long-term viability favors vendors with integrated monitoring subsystem capabilities aligned with continuous emission monitoring mandates. Acquisition target archetype: regional service specialists with EPA or EU F-Gas Regulation certification credentials and established relationships in automotive or chemical manufacturing corridors. Monitor EPA National Emission Standards for Hazardous Air Pollutants enforcement variance across US states as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Supply | Captive synthetic zeolite production insulates margin pressure from Japanese and German allocation constraints. |
| Membrane Technology Licensing | Cleanroom-validated polymeric separation layers accelerate penetration of semiconductor fabrication facilities under METI mandates. |
| Service Agreement Unbundling | Standalone rotor replacement contracts capture aftermarket value from automotive paint shops prioritizing uptime over captive vendor relationships. |
| Point-Source Architecture Development | Skid-mounted distributed systems reduce ductwork re-engineering costs for pharmaceutical multi-product facilities. |
| Continuous Emission Monitoring Integration | Pre-installed analyzer subsystems preempt MEE inspection failures in Yangtze River Delta chemical clusters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for VOC concentrator procurement. Primary fieldwork engaged plant engineers at solvent-intensive manufacturing facilities, procurement leads at automotive OEMs, aftermarket service heads at regional distributors, and environmental compliance officers at chemical processing plants. Secondary validation drew from EPA enforcement databases, EU ECHA substance registration filings, Chinese MEE regional emission cap disclosures, and SEC 10-K equipment revenue segmentations. Bottom-up installation tracking across automotive paint shops and chemical manufacturing corridors triangulated against top-down market sizing from trade flow analysis.
Segment-weighting approaches distributed total addressable value across thermal, membrane, carbon adsorption, and biofiltration product architectures, then further subdivided by chemical manufacturing, automotive, pharmaceutical, and food processing applications. Technology dimensions modeled regenerative thermal oxidation, vapor recovery, cooling condensation, and catalytic oxidation pathways against end-user scale tiers from industrial centralized systems to commercial point-source installations. CAGRs were derived from regression analysis of historical procurement patterns against regulatory enforcement intensity indices. Industry-specific forecast inputs included EPA Maximum Achievable Control Technology compliance timelines and EU F-Gas Regulation phase-down schedules.
Revisions become necessary when EPA enforcement variance across US states accelerates or delays projected installation timelines, or when synthetic zeolite supply allocation from Japanese and German producers tightens beyond historical patterns. Forecasts reflect assumptions about continuous emission monitoring mandate expansion and thermal oxidizer retrofit bundling trends. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Hydro Fluorocarbon Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Mining Explosives Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
Fireworks and Firecrackers Market