
 Vitamin C Ingredients Market | 2026-2036
Vitamin C Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin C Ingredients Market Outlook
Pharmaceutical buyers is reorganizing the Vitamin C Ingredients landscape as nutraceutical manufacturers shift from commodity ascorbic acid toward certified pharmaceutical-grade inputs. DSM-Firmenich AG leverages its integrated fermentation and premix capabilities to sustain premium positioning across European and North American nutraceutical channels. Northeast Pharmaceutical Group Co., Ltd. anchors global bulk supply through its captive citric acid and sorbitol feedstock operations in Liaoning province. BASF SE differentiates via synthetic vitamin C derivatives for cosmetics applications, occupying a specialized tier above commodity ascorbic acid.
Vitamin C Ingredients comprise chemically synthesized or fermentation-derived ascorbic acid compounds and their salts, typically specified at 99% minimum purity for pharmaceutical use and produced via the Reichstein-Grüssner process or two-step bacterial fermentation from D-sorbitol. The primary commercial purpose centers on antioxidant stabilization, collagen synthesis support, and micronutrient fortification across ingestible and topical products. Ascorbic acid dominates volume flows as the foundational feedstock for derivative manufacturing, while calcium ascorbate captures expanding share in buffered dietary supplement formulations targeting gastric-sensitive consumers. Sodium ascorbate leads liquid applications including injectable pharmaceuticals and fortified beverages where solubility parameters determine specification compliance.
The US FDA enforces Current Good Manufacturing Practice regulations for dietary supplement ingredients under 21 CFR Part 111, mandating identity testing and contaminant screening that elevates compliance costs for non-integrated suppliers. China's NMPA aligns pharmaceutical-grade ascorbic acid with GB standards through SAMR oversight, while REACH registration requirements in Europe constrain market access for unregistered Asian exporters. EFSA's ongoing re-evaluation of ascorbic acid safety thresholds for fortified foods will reshape maximum permitted levels across member states. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade specifications as buyer audits intensify upstream traceability demands.
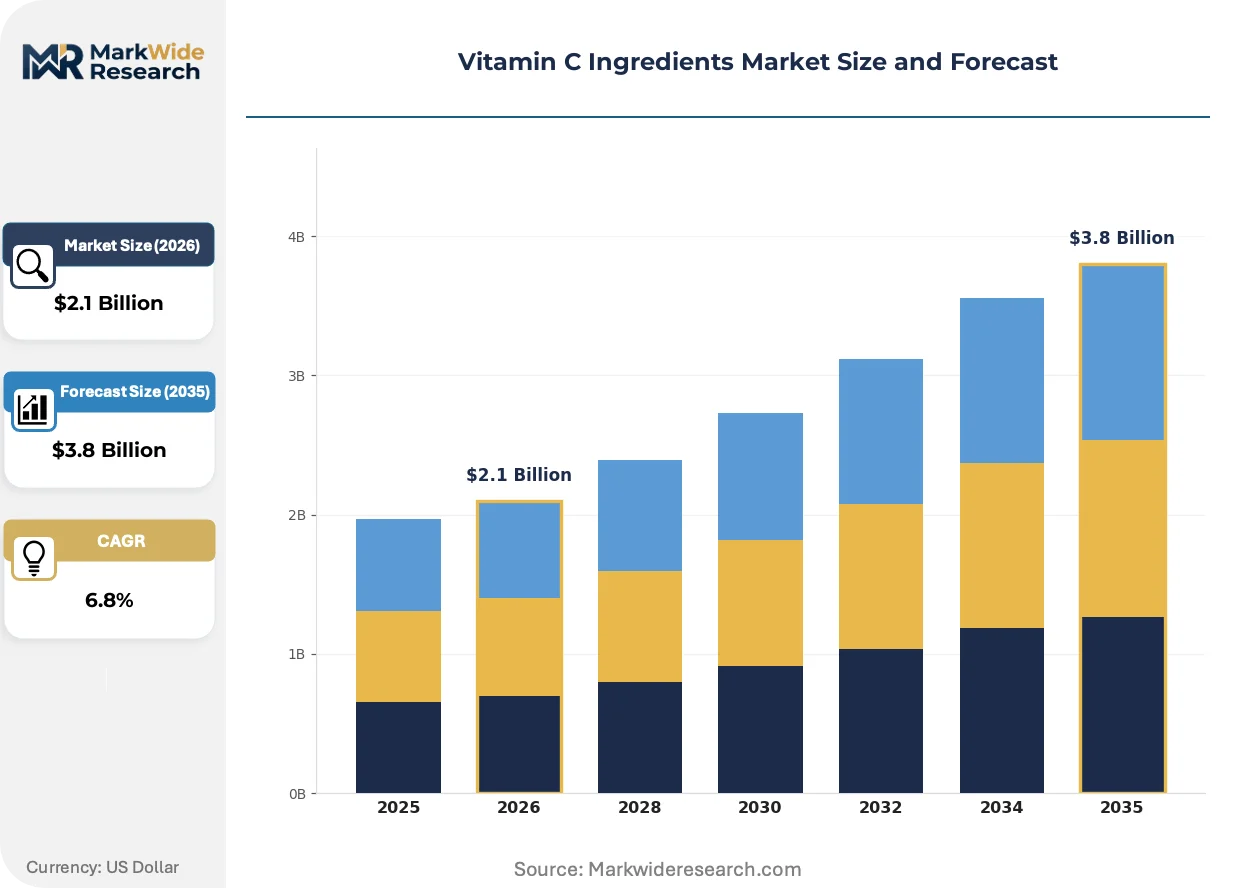
Market Dynamics
Pharmaceutical-grade purity mandates from the US FDA and China's NMPA are compressing supplier margins while accelerating consolidation among fermentation-based producers in Jiangsu and Shandong provinces.
Growth Catalysts
- Injectable pharmaceutical demand:Sodium ascorbate specifications for parenteral nutrition are tightening procurement standards across hospital supply chains.
- REACH registration compliance:European chemical safety protocols are filtering out unregistered Asian exporters, concentrating volume among pre-qualified suppliers.
- Fermentation process optimization:Two-step bacterial conversion from D-sorbitol is yielding higher yields per feedstock unit in Liaoning province operations.
Market Restraints
- Citric acid feedstock volatility:Captive sorbitol supply chains face input cost pressure from corn starch price fluctuations.
- Jiangsu-Shandong production concentration:Geographic clustering of fermentation capacity creates single-region exposure for global supply continuity.
- Synthetic derivative substitution:Ascorbyl palmitate and other lipophilic variants are capturing cosmetic formulation share from standard ascorbic acid.
Strategic Opportunities
- Buffered calcium ascorbate expansion:Gastric-sensitive consumer segments in Germany and France are driving premium formulation demand.
- EFSA safety threshold re-evaluation:Fortified food maximum permitted level adjustments will open new beverage fortification windows.
- Direct-to-manufacturer digital procurement:Nutraceutical formulators are bypassing traditional distributors for certified pharmaceutical-grade supply.
Industry Challenges
- Pharmacopeial-grade certification timelines:USP and EP compliance documentation extends supplier onboarding cycles by 12-18 months.
- Upstream traceability system integration:Batch-level D-sorbitol origin tracking requires legacy ERP upgrades at mid-scale fermentation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin C Ingredients Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ascorbic Acid, Sodium Ascorbate, Calcium Ascorbate, Ascorbyl Palmitate Form: Powder, Liquid, Granule, Tablet End User: Cosmetics, Food & Beverages, Pharmaceuticals, Dietary Supplements Application: Antioxidant, Preservative, Nutritional Supplement, Skin Care |
| Companies Covered | Northeast Pharmaceutical Group Co., Ltd., Hubei Grand Pharmaceutical Co., Ltd., DSM-Firmenich AG, Huanggang Huachang Pharmaceutical Co., Ltd., Shandong Luyin Pharmaceutical Co., Ltd., BASF SE, Hefei TNJ Chemical Industry Co., Ltd., Kemin Industries, Inc., Zhejiang Medicine Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin C Ingredients Market Strategic Shifts
Continuous fermentation monitoring systems and enzymatic conversion efficiency improvements are compressing production economics while regulatory divergence between pharmacopeial and food-grade specifications is fragmenting supplier qualification pathways.
Single-use bioreactor technology is displacing stainless steel vessel infrastructure among mid-scale ascorbic acid producers. Contract manufacturers serving North American nutraceutical brands are adopting disposable fermentation systems to reduce cross-contamination risk during product changeovers. This shift is compressing capital deployment timelines from 24 months to under 8 months for capacity expansion projects.
China's SAMR enforcement of revised GB standards for pharmaceutical-grade ascorbic acid is elevating purity testing protocols beyond historical food-grade benchmarks. Domestic producers in Liaoning province are retrofitting quality control laboratories to meet dual USP-ChP certification requirements. European importers are demanding third-party audit documentation that exceeds baseline REACH registration obligations.
Hospital procurement consortiums are consolidating sodium ascorbate purchasing through centralized tender mechanisms. Group purchasing organizations in the United States are replacing fragmented distributor relationships with direct manufacturer contracts tied to multi-year volume commitments. This concentration is visible most acutely in parenteral nutrition supply chains where specification compliance carries patient safety liability.
Vitamin C Ingredients Market Segmentation
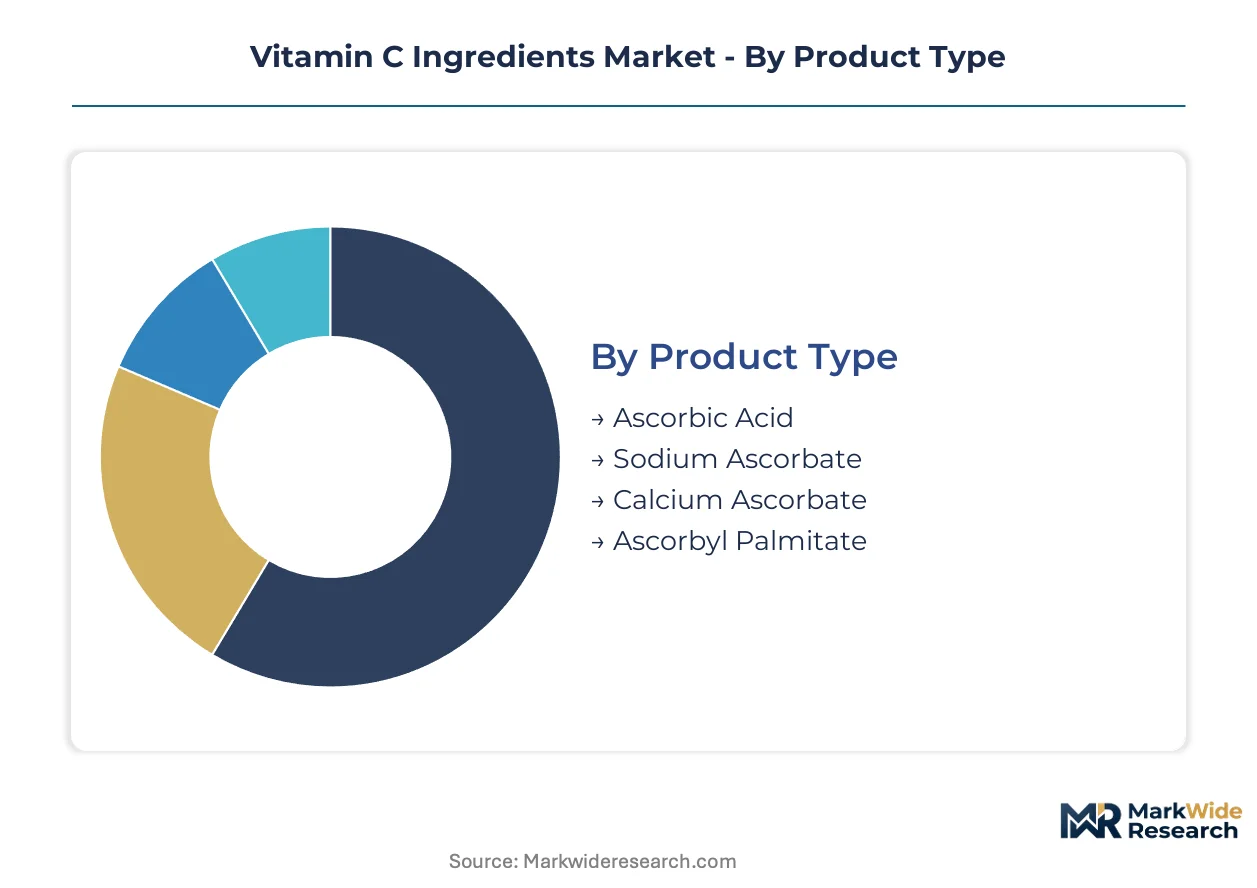
Vitamin C Ingredients stratify across purity grades, chemical forms, and end-use specifications that determine procurement economics. Pharmaceutical-grade certification commands premium positioning while food-grade and cosmetic-grade tiers operate on volume-based margin structures. Understanding segment boundaries clarifies where supplier qualification investments yield sustainable returns.
Product Type:
Margin pools concentrate in buffered salt derivatives where gastric-tolerance premiums offset higher processing costs, while commodity ascorbic acid competes on fermentation yield efficiency.
- Ascorbic Acid:The foundational feedstock for all derivative manufacturing, typically specified at 99% minimum purity for pharmaceutical applications. Demand concentrates in Jiangsu and Shandong province fermentation clusters where captive D-sorbitol supply chains constrain cost volatility for integrated producers.
- Sodium Ascorbate:Highly soluble salt form dominating liquid applications including parenteral nutrition formulations and fortified beverages. Hospital procurement consortiums in the United States are consolidating purchasing through centralized tenders tied to multi-year volume commitments.
- Calcium Ascorbate:Buffered formulation capturing premium positioning in gastric-sensitive dietary supplement segments across Germany and France.
- Ascorbyl Palmitate:Lipophilic derivative displacing standard ascorbic acid in cosmetic antioxidant applications where oil-phase compatibility determines formulation compliance.
Ascorbic acid holds installed capacity across Liaoning province operations. Sodium ascorbate is rotating up the share rankings through injectable pharmaceutical demand concentration.
Form:
Processing economics favor powder and granule formats where bulk handling infrastructure amortizes across high-volume nutraceutical production lines.
- Powder:Dominant format for ingredient premix manufacturing and direct compression tablet production. DSM-Firmenich AG leverages integrated fermentation and powder blending capabilities to sustain premium positioning across European nutraceutical channels.
- Liquid:Specialized format for beverage fortification and parenteral pharmaceutical applications where solubility parameters dictate specification compliance. Sodium ascorbate liquid specifications are tightening procurement standards across United States hospital supply chains.
- Granule:Intermediate format optimizing flow properties for high-speed capsule filling operations. Northeast Pharmaceutical Group Co., Ltd. anchors granule supply through captive citric acid and sorbitol feedstock operations.
- Tablet:Finished dosage form bypassing raw ingredient procurement for direct-to-consumer supplement brands. Contract manufacturers serving North American nutraceutical brands are adopting single-use bioreactor technology to reduce cross-contamination risk during product changeovers.
Powder maintains the broadest installed base across fermentation facilities. Liquid is climbing the fastest through beverage fortification and injectable pharmaceutical demand expansion.
End User:
Pharmaceutical and dietary supplement channels absorb the highest purity grades while cosmetics and food applications tolerate broader specification ranges.
- Pharmaceuticals:Stringent USP and EP compliance requirements governing parenteral nutrition, injectable antibiotics, and prescription formulations. China's NMPA and the US FDA have tightened purity benchmarks for pharmaceutical-grade ascorbic acid raw materials.
- Dietary Supplements:High-volume channel for tablet, capsule, and powder formulations targeting immune support and collagen synthesis positioning. Direct-to-manufacturer digital procurement is displacing traditional distributor relationships for certified pharmaceutical-grade supply.
- Cosmetics:Antioxidant and skin-brightening applications where ascorbyl palmitate and stabilized ascorbic acid derivatives command formulation premiums. BASF SE differentiates via synthetic vitamin C derivatives occupying a specialized tier above commodity ascorbic acid.
- Food & Beverages:Fortification applications in juices, dairy, and baked goods where EFSA safety threshold re-evaluations will reshape maximum permitted levels across European member states.
Pharmaceuticals retains the most rigorous qualification barriers. Dietary supplements is expanding most quickly through direct procurement channel development and gastric-sensitive formulation premiums.
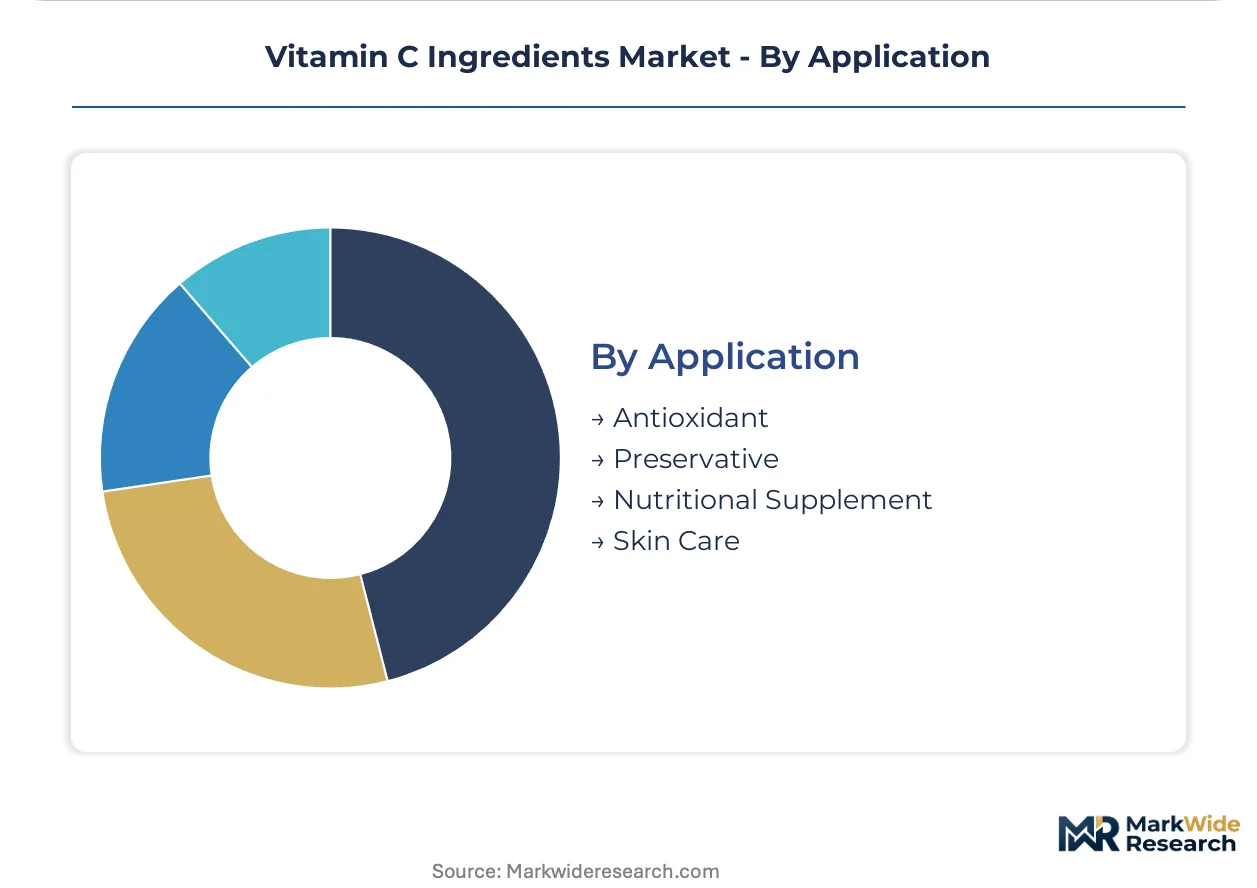
Application:
Antioxidant functionality spans the broadest end-use footprint while nutritional supplement positioning captures the highest per-kilogram value realization.
- Nutritional Supplement:Core positioning for immune support, collagen synthesis, and micronutrient fortification across ingestible products. Buffered calcium ascorbate expansion is driving premium formulation demand in gastric-sensitive consumer segments.
- Antioxidant:Cross-cutting function in food preservation, cosmetic stability, and pharmaceutical oxidation prevention. Two-step bacterial fermentation from D-sorbitol is yielding higher conversion efficiency in Liaoning province operations.
- Skin Care:Topical collagen synthesis support and photodamage mitigation driving cosmetic-grade ascorbic acid and derivative demand. Lipophilic variants are capturing formulation share from standard ascorbic acid in oil-phase compatible products.
- Preservative:Food and beverage oxidation inhibition where cost sensitivity limits specification grades to non-pharmaceutical tiers. EFSA ongoing re-evaluation of ascorbic acid safety thresholds will reshape maximum permitted levels across fortified food applications.
Nutritional supplement commands the steepest expansion trajectory through parenteral nutrition and direct-to-consumer immune positioning. Antioxidant maintains the deepest installed base across food, cosmetic, and pharmaceutical preservation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao Port container terminal underwrites Shandong province's dominance in fermentation-derived ascorbic acid export logistics, connecting Jiangsu and Liaoning production clusters to trans-Pacific shipping lanes.
China
Hospital procurement consortiums are consolidating sodium ascorbate purchasing through centralized tender mechanisms for parenteral nutrition applications. SAMR enforcement of revised GB standards for pharmaceutical-grade ascorbic acid is elevating purity testing protocols beyond historical food-grade benchmarks. Liaoning province producers are retrofitting quality control laboratories to meet dual USP-ChP certification requirements.
United States
Group purchasing organizations are replacing fragmented distributor relationships with direct manufacturer contracts tied to multi-year volume commitments. FDA enforcement of Current Good Manufacturing Practice regulations under 21 CFR Part 111 mandates identity testing and contaminant screening that elevates compliance costs for non-integrated suppliers. Hospital supply chains in the Midwest and Southeast are concentrating sodium ascorbate procurement through centralized mechanisms.
Germany
Buffered calcium ascorbate demand is expanding among gastric-sensitive consumer segments seeking premium dietary supplement formulations. EFSA's ongoing re-evaluation of ascorbic acid safety thresholds for fortified foods will reshape maximum permitted levels across member states. REACH registration requirements constrain market access for unregistered Asian exporters, concentrating volume among pre-qualified suppliers in the Rhine-Ruhr industrial corridor.
France
Cosmetic formulators are displacing standard ascorbic acid with lipophilic derivatives for oil-phase compatible antioxidant applications. ANSM oversight aligns with EMA pharmaceutical-grade purity benchmarks for injectable formulations. The Île-de-France region hosts specialized distributors serving premium cosmetic and pharmaceutical channels with certified pharmaceutical-grade supply.
India
Dietary supplement manufacturers are developing direct-to-manufacturer digital procurement channels bypassing traditional distributors. CDSCO pharmaceutical-grade certification timelines extend supplier onboarding cycles for parenteral nutrition applications. Maharashtra and Gujarat fermentation facilities are upgrading batch-level D-sorbitol origin tracking systems to meet legacy ERP integration requirements.
Vitamin C Ingredients Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with publicly traded entities dominating premium pharmaceutical-grade supply while private fermentation operators anchor commodity volume production. The vendor base stratifies across three functional tiers: integrated fermentation-to-premix conglomerates, captive feedstock specialists, and synthetic derivative innovators. Consolidation pressure concentrates among Jiangsu and Shandong province operators as purity mandates compress margins. Dominant competitive moves include backward integration into D-sorbitol feedstock production and dual pharmacopeial certification investments.
Within the integrated fermentation tier, DSM-Firmenich AG exemplifies premium positioning across European and North American nutraceutical channels. Among Chinese captive feedstock operators, Northeast Pharmaceutical Group Co., Ltd. anchors global bulk supply through Liaoning province operations. BASF SE occupies the synthetic derivative specialization tier, serving cosmetic applications above commodity ascorbic acid pricing levels.
| Leading Market Players |
|---|
| Northeast Pharmaceutical Group Co., Ltd. |
| Hubei Grand Pharmaceutical Co., Ltd. |
| DSM-Firmenich AG |
| Huanggang Huachang Pharmaceutical Co., Ltd. |
| Shandong Luyin Pharmaceutical Co., Ltd. |
| BASF SE |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Kemin Industries, Inc. |
| Zhejiang Medicine Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between hospital procurement consortiums and Liaoning province fermentation facilities lock in multi-year sodium ascorbate supply while anchoring price visibility against corn starch feedstock volatility. These arrangements concentrate purchasing power among US group purchasing organizations and Chinese state tender mechanisms, compressing spot-market liquidity for pharmaceutical-grade material.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade USP-ChP dual-certified supply from food-grade commodity ascorbic acid and cosmetic-grade derivatives. Price differentiation hinges on certification documentation burden and batch-level traceability compliance, with gastric-sensitive calcium ascorbate formulations commanding premium positioning. Pricing pressure stems from REACH registration compliance costs filtering unregistered Asian exporters from European channels. Hospital procurement managers exhibit lowest price sensitivity due to patient safety liability, while beverage fortification buyers prioritize cost per active unit.
Supply Chain Analysis
Just-in-time inventory strategies dominate North American nutraceutical formulation, while Chinese producers maintain strategic stockpiles of D-sorbitol feedstock against corn starch harvest cycles. Supply concentrates in China, specifically Jiangsu, Shandong and Liaoning provinces, with secondary fermentation capacity in India. Raw material dependencies center on corn-derived sorbitol, citric acid process intermediates, and pharmaceutical-grade packaging films. Single-region production clustering creates structural vulnerability to provincial environmental enforcement actions. Distribution runs through Qingdao Port container terminals connecting fermentation clusters to trans-Pacific lanes, with European REACH-registered volumes flowing through Rotterdam consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital procurement platform adoption is transforming this market toward direct-manufacturer contracting, bypassing traditional distributor layers and creating interoperability standards for batch-level traceability data exchange.
For Market Incumbents: Secure captive D-sorbitol feedstock supply through backward integration or long-term agricultural partnerships, insulating margin structures from corn starch price spikes. Lock in dual USP-ChP pharmacopeial certification ahead of SAMR enforcement escalations, defending position against emerging Indian fermentation capacity. Channel control through direct-to-manufacturer digital procurement portals represents the critical defensive lever against distributor disintermediation.
For New Entrants and Emerging Players: Differentiate on single-use bioreactor technology deployment, offering contract manufacturing services with sub-8-month capacity expansion timelines versus incumbent stainless steel retrofits. Target buffered calcium ascorbate formulation supply for German and French gastric-sensitive supplement segments, the most penetrable premium tier. A white-label certification-fast-track service model addresses 12-18 month USP-EP onboarding barriers facing mid-scale competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-to-premix integrated conglomerates with established REACH registration and hospital procurement consortium relationships, positioning for 5-10 year regulatory consolidation. Acquisition target archetypes include Liaoning province operators with captive sorbitol supply and dual pharmacopeial laboratory infrastructure. The signal to watch is EFSA safety threshold re-evaluation timing, which will trigger beverage fortification formulation demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Pharmacopeial Certification Investment | USP-ChP laboratory retrofitting opens hospital procurement consortium access in United States and China. |
| Backward Integration into Sorbitol Feedstock | Corn starch processing capacity anchors cost stability against agricultural commodity volatility. |
| Single-Use Bioreactor Technology Adoption | Disposable fermentation systems compress capital deployment timelines for contract manufacturing expansion. |
| Direct-to-Manufacturer Digital Procurement Platform | Bypassing traditional distributors captures margin compression from group purchasing organization consolidation. |
| Buffered Salt Derivative Capacity Expansion | Calcium ascorbate production lines target gastric-sensitive premium formulation demand in Germany and France. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, pharmaceutical procurement leads at hospital group purchasing organizations, regulatory affairs directors, and downstream nutraceutical formulators; and secondary validation through SAMR GB standard filings, US FDA 21 CFR Part 111 enforcement actions, REACH registration databases, and customs export records from Qingdao Port. Bottom-up capacity modeling triangulated against top-down demand segmentation across purity grades and end-use specifications.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, chemical form, end-user channel, and geographic production hub, with CAGRs derived from regression analysis of historical fermentation yield improvements and procurement pattern shifts. Industry-specific inputs incorporated corn starch price correlation coefficients, pharmacopeial certification adoption curves, and hospital tender consolidation rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or feedstock price stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding SAMR GB standard implementation timing and EFSA re-evaluation proceedings. Revision becomes warranted when hospital procurement consortium concentration crosses threshold dominance levels or single-region production clustering triggers supply continuity interventions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Soy Protein Market
Ingredients
Soybean Meal Market
Ingredients
Vegetable Extract Market
Ingredients
Soy Protein Isolate Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Food Minerals Market
Ingredients
Plant Extracts Market
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Vegetable Glycerin Market
Ingredients
Savory Ingredients Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Chewing Gum Base Market
Ingredients
Non-GMO Soya Market
Ingredients
Global Tomato Powder Market
Ingredients
Spray-Dried Isolate Market
Ingredients
Sodium Reduction Ingredients Market