
 Plant Extracts Market | 2026-2036
Plant Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Extracts Market Intelligence
Organic-certified and pharmacopeia-grade specifications is reorganizing procurement priorities across downstream sectors. Givaudan leverages vertical integration into raw botanical sourcing to secure supply consistency for flavor applications. dsm-firmenich anchors its position through R&D intensity in fermentation-derived phytochemicals. Synthite Industries Ltd dominates oleoresin output from its Kerala extraction base, competing on solvent recovery technology and geographic concentration.
Plant extracts are concentrated bioactive preparations obtained from botanical matrices through solvent extraction, steam distillation, or supercritical CO2 processing, typically standardized to marker compound content such as polyphenol percentage or essential oil yield, and serve as functional inputs for flavoring, therapeutic formulation, and cosmetic active delivery. Essential oils and phytochemicals command premium positioning due to pharmaceutical and nutraceutical standardization requirements, while herbal extracts maintain volume leadership in food and beverage applications where cost efficiency governs procurement. Oleoresins represent a specialized margin pool in spice-derived color and flavor systems, with powder and liquid forms diverging based on end-use handling requirements in dietary supplements versus personal care manufacturing.
EMA pharmacopeial standards and FDA botanical drug guidance shape purity benchmarks and analytical method requirements for market access, while India's CDSCO and BIS certification frameworks govern export-oriented extraction operations based in Kerala and Karnataka. REACH compliance in Europe and evolving EPA residue limits for agricultural botanicals further constrain formulation choices and extraction solvent selection. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade specifications as classification decisions directly determine applicable testing burdens and market entry pathways.
Market Dynamics
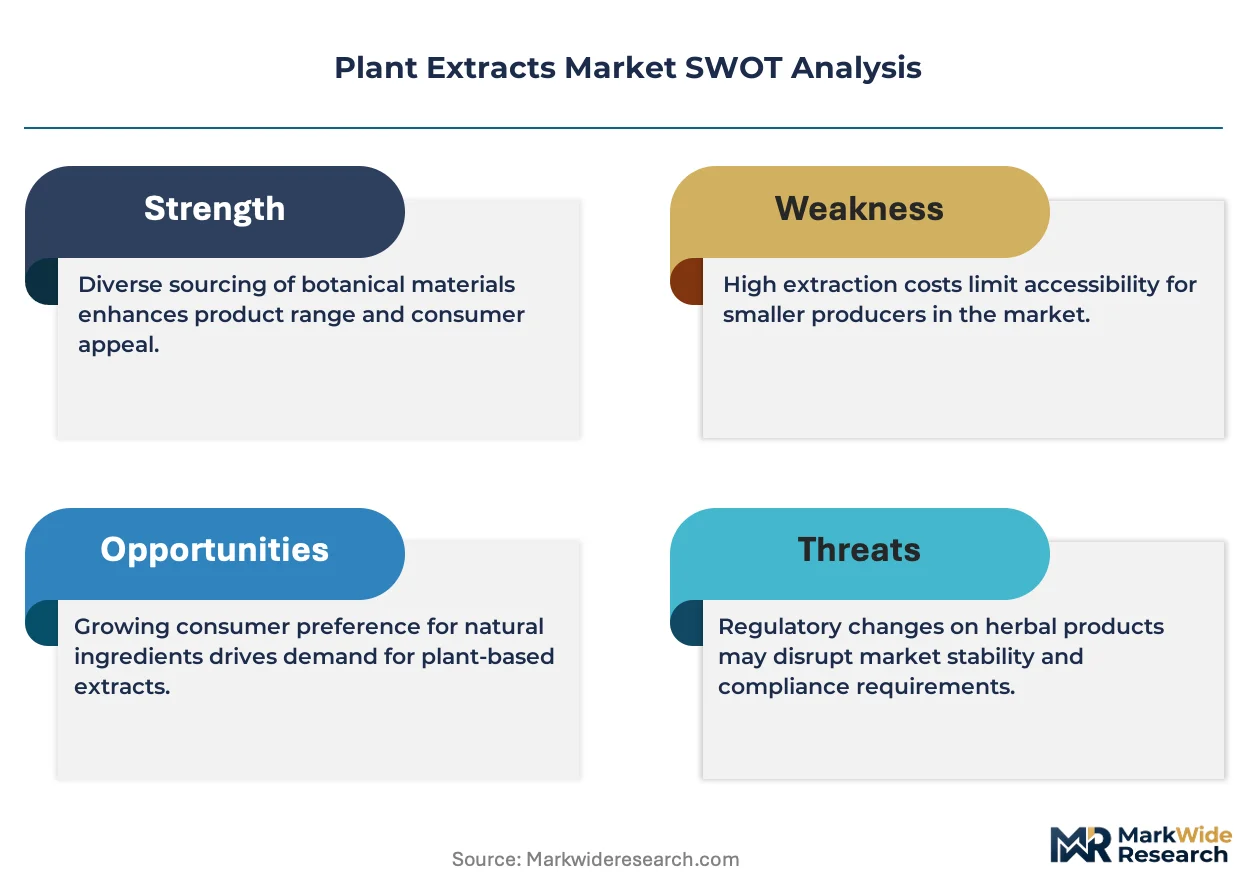
Pharmaceutical formulators are intensifying botanical API sourcing as EMA and FDA pharmacopeial standards tighten purity benchmarks for natural-origin compounds, forcing extraction operations to upgrade analytical capabilities and solvent recovery systems.
Growth Catalysts
- REACH compliance evolution:European manufacturers face mandatory substitution of synthetic additives with plant-derived alternatives, expanding addressable demand for certified oleoresins and essential oils.
- Nutraceutical standardization:Dietary supplement brands now require marker compound verification for polyphenol content, creating premium pricing tiers for pharmacopeia-grade extracts.
- Kerala agro-climatic concentration:India's spice belt enables year-round solvent-free extraction output with geographic proximity to raw material sourcing.
Market Restraints
- Input cost volatility:Weather-sensitive botanical harvests in Madagascar and Indonesia create raw material price instability for vanilla and clove derivatives.
- Supply concentration risk:Supercritical CO2 extraction equipment manufacturing concentrates in German and Italian engineering clusters, creating procurement bottlenecks.
- Regulatory friction:Divergent FDA botanical drug guidance and EMA herbal medicine frameworks force dual certification investments for cross-Atlantic market access.
Strategic Opportunities
- Fermentation-derived phytochemicals:Precision biotechnology enables biosynthesis of rare cannabinoids and alkaloids without agricultural cultivation constraints.
- Personal care active delivery:Cosmetic formulators seek standardized polyphenol complexes for anti-aging applications, opening pharmaceutical-grade supply channels.
- CDSCO export facilitation:India's streamlined botanical export certification under DGFT incentives reduces time-to-market for Kerala-based extraction operations.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC and GC-MS method development for marker compound quantification requires specialized skill sets in short supply across extraction facilities.
- Certification timeline compression:Organic and pharmacopeia-grade audits now demand 18-24 month validation cycles, delaying revenue recognition for new product lines.
- Legacy solvent system retrofitting:Established hexane-based extraction infrastructure requires capital-intensive conversion to supercritical CO2 or ethanol systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Extracts Market |
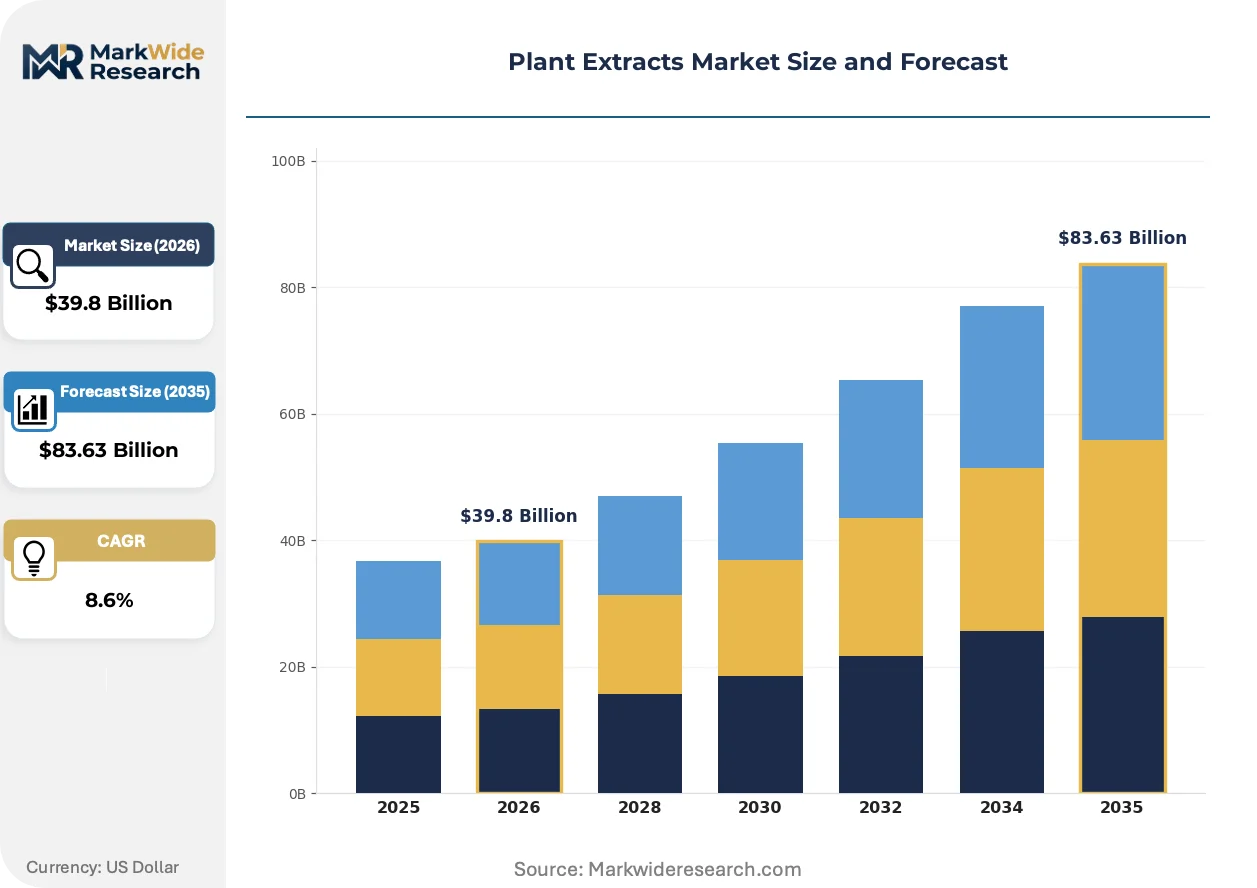
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $83.63 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbal Extracts, Phytochemicals, Oleoresins Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End Use Industry: Food Processing, Personal Care, Dietary Supplements, Agriculture Form: Liquid, Powder, Solid, Granules |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Symrise AG, Sensient Technologies Corporation, dsm-firmenich, Synthite Industries Ltd, ADM, Cargill Incorporated, Döhler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Extracts Market Strategic Shifts & Innovations
Extraction technology and regulatory classification systems are actively reconfiguring competitive positioning across pharmaceutical, nutraceutical, and cosmetic end-uses. Three developments dominate the current transformation.
Supercritical CO2 extraction is fragmenting traditional solvent-based processing economics. Pharmaceutical formulators in Switzerland and Germany now specify this technology for pharmacopeia-grade output, compressing margins for hexane-dependent operations while enabling temperature-sensitive compound preservation.
EMA's revised herbal medicine quality guidelines now mandate DNA barcoding for botanical identity verification. European extraction facilities must install sequencing capabilities or outsource to certified laboratories, with spice-derived oleoresins facing the steepest compliance burden.
Buyers now consolidate procurement through direct contracts with extraction specialists rather than trading intermediaries. Flavor houses in France and cosmetic manufacturers in Japan establish captive supply relationships with Kerala and Karnataka operations, compressing traditional distributor margins.
Plant Extracts Market Segmentation
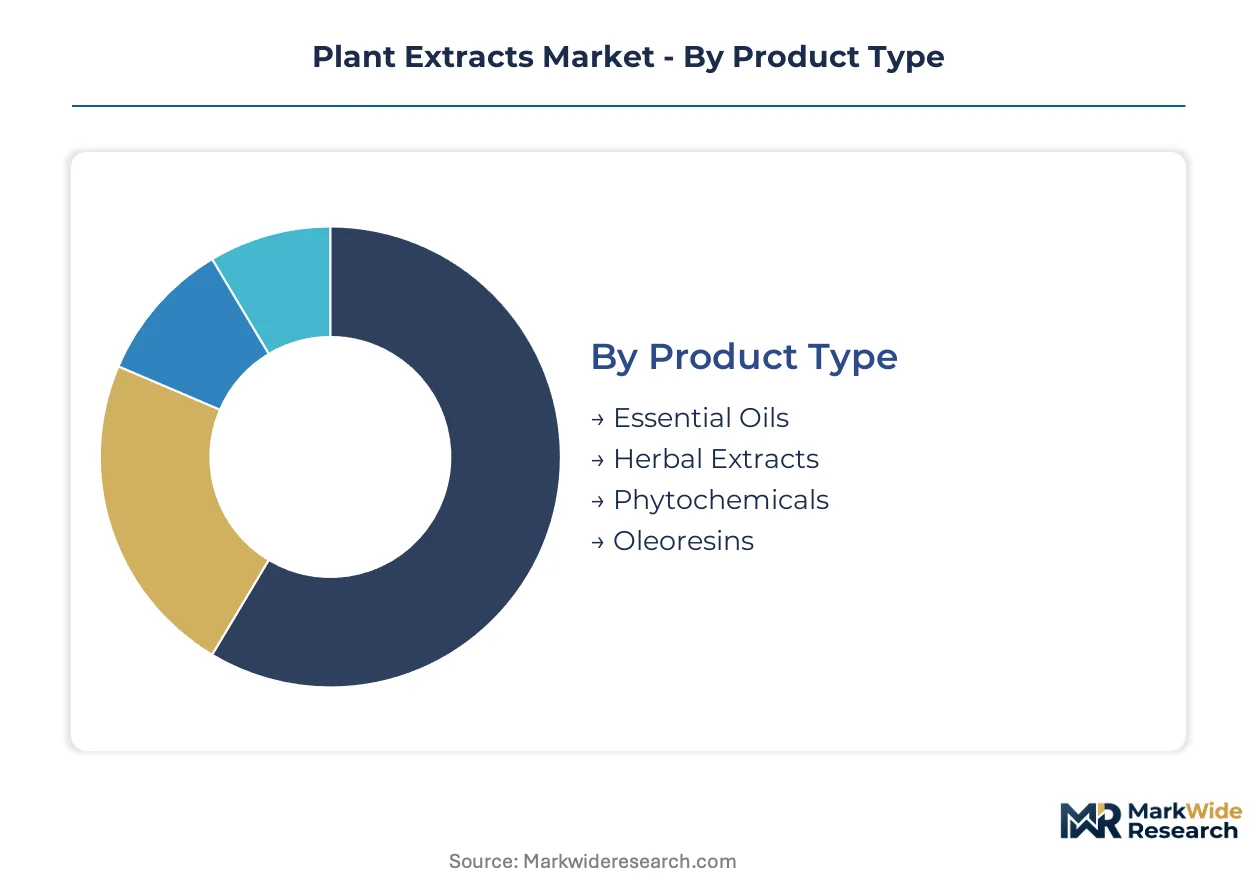
Segmentation in plant extracts reveals divergent margin structures and regulatory pathways. Product type determines extraction technology investment, while application dictates pharmacopeial versus food-grade certification requirements.
Product Type:
Domestic consumption concentrates in herbal extracts and essential oils across India and China, while oleoresins and phytochemicals drive export-led revenue into European and North American pharmaceutical channels.
- Essential Oils:Steam-distilled volatile aromatic compounds standardized to terpene profiles. Pharmaceutical formulators in Switzerland and Germany now mandate supercritical CO2-derived grades for pharmacopeia compliance, compressing margins for traditional solvent-based producers.
- Herbal Extracts:Solvent-extracted or aqueous preparations concentrated to marker polyphenol percentages. India's Kerala and Karnataka operations dominate volume output for food and beverage applications where cost efficiency governs procurement decisions.
- Phytochemicals:Isolated bioactive compounds including alkaloids and cannabinoids requiring chromatographic purification.
- Oleoresins:Solvent-extracted spice concentrates combining essential oils and resinous fractions for color and flavor systems.
Herbal extracts command the established base. The steepest expansion runs through phytochemicals.
Application:
Cost tier stratification separates premium pharmacopeia-grade pharmaceutical demand from commoditized food-grade procurement.
- Pharmaceuticals:Botanical APIs and standardized extracts meeting EMA and FDA purity benchmarks. Swiss and German formulators drive specification intensity for DNA-barcoded identity verification and heavy metal testing protocols.
- Nutraceuticals:Dietary supplement inputs requiring marker compound quantification via HPLC methods. US and Japanese brands now require third-party certification for polyphenol standardization, creating premium pricing tiers.
- Food & Beverage:Flavoring and coloring applications governed by cost-per-unit sensitivity.
- Cosmetics:Active delivery systems for anti-aging formulations seeking standardized antioxidant complexes.
Food and beverage anchors volume throughput. Nutraceuticals are climbing the fastest on certification premiums.
End Use Industry:
Customer type fragmentation splits between multinational formulators demanding captive supply contracts and regional processors buying spot market.
- Food Processing:Industrial-scale flavor and colorant procurement concentrated in European and Japanese manufacturing hubs.
- Dietary Supplements:Contract manufacturers and direct-to-consumer brands requiring batch-specific certificates of analysis.
- Personal Care:Cosmetic formulators in France and Japan seeking polyphenol complexes for topical active delivery.
- Agriculture:Botanical pesticide and growth regulator applications governed by EPA and evolving residue limits.
Food processing maintains the largest installed demand. Personal care shows the steepest trajectory on pharmaceutical-grade supply channel expansion.
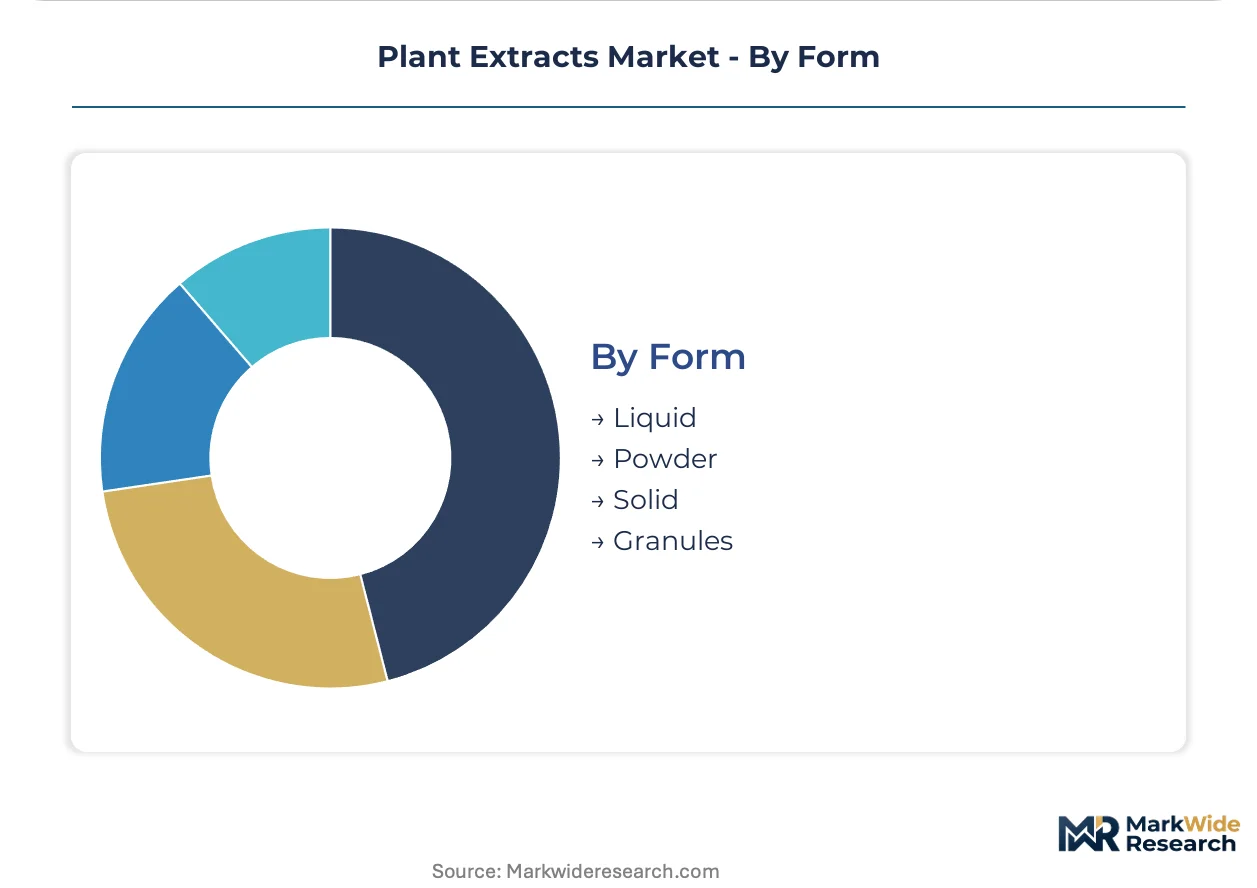
Form:
Supply concentration in powder processing equipment creates procurement bottlenecks for dietary supplement manufacturers.
- Liquid:Essential oil and oleoresin formats preferred for flavor house handling efficiency and rapid dispersion in beverage matrices.
- Powder:Spray-dried and standardized extracts for dietary supplement encapsulation and cosmetic dry formulation.
- Solid:Compressed or crystallized phytochemical isolates for pharmaceutical tablet manufacturing.
- Granules:Intermediate processing format for controlled-release nutraceutical applications.
Liquid forms dominate flavor and fragrance offtake. Powder is gaining share fastest on nutraceutical encapsulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports oleoresins and standardized extracts to European pharmaceutical formulators and Japanese flavor houses, with Kerala-based operations commanding geographic proximity advantages to spice cultivation belts.
United States
Dietary supplement brands drive demand for marker-compound-verified botanical inputs. FDA botanical drug guidance and EPA residue limits constrain solvent selection and agricultural sourcing protocols. New Jersey and California house contract manufacturing clusters serving direct-to-consumer wellness brands.
Germany
Pharmaceutical formulators specify supercritical CO2 extraction for pharmacopeia-grade essential oils. EMA herbal medicine quality guidelines mandate DNA barcoding for identity verification. Bavarian and Baden-Württemberg facilities install sequencing capabilities to meet revised purity benchmarks.
India
Synthite Industries and regional suppliers leverage agro-climatic diversity for solvent-free extraction output. CDSCO export certification under DGFT incentives streamlines time-to-market for Kerala-based operations. Karnataka and Kerala concentrate oleoresin production with backward integration into raw botanical sourcing.
Switzerland
Flavor and fragrance houses demand certified organic grades with full supply chain traceability. Swissmedic pharmacopeial standards exceed baseline EMA requirements for heavy metal testing. Geneva and Basel clusters specialize in premium terpene profiles for pharmaceutical applications.
Japan
Cosmetic formulators seek standardized polyphenol complexes for anti-aging topical delivery. METI and PMDA frameworks govern import documentation for botanical actives. Tokyo and Osaka house R&D facilities developing fermentation-derived phytochemical alternatives to agricultural extraction.
Plant Extracts Market Key Industry Players
Listed leaders compete with private specialists across extraction technology tiers and certification grade positioning. The vendor base splits between multinational flavor houses with captive supply networks and regional extraction specialists competing on solvent recovery efficiency and geographic raw material access. Three archetypes dominate: vertically integrated agrifood conglomerates controlling upstream cultivation, specialized oleoresin producers concentrated in India's spice belt, and biotechnology platforms developing fermentation-derived alternatives. Competitive moves concentrate on backward integration into botanical sourcing and supercritical CO2 capacity expansion to meet pharmaceutical-grade specifications.
Within the premium-tier vector, Givaudan and dsm-firmenich exemplify multinational flavor and nutrition houses with captive R&D intensity. Synthite Industries Ltd occupies a position among Kerala-based extraction specialists competing on solvent-free output and geographic concentration. These three represent divergent strategic positions: biotechnology-forward fermentation platforms, vertical agrifood integration, and regional extraction specialization serving export pharmaceutical channels.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Sensient Technologies Corporation |
| dsm-firmenich |
| Synthite Industries Ltd |
| ADM |
| Cargill Incorporated |
| Döhler |
| Others |
Cost & Logistics Intelligence
Supercritical CO2 extraction capacity utilization above 85% in German and Swiss pharmaceutical corridors compresses price floors for hexane-dependent operators while elevating premiums for pharmacopeia-grade output. Scale concentration in Kerala's solvent-free extraction belt simultaneously anchors economy-tier pricing for oleoresin exports to European flavor houses.
Pricing Analysis
Hexane-based extraction, supercritical CO2 processing, and emerging ethanol systems occupy divergent pricing tiers. Three-tier pricing structure across pharmacopeia-grade, food-grade, and feed-grade certification levels reflects EMA purity benchmark compliance costs and DNA barcoding investments. Cost compression in traditional solvent tiers is intensifying because REACH substitution mandates expand demand for certified botanical alternatives. Dietary supplement contract manufacturers exhibit highest price sensitivity, while Swiss pharmaceutical formulators accept premium positioning for terpene-standardized essential oils.
Supply Chain Analysis
Strait of Malacca transit underwrites vanilla and clove derivative flows from Madagascar and Indonesia to European extraction facilities. Raw material sourcing concentrates in India, Madagascar, and Indonesia for spice-derived matrices, while supercritical CO2 equipment manufacturing rests on German and Italian engineering clusters. Single-source vulnerability in chromatography resin supply creates procurement bottlenecks for alkaloid isolation operations. Distribution runs through direct captive contracts between Kerala extraction specialists and Swiss flavor houses, bypassing traditional trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant extracts markets are approaching a platform-economics inflection where DNA barcoding standardization and fermentation-derived biosynthesis interoperability will determine which extraction technologies capture pharmaceutical-grade premiums.
For Market Incumbents: Compound defensive positioning through backward integration into Kerala and Karnataka raw botanical sourcing to secure supply consistency against fermentation-derived substitute threats. Prioritize supercritical CO2 capacity expansion in Swiss and German corridors where EMA pharmacopeial standards command certification premiums. Lock in multi-year offtake agreements with Japanese cosmetic formulators seeking polyphenol complexes before biosynthesis platforms achieve cost parity. For New Entrants and Emerging Players: Lead with personal care active delivery as the most penetrable vector, where French and Japanese cosmetic formulators seek standardized antioxidant complexes without incumbent supply relationships. Target CDSCO-export-certified Kerala operations as acquisition candidates for immediate regulatory pathway access. Differentiate through fermentation-derived cannabinoid and alkaloid platforms that bypass agricultural cultivation constraints entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extraction specialists with captive supply contracts to multinational flavor houses and pharmaceutical formulators. Long-term viability across the next decade favors operations with dual certification in pharmacopeia-grade and organic standards. Monitor EMA herbal medicine guideline revisions as the critical inflection signal for DNA barcoding infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Botanical Sourcing | Kerala spice belt proximity secures year-round solvent-free extraction output for export channels. |
| Supercritical CO2 Capacity Expansion | Swiss and German pharmaceutical formulators now mandate this technology for pharmacopeia compliance. |
| Fermentation-Derived Phytochemical Development | Biosynthesis platforms bypass Madagascar vanilla and Indonesian clove harvest volatility constraints. |
| DNA Barcoding Infrastructure Investment | EMA revised herbal medicine guidelines mandate sequencing capabilities for European market access. |
| Direct Captive Supply Contracting | Japanese cosmetic and French flavor houses consolidate procurement away from trading intermediaries. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with extraction facility operators, pharmaceutical formulators, cosmetic R&D directors, and flavor house procurement leads; and secondary validation through CDSCO export filings, EMA herbal medicine guideline revisions, FSSAI certification databases, and customs trade records. Bottom-up triangulation across Kerala and Karnataka production volumes reconciled with top-down demand estimates from European and Japanese end-use channels.
Across the analysis window, forecasts modeled product type segmentation by extraction technology, application tier by certification grade, and regional supply concentration by agro-climatic zone. CAGRs derived from installed capacity expansion timelines, substitution elasticity estimates for synthetic-to-botanical transitions, and penetration curves for supercritical CO2 technology adoption in pharmaceutical corridors. Input assumptions incorporated REACH compliance evolution timelines and FDA botanical drug guidance revision patterns.
Forecasts assume regulatory continuity in EMA herbal medicine frameworks and FDA botanical drug guidance; material policy shifts in DNA barcoding mandates or fermentation-derived compound classification would require re-modeling. Practitioners should keep alternative scenarios live as biosynthesis cost curves and climate volatility in Madagascar and Indonesia evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Bread Flour Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Mineral Premix Market
Ingredients
Global Natural Gum Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Industrial Starch Market
Ingredients
Licorice Root Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Ground-Nut Oil Market
Ingredients
Glucosylglycerol Market
Ingredients
Liquid Egg Market
Ingredients
Agarwood Oil Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Milk Ingredients Market
Ingredients
Global Malt Ingredients Market