
 Ascorbyl Palmitate Market | 2026-2036
Ascorbyl Palmitate Market Size, Share, and Industry Trends Forecast 2026-2036
Ascorbyl Palmitate Market Outlook
The divergence between pharmaceutical-grade and food-grade ascorbyl palmitate is realigning procurement priorities across the value chain. BASF SE leverages its integrated vitamin E and C derivative platform to sustain premium positioning in European cosmetics applications. DSM-Firmenich AG anchors its competitive stance through biotechnology-led manufacturing scale, while Zhejiang NHU Co., Ltd. dominates cost-engineered output for Asian nutraceutical buyers.
Ascorbyl palmitate is a fat-soluble ester synthesized from ascorbic acid and palmitic acid, typically containing 40-42% active vitamin C by weight and functioning primarily as an antioxidant stabilizer in lipid-based matrices. Powder formulations lead volume due to extended shelf stability and ease of bulk handling, while oil and emulsion variants capture margin pools in high-performance cosmetics. Nutraceutical applications are expanding fastest as dietary supplement manufacturers reformulate toward lipid-compatible vitamin C delivery systems.
FDA food additive regulations, EFSA antioxidant authorization frameworks, and China's GB standards for food-grade chemicals collectively determine purity thresholds and market access conditions for ascorbyl palmitate producers. REACH registration requirements in Europe impose testing burdens that favor established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving cosmetic ingredient disclosure mandates and food fortification policy shifts to anticipate demand migration between application segments.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing food-grade margins while redirecting capital toward synthesis automation and regulatory compliance infrastructure across the value chain.
Growth Catalysts
- EFSA antioxidant authorization:Expanded food additive approvals in lipid matrices accelerate bakery and infant formula applications across EU member states.
- Nutraceutical encapsulation demand:Softgel manufacturers in China and India are scaling lipid-compatible vitamin C formulations for bioavailability-focused supplements.
- Cosmeceutical antioxidant layering:Multi-functional skincare formulations in South Korea and Japan integrate ascorbyl palmitate for oxidative stability in oil-based serums.
Market Restraints
- Palmitic acid feedstock volatility:Palm oil price swings and sustainability certification costs compress synthesis margins for non-integrated producers.
- REACH registration concentration:Testing burdens and dossier maintenance costs favor established European suppliers, limiting new entrant participation.
- Ascorbyl tetraisopalmitate substitution:Higher vitamin C content and improved skin penetration in premium cosmetics displace standard-grade material in facial care.
Strategic Opportunities
- Clean-label bakery expansion:Natural antioxidant positioning in Germany and France drives reformulation away from synthetic TBHQ and BHA.
- Biotechnology convergence:Enzymatic esterification processes reduce solvent use and enable carbon footprint claims for sustainability-scored procurement.
- Veterinary nutraceuticals:Pet supplement manufacturers in the United States are adopting lipid-stabilized vitamin C for companion animal joint health products.
Industry Challenges
- Analytical method standardization:Inconsistent HPLC assay protocols across pharmacopeias create batch release delays and customer qualification friction.
- Multipurpose facility validation:Shared equipment lines for food and pharmaceutical grades require extensive cleaning validation and segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ascorbyl Palmitate Market |
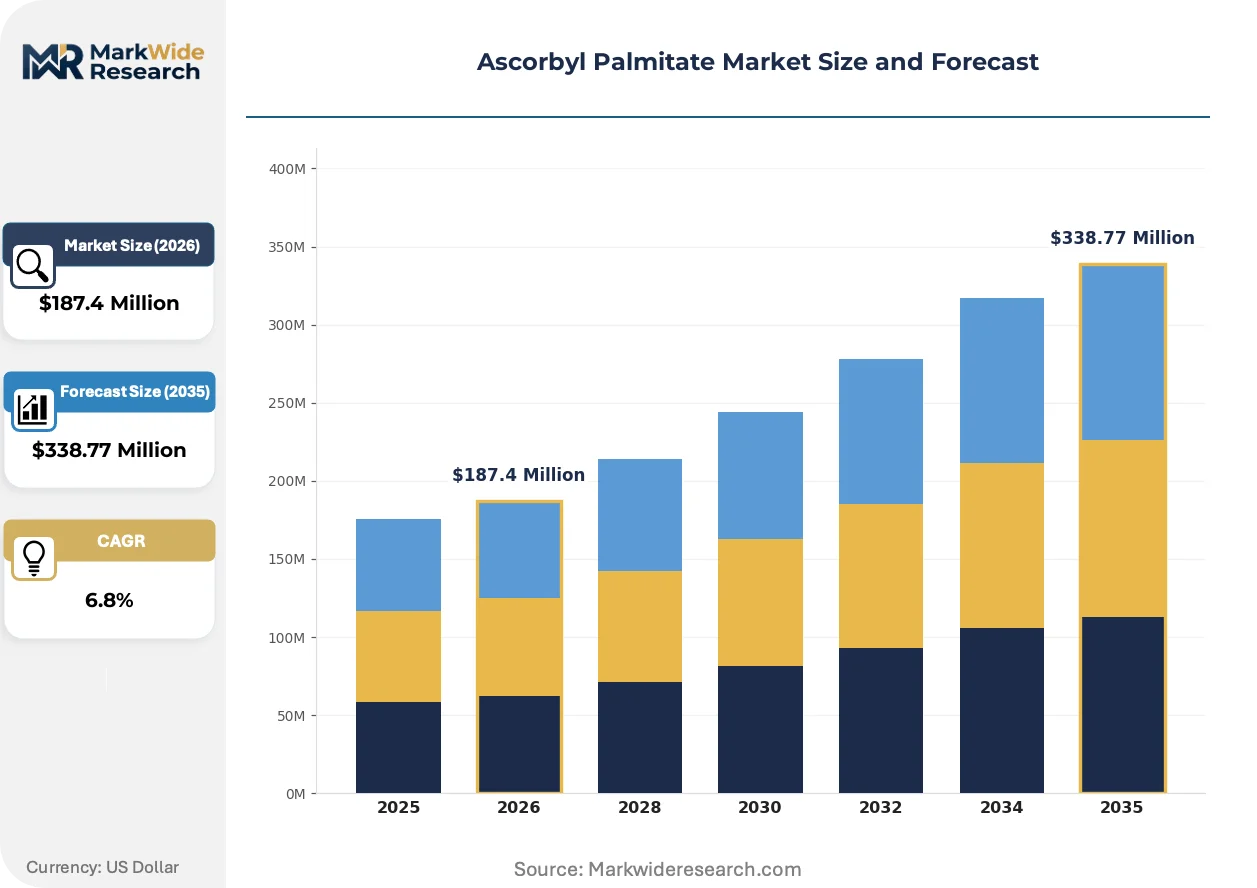
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Emulsion, Gel Application: Cosmetics, Food Preservation, Nutraceuticals, Dietary Supplements End User: Pharmaceuticals, Personal Care, Food & Beverage, Health & Wellness Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | BASF SE, Bajaj Healthcare Ltd., MilliporeSigma, Carbone Scientific, Zhejiang NHU Co., Ltd., DSM-Firmenich AG, Kemin Industries, Inc., Chemos, Comvikin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ascorbyl Palmitate Market Strategic Shifts
Enzymatic synthesis routes and continuous processing equipment are displacing batch chemistry, while regulatory disclosure mandates and carbon accounting reshape supplier qualification criteria.
Continuous flow reactor technology for ascorbyl palmitate synthesis is absorbing capital investment from European and Chinese producers seeking yield improvements and solvent reduction. Mid-scale manufacturers in Zhejiang and Jiangsu provinces are retrofitting batch lines with plug-flow modules to meet pharmaceutical-grade impurity specifications. The technology is absorbing market share from conventional stirred-tank processes as energy costs and environmental permitting tighten.
REACH authorization timelines for antioxidant substances are extending substance evaluation periods, forcing formulators to secure dual-source supply agreements before sunset date uncertainties. The European Chemicals Agency's 2024-2026 rolling action plan prioritizes vitamin derivatives for hazard reclassification, prompting downstream users to accelerate inventory qualification of alternative suppliers. Cosmetic ingredient disclosure mandates in France and Germany are tightening traceability documentation beyond standard certificates of analysis.
Direct procurement contracts between nutraceutical brand owners and synthesis facilities are shortening traditional distributor channels in North American and European markets. Large supplement marketers are establishing quality agreements with Zhejiang-based producers, bypassing regional trading houses that previously managed logistics and customs clearance. This channel compression is most visible in private-label vitamin C softgel programs where margin pressure and supply security concerns dominate sourcing decisions.
Ascorbyl Palmitate Market Segmentation
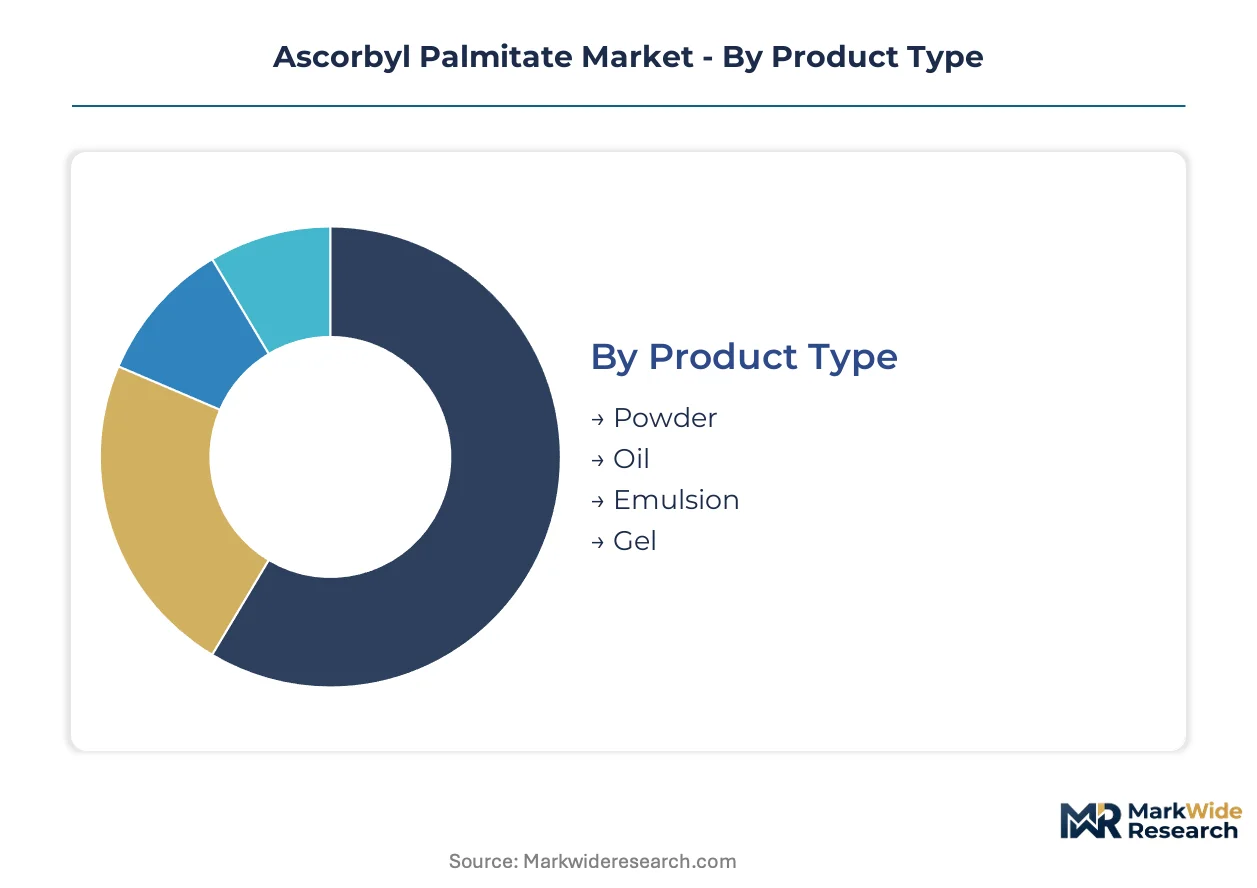
Ascorbyl palmitate's functional versatility across lipid matrices creates distinct specification requirements by formulation type. Procurement patterns diverge sharply between bulk industrial buyers seeking antioxidant stability and premium cosmetics formulators prioritizing skin penetration performance.
Product Type:
Powder formulations dominate procurement volumes due to extended shelf stability and handling efficiency in bulk operations. Oil and emulsion variants command specification premiums in performance-driven applications.
- Powder:Crystalline form containing 40-42% active vitamin C by weight, standardized for bulk antioxidant applications. Demand concentrates in Chinese nutraceutical manufacturing facilities and German bakery ingredient suppliers seeking TBHQ replacement pathways.
- Oil:Lipid-dissolved concentrate optimized for direct incorporation into anhydrous cosmetic bases. Newer deployment is concentrated in South Korean oil-serum formulations and Japanese cosmeceutical lines targeting oxidative stability in squalane matrices.
- Emulsion:Pre-dispersed aqueous-lipid system reducing homogenization energy for food technologists. Mature deployment sits with infant formula manufacturers in the Netherlands and France under EFSA antioxidant authorization frameworks.
- Gel:Thixotropic delivery vehicle for topical pharmaceutical applications. Demand clusters in transdermal patch development programs and veterinary dermatology formulations in the United States.
Mature deployment sits with Powder. Newer deployment is concentrated in Oil.
Application:
End-use specifications range from pharmaceutical-grade impurity thresholds to food-grade antioxidant efficacy benchmarks. Regulatory authorization status varies substantially across use cases.
- Cosmetics:Oil-compatible antioxidant stabilizing retinol and vitamin E in anhydrous serums. Demand concentrates in South Korean multi-step skincare routines and Japanese premium facial oil formulations seeking oxidative protection without water-phase degradation.
- Food Preservation:Natural antioxidant replacement for synthetic TBHQ in lipid-rich baked goods. Procurement is climbing fastest in German and French clean-label bakery reformulations driven by retailer ingredient blacklists.
- Nutraceuticals:Lipid-encapsulated vitamin C for enhanced bioavailability in softgel delivery. Mature deployment sits with Chinese domestic supplement brands and Indian contract manufacturers serving export markets.
- Dietary Supplements:Stand-alone antioxidant ingredient in tablet and capsule formats. Specification requirements align with USP monograph standards for US and European brand owners.
Volume leadership resides with Food Preservation. Margin expansion is steepest in Cosmetics.
End User:
Customer technical capabilities determine specification complexity and quality agreement requirements. Direct procurement contracts are displacing distributor channels among sophisticated buyers.
- Pharmaceuticals:Injectable and topical drug formulations requiring compendial-grade material with full impurity profiling. Procurement concentrates in European generics manufacturers and US sterile compounding facilities under FDA cGMP oversight.
- Personal Care:Mass-market and prestige skincare brands specifying cosmetic-grade antioxidant performance. Channel compression is most visible in North American private-label programs bypassing traditional trading houses.
- Food & Beverage:Industrial bakeries and edible oil processors seeking natural antioxidant solutions. Mature deployment sits with EU-based margarine and shortening manufacturers under EFSA authorization.
- Health & Wellness:Sports nutrition and functional food startups formulating novel delivery formats. Demand clusters in US direct-to-consumer supplement brands and Chinese TCM-inspired product lines.
Specification stringency peaks with Pharmaceuticals. Procurement velocity is climbing fastest in Health & Wellness.
Distribution Channel:
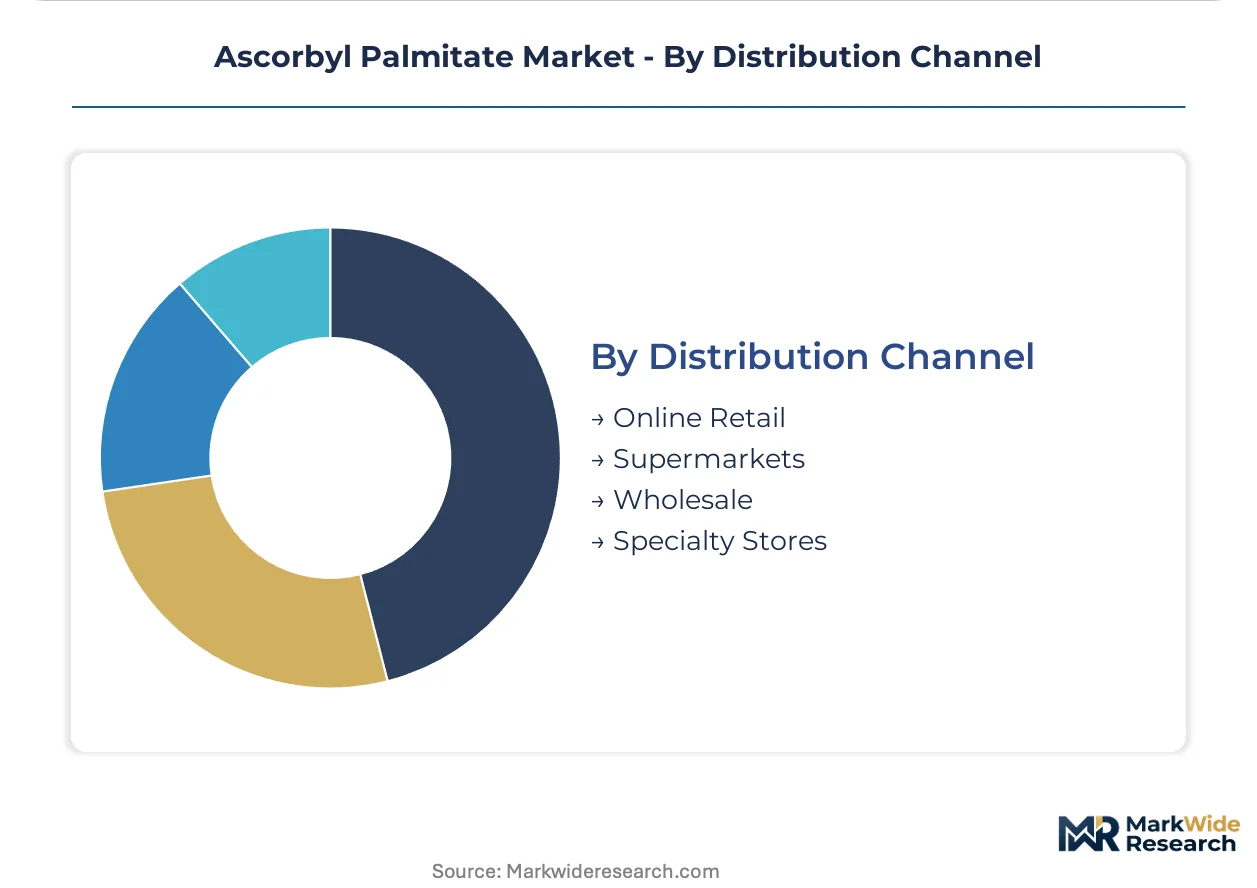
Channel selection reflects buyer scale, technical service requirements, and geographic proximity to manufacturing clusters. Digital procurement platforms are capturing share from traditional chemical distribution.
- Online Retail:E-commerce platforms serving small-scale cosmetics formulators and independent supplement brands. Mature deployment sits with US and European ingredient marketplaces offering certificate-of-analysis documentation.
- Supermarkets:Limited penetration confined to consumer-facing vitamin C supplement products in select Asian markets. Shelf presence remains minimal due to B2B ingredient positioning.
- Wholesale:Bulk chemical distributors managing logistics and customs clearance for mid-scale processors. Channel compression is accelerating as large nutraceutical brand owners establish direct synthesis facility relationships.
- Specialty Stores:Technical ingredient suppliers offering formulation support and regulatory documentation. Demand concentrates in French and German cosmetics clusters requiring REACH compliance verification.
Transaction volume concentrates in Wholesale. Digital migration is steepest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors the global supply base for ascorbyl palmitate synthesis, with Hangzhou and Shaoxing hosting concentrated esterification capacity serving nutraceutical and cosmetics buyers worldwide.
China
Domestic nutraceutical manufacturers in Zhejiang and Jiangsu provinces drive volume procurement of powder-grade material for softgel encapsulation. GB standards for food-grade chemicals set purity thresholds that align with export market requirements. Hangzhou-based synthesis clusters are retrofitting batch lines with continuous flow modules to meet pharmaceutical-grade impurity specifications for European and North American customers.
Germany
Clean-label bakery reformulations in Bavaria and North Rhine-Westphalia accelerate demand for natural TBHQ replacement in lipid-rich baked goods. EFSA antioxidant authorization frameworks determine market access conditions for food preservation applications. Frankfurt-Rhine-Main specialty chemical distributors maintain REACH compliance documentation for cosmetics formulators seeking oxidative stability in anhydrous serums.
United States
Pet supplement manufacturers in California and Colorado adopt lipid-stabilized vitamin C for companion animal joint health products. FDA food additive regulations and cGMP oversight for dietary supplements shape procurement qualification protocols. New Jersey and Pennsylvania pharmaceutical corridors source compendial-grade material for injectable and topical drug formulations requiring full impurity profiling.
South Korea
Multi-step skincare routines in Seoul and Busan integrate ascorbyl palmitate for oxidative stability in oil-based serums and retinol formulations. MFDS cosmetic ingredient regulations align with ECHA disclosure mandates on traceability documentation. Gyeonggi-do cosmetics manufacturing clusters specify oil-compatible antioxidants for premium facial oil products targeting domestic and export markets.
India
Contract manufacturers in Maharashtra and Gujarat scale lipid-compatible vitamin C formulations for bioavailability-focused supplements serving export markets. FSSAI food additive standards and CDSCO pharmaceutical regulations create dual compliance pathways for domestic and international buyers. Mumbai-Pune nutraceutical corridors establish direct procurement relationships with Chinese synthesis facilities, bypassing traditional distributor channels.
Ascorbyl Palmitate Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory capability and synthesis automation dimensions. The vendor base stratifies between integrated vitamin derivative platforms, biotechnology-led manufacturing specialists, and cost-engineered regional suppliers. Three archetypes dominate: European chemical conglomerates with REACH dossier expertise, Chinese scale producers with continuous flow retrofit capacity, and mid-tier distributors managing customs clearance and logistics. Competitive moves concentrate on backward integration into palmitic acid feedstock and enzymatic esterification licensing.
Within the integrated platform tier, BASF SE and DSM-Firmenich AG exemplify European suppliers leveraging combined vitamin E and C derivative portfolios for cosmetics applications. Zhejiang NHU Co., Ltd. occupies a position among cost-engineered Chinese producers dominating regional nutraceutical supply chains. These three anchors represent the divergence between regulatory-heavy European positioning and volume-focused Asian manufacturing scale.
| Leading Market Players |
|---|
| BASF SE |
| Bajaj Healthcare Ltd. |
| MilliporeSigma |
| Carbone Scientific |
| Zhejiang NHU Co., Ltd. |
| DSM-Firmenich AG |
| Kemin Industries, Inc. |
| Chemos |
| Comvikin |
| Others |
Value Chain & Pricing Dynamics
Backward integration into palmitic acid feedstock anchors both supply security and margin defense for established ascorbyl palmitate producers. Chinese synthesis clusters in Zhejiang province leverage captive palm oil derivative supply to undercut European competitors facing REACH compliance cost burdens and volatile commodity procurement.
Pricing Analysis
Yield-based pricing anchors contract negotiations between nutraceutical brand owners and synthesis facilities. Three-tier pricing structure across pharmaceutical-grade, food-grade, and cosmetic-grade levels reflects purity specification differentials and regulatory dossier investments. Cost compression in food-grade powder is intensifying because Chinese scale producers are retrofitting continuous flow modules that reduce solvent waste and energy inputs. Mid-scale European cosmetics formulators show least price sensitivity due to premium positioning requirements, while Indian contract manufacturers serving export softgel programs exhibit highest price elasticity.
Supply Chain Analysis
Specialized chemical engineering talent availability in Hangzhou and Shaoxing manufacturing corridors enables rapid continuous flow reactor deployment. Supply concentrates in China, Germany, and India, with Zhejiang province hosting dominant esterification capacity. Palmitic acid, ascorbic acid, and enzymatic catalysts constitute critical input dependencies. Single-source vulnerability runs through Malaysian and Indonesian palm oil supply chains subject to sustainability certification disruptions. Distribution runs through direct procurement contracts displacing wholesale chemical distributors for large nutraceutical and cosmetics buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow reactor technology is displacing legacy batch chemistry across synthesis operations, compressing capital requirements for yield improvements while tightening impurity specifications for pharmaceutical-grade output.
For Market Incumbents: Anchor market position through enzymatic esterification licensing and REACH dossier maintenance investments. BASF SE and DSM-Firmenich AG should deepen backward integration into palmitic acid feedstock to offset commodity volatility threatening food-grade margins. Defensive priority sits with patenting novel solvent-reduction processes before Chinese competitors achieve comparable pharmaceutical-grade purity thresholds. For New Entrants and Emerging Players: Specialty ingredient distributors serving French and German cosmetics clusters offer the most penetrable channel partnership pathway. Target veterinary nutraceuticals in the United States and clean-label bakery reformulations in Bavaria as white-space segments with lower regulatory barriers than pharmaceutical applications. Go-to-market leverage rests on carbon footprint certification and biotechnology-led manufacturing claims for sustainability-scored procurement programs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated vitamin derivative platforms seeking enzymatic synthesis capabilities. Long-term viability favors mid-scale Chinese producers with continuous flow retrofit capacity and established direct procurement relationships with North American nutraceutical brand owners. Signal to monitor: ECHA hazard reclassification timelines for vitamin derivatives accelerating inventory qualification demand for dual-source supply agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Deployment | Hangzhou-based synthesis clusters reduce solvent use and meet pharmaceutical-grade impurity specifications for European buyers. |
| Backward Integration into Palmitic Acid | Captive palm oil derivative supply insulates margin compression from Malaysian and Indonesian commodity price volatility. |
| Enzymatic Esterification Licensing | Carbon footprint claims enable sustainability-scored procurement positioning for German and French cosmetics formulators. |
| Direct Procurement Contracting | Bypassing wholesale distributors strengthens supply security for North American private-label vitamin C softgel programs. |
| REACH Dossier Maintenance Investment | ECHA authorization timelines favor established suppliers with dedicated regulatory affairs capabilities over new entrants. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at Chinese synthesis facilities, procurement leads at nutraceutical brand owners, technical R&D directors at cosmetics formulators, and distribution channel partners in European specialty chemical clusters combined with secondary validation. Bottom-up capacity and production estimates triangulated against top-down demand aggregation from end-use application segments.
Reconciliation of shipment data, import-export statistics, and producer capacity disclosures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, formulation type, and regional production hub. CAGRs derived from trend extrapolation of volume and value outputs with cross-validation against industry stakeholder growth expectations. Forecast inputs incorporated EFSA antioxidant authorization expansion scenarios and FDA food additive regulatory pathway developments.
Several conditions sit outside the modeled scope, including unforeseen ECHA hazard reclassification outcomes and abrupt palm oil supply disruptions from sustainability certification enforcement. Forecasts reflect documented assumptions about continuous flow technology adoption rates and direct procurement channel compression velocity. Material deviation in palmitic acid feedstock pricing or REACH authorization timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Brazil Food Ingredient Market