
 Spray-Dried Isolate Market | 2026-2036
Spray-Dried Isolate Market Size, Share, and Industry Trends Forecast 2026-2036
Spray-Dried Isolate Market Analytics
Clean-label protein extraction is fragmenting the traditional dairy-centric supply base. Kerry Group plc leverages enzymatic separation technologies to sustain premium positioning in whey isolate fractions. Glanbia plc anchors its North American manufacturing network around high-throughput spray-drying capacity for sports nutrition clients. Fonterra Co-operative Group Limited competes through backward integration into New Zealand grass-fed milk pools, controlling raw protein quality from farm to dryer.
Spray-dried isolate denotes a refined protein powder produced by atomizing concentrated protein slurry into a heated chamber, yielding particles with moisture content below 5 percent and solubility exceeding 90 percent for beverage and bar applications. The process strips lipids and carbohydrates from whey, soy, pea, or casein feedstocks to achieve protein concentrations of 90 percent or higher. Among product types, whey isolate retains the largest margin pool due to established sports nutrition demand, while pea isolate captures the fastest growth trajectory as beverage brands reformulate for allergen-free positioning. Within applications, nutritional supplements dominate volume, though bakery products present untapped formulation complexity where protein functionality must balance water binding with crumb structure integrity.
FDA protein labeling standards and the USDA organic certification framework govern product claims and import eligibility in the United States, while EFSA novel food assessments shape market access for emerging plant isolates within Europe. China's SAMR enforces GB standards for protein content and microbial limits, creating compliance barriers for unqualified exporters. Stakeholders must monitor divergence between regional purity thresholds and emerging sustainability disclosure requirements as procurement criteria harden across institutional buyers.
Market Dynamics
Sports nutrition brands now consolidate procurement around whey and pea isolates while enzymatic separation technologies fragment traditional dairy-centric supply structures. FDA protein labeling revisions tighten purity disclosure requirements, forcing reformulation cycles across beverage and bar applications.
Growth Catalysts
- Clean-label extraction protocols:Enzymatic separation methods strip lipids and carbohydrates more efficiently than legacy acid precipitation, yielding 90-plus percent protein concentrations that beverage brands require for allergen-free positioning.
- India's PLI scheme for food processing:Production-linked incentives accelerate domestic spray-drying capacity expansion, reducing import dependence for plant-derived isolates across South Asian markets.
- Sports nutrition procurement consolidation:Bulk purchasing agreements from performance nutrition brands anchor volume commitments for high-throughput whey isolate fractions, stabilizing capacity utilization for dedicated dryer assets.
Market Restraints
- Milk pool concentration in Oceania:Fonterra's backward integration into New Zealand grass-fed supply chains creates raw material bottlenecks for non-integrated processors during seasonal production swings.
- GB standard microbial limits:China's SAMR enforces protein content and contamination thresholds that disqualify unqualified exporters, raising compliance costs for cross-border plant isolate shipments.
- Pea protein functionality gaps:Water binding and emulsification performance in bakery applications trails dairy isolates, limiting substitution rates in crumb-structure-sensitive formulations.
Strategic Opportunities
- EFSA novel food pathway:Emerging plant isolates from fava bean and chickpea feedstocks await regulatory clearance, creating first-mover positioning for European beverage reformulation pipelines.
- Bakery application underpenetration:Protein functionality requirements for water binding and crumb integrity remain unresolved, offering white space for hydrocolloid-spray dried hybrid formulations.
- Direct-to-brand distribution:Bypassing traditional ingredient distributors, spray-dryer operators now contract directly with sports nutrition and ready-to-drink brands for customized particle size specifications.
Industry Challenges
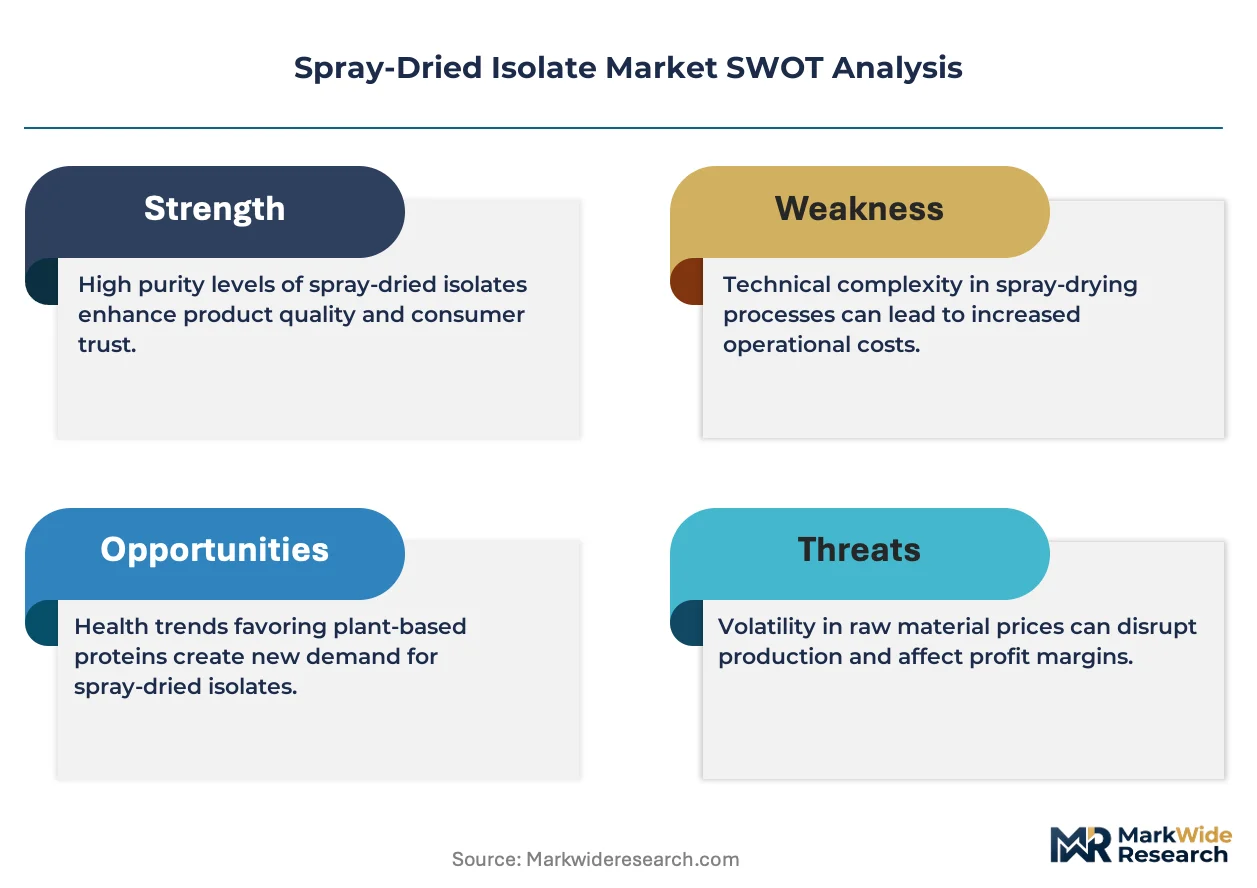
- Spray-dryer capex intensity:High-throughput atomization chambers and integrated separation systems require substantial capital deployment, constraining mid-scale entrants.
- USDA organic certification timelines:Multi-year transition periods for grass-fed milk pools and non-GMO plant sourcing delay premium positioning for isolate fractions targeting natural channel distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray-Dried Isolate Market |
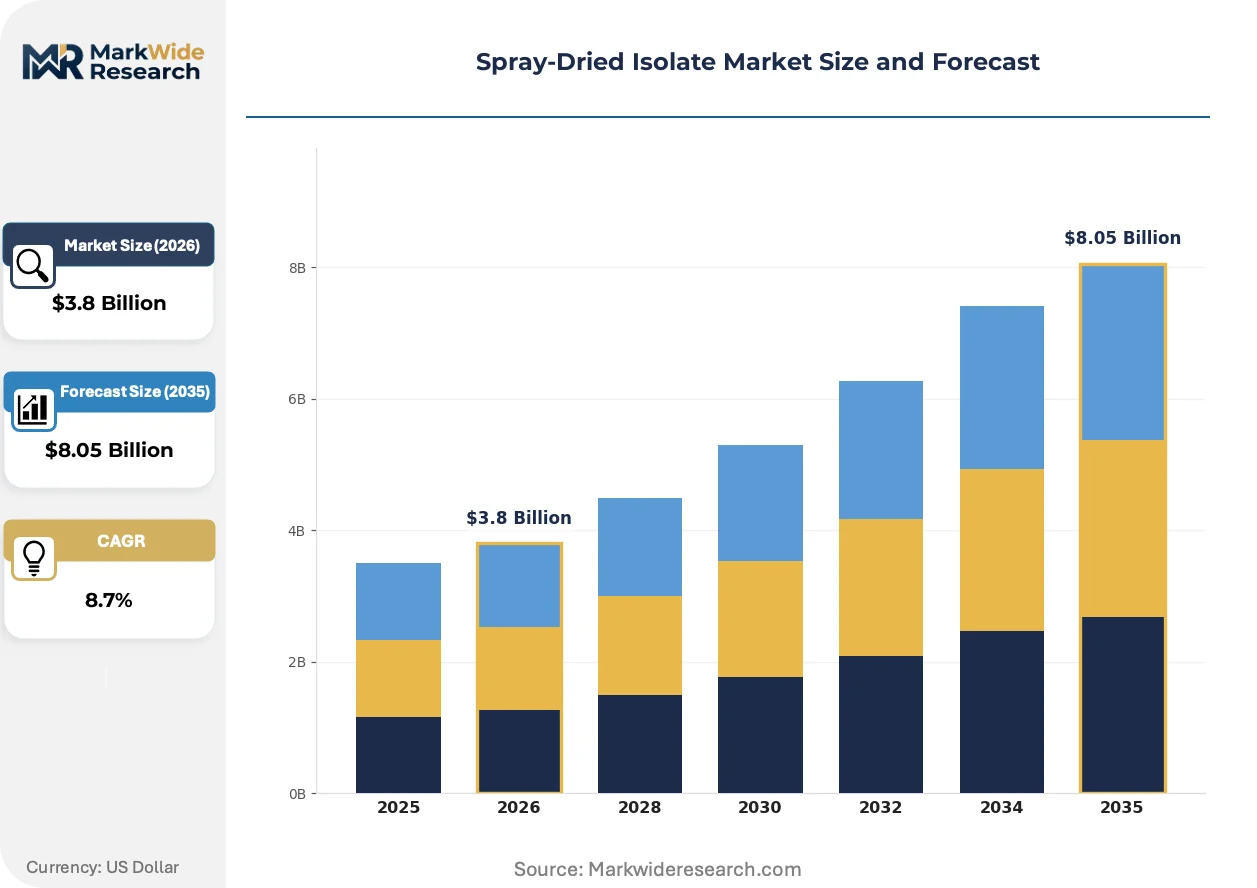
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Isolate, Soy Isolate, Pea Isolate, Casein Isolate Application: Nutritional Supplements, Food & Beverage, Bakery Products, Confectionery End User: Health Conscious Consumers, Athletes, Fitness Enthusiasts, Culinary Professionals Distribution Channel: Online Retailers, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Nestlé S.A., Kerry Group plc, Glanbia plc, FrieslandCampina, Fonterra Co-operative Group Limited, DSM-Firmenich, Ingredion Incorporated, Sensient Technologies Corporation, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray-Dried Isolate Market Evolving Landscape
Atomization technologies and enzymatic processing methods now converge with regulatory disclosure mandates and procurement consolidation patterns. These forces reshape competitive positioning across whey and plant-derived isolate supply chains.
Membrane filtration is hybridizing with traditional spray-drying operations, enabling simultaneous protein concentration and lipid removal in continuous processing lines. Beverage manufacturers adopt these integrated systems to reduce batch-to-batch variability in solubility metrics. The technology is hybridizing capital equipment requirements, compressing facility footprints while raising technical barriers for non-integrated processors.
EFSA novel food assessments now govern market access for emerging plant isolates across European Union member states. The regulatory framework mandates comprehensive safety dossiers for proteins lacking substantial consumption history, extending approval timelines. Plant isolate suppliers targeting beverage applications face the steepest compliance burdens, redirecting development resources toward established whey and soy fractions.
Buyer concentration among sports nutrition brands now dictates contract structures for spray-dried isolate procurement. Long-term volume commitments with performance tier pricing replace spot market purchasing for high-purity whey fractions. North American sports nutrition verticals exhibit the most pronounced consolidation, with three brands commanding the majority of isolate procurement volumes.
Spray-Dried Isolate Market Segmentation
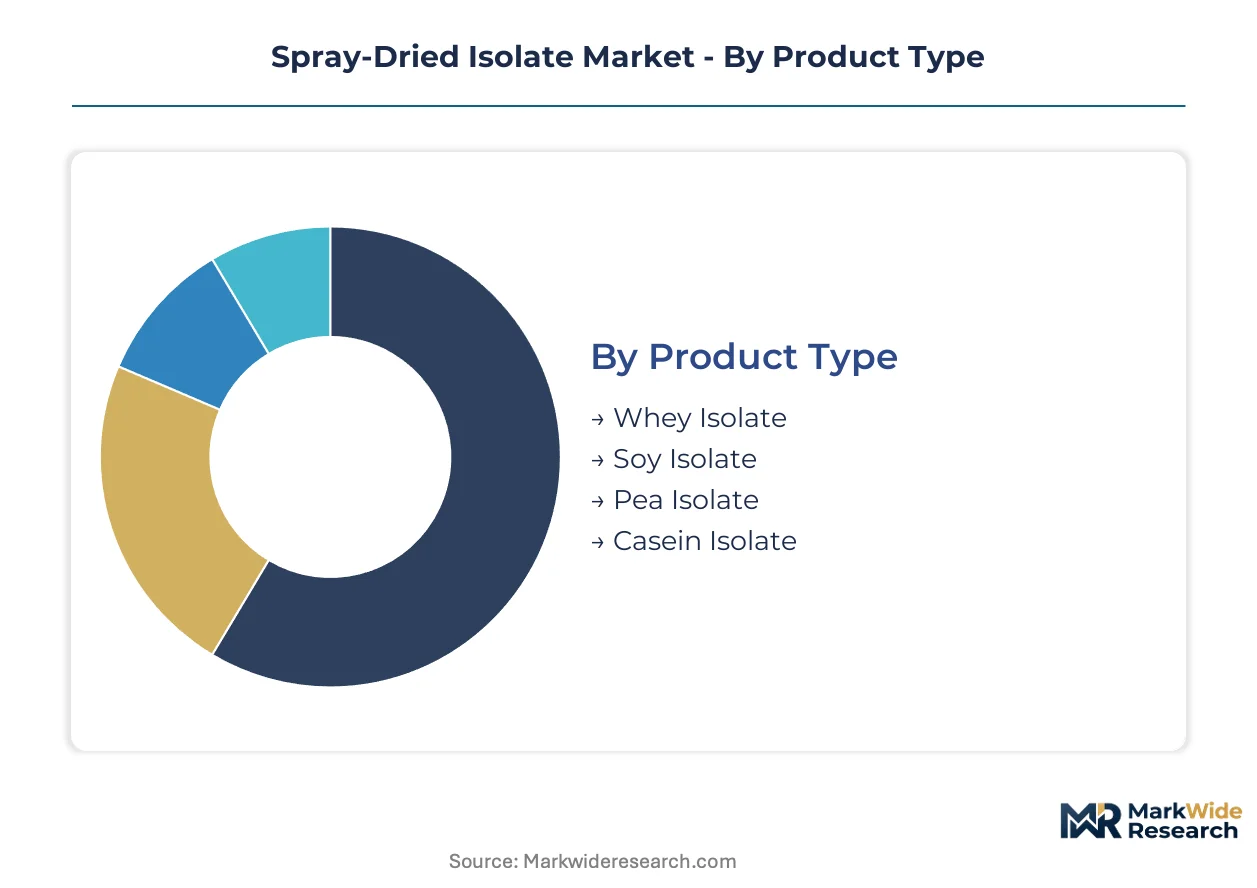
Segmentation in spray-dried isolates reveals divergent margin structures and procurement cycles across protein sources and end-use channels. Manufacturers configure dryer assets differently depending on whether they serve bulk sports nutrition contracts or specialty food ingredient orders.
Product Type:
Whey isolate turns inventory fastest through sports nutrition procurement consolidation, while casein isolate cycles slowest due to extended overnight-release positioning in medical nutrition.
- Whey Isolate:Derived from milk through microfiltration and ion exchange, this fraction achieves protein concentrations above 90 percent with minimal lactose residue. North American sports nutrition brands anchor volume commitments here, though seasonal milk pool fluctuations in New Zealand constrain supply elasticity during peak demand windows.
- Pea Isolate:Yellow pea protein extracted via aqueous separation yields allergen-free positioning that beverage reformulators prioritize. European beverage brands drive the steepest procurement acceleration as EFSA novel food pathways clear additional plant sources for mainstream distribution.
- Soy Isolate:Defatted soy flake processing produces functional emulsification properties for meat analog applications.
- Casein Isolate:Micellar casein fractions command extended production lead times due to slow-digestion medical nutrition specifications.
Whey isolate anchors the volume base while pea isolate gains share at the steepest rate.
Application:
Cost tier stratification separates commodity nutritional supplements from formulation-intensive bakery applications where protein functionality commands premium pricing.
- Nutritional Supplements:Powder and capsule formats dominate procurement volumes with standardized solubility specifications above 90 percent. Bulk purchasing agreements from performance nutrition brands stabilize capacity utilization for dedicated spray-dryer assets across North American manufacturing networks.
- Bakery Products:Crumb structure integrity requirements create formulation complexity that hydrocolloid hybridization addresses. Water binding performance gaps versus dairy isolates currently limit substitution rates in artisan bread applications.
- Food & Beverage:Ready-to-drink formulations require instantized particle specifications for dispersion stability.
- Confectionery:Aeration and texture modification applications represent niche volume with high margin concentration.
Nutritional supplements concentrate procurement scale while bakery products present the steepest expansion trajectory for functional protein development.
End User:
Customer type fragmentation spans direct-to-consumer subscription models and institutional procurement from foodservice operators with divergent specification tolerance.
- Athletes:Performance-tier pricing structures govern isolate procurement with batch-certified purity documentation. Sports nutrition brands serving this segment enforce the tightest microbial and heavy metal thresholds, extending quality control cycle times.
- Health Conscious Consumers:Clean-label extraction protocols and organic certification status drive purchasing decisions in natural channel distribution. USDA organic transition timelines delay premium positioning for grass-fed whey and non-GMO plant isolates.
- Fitness Enthusiasts:Mid-market positioning balances cost sensitivity with protein concentration requirements.
- Culinary Professionals:Functional performance in emulsification and gelation governs ingredient selection for recipe development.
Athletes anchor the volume base through bulk procurement while health conscious consumers are expanding most quickly in plant-derived isolate adoption.
Distribution Channel:
Supply concentration diverges between direct-to-brand contracting and traditional ingredient distributor networks with divergent technical service capabilities.
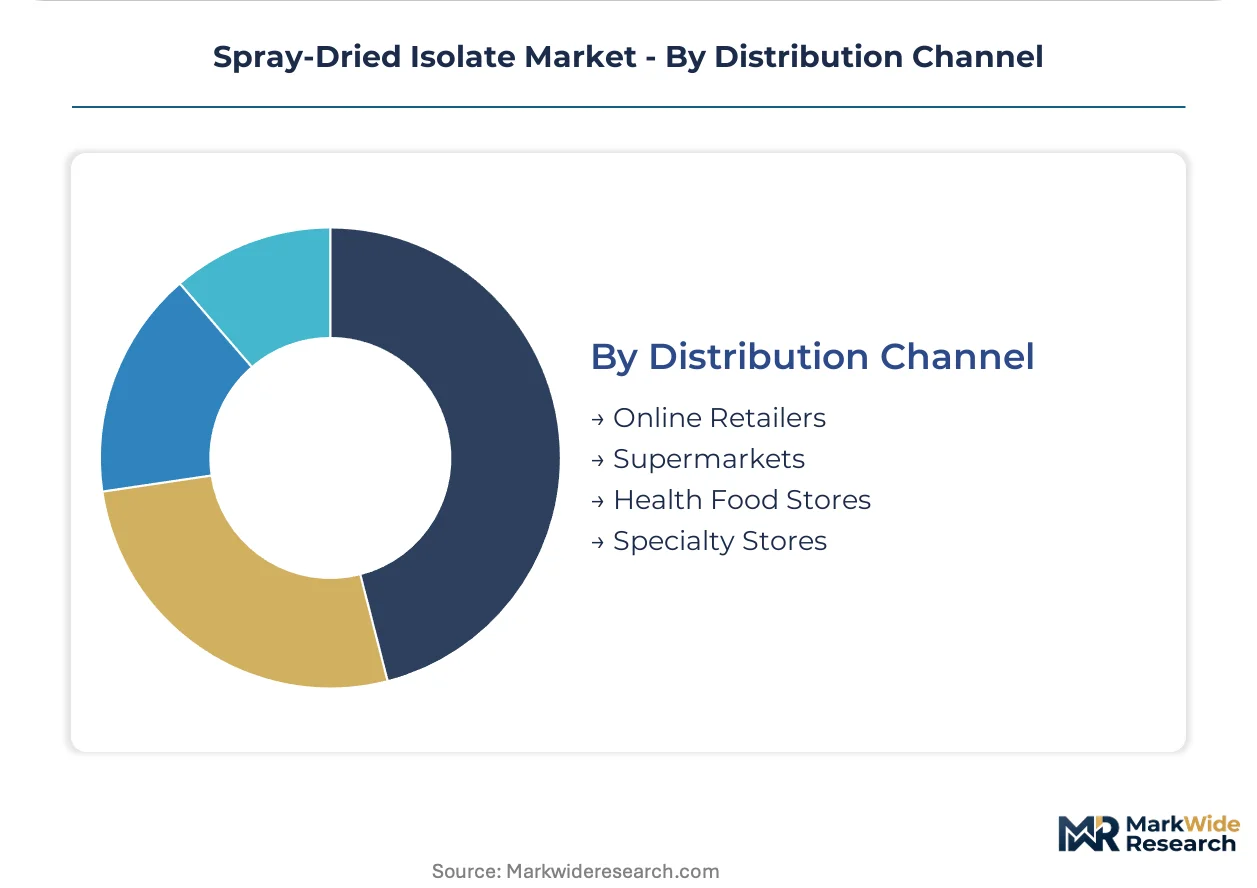
- Online Retailers:Direct-to-consumer fulfillment enables customized particle size specifications and private-label formulation services. Spray-dryer operators bypass traditional distributors here, capturing margin that intermediaries previously extracted.
- Supermarkets:Mass-market placement requires price-competitive positioning and scaled production runs that favor whey isolate commoditization.
- Health Food Stores:Natural channel placement demands organic certification and transparent sourcing documentation.
- Specialty Stores:Performance nutrition boutiques serve athlete segments with premium-tier product curation.
Online retailers anchor the volume base through procurement consolidation while specialty stores gain share fastest in premium isolate fractions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping regional sourcing strategies for spray-dried isolates. The United States maintains a structural deficit in whey isolate, drawing heavily from Oceania and European suppliers. China and India are expanding domestic spray-drying capacity to reduce import dependence for plant-derived fractions.
United States
Sports nutrition brands in the United States drive bulk procurement of whey isolate for protein powder and ready-to-drink formulations. The FDA's updated protein labeling rules tighten purity disclosure requirements, forcing reformulation cycles across beverage applications. Wisconsin and Idaho dairy processing clusters anchor whey fractionation capacity, though seasonal milk pool fluctuations constrain supply elasticity during peak demand windows.
China
Beverage manufacturers in China accelerate procurement of pea and soy isolates for allergen-free product lines targeting health-conscious urban consumers. SAMR enforces GB standards for protein content and microbial limits that disqualify unqualified exporters, raising compliance costs for cross-border shipments. Shandong Province and Jiangsu Province host expanding spray-drying facilities for plant-derived isolates, with local processors capturing share from imported whey fractions.
India
Domestic food brands in India scale procurement of spray-dried isolates for nutritional supplements and bakery reformulations. The PLI scheme for food processing accelerates capital deployment into spray-drying capacity, reducing import dependence for protein ingredients. Maharashtra and Gujarat dairy cooperatives expand whey fractionation infrastructure, while Karnataka and Telangana emerge as hubs for pea and mung bean isolate processing.
Germany
European beverage manufacturers in Germany prioritize pea isolate procurement for clean-label reformulations targeting allergen-sensitive consumers. EFSA novel food assessments govern market access for emerging plant isolates, extending approval timelines for fava bean and chickpea fractions. Bavaria and North Rhine-Westphalia concentrate enzymatic separation technology providers serving reformulation pipelines across the European Union.
Brazil
Food processors in Brazil expand soy isolate production for domestic meat analog and bakery applications while importing whey fractions for sports nutrition. ANVISA regulates protein content claims and import eligibility, creating compliance barriers for unqualified suppliers. São State's soy processing corridor anchors defatted flake production, with emerging spray-drying investments targeting Mercosur export markets.
Spray-Dried Isolate Market Competitive Landscape
On the supply side, the industry is consolidating around integrated dairy cooperatives and diversified ingredient conglomerates with captive spray-drying assets. Three strategic archetypes dominate: backward-integrated dairy processors controlling grass-fed milk pools, enzymatic separation technology licensors, and contract spray-dryer operators serving direct-to-brand distribution channels. Competitive intensity centers on capacity expansion in high-throughput atomization chambers and geographic diversification of plant-derived feedstock sourcing.
Among Irish-domiciled nutrition ingredient groups, Kerry Group plc and Glanbia plc exemplify divergent strategic positioning within the whey isolate segment. Kerry Group plc occupies a technology-forward position leveraging enzymatic separation methods for premium fractionation, while Glanbia plc anchors North American manufacturing scale around dedicated dryer assets for sports nutrition procurement consolidation. Fonterra Co-operative Group Limited represents the cooperative archetype, with New Zealand-based backward integration into grass-fed milk supply chains controlling raw protein quality from farm to dryer.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Kerry Group plc |
| Glanbia plc |
| FrieslandCampina |
| Fonterra Co-operative Group Limited |
| DSM-Firmenich |
| Ingredion Incorporated |
| Sensient Technologies Corporation |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Shandong Province spray-drying corridors is compressing spot pricing for pea isolate fractions while forcing contract renegotiations across Pacific export lanes. Utilization rates below 70 percent at regional atomization facilities are driving suppliers toward volume-commitment pricing models that sacrifice margin for capacity coverage.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the whey isolate segment. Price differentiation stems from USDA organic certification status and sports nutrition brand volume scale, with premium tiers commanding 40-60 percent uplifts for grass-fed sourcing documentation. Cost compression in standard-grade whey fractions is intensifying because Fonterra's seasonal milk pool fluctuations create spot market volatility. Health-conscious consumers in natural channels exhibit the lowest price sensitivity, while mass-market supermarket procurement teams drive aggressive commoditization pressure.
Supply Chain Analysis
Contract spray-drying concentration rests with Glanbia's North American dryer network and Kerry Group's enzymatic separation facilities across Ireland and Wisconsin. Geographic supply concentration centers on New Zealand for grass-fed whey feedstock, China for pea protein aqueous extraction, and India for mung bean isolate fractionation under PLI scheme incentives. Raw material dependencies include yellow pea protein concentrate, micellar casein curd, and defatted soy flake. Single-source vulnerability in Oceania milk pools creates procurement risk during Southern Hemisphere drought cycles. Distribution runs through direct-to-brand contracting with sports nutrition OEMs, bypassing traditional ingredient distributors for customized particle specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spray-dried isolate market is cycling through a capacity absorption phase as China's 2023-2024 spray-dryer buildouts clear utilization hurdles. Recovery trajectory hinges on EFSA novel food approvals unlocking European beverage reformulation pipelines.
For Market Incumbents: Build certification moats around USDA organic and Non-GMO Project verification to defend against commodity whey price erosion. Incumbents should deepen backward integration into named grass-fed milk pools in New Zealand and Idaho dairy clusters, while accelerating enzymatic separation R&D to maintain premium positioning against acid-precipitation competitors from India. For New Entrants and Emerging Players: India's bakery application segment offers the most penetrable white space, where hydrocolloid-spray dried hybrid formulations remain unresolved for crumb structure integrity. New entrants should target direct-to-brand distribution contracts with mid-tier sports nutrition labels seeking customized particle sizes, leveraging Karnataka's emerging pea isolate processing hub as a cost-competitive feedstock base. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plant-derived isolate sub-segments as aqueous separation equipment and membrane filtration systems compress facility economics. Long-term viability favors acquiring enzymatic technology licensors with EFSA dossier pipelines rather than pure-play dryer operators. The signal to watch is SAMR enforcement actions against unqualified exporters, which would accelerate consolidation toward compliant integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grass-Fed Milk Pools | Fonterra's farm-to-dryer control locks in premium whey isolate feedstock quality for sports nutrition brands. |
| EFSA Novel Food Dossier Investment | First-mover clearance for fava bean and chickpea isolates secures European beverage reformulation partnerships. |
| Direct-to-Brand Distribution Bypass | Spray-dryer operators capture distributor margins by contracting directly with performance nutrition OEMs for custom specifications. |
| Enzymatic Separation Technology Licensing | Kerry Group's IP portfolio enables premium fractionation beyond legacy acid precipitation methods. |
| PLI Scheme Capacity Expansion in India | Domestic spray-dryer deployment under Maharashtra and Gujarat incentives reduces import dependence for South Asian brands. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with spray-dryer operations managers, sports nutrition procurement directors, and FSSAI compliance officers; and secondary validation through FDA protein labeling guidance documents, SAMR GB standard publications, EFSA novel food assessment registers, and customs trade data for whey and pea isolate shipments. Bottom-up capacity modeling across atomization facilities in Wisconsin, Idaho, Shandong, and Maharashtra was triangulated against top-down procurement volume estimates from North American sports nutrition brands.
Forecast inputs considered protein source segmentation, application functionality requirements, and end-user price sensitivity tiers across the projection horizon. The analytical framework modeled whey isolate, pea isolate, soy isolate, and casein isolate trajectories alongside bakery, nutritional supplement, and beverage application channels. CAGRs were derived from capacity utilization curves and procurement commitment visibility windows. Industry-specific inputs included EFSA approval timelines for novel plant proteins and India's PLI scheme disbursement velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-sponsored processors or enzymatic technology licensors would shift outcomes beyond modeled ranges. Forecasts reflect assumptions around SAMR enforcement consistency and EFSA dossier clearance cadence. Quarterly review of capacity utilization signals in Shandong Province and EFSA novel food assessment queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
France Soy Protein Market
Ingredients
Cacao Bean Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Organic Pastry Flour Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Europe Feed Yeast Market
Ingredients
Canola Oil Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Pine Needle Oil Market
Ingredients
Wheat Malt Market
Ingredients
Fruit Pectin Market
Ingredients
Fruit Concentrate Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Potato Granules Market