
 Europe Soy Protein Market | 2026-2036
Europe Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soy Protein Market Foresight
Consolidation among European plant-based meat startups is repositioning procurement leverage toward larger soy protein suppliers. Archer Daniels Midland Company leverages its crushing and extraction infrastructure across the Netherlands and Germany to secure supply continuity for food manufacturers. Cargill, Incorporated anchors its European position through identity-preserved soybean sourcing programs that trace non-GMO varieties from farm to isolate. Roquette Frères differentiates via pea-soy protein blending expertise, competing for clean-label formulations in France and Belgium.
Europe soy protein encompasses defatted soybean meal processed into isolates, concentrates, and textured forms with protein contents ranging from 50% to 90% on a dry-weight basis, serving primarily as functional ingredients in meat analogues, sports nutrition, and animal feed. Textured soy protein dominates volume flows into meat alternatives, where hydration and fibrous structure replication command premium formulation slots. Soy isolate leads margin pools in sports nutrition and clinical dietary supplements, where amino acid completeness and low carbohydrate residuals justify higher unit economics. Protein fortification applications in bakery and dairy alternatives represent the fastest-expanding demand corridor, driven by flexitarian consumers seeking partial animal protein substitution without sensory compromise.
EFSA maintains strict novel food and allergen labeling requirements that govern soy protein inclusion thresholds and cross-contamination warnings across EU member states. REACH and EU Green Deal agricultural targets are redirecting subsidy flows toward domestic protein crop cultivation, tightening import dependency calculations for soy processors. The F-Gas Regulation indirectly affects isolate production through solvent recovery system mandates in hexane-based extraction facilities. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their documentation burdens on South American soybean origins.
Market Dynamics
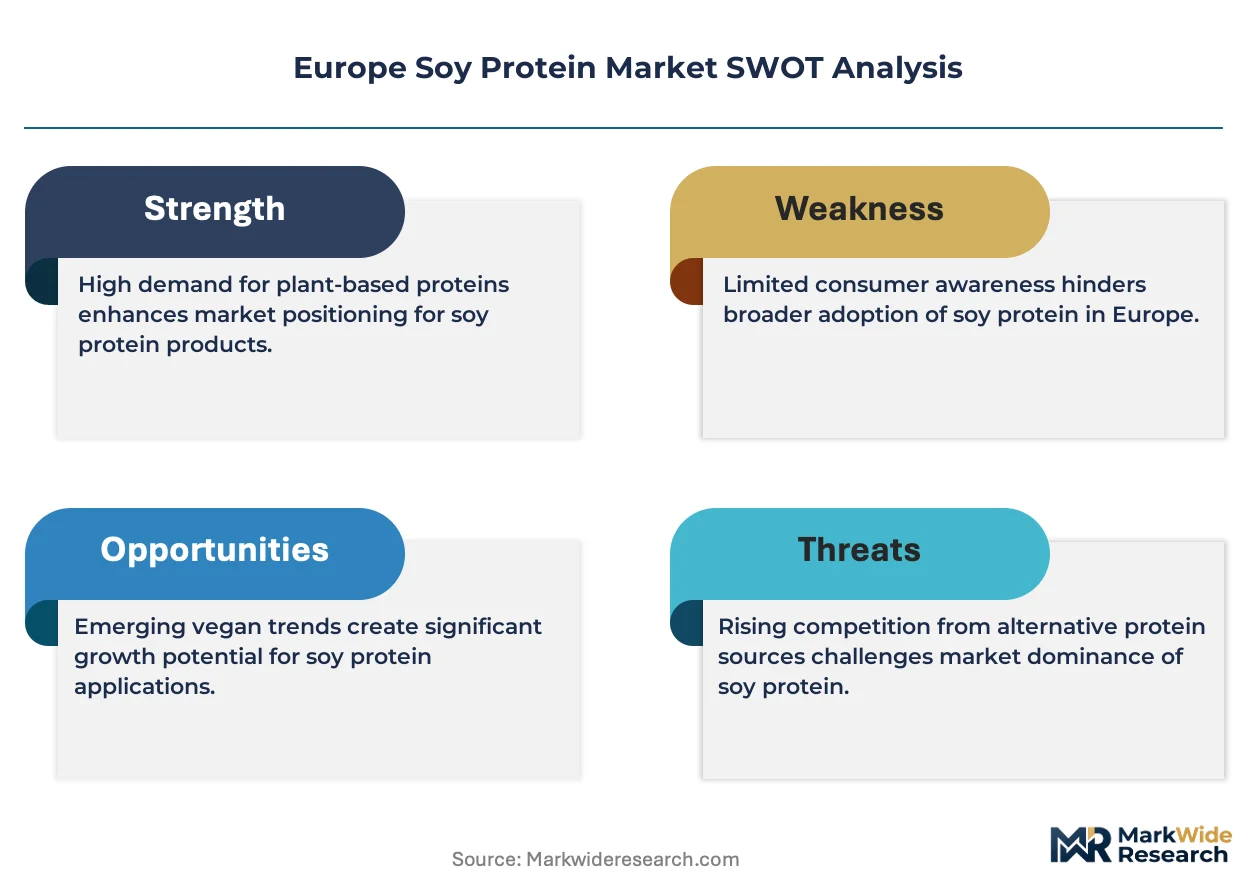
EFSA novel food authorizations and EU Green Deal protein diversification mandates are compressing formulation timelines for European meat analogue manufacturers, forcing simultaneous compliance with allergen labeling thresholds and sustainability sourcing documentation.
Growth Catalysts
- EU Green Deal protein targets:Subsidy flows toward domestic protein crop cultivation are accelerating textured soy protein adoption in German and Dutch plant-based meat facilities.
- Flexitarian consumption patterns:Partial animal protein substitution without sensory compromise is expanding soy isolate demand in French and Belgian bakery fortification applications.
- REACH solvent recovery mandates:Hexane-based extraction facility upgrades are isolating technical leaders capable of isolate production at food-grade purity thresholds.
Market Restraints
- South American supply concentration:EU deforestation-free supply chain regulations impose documentation burdens on Brazilian and Argentinian soybean origins, tightening import dependency calculations.
- Pea protein substitution threat:Roquette Frères and other processors are advancing pea-soy protein blends that capture clean-label formulation slots in France and Belgium.
- F-Gas Regulation compliance costs:Solvent recovery system mandates for hexane-based extraction facilities are elevating capital requirements for isolate production scale-up.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania present formulation white space where traditional meat consumption patterns remain dominant but retailer sustainability specifications are emerging.
- Sports nutrition channel expansion:Amino acid completeness and low carbohydrate residuals in soy isolate are capturing premium positioning in German and Dutch clinical dietary supplement distribution.
- Identity-preserved sourcing programs:Non-GMO variety traceability from farm to isolate is converging with retailer procurement specifications to create margin differentiation for compliant suppliers.
Industry Challenges
- Cross-contamination compliance timelines:EFSA allergen labeling thresholds require facility segregation investments that compress production scheduling flexibility for multi-ingredient processors.
- Food technologist talent scarcity:Meat analogue formulation expertise combining hydration science and fibrous structure replication remains concentrated in German and Netherlands research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soy Protein Market |
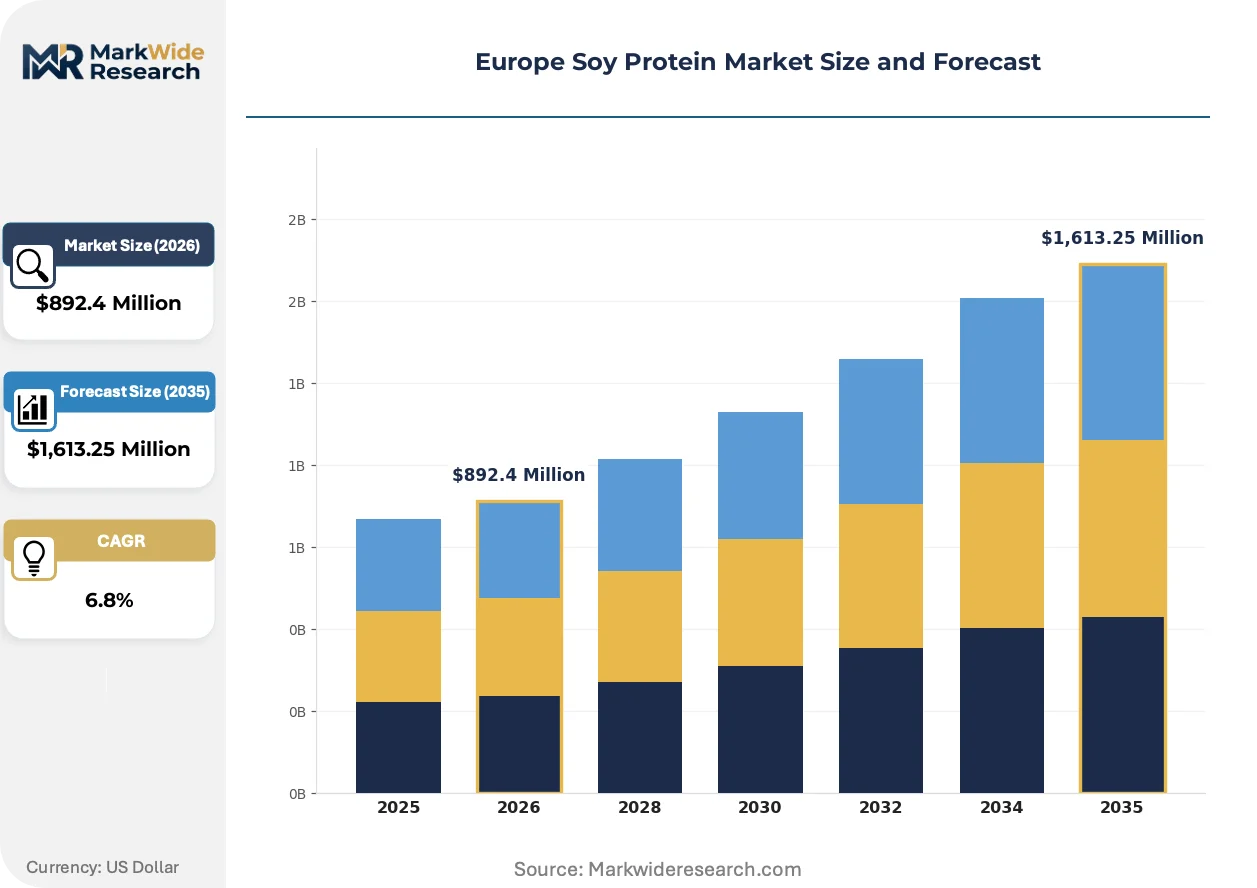
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Soy Protein, Soy Isolate, Soy Flour, Concentrates End User: Food Industry, Dietary Supplements, Animal Feed, Pharmaceuticals Form: Powder, Granules, Flakes, Protein Bars Application: Meat Alternatives, Protein Fortification, Functional Foods, Nutraceuticals |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, DuPont, Kerry Group plc, Wilmar International Limited, Roquette Frères, CHS Inc., The Scoular Company, Fuji Oil, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soy Protein Market Shifts & Advancements
Novel extraction technologies and regulatory documentation requirements are simultaneously elevating capital barriers and rewarding technical specialization among European soy protein processors.
Enzyme-assisted aqueous extraction is converging with traditional hexane-based methods to reduce solvent residuals in soy isolate destined for infant nutrition and clinical dietary applications. Dutch food technologists are piloting these hybrid processes at semi-commercial scale. The structural consequence is compressing margin pools for conventional extraction-only facilities while rewarding integrated processors with patent-protected enzyme portfolios.
EFSA maintains strict novel food authorization pathways that govern protein content claims and allergen cross-contamination warnings across EU member states. These requirements are elevating documentation burdens for South American soybean imports under evolving deforestation-free supply chain regulations. German and Dutch manufacturers are responding by accelerating identity-preserved sourcing program adoption to preempt regulatory enforcement timelines.
Retailer sustainability specifications are compressing procurement cycles for textured soy protein used in meat analogue formulations. French and Belgian supermarket chains are displacing traditional commodity purchasing with batch-level carbon footprint documentation requirements. This shift is most visible in Germany, where Aldi and Lidl sustainability scorecards now weight soy protein sourcing transparency above unit cost in supplier selection protocols.
Europe Soy Protein Market Segmentation
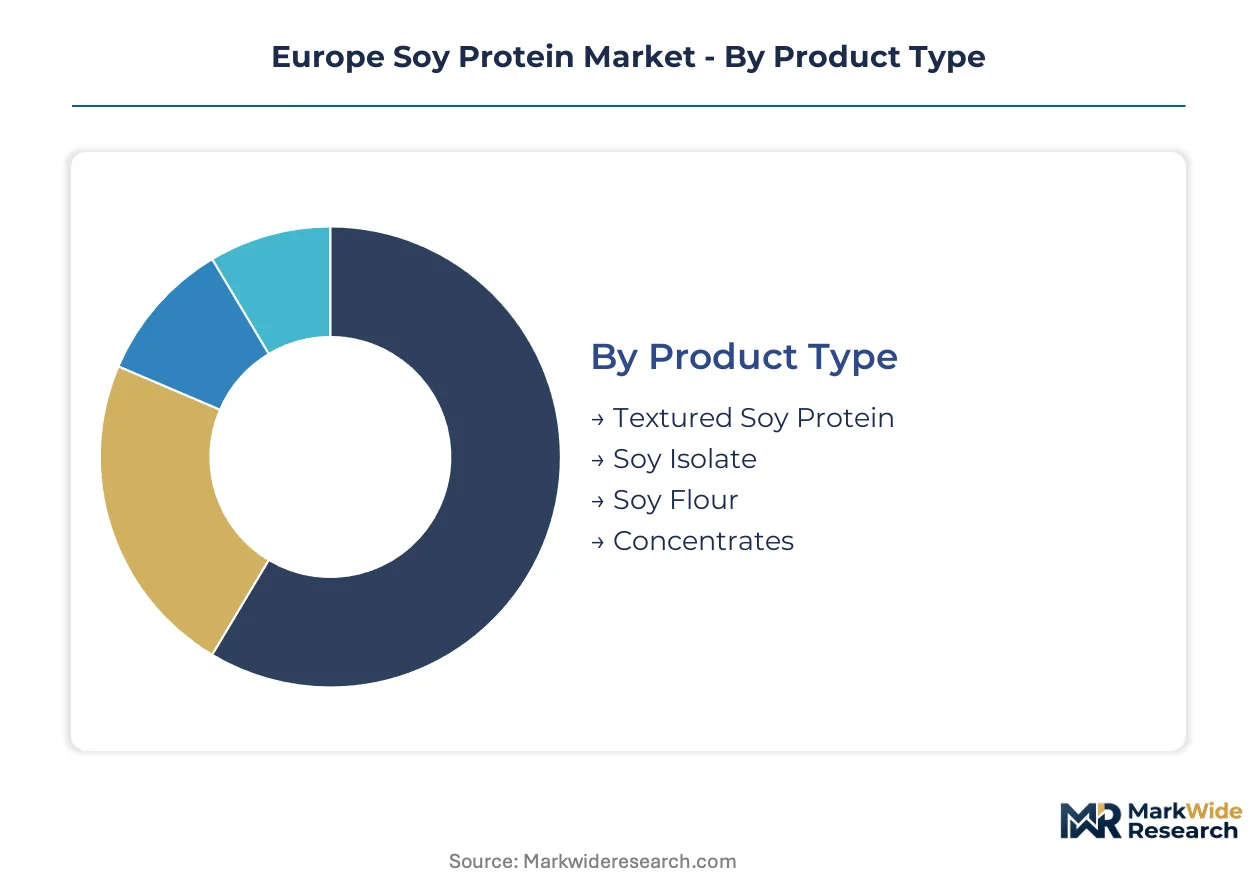
European soy protein procurement decisions pivot on protein purity thresholds and functional performance specifications. Formulators weigh hydration capacity against allergen labeling burdens when selecting across isolate, concentrate, and textured grades.
Product Type:
Buyers prioritize protein content gradients against formulation flexibility requirements when selecting across extraction grades.
- Textured Soy Protein:Defatted soy flour extruded into fibrous matrices achieves 50-70% protein content with sponge-like hydration properties. German plant-based meat manufacturers specify this grade for burger and sausage analogues where bite texture replication commands premium slots. EFSA allergen thresholds and EU Green Deal sourcing documentation compress procurement timelines for this volume-leading segment.
- Soy Isolate:Alkaline extraction and isoelectric precipitation yield 90%+ protein content with minimal carbohydrate residuals. Dutch sports nutrition and clinical dietary supplement channels absorb this highest-margin grade, where amino acid completeness justifies unit cost premiums over concentrate alternatives.
- Soy Flour:Full-fat or defatted milling produces 40-50% protein content for bakery fortification and cost-sensitive applications.
- Concentrates:Aqueous alcohol washing achieves 65-85% protein content, occupying a functional middle ground between flour and isolate economics.
Volume sits with Textured Soy Protein; growth tilts toward Soy Isolate.
End User:
Customer procurement sophistication varies sharply across food manufacturing versus clinical and feed applications.
- Food Industry:Meat analogue manufacturers in Germany and the Netherlands drive specification-grade demand for textured and isolate forms. Retailer sustainability scorecards at Aldi and Lidl now weight batch-level carbon footprint documentation above unit cost in supplier selection protocols.
- Dietary Supplements:Sports nutrition and clinical dietary channels in France and Belgium absorb isolate grades where low carbohydrate residuals and complete amino acid profiles command premium positioning.
- Animal Feed:Compound feed manufacturers utilize defatted meal and lower-protein concentrates for aquaculture and poultry ration formulations.
- Pharmaceuticals:Specialized excipient and parenteral nutrition applications require isolate grades meeting pharmacopeial purity standards.
Food Industry commands current volume; Dietary Supplements are climbing the fastest.
Form:
Handling characteristics and reconstitution speed dictate form selection across manufacturing environments.
- Powder:Fine-milled isolates and concentrates dominate industrial-scale blending operations for beverages, bars, and analogue formulations.
- Granules:Intermediate particle size optimizes hydration kinetics for meat analogue extrusion lines in Dutch and German facilities.
- Flakes:Textured soy protein in flake form serves rehydration-intensive applications where fibrous structure replication is prioritized.
- Protein Bars:Pre-formulated bar formats capture convenience-oriented sports nutrition channels with minimal processing requirements.
Powder leads installed base; granules are expanding most quickly in meat analogue manufacturing.
Application:
End-use performance requirements segment demand across sensory replication versus nutritional fortification priorities.
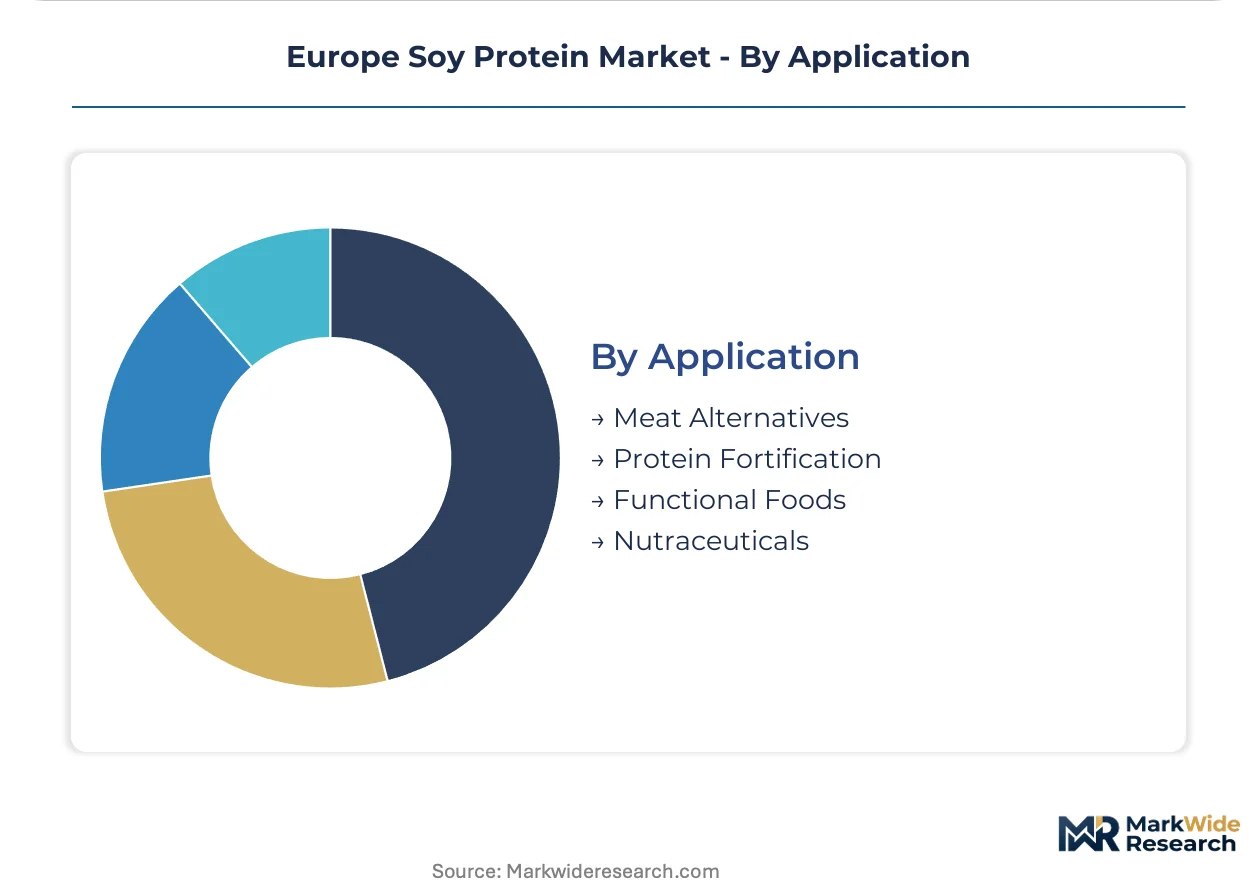
- Meat Alternatives:Textured soy protein with calibrated hydration and fibrous structure replication anchors German and Dutch plant-based burger and sausage formulations. EFSA novel food authorizations and retailer sustainability specifications compress development timelines for this application corridor.
- Protein Fortification:Bakery, dairy alternative, and beverage applications in France and Belgium drive isolate and concentrate demand among flexitarian consumers seeking partial animal protein substitution without sensory compromise.
- Functional Foods:Cholesterol-lowering and menopausal health positioning leverages soy isoflavone content in specialized product development.
- Nutraceuticals:Capsule and tablet formulations utilize isolate grades for targeted protein supplementation protocols.
Meat Alternatives anchor current volume; Protein Fortification shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South American soybean crushing infrastructure feeds Dutch and German extraction facilities that dominate European isolate production. EFSA novel food pathways and REACH solvent recovery mandates compress operational timelines for processors serving meat analogue manufacturers.
Germany
Plant-based meat manufacturers in Cologne and Hamburg drive specification-grade textured soy protein demand for burger formulations. EFSA allergen labeling thresholds require facility segregation investments that elevate compliance costs for multi-ingredient processors. The Ruhr industrial corridor concentrates extrusion capacity serving Aldi and Lidl sustainability scorecards.
Netherlands
Rotterdam port infrastructure anchors identity-preserved soybean import flows for non-GMO isolate production. REACH hexane recovery mandates are isolating technical leaders capable of food-grade purity thresholds. Wageningen food technology clusters pilot enzyme-assisted aqueous extraction at semi-commercial scale.
France
Flexitarian consumption in Paris and Lyon expands soy isolate demand for bakery fortification and dairy alternatives. EU Green Deal protein diversification targets redirect subsidy flows toward domestic protein crop cultivation. Roquette Frères anchors pea-soy blending expertise in Lille for clean-label formulation slots.
Belgium
Retail procurement specifications at Colruyt and Delhaize compress sourcing cycles for textured soy protein with batch-level carbon footprint documentation. EFSA novel food authorizations govern protein content claims in meat analogue formulations. Antwerp logistics hubs facilitate South American soybean distribution to German processors.
Poland
Traditional meat consumption patterns in Warsaw and Krakow present formulation white space as retailer sustainability specifications emerge. EU deforestation-free supply chain regulations impose documentation burdens on Brazilian soybean origins entering Baltic ports. Poznan food manufacturing clusters attract investment in extrusion capacity for Central European distribution.
Europe Soy Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enzyme-assisted extraction patents and identity-preserved sourcing programs. The supplier base concentrates around crushing-extraction integrated operations and specialized isolate refiners. Three archetypes dominate: agricultural commodity traders with downstream processing assets, European family-owned processors with regional formulation expertise, and Asian integrated oilseed crushers with export-oriented isolate capacity. Competitive moves center on backward integration into identity-preserved soybean origination and capacity expansion in enzyme-assisted aqueous extraction.
Among North American agricultural conglomerates, Archer Daniels Midland Company and Cargill, Incorporated exemplify the integrated commodity-processor archetype with European crushing infrastructure. Roquette Frères occupies a position representing European specialized processors with blending expertise in pea-soy formulations. These three anchors illustrate divergent strategic positions: commodity scale versus regional formulation specialization versus hybrid legume integration.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| DuPont |
| Kerry Group plc |
| Wilmar International Limited |
| Roquette Frères |
| CHS Inc. |
| The Scoular Company |
| Fuji Oil |
| Others |
Supply & Pricing Matrix
Food technologist concentration in Wageningen and Cologne research clusters compresses labor-cost differentials into premium-mid-economy pricing spreads across extraction grades. REACH solvent recovery mandates and EFSA allergen compliance investments widen tier separation between integrated processors and commodity traders.
Pricing Analysis
Volume sits with textured soy protein at economy-tier contract structures; margins concentrate in soy isolate grades serving Dutch sports nutrition channels. Price differentiation hinges on EFSA novel food authorization status and identity-preserved non-GMO certification from South American origins. Cost compression in standard-tier concentrates is intensifying because Roquette Frères and European blenders are advancing pea-soy hybrid formulations. Food industry buyers at Aldi and Lidl show lowest price sensitivity where sustainability scorecards dominate procurement; compound feed manufacturers exhibit highest sensitivity to protein-content-per-euro metrics.
Supply Chain Analysis
South American soybean supply rests on Brazilian and Argentinian crushing infrastructure feeding Rotterdam port terminals. Hexane solvent and food-grade enzyme inputs draw from German and Dutch specialty chemical producers. Single-source vulnerability concentrates in Brazilian origin documentation under EU deforestation-free regulations. Distribution runs through Antwerp logistics hubs to German extrusion facilities and French bakery ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating across European soy protein processing as REACH capital requirements and EFSA compliance timelines force sub-scale operators toward exit or acquisition.
For Market Incumbents: Lock in identity-preserved sourcing programs with Brazilian non-GMO cooperatives before EU deforestation-free enforcement tightens. Expand enzyme-assisted aqueous extraction capacity in the Netherlands to capture infant nutrition and clinical dietary premium tiers. Pea protein substitution from Roquette Frères and clean-label blenders threatens isolate margins in French bakery applications. For New Entrants and Emerging Players: Enzyme-assisted extraction patents at semi-commercial scale offer a technology-first wedge into Polish and Romanian meat analogue formulation white space. Target retailer sustainability specification emergence in Warsaw and Krakow before Aldi and Lidl scorecard adoption accelerates. Go-to-market through Poznan extrusion capacity partnerships bypasses German facility saturation. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale Dutch and German processors possessing REACH-compliant hexane recovery systems given EFSA novel food authorization backlogs. Five-to-ten year viability favors integrated crushers with downstream isolate refining and identity-preserved origination programs. Watch enzyme-assisted aqueous extraction patent grants as inflection signal for technical-leader premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Identity-Preserved Origination | Non-GMO Brazilian farm partnerships preempt EU deforestation-free documentation burdens. |
| Enzyme-Assisted Aqueous Extraction Scale-Up | Hybrid processing reduces solvent residuals for EFSA infant nutrition approvals. |
| Pea-Soy Protein Blending Capacity Expansion | Roquette Frères expertise in Lille captures French clean-label formulation demand. |
| REACH Hexane Recovery System Investment | Technical compliance isolates food-grade purity leaders from commodity processors. |
| Eastern European Distribution Partnership | Polish and Romanian retailer sustainability emergence opens pre-saturation growth corridors. |
Research Methodology
Multi-period observation of EFSA novel food authorization timelines and EU Green Deal subsidy disbursements anchored the trend analysis, supplemented by interviews with Dutch food technologists, German plant-based meat procurement directors, French bakery ingredient formulators, and Belgian retail category managers. Secondary validation drew from REACH regulatory filings, EFSA scientific opinions, EU Commission agricultural statistics, and customs trade data for South American soybean flows. Bottom-up capacity modeling across Dutch and German extraction facilities triangulated against top-down protein diversification target assessments.
Segment-weighting applied product-type splits across textured protein, isolate, concentrate, and flour grades crossed with end-user channels including food manufacturing, dietary supplements, animal feed, and pharmaceuticals. Deployment form and application segmentation further disaggregated volume. CAGR derivation combined historical procurement pattern analysis with forward projection of retailer sustainability specification adoption and flexitarian consumption trajectory shifts. Enzyme technology penetration curves and identity-preserved sourcing program expansion served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced EFSA regulatory amendments, abrupt Brazilian export policy shifts, and pea protein cost-parity breakthroughs. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and REACH enforcement consistency. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Hydrolyzed Egg Market
Ingredients
Gymnema Extract Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Dry Molasses Products Market
Ingredients
Glucomannan Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Corn Starch Market
Ingredients
Glucuronolactone Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
India Olive Oil Market
Ingredients
Ahiflower Oil Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Europe Agar Market
Ingredients
Europe Protein Market
Ingredients
Protein Ingredients Market