
 Global Antimicrobial (Enzymatic) Protein Hydrolysates Market | 2026-2036
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market Analysis
Modular formulation kits that pair enzymatic hydrolysates with carrier systems are expanding buyer flexibility across cosmetic and pharmaceutical channels. Kerry Group leverages its flavor and nutrition platform to anchor hydrolysate supply contracts with multinational food manufacturers. AMCO Proteins specializes in custom enzymatic processing configurations for clients requiring specific peptide chain lengths. BRF Ingredients dominates South American meat hydrolysate output, sustaining regional supply advantages through integrated rendering operations.
Antimicrobial (enzymatic) protein hydrolysates comprise bioactive peptide fractions generated through controlled proteolysis of fish, plant, meat, or microbial proteins, typically yielding oligopeptides between 2-20 amino acid residues with demonstrated bacteriostatic or bactericidal properties against Gram-positive and Gram-negative pathogens. These hydrolysates function as natural preservation agents, therapeutic delivery vehicles, and functional cosmetic actives that replace synthetic biocides in regulated consumer products. Fish hydrolysates command premium positioning in pharmaceutical applications where marine bioactive peptides demonstrate superior cell membrane penetration against drug-resistant bacterial strains. Plant hydrolysates from soy and pea protein sources are gaining fastest in cosmetic formulations as vegan certification requirements harden across European and North American markets. Powder forms retain dominant share in dietary supplements due to extended shelf stability and standardized dosing precision, though liquid concentrates are penetrating food preservation lines for inline processing efficiency.
FDA food additive regulations and EFSA novel food ingredient frameworks jointly determine market access timelines for new hydrolysate compositions in North America and Europe. REACH chemical registration requirements in the European Union impose toxicological documentation burdens on hydrolysate suppliers targeting cosmetic and pharmaceutical end uses. Japan's PMDA maintains distinct peptide therapeutic classification standards that influence export specifications for hydrolysates entering East Asian healthcare markets. Stakeholders must monitor evolving antimicrobial resistance labeling protocols across FDA, EMA, and WHO guideline revisions to anticipate reformulation mandates before compliance deadlines crystallize.
Market Dynamics
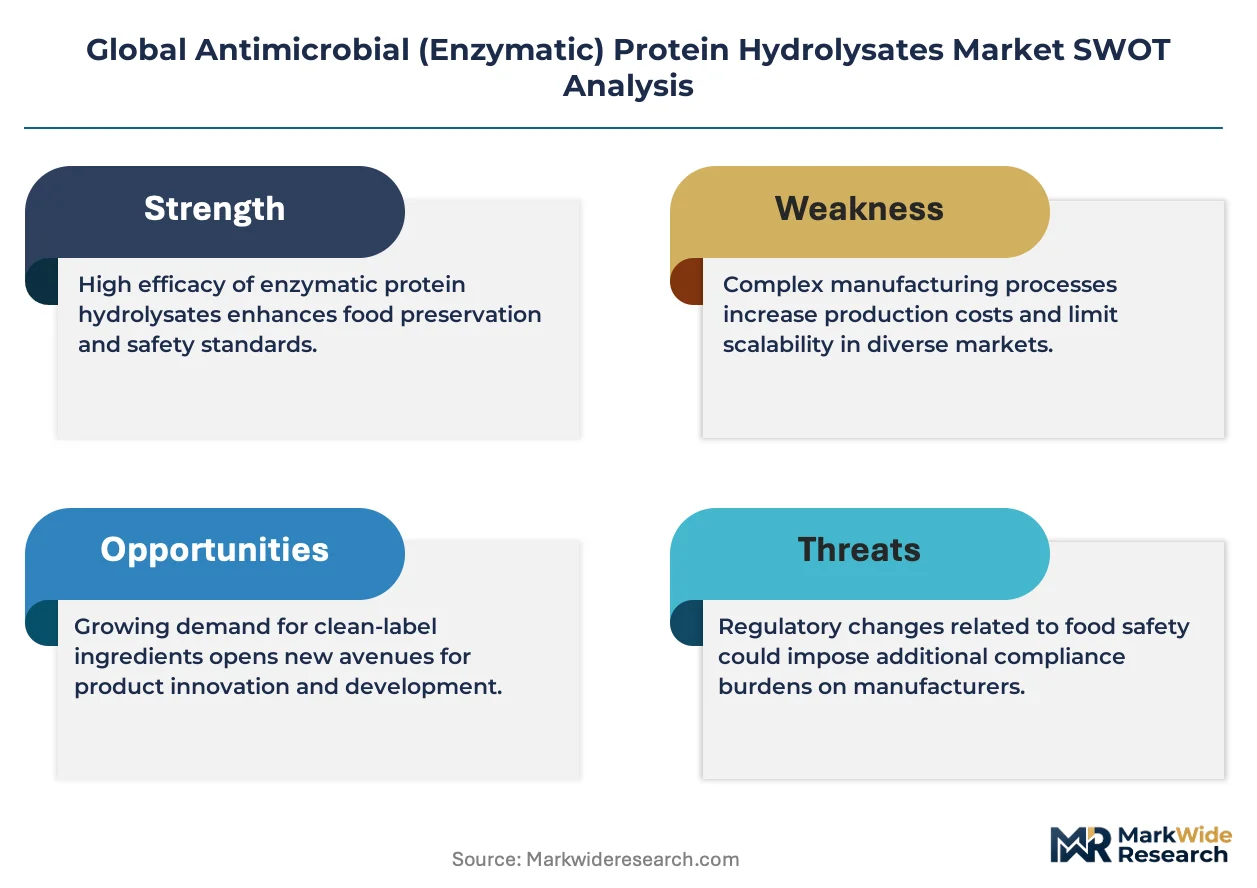
Enzymatic hydrolysate producers face mounting pressure from EFSA's tightening novel food ingredient purity benchmarks, which are compressing market access timelines and forcing reformulation investments across European pharmaceutical and nutraceutical channels.
Growth Catalysts
- Clean-label food preservation mandates:North American food manufacturers are absorbing larger volumes of fish-derived hydrolysates as synthetic preservatives face retailer blacklists and consumer rejection.
- REACH compliance reformulation:German cosmetics manufacturers are redesigning antimicrobial peptide products to meet skin-contact chemical safety requirements, creating specialized demand for documented peptide chain specifications.
- Marine bioactive peptide superiority:Pharmaceutical formulators prioritize fish hydrolysates for drug-resistant bacterial strain applications where cell membrane penetration determines therapeutic efficacy.
Market Restraints
- Raw material concentration risk:South American meat hydrolysate supply concentrates through integrated rendering operations controlled by dominant regional processors.
- EFSA evaluation timeline friction:Novel food ingredient safety assessments extend market entry delays by 18-36 months for new enzymatic compositions targeting European pharmaceutical channels.
- Plant protein yield limitations:Soy and pea hydrolysate peptide recovery rates lag marine sources by 15-25% on a mass basis, constraining cost-competitive scale-up.
Strategic Opportunities
- Japan PMDA peptide therapeutic classification:Export specification alignment for East Asian healthcare markets opens differentiated positioning for documented bioactive peptide fractions.
- Vegan certification acceleration:European and North American cosmetic formulators are sourcing plant hydrolysates to replace marine-derived actives in certified vegan product lines.
- Liquid concentrate inline processing:Food preservation manufacturers are adopting pumpable hydrolysate formats to eliminate powder rehydration steps and reduce sanitation downtime.
Industry Challenges
- Peptide characterization skill scarcity:Analytical chemists capable of validating specific amino acid residue sequences against bactericidal potency claims command premium compensation and extended recruitment timelines.
- Multiregional registration capital intensity:Simultaneous FDA food additive petitions, EFSA novel food dossiers, and PMDA therapeutic peptide filings require dedicated regulatory affairs infrastructure exceeding mid-tier producer budgets.
- Antimicrobial resistance labeling protocol uncertainty:Evolving WHO guideline revisions on resistance claim substantiation force speculative reformulation investments before compliance deadlines crystallize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antimicrobial (Enzymatic) Protein Hydrolysates Market |
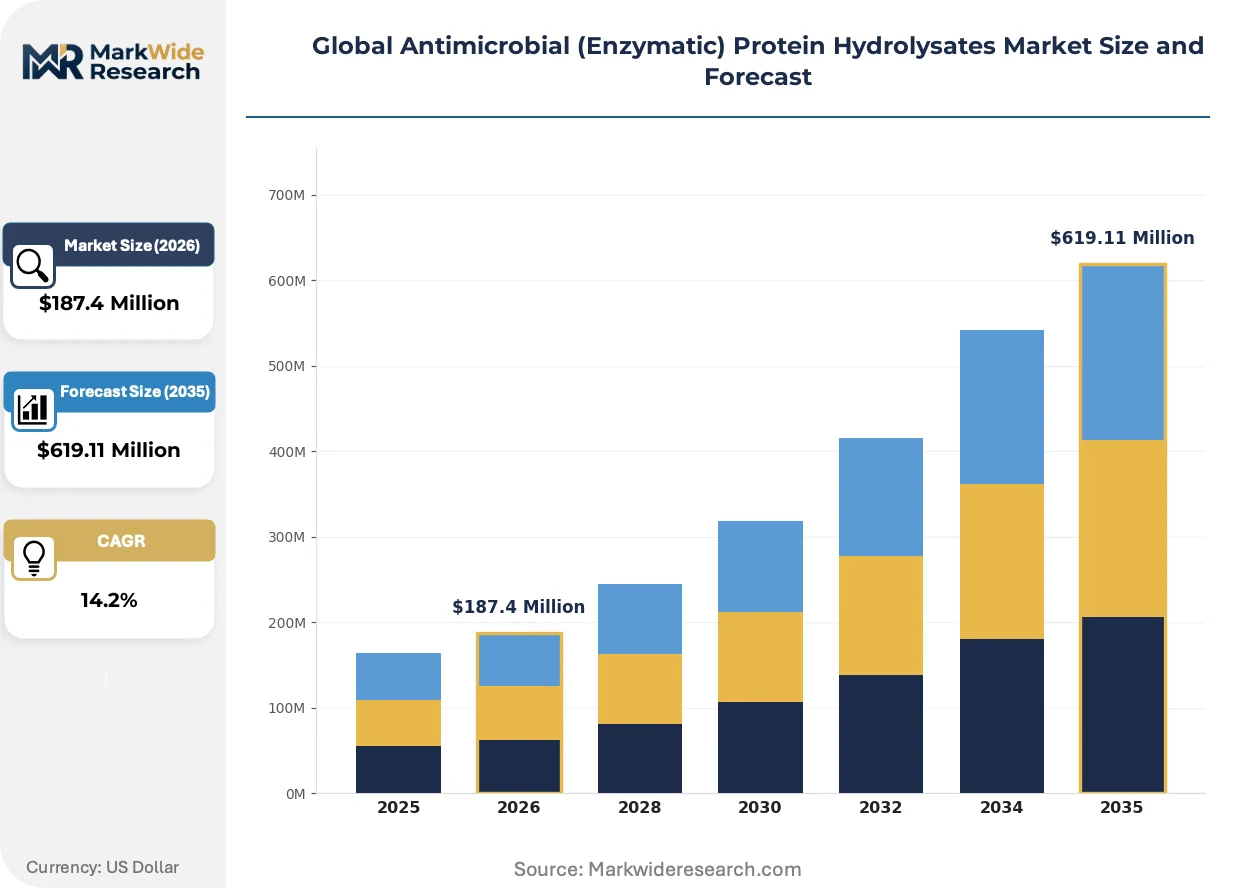
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Hydrolysates, Plant Hydrolysates, Meat Hydrolysates, Microbial Hydrolysates Application: Food Preservation, Pharmaceuticals, Cosmetic Formulations, Dietary Supplements Form: Liquid, Powder, Granules, Capsules End User: Food Industry, Healthcare Providers, Cosmetics Manufacturers, Nutraceutical Companies |
| Companies Covered | A Constantino & C Spa, Aker Biomarine, AMCO Proteins, Biomega Group, BRF Ingredients, Arla Foods Ingredients, Kerry Group, Archer Daniels Midland Company, Koninklijke DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market Emerging Trajectories
Controlled proteolysis systems are fragmenting along substrate specificity lines, with equipment manufacturers and enzyme suppliers co-developing modular platforms that shorten peptide optimization cycles for end-use specific applications.
Membrane filtration-coupled enzymatic reactors are expanding into pharmaceutical-grade hydrolysate production. These integrated systems enable real-time molecular weight cutoff adjustment during proteolysis. Contract manufacturers serving drug delivery peptide suppliers are adopting this configuration to reduce downstream purification steps and improve batch-to-batch potency consistency.
REACH chemical registration requirements are tightening toxicological documentation burdens for hydrolysate suppliers targeting European cosmetic and pharmaceutical end uses. ECHA's updated guidance on proteinaceous substance classification demands expanded skin sensitization data packages. German and French formulators are consolidating supplier bases to those with pre-submitted registration dossiers, compressing vendor qualification timelines.
Cosmetic brand procurement teams are unbundling peptide sourcing from turnkey formulation services, creating direct contracting relationships with enzymatic hydrolysate specialists. This disintermediation bypasses traditional ingredient distributors in premium skin-care segments. The shift is most visible in German and French markets where clean-label positioning commands shelf price premiums and supply chain transparency requirements have hardened.
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market Segmentation
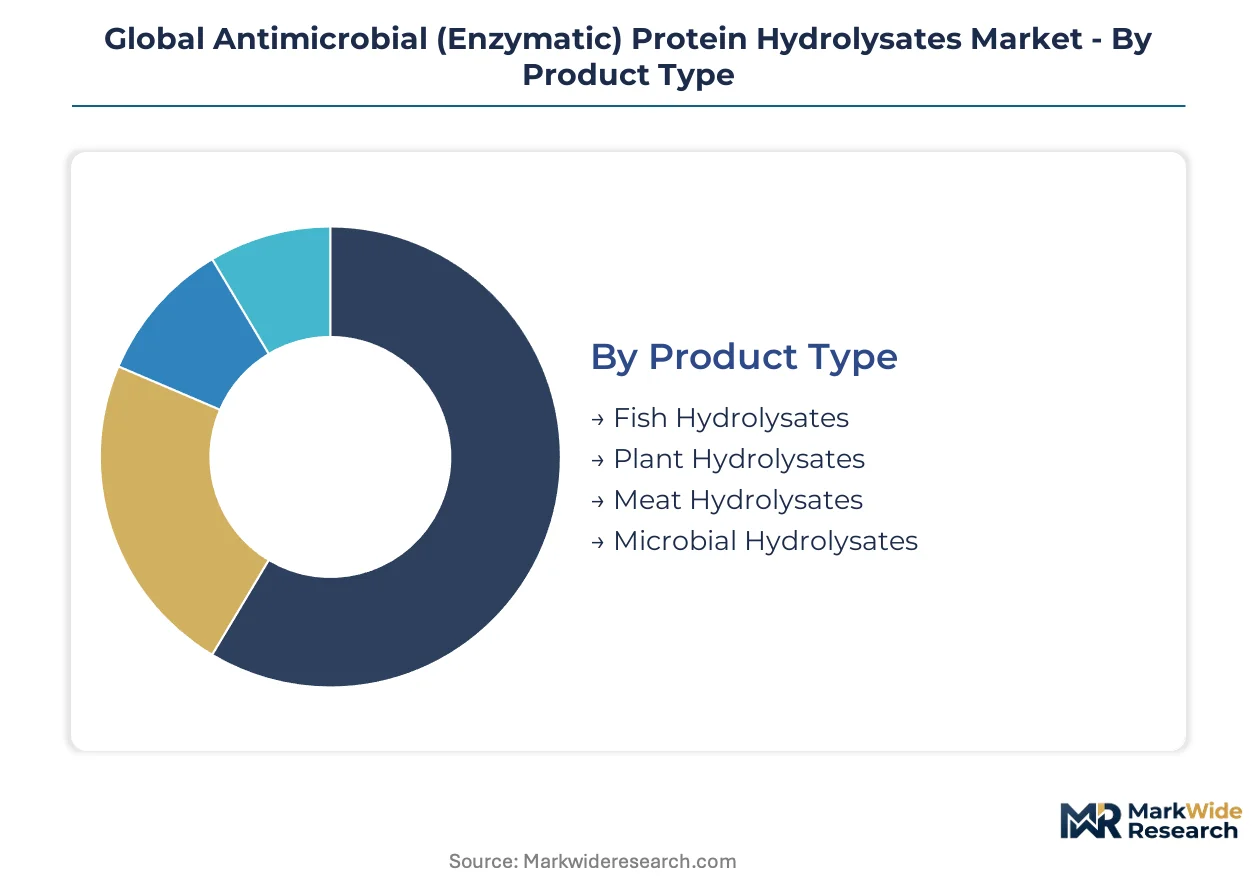
Enzymatic protein hydrolysates serve distinct functional requirements across preservation, therapeutic, and cosmetic channels. Peptide chain length, substrate origin, and delivery format determine regulatory pathways and procurement specifications for each segment.
Product Type:
Manufacturers upgrade from commodity hydrolysates to precision-fractionated peptide products as end-users demand documented bioactivity profiles and chain-length specificity.
- Fish Hydrolysates:Marine-derived oligopeptides between 2-20 amino acid residues demonstrate superior cell membrane penetration against drug-resistant bacterial strains. Pharmaceutical formulators in Germany and Japan prioritize these hydrolysates for therapeutic applications where bioactive peptide documentation determines regulatory approval timelines.
- Plant Hydrolysates:Soy and pea protein sources yield vegan-certified peptide fractions for cosmetic reformulations. European cosmetics manufacturers in France and Germany absorb expanding volumes as REACH compliance hardens documentation requirements for skin-contact applications.
- Meat Hydrolysates:Integrated rendering operations in Brazil control regional supply through captive protein streams.
- Microbial Hydrolysates:Fermentation-derived peptides offer standardized batch consistency for industrial preservation applications.
Volume placements concentrate in fish hydrolysates; the faster expansion belongs to plant hydrolysates.
Application:
Cost tier differentiation separates commodity preservation uses from premium pharmaceutical and cosmetic channels requiring peptide characterization investments.
- Food Preservation:Clean-label mandates drive synthetic preservative replacement with documented bacteriostatic peptide fractions. North American food manufacturers specify fish-derived hydrolysates as retailer blacklists eliminate chemical preservatives from approved ingredient lists.
- Pharmaceuticals:Therapeutic peptide delivery vehicles demand validated amino acid residue sequences against specific pathogen targets. PMDA classification requirements in Japan and FDA additive petitions in the United States impose parallel documentation burdens on suppliers.
- Cosmetic Formulations:Skin-contact antimicrobial actives require ECHA skin sensitization data packages for REACH registration.
- Dietary Supplements:Powder formats dominate shelf-stable dosing precision in nutraceutical channels.
Revenue margins peak in pharmaceutical applications; dietary supplements capture the broadest volume base.
Form:
Processing efficiency requirements favor liquid concentrates for inline manufacturing while stability demands preserve powder dominance in shelf-dependent channels.
- Liquid:Pumpable hydrolysate formats eliminate rehydration steps in food preservation lines. Inline processing adoption reduces sanitation downtime for high-throughput manufacturers.
- Powder:Extended shelf stability and standardized dosing precision retain dominant share in dietary supplement packaging. Moisture-sensitive peptide integrity favors this format for international shipment.
- Granules:Intermediate flow properties suit tableting operations in nutraceutical manufacturing.
- Capsules:Pre-measured unit dosing serves direct-to-consumer supplement distribution.
Manufacturing throughput favors liquid adoption; powder retains the installed base advantage.
End User:
Customer procurement sophistication separates commodity buyers from partners requiring co-development of peptide-specific bioactivity documentation.
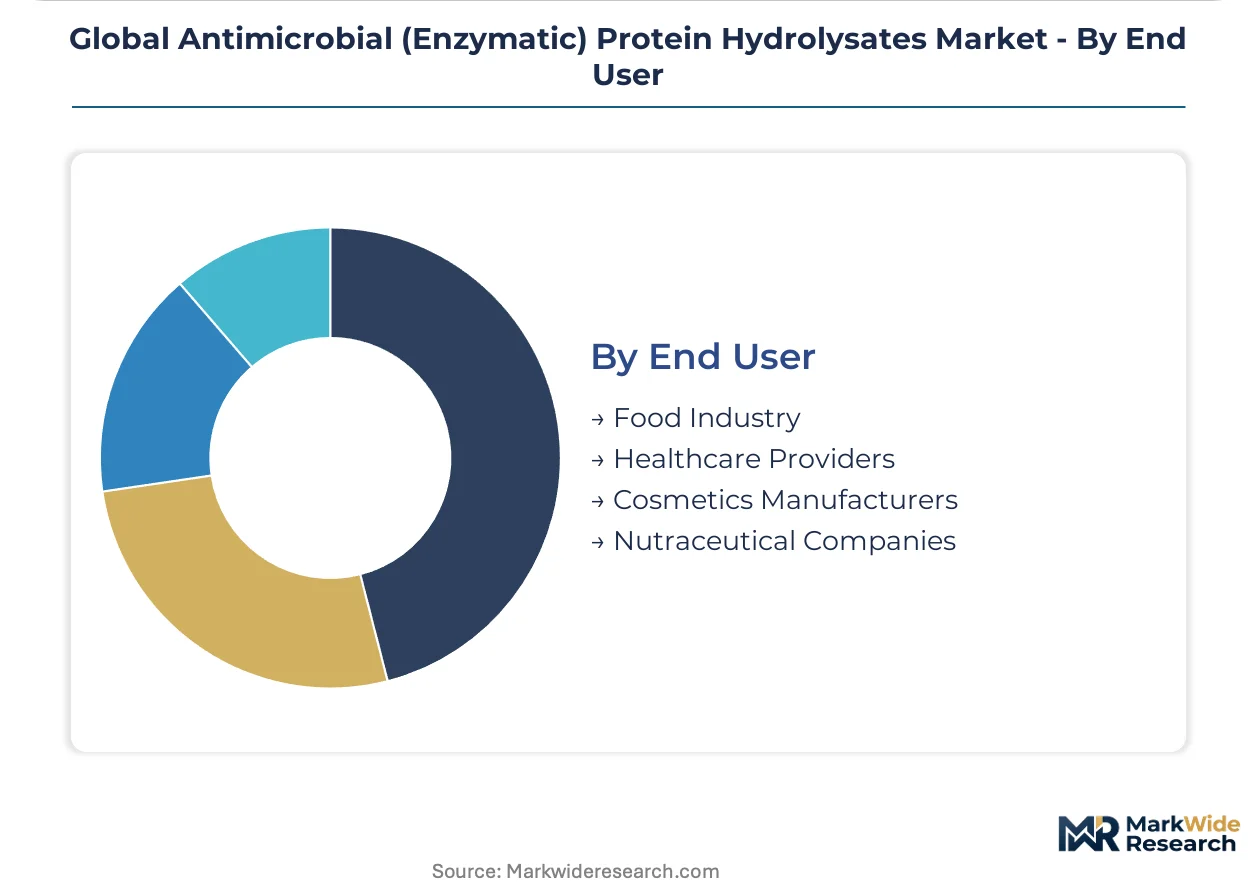
- Food Industry:Clean-label preservation mandates absorb expanding fish hydrolysate volumes as synthetic alternatives face formulation bans. Major manufacturers anchor supply contracts with enzymatic processing specialists.
- Healthcare Providers:Therapeutic peptide applications demand validated bactericidal potency claims against named pathogen strains. Clinical procurement specifications increasingly require chain-of-custody documentation.
- Cosmetics Manufacturers:German and French formulators consolidate supplier bases to pre-registered REACH dossier holders. Skin-contact safety data packages determine vendor qualification.
- Nutraceutical Companies:Standardized peptide content specifications drive powder format procurement for capsule and tablet production.
Contract values concentrate in healthcare procurement; cosmetics manufacturers drive the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces accelerate enzymatic hydrolysate manufacturing concentration through tax incentives and streamlined customs processing for marine protein imports.
United States
Food preservation manufacturers in Wisconsin and California absorb expanding fish hydrolysate volumes as FDA food additive petitions clear synthetic preservative alternatives. Retailer blacklists at Kroger and Whole Foods Market eliminate chemical preservatives from approved ingredient lists. Chicago-area contract manufacturers anchor supply contracts with enzymatic processing specialists for clean-label reformulations.
Germany
Cosmetics manufacturers in Hamburg and Düsseldorf redesign antimicrobial peptide products to meet ECHA skin sensitization data requirements under REACH. EFSA novel food ingredient evaluations compress market access timelines for pharmaceutical-grade hydrolysates. Bavarian ingredient distributors consolidate supplier bases to pre-registered dossier holders with documented peptide chain specifications.
Japan
PMDA peptide therapeutic classification standards drive export specification alignment for marine bioactive fractions entering Tokyo and Osaka healthcare markets. Pharmaceutical formulators in Kansai prioritize documented cell membrane penetration data against drug-resistant bacterial strains. Yokohama-based contract manufacturers adopt membrane filtration-coupled enzymatic reactors for real-time molecular weight cutoff adjustment.
Brazil
Integrated rendering operations in São Paulo and Paraná control regional meat hydrolysate supply through captive protein streams from BRF Ingredients' vertically integrated network. ANVISA pharmaceutical ingredient registrations impose parallel documentation burdens on suppliers targeting therapeutic channels. Rio Grande do Sul rendering clusters sustain cost advantages through backward integration into slaughterhouse operations.
France
Cosmetic brand procurement teams in Paris and Lyon unbundle peptide sourcing from turnkey formulation services, creating direct contracting relationships with enzymatic hydrolysate specialists. ANSM cosmetic ingredient safety assessments demand expanded toxicological packages for skin-contact applications. Provence-Alpes-Côte d'Azur formulators drive vegan certification acceleration through plant hydrolysate substitution for marine-derived actives.
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across enzymatic hydrolysate supply tiers. The vendor base stratifies into three concentration levels: multinational nutrition platforms with flavor and protein divisions, regional rendering-integrated processors with captive raw material access, and contract manufacturers with modular enzymatic processing configurations. Strategic moves center on peptide characterization capability acquisition and REACH dossier pre-submission to compress European vendor qualification timelines.
Among diversified nutrition platforms, Kerry Group and Archer Daniels Midland occupy positions spanning flavor, nutrition, and preservation ingredient portfolios. AMCO Proteins and BRF Ingredients exemplify regional specialists with custom processing and integrated rendering capabilities respectively. Aker Biomarine anchors the marine bioactive peptide vector with Antarctic krill and fish protein sourcing advantages. Koninklijke DSM represents the pharmaceutical-grade peptide fractionation tier through its health and nutrition science platform.
| Leading Market Players |
|---|
| A Constantino & C Spa |
| Aker Biomarine |
| AMCO Proteins |
| Biomega Group |
| BRF Ingredients |
| Arla Foods Ingredients |
| Kerry Group |
| Archer Daniels Midland Company |
| Koninklijke DSM |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap enzymatic processing specialists in coastal Norway and Denmark anchor premium peptide supply, translating captive marine protein access into pricing discipline that resists commoditization pressure from South American rendering conglomerates. Their refusal to integrate downstream preserves margin capture at the ingredient tier while forcing multinational formulators into long-term offtake commitments with indexed raw material clauses.
Pricing Analysis
Margin tightening in pharmaceutical-grade fractions reflects EFSA novel food dossier costs being passed through to European buyers. Three-tier pricing structure across REACH-registered, food-grade, and industrial preservation levels separates vendors by toxicological documentation depth. Cost-down pressure on commodity meat hydrolysates accelerates because Brazilian integrated processors leverage captive supply to undercut spot market participants. Nutraceutical capsule manufacturers exhibit highest price sensitivity; German cosmetics formulators show least elasticity due to reformulation switching costs.
Supply Chain Analysis
REACH dossier pre-submission requirements gate supplier qualification, compressing vendor pools to documented peptide chain specification holders. Production concentrates in Norway, Denmark, and Brazil. Raw material flows draw from Antarctic krill fisheries, North Atlantic whitefish processing residuals, and Brazilian beef rendering streams. Single-source vulnerability concentrates in marine protein seasons. Distribution runs through ingredient distributors consolidating toward pre-registered dossier specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemist scarcity props pricing for validated bioactive peptide fractions, creating durable margin pools for capacity-constrained specialists across the projection horizon.
For Market Incumbents: Anticipate EFSA evaluation timeline extensions by securing parallel PMDA submission pathways for marine bioactive fractions. Prioritize membrane filtration-coupled reactor investments in Yokohama and Hamburg contract manufacturing clusters to defend against emerging modular platform specialists. Lock long-term offtake with North American clean-label food manufacturers before retailer blacklist expansion accelerates. For New Entrants and Emerging Players: Capture liquid concentrate inline processing demand from Wisconsin and California food preservation lines where powder rehydration elimination commands premium placement. Target vegan-certified plant hydrolysate supply gaps in French and German cosmetics channels. Pursue direct contracting relationships with Paris and Lyon procurement teams disintermediating traditional distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor peptide characterization capability holders in Norway and Denmark where family succession transitions create acquisition windows. Five-to-ten year viability hinges on REACH dossier pre-submission completion. Watch ECHA skin sensitization guidance revision timing as inflection trigger for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Pre-submission | Compresses German and French vendor qualification timelines for skin-contact applications. |
| Membrane Filtration Reactor Deployment | Yokohama contract manufacturers adopt real-time molecular weight cutoff adjustment for pharmaceutical-grade output. |
| Direct Procurement Relationship Establishment | Paris cosmetic brand teams bypass distributors to contract enzymatic hydrolysate specialists directly. |
| Vegan Certification Acceleration | Provence-Alpes-Côte d'Azur formulators substitute plant hydrolysates for marine-derived actives. |
| PMDA Export Specification Alignment | Tokyo and Osaka healthcare markets demand documented cell membrane penetration data for therapeutic peptide classification. |
Methodological Framework
Multi-period observation of EFSA evaluation timelines, REACH registration completions, and PMDA therapeutic peptide classifications anchored the trend analysis, supplemented by interviews with enzymatic processing plant managers, regulatory affairs leads at hydrolysate suppliers, cosmetic formulation R&D directors, and North American food manufacturer procurement officers. Secondary validation drew from ECHA registration databases, FDA food additive petition filings, Japanese Ministry of Health peptide classification notices, and customs trade data for marine protein imports. Bottom-up capacity estimates triangulated against top-down end-use demand aggregation.
Input-output matrices modeled peptide recovery rates by substrate source against end-use specification requirements across the projection horizon. Segmentation dimensions included hydrolysate substrate origin, peptide chain length distribution, application channel, delivery format, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to documented capacity expansion announcements and buyer procurement intention surveys. Industry-specific inputs incorporated EFSA novel food ingredient approval velocity and clean-label retailer blacklist expansion patterns.
The model holds under stable EFSA evaluation throughput and REACH guidance continuity; deviation in antimicrobial resistance labeling protocol revisions or marine protein seasonal availability would shift trajectory. Forecasts reflect these base conditions and documented stakeholder capacity plans. A model refresh is warranted upon material change in ECHA proteinaceous substance classification guidance or major retailer clean-label mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Coconut Flour Market
Ingredients
Europe Malt Extract Market
Ingredients
Pea Flour Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Tannin Market
Ingredients
Corn Oil Cake Market
Ingredients
Ground-Nut Oil Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Vegetable Powder Market
Ingredients
Carob Protein Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Bread Flour Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Waxy Maize Starch Market
Ingredients
Food Colors Market
Ingredients
Notoginseng Root Extract Market