

Dry-Molded Fibre Market Size, Share, and Industry Trends Forecast 2026-2036
Dry-Molded Fibre Market Insights
Project finance tied to green packaging infrastructure is reshaping competitive entry in dry-molded fibre. PulPac leverages its proprietary Dry Molded Fiber technology to control licensing costs for converters entering at scale. Stora Enso anchors Nordic pulp supply through backward integration into certified fibre streams. Huhtamaki competes across clamshell and tray formats with manufacturing positions in multiple European countries.
Dry-molded fibre forms three-dimensional packaging from compressed cellulose pulp without water-intensive slurry processes, achieving wall thicknesses of 0.8–2.5 mm and densities of 0.6–1.1 g/cm³ for protective and food-contact applications. The pulp fiber segment dominates volume due to established bleached kraft supply chains, while recycled fiber posts the fastest growth as post-consumer collection systems expand. Food packaging captures the largest margin pool because temperature resistance and grease-barrier specifications command premium pricing over industrial component grades.
EMA food-contact frameworks, REACH chemical restrictions, and EU Green Deal packaging waste directives collectively mandate fibre-based alternatives to expanded polystyrene across Europe. The F-Gas Regulation indirectly reinforces this shift by restricting foam-blowing agents that compete with molded fibre insulation. Stakeholders must monitor whether fibre barrier coatings can achieve the oxygen and moisture performance that personal care brands and electronics assemblers require without triggering ECHA substance-of-concern classifications.
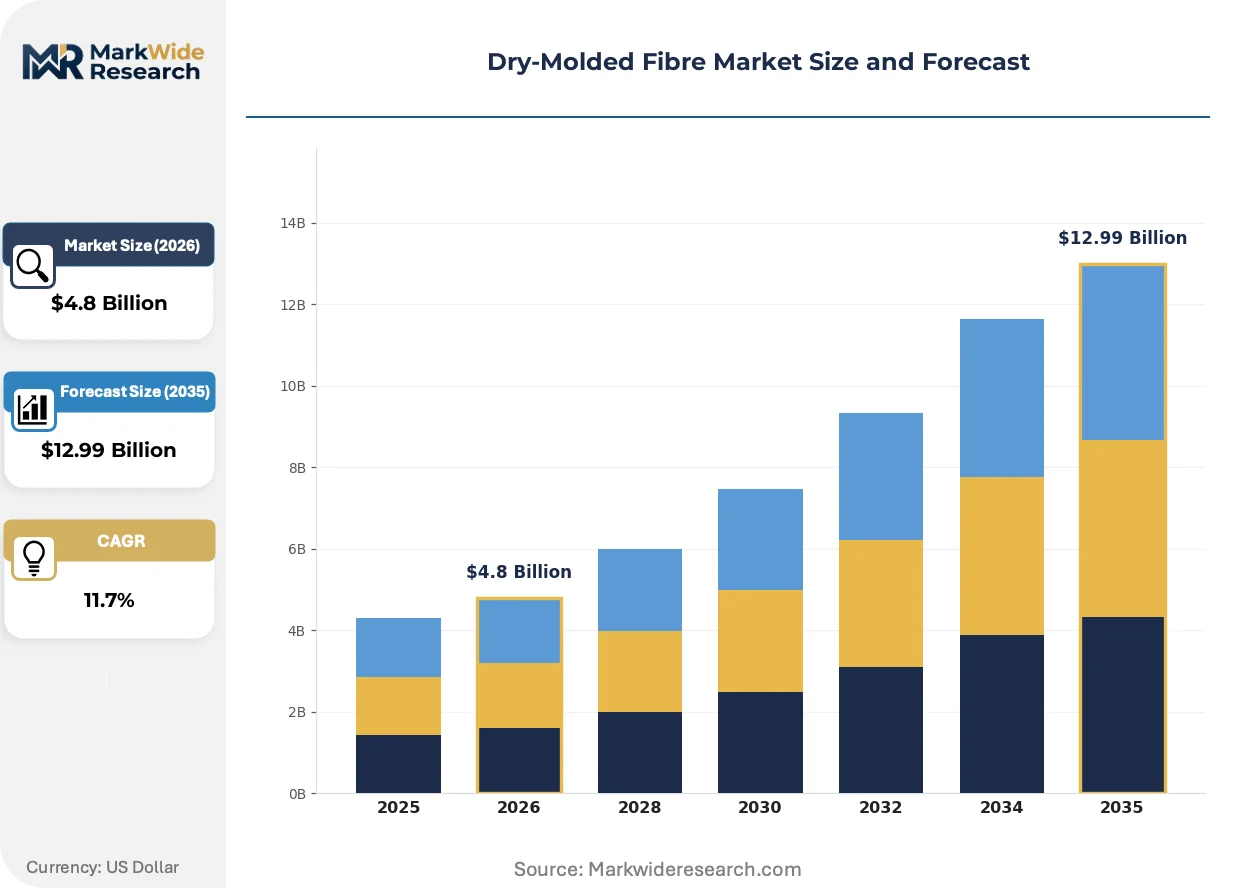
Market Dynamics
The EU Green Deal's packaging waste directives are compressing expanded polystyrene demand while forcing converters to retool for dry-molded fibre capacity. This regulatory pressure intersects with pulp supply concentration in Nordic regions, creating a structural bottleneck that favors backward-integrated players over independent molders.
Growth Catalysts
- REACH chemical restrictions:Substance-of-concern classifications for per- and polyfluoroalkyl substances in food-contact materials are redirecting brand R&D budgets toward fluorine-free barrier coatings for molded fibre.
- Electronics assemblers:Smartphone and laptop manufacturers in Germany are specifying molded fibre trays for component shipping, replacing thermoformed PET at volume scale.
- F-Gas Regulation:Restrictions on hydrofluorocarbon blowing agents for foam insulation are elevating molded fibre's competitiveness in temperature-controlled packaging for pharmaceuticals.
Market Restraints
- Bleached kraft pulp concentration:Nordic suppliers control critical fibre streams, exposing converters to input cost volatility when pulp futures spike.
- Oxygen barrier performance gap:Uncoated molded fibre cannot match metallized film's shelf-life extension for oxygen-sensitive foods, limiting penetration in premium nutrition segments.
- Slurry process incumbency:Wet-molded fibre equipment depreciates slowly, creating capital friction for plants considering dry-process conversion.
Strategic Opportunities
- Post-consumer recycled fibre:Collection system expansion in France and Benelux is creating virgin-equivalent pulp streams at 15-20% cost discount for non-food applications.
- Personal care pump dispensers:Cosmetic brands are prototyping dry-molded fibre outer shells for refillable systems, opening unit-dose formats previously locked to rigid plastics.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are forcing packaging procurement teams to document Scope 3 reductions, elevating fibre-based alternatives in vendor scorecards.
Industry Challenges
- Thermoforming engineer scarcity:Dry-molded fibre tool design requires hybrid expertise in pulp rheology and precision molding that European technical universities have not yet standardized in curricula.
- Food-contact notification timelines:EFSA novel food approval processes for new barrier chemistries extend 18-24 months, compressing product launch windows against plastic replacement deadlines.
- Heat-seal compatibility:Fibre lid-stock must interface with existing tray-sealing equipment on filling lines, requiring retrofit coordination between converter and CPG engineering teams.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry-Molded Fibre Market Trends and Innovations
Process control systems are eliminating the manual calibration that historically constrained dry-molded fibre quality consistency. Three developments are compressing the gap between pilot-scale prototypes and mass-production reliability.
Machine vision inspection is digitizing real-time defect detection across fiber distribution, wall thickness uniformity, and dimensional tolerance. Electronics contract manufacturers in Germany are adopting these systems for tray production at cycle speeds matching thermoformed plastic. The technology is digitizing quality assurance labor out of the molding floor, enabling unattended production shifts that reduce unit labor costs.
EMA's updated guidance on recycled plastic content in food-contact applications is tightening purity requirements for mechanical recycling streams. This regulatory friction is redirecting brand technical resources toward fiber-based alternatives that bypass complex contamination tracing. Personal care and prepared food segments are responding fastest, with formulation teams validating grease-barrier coatings that satisfy both EFSA migration limits and shelf-life specifications.
Brand sustainability scorecards are consolidating supplier selection criteria around verified carbon intensity per unit. Procurement teams at major retailers are weighting fibre-based packaging higher in RFP evaluations, displacing incumbent plastic vendors before contract renewals. This preference shift is most visible in Nordic markets where consumer-facing carbon labeling creates downstream pressure through the private-label supply chain.
Dry-Molded Fibre Market Segmentation
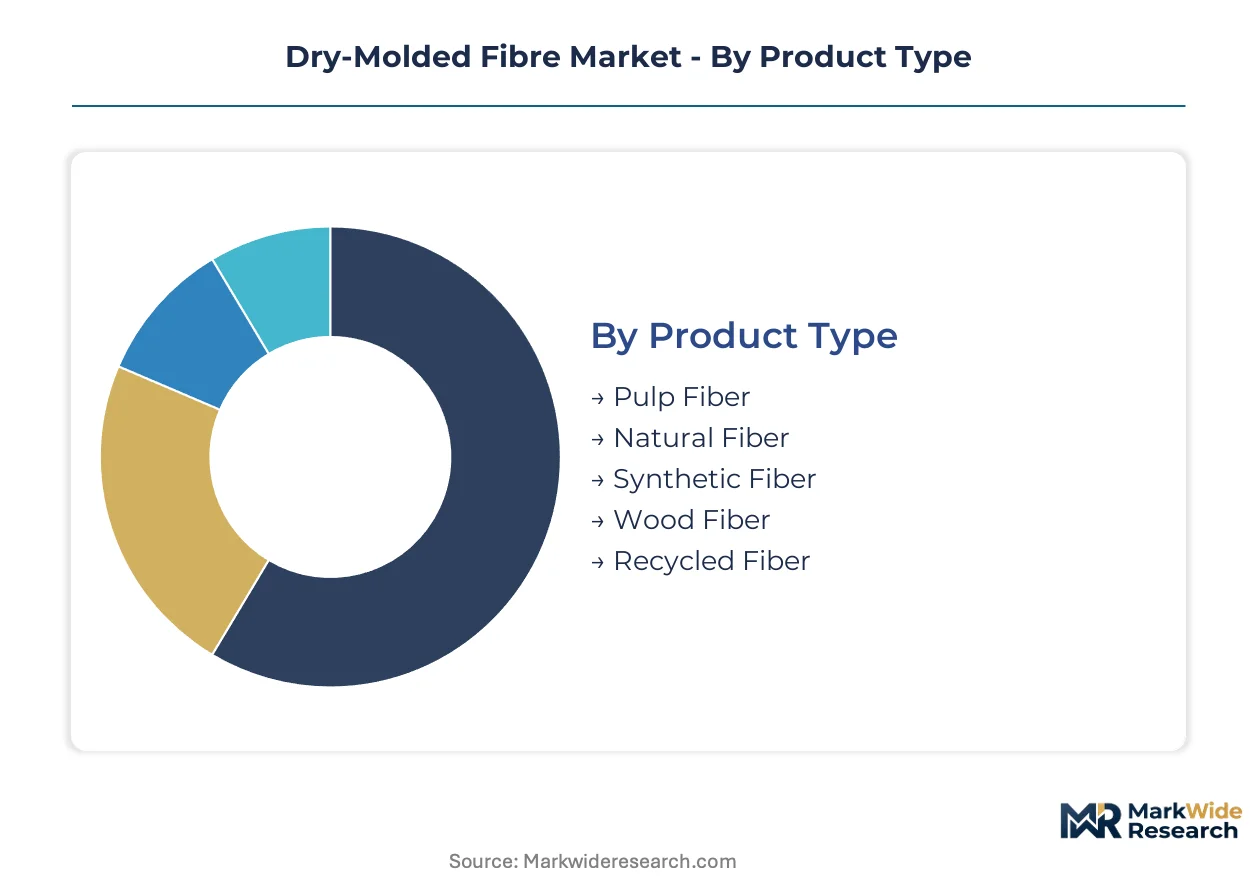
Dry-molded fibre applications span radically different performance requirements, from grease-barrier food contact to electrostatic-dissipative electronics handling. Material selection and forming geometry must align precisely with end-use specifications to secure EFSA approvals and OEM qualification.
Product Type:
Material composition dictates barrier performance, surface finish, and regulatory pathway across the use-case spectrum.
- Pulp Fiber:Bleached kraft pulp delivers consistent fiber length distribution and controlled lignin content for food-contact smoothness. Electronics assemblers in Germany specify this grade for tray applications requiring dimensional stability during automated handling.
- Recycled Fiber:Post-consumer recovered streams achieve virgin-equivalent strength through advanced de-inking and fractionation. French and Benelux collection expansion is driving cost-competitive supply for non-food protective packaging.
- Natural Fiber:Agricultural residues including wheat straw and bagasse provide regional supply security where wood pulp logistics are unfavorable.
- Synthetic Fiber:Man-made cellulose derivatives enhance wet strength and moldability for complex geometries in personal care dispensers.
- Wood Fiber:Unbleached mechanical pulp offers cost positioning for industrial dunnage where color uniformity is non-critical.
The dominant share belongs to pulp fiber, while recycled fiber is closing the gap fastest.
Application:
End-use performance tiers separate premium food-contact specifications from industrial commodity grades.
- Food Packaging:Temperature resistance and grease-barrier specifications command premium positioning. EMA food-contact frameworks and REACH PFAS restrictions are redirecting brand R&D budgets toward fluorine-free coated alternatives for ready-meal and takeaway segments.
- Electronics Packaging:Smartphone and laptop manufacturers specify molded fibre trays for component shipping. German contract manufacturers are adopting machine vision inspection systems to match thermoformed plastic cycle speeds.
- Personal Care Containers:Cosmetic brands prototype dry-molded fibre outer shells for refillable pump systems. Unit-dose formats previously locked to rigid plastics now face fibre-based competition.
- Industrial Components:Protective dunnage for machinery and automotive parts prioritizes impact absorption over surface aesthetics.
- Automotive Parts:Interior trim and insulation applications leverage molded fibre's acoustic dampening and lightweighting potential.
Food packaging captures the largest margin pool, with electronics packaging gaining share fastest through German OEM adoption.
End User Industry:
Procurement sophistication varies sharply between sustainability-mandated consumer brands and cost-driven industrial buyers.
- Consumer Goods Manufacturing:CSRD disclosure requirements force packaging procurement teams to document Scope 3 reductions. Fibre-based alternatives score higher in vendor scorecards at major retailers.
- Electronics Assembly:German smartphone and laptop manufacturers specify molded fibre trays. Automated handling compatibility and electrostatic control drive material selection.
- Personal Care Brands:Refillable system prototypes open unit-dose formats to fibre-based outer shells. EFSA migration limits constrain barrier coating chemistry choices.
- Vehicle Assemblers:Interior acoustic and lightweighting specifications favor molded fibre for non-structural components.
- Packaging Providers:Independent converters face backward-integrated competition from Nordic pulp suppliers controlling critical fibre streams.
Consumer goods manufacturing leads procurement volume, while electronics assembly is expanding fastest through German OEM qualification programs.
Packaging Type:
Forming geometry determines equipment investment, cycle speed, and heat-seal compatibility with existing filling lines.
- Clamshells:Hinged structures for produce and electronics retail display require precise fiber distribution to prevent hinge cracking. Huhtamaki competes across this format with multi-country European manufacturing positions.
- Trays:Electronics component shipping and prepared meal applications demand tight dimensional tolerance. German contract manufacturers are scaling capacity with process control systems enabling unattended production shifts.
- Cups:Hot and cold beverage containment requires heat resistance and leak-proof rim forming. Heat-seal compatibility with existing tray-sealing equipment demands retrofit coordination between converter and CPG engineering teams.
- Plates:Flatware substitutes for catering and institutional foodservice prioritize cost positioning over premium surface finish.
- Protective Inserts:Custom-molded cushioning for fragile goods leverages fiber's vibration dampening without complex barrier requirements.
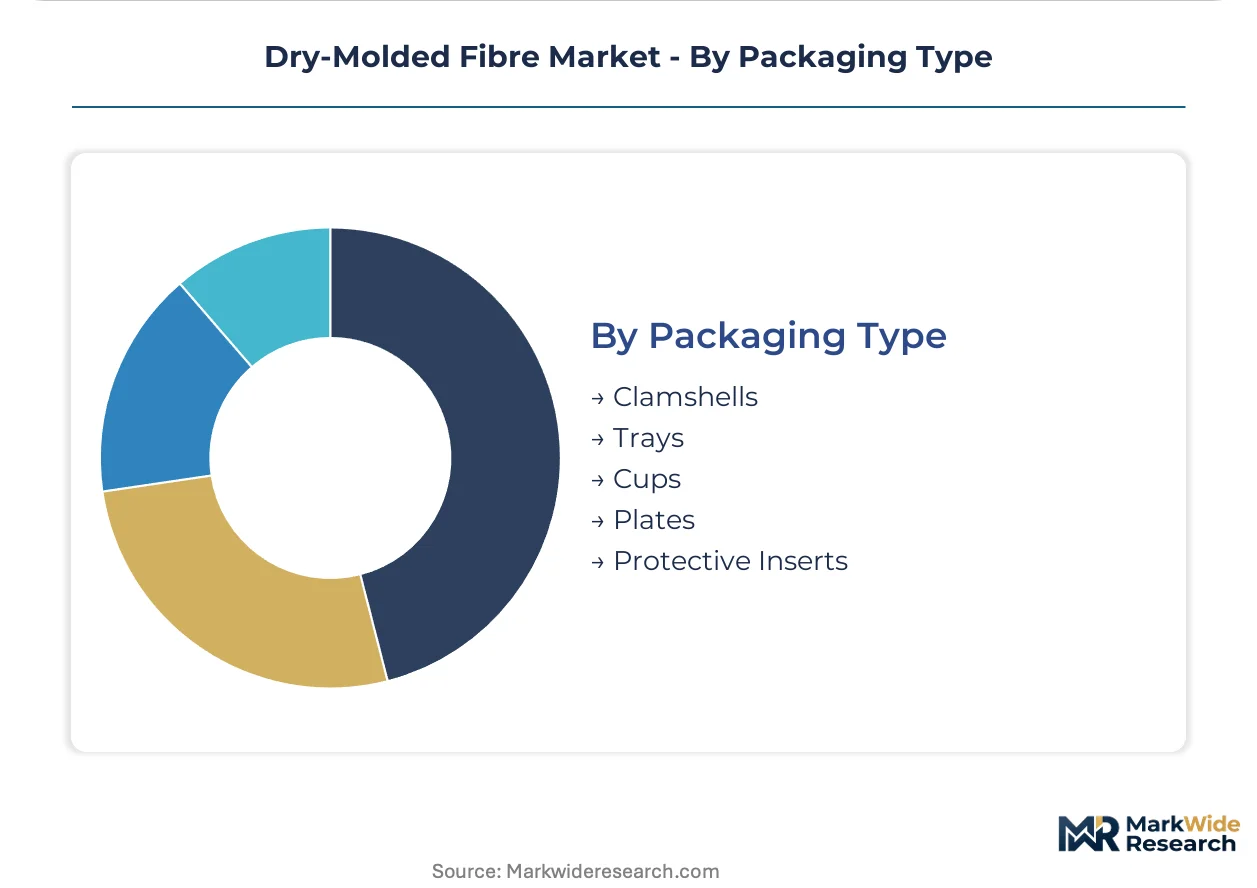
Trays hold the dominant position, with clamshells climbing fastest through produce retail replacement of thermoformed PET.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry-molded fibre trade flows reflect a European export surplus in pulp feedstock against Asian import dependency for forming equipment. Nordic suppliers ship bleached kraft to converters in Germany and France, while Chinese machinery builders capture capital expenditure in emerging Southeast Asian markets.
Germany
Electronics contract manufacturers in Bavaria and Baden-Württemberg specify molded fibre trays for smartphone component logistics. The F-Gas Regulation restricts foam-blowing agents for temperature-controlled pharma packaging, elevating fibre insulation competitiveness. Berlin-Brandenburg hosts packaging R&D clusters where converters prototype barrier coatings for ready-meal applications.
France
Post-consumer collection expansion in Île-de-France and Hauts-de-France generates virgin-equivalent recycled pulp streams at cost discounts. EMA food-contact frameworks mandate fibre alternatives to expanded polystyrene in takeaway segments. Lyon-based cosmetic brands trial dry-molded fibre outer shells for refillable pump dispensers.
Sweden
Backward-integrated pulp producers in Stockholm and Norrland control critical bleached kraft supply chains for European converters. The EU Green Deal packaging waste directives compress polystyrene demand while favoring Nordic fibre streams. Gothenburg packaging engineering clusters develop process control systems for unattended production shifts.
United States
CPG procurement teams in the Midwest and Southeast weight fibre-based packaging higher in vendor scorecards under CSRD-aligned sustainability mandates. FDA food-contact notification timelines constrain barrier chemistry launches against plastic replacement deadlines. California's extended producer responsibility laws accelerate clamshell format conversion away from thermoformed PET.
China
Dual carbon goals and GB standards for packaging waste redirect domestic brand technical resources toward fibre-based alternatives. Yangtze River Delta machinery builders export dry-molded forming equipment to Southeast Asian converters. Shenzhen electronics assemblers qualify molded fibre trays for component export logistics to European OEMs.
Dry-Molded Fibre Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling fibre supply and tooling design. The vendor base stratifies between backward-integrated Nordic pulp suppliers, technology licensors with proprietary dry-forming patents, and independent converters scaling multi-country manufacturing footprints. Three archetypes dominate: captive fibre stream owners, process technology licensors, and format-focused contract manufacturers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with converters securing long-term pulp offtake agreements while equipment builders license forming technology to regional fabricators.
Among Nordic integrated suppliers, Stora Enso anchors the captive fibre archetype through upstream control over certified pulp streams. Technology licensors occupy a distinct tier, with PulPac representing the proprietary dry-forming patent holder model that converters license for market entry. Format specialists compete across clamshell and tray geometries, where Huhtamaki exemplifies multi-country European manufacturing positions. Brødrene Hartmann sits within the molded fibre converter archetype with established dairy and egg packaging formats. These four entities collectively illustrate the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Huhtamaki |
| Brødrene Hartmann |
| PulPac |
| Yangi |
| Stora Enso |
| Omni-Pac Group |
| UFP Technologies |
| Sabert Corporation |
| TekniPlex |
| Others |
Pricing and Supply Chain Analysis
Stockholm-Norrland pulp clusters command premium positioning through captive bleached kraft supply, translating upstream fibre concentration into downstream pricing leverage for food-contact grades. Nordic backward-integrated producers extract margin premiums from German and French converters facing REACH-compliant barrier coating mandates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on EFSA certification status and volume scale. Cost compression in standard-grade electronics packaging is intensifying because German contract manufacturers negotiate cycle-speed guarantees against thermoformed plastic benchmarks. Food-contact certified grades show least price sensitivity due to fluorine-free barrier R&D sunk costs, while industrial dunnage buyers drive hardest bargain on unbleached mechanical pulp alternatives.
Supply Chain Analysis
Bleached kraft pulp feedstock draws from Sweden, Finland, and Canada, with post-consumer recovered fibre sourcing from French and Benelux collection expansion. Critical inputs span Nordic wood pulp, barrier coating chemistries, and precision thermoforming tooling. Single-source vulnerability concentrates in Stockholm-Norrland fibre streams, where pulp futures volatility transmits directly to converter margins. Distribution runs through converter-direct relationships with German electronics assemblers and French cosmetic brands, bypassing traditional packaging distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry-molded fibre platforms are crossing an interoperability threshold where PulPac's licensed forming technology and Stora Enso's certified pulp streams create two-sided network effects, locking in converter adoption through combined equipment-fibre bundled offerings.
For Market Incumbents: Pre-empt margin erosion in standard-grade electronics trays by securing exclusive long-term pulp offtake agreements with Nordic suppliers before independent molders scale capacity. Defend food-contact premium positioning through accelerated EFSA notification timelines for fluorine-free barrier chemistries, closing the window for specialty coating entrants. For New Entrants and Emerging Players: Build out post-consumer recycled fibre processing capacity in France and Benelux, where collection system expansion creates virgin-equivalent pulp at cost discounts for non-food protective packaging. Target personal care pump dispenser outer shells as the most penetrable segment, leveraging cosmetic brands' refillable system prototypes to bypass incumbent rigid plastic tooling lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Green Deal packaging waste directives and F-Gas Regulation restrictions on foam-blowing agents structurally elevate fibre-based alternatives regardless of near-term barrier performance gaps. Monitor EFSA migration limit rulings on novel barrier chemistries as the signal for premium food-contact margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fibre Streams | Stora Enso's Nordic pulp control locks in converter supply security against spot market volatility. |
| Technology Licensing to Regional Fabricators | PulPac's patent licensing model accelerates dry-forming equipment deployment without capital-heavy manufacturing. |
| Barrier Coating R&D Partnership | EFSA-compliant fluorine-free formulations open premium ready-meal segments previously blocked by PFAS restrictions. |
| Machine Vision Quality Systems Deployment | German electronics contract manufacturers match thermoformed plastic cycle speeds through automated defect detection. |
| Post-Consumer Collection Infrastructure Investment | French and Benelux expansion generates cost-competitive recycled pulp streams for non-food protective applications. |
Research Methodology
A spread of perspectives from packaging converter operations directors, pulp procurement leads at Nordic suppliers, EFSA regulatory affairs specialists, and German electronics OEM sustainability officers converged on the working assumptions. Secondary validation drew from EU Green Deal directive texts, ECHA substance-of-concern classification databases, SEC filings of listed packaging groups, and Nordic pulp futures trade data. Bottom-up capacity modeling across forming equipment installations was triangulated against top-down brand procurement survey data.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled by material composition, application performance tier, end-user procurement sophistication, and forming geometry complexity. CAGRs were derived from installed capacity expansion trajectories and brand substitution timelines for plastic replacement. Key inputs included EFSA novel food approval pipeline status and German electronics OEM qualification program progress.
Stress conditions across pulp futures volatility, REACH chemical restriction scope expansion, and barrier coating performance thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement timelines and brand sustainability procurement weighting. Cross-checking against Nordic pulp producer order backlogs and German packaging converter capacity utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.