
 Asia-Pacific Optical Fiber Raw Material Market | 2026-2036
Asia-Pacific Optical Fiber Raw Material Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Optical Fiber Raw Material Market Insights
China is narrowing the regional supply gap for high-purity silicon tetrachloride and germanium tetrachloride precursors. Yangtze Optical Fibre and Cable Co., Ltd. leverages captive chlorosilane production to secure feedstock continuity. Hengtong Optic-Electric Co., Ltd. anchors its position through integrated preform-to-fiber manufacturing. Sumitomo Electric Industries, Ltd. competes on specialty fiber dopant chemistry for submarine cable grades.
Asia-Pacific optical fiber raw material comprises silica-based glass precursors, polymer cladding compounds, and rare-earth dopants formulated to achieve attenuation below 0.2 dB/km at 1550 nm wavelength. Glass fiber dominates material type consumption due to its established use in long-haul telecommunications infrastructure. Data centers represent the fastest-growing application segment as hyperscalers expand intra-campus fiber counts. Cable manufacturers within the end-user base capture margin pools through backward integration into preform drawing.
China's MIIT enforces GB standards for optical fiber mechanical reliability and environmental durability. Japan's METI coordinates JIS certification for undersea cable materials through NTT supply chain requirements. India's BIS mandates fiber optic cable quality control orders for public network tenders. Stakeholders must monitor divergence between national standards and IEC harmonization timelines as cross-border project specifications tighten.
Market Dynamics
China's MIIT gigabit broadband mandates are compressing deployment timelines across Southeast Asian telecom networks, forcing raw material suppliers to synchronize capacity expansion with infrastructure subsidy cycles rather than organic demand curves.
Growth Catalysts
- Silica precursor localization:China's captive chlorosilane production is eliminating import dependency for high-purity silicon tetrachloride feedstock. Domestic Yangtze River corridor facilities now supply regional preform manufacturers.
- Fiber-to-the-home mandates:India's BharatNet corridors and Indonesia's Palapa Ring expansion are creating anchored demand for single-mode fiber raw materials through sovereign-backed procurement.
- Submarine cable upgrades:Japan's METI-coordinated Pacific cable initiatives are pulling specialty germanium-doped preform demand for ultra-low-loss transoceanic grades.
Market Restraints
- Geographic supply concentration:High-purity germanium tetrachloride refining capacity clusters in China's Hubei and Jiangsu provinces, creating single-source vulnerability for specialty fiber dopants.
- Energy cost volatility:Fused silica precursor synthesis requires continuous high-temperature plasma processing; electricity tariff spikes in South Korea and Taiwan directly compress preform margins.
- Optical polymer substitution:Perfluorinated polymer-clad multimode fiber is capturing data center interconnect applications below 100 meters, displacing glass fiber in hyperscale campus builds.
Strategic Opportunities
- Vietnam manufacturing corridors:Northern industrial zones around Hai Phong offer tariff-advantaged positions for Japanese and Korean compound suppliers serving ASEAN cable assembly.
- Co-packaged optics convergence:Silicon photonics integration with switch ASICs is collapsing optical engine form factors, creating demand for precision-cleaved fiber arrays and novel ferrule materials.
- India PLI scheme alignment:The country's production-linked incentive framework for telecom equipment is extending backward into preform and precursor domestic manufacturing.
Industry Challenges
- Preform engineering talent scarcity:Modified chemical vapor deposition and outside vapor deposition process expertise concentrates in legacy Japanese and American facilities, constraining technology transfer to new Chinese and Indian entrants.
- Cross-border certification friction:Divergence between China's GB/T fiber mechanical standards and IEC 60793 creates dual-testing burdens for suppliers serving both domestic and export cable markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Optical Fiber Raw Material Market |
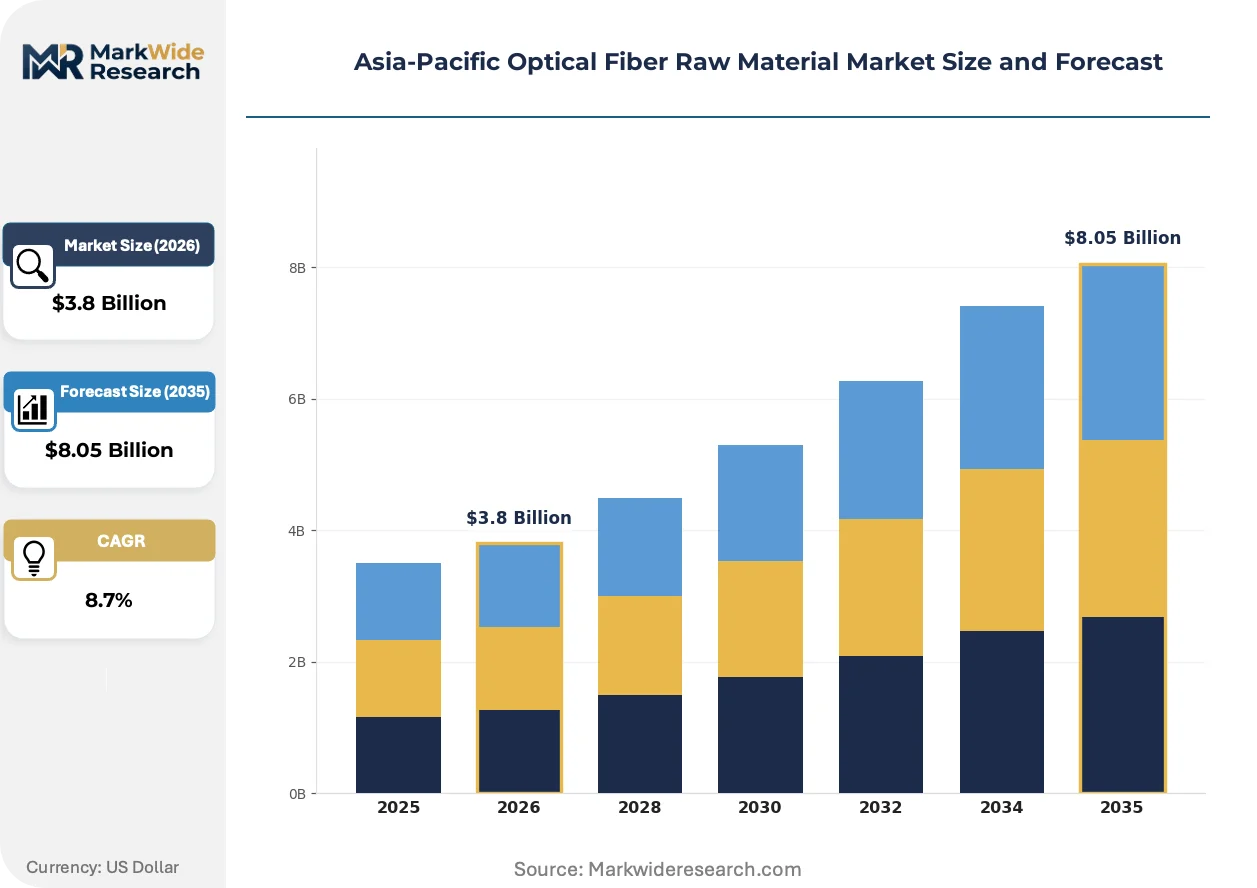
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass Fiber, Plastic Fiber, Specialty Fiber, Composite Fiber Application: Telecommunications, Data Centers, Broadcast, Industrial End User: Telecom Operators, Cable Manufacturers, Utility Providers, OEMs Distribution Channel: Wholesale, Retail, Direct Sales, Online Sales |
| Companies Covered | Hengtong Optic-Electric Co., Ltd., Yangtze Optical Fibre and Cable Co., Ltd., Futong Group Co., Ltd., Changfei Optical Fibre and Cable Co., Ltd., ZTT Group, Sumitomo Electric Industries, Ltd., Fujikura Ltd., Mitsubishi Chemical Corporation, Sterlite Technologies Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Optical Fiber Raw Material Market Trends and Innovations
Raw material formulation is pivoting from attenuation-centric specifications toward bend-insensitive and high-density cable compatibility, driven by fiber count inflation in metropolitan distribution networks and data center spine architectures.
Multicore fiber preform designs are collapsing the fiber-count-per-cable paradigm by enabling spatial multiplexing in a single cladding structure. Submarine cable consortiums are piloting 19-core and 24-core variants for transpacific routes. This geometry is compressing the raw material intensity per bit-transmitted-kilometer despite higher dopant complexity.
Japan's METI has accelerated JIS C 6832 revision cycles to incorporate environmental durability testing for undersea cable materials exposed to deep-ocean pressure cycling. Preform suppliers must now qualify thermal shock resistance across simulated 6,000-meter depth profiles. The Pacific cable manufacturing cluster around Kawasaki and Yokohama is absorbing these certification costs into long-term supply agreements.
Hyperscaler procurement teams are consolidating optical fiber purchasing through direct preform offtake contracts rather than arm's-length cable procurement. This disintermediation is compressing margin pools for traditional cable manufacturers and forcing compound suppliers to certify directly with cloud infrastructure operators. The pattern is most visible in Singapore's data center hub, where Microsoft, Google, and Amazon Web Services maintain dedicated fiber specification engineering teams.
Asia-Pacific Optical Fiber Raw Material Market Segmentation
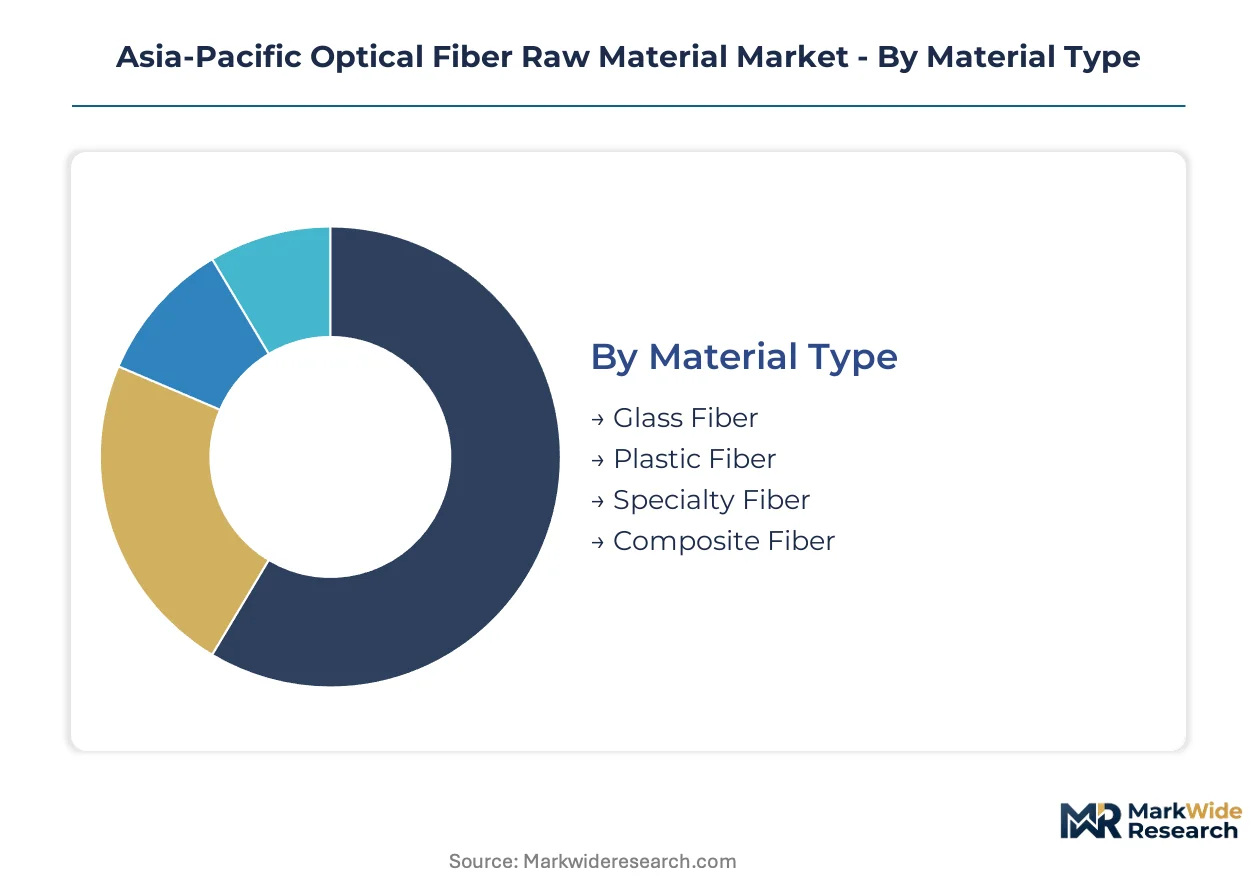
Optical fiber raw material segmentation reveals how performance specifications, procurement patterns, and supply chain configurations vary across distinct material grades and customer archetypes. Understanding these partitions enables suppliers to align capacity investments with the divergent technical and commercial requirements of telecommunications infrastructure versus data center interconnect deployments.
Material Type:
Material chemistry spans the use-case spectrum from standard telecommunications to specialized sensing and short-reach applications.
- Glass Fiber:Silica-based glass precursors formulated for attenuation below 0.2 dB/km at 1550 nm wavelength dominate long-haul infrastructure. China's MIIT gigabit broadband mandates are compressing deployment timelines across Southeast Asian telecom networks, forcing raw material suppliers to synchronize capacity expansion with infrastructure subsidy cycles.
- Specialty Fiber:Germanium-doped and rare-earth-doped variants achieve ultra-low-loss specifications for submarine cable grades. Japan's METI-coordinated Pacific cable initiatives are pulling demand for transoceanic preform materials through NTT supply chain requirements.
- Plastic Fiber:Perfluorinated polymer-clad multimode construction serves short-reach applications below 100 meters.
- Composite Fiber:Hybrid glass-polymer structures address bend-insensitive metropolitan distribution requirements.
The dominant share belongs to Glass Fiber, while Specialty Fiber is closing the gap fastest.
Application:
End-use intensity correlates directly with fiber count inflation and link distance requirements.
- Telecommunications:Single-mode fiber raw materials anchor BharatNet corridors in India and Indonesia's Palapa Ring expansion through sovereign-backed procurement. India's BIS mandates fiber optic cable quality control orders for public network tenders.
- Data Centers:Intra-campus fiber counts are expanding as hyperscalers consolidate optical fiber purchasing through direct preform offtake contracts. Singapore's data center hub hosts dedicated fiber specification engineering teams from major cloud infrastructure operators.
- Broadcast:High-bandwidth video transport drives single-mode demand for content distribution networks.
- Industrial:Harsh-environment fiber sensing applications require specialized coating chemistries.
Telecommunications retains volume leadership, though Data Centers is expanding most quickly through hyperscaler capital deployment.
End User:
Customer type determines specification authority and backward integration depth.
- Telecom Operators:State-backed carriers in India and Indonesia anchor demand through multi-year supply agreements with preform manufacturers.
- Cable Manufacturers:Capture margin pools through in-house production of preform drawing capabilities. Yangtze Optical Fibre and Cable leverages captive chlorosilane production to secure feedstock continuity.
- Utility Providers:Power grid fiber optic ground wire deployments create secondary demand channels.
- OEMs:Equipment manufacturers source precision-cleaved fiber arrays for co-packaged optics integration with switch ASICs.
Cable Manufacturers command the largest procurement volume, while OEMs are gaining specification influence fastest through silicon photonics convergence.
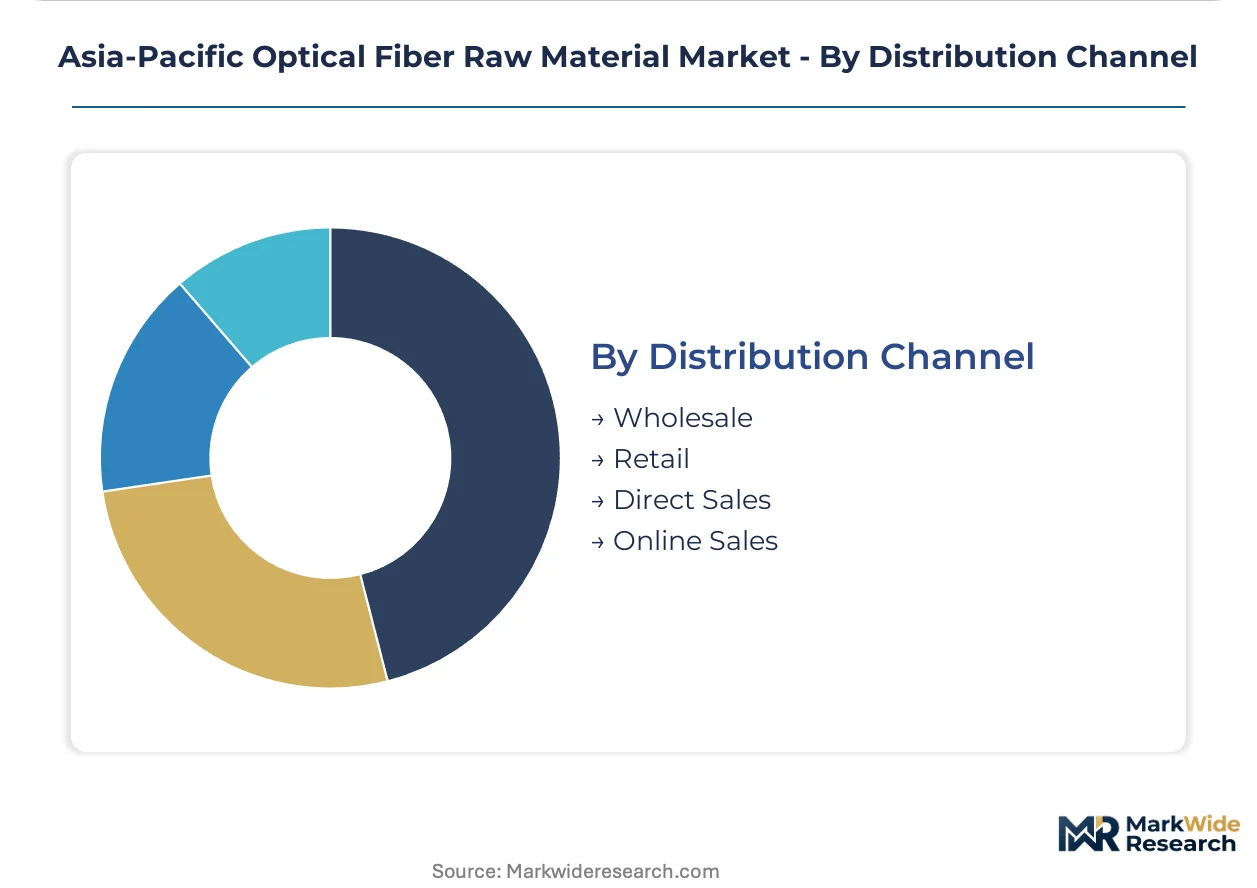
Distribution Channel:
Channel structure reflects customer scale and technical support requirements.
- Direct Sales:Preform offtake contracts with hyperscalers and submarine cable consortiums eliminate intermediary margin layers. Microsoft's Singapore engineering team negotiates fiber specifications directly with compound suppliers.
- Wholesale:Regional cable assembly clusters in Vietnam's Hai Phong industrial zones aggregate precursor demand for Japanese and Korean compound suppliers.
- Retail:Small-batch specialty fiber sales serve research and prototype development.
- Online Sales:Standard polymer cladding compounds move through digital procurement platforms.
Direct Sales captures the highest-value transactions, while Wholesale is climbing the fastest through ASEAN manufacturing corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the region. China deploys silica precursors at scale for terrestrial gigabit infrastructure. Japan concentrates on ultra-low-loss specialty grades for submarine systems. India and Southeast Asian markets prioritize cost-optimized single-mode fiber for broadband access networks.
China
MIIT-mandated gigabit broadband targets compress deployment timelines across provincial networks. The regulator's GB standards enforce mechanical reliability specifications for fiber optic cables in public tenders. The Yangtze River Delta corridor hosts captive chlorosilane facilities supplying domestic preform manufacturers with high-purity silicon tetrachloride feedstock.
Japan
METI-coordinated Pacific cable initiatives pull demand for germanium-doped preform materials in ultra-low-loss transoceanic grades. The ministry's JIS C 6832 revisions now mandate thermal shock resistance testing across simulated 6,000-meter depth profiles. The Kawasaki-Yokohama manufacturing cluster absorbs certification costs into long-term supply agreements with submarine cable consortiums.
India
BharatNet corridors anchor demand for single-mode fiber raw materials through sovereign-backed procurement mechanisms. BIS quality control orders mandate fiber optic cable certification for all public network tenders. Gujarat and Maharashtra industrial zones concentrate cable assembly operations serving national broadband mission deployments.
South Korea
Hyperscaler data center expansion drives intra-campus fiber count inflation for precision-cleaved fiber arrays. The country's national telecom regulator coordinates spectrum policy with infrastructure deployment cycles. The Seoul Capital Area hosts dedicated fiber specification engineering teams from major cloud infrastructure operators.
Vietnam
Northern industrial zones around Hai Phong offer tariff-advantaged positions for Japanese and Korean compound suppliers serving ASEAN cable assembly markets. The government's national digital transformation agenda prioritizes fiber-to-the-home infrastructure in urban corridors. Manufacturing clusters in Bac Ninh and Hai Duong provinces aggregate precursor demand for regional export-oriented cable production.
Asia-Pacific Optical Fiber Raw Material Market Competitive Landscape
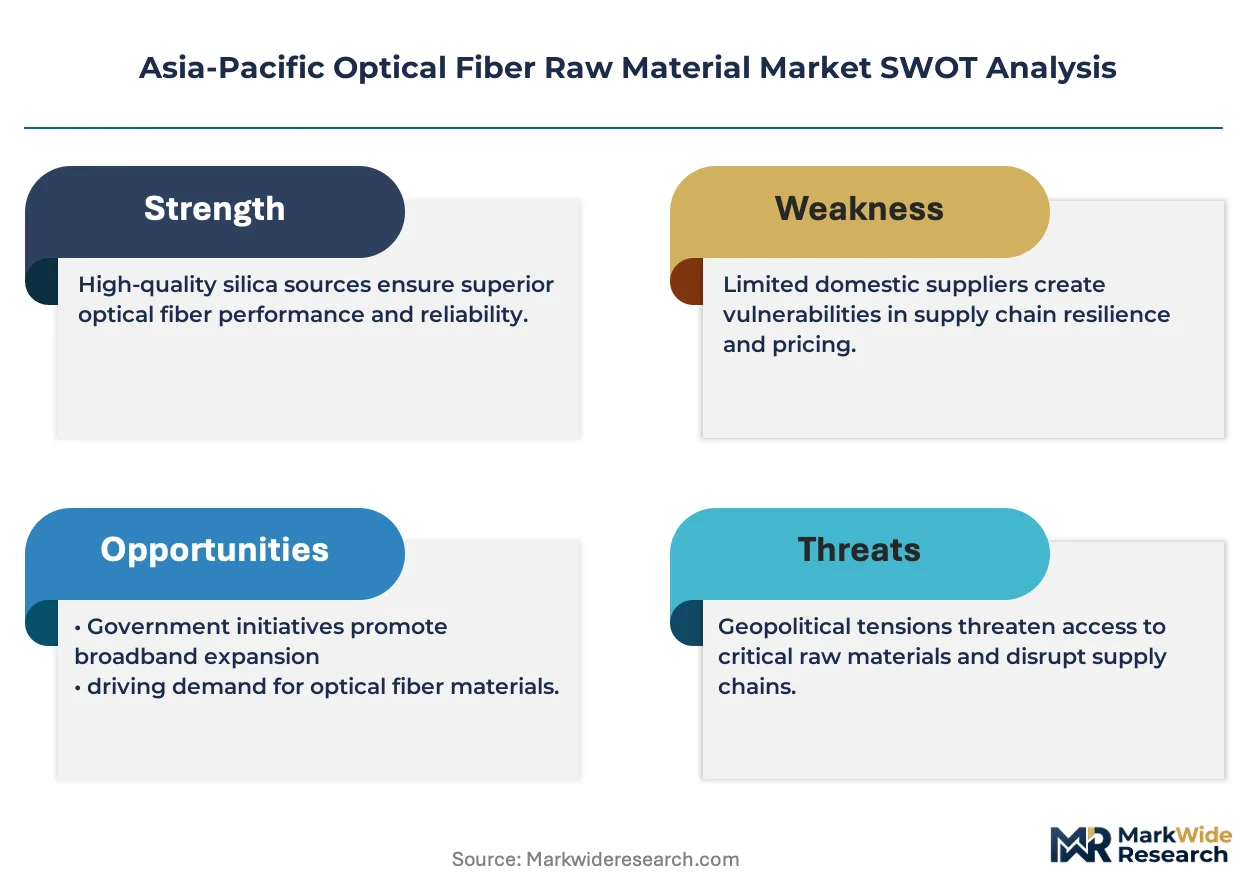
Capability concentration sits with one tier; scale advantage sits with another. The market structures around integrated preform-to-fiber manufacturers with captive feedstock supply, specialty dopant chemists serving submarine cable grades, and regional cable assemblers capturing margin through backward integration. Three archetypes dominate: chlorosilane-integrated precursors specialists, rare-earth dopant formulators, and polymer cladding compound suppliers. Capacity expansion and strategic partnerships constitute the primary competitive moves as players synchronize with infrastructure subsidy cycles.
Among Chinese integrated manufacturers, Yangtze Optical Fibre and Cable Co., Ltd. and Hengtong Optic-Electric Co., Ltd. exemplify the captive chlorosilane production model. Sumitomo Electric Industries, Ltd. occupies a position representing specialty fiber dopant chemistry for transoceanic cable applications. These three anchors illustrate the divergence between scale-driven terrestrial supply and precision-focused submarine grade formulation.
| Leading Market Players |
|---|
| Hengtong Optic-Electric Co., Ltd. |
| Yangtze Optical Fibre and Cable Co., Ltd. |
| Futong Group Co., Ltd. |
| Changfei Optical Fibre and Cable Co., Ltd. |
| ZTT Group |
| Sumitomo Electric Industries, Ltd. |
| Fujikura Ltd. |
| Mitsubishi Chemical Corporation |
| Sterlite Technologies Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta chlorosilane corridor is compressing preform margins and forcing suppliers toward long-term offtake structures to lock in volume commitments before subsidy cycles expire.
Pricing Analysis
Long-term preform offtake contracts dominate high-volume transactions, with spot markets reserved for specialty dopant batches and prototype development. Price differentiation rests on MIIT GB certification tier and captive chlorosilane integration depth. Cost compression in standard single-mode grades is intensifying because Indian and Indonesian sovereign procurement mandates prioritize lowest-compliant-bid mechanisms. Hyperscaler direct procurement teams exhibit lowest price sensitivity due to fiber specification engineering investments, while ASEAN cable assemblers face acute margin pressure from tariff exposure.
Supply Chain Analysis
Export control regimes on high-purity germanium tetrachloride refining technology limit capacity expansion outside China's Hubei and Jiangsu provinces. Supply concentration in China, Japan, and South Korea draws from quartz sand beneficiation, chlorosilane synthesis, and rare-earth dopant formulation as critical inputs. Single-source vulnerability for specialty submarine-grade dopants creates structural risk for transoceanic cable consortiums. Distribution runs through direct preform offtake to hyperscalers and submarine cable manufacturers, with wholesale aggregation serving Vietnam's Hai Phong cable assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where hyperscaler direct procurement is collapsing traditional cable manufacturer intermediation, forcing raw material suppliers to certify interoperability directly with cloud infrastructure specification teams.
For Market Incumbents: Insulate margin pools by deepening captive chlorosilane production in the Yangtze River corridor and securing MIIT GB certification ahead of IEC harmonization divergence. Perfluorinated polymer-clad multimode substitution in hyperscale data centers threatens glass fiber volume; counter through bend-insensitive composite fiber R&D for metropolitan distribution density. For New Entrants and Emerging Players: Pursue Vietnam's Hai Phong and Bac Ninh industrial zones as tariff-advantaged manufacturing corridors for Japanese and Korean compound suppliers serving ASEAN cable assembly. India's PLI scheme extension into preform domestic manufacturing represents the most penetrable white-space; align with Gujarat and Maharashtra cable assembly clusters through BIS-certified quality control partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty germanium-doped preform suppliers serving METI-coordinated Pacific cable initiatives with decade-long supply agreements. Long-term viability hinges on technology transfer capability for modified chemical vapor deposition processes. Watch for silicon photonics co-packaged optics convergence as inflection signal—precision-cleaved fiber array demand from OEMs indicates specification authority shift away from traditional cable manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Production | Yangtze Optical Fibre and Hengtong anchor feedstock continuity through captive synthesis facilities. |
| MIIT GB Certification Investment | Mechanical reliability standards enforcement creates compliance barrier for uncertified import competitors. |
| Direct Hyperscaler Specification Engineering | Microsoft and Google Singapore teams negotiate fiber arrays bypassing traditional cable manufacturer intermediation. |
| Vietnam Manufacturing Corridor Expansion | Hai Phong tariff advantages aggregate Japanese and Korean compound supply for ASEAN cable assembly. |
| Multicore Fiber Preform Development | 19-core and 24-core submarine variants compress raw material intensity per bit-transmitted-kilometer. |
Research Methodology
Initial hypotheses were tested against primary input from preform manufacturing executives, MIIT regulatory affairs specialists, hyperscaler fiber specification engineers, and submarine cable consortium procurement leads, then refined through secondary validation. Sources included MIIT GB standard filings, METI JIS C 6832 revision documentation, BharatNet tender records, customs data on silicon tetrachloride trade flows, and hyperscaler capital expenditure disclosures. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Demand-supply balance dynamics across the analysis window were modeled through preform draw tower utilization rates, chlorosilane capacity expansion pipelines, and sovereign infrastructure subsidy cycle phasing. Segmentation dimensions included material chemistry tier, application distance requirement, end-user backward integration depth, and regional regulatory cluster. CAGRs were derived from installed base depreciation curves and fiber count inflation in data center spine architectures.
Sensitivities concentrate around MIIT subsidy cycle compression, METI Pacific cable initiative funding authorization, and perfluorinated polymer substitution rates in hyperscale campuses. Forecasts reflect documented assumptions on infrastructure deployment timelines and certification harmonization progress. Material shifts in silicon photonics integration velocity or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Metal Fiber Felt Market
Fibers
Vinylon Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Precision Fiber Molding Market
Fibers
Global Nylon Monofilament Market
Fibers
Fiberglass Sunscreen Market
Fibers
North America Nanofiber Market
Fibers
Keratin Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Viscose Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Global Basalt Fiber Market
Fibers
Polycrystalline Alumina Fiber Market