
 Carbon Fiber Tapes Market | 2026-2036
Carbon Fiber Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Tapes Market Intelligence
The shift towards application-specific pre-kitted tape systems from standalone roll sales is rebalancing buyer preference towards suppliers offering integrated solutions. This modular approach simplifies inventory and production for OEMs. Hexcel Corporation leverages its deep aerospace relationships to offer these tailored kits for structural components. Solvay specializes in advanced thermoplastic composites, targeting next-generation aircraft programs. Toray Industries, Inc. sustains its market position through its extensive scale in precursor and fiber production.
Carbon fiber tapes are narrow, continuous strips of unidirectionally aligned carbon filaments consolidated within a polymer matrix. These materials, specified by parameters like fiber areal weight and thickness, are designed for automated tape laying (ATL) and automated fiber placement (AFP) processes. The aerospace application segment commands the highest value due to stringent qualification requirements and performance demands. In terms of technology, thermoset-based tapes remain dominant, but thermoplastic variants are gaining share due to recyclability and faster processing potential.
Material qualification and process validation are heavily influenced by aerospace regulators like the US Federal Aviation Administration (FAA). In Europe, compliance with frameworks such as REACH governs the chemical constituents used in the tape's polymer matrix. Adherence to quality management standards like ISO 9001 and the aerospace-specific AS9100 is a fundamental prerequisite for suppliers. Supplier success will hinge on navigating the complex material qualification pathways for next-generation thermoplastic composites in high-volume applications.
Market Dynamics
The fundamental dynamic in the carbon fiber tapes market is the tension between the high-performance, long-cycle qualification demands of the aerospace sector and the push for rapid, cost-effective industrialization from automotive and renewable energy applications. This divergence influences material development, process automation, and supply chain configuration.
Growth Catalysts
- Thermoplastic Innovations:Advancements in thermoplastic matrix tapes enable out-of-autoclave processing and welding, significantly reducing cycle times for high-volume automotive structural components and airframes.
- Wind Energy Expansion:The drive for larger wind turbine blades to increase energy capture efficiency necessitates the use of high-stiffness, low-weight carbon fiber tapes in spar caps, providing a significant demand pull.
- Emissions Regulations:Mandates in Europe and North America to reduce vehicle CO2 emissions push automotive OEMs to adopt lightweight composite materials, including carbon fiber tapes, for body-in-white and chassis applications.
Market Restraints
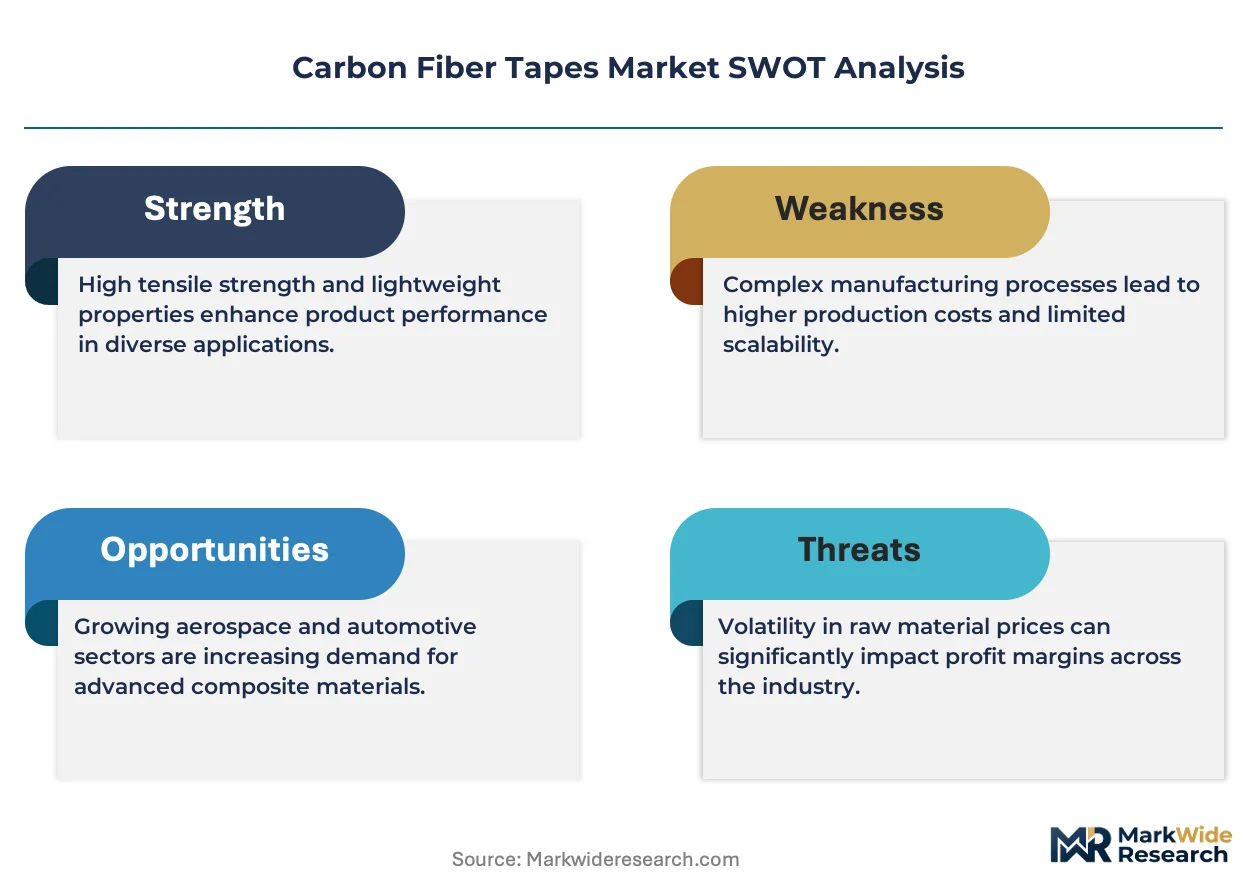
- Precursor Cost Volatility:The price of polyacrylonitrile (PAN), the primary precursor for aerospace-grade carbon fiber, is a significant component of tape cost and is subject to fluctuations based on energy and chemical feedstock prices.
- Thermoset Processing Speed:The long cure cycles required for traditional thermoset epoxy-based tapes create a bottleneck for high-rate production, limiting their use in mass-market automotive applications. -
- Substitution from High-Strength Steel:In some automotive applications, advances in ultra-high-strength steels (UHSS) offer a more cost-effective lightweighting solution, presenting a substitution threat for less critical structural components.
Strategic Opportunities
- Hydrogen Storage Vessels:The emerging hydrogen economy creates a substantial opportunity for filament-wound carbon fiber tapes in the manufacturing of Type IV and Type V composite overwrapped pressure vessels (COPVs) for vehicle and ground storage.
- Urban Air Mobility (UAM):The development of electric vertical take-off and landing (eVTOL) aircraft provides a new application segment for lightweight tapes in fuselages, wings, and rotor blades, with different qualification pathways than traditional aviation.
- Digital Manufacturing Integration:Combining automated tape laying (ATL) with digital twin models and in-process inspection sensors offers a path to certified, "as-built" quality data, reducing post-process inspection costs for aerospace OEMs.
Industry Challenges
- Aerospace Qualification Timelines:The multi-year process for qualifying a new tape material and its associated manufacturing process with regulators like the FAA and EASA remains a major barrier to entry and innovation.
- Skilled Technician Scarcity:A shortage of trained operators and programmers for complex automated fiber placement (AFP) and ATL systems constrains production capacity and increases labor costs for fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Tapes Market |
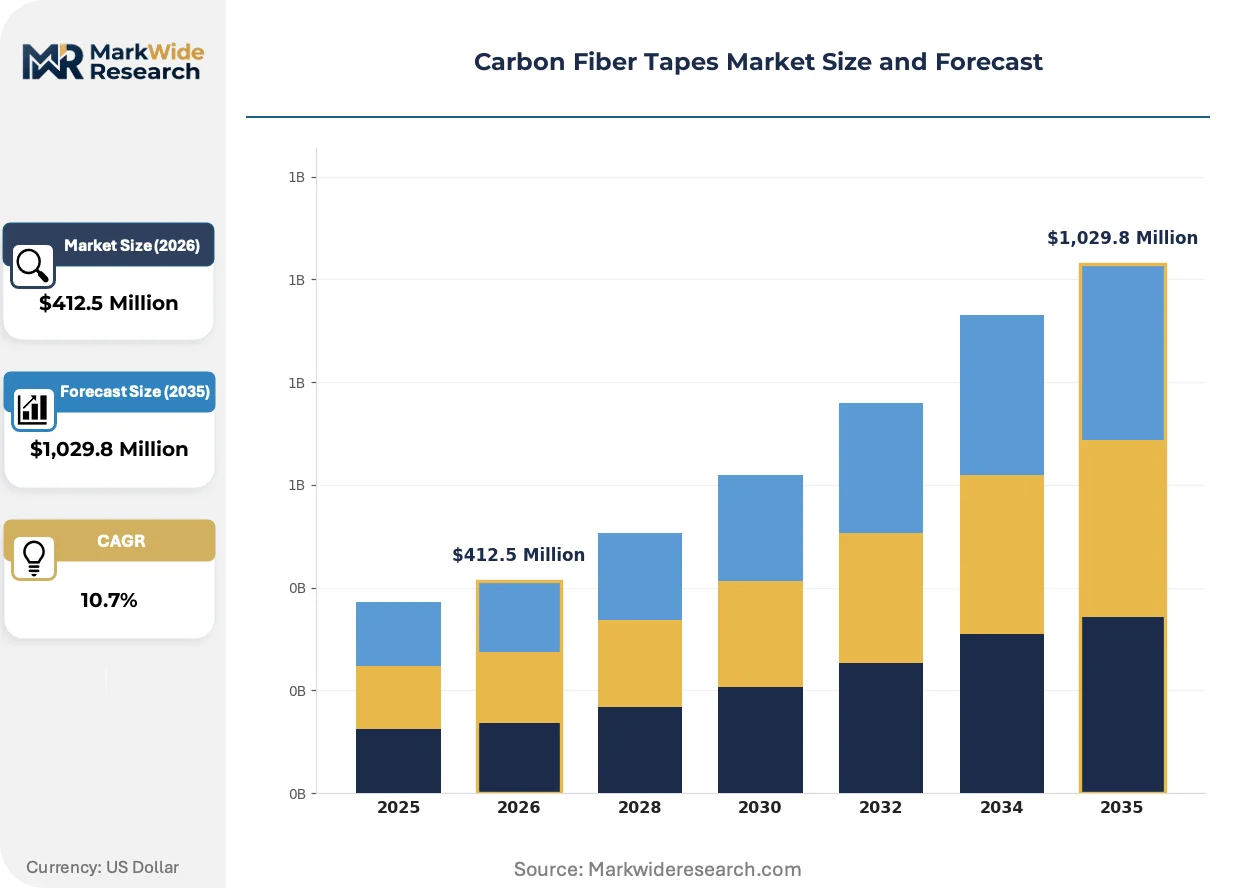
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,029.8 Million |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UD Tapes, Woven Tapes, Spread Tow Tapes, Braided Tapes, Multiaxial Tapes Technology: Thermoset, Thermoplastic, Prepreg, Polymer Matrix, Nano-enhanced Application: Aerospace, Wind Turbine Blades, Sporting Goods, Marine Equipment, Civil Engineering End User: OEMs, Aftermarket Suppliers, Research Institutes, Defense Contractors, Infrastructure Developers |
| Companies Covered | SGL Carbon, Solvay, Toray Industries, Inc., Toho Tenax Co., Ltd., SABIC, Hexcel Corporation, Mitsubishi Chemical Group Corporation, DowAksa Advanced Composites LLC, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Tapes Market Strategic Shifts & Innovations
The industrialization of composite manufacturing is the primary force shaping the carbon fiber tapes market. This involves a move away from manual, aerospace-centric methods towards automated, data-driven processes suitable for higher-volume sectors like automotive and renewable energy.
Automated Fiber Placement (AFP) systems are a key enabling technology for producing complex composite structures. Mid-tier industrial and automotive parts manufacturers are increasingly adopting smaller, more modular AFP work cells to gain production flexibility. This adoption of more accessible automation is decentralizing advanced composite fabrication capabilities beyond the traditional domain of large aerospace prime contractors.
European Union regulations such as REACH are altering material formulation strategies for tape manufacturers. The framework's restrictions on specific chemicals used in some epoxy resins and curing agents compel suppliers to invest in R&D for compliant alternatives or accelerate their shift toward thermoplastic polymers. This regulatory pressure most directly impacts suppliers of thermoset tapes, who must reformulate products to maintain access to the European aerospace and industrial markets.
A significant behavioral shift is occurring as customers transition from purchasing standard tape rolls to procuring complete, pre-kitted systems tailored for a specific component. This disrupts the traditional role of the supplier, demanding capabilities in part design, nesting optimization, and just-in-time logistics rather than just material sales. This trend is most advanced within the aerospace industry, where airframers use kitting to simplify inventory management and streamline final assembly workflows.
Carbon Fiber Tapes Market Segmentation
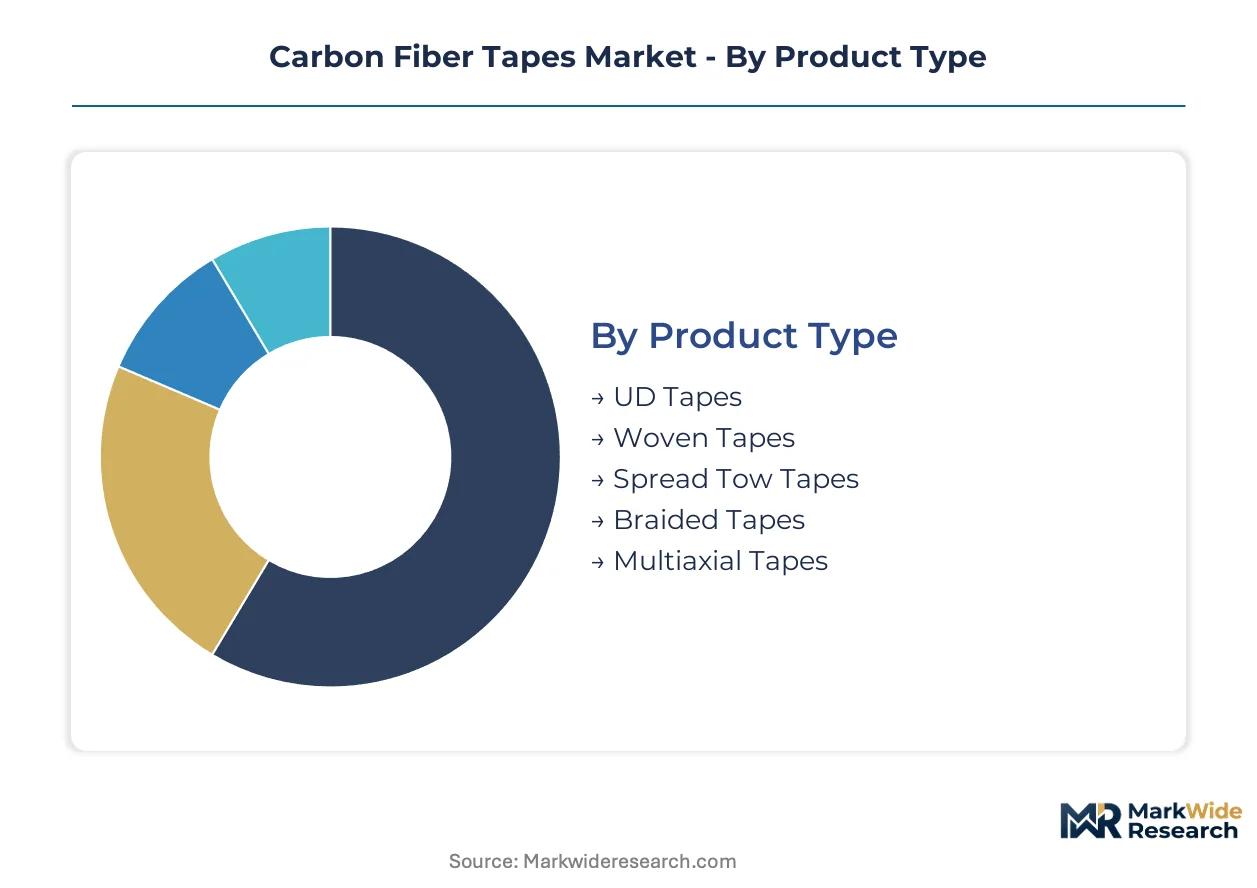
Segmentation in the carbon fiber tapes market reveals how material properties and processing methods align with diverse industry requirements. Understanding these distinctions helps suppliers tailor product offerings and development strategies. This granular analysis highlights specific demand drivers and technological preferences across various end-use sectors.
Product Type:
Buyers in the product type category differentiate based on fiber orientation, structural performance needs, and manufacturing process compatibility.
- UD Tapes:These tapes feature carbon filaments aligned in a single direction, maximizing strength and stiffness along the fiber axis. Aerospace demands UD tapes for primary structural components, driven by stringent performance for lightweighting.
- Spread Tow Tapes:Spread tow tapes utilize flattened fiber bundles, enabling lower ply thickness and reduced crimp, which enhances mechanical properties. Wind turbine blade manufacturers seek these tapes for spar caps, optimizing aerodynamic efficiency.
- Woven Tapes:These interlace carbon fibers, providing balanced mechanical properties and improved handleability for various composite structures.
- Braided Tapes:Braided tapes create seamless, continuous structures, offering excellent damage tolerance and conformability for complex geometries.
- Multiaxial Tapes:Multiaxial tapes combine fibers in multiple orientations within a single ply, allowing highly customized load path management in composite designs.
Volume sits with UD Tapes; growth tilts toward Spread Tow Tapes.
Technology:
Technology choices are primarily driven by desired processing characteristics, end-use performance requirements, and regulatory compliance.
- Thermoset:Thermoset tapes employ resins that undergo irreversible chemical curing, providing high temperature resistance and excellent mechanical properties. Aerospace and defense sectors rely on thermoset systems due to proven long-term performance.
- Thermoplastic:Thermoplastic tapes utilize polymer matrices that can be repeatedly melted and reformed, enabling faster processing cycles, welding, and improved recyclability. Automotive OEMs adopt thermoplastics for high-volume structural components.
- Prepreg:Prepreg refers to carbon fiber tapes pre-impregnated with a resin system, ensuring consistent fiber-to-resin ratio for precise manufacturing.
- Polymer Matrix:This segment encompasses the broad range of polymer materials used to bind carbon fibers, influencing toughness and chemical resistance.
- Nano-enhanced:Nano-enhanced tapes incorporate nanoparticles into the polymer matrix, improving properties such as interlaminar toughness and electrical conductivity.
Thermoset technologies demonstrate market maturity; thermoplastic variants are rapidly expanding their market penetration.
Application:
Application segments differentiate based on the specific performance requirements, structural integrity demands, and certification landscapes of each industry.
- Aerospace:This application demands the highest performance from carbon fiber tapes for structural components in aircraft, rockets, and satellites. Regulators like the FAA ensure materials meet extreme safety and durability standards.
- Wind Turbine Blades:Carbon fiber tapes are critical for manufacturing larger, more efficient wind turbine blades, particularly in spar caps, to achieve high stiffness and reduce weight. Renewable energy expansion drives sustained demand.
- Sporting Goods:This segment utilizes carbon fiber tapes for lightweight, high-strength equipment like bicycles and tennis rackets, enhancing athletic performance.
- Marine Equipment:Carbon fiber tapes reduce weight and increase stiffness in marine applications such as high-performance yachts, improving speed and fuel efficiency.
- Civil Engineering:Civil engineering applications employ carbon fiber tapes for structural reinforcement in bridges and buildings, extending infrastructure lifespan.
Aerospace commands the highest value per unit; wind turbine blades generate substantial volume demand.
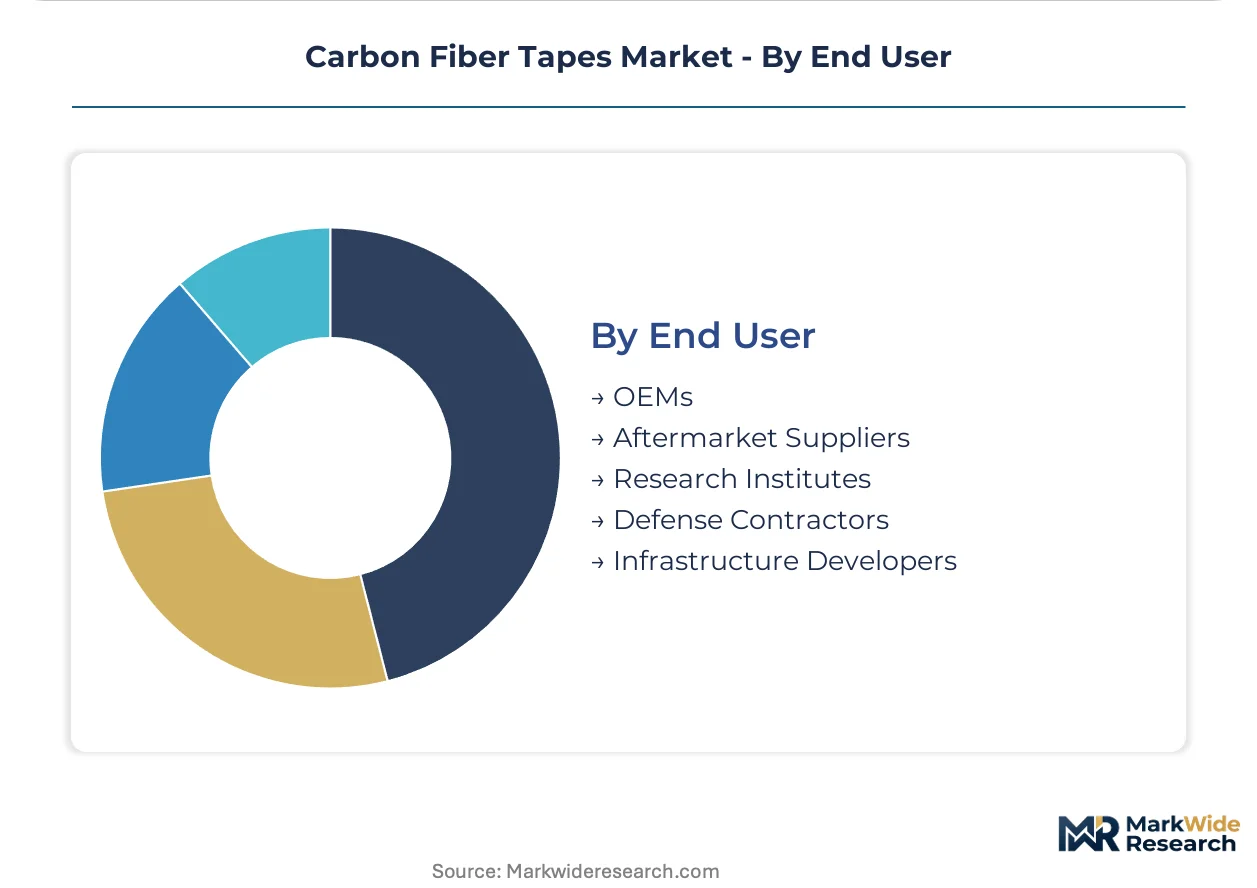
End User:
End users are distinguished by their role in the value chain, procurement models, and the specific stage of product development they represent.
- OEMs:Original Equipment Manufacturers integrate carbon fiber tapes directly into their final products, such as aircraft, automobiles, or wind turbines. Their procurement focuses on high-volume supply, quality, and integrated kitting solutions.
- Defense Contractors:Defense contractors utilize carbon fiber tapes for military aircraft, UAVs, and ballistic protection systems, where extreme performance and reliability are paramount. Procurement involves adherence to strict military specifications.
- Aftermarket Suppliers:These suppliers provide carbon fiber tape-based components for repair, maintenance, and upgrades of existing products, supporting longevity.
- Research Institutes:Research institutes consume carbon fiber tapes for material science studies, process optimization, and development of next-generation composite technologies.
- Infrastructure Developers:Infrastructure developers apply carbon fiber tapes for strengthening and rehabilitating civil structures, improving resilience and extending service life.
OEMs represent the primary strategic customer; research institutes drive future innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global carbon fiber tapes market exhibits a distinct geographical divide, with advanced material production often concentrated in East Asian nations while high-value consumption centers reside in North America and Western Europe. This dynamic influences supply chain logistics and material qualification pathways. Demand for specific material types varies significantly by region, driven by local industrial strengths.
United States
Demand for carbon fiber tapes in the United States is strong from aerospace structural components and advanced defense applications. The US Federal Aviation Administration (FAA) sets rigorous qualification standards for these materials. Aerospace manufacturing clusters in Seattle and Wichita continue to drive innovation and consumption for high-performance composites.
Germany
Germany represents a significant market for carbon fiber tapes, particularly for high-performance automotive applications and large wind turbine blades. Compliance with EU Green Deal initiatives and REACH regulations influences material formulation. The automotive industry in Stuttgart and the renewable energy sector in Saxony remain key consumption hubs.
France
Aerospace manufacturing in France provides substantial demand for carbon fiber tapes, especially for commercial aircraft programs. The European Union Aviation Safety Agency (EASA) dictates stringent certification requirements for these critical materials. Toulouse, home to major aerospace manufacturers, serves as a primary center for advanced composite integration.
China
China's market for carbon fiber tapes is expanding rapidly, fueled by wind energy expansion and electric vehicle lightweighting initiatives. The country's dual carbon goals accelerate the adoption of advanced materials for sustainability. Industrial clusters in the Yangtze River Delta drive both automotive and wind turbine blade manufacturing.
Japan
Japan maintains a strong position in advanced materials, with carbon fiber tapes seeing demand from automotive applications and specialized industrial equipment. The Ministry of Economy, Trade and Industry (METI) supports research and development in high-performance composites. Production and innovation centers in Ishikawa and Nagoya contribute to global supply.
Carbon Fiber Tapes Market Key Industry Players
The competitive structure tilts toward integrated solution providers and specialized material developers in the carbon fiber tapes market. Consolidation occurs through strategic acquisitions and technology licensing, as companies seek to broaden their product portfolios. Key competitive moves include capacity expansion and the formation of strategic partnerships to address specific application needs.
Solvay, Hexcel Corporation, and Toray Industries, Inc. exemplify different strategic positions within the market. Solvay, a Belgian multinational, occupies a position as a specialist in advanced thermoplastic composites, targeting next-generation aircraft programs. Hexcel Corporation, a US-based entity, represents a key player leveraging deep aerospace relationships for tailored structural component kits. Toray Industries, Inc., a Japanese conglomerate, anchors its market position through extensive precursor and fiber production capabilities.
| Leading Market Players |
|---|
| SGL Carbon |
| Solvay |
| Toray Industries, Inc. |
| Toho Tenax Co., Ltd. |
| SABIC |
| Hexcel Corporation |
| Mitsubishi Chemical Group Corporation |
| DowAksa Advanced Composites LLC |
| Teijin Limited |
| Others |
Cost & Logistics Intelligence
Polyacrylonitrile (PAN) precursor cost, a significant input for carbon fiber production, directly influences the pricing of carbon fiber tapes for downstream manufacturers. This upstream volatility translates into variable material costs for OEMs integrating these advanced composites.
Pricing Analysis
Cost-down pressure on automotive OEMs accelerates due to the increasing adoption of ultra-high-strength steels and thermoplastic variants. Pricing in this market often follows a contract-based long-term offtake model, particularly for high-volume aerospace and wind energy applications. Price differentiation stems from the stringent certification level required for aerospace-grade materials, contrasted with more volume-driven industrial applications. Aerospace customers exhibit the lowest price sensitivity, prioritizing performance and qualification, while automotive OEMs are highly sensitive to material cost.
Supply Chain Analysis
Single-source vulnerability sits with the limited number of global polyacrylonitrile (PAN) precursor suppliers, primarily concentrated in Japan and the United States. The supply chain for carbon fiber tapes relies heavily on these PAN fibers and specialized polymer resins. Precursor cost volatility represents a significant structural risk, impacting material stability and long-term planning for tape manufacturers. Distribution typically runs through direct sales channels to large OEMs, with specialized distributors serving smaller fabricators and research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon fiber tapes market presents a significant cost-of-compliance story, where adherence to aerospace qualification standards, such as those set by the US Federal Aviation Administration (FAA), creates a substantial barrier to entry for new suppliers. This regulatory moat ensures validated materials meet extreme performance and safety demands.
For Market Incumbents:Extend deep aerospace relationships by offering integrated, application-specific pre-kitted tape systems to combat emerging substitution threats from high-strength steels. Invest in advanced thermoplastic processing R&D to accelerate material qualification pathways for next-generation aircraft programs. Leverage digital manufacturing integration to reduce post-process inspection costs and maintain a competitive edge. This strategy defends against new entrants targeting faster processing cycles.
For New Entrants and Emerging Players:A price-point gap exists in industrial applications, allowing entry for suppliers offering cost-effective carbon fiber tapes for wind energy and automotive sectors. Target the emerging urban air mobility (UAM) segment with lightweight thermoplastic solutions, leveraging different qualification pathways than traditional aviation. Develop modular automated fiber placement (AFP) work cells to enable more accessible advanced composite fabrication for mid-tier manufacturers. Focus on sustainable thermoplastic materials for rapid processing and recyclability.
For Investors and Strategic Acquirers:Regulatory approval of new thermoplastic composite systems by the FAA and EASA is the leading indicator that high-volume applications are viable, signaling long-term market growth potential over the next decade. Seek out specialized material developers with strong intellectual property in thermoplastic matrices or integrated solution providers offering pre-kitted systems. Monitor investments in hydrogen storage vessel manufacturing capacity as a key demand driver beyond traditional aerospace.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Thermoplastic Tapes | This initiative supports the shift towards faster processing cycles for automotive and UAM applications. |
| Technology Licensing for Advanced AFP Systems | Licensing enables broader adoption of automated composite manufacturing processes across diverse industries. |
| Joint Venture in Hydrogen Storage Vessel Manufacturing | This move capitalizes on the emerging demand for Type IV and Type V composite pressure vessels. |
| Green Manufacturing Transition to REACH-Compliant Resins | Ensuring compliance with European Union regulations maintains market access for thermoset tape suppliers. |
| Long-term Supply Agreements with Wind Turbine Blade OEMs | These agreements secure consistent demand for high-stiffness carbon fiber tapes in renewable energy. |
Research Approach
Document review covered corporate filings, industry association reports, patent databases, and regulatory documents from the FAA and EASA, complemented by interviews with industry stakeholders. Primary research included conversations with tape manufacturers, aerospace OEMs, wind turbine blade fabricators, and material scientists. This approach allowed for bottom-up data collection and top-down validation, triangulating insights across diverse sources.
Volume and value projections were generated through a robust analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, technology, application, end user, and regional demand. Compound annual growth rates were derived from historical trends and anticipated shifts, factoring in new aircraft program schedules and increasing wind turbine blade size trends.
Inputs from publicly available data and expert interviews were available through the study window; gaps in real-time supply chain data introduce uncertainty bands. Forecasts reflect assumptions regarding precursor price volatility and future regulatory changes impacting material adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Artificial Muscle Fibers Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Global Basalt Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Global Concrete Fiber Market
Fibers
Carbon Fiber Filament Market
Fibers
Viscose Market
Fibers
Metal Fiber Felt Market
Fibers
Fiberglass Mat Market
Fibers
Sisal Market
Fibers
Bleached Linter Cellulose Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
North America Nanofiber Market
Fibers
Activated Carbon Fiber (ACF) Market