
 Fiber Metal Laminate (FML) Market | 2026-2036
Fiber Metal Laminate (FML) Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Metal Laminate (FML) Market Analytics
Commercial aviation is realigning toward fuel-efficient airframes. Hexcel Corporation leverages its carbon fiber prepreg expertise to supply aerospace-grade FML precursors. Toray Industries anchors Japanese supply chains with high-modulus fiber reinforcements. Airbus Group dominates downstream integration through proprietary GLARE laminate technology on A380 and future programs.
Fiber metal laminates bond thin aluminum or steel sheets with fiber-reinforced polymer cores to achieve fatigue resistance beyond monolithic metals. GLARE variants stack 2024-T3 aluminum with S2-glass or carbon fiber epoxy layers, delivering 15-30% weight reduction versus conventional alloys. Aluminum laminate products occupy the mature volume tier across commercial aviation programs. Hybrid laminate formulations represent the fastest-expanding segment as OEMs pursue tailored stiffness-to-density ratios. Structural components applications command the deepest margin pools due to qualification barriers and long-term supply agreements.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks mandate damage tolerance and fatigue testing for primary aircraft structures. REACH compliance in Europe restricts hexavalent chromium surface treatments, pushing suppliers toward sol-gel and plasma electrolytic oxidation bonding processes. Stakeholders must monitor evolving MDR traceability requirements and dual carbon regulatory timelines in China as these reshape material qualification and cross-border certification reciprocity.
Market Dynamics
Aerospace OEM procurement is consolidating around damage-tolerant composite-metal hybrids as FAA and EASA fatigue-resistance mandates harden qualification barriers for primary structures.
Growth Catalysts
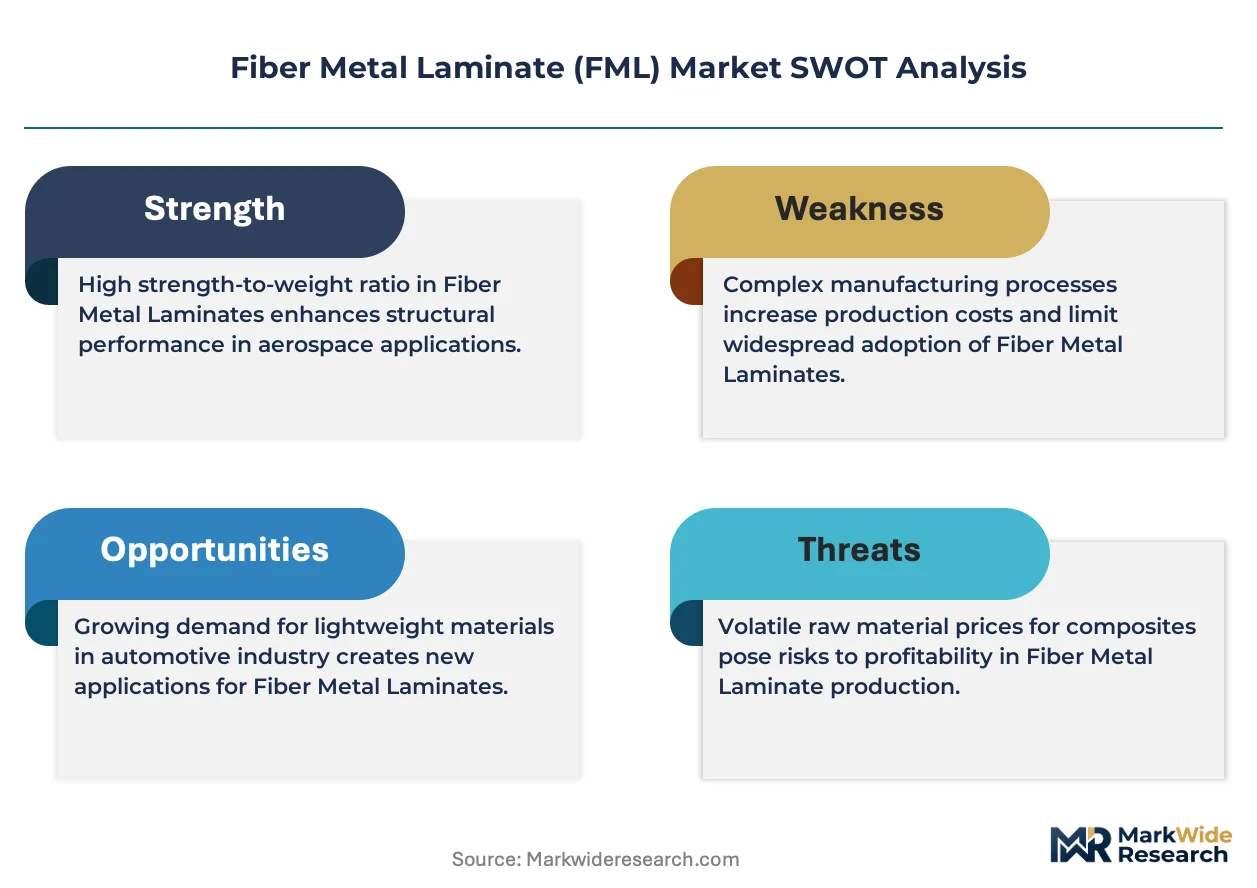
- CS-25 Certification Requirements:EASA's damage-tolerance standards for primary airframes compel adoption of GLARE and hybrid laminate systems in next-generation fuselage programs.
- Glass Fiber Epoxy Advancement:S2-glass reinforced prepregs deliver 15-30% weight reduction versus monolithic aluminum, accelerating substitution in commercial aviation structural applications.
- German Production Clustering:Airbus and Premium AEROTEC anchor FML fabrication capacity in Hamburg and Augsburg, concentrating specialized tooling and bonding expertise.
Market Restraints
- Aramid Fiber Price Volatility:Raw material input swings for high-performance reinforcements compress margin predictability at precursor suppliers.
- Autoclave Capacity Concentration:Curing infrastructure for aerospace-grade laminates clusters among tier-one processors in Germany and Japan, creating supply bottleneck risk.
- Thermoplastic Tape Substitution:Automated fiber placement of PEEK and PPS composites threatens FML penetration in secondary structures where damage tolerance is less critical.
Strategic Opportunities
- Urban Air Mobility Airframes:eVTOL manufacturers in California and Texas seek certified lightweight structures for electric propulsion integration.
- Sol-Gel Bonding Processes:REACH-mandated elimination of hexavalent chromium surface treatments opens qualification pathways for plasma electrolytic oxidation suppliers.
- Rail Rolling Stock Panels:European crashworthiness regulations for high-speed train carriages create adjacent demand for impact-resistant aluminum-fiber hybrids.
Industry Challenges
- Adhesive Bonding Technician Scarcity:Qualified personnel for autoclave operation and non-destructive inspection of hybrid laminates remain concentrated at legacy aerospace sites.
- Dual Certification Timelines:Simultaneous FAA Part 25 and EASA CS-25 qualification for new FML formulations extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Metal Laminate (FML) Market |
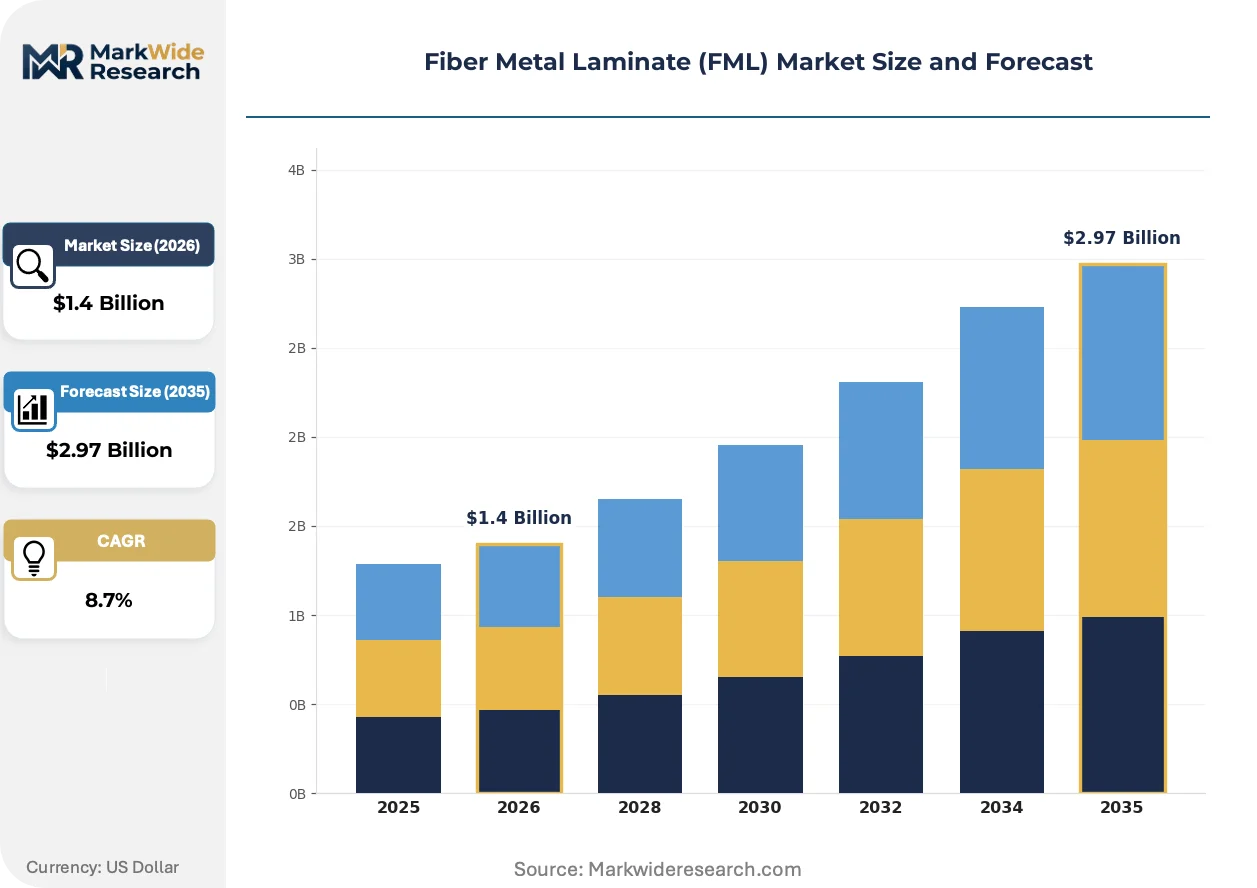
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Laminate, Steel Laminate, Aluminum Laminate, Composite Laminate End User: Aerospace, Automotive, Marine, Defense Application: Structural Components, Insulation, Surface Protection, Lightweight Parts Manufacturing Stage: Forming, Machining, Assembly, Surface Finishing |
| Companies Covered | Hexcel Corporation, Toray Industries, Inc., Airbus Group, Premium AEROTEC GmbH, Fokker Technologies, Cytec Solvay Group, Teijin Limited, 3M Company, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Metal Laminate (FML) Market Evolving Landscape
Process automation and regulatory chemistry bans are compressing traditional bonding workflows while expanding addressable applications beyond legacy aviation programs.
Automated fiber placement of thermoplastic tapes is unifying the fabrication speed of composites with the damage tolerance of metal laminates. Tier-one suppliers in Japan and Germany are retrofitting AFP lines for hybrid laminate precursors. This convergence is compressing the cost gap between FMLs and monolithic thermoset composites in secondary structures.
REACH Annex XVII restrictions on hexavalent chromium are forcing surface treatment migration toward sol-gel and plasma electrolytic oxidation bonding. European suppliers face 2024-2026 compliance deadlines for existing qualification portfolios. MRO facilities in France and Germany are re-equipping pretreatment lines to maintain airworthiness certification reciprocity.
Airline procurement departments are bundling long-term airframe contracts with aftermarket repair commitments. OEMs now specify FML suppliers based on global depot network coverage rather than unit cost alone. This preference shift concentrates supplier selection among vertically integrated processors with captive MRO infrastructure.
Fiber Metal Laminate (FML) Market Segmentation
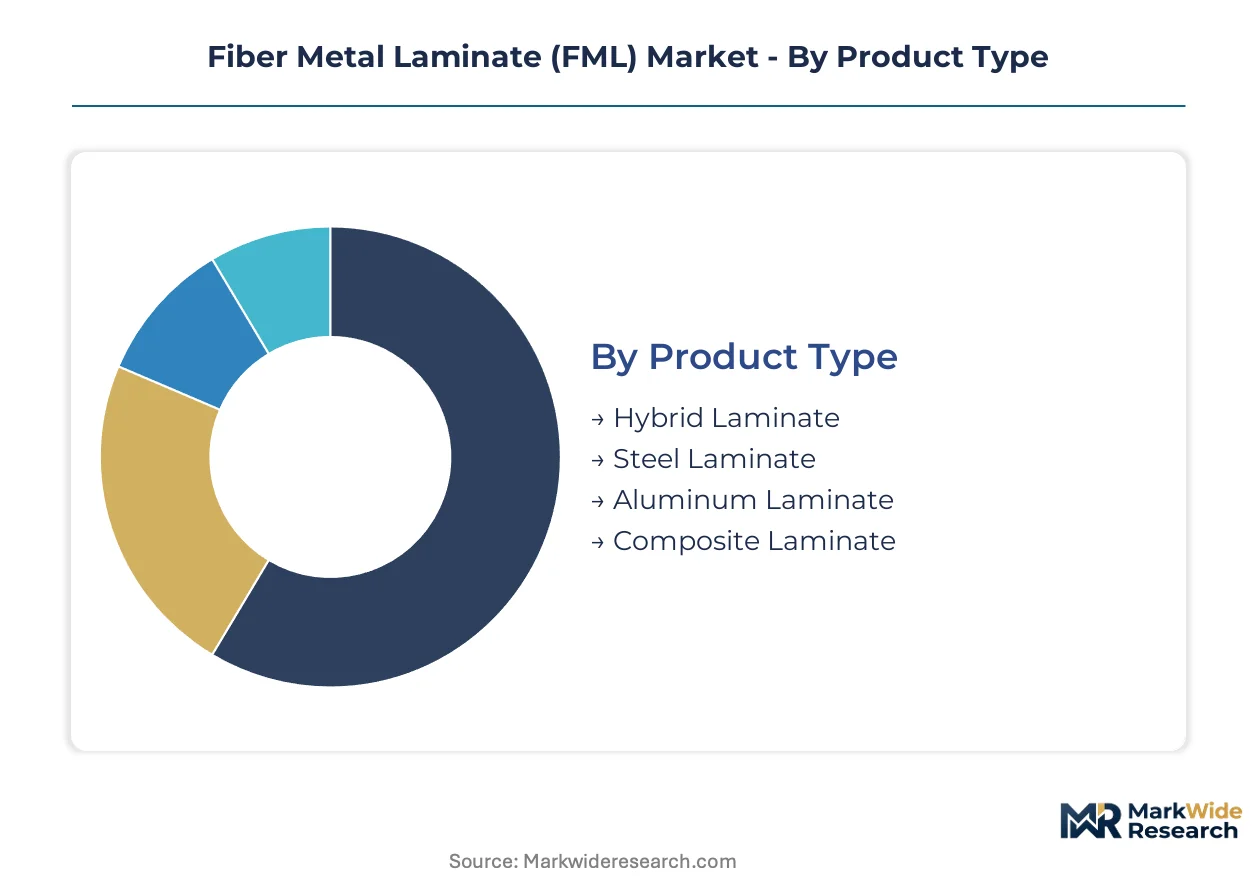
FML procurement decisions hinge on certification grade, damage-tolerance requirements, and bonding process compatibility. Segmentation reveals where capital deployment concentrates and which formulations command premium qualification timelines.
Product Type:
Capital intensity escalates with fiber-metal interface complexity and autoclave curing cycles. Aluminum laminates require moderate tooling investment. Hybrid formulations demand multi-material bonding expertise and extended qualification protocols.
- Aluminum Laminate:Stacks 2024-T3 or 7075-T6 sheets with S2-glass or carbon fiber epoxy cores. Airbus A380 fuselage panels anchor demand in Germany and France, where GLARE qualification sets the benchmark for fatigue resistance. Mature supply chains and established FAA Part 25 certification pathways sustain volume leadership despite weight penalties versus hybrid alternatives.
- Hybrid Laminate:Integrates discontinuous metal layers with high-modulus fiber prepregs to achieve tailored stiffness-to-density ratios. eVTOL manufacturers in California and Texas are specifying hybrid systems for electric propulsion integration, driven by CS-25 damage-tolerance mandates for primary structures. Plasma electrolytic oxidation bonding investments are expanding fastest here.
- Steel Laminate:Bonds martensitic or austenitic steel sheets with glass fiber cores for impact-resistant rail and marine applications.
- Composite Laminate:Full polymer-fiber constructions without metal layers, competing at the margin in secondary structures.
Aluminum laminate absorbs the bulk of installed capacity; hybrid laminate is expanding most quickly.
End User:
Procurement scale and certification stringency separate volume tiers. Aerospace programs demand multi-year qualification cycles. Automotive and marine buyers prioritize unit economics over damage-tolerance redundancy.
- Aerospace:Primary fuselage and wing structures require EASA CS-25 and FAA Part 25 fatigue certification. Airbus Hamburg and Premium AEROTEC Augsburg concentrate fabrication capacity for A350 and future narrowbody programs. Long-term supply agreements now bundle aftermarket repair commitments with airframe contracts.
- Defense:Military airframe specifications emphasize ballistic tolerance and repairability in field conditions. US DoD procurement is qualifying FML for rotorcraft and unmanned platforms where crashworthiness requirements exceed commercial standards.
- Automotive:Crash structures and battery enclosures seek weight reduction without thermoset recycling constraints.
- Marine:Hull panels and superstructures exploit corrosion resistance in saltwater environments.
Aerospace commands the deepest margin pools; defense procurement is climbing the fastest on platform modernization timelines.
Application:
Functional requirements dictate material selection and bonding process. Structural loads demand full qualification. Surface and insulation applications tolerate lower-tier formulations.
- Structural Components:Primary load-bearing elements including fuselage skins, wing leading edges, and pressure bulkheads. These applications concentrate in Hamburg and Toulouse, where autoclave capacity and adhesive bonding technician scarcity create supply bottlenecks. REACH-mandated hexavalent chromium elimination is forcing sol-gel process migration.
- Surface Protection:Erosion shields and leading-edge protection for rotorcraft and high-speed trains. European rail rolling stock regulations are expanding addressable demand beyond aviation.
- Lightweight Parts:Secondary brackets and fairings where thermoplastic tape substitution threatens penetration.
- Insulation:Thermal and acoustic barriers in engine nacelles and auxiliary power units.
Structural components lock in the longest supply agreements; surface protection is gaining share fastest on adjacent market expansion.
Manufacturing Stage:
Process control requirements and capital equipment specialization fragment the value chain. Forming and surface finishing claim the tightest capacity constraints.
- Forming:Hot and cold forming of metal-fiber stacks into complex curvatures. German and Japanese tier-one suppliers control superplastic forming presses and creep-forming tooling. Autoclave capacity concentration in Hamburg and Nagoya creates regional supply bottlenecks for aerospace-grade laminates.
- Surface Finishing:Sol-gel and plasma electrolytic oxidation pretreatment for REACH-compliant bonding. European MRO facilities in France and Germany are re-equipping lines to maintain certification reciprocity.
- Machining:Precision trimming and hole drilling for fastener integration.
- Assembly:Adhesive bonding and mechanical fastening of cured laminate panels.
Forming absorbs the bulk of fixed capital investment; surface finishing is expanding most quickly on regulatory chemistry bans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones in Hamburg and Toulouse concentrate FML fabrication infrastructure, while tax-advantaged aerospace clusters in Japan and California draw precursor supply investment. Regulatory reciprocity agreements between FAA and EASA anchor cross-border qualification pathways.
Germany
Airbus Hamburg anchors GLARE laminate production for A350 and future narrowbody programs. EASA CS-25 certification requirements mandate damage-tolerance testing for primary fuselage structures. Premium AEROTEC Augsburg concentrates autoclave capacity and adhesive bonding expertise for hybrid laminate fabrication.
United States
California and Texas eVTOL manufacturers specify certified lightweight structures for electric propulsion integration. FAA Part 25 airworthiness standards shape qualification timelines for primary aircraft structures. Boeing Charleston and Spirit AeroSystems Wichita maintain legacy FML repair and modification capacity.
Japan
Toray Industries Nagoya anchors high-modulus carbon fiber precursor supply for aerospace-grade laminates. METI industrial standards govern composite-metal bonding process certification. Chubu region autoclave infrastructure serves as regional curing capacity for tier-one processors.
France
Airbus Toulouse integrates GLARE technology across A380 heritage programs and next-generation designs. REACH Annex XVII restrictions on hexavalent chromium force sol-gel surface treatment migration at MRO facilities. French aerospace suppliers re-equip pretreatment lines to maintain EASA certification reciprocity.
United Kingdom
BAE Systems and GKN Aerospace sustain defense FML qualification for rotorcraft and unmanned platforms. UK Ministry of Defence procurement emphasizes ballistic tolerance and field repairability. Southwest England composites clusters retain adhesive bonding technician pools for legacy program support.
Fiber Metal Laminate (FML) Market Competitive Landscape
Top-tier vendors anchor aerospace-grade laminate supply, while mid-tier fabricators concentrate on adjacent rail and marine applications. The vendor base stratifies around qualification depth rather than unit volume. Three archetypes dominate: vertically integrated OEMs with captive FML production, specialized tier-one laminate processors with multi-program certification, and precursor suppliers controlling fiber and resin formulation. Capacity expansion and strategic technology licensing represent the dominant competitive moves as firms secure long-term airframe contracts.
Within the tier-one processor archetype, Premium AEROTEC GmbH and Fokker Technologies exemplify European fabrication specialists with established EASA qualification pathways. Hexcel Corporation occupies a position among North American precursor suppliers leveraging carbon fiber prepreg expertise. Toray Industries, Inc. anchors Japanese supply chain concentration for high-modulus fiber reinforcements. These three represent distinct geographic and functional specializations within the competitive structure.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries, Inc. |
| Airbus Group |
| Premium AEROTEC GmbH |
| Fokker Technologies |
| Cytec Solvay Group |
| Teijin Limited |
| 3M Company |
| Alcoa Corporation |
| Others |
Value Network & Pricing Analysis
Automated fiber placement of thermoplastic tapes is compressing fabrication economics while concentrating bargaining power among tier-one processors with captive autoclave infrastructure in Germany and Japan. This dual shift rewards suppliers who control both bonding process qualification and curing capacity, while squeezing margins at precursor-only vendors exposed to aramid fiber price volatility.
Pricing Analysis
Short-lead-time premiums for certified aerospace-grade FML panels run 15-25% above contract baselines, while spot inventory of aluminum laminate precursors trades at discounts to long-term offtake agreements. Three-tier pricing structure across aerospace-certified, industrial-grade, and emerging eVTOL specifications reflects EASA CS-25 qualification depth as the primary differentiation driver. Cost compression in hybrid laminate segments is intensifying because plasma electrolytic oxidation equipment amortization spreads across smaller production batches. Automotive battery enclosure buyers exhibit highest price sensitivity; Airbus and Boeing procurement teams prioritize global depot network coverage over unit cost.
Supply Chain Analysis
Domestic-content mandates in US defense procurement and China's dual carbon regulatory timelines are reshaping sourcing patterns for high-modulus fiber reinforcements. Geographic supply concentration centers on Germany, Japan, and the United States, with Hamburg and Nagoya anchoring autoclave curing capacity. Raw material flows draw from S2-glass rovings, carbon fiber prepregs, and 2024-T3 aluminum sheet. Single-source vulnerability at plasma electrolytic oxidation equipment suppliers creates qualification bottlenecks. Distribution runs through tier-one laminate processors with captive MRO infrastructure rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FML sector sits at a technology-transition inflection as sol-gel and plasma electrolytic oxidation bonding displace hexavalent chromium surface treatments mandated by REACH Annex XVII. Legacy suppliers must requalify entire process portfolios while defending against thermoplastic tape substitution in secondary structures.
For Market Incumbents: Hedge thermoplastic tape displacement risk by deepening captive MRO infrastructure and securing long-term airframe contracts bundled with aftermarket repair commitments. Airbus procurement teams now specify suppliers based on global depot network coverage rather than unit cost alone. Premium AEROTEC and Fokker Technologies demonstrate defensible positioning through EASA CS-25 qualification depth and Hamburg-Augsburg production clustering. For New Entrants and Emerging Players: Enter via European rail rolling stock crashworthiness regulations and Texas-California eVTOL airframe programs where damage-tolerance requirements exceed incumbent capacity. Urban air mobility manufacturers seek certified lightweight structures for electric propulsion integration without legacy aerospace supplier lead times. Target sol-gel bonding process qualification as the go-to-market angle, leveraging REACH-mandated hexavalent chromium elimination to bypass entrenched incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in tier-one laminate processors with multi-program EASA and FAA certification, vertical integration into precursor supply, and captive MRO infrastructure. Long-term viability hinges on 5-10 year airframe program visibility and bonding process technology transitions. Watch plasma electrolytic oxidation equipment supplier consolidation as the inflection signal—qualification bottlenecks there will determine which processors capture hybrid laminate volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Electrolytic Oxidation Equipment Investment | REACH Annex XVII compliance opens qualification pathways beyond hexavalent chromium-dependent incumbents. |
| Long-term Supply Agreement with eVTOL OEM | Urban air mobility airframe contracts bundle certified lightweight structures with electric propulsion integration. |
| Captive MRO Infrastructure Expansion | Airbus procurement now prioritizes global depot network coverage over unit cost in supplier selection. |
| Hybrid Laminate Process Qualification | Tailored stiffness-to-density ratios capture fastest-expanding segment in next-generation fuselage programs. |
| Rail Rolling Stock Panel Certification | European crashworthiness regulations create adjacent demand for impact-resistant aluminum-fiber hybrids. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across aerospace procurement directors, adhesive bonding technicians, autoclave operations managers, and EASA certification specialists. EASA CS-25 documentation, FAA Part 25 airworthiness standards, REACH Annex XVII compliance databases, and METI industrial standards provided regulatory scaffolding. Bottom-up triangulation across laminate processor capacity utilization and top-down validation against airframe OEM procurement disclosures ensured cross-verification.
Granularity-level modeling distinguished aluminum laminate, hybrid laminate, steel laminate, and composite laminate product types; aerospace, defense, automotive, and marine end users; and structural components, surface protection, lightweight parts, and insulation applications. CAGRs derived from segment-level volume builds and value-per-unit assumptions across the projection horizon. Forecast inputs incorporated EASA-FAA certification timeline reciprocity, autoclave capacity expansion schedules, and REACH compliance deadline clustering.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aramid fiber price volatility and thermoplastic tape substitution acceleration. Forecasts reflect assumptions around EASA CS-25 damage-tolerance standard continuity, dual carbon regulatory timeline enforcement in China, and adhesive bonding technician availability at legacy aerospace sites. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Viscose Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Global Fiberglass Mold Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Ceramic Fiber Market
Fibers
Fiberglass Mat Market
Fibers
Bleached Linter Cellulose Market
Fibers
Renewable Carbon Fibers Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Thermoformed Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Citrus Pulp Fiber Market