
 Keratin Market | 2026-2036
Keratin Market Size, Share, and Industry Trends Forecast 2026-2036
Keratin Market Intelligence
Modular keratin dosing—single-use ampoules and at-home treatment kits—is decoupling professional salon services from brand loyalty, letting consumers mix salon-grade formulas with retail maintenance cycles. BASF SE leverages its specialty chemicals portfolio to supply hydrolyzed keratin precursors to formulators across Europe. Croda International Plc anchors its position through biotechnology-derived keratin alternatives that bypass animal sourcing constraints. L'Oréal S.A. competes by controlling distribution density in professional beauty channels across France and Brazil.
Keratin denotes a family of fibrous structural proteins rich in cysteine, characterized by high disulfide bond density that confers mechanical durability and water resistance; industrial grades typically achieve molecular weights between 10 and 150 kDa depending on hydrolysis intensity, with primary commercial purpose spanning cosmetic film-formation, pharmaceutical wound scaffolding, and nutraceutical amino acid supplementation. Hydrolyzed Keratin leads product type revenue due to its compatibility with aqueous cosmetic bases and established INCI registry status, while Keratin Treatments command premium positioning in salon channels where formaldehyde-free certification now gates market access. Animal-Based sourcing still dominates volume but faces margin compression from Plant-Based alternatives as European formulators navigate ECHA scrutiny on bovine-derived inputs.
FDA oversight of cosmetic safety through the Modernization of Cosmetics Regulation Act tightens adverse event reporting for keratin-based hair straighteners, while REACH registration requirements in Europe elevate analytical costs for imported hydrolyzed proteins. China's NMPA and SAMR jointly enforce labeling standards for functional cosmetics containing keratin peptides, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor how fragmented regulatory timelines for formaldehyde-releasing preservatives reshape formulation R&D priorities and regional product registration strategies.
Market Dynamics
Formaldehyde-free certification requirements are compressing formulation margins while accelerating biotechnology investment, as European REACH thresholds and FDA adverse-event reporting reshape R&D allocation across professional hair care channels.
Growth Catalysts
- REACH purity thresholds:ECHA-mandated hydrolyzed protein standards push manufacturers toward cleaner extraction methods, creating competitive differentiation for compliant suppliers.
- Salon service recovery:Post-pandemic professional hair straightening demand in Brazil and South Korea expands addressable volume for salon-grade keratin portfolios.
- Biotechnology-derived alternatives:Precision fermentation processes bypass animal sourcing constraints, opening formulation pathways previously blocked by bovine-derived input restrictions.
Market Restraints
- Analytical cost inflation:REACH registration requirements elevate testing expenditures for imported hydrolyzed proteins, compressing margins for small-scale European formulators.
- Substitution pressure:Plant-based protein hydrolysates from rice and wheat gain traction in mass-market conditioners, threatening volume in cosmetic film-formation applications.
- Supply concentration:Specialty chemical precursors for hydrolyzed keratin concentrate among limited European suppliers, creating input vulnerability for Asian formulators.
Strategic Opportunities
- Modular at-home dosing:Single-use ampoules and maintenance kits decouple professional services from brand loyalty, enabling hybrid salon-retail revenue models.
- Pharmaceutical wound scaffolding:Keratin's cysteine-rich disulfide bonding properties suit chronic wound management applications, an underpenetrated therapeutic vertical.
- China functional cosmetics labeling:NMPA and SAMR joint enforcement creates first-mover advantage for peptide-grade keratin suppliers meeting documentation standards.
Industry Challenges
- Regulatory timeline fragmentation:Divergent formaldehyde-releasing preservative bans across FDA, REACH, and China's GB standards force parallel formulation tracks and extended registration cycles.
- Bioprocess scale-up complexity:Precision fermentation capacity for animal-free keratin alternatives requires capital-intensive bioreactor infrastructure that mid-scale suppliers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keratin Market |
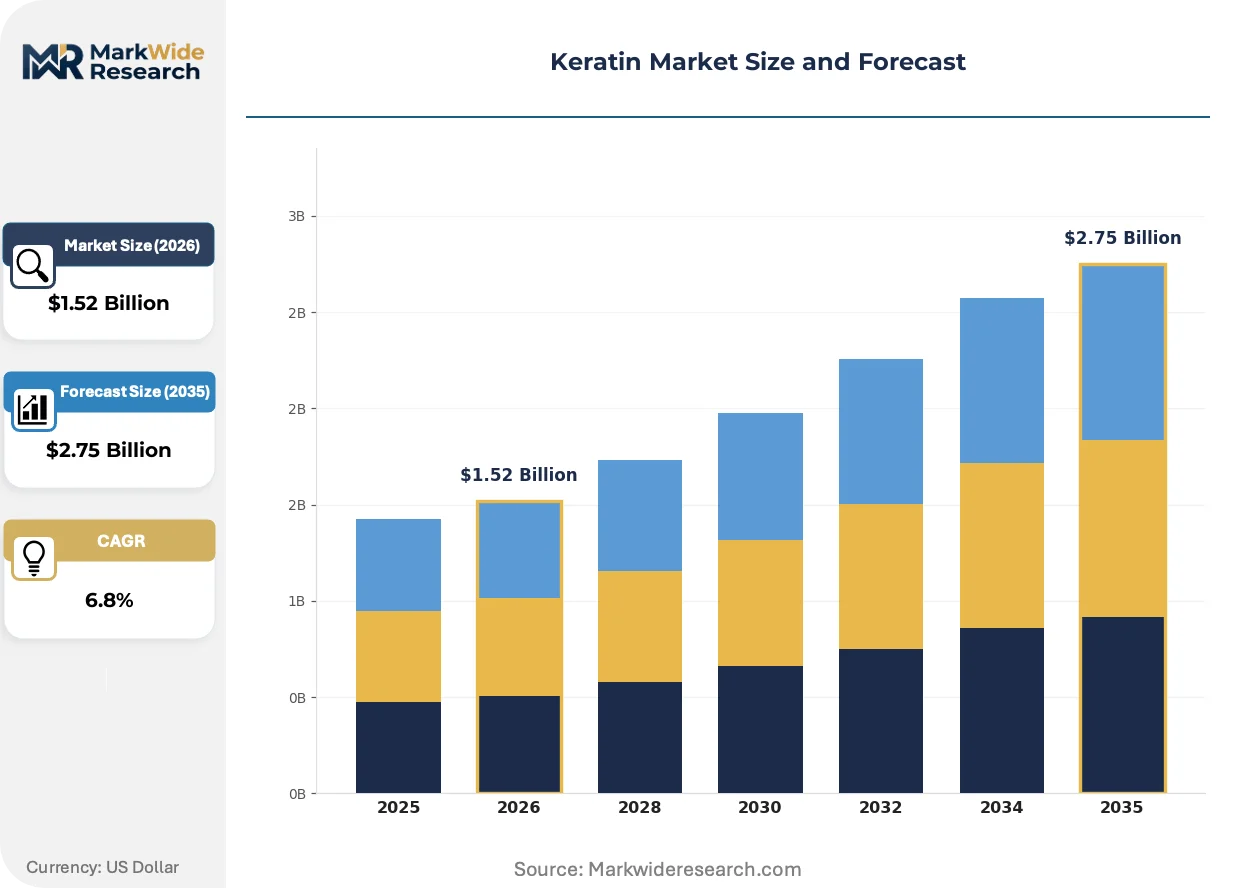
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Keratin, Keratin Amino Acids, Liquid Keratin, Keratin Treatments Application: Cosmetics, Hair Care Products, Pharmaceuticals, Nutraceuticals Source: Animal-Based, Plant-Based, Synthetic, Human-Based End User: Beauty Salons, Retail Consumers, Hospitals, Commercial Hair Care |
| Companies Covered | BASF SE, Keratin Complex, L’Oréal S.A., Croda International Plc, Wella Professionals, Unilever PLC, Keraplast Technologies, Active Concepts LLC, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keratin Market Strategic Shifts & Innovations
Biotechnology is rewriting raw-material sourcing economics while regulatory divergence fragments compliance pathways, forcing simultaneous investment in multiple certification frameworks across production networks.
Precision fermentation-derived keratin alternatives replicate cysteine-rich disulfide bonding without animal sourcing. European formulators facing ECHA bovine-input scrutiny adopt these bioprocessed substitutes fastest. This technology is electrifying competitive positioning by collapsing the cost premium between ethical and performance-grade inputs.
REACH registration requirements for hydrolyzed protein imports tighten analytical documentation standards. European manufacturers absorb elevated testing costs or exit lower-margin cosmetic segments. Salon-grade keratin treatments bear the heaviest compliance burden, accelerating consolidation among formulators with captive analytical capabilities.
Single-use ampoules and at-home maintenance kits fragment the traditional salon-service bundle. Professional channels in China's tier-one cities face disintermediation as consumers mix retail-grade formulas with periodic professional applications. This consumption-pattern shift compresses brand loyalty cycles and expands direct-to-consumer formulation sales.
Keratin Market Segmentation
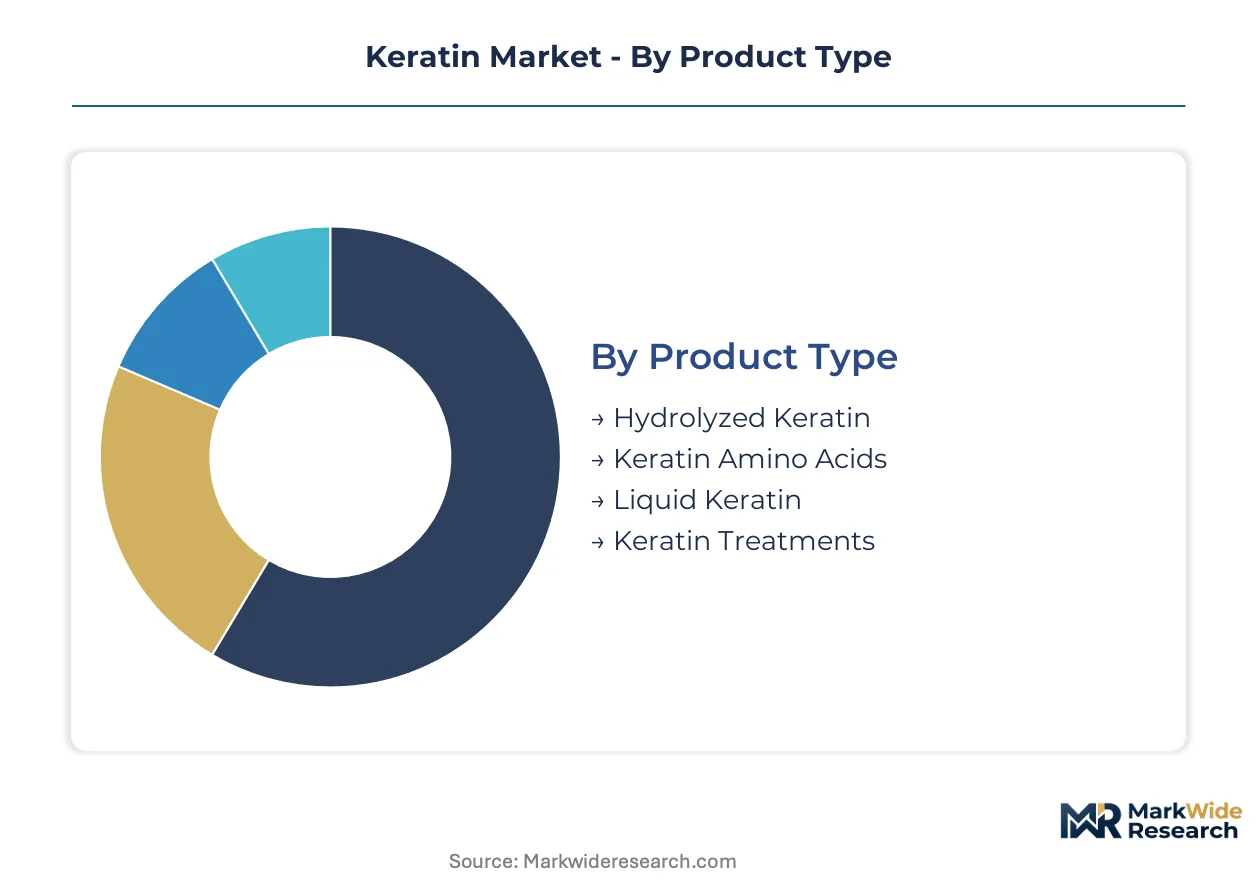
Keratin's commercial value hinges on molecular weight, hydrolysis intensity, and sourcing provenance. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that reshape supplier priorities across professional and retail channels.
Product Type:
Hydrolyzed Keratin commands volume leadership through aqueous compatibility, while Keratin Treatments extract premium pricing from salon certification requirements.
- Hydrolyzed Keratin:Partially hydrolyzed protein fractions ranging 10-150 kDa molecular weight dissolve readily in water-based cosmetic bases. Established INCI registry status drives formulation adoption across mass-market conditioners in China's tier-one cities, though REACH purity documentation elevates analytical costs for European imports.
- Keratin Treatments:Salon-grade formulations requiring formaldehyde-free certification for market access. Brazilian and South Korean professional channels absorb the highest unit volumes as post-pandemic service spending recovers, with ECHA scrutiny on preservative chemistry compressing formulation margins.
- Keratin Amino Acids:Fully hydrolyzed cysteine-rich peptide fractions for nutraceutical encapsulation and pharmaceutical wound scaffolding applications.
- Liquid Keratin:Pre-dispersed aqueous concentrates simplifying manufacturing integration for mid-scale cosmetic formulators.
Today's leader: Hydrolyzed Keratin. Tomorrow's challenger: Keratin Treatments.
Application:
Cosmetic film-formation generates baseline demand, while pharmaceutical wound management offers the steepest expansion trajectory for cysteine-rich protein structures.
- Cosmetics:Film-forming properties deliver surface protection and aesthetic enhancement across skin and nail formulations. European formulators facing ECHA bovine-input constraints accelerate adoption of biotechnology-derived alternatives.
- Hair Care Products:Professional straightening services in Brazil and South Korea represent the largest volume sink for salon-grade keratin, with modular at-home dosing kits fragmenting traditional service bundles.
- Pharmaceuticals:Disulfide bond density enables chronic wound scaffolding applications, an underpenetrated therapeutic vertical where keratin's mechanical durability matches collagen substitutes.
- Nutraceuticals:Amino acid supplementation targeting hair and nail health through oral delivery formats.
Cosmetics anchor current revenue. Pharmaceuticals promise the fastest climb.
Source:
Animal-derived inputs retain cost advantage, yet plant and synthetic alternatives gain share fastest where ECHA and FDA scrutiny tightens.
- Animal-Based:Bovine and poultry feather hydrolysates dominate existing volume through established supply chains and lower unit economics.
- Plant-Based:Rice and wheat protein hydrolysates substitute for cosmetic film-formation, threatening keratin volume in mass-market conditioners as European formulators navigate sourcing constraints.
- Synthetic:Precision fermentation processes bypass animal sourcing entirely, replicating cysteine-rich disulfide bonding without biological origin constraints.
- Human-Based:Recombinant human keratin variants for pharmaceutical-grade wound management requiring biocompatibility certification.
Animal-Based supplies today's volume. Biotechnology alternatives capture tomorrow's investment.
End User:
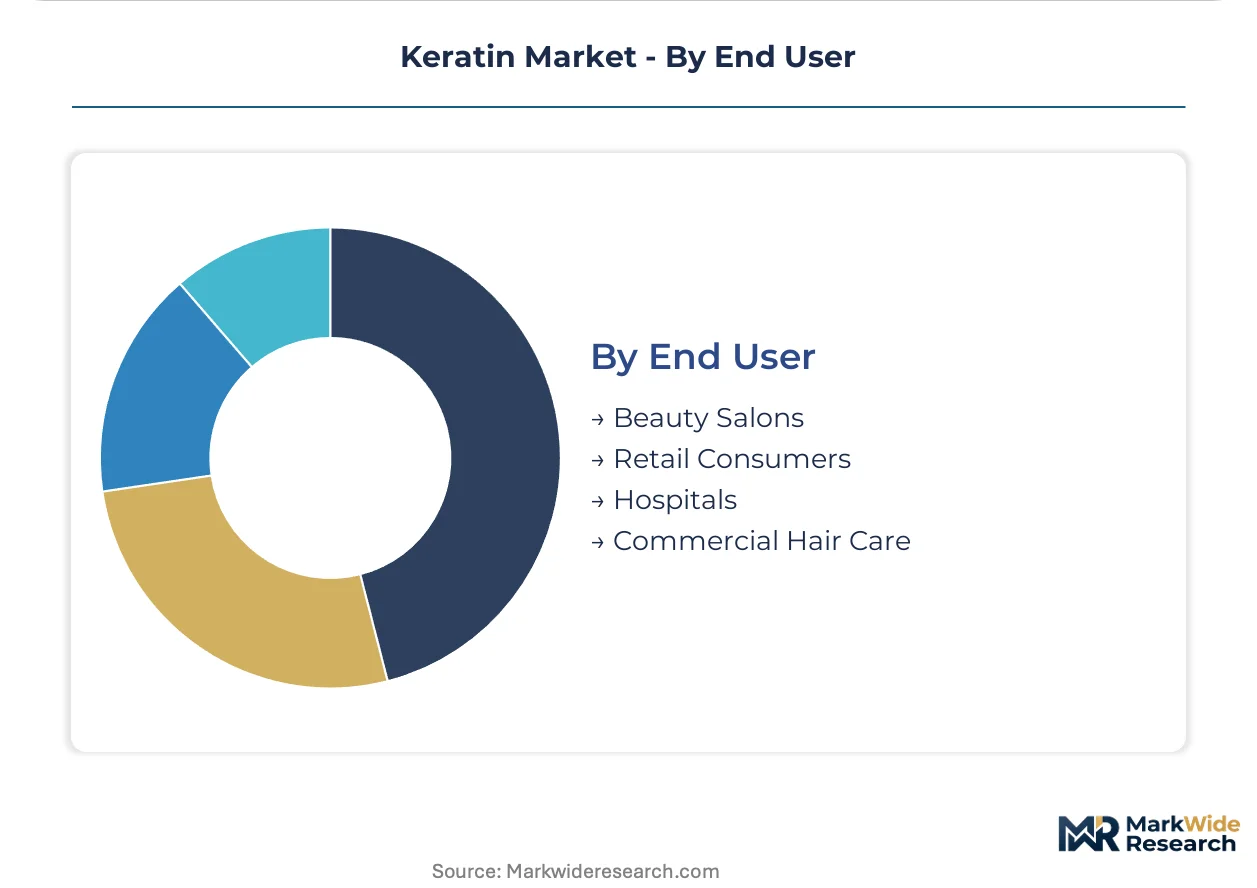
Professional salon channels concentrate premium pricing power, while retail direct-to-consumer formats erode brand loyalty cycles.
- Beauty Salons:Professional application services in China's tier-one cities and Brazilian metropolitan markets absorb high-unit-value formaldehyde-free treatment formulations.
- Retail Consumers:Single-use ampoules and maintenance kits enable hybrid salon-retail consumption patterns, decoupling professional services from brand attachment.
- Hospitals:Chronic wound management protocols in pharmaceutical-grade applications requiring sterile keratin scaffolding materials.
- Commercial Hair Care:Industrial-scale procurement for hotel amenities, cruise lines, and institutional grooming services.
Beauty Salons defend premium positioning. Retail Consumers drive volume democratization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Keratin extraction and formulation originated in European leather and wool processing centers during the early industrial period. The industry subsequently migrated toward pharmaceutical and cosmetic applications as hydrolysis technologies matured. Geographic distribution now reflects divergent regulatory environments and end-use demand patterns across major economies.
United States
Professional salon channels in Miami, Los Angeles, and New York City absorb substantial volumes of formaldehyde-free treatment formulations. FDA oversight through the Modernization of Cosmetics Regulation Act tightens adverse event reporting requirements for keratin-based hair straighteners. Texas and California host contract manufacturing clusters serving North American professional beauty distributors.
Germany
REACH registration requirements elevate analytical costs for imported hydrolyzed proteins, compressing margins for small-scale formulators. ECHA-mandated purity thresholds for bovine-derived inputs push manufacturers toward biotechnology-derived alternatives. The Rhine-Ruhr industrial corridor concentrates specialty chemical precursors for European keratin supply chains.
China
NMPA and SAMR joint enforcement of functional cosmetics labeling standards creates compliance complexity for peptide-grade keratin suppliers. Professional hair straightening services in Shanghai, Beijing, and Shenzhen represent the largest volume sink for salon-grade formulations. Guangdong province anchors manufacturing capacity for hydrolyzed protein exports.
Brazil
ANVISA regulates cosmetic safety standards for professional keratin treatments distributed through São Paulo and Rio de Janeiro salon networks. Post-pandemic recovery in metropolitan beauty services expands addressable volume for formaldehyde-free certification portfolios. The São Paulo industrial belt houses regional formulation and packaging operations.
South Korea
MFDS oversight of cosmetic ingredient safety intersects with K-beauty export requirements for keratin peptide documentation. Seoul and Busan professional channels drive demand for modular at-home maintenance kits alongside salon services. Gyeonggi-do province clusters biotechnology research facilities exploring precision fermentation alternatives.
Keratin Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification and sourcing dimensions. The vendor base organizes into three tiers: multinational specialty chemical suppliers with captive analytical capabilities, mid-scale formulators dependent on external testing services, and regional distributors with limited formulation assets. Strategic archetypes include biotechnology innovators bypassing animal sourcing constraints, integrated beauty conglomerates controlling professional channel density, and contract manufacturers serving private-label retail programs. Dominant competitive moves encompass backward integration into hydrolyzed protein production and geographic expansion into China's tier-one city salon networks.
Within the multinational chemical supply tier, BASF SE and Croda International Plc exemplify divergent sourcing strategies. BASF SE anchors European supply of hydrolyzed keratin precursors through established specialty chemicals infrastructure. Croda International Plc occupies a position emphasizing biotechnology-derived alternatives that circumvent ECHA scrutiny on bovine-derived inputs. L'Oréal S.A. represents the integrated beauty conglomerate archetype, with professional channel control across France and Brazil shaping competitive access to high-unit-value treatment formulations.
| Leading Market Players |
|---|
| BASF SE |
| Keratin Complex |
| L’Oréal S.A. |
| Croda International Plc |
| Wella Professionals |
| Unilever PLC |
| Keraplast Technologies |
| Active Concepts LLC |
| Henkel AG & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between formaldehyde-free salon treatments and commodity hydrolyzed protein inputs manifests in parallel pricing and sourcing configurations across European and Asian production networks. REACH-mandated analytical documentation elevates procurement costs for premium-grade keratin while compressing margins on mass-market cosmetic applications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs keratin procurement, with formaldehyde-free certification and molecular weight purity anchoring premium differentiation. Price differentiation stems from ECHA compliance documentation intensity and captive hydrolysis capability among European suppliers. Cost compression in standard-grade hydrolyzed keratin is intensifying because plant-based protein substitutes from rice and wheat erode volume in cosmetic film-formation. Mass-market cosmetic formulators exhibit highest price sensitivity, while pharmaceutical wound-scaffolding buyers absorb premium positioning for biocompatibility-certified grades.
Supply Chain Analysis
Direct-to-salon channels handle professional-grade treatment demand in Brazil and South Korea, while bulk chemical distribution serves mid-scale cosmetic formulators across China's manufacturing belt. Geographic supply concentration centers on Germany for specialty chemical precursors, China for hydrolyzed protein manufacturing capacity, and the United States for pharmaceutical-grade recombinant production. Raw material dependencies draw from bovine byproduct streams, poultry feather hydrolysates, and precision fermentation feedstocks. Single-source vulnerability concentrates among European suppliers of REACH-compliant analytical certification. Distribution runs through professional beauty distributors, direct OEM procurement, and specialty chemical traders serving formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Keratin functions as a regulatory compounder where REACH purity thresholds and FDA adverse-event reporting create sustained demand for certified-grade inputs. The Modernization of Cosmetics Regulation Act tightening on hair straightener safety documentation exemplifies this regulatory momentum.
For Market Incumbents: Deploy captive analytical capabilities to absorb REACH documentation burdens that externalize smaller competitors. BASF SE and Croda International Plc already leverage in-house testing infrastructure to defend margin position against mid-scale European formulators exiting lower-margin segments. Biotechnology-derived sourcing alternatives offer a secondary lever against ECHA bovine-input scrutiny compressing animal-based supply economics.
For New Entrants and Emerging Players: Pharmaceutical wound-scaffolding applications represent the most penetrable vertical for cysteine-rich keratin variants requiring biocompatibility certification. China's tier-one city salon networks present a secondary white-space target where NMPA and SAMR joint enforcement creates first-mover documentation advantages. A go-to-market angle anchored in modular at-home dosing kits bypasses entrenched professional channel control by L'Oréal S.A. and Wella Professionals.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration costs exceed revenue thresholds for sub-scale European formulators. Long-term viability favors suppliers with integrated biotechnology fermentation capacity and captive analytical certification infrastructure. Acquisition targets include mid-scale formulators with established INCI registry status but insufficient capital for bioprocess scale-up. The signal to watch is precision fermentation capacity utilization rates as animal-free alternatives achieve cost parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrolyzed Protein Production | BASF SE secures captive supply of keratin precursors against REACH import documentation inflation. |
| Biotechnology-Derived Alternative Scale-Up | Croda International Plc bypasses ECHA bovine-input constraints through precision fermentation pathways. |
| Professional Channel Density Expansion | L'Oréal S.A. controls salon-grade treatment distribution across France and Brazil metropolitan networks. |
| Modular At-Home Dosing Kit Development | Single-use ampoules fragment traditional service bundles in China's tier-one city retail channels. |
| Pharmaceutical Wound Scaffolding Certification | Keraplast Technologies targets chronic wound management applications requiring sterile keratin scaffolding materials. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with specialty chemical procurement leads, professional salon channel managers, cosmetic formulators, pharmaceutical wound-care specialists, and biotechnology R&D directors. Secondary validation drew from ECHA registration databases, FDA adverse-event reporting systems, NMPA functional cosmetics filings, customs trade records for hydrolyzed protein imports, and SEC disclosures from listed beauty conglomerates. Bottom-up volume estimates from individual application segments triangulated against top-down market sizing from regional production capacity assessments.
Segment-weighting approaches distributed value and volume across hydrolysis intensity tiers, sourcing provenance categories, end-use applications, and geographic regulatory clusters throughout the forecast period. CAGRs derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated REACH purity threshold implementation timelines and precision fermentation capacity expansion announcements.
Underlying measurement precision varies by segment; pharmaceutical-grade and biotechnology-derived categories carry tighter precision than commodity hydrolyzed keratin volumes subject to trade data reporting lags. Forecasts reflect assumptions on regulatory timeline adherence and substitution elasticity between animal and synthetic sourcing pathways. Periodic stress-testing of base assumptions is recommended against divergent formaldehyde-releasing preservative bans across FDA, REACH, and China's GB standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Global Electronic Fiberglass Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Viscose Market
Fibers
Renewable Carbon Fibers Market
Fibers
Global Metal Fiber Market
Fibers
Polytetrahydrofuran Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Dry-Molded Fibre Market
Fibers
Sisal Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Global Bicomponent Fiber Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Viscose Filament Yarn Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
North America Glass Fiber Reinforced Gypsum Market