
 Viscose Filament Yarn Market | 2026-2036
Viscose Filament Yarn Market Size, Share, and Industry Trends Forecast 2026-2036
Viscose Filament Yarn Market Outlook
Buyer concentration among large apparel exporters is expanding as mid-sized textile manufacturers consolidate purchasing power. Lenzing Group leverages its integrated pulp-to-yarn model to sustain European supply reliability. Grasim Industries anchors Indian domestic demand through captive viscose staple and filament operations. Xinxiang Bailu Chemical Fibre Group specializes in high-tenacity industrial-grade twisted yarn for technical textile applications.
Viscose filament yarn consists of regenerated cellulose filaments extruded through spinnerets into continuous strands, typically measuring 75–300 denier with controlled luster and dye affinity for weaving and knitting applications. Flat yarn dominates apparel weaving for its smooth surface and draping quality, while textured yarn commands premium positioning in upholstery and home textiles where bulk and elasticity matter. Twisted yarn retains stronghold in industrial fabrics requiring dimensional stability under mechanical stress.
REACH compliance in Europe restricts carbon disulfide emissions from viscose manufacturing, pushing producers toward closed-loop lyocell alternatives. China's MEE enforces wastewater discharge limits on filament plants along the Yangtze basin. India's BIS mandates tensile strength and moisture regain testing for yarn sold into export channels. Stakeholders must monitor how regional environmental enforcement reshapes cost structures and sourcing geography without assuming uniform regulatory timelines.
Market Dynamics
Apparel exporters in South Asia are consolidating yarn procurement contracts to secure volume commitments from integrated viscose producers, compressing margins for smaller weaving houses and accelerating backward integration among mid-tier textile groups.
Growth Catalysts
- REACH carbon disulfide caps:European emission limits are pushing filament plants toward closed-loop solvent recovery systems, creating first-mover advantage for compliant exporters.
- Technical textile weaving:Industrial fabric manufacturers in automotive and aerospace sectors are sourcing high-tenacity twisted yarn grades for composite reinforcement applications.
- Gujarat cluster expansion:Integrated weaving hubs in Surat and Ahmedabad are absorbing rising volumes of continuous filament for premium silk-substitute garment lines.
Market Restraints
- Dissolving pulp price volatility:Eucalyptus and beech pulp costs fluctuate with Brazilian and Indonesian hardwood supply cycles, squeezing filament margin stability.
- Yangtze basin supply concentration:Three Chinese provinces control over half of global filament capacity, exposing buyers to single-region logistics disruption.
- Lyocell substitution pressure:Closed-loop Tencel production avoids carbon disulfide entirely, capturing share in premium apparel where sustainability certification commands price premiums.
Strategic Opportunities
- Bangladesh garment export surge:Dhaka-based woven apparel factories are expanding viscose blend capacity to meet EU GSP+ origin requirements for duty-free access.
- Digital textile printing compatibility:Filament yarn with modified cross-sections enables sharper pigment absorption, opening home décor and fast-fashion sublimation markets.
- India PLI scheme for man-made fibers:Production-linked incentives for textile parks in Maharashtra and Tamil Nadu are attracting greenfield filament investments with tax holidays.
Industry Challenges
- Spinning technician scarcity:Wet-spinning process control requires skilled operators familiar with viscose ripening and coagulation chemistry, a workforce pool shrinking in Eastern Europe.
- BIS certification timelines:Export-grade yarn testing for tensile strength and moisture regain faces backlog at Mumbai and Chennai laboratories, delaying shipment schedules.
- Legacy DCS integration:Older filament plants running 1990s distributed control systems struggle to retrofit real-time emission monitoring for MEE wastewater compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscose Filament Yarn Market |
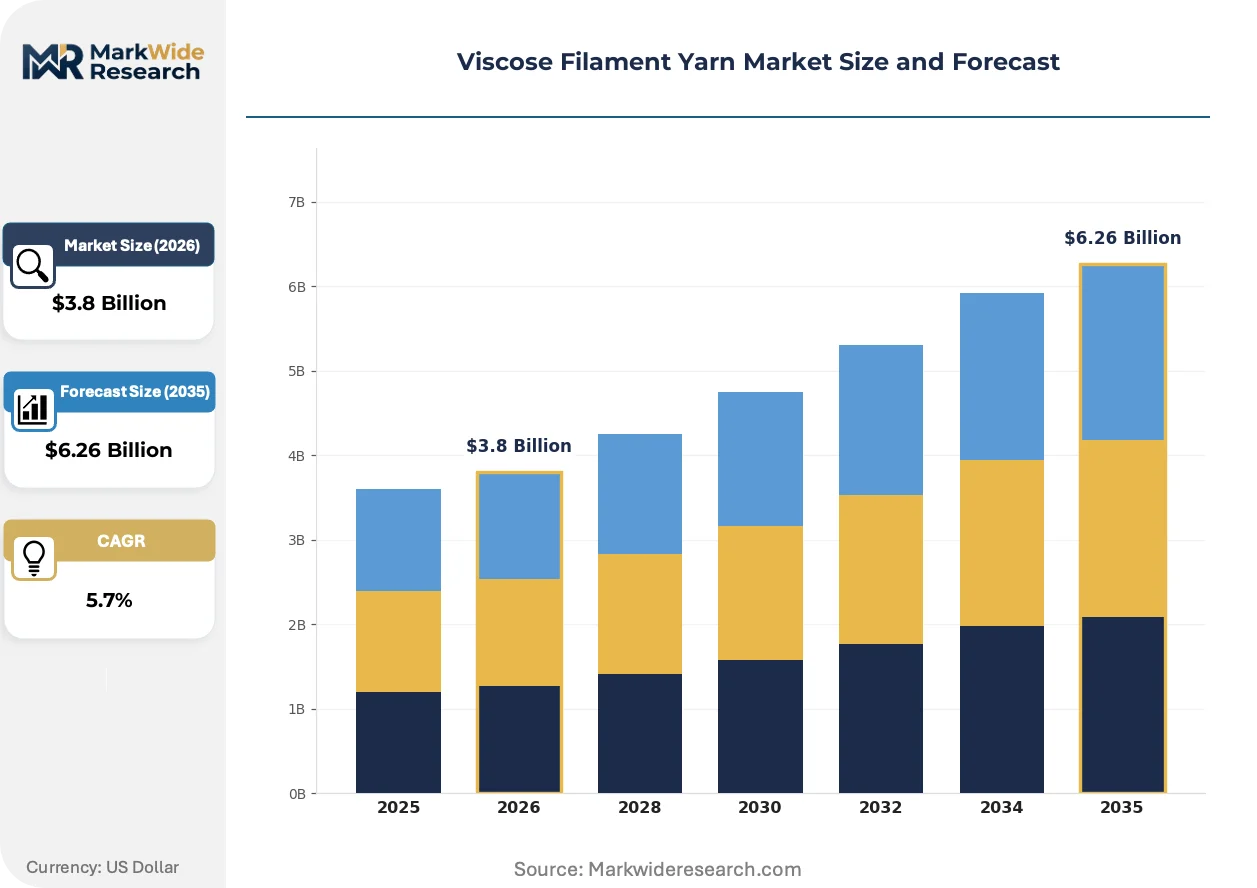
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Yarn, Twisted Yarn, Textured Yarn, Continuous Yarn Application: Apparel, Home Textiles, Industrial Fabrics, Upholstery End User: Textile Manufacturers, Exporters, Retailers, Designers Delivery Mode: Bulk Supply, Direct Shipping, Online Order, Retail Packaging |
| Companies Covered | Vardhman Textiles, Sateri Holdings, Lenzing Group, Jilin Chemical Fibre, Indorama Ventures, Grasim Industries, Yibin Grace Group, Xinxiang Bailu Chemical Fibre Group, Indo Bharat Rayon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscose Filament Yarn Market Strategic Shifts
Filament manufacturing is pivoting toward solvent-recovery architectures and specialty cross-section engineering, while downstream buyers reconfigure sourcing relationships around compliance documentation rather than pure price competition.
Modified spinneret technology producing tri-lobal and hollow filament cross-sections is converging with moisture-wicking activewear specifications. Sportswear brands in Germany and Japan are qualifying these engineered yarns for performance apparel lines. The structural result is premium pricing power migrating from commodity filament suppliers to specialty cross-section converters with proprietary die designs.
China's MEE enforcement of GB 31572 wastewater discharge standards along the Yangtze corridor is forcing filament plants to install biological treatment and closed-loop cooling. Plants in Jiangsu and Zhejiang provinces face operational suspension for non-compliance. Small independent spinners without captive chemical recovery are exiting or consolidating into larger chemical fiber groups with environmental compliance departments.
Large apparel exporters are consolidating annual yarn contracts into multi-year framework agreements with integrated pulp-to-filament producers. Mid-sized weaving houses in India and Turkey are losing leverage and volume discounts, pushing some toward cooperative purchasing pools. The shift is most visible in Gujarat's Surat cluster, where export-oriented garment manufacturers now contract directly with Grasim and Lenzing rather than trading through regional distributors.
Viscose Filament Yarn Market Segmentation
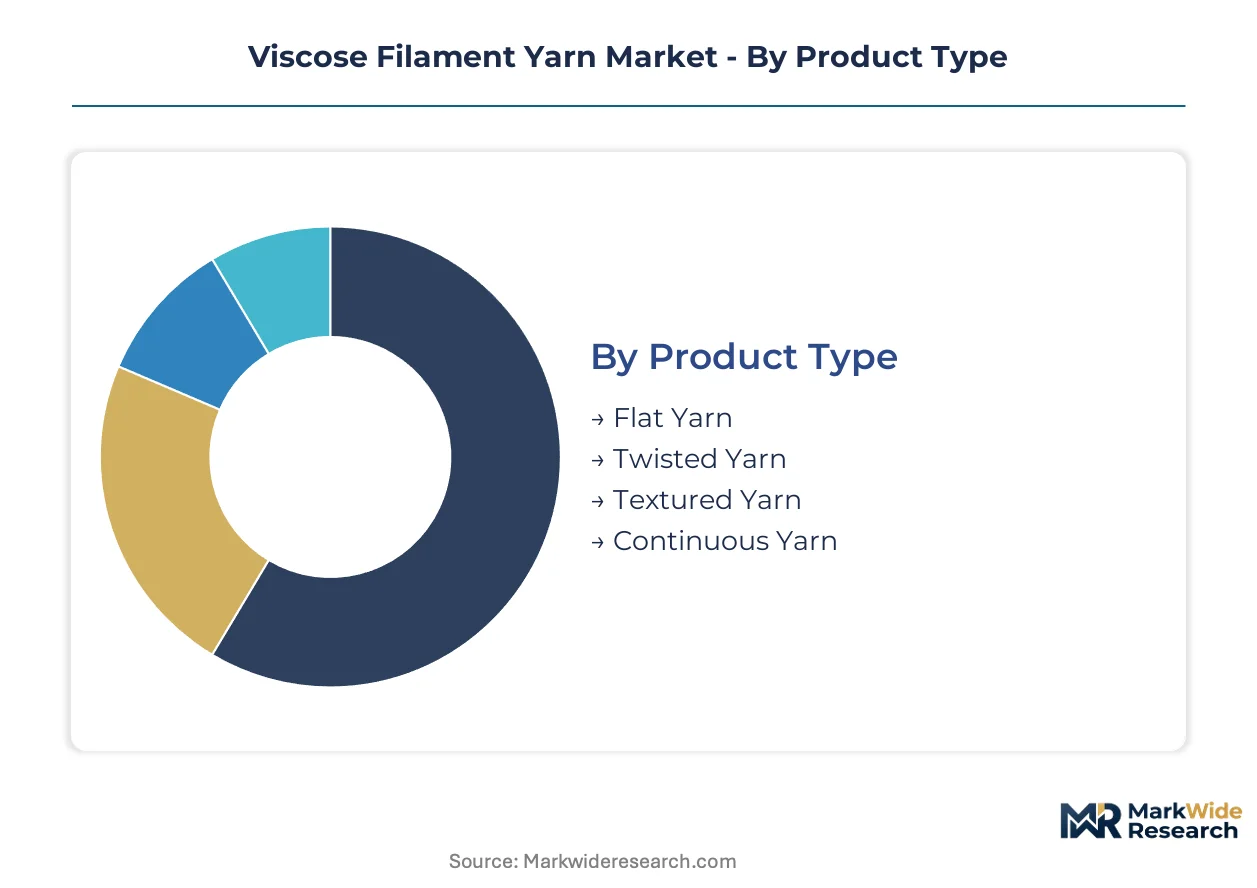
Viscose filament yarn demand fragments across product specifications, end-use applications, and procurement channels. Supply concentration among integrated pulp-to-yarn producers reshapes how buyers navigate grade selection and volume contracting.
Product Type:
Supply concentration among integrated producers favors grades with captive chemical recovery and spinneret customization capabilities.
- Flat Yarn:Continuous filaments with smooth, untextured surfaces deliver superior luster and draping quality for silk-substitute weaving. Surat and Ahmedabad garment exporters in Gujarat's textile belt source rising volumes for premium women's wear lines where surface aesthetics command price premiums.
- Twisted Yarn:Multiple filaments twisted together enhance dimensional stability and tensile strength for mechanical stress applications. Automotive and aerospace composite manufacturers in Germany and Japan specify high-tenacity twisted grades for technical textile reinforcement where failure tolerance is minimal.
- Textured Yarn:Bulked filaments create elasticity and loft for upholstery and home textile applications.
- Continuous Yarn:Single-strand extrusion without intermediate processing serves high-speed weaving operations requiring uniform feed consistency.
Today's leader: Flat yarn. Tomorrow's challenger: Twisted yarn.
Application:
Cost tier stratification separates commodity volume plays from certified premium positioning across end-use markets.
- Apparel:Woven and knitted garments exploit viscose filament's moisture absorption and dye affinity for comfort wear and formal attire. Dhaka-based woven apparel factories in Bangladesh expand viscose blend capacity to meet EU GSP+ origin requirements for duty-free market access.
- Home Textiles:Curtains, bed linens, and decorative fabrics leverage filament luster and drape for residential and hospitality specifications.
- Industrial Fabrics:High-tenacity constructions serve conveyor belts, tire cord, and filtration media where mechanical performance supersedes aesthetics. REACH carbon disulfide emission caps push European industrial fabric weavers toward compliant filament sources with closed-loop solvent recovery.
- Upholstery:Heavy-duty textured yarns withstand abrasion and compression in furniture and automotive seating applications.
Apparel dominates current volume. Industrial fabrics claim the steepest expansion trajectory as technical specifications tighten.
End User:
Customer type determines contract structure, with large volume buyers consolidating procurement power against fragmented downstream players.
- Textile Manufacturers:Integrated weaving and knitting operations consume bulk filament for in-house fabric production. Mid-sized weaving houses in Turkey and India face margin compression as larger competitors consolidate annual contracts into multi-year framework agreements with Grasim and Lenzing.
- Exporters:Garment houses shipping finished apparel to EU and US markets require BIS-certified yarn with documented tensile strength and moisture regain testing for customs clearance.
- Retailers:Fast-fashion and premium brands source finished fabrics rather than raw filament, exerting indirect pressure upstream for sustainability certification.
- Designers:Small-batch creative studios specify specialty cross-section filaments for limited-run collections.
Procurement power concentrates with textile manufacturers. Exporters are gaining leverage fastest through direct mill relationships.
Delivery Mode:
Supply chain configuration separates just-in-time responsive channels from bulk commodity logistics.
- Bulk Supply:Containerized volume shipments from Jiangsu and Zhejiang filament plants serve large weaving clusters with predictable consumption patterns. Yangtze basin supply concentration exposes buyers to single-region logistics disruption risk.
- Direct Shipping:Mill-to-loom arrangements bypass distributor markups for integrated textile groups with volume commitments.
- Online Order:Digital procurement platforms enable smaller weaving houses to access spot quantities without minimum order constraints.
- Retail Packaging:Small-denomination spools and cones serve designer studios and sampling operations.
Bulk supply retains volume dominance. Online order channels are expanding most quickly among fragmented downstream buyers seeking procurement flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's filament plants along the Yangtze basin supply over half of global volume, while India's Gujarat textile belt drives premium garment-grade consumption through integrated weaving clusters. Germany's technical textile weavers source high-tenacity grades for automotive and aerospace composites under REACH carbon disulfide caps.
China
Jiangsu and Zhejiang provinces host concentrated filament capacity serving both domestic apparel weavers and export markets. MEE enforcement of GB 31572 wastewater discharge standards forces biological treatment retrofits and closed-loop cooling installations. Plants in the Yangtze corridor face operational suspension for non-compliance, accelerating consolidation into larger chemical fiber groups with environmental compliance departments.
India
Gujarat's Surat and Ahmedabad clusters absorb rising volumes of continuous filament for silk-substitute premium women's wear lines. BIS mandates tensile strength and moisture regain testing for yarn sold into export channels, with certification backlogs at Mumbai and Chennai laboratories delaying shipment schedules. Maharashtra and Tamil Nadu textile parks attract greenfield filament investments under PLI scheme tax holidays.
Germany
Technical textile manufacturers in Baden-Württemberg and North Rhine-Westphalia source high-tenacity twisted yarn grades for automotive composite reinforcement and aerospace applications. REACH carbon disulfide emission caps push industrial fabric weavers toward compliant filament sources with closed-loop solvent recovery systems. ECHA regulatory pressure creates first-mover advantage for European exporters meeting emission thresholds.
Bangladesh
Dhaka-based woven apparel factories expand viscose blend capacity to meet EU GSP+ origin requirements for duty-free market access. The country's garment export surge concentrates procurement among large volume buyers contracting directly with integrated pulp-to-filament producers. Chittagong port logistics support just-in-time delivery to European fast-fashion retailers.
Japan
Sportswear brands in Osaka and Tokyo metropolitan areas qualify engineered tri-lobal and hollow filament cross-sections for performance activewear lines. METI industrial standards emphasize moisture-wicking specifications driving premium pricing power toward specialty cross-section converters. Technical textile weavers in Nagoya industrial corridor source high-tenacity grades for automotive seating and industrial fabric applications.
Viscose Filament Yarn Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the viscose filament yarn supply base. Integrated pulp-to-yarn producers command procurement leverage through captive chemical recovery and spinneret customization capabilities. Three strategic archetypes dominate: Asian chemical fiber groups with environmental compliance departments, European specialty cross-section converters with proprietary die designs, and South Asian textile conglomerates with backward integration into filament production. Competitive moves center on multi-year framework contracting with large apparel exporters and M&A consolidation of small independent spinners lacking emission compliance infrastructure.
Within the integrated chemical fiber tier, Lenzing Group and Grasim Industries exemplify divergent geographic anchoring strategies. Lenzing sustains European supply reliability through Austrian-based pulp-to-yarn operations, while Grasim anchors Indian domestic demand through captive viscose staple and filament manufacturing. Xinxiang Bailu Chemical Fibre Group occupies a position among Chinese specialists in high-tenacity industrial-grade twisted yarn for technical textile applications. These three represent distinct archetypes: European sustainability-certified supply, South Asian volume-integrated production, and Chinese industrial-grade specialization.
| Leading Market Players |
|---|
| Vardhman Textiles |
| Sateri Holdings |
| Lenzing Group |
| Jilin Chemical Fibre |
| Indorama Ventures |
| Grasim Industries |
| Yibin Grace Group |
| Xinxiang Bailu Chemical Fibre Group |
| Indo Bharat Rayon |
| Others |
Value Chain & Pricing Dynamics
Closed-loop solvent recovery retrofits in Jiangsu and Zhejiang filament plants are compressing operating margins while simultaneously concentrating supply among integrated chemical fiber groups with captive environmental compliance infrastructure. This technical transition simultaneously elevates cost floors and eliminates small independent spinners from price competition.
Pricing Analysis
Capacity additions in Maharashtra and Tamil Nadu under India's PLI scheme are reshaping price floors for standard-grade flat yarn. Pricing stratifies across REACH-certified premium tiers, BIS-mandated export-grade certification levels, and uncertified spot-market commodity lots. Cost compression in economy-grade filament is intensifying as Yangtze basin producers absorb wastewater treatment overhead. Small weaving houses in Surat exhibit highest price sensitivity, while automotive composite manufacturers in Germany accept premium positioning for high-tenacity twisted grades.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu and Zhejiang provinces controlling over half of global filament capacity. Dissolving pulp draws from Brazilian eucalyptus and Indonesian beech hardwood supply cycles. Logistics chokepoint exposure concentrates at Chittagong port for Bangladesh garment exporters and Mumbai port for Indian certification backlogs. Distribution runs through bulk container shipments to integrated weaving clusters, with direct mill-to-loom arrangements expanding among large apparel exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The viscose filament yarn market functions as a stable compounder anchored by technical textile demand from automotive and aerospace sectors requiring certified high-tenacity grades.
For Market Incumbents: Anticipate lyocell substitution pressure in premium apparel by securing backward integration into dissolving pulp supply and accelerating closed-loop solvent recovery certification. Prioritize multi-year framework contracts with Dhaka-based garment exporters expanding EU GSP+ capacity. Defend margin position through captive spinneret customization capabilities for tri-lobal and hollow cross-section engineering.
For New Entrants and Emerging Players: Enter via specialty cross-section conversion for moisture-wicking activewear specifications serving Osaka and Tokyo sportswear brands. Target industrial fabric reinforcement applications in Nagoya and Baden-Württemberg where failure tolerance requirements create qualification barriers. Pursue cooperative purchasing pool arrangements with mid-sized Turkish weaving houses losing leverage against consolidated buyers.
For Investors and Strategic Acquirers: Valuations sit cheapest among small independent spinners in Eastern Europe lacking MEE-compliant wastewater infrastructure and facing spinning technician scarcity. Long-term viability hinges on regulatory compliance moats widening through REACH carbon disulfide caps and China's GB 31572 enforcement. Monitor BIS certification backlog resolution at Mumbai and Chennai laboratories as inflection indicator for Indian export channel throughput.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Solvent Recovery Installation | MEE wastewater compliance in Jiangsu and Zhejiang separates viable producers from suspended operations. |
| Backward Integration into Dissolving Pulp | Captive hardwood supply from Brazilian and Indonesian sources insulates margin stability against pulp price cycles. |
| Specialty Cross-Section Engineering | Proprietary tri-lobal and hollow spinneret designs capture premium pricing from German and Japanese sportswear brands. |
| Multi-Year Framework Contracting | Direct mill relationships with Surat and Ahmedabad garment exporters displace regional distributor intermediaries. |
| BIS Certification Investment | Tensile strength and moisture regain testing capability unlocks Indian yarn export channels facing Mumbai laboratory backlogs. |
Study Parameters
Multiple input streams — filament plant managers, textile procurement leads at Surat weaving clusters, distribution channel partners, and technical R&D directors at specialty cross-section converters — were reconciled against customs and trade data, CDSCO filings, BIS certification records, and SEC disclosures from integrated chemical fiber groups. Bottom-up volume modeling across flat, twisted, textured, and continuous yarn grades was cross-validated through top-down demand aggregation from apparel, home textile, industrial fabric, and upholstery end-use segments.
Historical capacity utilization patterns were cross-referenced against panel input from plant engineering directors to establish baseline assumptions across the projection horizon. Segmentation dimensions modeled include yarn grade tier, end-use industry, certification level, and regional production hub clustering. CAGRs were derived through exponential smoothing of reconciled primary and secondary inputs, with specific weighting applied to REACH compliance timelines and PLI scheme implementation pacing in Maharashtra and Tamil Nadu.
Inputs from Yangtze basin filament operators and Gujarat weaving cluster procurement heads were available through the study window; gaps in real-time emission monitoring retrofit progress at legacy DCS plants introduce uncertainty bands around compliance cost assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Global Metal Fiber Market
Fibers
Thermoformed Fiber Market
Fibers
Bioglass Fiber Market
Fibers
Acoustical Fiber Board Market
Fibers
Global Fiberglass Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Global Fiberglass Mold Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Ceramic Fiber Market
Fibers
Viscose Market
Fibers
Carbon Fiber Wrap Market
Fibers
Viscose Staple Fiber Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Global Fiber Reinforced Composites Market