
 Global Rubber Coated Fabrics Market | 2026-2036
Global Rubber Coated Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubber Coated Fabrics Market Foresight
ISO 14116 limited flame spread certification is redrawing competitive boundaries for suppliers serving protective equipment and transportation sectors. Continental AG leverages integrated rubber compounding and textile finishing operations across European manufacturing centers to sustain specification-grade output for automotive and industrial buyers. Trelleborg AB anchors its position through marine and offshore specialization, where coated fabric durability under saltwater exposure commands premium positioning. Saint-Gobain S.A. differentiates via high-performance polymer expertise inherited from aerospace and chemical processing heritage, competing on thermal resistance and extended service intervals.
Rubber coated fabrics consist of woven, knitted, or nonwoven textile substrates bonded with elastomer layers through calendering, dip coating, or spread coating processes, typically achieving thicknesses between 0.2 mm and 5.0 mm depending on end-use mechanical and barrier requirements. These engineered composites deliver impermeability, abrasion resistance, and chemical protection for applications ranging from inflatable life rafts to industrial containment systems. Nitrile rubber and neoprene formulations dominate protective clothing and marine segments where oil resistance and weatherability justify material cost premiums, while silicone rubber occupies aerospace and medical supply niches demanding thermal stability and biocompatibility. Spread coating and calendering technologies lead production volume due to throughput scalability and gauge control precision, though dip coating gains traction for intricate geometries in medical and electronics applications.
EPA oversees volatile organic compound emissions from coating operations under Clean Air Act standards, while REACH restricts hazardous substance content in rubber chemicals sold within Europe, and OSHA mandates permeation testing for protective garments deployed in chemical handling environments. These frameworks elevate compliance costs for smaller compounders and favor vertically integrated manufacturers with in-house analytical and certification capabilities. Stakeholders must monitor evolving flammability standards in transportation and tightening chemical transparency rules as determinants of supplier viability and product liability exposure.
Market Dynamics
REACH compliance deadlines and evolving EPA volatile organic compound standards are compressing formulation flexibility for compounders while concentrating procurement among vertically integrated manufacturers with captive analytical certification capabilities.
Growth Catalysts
- Aerospace flame-resistance mandates:Crew protection system specifications are tightening across commercial aviation and defense platforms, pulling specification-grade neoprene and silicone-coated assemblies into long-term supply agreements.
- REACH Article 33 disclosure rules:Substance of Very High Concern reporting obligations are filtering out non-compliant compounders and consolidating specification-grade supply relationships with certified European manufacturers.
- Marine safety equipment replacement cycles:Inflatable life raft and offshore containment fabric refresh programs in Germany and Japan are sustaining aftermarket demand for hypalon and polyurethane-coated textiles.
Market Restraints
- Petrochemical input volatility:Nitrile rubber and neoprene base polymer costs swing with crude oil and butadiene pricing, compressing margin predictability for spread coating operations.
- Specialized calendering equipment scarcity:Precision gauge control machinery for thin-film aerospace grades concentrates among German and Japanese equipment builders, creating capacity bottlenecks.
- Fluoropolymer substitution in chemical protection:PTFE-laminated textiles are capturing segments of industrial protective clothing where permeation resistance thresholds exceed rubber coating performance ceilings.
Strategic Opportunities
- India industrial safety equipment localization:BIS certification requirements and PLI scheme incentives for domestic manufacturing are opening specification-grade supply relationships for automotive and chemical processing sectors.
- Silicone-hydrogel hybrid medical drapes:Convergence of platinum-cured silicone coating with antimicrobial textile finishing is creating surgical drape segments where biocompatibility and barrier performance command premium positioning.
- Brazil offshore pre-salt development:ANVISA and environmental licensing for deepwater containment systems is generating demand for saltwater-resistant coated fabric assemblies in flexible riser and boom applications.
Industry Challenges
- ISO 14116 certification timeline compression:Limited flame spread testing protocols for protective equipment require 12-18 month validation cycles that delay new compound qualification and contract awards.
- Multi-layer adhesion chemistry expertise:Bonding dissimilar elastomers to aramid and glass fiber substrates demands polymer science skill sets concentrated among retiring European compound formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubber Coated Fabrics Market |
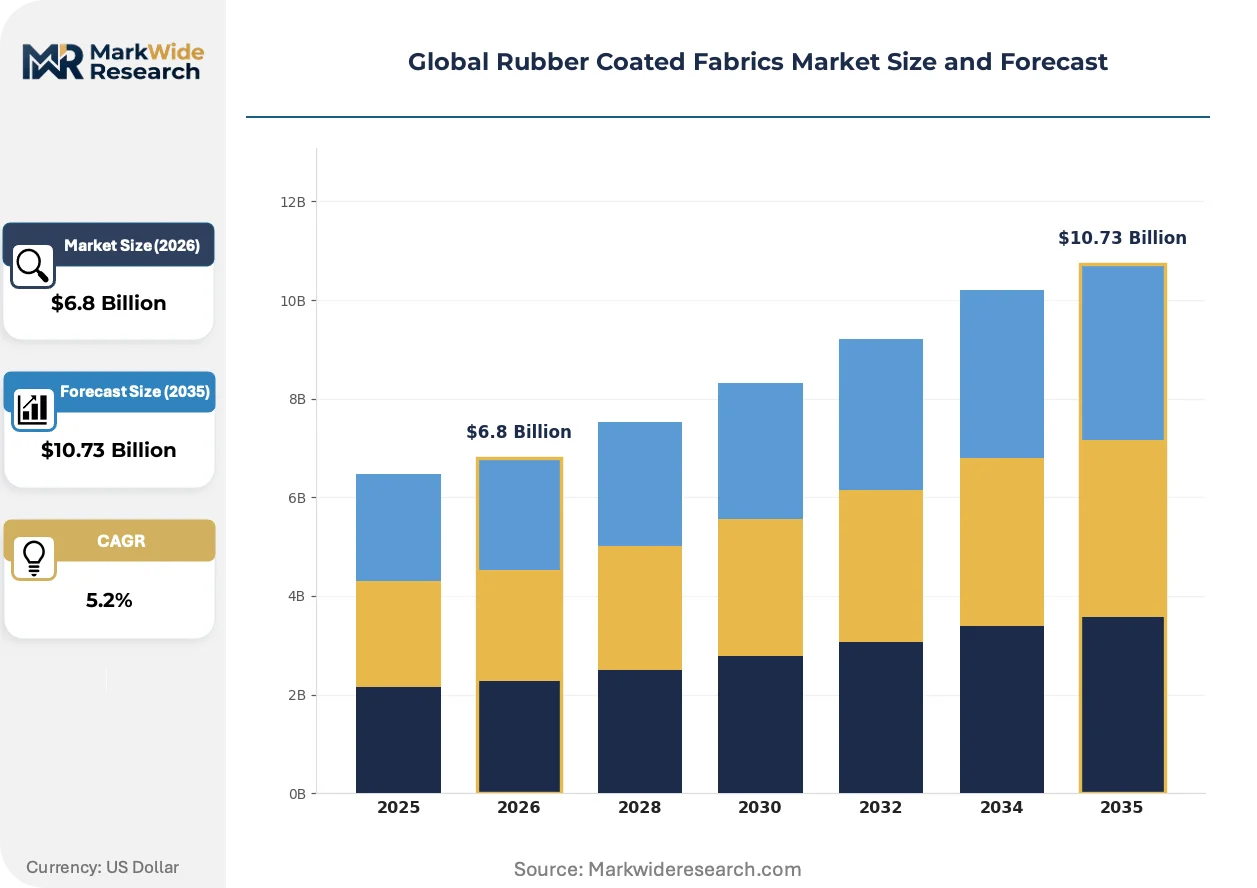
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Nitrile Rubber, Neoprene, Silicone Rubber, EPDM, Butyl Rubber Coating Technology: Dip Coating, Calendering, Extrusion Coating, Foam Coating, Latex Coating, Spread Coating Application: Protective Clothing, Industrial Curtains, Automotive Components, Conveyor Belts, Inflatable Structures, Medical Supplies End User Industry: Oil & Gas, Marine, Aerospace, Construction, Electronics, Agriculture |
| Companies Covered | Continental AG, Trelleborg AB, Saint-Gobain S.A., Colmant Coated Fabrics, Auburn Manufacturing, Arville Textiles Limited, Zenith Rubber, The Rubber Company, Fothergill Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubber Coated Fabrics Market Shifts & Advancements
Water-based dispersion coating technologies are displacing solvent-based spread coating in European manufacturing, while digital print integration and predictive wear monitoring are reconfiguring value capture across the supply chain.
Plasma surface activation pretreatment is displacing mechanical abrasion and solvent wiping for substrate preparation in aerospace and medical coating lines. Tier 1 suppliers in Germany and France are adopting atmospheric plasma systems to improve elastomer-to-textile bond strength on aramid and PBI substrates. This shift is displacing legacy corona treatment equipment and reducing volatile organic compound generation at the coating line head.
EPA National Emission Standards for Hazardous Air Pollutants for rubber coating operations are tightening volatile organic compound capture requirements at US manufacturing facilities. The 2024 residual risk and technology review is forcing capital deployment into thermal oxidizer and carbon adsorption systems at mid-scale compounders. Protective garment and industrial conveyor belt segments in the Ohio River Valley and Gulf Coast clusters are absorbing compliance cost pass-throughs while consolidating supply relationships with larger integrated manufacturers.
Specification-driven procurement is compressing supplier qualification cycles and unbundling after-sales technical service from material supply contracts. Automotive OEMs in Germany and industrial equipment builders in Japan are separating coating formulation support from volume supply agreements, engaging specialized technical consultancies for compound optimization. This pattern is most visible in sealing and insulation applications where thermal cycling performance guarantees require discrete engineering validation before production release.
Global Rubber Coated Fabrics Market Segmentation
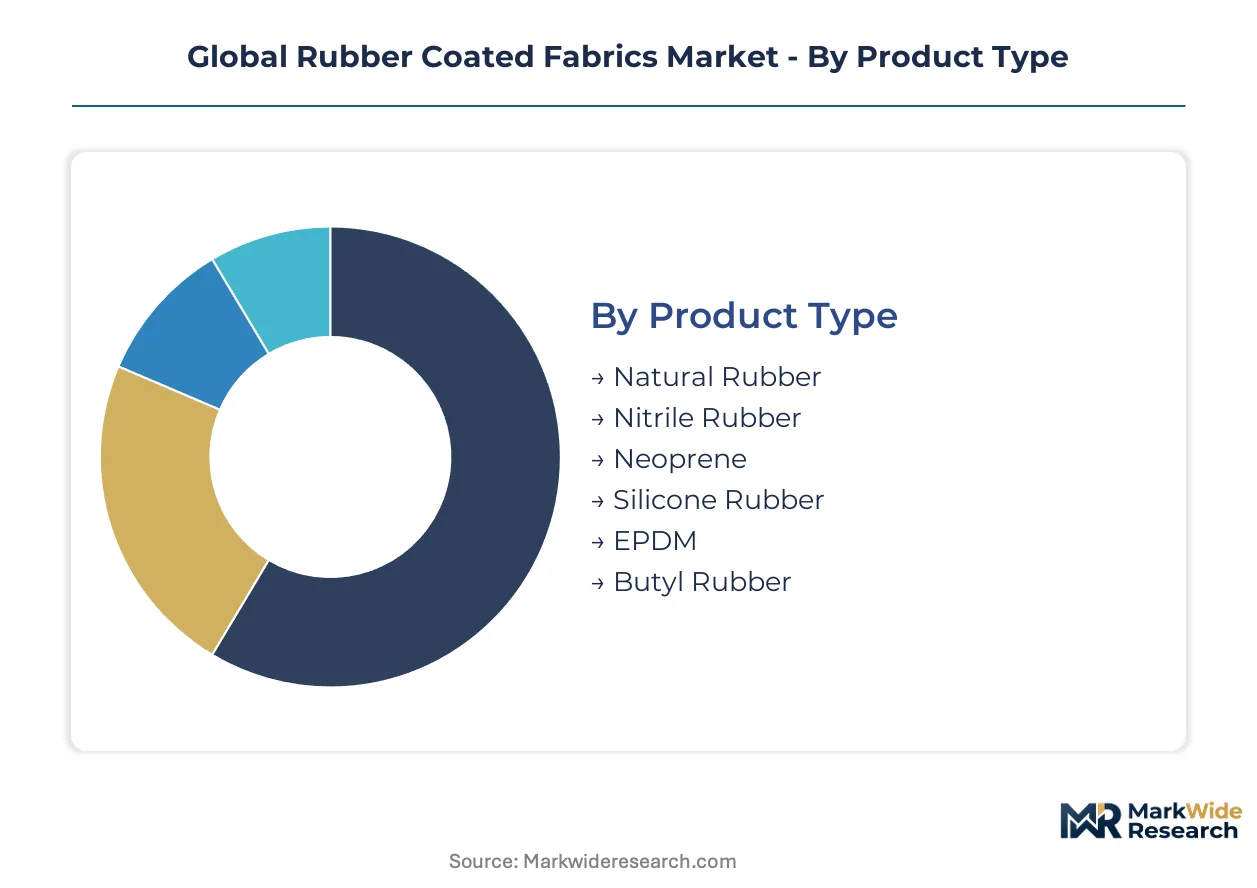
Rubber coated fabrics serve divergent performance requirements across protective equipment, transportation, and containment systems. Segmentation reveals how formulation chemistry and substrate engineering align with end-use certification demands and procurement channel structures.
Product Type:
Specialty elastomer grades flow through specification-certified distributors to aerospace and marine OEMs, while commodity formulations reach industrial buyers via compounder-direct channels.
- Nitrile Rubber:Oil-resistant acrylonitrile-butadiene copolymer formulations deliver hydrocarbon barrier performance for protective gloves and industrial seals. Demand concentrates in Germany's automotive supplier cluster where REACH-certified nitrile assemblies feed fuel system component manufacturers facing permeation resistance mandates.
- Neoprene:Chloroprene-based compounds balance weatherability, flame resistance, and mechanical durability across marine safety equipment and industrial curtains. Expansion concentrates in Japan's inflatable life raft replacement programs and offshore containment refresh cycles where saltwater degradation resistance commands specification premiums.
- Natural Rubber:Polyisoprene formulations offer high elasticity and tear strength for general industrial belting and agricultural tarpaulins in cost-sensitive procurement channels.
- Silicone Rubber:Platinum-cured polysiloxane coatings provide thermal stability from -60°C to 230°C for aerospace crew protection and medical drape applications requiring biocompatibility certification.
- EPDM:Ethylene-propylene-diene terpolymer compounds resist ozone and UV degradation for outdoor architectural membranes and agricultural pond liners in sun-exposed geographies.
- Butyl Rubber:Isobutylene-isoprene copolymers deliver exceptional gas impermeability for inflatable structures and pharmaceutical processing equipment where hermetic sealing is critical.
Nitrile rubber dominates installed base across industrial protective equipment. Silicone rubber formulations are where expansion concentrates for aerospace thermal protection and medical barrier applications.
Coating Technology:
Production scale and gauge precision requirements create distinct cost tiers, with thin-film aerospace grades commanding equipment investment thresholds that filter supplier participation.
- Calendering:Multi-roll precision gap control achieves thickness tolerances of ±0.02 mm for specification-grade automotive and aerospace substrates. High capital requirements for German and Japanese-built machinery concentrate capacity among integrated compounders serving long-term OEM contracts.
- Spread Coating:Knife-over-roll and reverse-roll methods deposit controlled elastomer layers onto woven and knitted textiles at throughput rates suitable for industrial conveyor belt and protective clothing volume production. This technology captures the broadest application range where gauge flexibility outweighs extreme precision requirements.
- Dip Coating:Immersion saturation coats complex geometries including medical device textiles and electronics gaskets where complete encapsulation matters more than surface finish uniformity.
- Extrusion Coating:Molten polymer direct extrusion onto moving substrates suits thick-film industrial applications including geomembranes and heavy-duty containment systems.
- Foam Coating:Cellular elastomer structures reduce weight while maintaining barrier properties for flotation devices and thermal insulation assemblies.
- Latex Coating:Aqueous dispersion deposition enables water-based processing for medical and food-contact applications where solvent residue restrictions apply.
Spread coating commands the widest installed equipment base. Calendering lines are where capacity expansion concentrates for specification-grade thin-film supply to automotive and aerospace programs.
Application:
Certification intensity varies sharply across use cases, with personal protective equipment and medical applications facing multi-agency validation that extends supplier qualification timelines.
- Protective Clothing:Chemical-resistant garments for industrial and emergency response deploy multilayer barrier constructions combining nitrile or butyl coatings with aramid substrates. OSHA permeation testing requirements and ISO 14116 flame spread certification compress the qualified supplier base for US and European public procurement.
- Automotive Components:Sealing systems, insulation pads, and anti-vibration mounts utilize EPDM and nitrile coated fabrics for underhood thermal and fluid resistance. Germany's OEM supplier network sources these assemblies through IATF-certified compounders with captive textile finishing operations.
- Conveyor Belts:Abrasion-resistant top and bottom covers protect carcass plies in mining, agriculture, and bulk material handling installations.
- Industrial Curtains:Welding screens, paint booth partitions, and temperature zone dividers employ neoprene and hypalon coatings for spark resistance and chemical splash protection.
- Inflatable Structures:Life rafts, rescue boats, and architectural pneumatic forms rely on woven polyester substrates with neoprene or polyurethane coatings for air retention and UV stability.
- Medical Supplies:Surgical drapes, mattress covers, and isolation barriers utilize platinum-cured silicone and latex coatings meeting biocompatibility standards for patient contact.
Conveyor belts represent the largest installed application base by volume. Protective clothing and medical supplies are where specification-grade pricing and certification barriers create the steepest expansion trajectory for qualified suppliers.
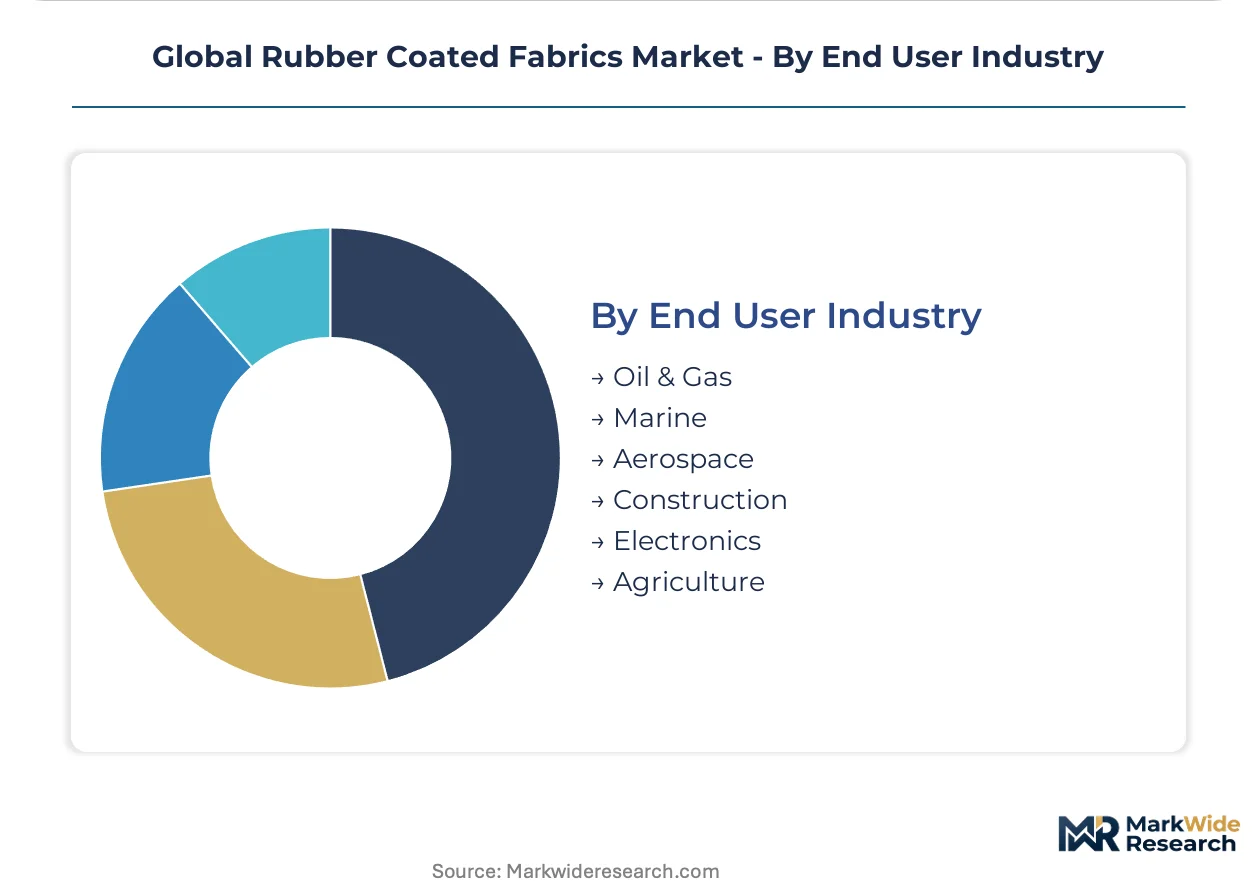
End User Industry:
Regulatory exposure intensity shapes procurement patterns, with oil and gas and marine sectors driving specification-grade demand while agriculture and construction absorb commodity-grade supply.
- Aerospace:Crew protection systems, thermal insulation blankets, and fuel cell sealing demand silicone and fluorosilicone coated fabrics certified to FAA flammability standards and OEM-specific outgassing requirements. Long program lifecycles lock in supplier relationships through exclusive source approvals.
- Marine:SOLAS-mandated life raft and evacuation system fabric replacement cycles sustain aftermarket demand for neoprene and hypalon coated textiles in Germany, Japan, and South Korea shipbuilding clusters.
- Oil & Gas:Secondary containment booms, flexible riser covers, and protective workwear require hydrocarbon-resistant nitrile and neoprene formulations for upstream and downstream operations.
- Construction:Architectural membranes, temporary shelters, and noise barriers utilize EPDM and natural rubber coated fabrics for weather protection and acoustic damping.
- Electronics:EMI shielding gaskets and cleanroom garments employ conductive particle-loaded silicone coatings for static control applications.
- Agriculture:Grain storage covers, irrigation pond liners, and equipment tarpaulins prioritize cost efficiency over extended service life in seasonal use patterns.
Construction and agriculture dominate installed base by volume. Aerospace and marine applications are where premium positioning and long-term contract stability concentrate expansion investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Article 33 disclosure obligations and India's PLI scheme for domestic manufacturing are redrawing procurement geography across rubber coated fabrics. National regulators are filtering supplier participation through certification mandates that favor compounders with captive analytical capabilities.
Germany
Automotive OEMs in Stuttgart and Munich source specification-grade neoprene and EPDM coated assemblies for underhood sealing and thermal insulation. ECHA enforcement of Substance of Very High Concern reporting compresses the qualified supplier base for IATF-certified compounders. The Rhine-Ruhr industrial corridor hosts integrated rubber compounding and textile finishing operations serving long-term contracts with tier-1 automotive suppliers.
United States
EPA National Emission Standards for Hazardous Air Pollutants are forcing thermal oxidizer deployment at Ohio River Valley coating facilities. OSHA permeation testing requirements for chemical protective garments sustain demand for nitrile and butyl coated textiles in Gulf Coast petrochemical clusters. Houston-area compounders are consolidating supply relationships as compliance cost pass-throughs filter smaller participants.
Japan
METI-mandated marine safety equipment refresh programs sustain aftermarket demand for hypalon-coated inflatable life raft fabrics. JIS standard certification for offshore containment systems creates specification barriers for imported assemblies. The Nagoya shipbuilding cluster sources neoprene-coated textiles through exclusive source approvals with domestic compounders.
India
BIS certification requirements and PLI scheme incentives for domestic manufacturing are opening specification-grade supply channels for automotive and chemical processing sectors. CDSCO biocompatibility standards for medical drapes create entry barriers for unqualified silicone coating imports. The Gujarat chemical belt is attracting capacity investment from compounders seeking tariff-advantaged supply to domestic industrial safety equipment manufacturers.
Brazil
ANVISA licensing for deepwater containment systems generates demand for saltwater-resistant neoprene and polyurethane coated fabrics in flexible riser applications. Environmental licensing for pre-salt offshore development sustains procurement of specification-grade assemblies. The Rio de Janeiro offshore services cluster sources coated fabric booms and protective workwear through long-term supply agreements with certified compounders.
Global Rubber Coated Fabrics Market Competitive Landscape
Player mix skews toward integrated European compounders with captive textile finishing operations and specialized marine-aerospace specialists with specification-grade certification depth. Market structure concentrates procurement among three to five vertically integrated manufacturers with in-house REACH and FAA compliance capabilities. Strategic archetypes include automotive-sealing focused compounders, marine-offshore durability specialists, and high-performance polymer formulators serving aerospace thermal protection. Dominant competitive moves encompass backward integration into rubber compounding and selective technology licensing for plasma surface activation pretreatment.
Among European integrated manufacturers, Continental AG anchors the automotive-industrial tier through specification-grade output from Rhine-Ruhr manufacturing centers. Trelleborg AB occupies the marine-offshore specialization vector where saltwater exposure resistance commands premium positioning. Saint-Gobain S.A. exemplifies high-performance polymer expertise inherited from aerospace and chemical processing heritage, competing on thermal resistance metrics. These three entities represent distinct capability configurations that filter competitive participation by certification domain.
| Leading Market Players |
|---|
| Continental AG |
| Trelleborg AB |
| Saint-Gobain S.A. |
| Colmant Coated Fabrics |
| Auburn Manufacturing |
| Arville Textiles Limited |
| Zenith Rubber |
| The Rubber Company |
| Fothergill Group |
| Others |
Supply & Pricing Matrix
REACH Article 33 disclosure obligations gate both supplier qualification and price differentiation simultaneously, compressing the compounder base to vertically integrated manufacturers with captive analytical capabilities while concentrating premium pricing power among IATF-certified European producers serving automotive OEMs.
Pricing Analysis
Certification level (ISO 14116/REACH/FAA-grade) creates the primary spread between specification-grade and commodity tiers. Contract-based long-term offtake dominates automotive and aerospace procurement, while spot purchasing persists in agricultural tarpaulins. Price differentiation hinges on flame-resistance certification depth and volume scale, with public safety equipment buyers least sensitive and construction sector buyers most responsive to cost. Cost compression in commodity nitrile formulations is intensifying because petrochemical input volatility transfers directly to spread coating operations.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for butadiene-derived feedstocks and precision calendering equipment. Supply concentrates in Germany, Japan, and the United States, with German compounders drawing from Rhine-Ruhr petrochemical clusters and Japanese manufacturers sourcing from Nagoya textile finishing corridors. Raw material dependencies rest on acrylonitrile, chloroprene monomer, and aramid fiber substrates. Single-source vulnerability characterizes precision gauge control machinery from German and Japanese equipment builders. Distribution runs through specification-certified distributors for aerospace and marine OEMs, with compounder-direct channels serving industrial volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across certification-intensive segments where SOLAS-mandated replacement cycles and evolving EPA emission standards are spawning niche supply relationships beyond incumbent strongholds.
For Market Incumbents: Fortify specification-grade positioning through backward integration into rubber compounding and plasma surface activation pretreatment capabilities. Threats from fluoropolymer substitution in chemical protection garments demand accelerated silicone-hydrogel hybrid development. Channel control over IATF-certified automotive supply relationships remains the critical defensive lever. For New Entrants and Emerging Players: Lead with BIS-certified supply to India's PLI-incentivized industrial safety equipment localization, the most penetrable geography where domestic manufacturing mandates filter import competition. Target silicone-coated medical drapes for CDSCO biocompatibility-certified entry, deploying technical consultancy partnerships to unbundle formulation support from volume contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thin-film aerospace grades where precision calendering equipment scarcity elevates barrier to entry. Long-term viability favors acquiring European compounders with REACH compliance depth and captive textile finishing operations. Watch EPA residual risk review implementation as inflection signal for US manufacturing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive control over REACH-certified formulation secures automotive OEM specification-grade supply relationships. |
| Plasma Surface Activation Pretreatment Adoption | Atmospheric plasma systems from German and French tier-1 suppliers displace legacy corona treatment equipment. |
| Water-Based Dispersion Coating Transition | European manufacturing shifts from solvent-based spread coating to meet tightening EPA volatile organic compound standards. |
| India PLI Scheme Localization | BIS certification and domestic manufacturing incentives open specification-grade supply channels for automotive and chemical processing sectors. |
| Silicone-Hydrogel Hybrid Medical Drape Development | Platinum-cured silicone coating convergence with antimicrobial textile finishing commands premium surgical drape positioning. |
Research Methodology
The analysis maps protective equipment, transportation, and containment system sub-sectors, each validated through compounder technical directors, automotive OEM procurement leads, marine safety equipment certification managers, and industrial distributor channel heads. Primary interview intelligence triangulates against customs and trade data, ECHA substance registry filings, SEC 10-K disclosures from listed compounders, and ACC industry reports. Bottom-up segment sizing and top-down macro validation ensure consistency across estimation procedures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models by elastomer chemistry, coating technology precision tier, end-use certification intensity, and regional regulatory cluster. CAGRs derive from segment-level growth trajectory synthesis. Forecast inputs incorporate SOLAS-mandated marine equipment replacement cycles and REACH Article 33 compliance timeline compression.
The analysis sits within stated boundaries; outcomes outside sustained petrochemical input availability, certification regime stability, or aerospace program continuity would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM sourcing consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Snap on Rubber Stopper Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Europe Rubber Hose Market
Rubber
Reclaimed Rubber Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Carboxylated Nitrile Rubber Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Rubber Foam Market
Rubber
Fast Curing Nitrile Butadiene Rubber (NBR) Market
Rubber
Polybutadiene Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Tapes Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Rubber Carbon Black Market