
 Global Concrete Fiber Market | 2026-2036
Global Concrete Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Fiber Market Foresight
Multi-source procurement of high-tensile steel and synthetic fiber is expanding across major concrete admixture suppliers. BASF SE leverages its global chemicals infrastructure to secure consistent polymer feedstock for synthetic fiber production. Sika AG anchors its position through integrated R&D across admixture and reinforcement systems. Bekaert SA dominates drawn-wire steel fiber manufacturing with controlled metallurgical processes that meet stringent ductility specifications.
Concrete fiber consists of discrete reinforcing elements—typically 20-60 mm in length with aspect ratios of 30-100—dispersed throughout cementitious matrices to control plastic shrinkage cracking and enhance post-crack flexural toughness. These fibers serve primarily to replace or supplement conventional steel rebar in applications demanding fatigue resistance and impact absorption. Steel fibers command the largest product category share due to proven performance in heavy-duty industrial flooring and tunnel linings. Synthetic fibers, particularly macro-polypropylene and polyolefin variants, represent the fastest-expanding segment as specifications evolve toward corrosion-resistant alternatives. Glass fibers occupy a specialized niche in architectural and thin-section precast applications where alkali resistance and surface finish quality determine selection.
The US Federal Highway Administration mandates AASHTO-compliant reinforcement for bridge deck overlays, while the EU Construction Products Regulation enforces CE marking and harmonized EN 14889 standards for steel and polymer fibers. China's GB/T standards and Ministry of Ecology and Environment directives on embodied carbon in building materials are reshaping import qualification criteria and domestic procurement protocols. Stakeholders must monitor evolving national building codes and green certification thresholds that increasingly prescribe fiber dosage rates based on lifecycle carbon accounting rather than purely mechanical performance.
Market Dynamics
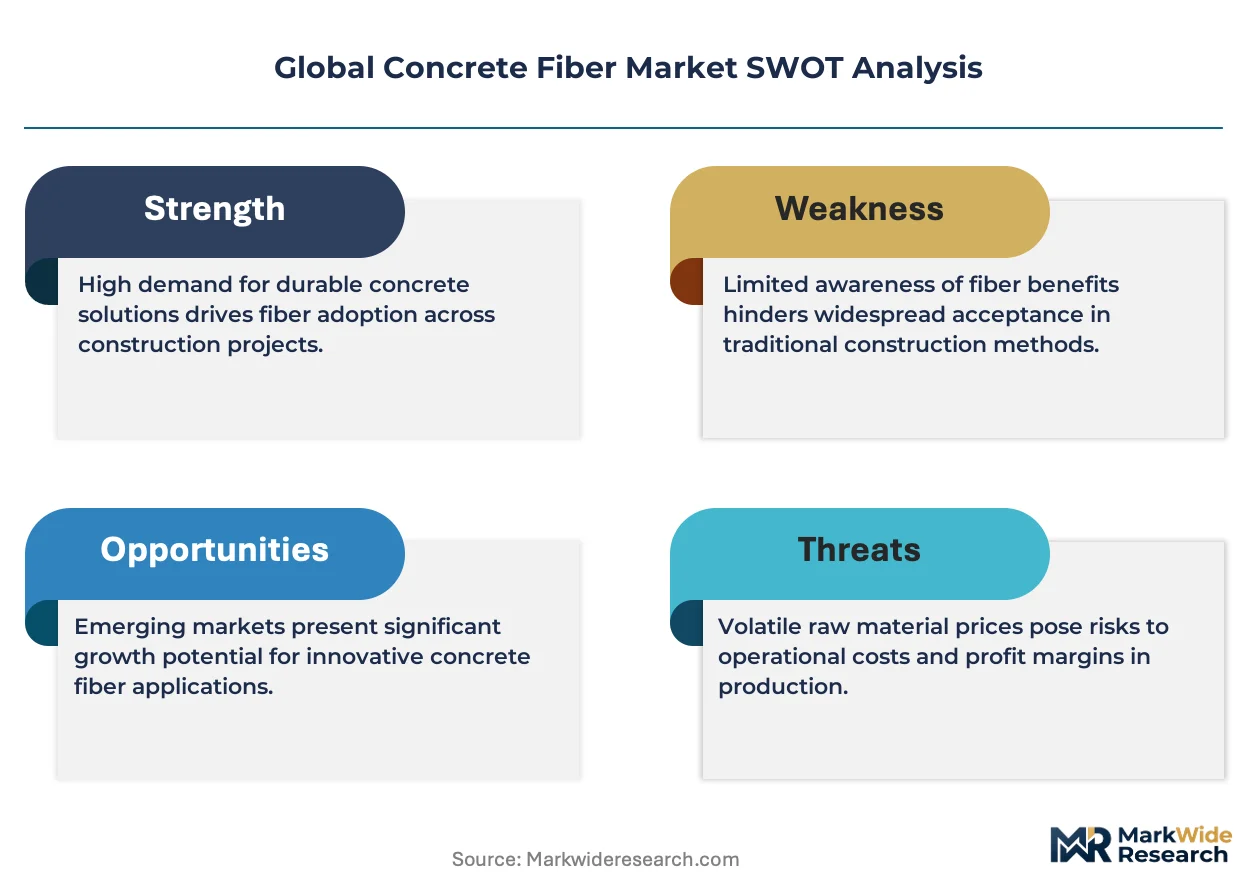
Steel fiber specifications are tightening as infrastructure engineers demand higher ductility ratings for seismic-resistant bridge decks, forcing metallurgical upgrades across drawn-wire production chains.
Growth Catalysts
- US Infrastructure Investment and Jobs Act:Federal highway appropriations mandate macro-synthetic fiber in bridge overlays, accelerating specification shifts away from conventional rebar in interstate corridors.
- EU Green Deal embodied carbon protocols:Lifecycle accounting rules now credit lower-carbon reinforcement alternatives, tilting public procurement toward polymer fiber in tunnel and rail applications.
- China's urban resilience programs:Ministry of Ecology and Environment directives on building material carbon intensity are reshaping domestic procurement protocols for fiber-reinforced concrete in flood-control infrastructure.
Market Restraints
- Polypropylene feedstock volatility:Synthetic fiber margins compress when naphtha and propylene prices spike, exposing producers to petrochemical cycle swings without pass-through mechanisms.
- Steel fiber supply concentration:Drawn-wire capacity clusters in Belgium and China, creating geographic vulnerability when trade flows face tariff or logistics friction.
- Alkali-silica reaction limitations:Glass fiber remains excluded from high-pH concrete environments, restricting architectural precast applications despite aesthetic advantages.
Strategic Opportunities
- India's highway expansion:National Highways Authority of India projects lack established fiber specifications, creating first-mover advantage for suppliers who qualify macro-polypropylene in rigid pavement designs.
- 3D-printed concrete convergence:Robotic construction systems require precisely dosed short-fiber reinforcement, opening specification windows for engineered micro-synthetics in additive manufacturing.
- EU Construction Products Regulation updates:Pending EN 14889 revisions will mandate recycled content thresholds, rewarding early movers with certified circular polymer feedstock streams.
Industry Challenges
- Dosage optimization expertise gap:Field engineers lack training in fiber-matrix interaction modeling, causing over-specification that inflates project costs and delays adoption.
- CE marking timeline compression:European Notified Body backlogs extend polymer fiber certification cycles, freezing new product launches for 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Fiber Market |
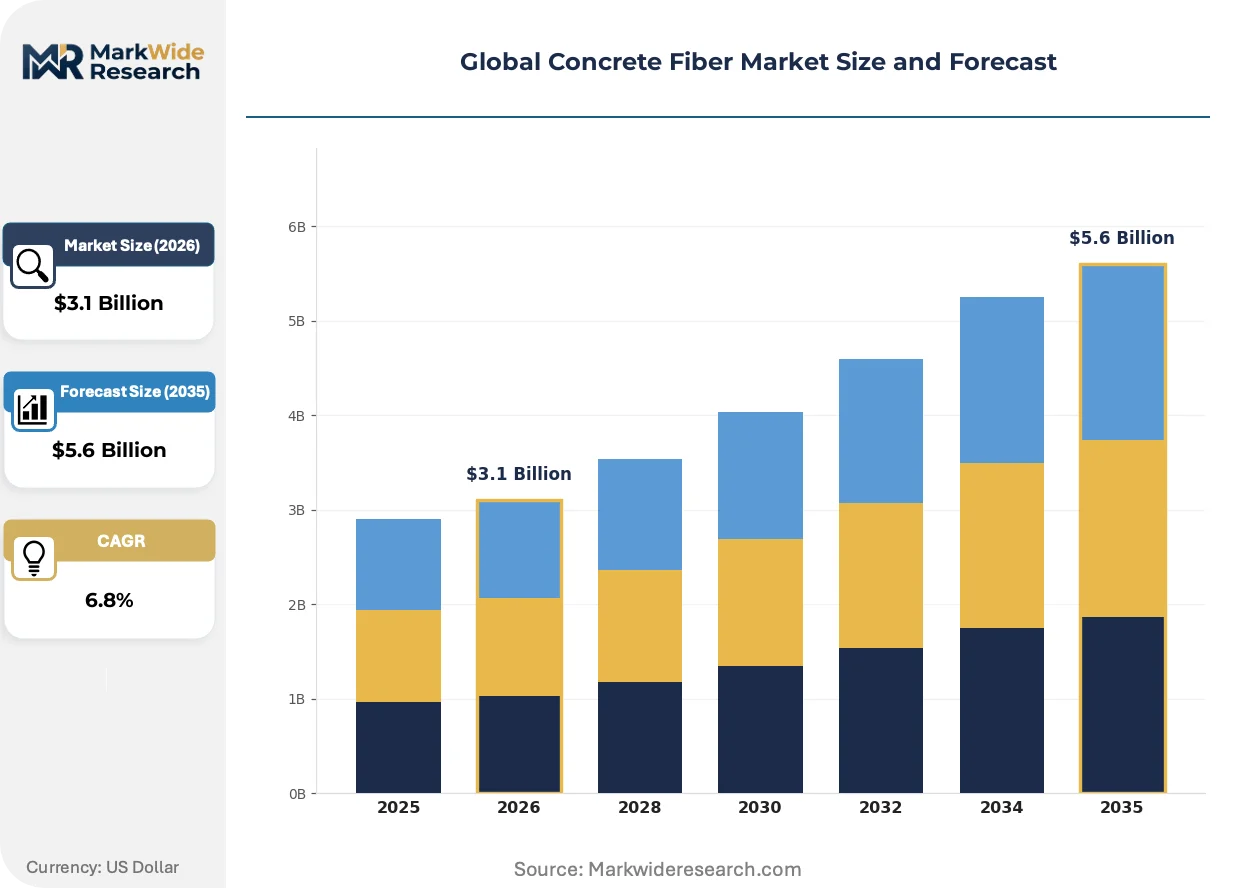
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Fibers, Synthetic Fibers, Glass Fibers, Natural Fibers Application: Roadways, Bridges, Tunnels, Industrial Flooring End User Industry: Construction Contractors, Infrastructure Developers, Commercial Builders, Residential Developers Deployment Method: Pre-mix, Spray-applied, Wet-mix, Dry-mix |
| Companies Covered | BASF SE, Sika AG, Bekaert SA, Owens Corning, GCP Applied Technologies Inc., CEMEX S.A.B. de C.V., ABC Polymer Industries LLC, The Euclid Chemical Company, Fibercon International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Fiber Market Shifts & Advancements
Hybrid fiber systems are displacing single-material reinforcement as engineers optimize crack control across plastic and hardened concrete phases. The convergence of synthetic and steel fiber in specified blends is compressing traditional category boundaries.
Macro-polyolefin fiber with improved elastic modulus is unifying post-crack performance standards previously segmented by material type. Highway contractors in Germany and the Netherlands are adopting these hybrids for industrial flooring. The technology is unifying procurement categories that steel and synthetic suppliers historically contested separately.
China's GB/T 21120 revisions are tightening steel fiber tensile strength minimums for tunnel segment applications. Domestic producers must upgrade drawing equipment to meet 1200 MPa thresholds. Underground rail projects in Chengdu and Xi'an are already rejecting non-compliant imports.
Specification engineers now bundle fiber selection with admixture packages rather than sourcing separately. Integrated suppliers capture bridge and dam contracts through combined R&D guarantees. This bundling concentrates most visibly in US Federal Highway Administration-funded projects where single-source accountability reduces litigation exposure.
Global Concrete Fiber Market Segmentation
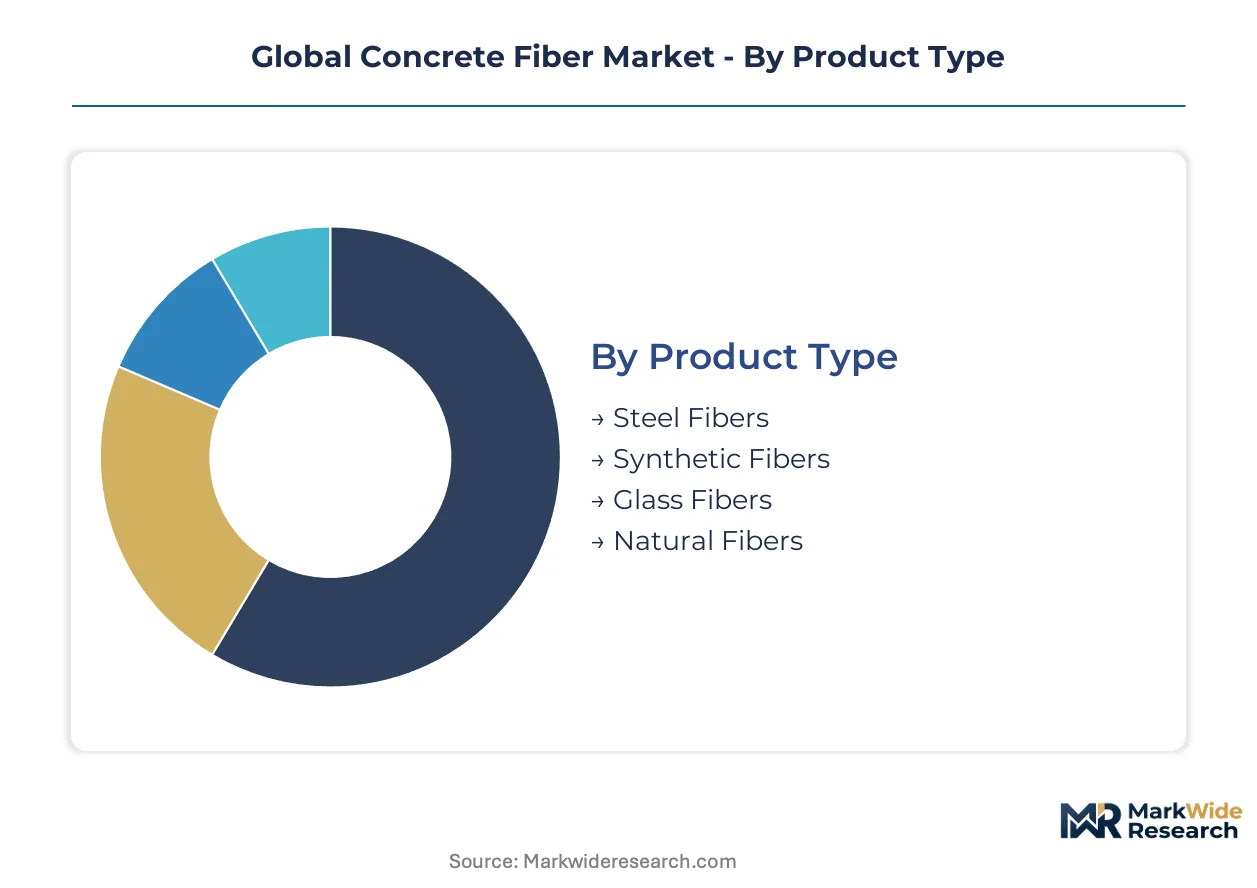
Concrete fiber procurement decisions hinge on performance requirements, installation constraints, and lifecycle carbon accounting. Engineers match fiber type to crack-control needs while contractors optimize deployment methods for project scale and labor availability.
Product Type:
Buyers prioritize post-crack ductility and corrosion resistance when selecting reinforcement categories.
- Steel Fibers:Cold-drawn wire segments with aspect ratios of 45-80 deliver the highest tensile strength for heavy-duty industrial slabs. Demand concentrates in Germany and China for tunnel segment lining where GB/T 21120 mandates 1200 MPa minimums.
- Synthetic Fibers:Macro-polypropylene and polyolefin variants resist alkali attack and eliminate corrosion risk in bridge deck overlays. Highway contractors in the United States specify these under Federal Highway Administration guidelines for interstate corridor rehabilitation.
- Glass Fibers:Alkali-resistant formulations serve architectural precast panels demanding surface finish quality.
- Natural Fibers:Cellulose and jute derivatives fill emerging low-carbon niche applications in non-structural screeds.
Volume sits with steel fibers; growth tilts toward synthetic fibers.
Application:
Project scale and load severity determine specification intensity across infrastructure verticals.
- Industrial Flooring:Warehouse and logistics centers demand hybrid fiber systems combining steel ductility with synthetic plastic shrinkage control. German industrial park developers specify these blends for 200mm-thick slabs under heavy racking loads.
- Bridges:Deck overlays require AASHTO-compliant macro-synthetic reinforcement to replace epoxy-coated rebar. US state DOTs are expanding fiber dosage mandates in coastal corrosion zones.
- Tunnels:Segmental lining applications favor high-tensile steel fiber for seismic energy absorption.
- Roadways:Rigid pavement designs in India lack established fiber protocols, creating specification gaps for macro-polypropylene qualification.
Industrial flooring commands the largest volume base; bridge applications are climbing the fastest.
End User Industry:
Procurement sophistication varies sharply between public infrastructure agencies and private developers.
- Infrastructure Developers:National highway authorities and rail agencies bundle fiber with admixture packages under single-source accountability frameworks. China's Ministry of Ecology and Environment carbon directives reshape their tender evaluation criteria.
- Construction Contractors:Mid-tier firms lack dosage optimization expertise, driving over-specification that inflates material costs on commercial projects.
- Commercial Builders:Speculative office and retail developers prioritize first-cost minimization over lifecycle performance.
- Residential Developers:Single-family and multifamily construction rarely specifies engineered fiber, relying instead on welded wire mesh for crack control.
Infrastructure developers absorb the highest fiber volumes; commercial builders present the steepest expansion trajectory as green building codes tighten.
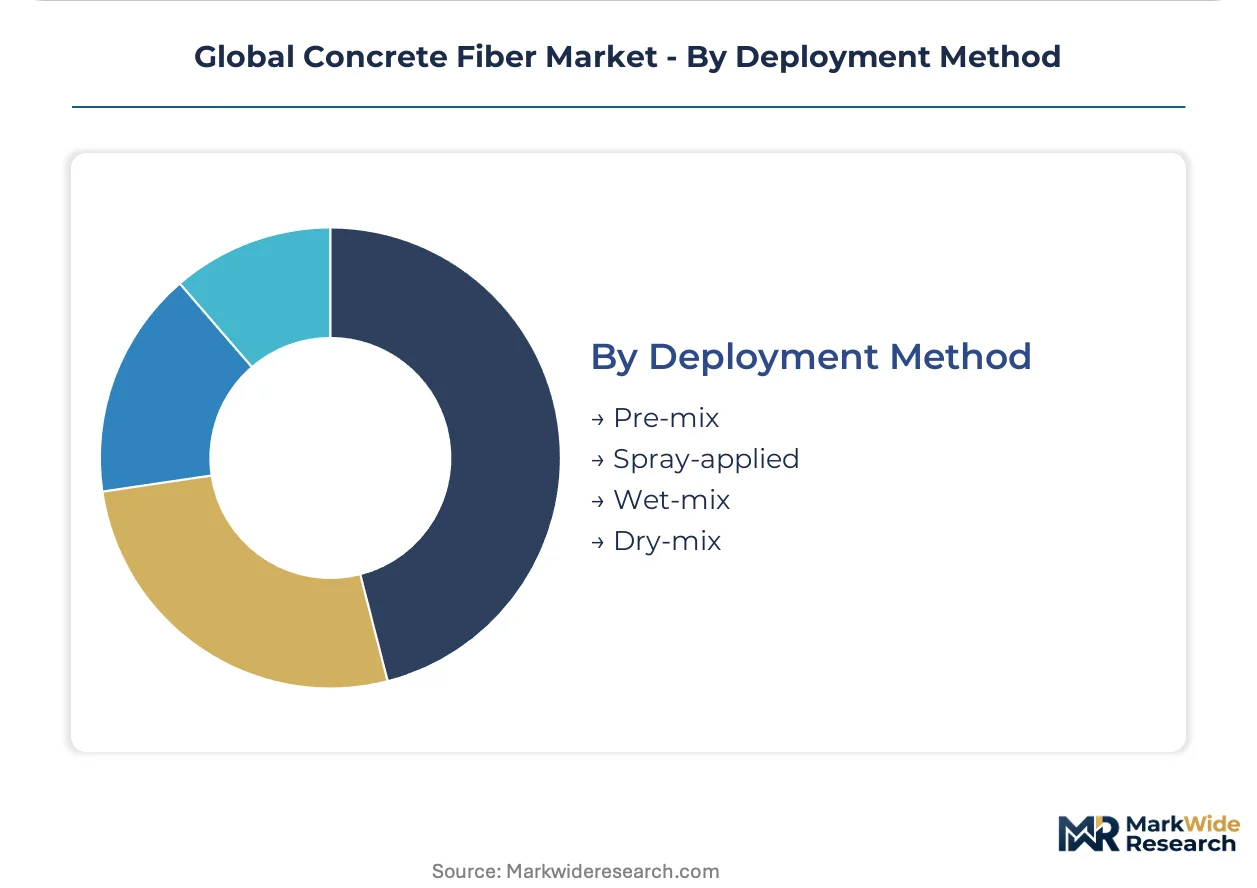
Deployment Method:
Equipment availability and batch plant infrastructure constrain method selection on remote or urban-constrained sites.
- Pre-mix:Central batch plant dispersion ensures uniform fiber distribution for large-volume highway and dam pours. European ready-mix suppliers have standardized automated dosing systems for macro-synthetic integration.
- Spray-applied:Shotcrete operations in tunneling and slope stabilization demand rapid-set formulations with micro-synthetic fiber for early-age crack suppression.
- Wet-mix:Pumped concrete applications for high-rise construction require fiber length limits to prevent line blockages.
- Dry-mix:Bagged mortar systems serve repair and overlay niches where site batching is unavoidable.
Pre-mix dominates volume; spray-applied methods are gaining share fastest in underground construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's drawn-wire steel production and China's metallurgical clusters anchor the upstream supply base for concrete fiber reinforcement. Germany's industrial flooring demand and India's highway expansion reshape procurement patterns across continents. Regulatory pressure on embodied carbon accelerates specification shifts in every major construction market.
United States
Federal highway appropriations under the Infrastructure Investment and Jobs Act mandate macro-synthetic fiber in bridge deck overlays across interstate corridors. The Federal Highway Administration enforces AASHTO-compliant reinforcement standards for corrosion-resistant applications. State DOTs in coastal zones from Florida to California are expanding fiber dosage mandates for marine-exposed infrastructure.
China
Urban resilience programs and flood-control infrastructure drive specification intensity for fiber-reinforced tunnel segments. The Ministry of Ecology and Environment issues directives on building material carbon intensity that reshape domestic procurement protocols. Underground rail projects in Chengdu and Xi'an reject steel fiber imports below 1200 MPa tensile strength thresholds.
Germany
Industrial park developers specify hybrid fiber systems for 200mm-thick warehouse slabs under heavy racking loads. The EU Green Deal's embodied carbon protocols credit lower-carbon reinforcement alternatives in public procurement. Highway contractors in the Netherlands and Germany adopt macro-polyolefin hybrids for industrial flooring applications.
India
National Highways Authority of India projects lack established fiber protocols, creating qualification gaps for macro-polypropylene in rigid pavement designs. The Bureau of Indian Standards develops certification frameworks for synthetic fiber reinforcement. Construction clusters in Gujarat and Maharashtra test dosage optimization for large-scale transportation corridors.
Belgium
Drawn-wire steel fiber capacity concentrates in Belgian metallurgical facilities serving European tunnel and heavy-duty flooring markets. CE marking requirements under the EU Construction Products Regulation enforce EN 14889 standards for steel and polymer fibers. Notified Body backlogs in Brussels and Leuven extend polymer fiber certification cycles for new product launches.
Global Concrete Fiber Market Competitive Landscape
Capacity expansion dominates the current landscape as producers upgrade drawing equipment and polymer extrusion lines to meet tightening tensile specifications. The vendor base organizes around three archetypes: integrated chemical conglomerates with captive polymer feedstock, specialized steel wire drawers with metallurgical process control, and admixture bundlers offering combined reinforcement systems. Geographic expansion and strategic partnerships constitute the primary competitive vectors as suppliers seek qualification in India's specification-ambiguous highway market.
Among integrated chemical conglomerates, BASF SE and Sika AG occupy positions that exemplify upstream control over polymer supply chains and cross-product R&D bundling. Bekaert SA anchors the specialized metallurgical tier with Belgian-based drawn-wire capabilities. These three entities represent distinct strategic postures: feedstock security, integrated admixture-reinforcement systems, and precision metallurgical processing.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Bekaert SA |
| Owens Corning |
| GCP Applied Technologies Inc. |
| CEMEX S.A.B. de C.V. |
| ABC Polymer Industries LLC |
| The Euclid Chemical Company |
| Fibercon International Inc. |
| Others |
Supply & Pricing Matrix
Family-owned Belgian metallurgical specialists and sovereign-backed Chinese steel producers anchor drawn-wire capacity, creating asymmetric pricing power where concentrated upstream ownership resists pass-through demands during petrochemical volatility cycles.
Pricing Analysis
Warranty-bundled dosage optimization services separate premium synthetic fiber suppliers from commodity traders serving spot buyers. Three-tier pricing structure across certified-performance, standard-grade, and unbundled-economy levels tracks EN 14889 compliance tiers and volume scale. Pricing pressure stems from polypropylene feedstock volatility compressing synthetic margins without contractual pass-through clauses. Mid-tier construction contractors exhibit acute price sensitivity, while infrastructure developers absorb premium tiers for single-source accountability.
Supply Chain Analysis
Regional distribution centers in Antwerp, Shanghai, and Houston maintain 30-60 day inventory buffers against drawn-wire production backlogs. Supply concentrates in Belgium and China for cold-drawn steel fiber, with polymer extrusion clustering in Germany and the United States. Raw material dependencies include naphtha-derived polypropylene, high-carbon wire rod, and alkali-resistant glass formulations. Single-source vulnerability in Belgian metallurgical equipment creates chokepoint risk for 1200 MPa tensile strength upgrades. Distribution runs through admixture bundlers capturing combined procurement decisions on federally funded highway projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drawn-wire capacity expansion lags specification tightening for seismic-grade steel fiber, propping pricing discipline as infrastructure agencies compete for qualified supply.
For Market Incumbents: Extend metallurgical R&D partnerships into Chengdu and Xi'an rail corridors to preempt GB/T 21120 compliance rejections. Secure captive polymer feedstock through backward integration into propylene supply chains before naphtha volatility intensifies. Lock long-term offtake agreements with National Highways Authority of India projects to anchor volume before specification standards crystallize. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian rigid pavement specifications opens qualification windows for macro-polypropylene suppliers with dosage optimization expertise. Target coastal US state DOTs expanding fiber mandates in marine corrosion zones where incumbent capacity is committed. Lead with integrated admixture-fiber bundling to bypass standalone specification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized steel wire drawers with EN 14889 certification assets in European tunnel markets. Long-term viability hinges on circular polymer feedstock positioning ahead of pending recycled content thresholds. Monitor CE marking timeline compression at Brussels Notified Bodies as inflection indicator for new product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | BASF SE's captive naphtha supply secures synthetic fiber margin stability against petrochemical cycles. |
| Certification Investment in GB/T 21120 Compliance | Bekaert SA's 1200 MPa tensile strength upgrades preserve access to Chengdu underground rail segments. |
| Joint Venture with Admixture Suppliers | Sika AG's bundled R&D guarantees capture US Federal Highway Administration single-source contracts. |
| Capacity Expansion in Drawn-Wire Steel | Belgian metallurgical clusters add seismic-grade output to meet EU tunnel lining demand. |
| Green Manufacturing Transition | Certified circular polymer streams position early movers for EN 14889 recycled content mandates. |
Research Methodology
Independent corroboration across plant managers at drawn-wire facilities, procurement leads at downstream admixture suppliers, and technical R&D directors at polymer producers underwrites the qualitative findings. Primary interviews with highway agency specification engineers and tunnel project contractors combined with secondary validation from customs/trade data, SEC 10-K filings, and Bureau of Indian Standards draft frameworks. Bottom-up volume estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Comparable-period anchoring to historical specification adoption curves calibrated the projection horizon for synthetic fiber displacement rates. Segmentation modeling spanned product type, application vertical, end-user industry sophistication, and deployment method complexity. CAGRs derived from elasticity-adjusted demand functions incorporating petrochemical input volatility and regulatory compliance timeline compression.
Inputs from European Notified Body certification databases and Chinese Ministry of Ecology and Environment procurement bulletins were available through the study window; gaps in real-time Indian Bureau of Indian Standards finalization introduce uncertainty bands around rigid pavement adoption timelines. Forecasts reflect documented assumptions on specification evolution speed and feedstock price regime stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Fiberglass Mat Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Bioglass Fiber Market
Fibers
Carbon Fiber Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Basalt Continuous Fiber (BCF) Market