
 Viscose Market | 2026-2036
Viscose Market Size, Share, and Industry Trends Forecast 2026-2036
Viscose Market Outlook
Multi-source pulp procurement is consolidating around vertically integrated producers with captive dissolving wood pulp capacity. Lenzing AG leverages its biorefinery model to sustain premium fiber output across European and Asian markets. Grasim Industries Limited anchors South Asian supply through backward integration into pulp manufacturing. Sateri Holdings competes on scale with integrated facilities in China that control cost structures across the value chain.
Viscose is a regenerated cellulose fiber produced by treating wood pulp with sodium hydroxide and carbon disulfide, then extruding the resulting viscose solution through spinnerets into an acid bath to form continuous filaments or staple fibers with cotton-like handle and moisture absorption properties. The fiber serves textile mills seeking biodegradable alternatives to petroleum-based synthetics in apparel and home furnishing applications. High tenacity viscose dominates industrial rope and tire cord applications where tensile strength requirements exceed standard grades. Specialty viscose captures margin pools in medical textiles and technical nonwovens where functional finishes command price premiums over commodity staple fiber.
The EU Green Deal and REACH chemical regulations in Europe constrain carbon disulfide emissions and wastewater discharge from viscose manufacturing, pushing producers toward closed-loop systems. China's Ministry of Ecology and Environment enforces discharge standards that filter small-scale dissolving pulp processors from the market. The International Organization for Standardization provides cellulose fiber traceability frameworks that buyers increasingly embed in procurement specifications. Stakeholders must monitor regulatory divergence between Asian manufacturing hubs and European end-markets when siting new capacity or certifying supply chains.
Market Dynamics
The viscose market is being reshaped by the EU Green Deal's tightening discharge standards, which are forcing producers to abandon conventional carbon disulfide processes and adopt closed-loop manufacturing systems across European supply chains.
Growth Catalysts
- EU Green Deal chemical regulations:REACH-enforced carbon disulfide emission limits are accelerating closed-loop adoption among European viscose producers, creating compliant capacity that commands procurement preference from fashion brands.
- Textile mill demand for biodegradable alternatives:Apparel manufacturers seeking petroleum-free fibers are expanding viscose purchase specifications to replace polyester in woven and knit applications.
- China's integrated pulp-to-fiber complexes:Concentrated manufacturing in Jiangsu and Zhejiang provinces delivers cost-competitive dissolving wood pulp conversion that anchors regional export supply.
Market Restraints
- Dissolving wood pulp supply concentration:Captive pulp production by Lenzing AG and Sateri Holdings creates input dependency for non-integrated spinners facing margin compression during pulp price spikes.
- Carbon disulfide toxicity constraints:OSHA workplace exposure limits and ECHA hazard classifications restrict conventional viscose expansion in North American and European jurisdictions.
- Lyocell substitution threat:Solvent-spun cellulose fibers produced via N-methylmorpholine-N-oxide direct dissolution are capturing medical textile and premium apparel share from conventional viscose.
Strategic Opportunities
- India's underpenetrated technical textile sector:Tire cord and industrial rope applications in Maharashtra and Gujarat offer volume expansion for high-tenacity viscose grades currently imported.
- EU CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements are creating certified fiber premiums that reward ISO traceability-compliant producers with procurement preference.
- Digital textile printing convergence:Reactive dye compatibility of viscose is expanding into on-demand apparel production where moisture management properties differentiate finished goods.
Industry Challenges
- Closed-loop engineering talent scarcity:Chemical process engineers with carbon disulfide recovery system expertise are concentrated among legacy European producers, constraining rapid technology transfer to Asian facilities.
- CanopyStyle audit timelines:Ancient and endangered forest certification requirements from Canopy Planet add 12-18 month procurement qualification delays for new pulp suppliers entering brand supply chains.
- Legacy spinneret replacement cycles:Acid bath extrusion equipment retrofits for reduced water consumption require extended downtime that conflicts with continuous production schedules at commodity-grade plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscose Market |
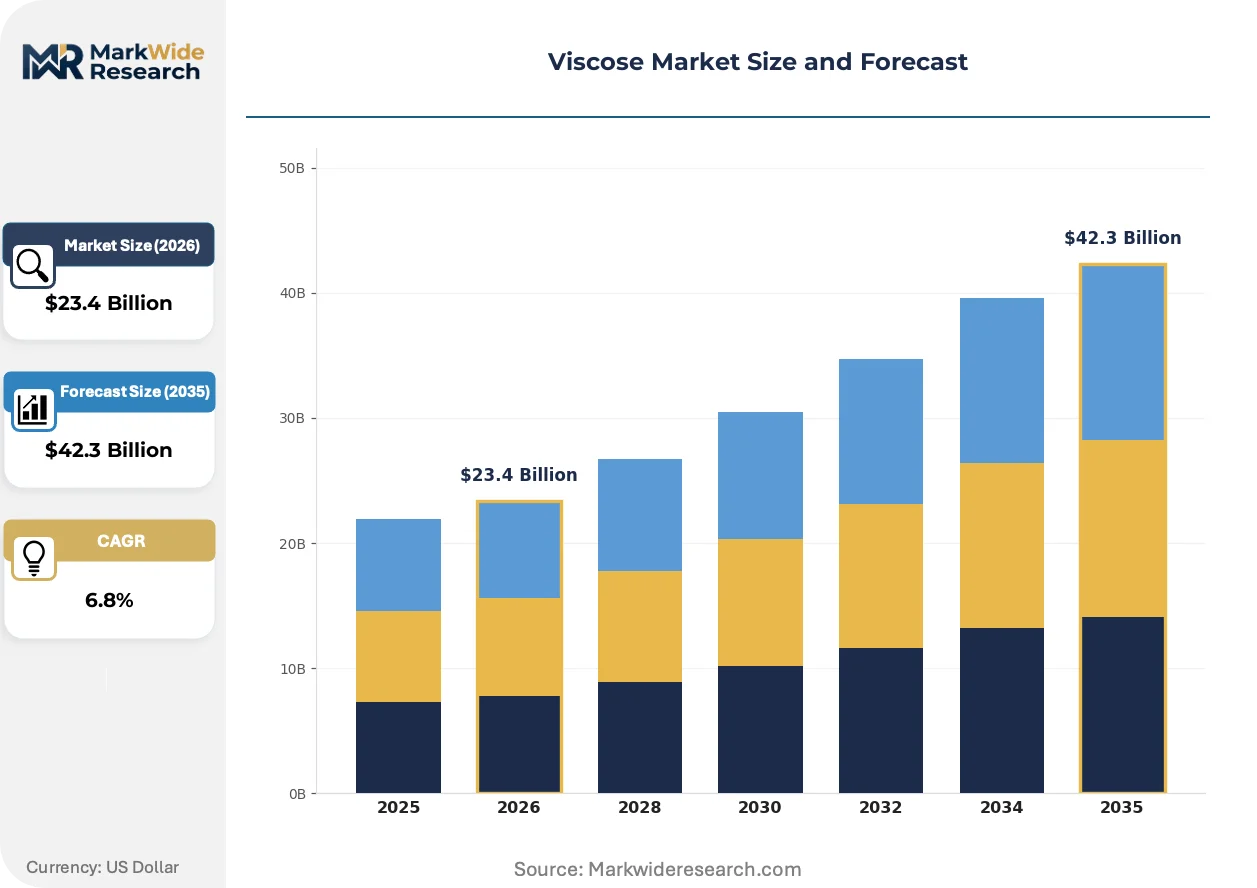
| Market Size in 2026 | $23.4 Billion |
| Market Size in 2035 | $42.3 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Viscose, High Tenacity Viscose, Specialty Viscose, Viscose Staple Fiber End Use Industry: Textiles, Home Furnishings, Nonwovens, Industrial Applications Form: Filament Yarn, Staple Fiber, Composites, Tow Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Sateri Holdings, Lenzing AG, Grasim Industries Limited, Tangshan Sanyou Group, Xinjiang Zhongtai Group, Kelheim Fibres GmbH, China National Chemical Corporation, Eastman Chemical Company, Xinxiang Bailu Chemical Fibre Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscose Market Strategic Shifts
Manufacturing technology and procurement specifications are converging to favor traceable, low-emission cellulose fiber production as brand sustainability commitments harden into enforceable supply chain requirements.
Lyocell production technology is expanding into conventional viscose market positions through solvent recycling systems that eliminate carbon disulfide entirely. Outdoor apparel brands in Germany and Scandinavia are specifying Tencel-branded lyocell for base layers and activewear at accelerating volumes. This transition is compressing demand for commodity viscose in premium segments while pushing conventional producers toward industrial and medical applications where cost sensitivity dominates.
China's Ministry of Ecology and Environment discharge standards are forcing dissolving pulp processors to install wastewater treatment infrastructure or exit the market entirely. Small-scale operators in Shandong and Hebei provinces face consolidation pressure as compliance costs exceed marginal revenue. Integrated producers with captive chemical recovery systems are capturing stranded market share from decommissioned competitors.
Textile mill procurement is rotating toward certified fiber sourcing as ZDHC Manufacturing Restricted Substances List compliance becomes a non-negotiable entry ticket to European brand supply chains. Spinners in Portugal and Turkey are demanding CanopyStyle and FSC chain-of-custody documentation that excludes conventional uncertified viscose. This behavioral shift is most visible in woven apparel supply chains where finished goods carry explicit fiber origin labeling for consumer-facing transparency.
Viscose Market Segmentation
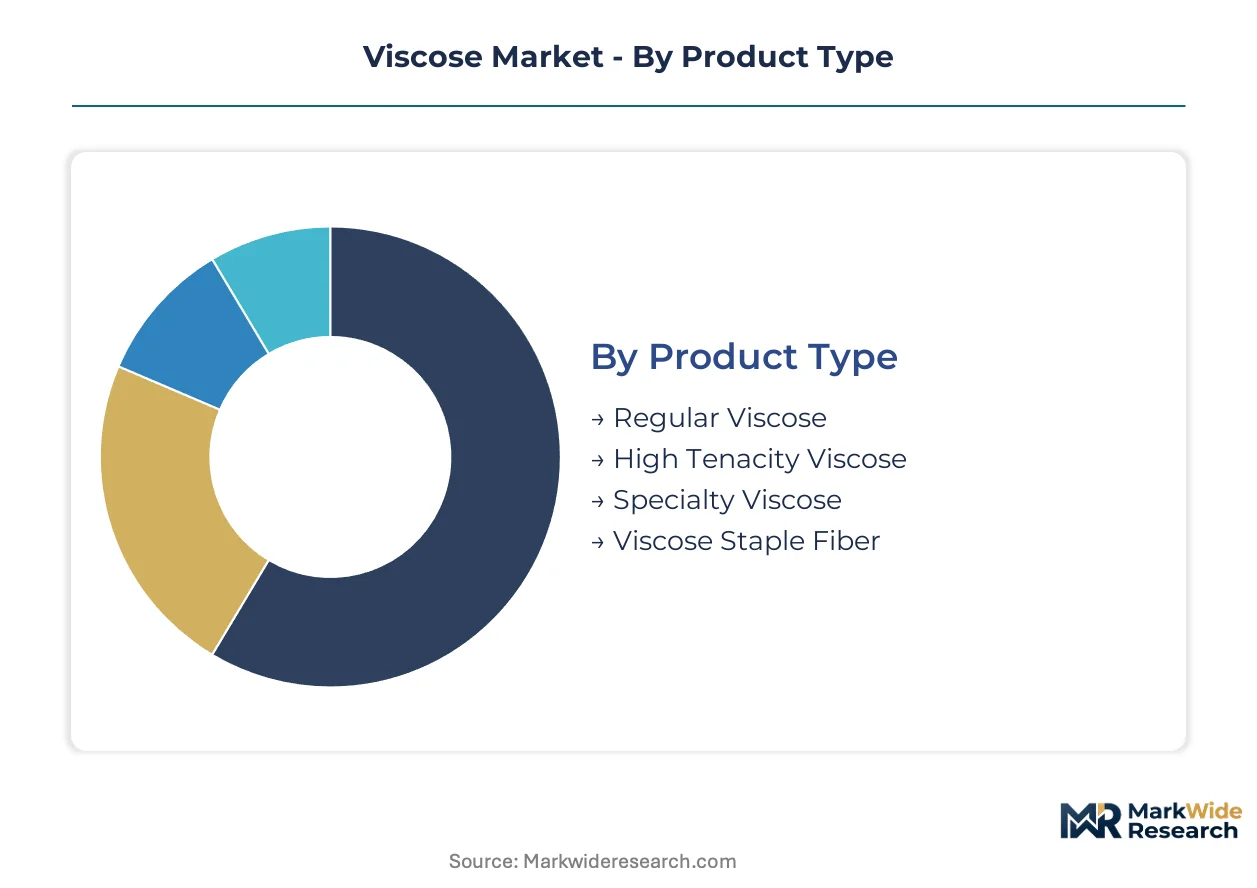
Segmentation in viscose reveals distinct capital requirements and margin profiles across product grades, end-use applications, and distribution channels. Each category carries specific technical specifications that determine equipment investment, regulatory compliance burden, and customer procurement behavior.
Product Type:
Capital intensity varies sharply across product categories, with high tenacity and specialty grades demanding precision spinneret arrays and extended acid bath recovery systems that regular commodity lines do not require.
- Regular Viscose:Standard-grade fiber produced through conventional carbon disulfide processing with cotton-like handle and moderate tenacity. Textile mills in Bangladesh and Vietnam absorb volume for fast-fashion woven and knit applications where cost minimization overrides performance specifications. This grade absorbs the bulk of installed capacity; specialty viscose is expanding most quickly.
- High Tenacity Viscose:Engineered for superior tensile strength through controlled molecular orientation during regeneration. Tire cord manufacturers in Thailand and industrial rope producers in Turkey specify this grade where load-bearing requirements exceed 4.0 cN/dtex. REACH-compliant European producers command procurement preference from automotive OEMs embedding sustainability criteria in supplier scorecards.
- Specialty Viscose:Functionalized variants with antimicrobial, flame-retardant, or superabsorbent finishes for medical textiles and technical nonwovens.
- Viscose Staple Fiber:Cut-length fiber for cotton blending in ring and open-end spinning systems.
Regular viscose absorbs the bulk of installed capacity; specialty viscose is expanding most quickly.
End Use Industry:
Application-driven segmentation separates consumer-facing segments with brand visibility requirements from industrial buyers prioritizing specification compliance over certification documentation.
- Textiles:Apparel and fashion fabrics where ZDHC MRSL compliance and CanopyStyle certification determine mill qualification for European brand supply chains. Portuguese and Turkish spinners now require chain-of-custody documentation as a non-negotiable entry condition.
- Home Furnishings:Upholstery, curtains, and bedding applications where moisture absorption and dye affinity differentiate viscose from polyester alternatives. Indian retailers in Mumbai and Delhi are expanding private-label home textile lines that specify certified fiber origins for consumer-facing transparency.
- Nonwovens:Disposable and durable nonwoven fabrics for hygiene and medical applications.
- Industrial Applications:Tire cord, conveyor belts, and hose reinforcement where high tenacity grades meet precise tensile specifications.
Textiles command the largest share of fiber offtake; nonwovens are climbing the fastest as medical hygiene demand accelerates.
Form:
Physical form determines downstream processing equipment compatibility and influences logistics cost structures through density and packaging efficiency.
- Filament Yarn:Continuous filament for silk-like fabrics and high-end lingerie. Italian weavers in Como specify bright and dull luster variants for luxury apparel where hand-feel drape properties justify premium positioning over spun alternatives.
- Staple Fiber:Discontinuous fiber cut to cotton-equivalent lengths for blending with natural and synthetic fibers in conventional spinning systems.
- Composites:Fiber-reinforced matrices for automotive interior panels and construction applications.
- Tow:Untwisted bundles of continuous filaments for conversion to staple or direct use in cigarette filters and technical applications.
Staple fiber dominates volume throughput; filament yarn is gaining share fastest in premium apparel segments.
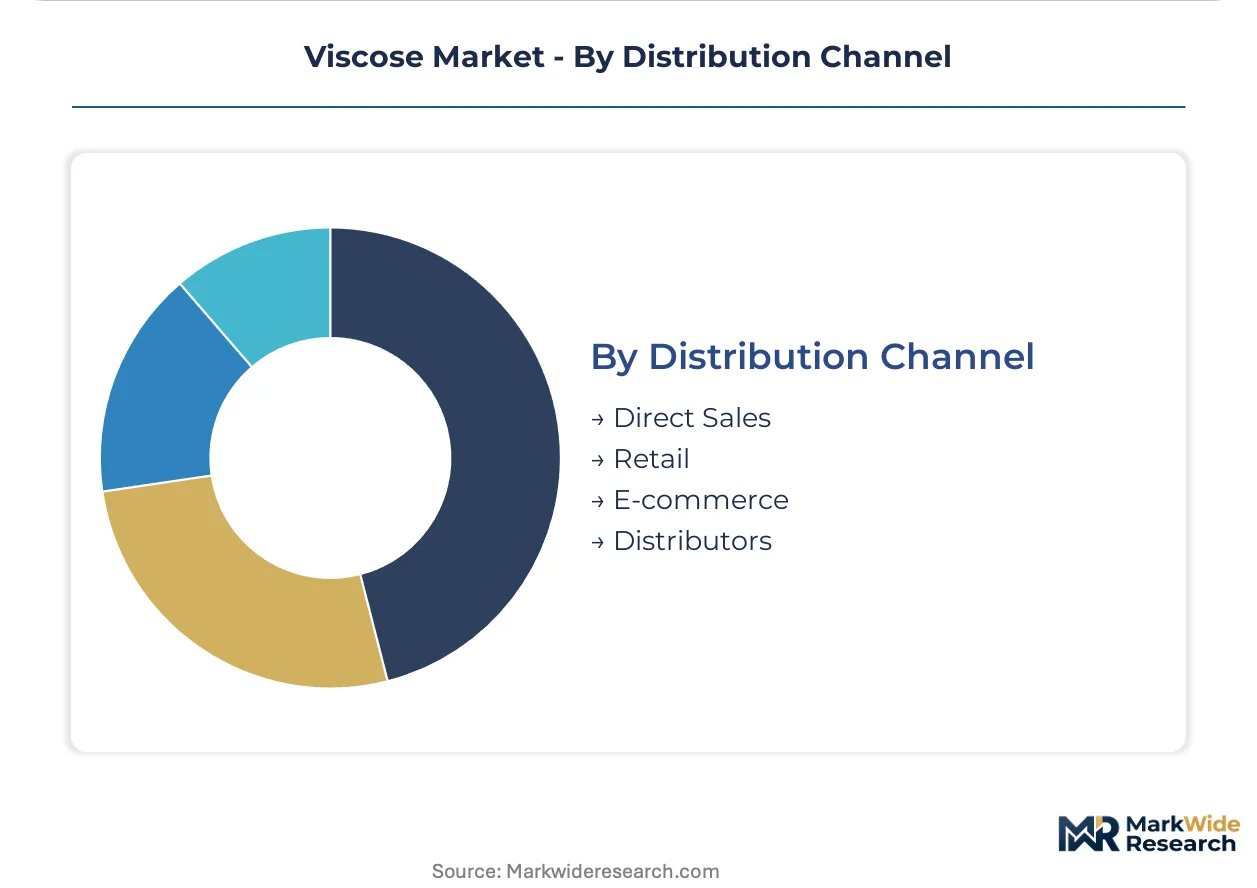
Distribution Channel:
Channel segmentation reflects customer scale and technical service requirements, with direct relationships reserved for volume buyers and specification-intensive applications.
- Direct Sales:Mill-direct contracts with integrated textile producers and nonwoven manufacturers. Lenzing AG and Grasim Industries leverage technical service teams to secure multi-year supply agreements with tire cord and medical textile producers requiring batch consistency documentation.
- Distributors:Regional stocking intermediaries serving small and mid-scale spinners with fragmented order patterns and mixed fiber requirements.
- Retail:Branded fiber sales to consumer-facing channels for craft and specialty sewing applications.
- E-commerce:Digital procurement platforms emerging for standardized grades with transparent pricing and rapid sample fulfillment.
Direct sales channels capture the majority of tonnage movement; e-commerce is expanding most quickly for standardized commodity grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dissolving wood pulp availability in Scandinavia and the Baltic states anchors European viscose feedstock security. Manufacturing clusters in China, Indonesia, and India convert this pulp into textile-grade fiber for apparel supply chains.
China
Jiangsu and Zhejiang provinces host integrated pulp-to-fiber complexes supplying global textile demand. MEE discharge standards are decommissioning small-scale processors in Shandong and Hebei, consolidating output among compliant operators with captive chemical recovery. Sateri Holdings anchors regional scale through facilities in Fujian that control cost structures from dissolving pulp through finished staple fiber.
India
Maharashtra and Gujarat textile mills are expanding viscose blending ratios in ring-spun yarn for export apparel. BIS quality certification requirements for imported dissolving pulp are tightening input specifications for non-integrated spinners. Grasim Industries Limited anchors South Asian supply through captive pulp manufacturing in Madhya Pradesh that feeds downstream fiber plants in Karnataka and Tamil Nadu.
Germany
REACH-enforced carbon disulfide emission limits are accelerating closed-loop retrofits among specialty fiber producers. ECHA hazard classifications for viscose process chemicals constrain conventional expansion, pushing investment toward solvent-spun alternatives. Kelheim Fibres GmbH occupies a position within the premium industrial fiber segment, supplying tire cord and technical textile manufacturers across the Rhine-Ruhr manufacturing corridor.
Indonesia
Apparel export zones in Java are absorbing viscose staple fiber for garment assembly serving European fast-fashion brands. The country's national environmental regulator enforces wastewater discharge standards that filter out non-compliant spinning operations. Integrated facilities in Central Java are capturing market share from decommissioned small-scale competitors through economies of scale in chemical recovery.
United States
OSHA workplace exposure limits for carbon disulfide restrict greenfield viscose investment, preserving import dependence for textile-grade fiber. EPA effluent guidelines for pulp and paper processing constrain dissolving wood pulp expansion in the Southeast. Eastman Chemical Company sits within the specialty cellulose derivatives tier, supplying non-textile applications where functional specifications command premium positioning over commodity fiber alternatives.
Viscose Market Competitive Environment
Backward integration into dissolving wood pulp dominates the current landscape as producers seek margin protection against feedstock volatility. The market exhibits tiered concentration: a handful of integrated multinationals control premium and industrial-grade output, while regional spinners compete on commodity staple fiber with fragmented procurement power. Two strategic archetypes predominate: biorefinery operators leveraging wood pulp diversification, and scale-driven Asian producers optimizing continuous production economics. Capacity expansion and captive pulp supply constitute the dominant competitive moves, with technology licensing emerging as a secondary vector for process efficiency gains.
Within the integrated multinational tier, Lenzing AG and Grasim Industries Limited exemplify divergent geographic strategies. Lenzing AG represents the European biorefinery archetype with Austrian headquarters and Asian production footprints. Grasim Industries Limited anchors the South Asian supply position through Indian corporate structure and regional manufacturing density. Sateri Holdings occupies the Chinese scale-driven position, exemplifying concentrated capacity in integrated facilities. These three entities collectively illustrate how pulp-to-fiber control separates margin-stable operators from input-dependent competitors facing price squeeze during dissolving pulp spikes.
| Leading Market Players |
|---|
| Sateri Holdings |
| Lenzing AG |
| Grasim Industries Limited |
| Tangshan Sanyou Group |
| Xinjiang Zhongtai Group |
| Kelheim Fibres GmbH |
| China National Chemical Corporation |
| Eastman Chemical Company |
| Xinxiang Bailu Chemical Fibre Group |
| Others |
Value Chain & Pricing Dynamics
European fashion brand procurement offices concentrate buying power for certified viscose grades, forcing pricing models toward long-term contract structures that bundle carbon footprint documentation with fiber tonnage. This buyer concentration elevates ISO-compliant producers to preferred supplier status while squeezing spot-market spinners into commodity pricing tiers.
Pricing Analysis
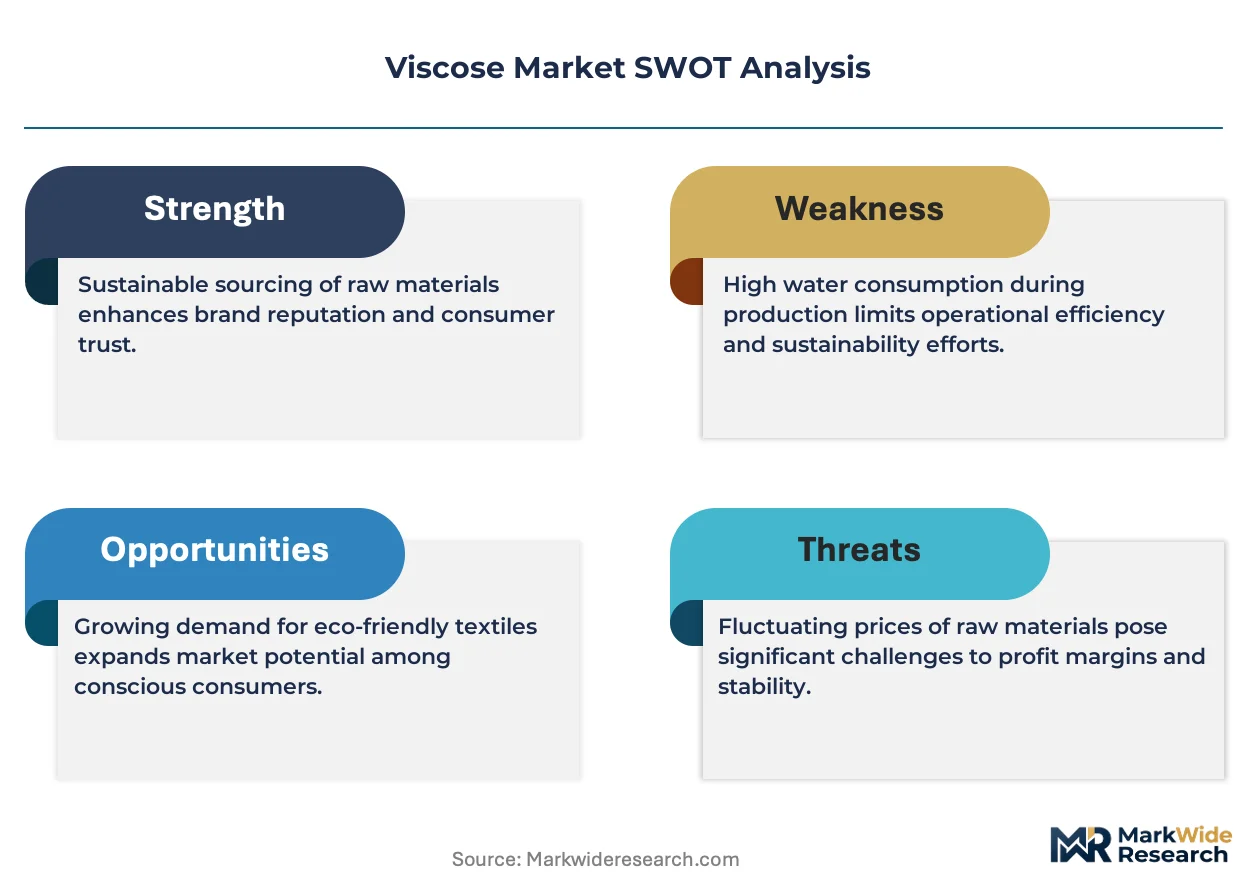
Technical service bundling separates premium fiber contracts from unbundled commodity transactions where mills bear certification costs separately. Three-tier pricing structure across CanopyStyle-certified, FSC-compliant, and uncertified grades reflects differentiation by traceability depth and carbon disclosure granularity. Cost compression in standard-grade staple fiber is intensifying because Indonesian and Vietnamese spinners are expanding captive blending capacity. Fast-fashion garment manufacturers in Bangladesh exhibit highest price sensitivity, while automotive tire cord producers in Germany accept premium positioning for batch consistency documentation.
Supply Chain Analysis
CanopyStyle and ZDHC MRSL qualification gating extends supplier onboarding timelines, filtering small-scale dissolving pulp processors from qualified vendor lists. Feedstock security rests on concentrated dissolving wood pulp supply from Austria, India, and China where integrated producers control cost structures. Carbon disulfide, sodium hydroxide, and sulfuric acid dependencies expose non-integrated spinners to chemical price volatility. Single-source vulnerability concentrates in Austrian biorefinery output for European specialty grades. Distribution runs through mill-direct contracts for industrial buyers and regional distributors serving fragmented textile spinners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dissolving wood pulp capacity expansion lags fiber demand growth across Asian manufacturing hubs, propping pricing power for backward-integrated producers with captive chemical recovery systems.
For Market Incumbents: Lock in multi-year supply agreements with automotive tire cord manufacturers before lyocell substitution accelerates in industrial segments. Expand closed-loop retrofit capacity in European facilities to capture CSRD-compliant procurement preference from fashion brands. Defensive consolidation around dissolving pulp assets in Scandinavia and the Baltic states protects margin stability against feedstock price spikes. For New Entrants and Emerging Players: EU Green Deal chemical regulations in Europe open a window for closed-loop technology licensors to capture retrofit demand from legacy carbon disulfide plants. India's underpenetrated technical textile sector in Maharashtra offers white-space expansion for high-tenacity grades currently imported from Southeast Asia. A certification-first go-to-market angle targeting Portuguese and Turkish spinners accelerates supply chain qualification. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated pulp-to-fiber operators in Central Java where environmental compliance costs are decommissioning small-scale competitors. Long-term viability hinges on biorefinery diversification beyond commodity viscose into lyocell and specialty cellulose derivatives. Watch for MEE enforcement intensity in Hebei and Shandong provinces as inflection indicator for Chinese supply consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive pulp supply at Grasim Industries' Madhya Pradesh complex insulates margin compression during feedstock spikes. |
| Closed-Loop Manufacturing Transition | Carbon disulfide recovery retrofits at Kelheim Fibres satisfy REACH emission limits for Rhine-Ruhr automotive supply chains. |
| Certification Program Expansion | CanopyStyle and FSC chain-of-custody documentation unlocks ZDHC-compliant procurement from Portuguese woven apparel mills. |
| Specialty Grade Capacity Addition | Antimicrobial and flame-retardant viscose output captures medical textile premiums from technical nonwoven manufacturers. |
| Joint Venture for Regional Supply | Integrated facilities in Fujian province position Sateri Holdings to serve Java garment export zones with scale economies. |
Study Parameters
Independent corroboration across plant managers at dissolving pulp facilities, procurement leads at European textile mills, and distribution channel partners in Southeast Asia underwrites the qualitative findings. Primary interviews with technical R&D directors at fiber producers, regulatory affairs specialists at chemical manufacturers, and sustainability officers at fashion brands combined with secondary validation from customs/trade data, SEC 10-K filings, and Cefic chemical industry reports. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical dissolving pulp price cycles and fiber demand elasticity patterns structured the projection horizon. Segmentation modeling spanned product grade tier, end-use industry, physical form, and regional production hub dimensions. CAGRs were derived from regression analysis against macro textile demand indicators and regulatory compliance cost trajectories. Forecast inputs incorporated carbon disulfide recovery technology adoption curves and lyocell substitution elasticity in premium apparel segments.
The model assumes a particular technology adoption path; alternative pathways for solvent-spun lyocell would alter the outlook if N-methylmorpholine-N-oxide process economics achieve parity with conventional viscose. Forecasts reflect assumptions regarding MEE enforcement consistency and EU Green Deal implementation pace. A model refresh is warranted upon material change in dissolving wood pulp capacity expansion timelines or lyocell brand licensing velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Artificial Muscle Fibers Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
High Performance Fibers for Defense Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Citrus Pulp Fiber Market
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Global Metal Fiber Market
Fibers
Ceramic Fiber Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Global Concrete Fiber Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Global Nylon Monofilament Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market