
 USA Automotive Smart Keys Market | 2026-2036
USA Automotive Smart Keys Market Size, Share, and Industry Trends Forecast 2026-2036
USA Automotive Smart Keys Market Analytics
Passive entry and passive start technology is tilting the smart key stack toward ultra-wideband and Bluetooth Low Energy architectures. Continental AG leverages its embedded software heritage to anchor premium OEM programs with integrated digital key platforms. Denso Corporation sustains manufacturing scale through its Tennessee operations, supplying transponder modules to Detroit Three assembly lines. ZF Friedrichshafen AG differentiates through mechatronic integration, bundling smart entry with chassis control electronics.
Automotive smart keys are wireless authentication devices that replace mechanical ignition and door entry through encrypted radio-frequency or near-field communication between a portable fob or smartphone and vehicle controller units, typically operating at frequencies between 125 kHz for low-frequency wake-up and 2.4 GHz for UWB distance-ranging with precision under 10 centimeters. Their primary purpose is to eliminate physical key insertion while enabling personalized cabin settings, immobilizer functions, and remote authorization transfers. Key fob systems still occupy the dominant share of installed base across passenger vehicles, though mobile applications represent the fastest-expanding segment as smartphone-native digital keys gain OEM certification. RFID technology leads in legacy fleet and commercial truck retrofit channels, while NFC and Bluetooth combinations are capturing new motorcycle and hire car service deployments where device-to-vehicle handoff speed determines user experience.
NHTSA vehicle cybersecurity guidelines and FCC Part 15 rules for unlicensed radio transmission jointly shape product certification timelines and spectrum allocation for smart key transmitters. EPA fuel economy tracking requirements indirectly influence smart key adoption, as passive start-stop integration with keyless systems supports idle-reduction strategies in light-duty trucks. Stakeholders must monitor state-level privacy legislation in California and Illinois that could restrict biometric key data retention, while evaluating how FMVSS electronic control unit standards will apply to over-the-air key provisioning systems.
Market Dynamics
Ultra-wideband localization is compressing the distance-ranging tolerance in passive entry systems from meters to centimeters, forcing incumbent radio-frequency suppliers to retool their transceiver architectures or cede position to semiconductor specialists with software-defined radio expertise.
Growth Catalysts
- NHTSA Cybersecurity Guidelines:Connected vehicle mandates for encrypted wireless handshakes are accelerating hardware security module integration into key fob and smartphone-based authentication stacks.
- Idle-Reduction Strategies:EPA fuel economy tracking requirements for light-duty trucks are bundling passive start-stop functionality with keyless ignition systems across Detroit Three powertrain lineups.
- California Privacy Legislation:Biometric data retention restrictions are pressuring OEMs to deploy edge-computed facial recognition for driver authentication rather than cloud-stored templates.
Market Restraints
- Lithium-Ion Cell Volatility:Key fob battery supply concentrates in East Asian chemical processing, exposing Detroit assembly schedules to cathode material price swings and ocean freight bottlenecks.
- Semiconductor Fab Concentration:Advanced UWB transceiver production clusters at TSMC and Samsung foundries, creating single-source vulnerability for Tier 1 smart key module suppliers.
- FCC Part 15 Spectrum Friction:Unlicensed 2.4 GHz congestion from Wi-Fi and Bluetooth devices degrades key fob reliability in dense urban RF environments, limiting passive entry range consistency.
Strategic Opportunities
- Texas EV Manufacturing Corridor:Austin and Dallas-Fort Worth battery plant construction is creating demand for smartphone-native digital key integration in domestic electric vehicle platforms.
- Illinois Biometric Privacy Act:Strict consent requirements for fingerprint and facial data are opening market space for decentralized, vehicle-stored credential architectures that eliminate cloud retention.
- Bluetooth-UWB Convergence:Hybrid ranging stacks combining 2.4 GHz BLE discovery with 6.5 GHz UWB precision are enabling tiered security models that authenticate at distance then verify proximity.
Industry Challenges
- Embedded Cryptography Talent Scarcity:Hardware security module design requires scarce expertise in side-channel attack mitigation, with Detroit engineering centers competing against fintech and defense contractors for the same labor pool.
- Over-the-Air Certification Complexity:FMVSS electronic control unit standards have not kept pace with cloud-based key provisioning architectures, creating regulatory uncertainty for remote credential transfer features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Automotive Smart Keys Market |
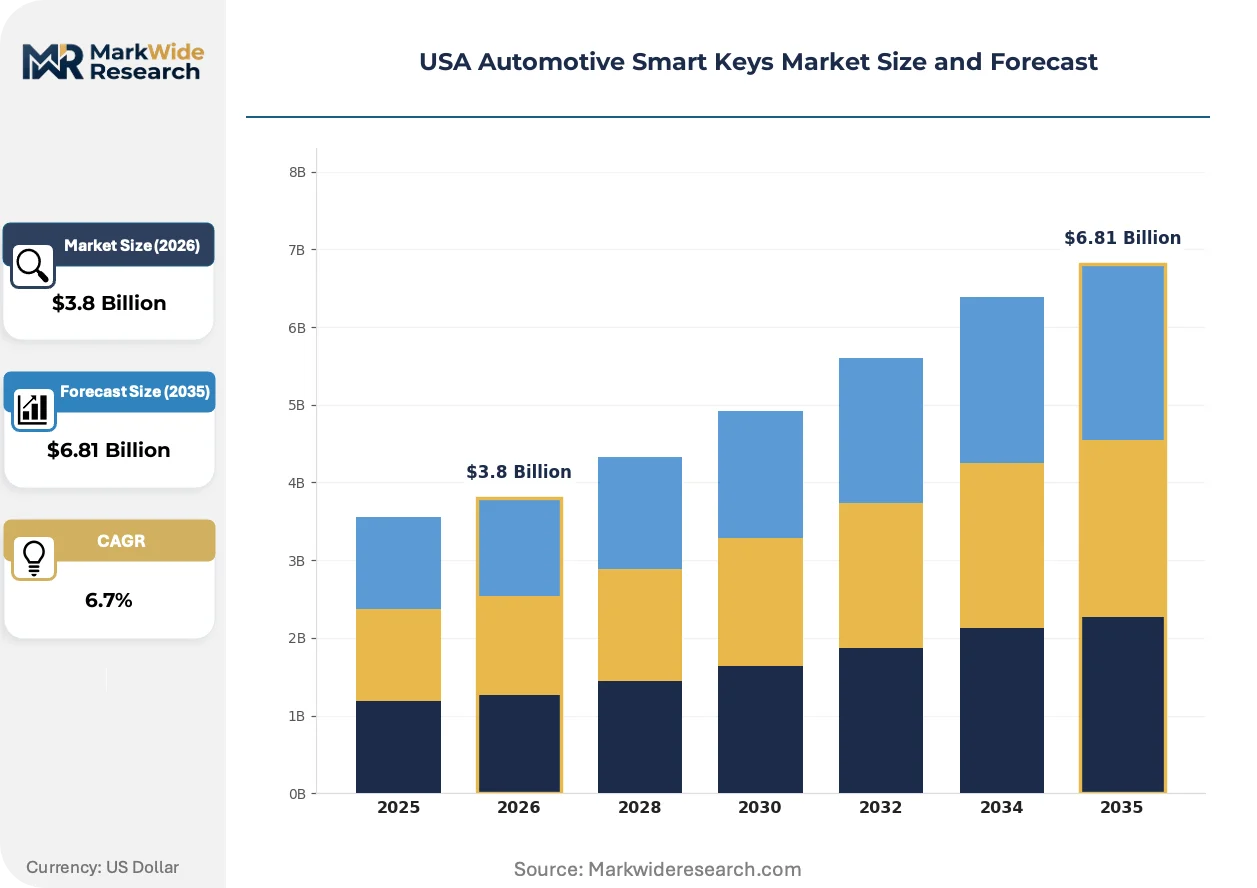
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
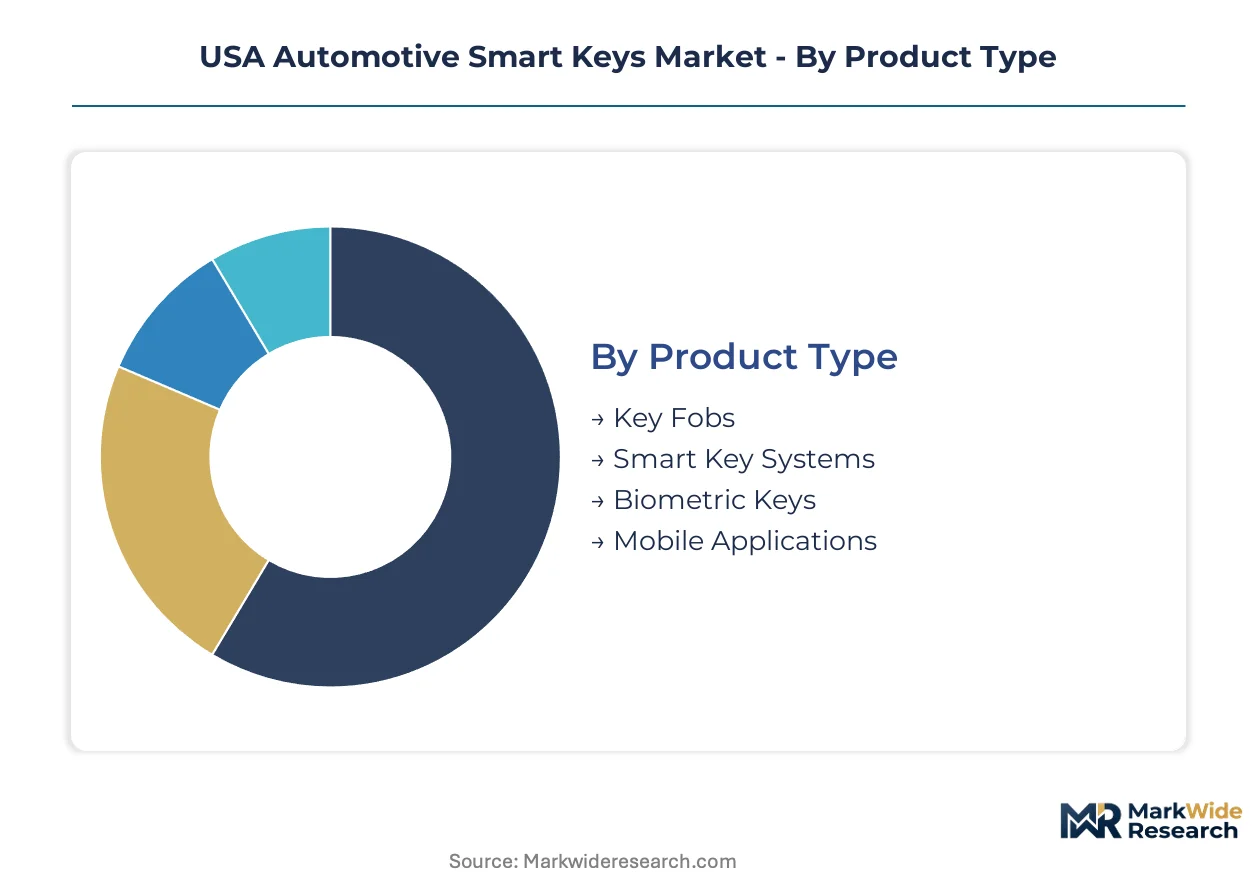
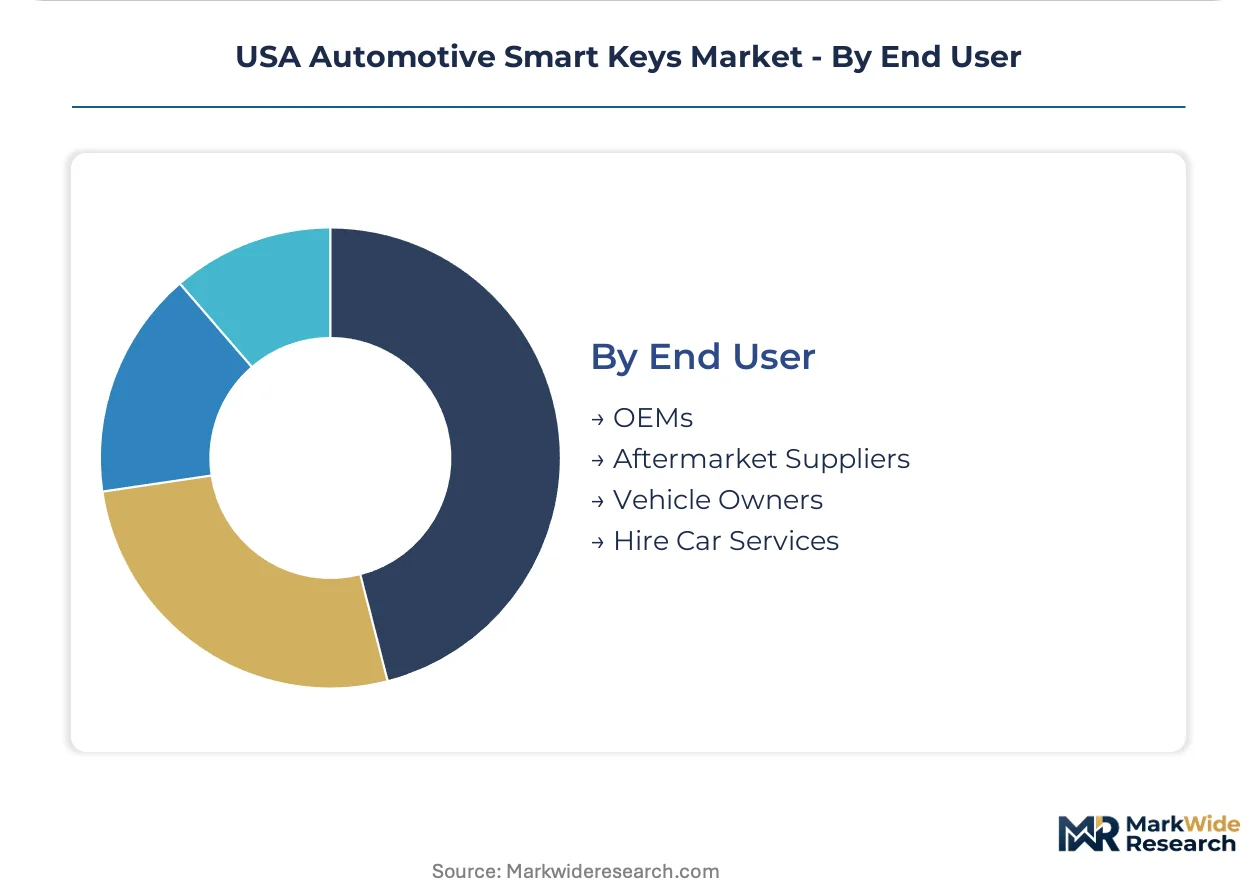
| Segmentation | Product Type: Key Fobs, Smart Key Systems, Biometric Keys, Mobile Applications Technology: RFID, Bluetooth, NFC, Infrared Application: Passenger Vehicles, Commercial Trucks, Motorcycles, Fleets End User: OEMs, Aftermarket Suppliers, Vehicle Owners, Hire Car Services |
| Companies Covered | Continental AG, Denso Corporation, ZF Friedrichshafen AG, Alpha Corporation, Valeo SA, Huf Hulsbeck & Furst GmbH & Co. KG, HELLA GmbH & Co. KGaA, Hyundai Mobis, Tokai Rika Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Automotive Smart Keys Market Evolving Landscape
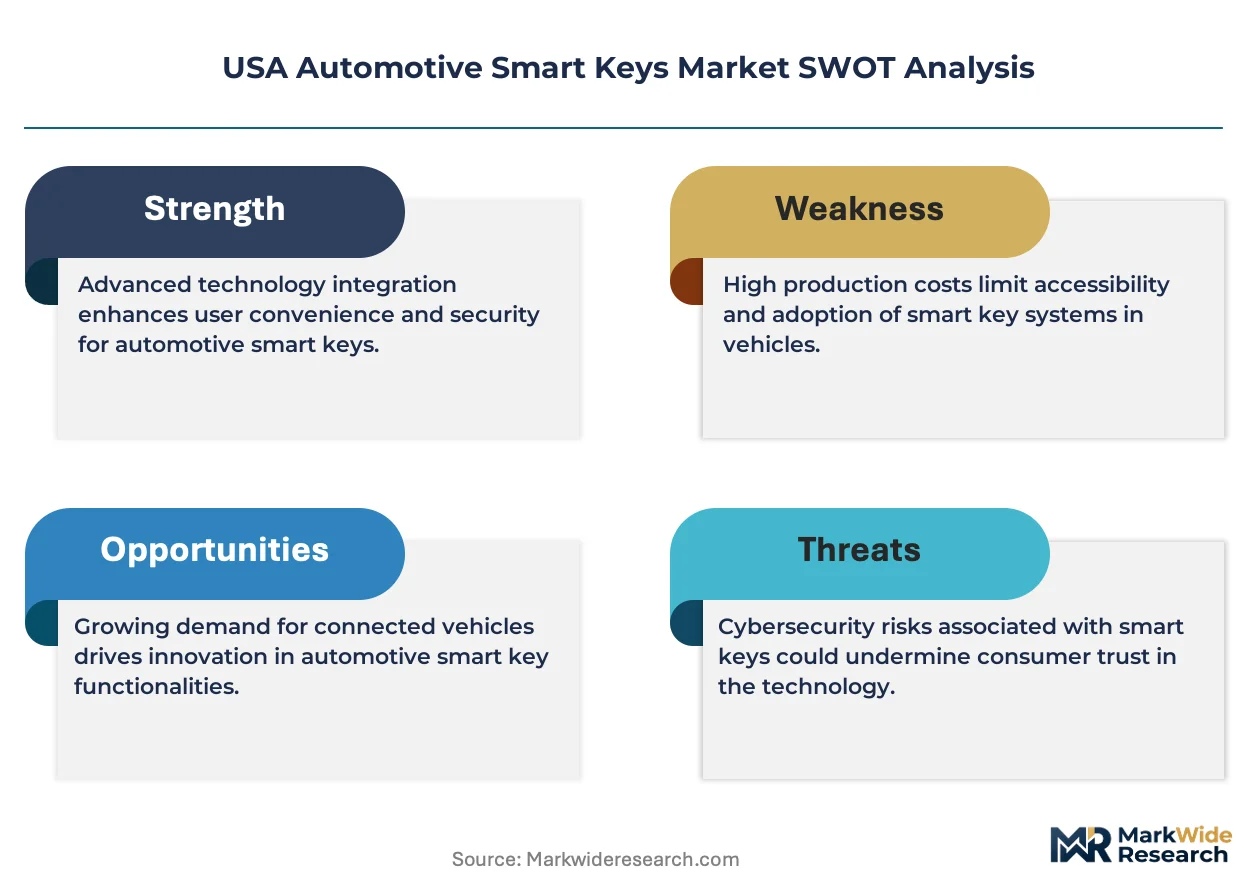
Authentication architectures are bifurcating between legacy transponder fobs and smartphone-native digital credentials, with the latter compressing hardware BOM costs while expanding software monetization surfaces for OEMs and mobility service operators.
Ultra-wideband distance-ranging is collapsing the spatial uncertainty that plagued earlier Bluetooth Low Energy passive entry systems. Luxury passenger vehicle OEMs are deploying UWB anchors at six or more vehicle touchpoints to enable centimeter-precise hands-free trunk access and cabin pre-conditioning activation. This precision is collapsing the competitive moat around mechanical backup keys, as digital authentication achieves functional parity with physical insertion for theft resistance.
NHTSA vehicle cybersecurity guidelines issued under the Infrastructure Investment and Jobs Act are mandating intrusion detection and secure boot capabilities for all wireless entry control modules. Tier 1 suppliers must now embed hardware security elements with FIPS 140-2 certification, adding six to nine months to product validation cycles. Michigan-based engineering centers are responding by co-locating penetration testing labs with RF anechoic chambers to compress certification timelines.
Fleet operators and car-sharing platforms are unbundling traditional key fob procurement from vehicle acquisition, instead licensing smartphone-based credential access as a recurring service. Turo, Zipcar, and corporate fleet managers are demanding API-first key provisioning that integrates with existing reservation and telematics stacks. This shift is most visible in California's electric vehicle design ecosystem, where native digital key support has become a non-negotiable procurement criterion for startup mobility services.
USA Automotive Smart Keys Market Segmentation
Smart key architectures fragment across hardware form factors, wireless protocols, vehicle platforms, and procurement channels. Each segmentation axis reveals distinct margin structures, certification burdens, and competitive dynamics that shape supplier positioning.
Product Type:
Use cases span legacy transponder hardware through smartphone-native credentials, with cost tiers separating mass-market fobs from biometric-enabled premium systems.
- Key Fobs:Battery-powered transponder units operating at 125 kHz low-frequency wake-up and 433 MHz ultra-high-frequency response. Demand concentrates in Detroit Three full-size truck lineups where passive entry penetration exceeds luxury car adoption rates. NHTSA cybersecurity guidelines are extending hardware security module integration timelines for new fob programs.
- Mobile Applications:Smartphone-native digital credentials leveraging BLE and UWB chipsets already resident in consumer devices. California electric vehicle startups and Austin-based battery plant operators are mandating phone-as-key capability as a fleet procurement standard, compressing hardware BOM costs while expanding software monetization surfaces.
- Smart Key Systems:Integrated transceiver modules combining fob reception, immobilizer logic, and cabin controller communication in single ECU packages.
- Biometric Keys:Fingerprint or facial recognition sensors embedded in door handles or steering columns for driver-specific authentication.
The dominant share belongs to Key Fobs, while Mobile Applications is closing the gap fastest.
Technology:
Wireless protocol selection determines ranging precision, power consumption, and vulnerability surface for relay attacks.
- Bluetooth:BLE 5.0 and 5.3 stacks dominate smartphone-to-vehicle discovery phases, with 2.4 GHz unlicensed operation enabling global SKU rationalization. FCC Part 15 congestion in dense urban RF environments degrades reliability, pushing Tier 1 suppliers toward hybrid BLE-UWB architectures.
- RFID:Legacy 125 kHz passive transponder technology persists in commercial truck retrofit channels and motorcycle immobilizer applications where cost sensitivity overrides precision requirements.
- NFC:13.56 MHz near-field protocols enable smartphone tap-to-unlock functionality with sub-10 centimeter intentional range that eliminates relay attack vectors.
- Infrared:Directional line-of-sight transmission for remote climate preconditioning and panic alarm activation in legacy Asian import platforms.
Bluetooth anchors the installed base, though NFC is gaining share fastest in hire car service deployments.
Application:
Vehicle platform characteristics dictate authentication range requirements, environmental sealing grades, and fleet management integration depth.
- Passenger Vehicles:Luxury OEM lineups deploy six-anchor UWB configurations enabling centimeter-precise hands-free trunk access. Michigan engineering corridors concentrate development activity for Detroit Three programs bundling passive start-stop with keyless ignition.
- Fleets:Corporate and mobility service operators demand API-first credential provisioning that unbundles key access from vehicle acquisition. Turo and Zipcar procurement specifications in California require over-the-air key transfer capabilities.
- Commercial Trucks:Light-duty segments adopt passenger-car architectures; heavy-duty applications prioritize immobilizer durability over convenience features.
- Motorcycles:Compact form factors and exposure to vibration and moisture drive simplified RFID or NFC-only solutions.
Passenger Vehicles command the dominant share, while Fleets is expanding most quickly as mobility-as-a-service procurement matures.
End User:
Procurement authority and volume concentration separate factory-installed programs from aftermarket retrofit and consumer direct channels.
- OEMs:Original equipment manufacturers specify transponder modules at platform development onset, locking suppliers into 5-7 year program lifecycles. Tennessee-based manufacturing scale and Michigan engineering proximity determine competitive positioning for Detroit Three allocations.
- Aftermarket Suppliers:Independent distributors serve legacy fleet retrofit and consumer replacement demand through retail auto parts channels.
- Vehicle Owners:Direct consumer procurement of replacement fobs and smartphone app subscriptions.
- Hire Car Services:Turo, Zipcar, and corporate fleet managers license credential access as recurring service rather than capital purchase.
OEMs retain the dominant share, though Hire Car Services is climbing the fastest as shared mobility procurement models displace traditional ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German smart key module exports flow predominantly into Michigan assembly plants and California EV design centers, establishing a transatlantic trade corridor that concentrates premium authentication hardware procurement within the USA automotive engineering ecosystem.
Michigan
Detroit Three full-size truck lineups drive passive entry penetration rates exceeding luxury sedan adoption, with Dearborn and Warren engineering corridors hosting NHTSA cybersecurity validation labs. The state's automotive supplier density anchors hardware security module integration programs for encrypted wireless handshakes. Tier 1 manufacturing facilities in Troy and Auburn Hills concentrate transponder module assembly for domestic OEM platform allocations.
California
Electric vehicle startups and mobility service operators mandate smartphone-native digital key capability as fleet procurement standard, with Silicon Valley software teams developing API-first credential provisioning systems. State privacy legislation restricts biometric data retention, pushing OEMs toward edge-computed facial recognition architectures. Los Angeles and San Francisco design studios concentrate user experience development for hands-free trunk access and cabin pre-conditioning activation.
Texas
Austin and Dallas-Fort Worth battery plant construction generates demand for UWB-anchored authentication in domestic EV platforms, with Gigafactory-adjacent suppliers establishing regional distribution nodes. The state's right-to-work manufacturing environment attracts semiconductor packaging operations for BLE transceiver modules. Houston logistics hubs handle cathode material shipments for key fob battery supply chains.
Tennessee
Denso's Maryville operations sustain transponder module manufacturing scale for Detroit Three assembly schedules, with Knoxville-area suppliers supporting just-in-time delivery protocols. The state's automotive corridor benefits from proximity to southeastern OEM assembly plants and East Coast port access. Memphis distribution centers manage aftermarket replacement fob inventory for retail auto parts channels.
Illinois
Chicago corporate fleet operators drive demand for over-the-air key transfer capabilities in mobility-as-a-service procurement, with the state's Biometric Privacy Act shaping decentralized credential architecture development. Rockford engineering firms specialize in RFID retrofit solutions for commercial truck immobilizer applications. Peoria-area suppliers serve legacy agricultural equipment channels requiring simplified authentication hardware.
USA Automotive Smart Keys Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven module suppliers anchor Detroit Three programs while mechatronic integrators bundle smart entry with chassis electronics. The vendor base separates into three strategic archetypes: embedded software heritage firms, manufacturing scale operators, and precision-ranging semiconductor specialists. Competitive dynamics center on hardware security module certification timelines and UWB transceiver architecture retooling. M&A activity targets penetration testing capabilities and RF anechoic chamber assets.
Within the embedded software tier, Continental AG and Denso Corporation exemplify divergent geographic anchoring strategies for North American OEM access. ZF Friedrichshafen AG occupies a position bridging mechatronic integration and chassis control electronics bundling. These three German and Japanese entities represent the dominant competitive anchors shaping supplier qualification protocols and program lifecycle commitments across Michigan and Tennessee manufacturing corridors.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Alpha Corporation |
| Valeo SA |
| Huf Hulsbeck & Furst GmbH & Co. KG |
| HELLA GmbH & Co. KGaA |
| Hyundai Mobis |
| Tokai Rika Co. Ltd |
| Others |
Value Network & Pricing Analysis
Single-source semiconductor fab concentration at TSMC and Samsung foundries compresses margin buffers across hardware tiers while amplifying price volatility for UWB transceiver modules. This dependency structure forces Tier 1 suppliers to absorb cost spikes in premium digital key programs or cede share to vertically integrated competitors with captive silicon supply.
Pricing Analysis
Next-generation UWB-BLE hybrid architectures command substantial premiums over legacy 433 MHz transponder fobs, while prior-generation RFID modules face accelerating price erosion in commercial truck retrofit channels. Three-tier pricing structure across premium, standard, and economy levels separates biometric-enabled OEM programs from mass-market passive entry bundles and aftermarket replacement units. Cost compression in economy tiers is intensifying because cathode material volatility in East Asian battery supply chains feeds through to key fob BOM costs. Fleet operators and hire car services exhibit highest price sensitivity due to volume procurement leverage, while luxury passenger vehicle OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Tariff exposure between China and the USA dominates sourcing decisions for lithium-ion cell components and BLE transceiver packaging operations. Advanced UWB chip fabrication concentrates in Taiwan and South Korea, while cathode material processing clusters in China and Japan. Raw material dependencies span lithium carbonate, cobalt sulfate, and rare-earth magnets for immobilizer transponders. Single-source vulnerability for 6.5 GHz UWB transceivers creates supply chain risk that Tier 1 suppliers mitigate through dual-qualification programs. Distribution runs through Michigan engineering corridors for Detroit Three OEM allocation, California EV design centers for startup platform integration, and Tennessee just-in-time hubs for southeastern assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA cybersecurity mandates under the Infrastructure Investment and Jobs Act accelerate hardware security module adoption, compressing supplier certification timelines and reshaping competitive moats around encrypted wireless authentication.
For Market Incumbents: Pre-empt smartphone-native digital key displacement by accelerating backward integration into UWB transceiver silicon and co-locating penetration testing labs with RF anechoic chambers in Michigan engineering corridors. Defensive consolidation around hardware security module certification capabilities protects against semiconductor specialists encroaching on premium OEM programs. Priority investment in Tennessee and Texas manufacturing scale secures Detroit Three and domestic EV platform allocations against Asian module suppliers. For New Entrants and Emerging Players: Establish a beachhead in Illinois corporate fleet procurement, where the Biometric Privacy Act creates demand for decentralized, vehicle-stored credential architectures that eliminate cloud retention. Target hire car service white space in California and Texas, where API-first key provisioning remains underdeveloped among regional mobility operators. Go-to-market leverage rests on software-defined radio expertise that compresses UWB distance-ranging tolerance below incumbent radio-frequency architectures. For Investors and Strategic Acquirers: NHTSA cybersecurity guideline implementation reshapes the acquisition landscape toward penetration testing capabilities and RF anechoic chamber assets. Long-term viability over the projection horizon favors suppliers with embedded software heritage and FIPS 140-2 certification track records. Acquisition target archetype: mid-cap specialists with UWB anchor integration programs and existing Detroit Three supplier qualifications. Signal to monitor: FMVSS electronic control unit standard updates for over-the-air key provisioning architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Certification Investment | FIPS 140-2 validation accelerates NHTSA cybersecurity guideline compliance timelines for Tier 1 suppliers. |
| UWB Transceiver Architecture Retooling | Software-defined radio expertise displaces legacy radio-frequency suppliers in premium OEM passive entry programs. |
| Penetration Testing Lab Co-location | Michigan-based RF anechoic chamber assets compress product validation cycles for encrypted wireless handshake modules. |
| Smartphone-Native Digital Key Platform Development | API-first credential provisioning captures California EV startup and Texas battery plant procurement specifications. |
| Decentralized Biometric Credential Architecture | Edge-computed facial recognition addresses Illinois Biometric Privacy Act restrictions on cloud-stored templates. |
Research Methodology
The analysis maps key fob hardware, mobile application credentials, UWB transceiver modules, and biometric authentication systems, each validated through Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distribution managers, and fleet operations directors. Primary interviews with stakeholders combined with secondary validation against NHTSA cybersecurity guideline filings, FCC Part 15 equipment authorization databases, vehicle production registries, and SEC supplier disclosure filings. Bottom-up segment sizing triangulated against top-down OEM platform allocation estimates.
Assumptions held fixed include NHTSA guideline implementation timelines, FCC spectrum allocation for unlicensed 2.4 GHz operation, and EPA fuel economy tracking requirements for light-duty trucks. Variables modeled across the analysis window encompass technology substitution rates between transponder fobs and smartphone-native credentials, UWB anchor adoption curves by vehicle class, and regional procurement concentration in Michigan, California, and Texas. CAGRs derived from segment-level volume projections weighted by content-per-vehicle estimates and OEM platform lifecycle commitments. Industry-specific inputs span hardware security module integration rates and BLE-UWB hybrid architecture penetration.
Sensitivities concentrate around semiconductor fab capacity allocation for advanced UWB transceivers, lithium-ion cell supply disruptions, and FMVSS standard updates for over-the-air key provisioning. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology substitution elasticities. Macroeconomic contraction, tariff escalation, or breakthrough relay attack mitigation technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market