
 South America Electric Bus Battery Pack Market | 2026-2036
South America Electric Bus Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Bus Battery Pack Market Insights
Battery-as-a-service subscription models for electric bus fleets is repositioning capital deployment across South American transit authorities. BYD Company Ltd leverages its integrated cell-to-vehicle manufacturing footprint to anchor pricing power in Chile and Colombia. CATL sustains aggressive LFP supply expansion through dedicated regional distribution hubs. LG Energy Solution competes on high-nickel chemistry portfolios tailored to longer-range intercity bus configurations.
A South America electric bus battery pack is a modular electrochemical energy storage system, typically comprising lithium iron phosphate or nickel manganese cobalt cells arranged in series-parallel configurations with integrated battery management systems, thermal regulation circuits, and high-voltage junction boxes rated for 400-800 VDC bus architectures. These assemblies store grid-delivered or regenerative braking energy to power permanent magnet synchronous traction motors, eliminating tailpipe emissions from public transit operations. LFP chemistry dominates procurement volumes due to superior thermal stability and extended cycle life under high-utilization fleet duty cycles, while NMC variants occupy premium positioning for operators prioritizing gravimetric energy density on extended routes. Fast charging infrastructure deployment outpaces alternative methods in Brazilian and Chilean urban centers, though opportunity charging systems are gaining traction for depot-light operational models.
Brazil's PROCONVE P-8 standards and Chile's electromobility strategy under the Ministry of Energy mandate progressive fleet decarbonization timelines that directly condition municipal procurement specifications. ANVISA, Brazil's national health surveillance agency, imposes transport safety protocols for lithium-ion cell transit that shape packaging and logistics costs across the Andean supply corridor. Stakeholders must monitor how Argentina's evolving renewable energy auction mechanisms and potential local content requirements will reshape cell import economics and regional assembly investment decisions.
Market Dynamics
Battery-as-a-service subscription models are restructuring capital deployment across South American transit authorities, converting upfront pack purchases into operational expenditures and accelerating fleet electrification timelines.
Growth Catalysts
- PROCONVE P-8 emission standards:Brazil's federal mandate for progressive fleet decarbonization is conditioning municipal procurement specifications toward zero-emission powertrains.
- LFP chemistry thermal stability:Lithium iron phosphate cell architectures deliver superior cycle life under high-utilization depot charging cycles prevalent in Andean fleet operations.
- São Paulo metropolitan corridor:Concentrated demand from Brazil's southeastern industrial hub is attracting regional cell-to-pack assembly investments.
Market Restraints
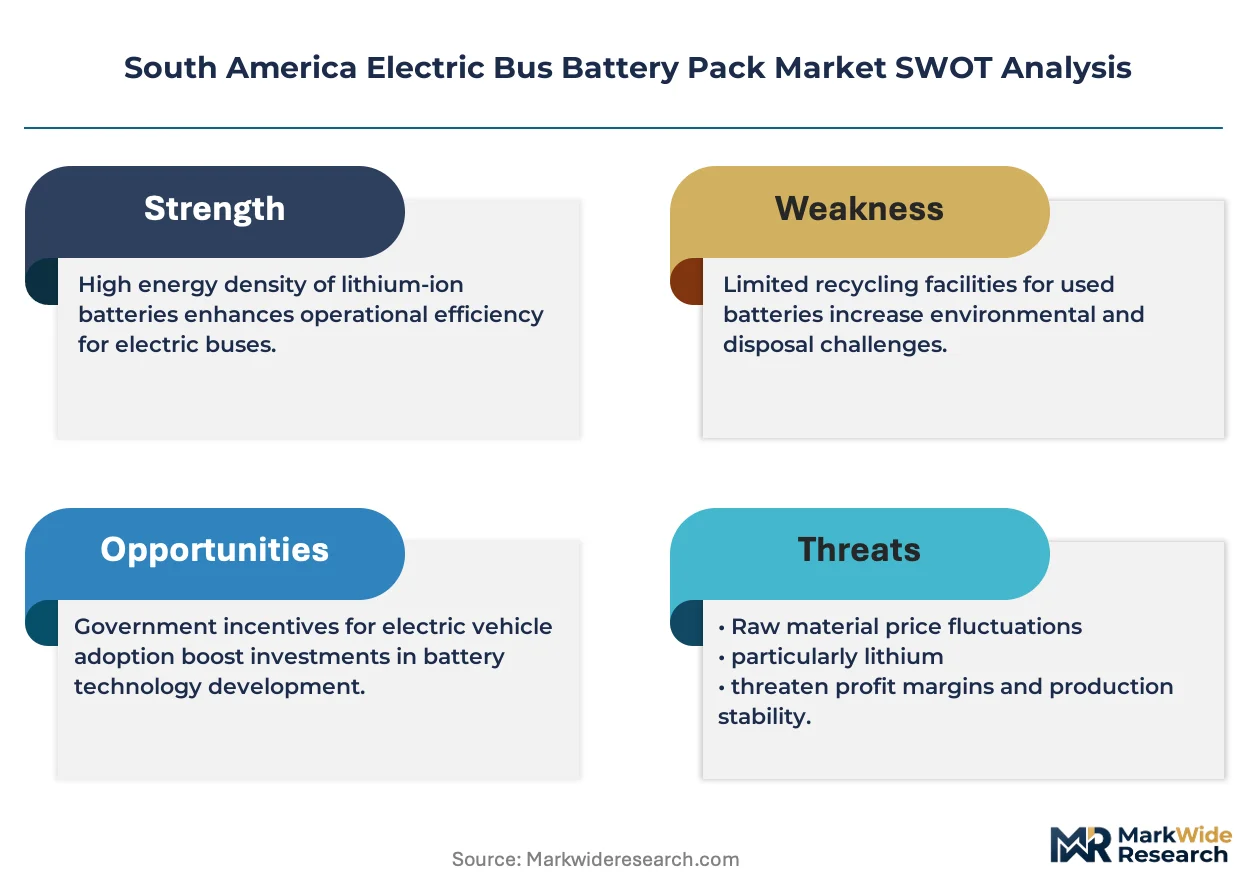
- Lithium carbonate price volatility:Input cost swings for cathode precursor materials compress pack assembler margins and destabilize long-term service contract pricing.
- Cell import concentration:Dependence on Asian cell suppliers exposes South American pack integrators to shipping cost spikes and customs clearance bottlenecks.
- ANVISA transport protocols:Brazil's lithium-ion cell transit safety requirements impose specialized packaging and logistics cost premiums across the Andean supply corridor.
Strategic Opportunities
- Argentina renewable auction mechanisms:Evolving power purchase agreement structures may enable behind-the-meter charging infrastructure co-location with provincial bus depots.
- Opportunity charging systems:Pantograph-based fast charging at route terminals reduces battery capacity requirements and total cost of ownership for intercity operators.
- Colombia local content incentives:Battery assembly tax credits are stimulating regional pack manufacturing joint ventures with municipal fleet operators.
Industry Challenges
- High-voltage technician scarcity:Qualified workforce for 800 VDC pack maintenance remains concentrated in São Paulo and Santiago, constraining fleet expansion into secondary cities.
- Thermal management integration complexity:Legacy bus chassis retrofits require extensive cooling loop reengineering to accommodate liquid-cooled LFP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Bus Battery Pack Market |
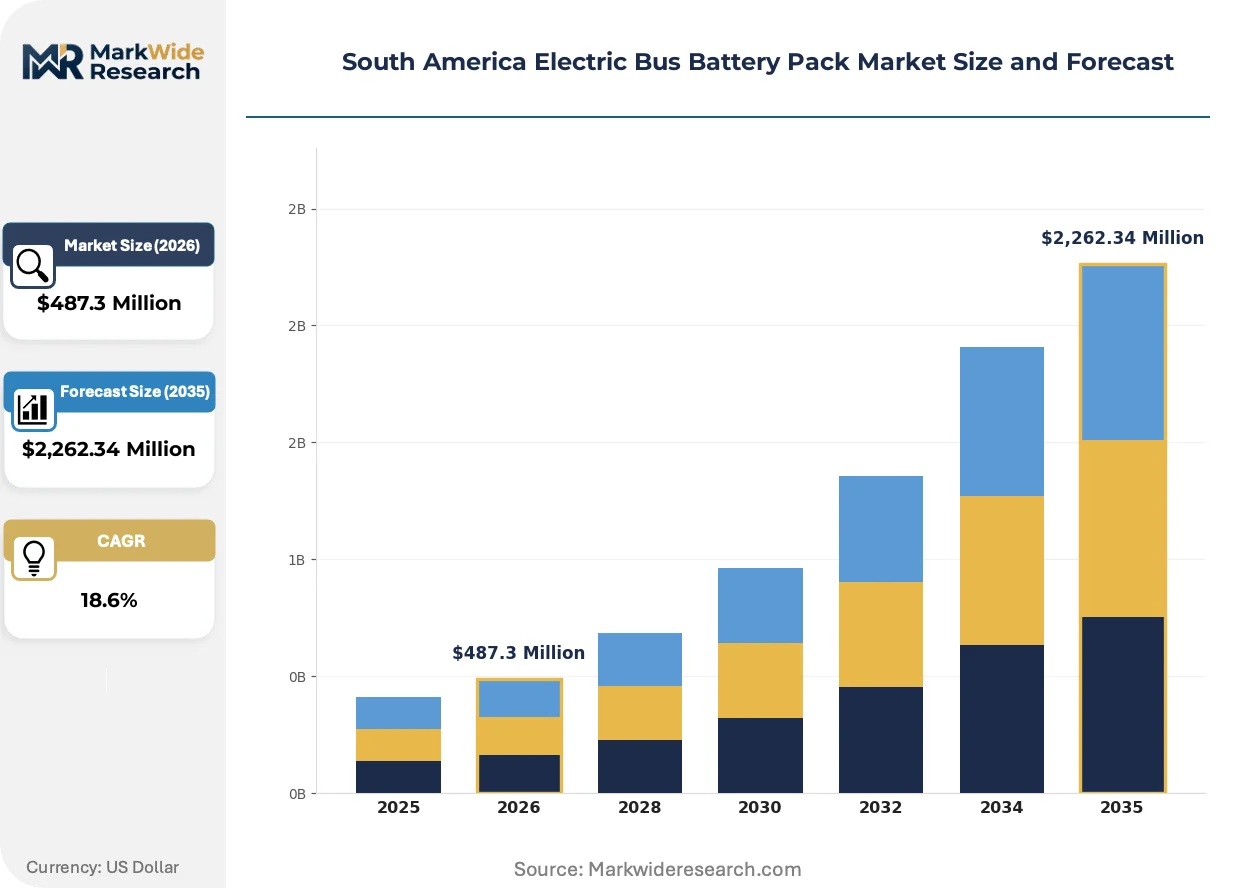
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: LFP, NMC, NCA, LTO End User: Public Transport, Private Operators, School Buses, Transit Agencies Power Capacity: 150 kWh, 200 kWh, 300 kWh, 400 kWh Charging Technology: Fast Charging, Slow Charging, Inductive Charging, Opportunity Charging |
| Companies Covered | BYD Company Ltd, Contemporary Amperex Technology Co Ltd (CATL), LG Energy Solution, Panasonic, China Aviation Battery Co Ltd (CALB), Farasis Energy (Ganzhou) Co Ltd, Gotion High-Tech Co Ltd, Guoxuan High-tech Co Ltd, BMZ Batterien-Montage-Zentrum GmbH, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Bus Battery Pack Market Trends and Innovations
Cell-to-pack architectures are eliminating module housings and busbars, compressing system weight and assembly cost while enabling direct thermal management contact with individual cells.
Modular battery swapping infrastructure is decentralizing depot charging investments across Chilean and Colombian transit networks. Mid-size municipal operators in Concepción and Medellín are piloting standardized pack exchange protocols to eliminate overnight charging capacity constraints. This topology reduces grid interconnection requirements and enables fleet scaling without substation upgrades.
Brazil's PROCONVE P-8 framework is mandating progressive emission reductions that effectively prohibit diesel bus procurement in metropolitan regions by 2028. The regulation is compressing manufacturer product development cycles and redirecting engineering resources from combustion platforms to electric powertrain integration. São Paulo's metropolitan transport authority has responded by accelerating tender specifications for 12-meter electric articulated buses with 350 kWh pack configurations.
Fleet operators are unbundling battery ownership from vehicle procurement, transferring residual value risk to specialized financiers and pack servicers. Chile's Ministry of Energy electromobility strategy has catalyzed this transition in Santiago's Transantiago system, where subscription-based pack contracts now dominate new fleet additions. The model shifts technical obsolescence risk away from cash-constrained municipal budgets.
South America Electric Bus Battery Pack Market Segmentation
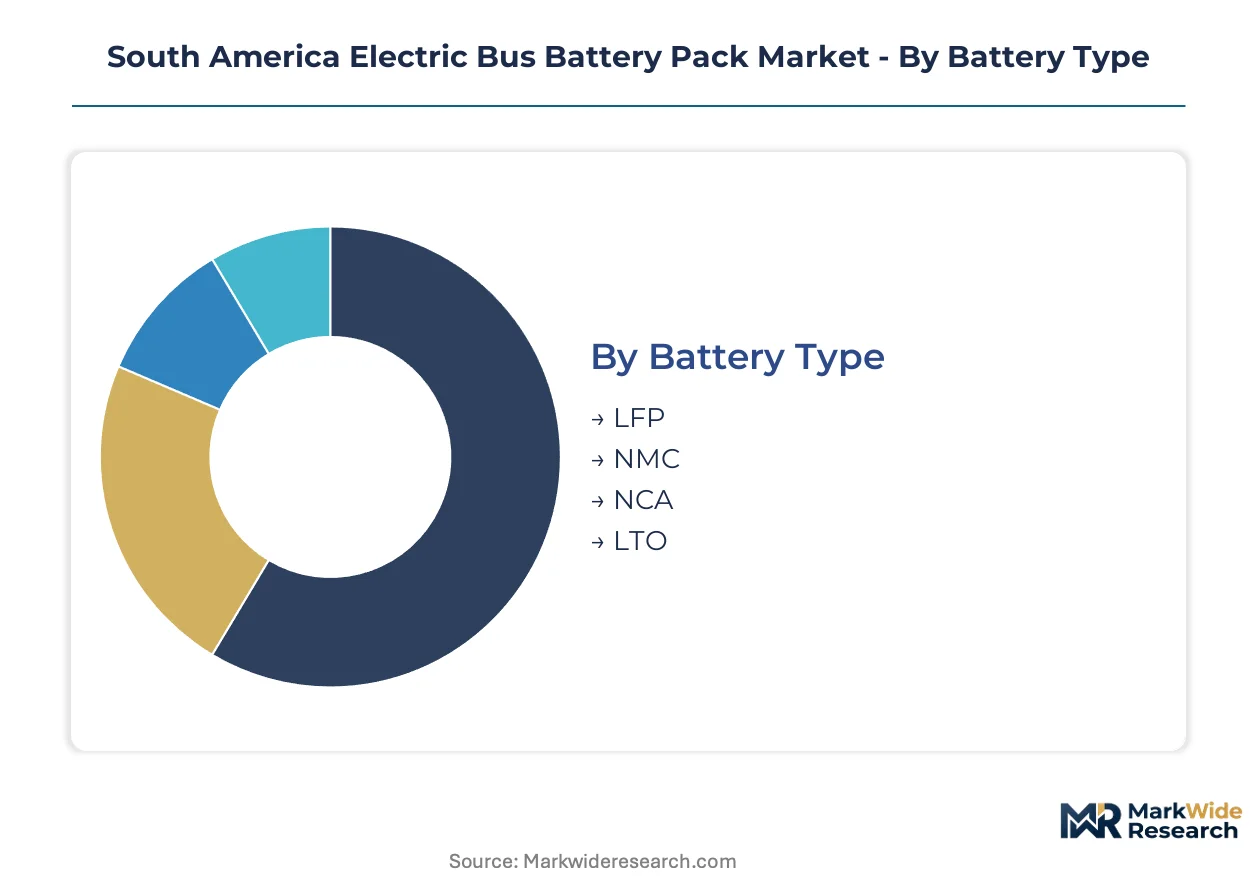
Battery chemistry selection and power capacity sizing determine fleet operational economics across South American transit networks. Procurement specifications in São Paulo and Santiago increasingly segment by duty cycle intensity and route length requirements.
Battery Type:
Upgrade cycles favor chemistries with extended calendar life and thermal tolerance under high-utilization depot charging regimes.
- LFP:Lithium iron phosphate cells deliver superior thermal stability and cycle longevity under continuous high-C-rate depot charging. São Paulo's metropolitan transport authority specifies LFP for 12-meter articulated buses with 350 kWh configurations, prioritizing safety margins over gravimetric density.
- NMC:Nickel manganese cobalt architectures achieve higher energy density for extended-range intercity routes. Colombian intercity operators in the Bogotá-Medellín corridor select NMC packs to minimize weight penalties on mountain-grade segments.
- NCA:Nickel cobalt aluminum formulations occupy niche positioning for premium rapid-transit applications demanding maximum range extension.
- LTO:Lithium titanate variants enable ultra-fast charging acceptance with minimal degradation, suited for opportunity charging topologies at route terminals.
Volume placements concentrate in LFP; the faster expansion belongs to NMC.
End User:
Procurement patterns diverge sharply between subsidized municipal fleets and self-financed commercial operators.
- Public Transport:State-subsidized metropolitan systems in Brazil and Chile dominate pack procurement volumes. PROCONVE P-8 mandates and Chile's Ministry of Energy electromobility strategy condition tender specifications toward zero-emission powertrains with standardized pack interfaces.
- Private Operators:Commercial intercity and airport shuttle fleets prioritize total cost of ownership metrics over upfront capital constraints. Battery-as-a-service subscriptions are penetrating this segment fastest.
- School Buses:Municipal education departments in Argentina and Colombia are piloting electrified fleet conversions with smaller 150-200 kWh pack configurations.
- Transit Agencies:Regional coordinating bodies aggregate procurement across multiple municipalities to achieve volume pricing on standardized pack architectures.
Public transport commands current volume leadership; private operators are climbing the fastest as financing models mature.
Power Capacity:
Route length and charging infrastructure availability dictate optimal pack sizing across Andean topography.
- 300 kWh:Mid-range configurations balance capital cost against operational flexibility for mixed urban-suburban routes. Brazilian southeastern industrial corridor operators standardize on this capacity for 12-meter single-deck buses with overnight depot charging.
- 400 kWh:Maximum-capacity packs enable all-day operation without opportunity charging on extended intercity segments. Chilean operators deploy these for Santiago-Concepción corridor services.
- 150 kWh:Compact packs serve short-loop circulator routes with midday opportunity charging.
- 200 kWh:Entry-level capacity for school bus and airport shuttle applications with predictable low-mileage duty cycles.
300 kWh placements dominate current tenders; 400 kWh configurations are gaining share fastest as intercity electrification accelerates.
Charging Technology:
Infrastructure investment decisions lock in pack thermal management and cycle life assumptions for fleet planning horizons.
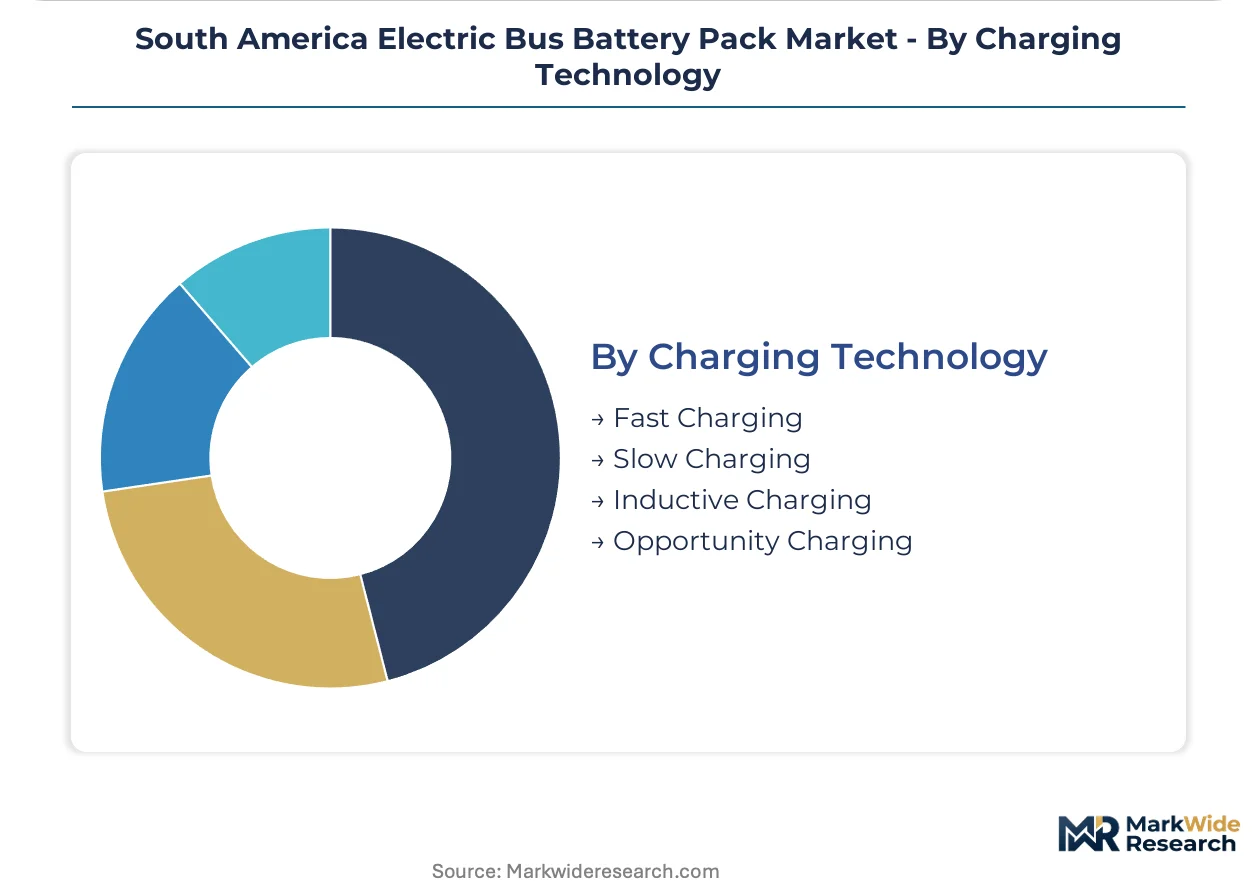
- Fast Charging:DC rapid infrastructure at depot facilities enables high-C-rate replenishment overnight. Brazilian urban centers are deploying 150 kW+ chargers to compress fleet downtime.
- Opportunity Charging:Pantograph-based systems at route terminals reduce required pack capacity and vehicle weight. Medellín's pilot program with standardized exchange protocols eliminates overnight charging constraints.
- Slow Charging:AC overnight depot charging remains prevalent for smaller municipal operators with extended dwell periods.
- Inductive Charging:Wireless pad systems at bus stops enable continuous opportunity charging without mechanical connector wear.
Fast charging infrastructure commands current investment; opportunity charging systems are expanding most quickly as grid interconnection constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's southeastern industrial corridor anchors South American electric bus battery pack demand, concentrating assembly investments and fleet procurement authority in Brazil's most populous metropolitan region.
Brazil
São Paulo's metropolitan transport authority drives procurement volumes for 12-meter articulated buses with 350 kWh LFP configurations. ANVISA transport safety protocols for lithium-ion cell transit impose specialized packaging requirements across the Andean supply corridor. Regional cell-to-pack assembly investments cluster in the southeastern industrial corridor surrounding São Paulo and adjacent Minas Gerais manufacturing zones.
Chile
Santiago's Transantiago system dominates municipal fleet electrification through subscription-based battery-as-a-service contracts. The Ministry of Energy electromobility strategy mandates progressive fleet decarbonization timelines that condition tender specifications. Concepción pilots modular battery swapping infrastructure with standardized pack exchange protocols to eliminate overnight charging constraints.
Colombia
Bogotá-Medellín corridor operators select NMC packs to minimize weight penalties on mountain-grade intercity segments. Local content incentives for battery assembly stimulate regional pack manufacturing joint ventures with municipal fleet operators. Medellín's opportunity charging pilot deploys pantograph-based systems at route terminals with standardized exchange protocols.
Argentina
Municipal education departments in Buenos Aires and Córdoba pilot electrified school bus conversions with 150-200 kWh pack configurations. Evolving renewable energy auction mechanisms may enable behind-the-meter charging infrastructure co-location with provincial bus depots. Secondary city fleet expansion faces constraints from qualified high-voltage technician scarcity concentrated in Buenos Aires.
South America Electric Bus Battery Pack Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the South America electric bus battery pack market. The supplier base consolidates around integrated cell-to-vehicle manufacturers and dedicated pack assemblers serving regional transit authorities. Three strategic archetypes dominate: chemistry-specialized cell producers, vertically integrated vehicle OEMs with captive battery operations, and regional pack integrators leveraging local assembly incentives. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure positioning ahead of PROCONVE P-8 compliance deadlines.
Among Chinese cell producers, BYD Company Ltd and Contemporary Amperex Technology Co Ltd exemplify the chemistry-specialized archetype with dedicated regional distribution strategies. LG Energy Solution represents the Korean industrial conglomerate model competing on high-nickel chemistry portfolios. These three anchors sit within distinct strategic positions: integrated vehicle-to-cell control, aggressive LFP supply expansion, and premium chemistry differentiation for extended-range configurations.
| Leading Market Players |
|---|
| BYD Company Ltd |
| Contemporary Amperex Technology Co Ltd (CATL) |
| LG Energy Solution |
| Panasonic |
| China Aviation Battery Co Ltd (CALB) |
| Farasis Energy (Ganzhou) Co Ltd |
| Gotion High-Tech Co Ltd |
| Guoxuan High-tech Co Ltd |
| BMZ Batterien-Montage-Zentrum GmbH |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate cathode precursor costs cascade through South American pack assembler margins, compressing subscription contract pricing for municipal fleets in São Paulo while elevating landed costs for Colombian operators dependent on Andean corridor logistics.
Pricing Analysis
Throughput-linked battery-as-a-service subscriptions anchor pricing to fleet uptime guarantees rather than pack capacity, with PROCONVE P-8 compliance timelines driving municipal buyers toward premium-tier LFP configurations certified for 800 VDC architectures. Price differentiation rests on thermal management integration complexity and ANVISA-certified packaging protocols for lithium-ion cell transit. Cost compression in standard 300 kWh depot-charging configurations is intensifying because of Asian cell import competition, while private intercity operators exhibit lowest price sensitivity due to total cost of ownership modeling.
Supply Chain Analysis
ANVISA transport safety certification gates cell import eligibility for Brazilian pack integrators, filtering supplier pools to qualified logistics operators with specialized hazmat handling infrastructure. Cell supply concentrates in China, South Korea, and Japan, with cathode active material dependencies on Chilean lithium carbonate, Indonesian nickel, and Chinese graphite processing. Single-source vulnerability pervades the Andean corridor where customs clearance bottlenecks at Port of Santos compound shipping cost spikes. Distribution runs through regional pack assembly joint ventures in São Paulo's southeastern industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell import bottlenecks and qualified high-voltage technician scarcity prop pack pricing power, constraining fleet expansion timelines beyond Brazil's metropolitan core.
For Market Incumbents: Deploy captive LFP cell supply agreements to lock in cathode precursor allocation ahead of PROCONVE P-8 compliance deadlines. BYD and CATL's regional distribution hubs threaten pricing power for pack assemblers lacking backward integration into cell production. Incumbents should secure ANVISA-certified logistics partnerships to defend margin position against customs clearance disruption. For New Entrants and Emerging Players: Municipal education departments in Argentina's secondary cities represent the most penetrable segment, with 150-200 kWh school bus configurations underserved by existing suppliers. Battery swapping infrastructure pilots in Concepción and Medellín create white-space for modular pack exchange protocol specialists. A go-to-market angle through transit agency procurement aggregation bypasses direct OEM competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional pack integrators with ANVISA certification and existing São Paulo assembly footprint. Long-term viability hinges on local content incentive capture across Brazil and Colombia's evolving battery assembly tax credit regimes. The signal to watch is Argentina's renewable energy auction mechanism maturation enabling behind-the-meter depot charging co-location.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Assembly Investment | Eliminates module housings to compress system weight and thermal management cost for São Paulo fleet operators. |
| ANVISA Certification Acquisition | Unlocks lithium-ion cell import eligibility for Brazilian pack integrators competing for PROCONVE P-8 tenders. |
| Opportunity Charging Infrastructure | Pantograph deployment at Medellín route terminals reduces pack capacity requirements for intercity operators. |
| LFP Supply Agreement | Secures cathode precursor allocation from Chilean lithium carbonate producers amid input cost volatility. |
| Battery-as-a-Service Platform | Converts Santiago municipal fleet procurement from capital expenditure to operational subscription models. |
Research Methodology
Multi-period observation of fleet procurement schedules, cell import volumes, and charging infrastructure deployment anchored the trend analysis, supplemented by interviews with metropolitan transport authority procurement directors, pack assembly plant managers, ANVISA regulatory compliance officers, and lithium carbonate trading desk analysts. Secondary validation drew from Brazilian customs records, Chilean Ministry of Energy electromobility strategy documents, PROCONVE regulatory filings, and SEC disclosures by listed cell producers. Bottom-up fleet sizing estimates triangulated against top-down market value reconstruction.
An input-output matrix structured the analytical framework, mapping battery chemistry selection, power capacity tier, and charging topology against municipal versus private operator segmentation across the projection horizon. CAGRs were derived from fleet replacement cycle modeling under PROCONVE P-8 mandate timelines and Chilean decarbonization commitments. Industry-specific forecast inputs included lithium carbonate price scenario bands and grid interconnection capacity constraints at Brazilian urban depots.
Caveats apply where lithium carbonate price volatility, ANVISA protocol amendments, or Argentina's local content requirement evolution could materially shift the outlook. Forecasts reflect assumptions on cell import tariff stability and qualified technician training pipeline expansion. A model refresh is warranted upon material change in PROCONVE P-8 enforcement intensity or regional renewable auction mechanism maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle Battery Trays Market