
 Off-Road High Performance Vehicle Market | 2026-2036
Off-Road High Performance Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Road High Performance Vehicle Market Analysis
EPA Tier 4 and CARB off-road emission rules is pivoting engineering budgets toward cleaner combustion architectures and electrified powertrains. Polaris Inc. dominates North American UTV distribution through its RZR and Ranger platforms. Yamaha Motor Co., Ltd. leverages its motorcycle heritage to anchor dirt bike performance credibility across Asian and European trail networks. BRP Inc. competes aggressively in the recreational segment with Can-Am Maverick side-by-sides engineered for desert terrain.
Off-road high performance vehicles comprise engineered chassis systems with long-travel suspension, high-displacement or electrified powertrains, and four-wheel-drive architectures purpose-built for unimproved terrain, competitive racing, or specialized utility tasks requiring traverse capability beyond standard passenger vehicles. Manufacturing emphasizes welded tubular frames, forged aluminum suspension components, and sealed drivetrain assemblies rated for mud, sand, and rock impact loads. The UTV segment leads volume as ranchers, hunters, and recreational buyers replace traditional ATVs with cab-equipped, cargo-capable platforms. Electric fuel type variants represent the fastest-growing structural category as lithium-ion pack energy density improvements enable trail-range parity with gasoline counterparts. Racing market segment applications command premium pricing through purpose-built suspension systems and engine power configurations that exceed recreational specifications.
FCC equipment authorization governs two-way radio and GPS telemetry integrations in military and expedition vehicles. NHTSA rollover resistance investigations shape side-by-side roof and occupant restraint mandates. EPA off-road emission certification creates compliance cost barriers that favor manufacturers with captive engine development. ISO 6469 electric vehicle safety standards will govern emerging battery-electric ATV architectures as voltage platforms climb above 400V. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal accelerate zero-emission product line commitments without sacrificing the torque delivery characteristics that define off-road performance.
Market Dynamics
EPA Tier 4 emission standards and CARB off-road rules are compressing development timelines for combustion powertrains while accelerating electrified platform investments across manufacturer engineering budgets.
Growth Catalysts
- Ranch Utility Modernization:Cab-equipped UTVs replace legacy ATVs for livestock management and property maintenance tasks. Hunters and rural property owners drive replacement cycles toward cargo-capable side-by-sides.
- Dual Carbon Goals:China's national carbon neutrality targets push domestic manufacturers toward battery-electric architectures with torque parity to gasoline engines. State subsidies accelerate fleet electrification pilots.
- Lithium-Ion Energy Density:Pack-level improvements enable trail-range equivalence with internal combustion counterparts. Desert racing and expedition applications now validate electric platforms for extreme terrain.
Market Restraints
- EPA Certification Barriers:Off-road spark-ignition engine testing protocols create fixed compliance costs that disadvantage smaller manufacturers without captive engine development.
- Raw Material Concentration:Neodymium and lithium supply chains concentrate in processing facilities outside North American and European jurisdiction, exposing OEMs to export restriction risks.
- Range Anxiety in Remote Terrain:Charging infrastructure absence across Australian Outback and Middle Eastern desert operating environments limits electric platform penetration for expedition use cases.
Strategic Opportunities
- Middle Eastern Defense Procurement:Armored UTV platforms gain traction in Saudi and UAE military modernization programs. Local assembly requirements create partnership entry points for established suppliers.
- ISO 6469-3 Compliance:Emerging battery-electric ATV architectures above 400V require safety certification that first-movers can leverage as competitive moats against late entrants.
- Telemetry Integration:FCC equipment authorization for two-way radio and GPS systems enables subscription-based fleet management services for commercial ranch and rental operators.
Industry Challenges
- Welded Tubular Frame Fabrication:Specialized welding certifications for chromoly and aluminum chassis construction constrain qualified supplier capacity during demand surges.
- Sealed Drivetrain Validation:Mud and rock impact load testing protocols extend product development cycles by 8-14 months for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Road High Performance Vehicle Market |
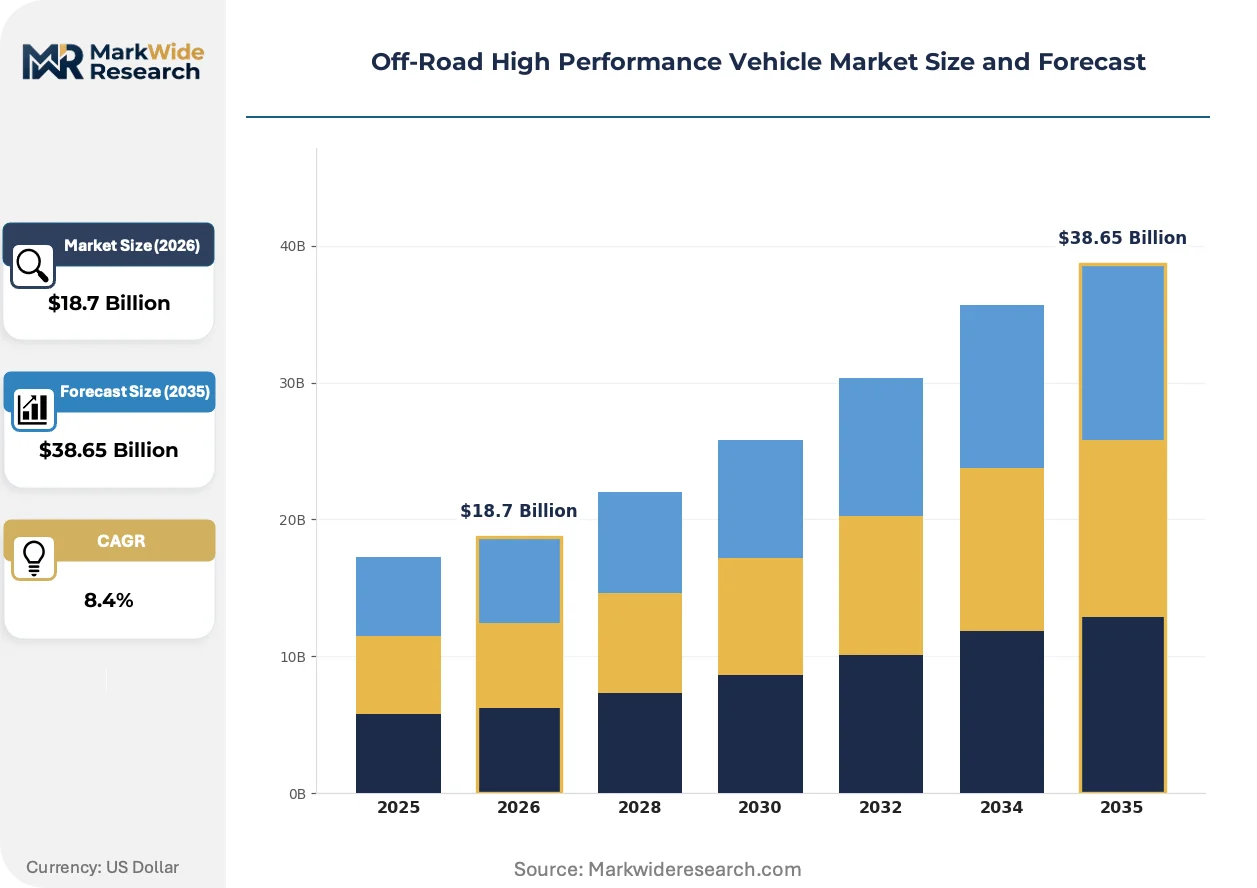
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, ATV, UTV, Dirt Bike Fuel Type: Gasoline, Diesel, Electric, Hybrid Performance Feature: Four-Wheel Drive, Suspension System, Traction Control, Engine Power Market Segment: Recreational, Racing, Utility, Military |
| Companies Covered | Polaris Inc., Yamaha Motor Co., Ltd., Honda Motor Co., Ltd., Bombardier Recreational Products Inc., Arctic Cat Inc., Kawasaki Heavy Industries, Ltd., Suzuki Motor Corporation, Textron Inc., BRP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Road High Performance Vehicle Market Emerging Trajectories
Electrification architectures and telemetry integration are compressing traditional hardware-centric business models toward software-enabled service platforms across recreational and commercial segments.
Active suspension calibration is automating terrain response through sensor-fused damping adjustment. Desert racing teams and high-end recreational buyers adopt these systems for real-time compression and rebound tuning. The technology is automating driver skill requirements while compressing lap time variance across amateur and professional operators.
EU Green Deal industrial policy mandates accelerate zero-emission product line commitments from manufacturers serving European trail networks. The regulation forces parallel powertrain development tracks that strain engineering resource allocation. Side-by-side and ATV categories face 2035 phase-out timelines for pure combustion offerings in Germany, France, and Benelux markets.
Ranch operators and commercial fleet buyers now specify total cost of ownership metrics over upfront acquisition price in procurement evaluations. Leasing and subscription models displace traditional dealer floorplan financing for vehicles above 50 horsepower. This shift concentrates most visibly in Texas, Arizona, and Australian cattle station operations where utilization rates exceed 1,200 annual hours.
Off-Road High Performance Vehicle Market Segmentation
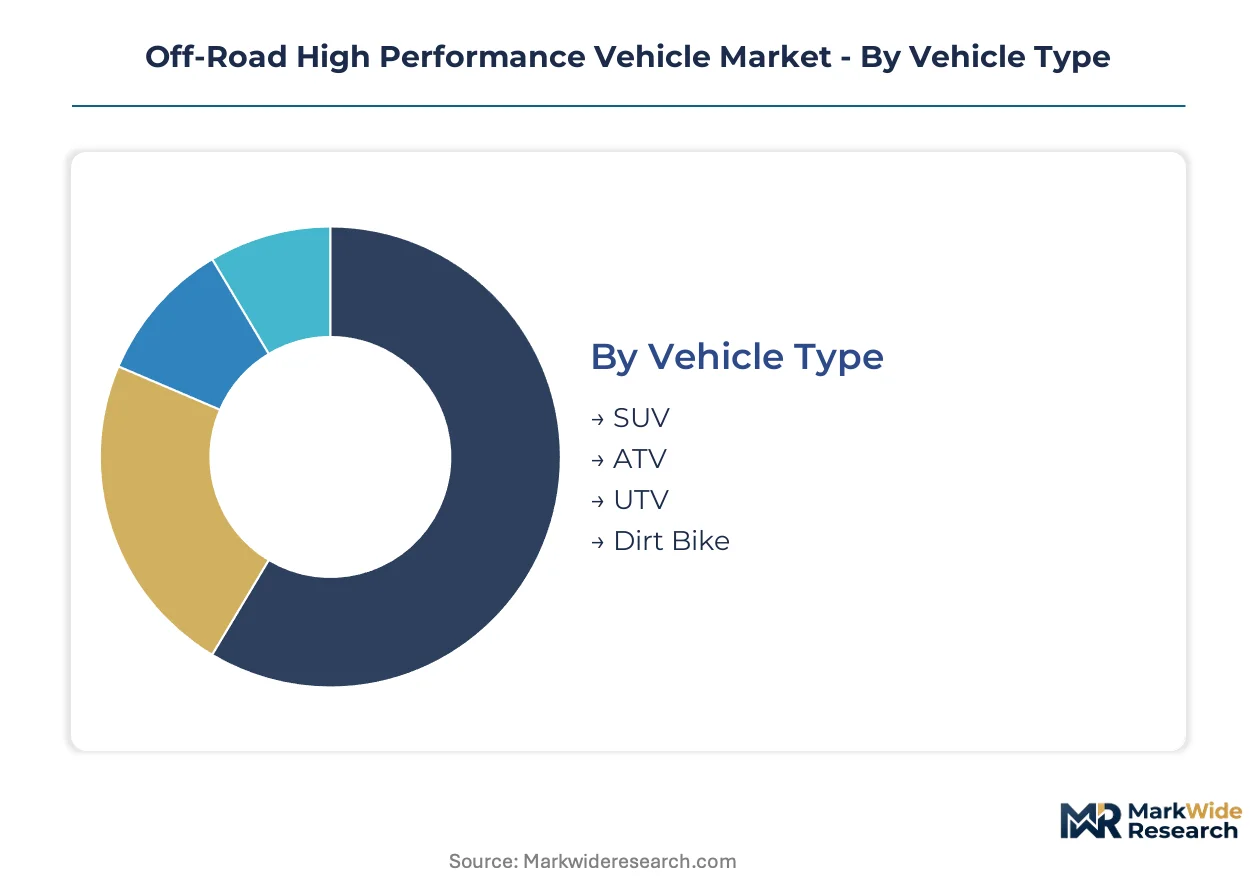
Segmentation in off-road high performance vehicles separates capital deployment strategies across divergent engineering requirements. Welded tubular frames for UTV platforms demand heavier tooling investments than motorcycle-derived dirt bike architectures. Electrification trajectories differ sharply by segment, with utility and military buyers prioritizing torque delivery over recreational buyers' range anxiety.
Vehicle Type:
UTV platforms absorb the highest upfront capital intensity due to cab structures, cargo systems, and four-wheel-drive architectures. ATV and dirt bike manufacturing leverage motorcycle-scale tooling with lower fixed asset thresholds.
- UTV:Side-by-side configurations with enclosed cabs and cargo beds dominate ranch utility and commercial fleet procurement. Australian cattle stations and Texas hunting operations drive replacement cycles toward these platforms for livestock management tasks. EPA Tier 4 compliance costs concentrate here due to higher displacement engines.
- SUV:Body-on-frame architectures with long-travel suspension systems serve expedition and overland applications. Middle Eastern defense procurement programs in Saudi Arabia and UAE specify armored variants for patrol and reconnaissance missions. Local assembly mandates create partnership requirements for foreign suppliers.
- ATV:Straddle-seat configurations retain presence in price-sensitive recreational segments and compact utility tasks. Yamaha Motor Co. anchors manufacturing scale through shared motorcycle powertrain platforms.
- Dirt Bike:Lightweight competition machines prioritize power-to-weight ratios over durability engineering. Asian trail networks and European enduro circuits sustain volume for two-stroke and four-stroke competition models.
Most installed capacity flows through UTV. Expansion is steepest in SUV for defense applications.
Fuel Type:
Powertrain selection determines regulatory exposure and supply chain concentration across manufacturing footprints. Electric architectures require battery cell procurement strategies that gasoline platforms avoid entirely.
- Electric:Lithium-ion pack configurations above 400V enable trail-range parity with gasoline counterparts for the first time. ISO 6469-3 safety certification creates compliance moats for first-movers in battery-electric ATV development. Desert racing validation in Baja California and Nevada desert circuits accelerates credibility building.
- Gasoline:Spark-ignition engines remain dominant in recreational and racing segments where refueling infrastructure is absent. CARB off-road emission rules and EPA Tier 4 standards compress development timelines and favor manufacturers with captive engine development.
- Hybrid:Parallel architectures blend electric torque delivery with gasoline range extension for expedition use cases. Australian Outback and Middle Eastern desert operating environments favor this configuration until charging infrastructure matures.
- Diesel:Compression-ignition powertrains concentrate in military and heavy utility applications requiring fuel commonality with tactical vehicle fleets. Torque characteristics suit towing and cargo tasks across uneven terrain.
Gasoline retains the largest installed base. Electric platforms are gaining share fastest in commercial ranch and rental fleet procurement.
Performance Feature:
Component-level segmentation reflects divergent engineering priorities across price tiers and use cases. Active suspension calibration systems command premium pricing through sensor-fused damping automation.
- Suspension System:Long-travel configurations with forged aluminum components and remote reservoir dampers define competitive positioning in desert racing and premium recreational segments. Real-time compression and rebound tuning automates terrain response and compresses lap time variance across operator skill levels.
- Four-Wheel Drive:Selectable and full-time architectures with locking differentials provide traverse capability for utility and expedition applications. Ranch operators in Arizona and Australian cattle stations specify these systems for property maintenance across unimproved terrain.
- Engine Power:Displacement and output calibration separate recreational from competition specifications. Racing applications command purpose-built configurations that exceed recreational durability limits.
- Traction Control:Electronic stability systems with terrain-selectable modes migrate from automotive into high-end UTV platforms. Integration with GPS telemetry enables subscription-based fleet management services for commercial operators.
Suspension system investment concentrates the highest engineering resources. Traction control integration is expanding most quickly through telemetry-enabled service platforms.
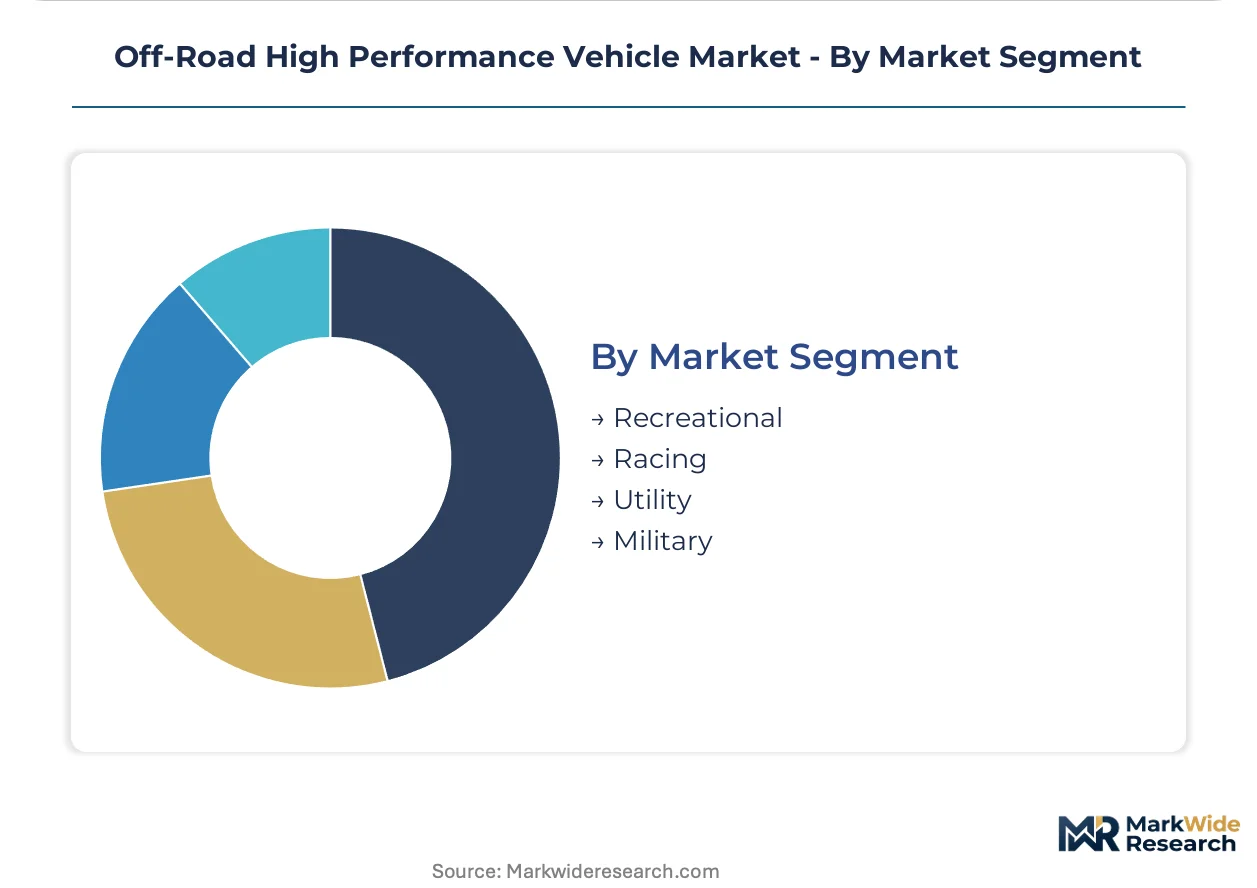
Market Segment:
End-use segmentation determines pricing architecture and distribution channel selection. Military procurement programs operate through defense contractors with security clearance requirements.
- Utility:Commercial ranch, agriculture, and property maintenance applications prioritize total cost of ownership over upfront acquisition price. Leasing and subscription models displace traditional dealer financing for vehicles exceeding 50 horsepower in Texas and Australian operations with utilization above 1,200 annual hours.
- Military:Armored UTV platforms gain traction in Australian and Middle Eastern modernization programs. Local content requirements and offset agreements shape supplier selection and partnership structures.
- Recreational:Desert racing culture in the United States sustains premium UTV and ATV volumes through enthusiast communities and trail network access. BRP Inc. competes aggressively here with terrain-specific side-by-side engineering.
- Racing:Purpose-built competition machines with specifications exceeding recreational durability limits command substantial price premiums. Validation in sanctioned series provides marketing leverage for production platform sales.
Utility applications deploy the largest fleet volumes. Military procurement is climbing the fastest as armored platform requirements expand across Middle Eastern defense budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welders and chassis fabricators concentrate in manufacturing clusters across Minnesota, Ontario, and Shizuoka Prefecture, anchoring production capacity for tubular frame architectures and long-travel suspension systems.
United States
Desert racing culture in Nevada and Arizona sustains premium UTV volumes through enthusiast communities and trail network access. EPA Tier 4 emission standards compress development timelines for spark-ignition engines while accelerating electrified platform investments. Minneapolis-St. Paul anchors North American distribution infrastructure for side-by-side and ATV platforms.
Australia
Cattle stations in Queensland and Western Australia drive replacement cycles toward cab-equipped UTVs for livestock management across unimproved terrain. TGA equipment standards govern telemetry integration for expedition and commercial fleet applications. Perth and Brisbane concentrate aftermarket modification workshops serving Outback operating environments.
Germany
EU Green Deal mandates accelerate zero-emission product line commitments with 2035 phase-out timelines for pure combustion offerings. KBA type approval processes shape side-by-side roof and occupant restraint mandates for European trail networks. Bavaria hosts engineering centers developing active suspension calibration systems for premium recreational segments.
China
Dual carbon goals push domestic manufacturers toward battery-electric architectures with torque parity to gasoline engines. MIIT GB standards govern emerging high-voltage ATV safety certification above 400V. Chongqing and Zhejiang Province concentrate lithium-ion pack assembly capacity for export-oriented manufacturers.
Saudi Arabia
Military modernization programs specify armored UTV platforms for patrol and reconnaissance missions across desert terrain. SFDA and local content requirements shape supplier selection and offset agreements for defense procurement. Riyadh and the Eastern Province concentrate final assembly partnerships serving GCC defense budgets.
Off-Road High Performance Vehicle Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: powersport conglomerates with captive engine development, motorcycle heritage manufacturers leveraging shared powertrain platforms, and defense contractors integrating armored architectures. Consolidation pressures favor M&A activity targeting sealed drivetrain validation capabilities and ISO 6469-3 compliance expertise for emerging electric platforms.
Among North American powersport conglomerates, Polaris Inc. and BRP Inc. occupy positions exemplifying scale-driven distribution dominance through RZR and Can-Am platform families. Yamaha Motor Co., Ltd. anchors the motorcycle heritage tier, representing manufacturers that leverage shared engine architectures across dirt bike and ATV categories. These three companies illustrate how engineering resource allocation splits between electrified powertrain development and Tier 4 compliance investment.
| Leading Market Players |
|---|
| Polaris Inc. |
| Yamaha Motor Co., Ltd. |
| Honda Motor Co., Ltd. |
| Bombardier Recreational Products Inc. |
| Arctic Cat Inc. |
| Kawasaki Heavy Industries, Ltd. |
| Suzuki Motor Corporation |
| Textron Inc. |
| BRP Inc. |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price indices cascade through battery-electric UTV architectures, compressing margins on electric platforms while gasoline-powered alternatives absorb EPA Tier 4 compliance costs through captive engine development. This input cost asymmetry stratifies pricing across powertrain categories, with hybrid configurations capturing premium positioning in Australian cattle station and Middle Eastern defense procurement where charging infrastructure remains absent.
Pricing Analysis
Subscription-based fleet management services unbundle from hardware acquisition for commercial ranch operators exceeding 1,200 annual utilization hours. Three-tier pricing structure across premium racing specifications, standard recreational configurations, and economy utility platforms differentiates through suspension travel and engine displacement tiers. Cost compression in electric powertrains stems from lithium-ion cell procurement exposure, while gasoline platforms face price pressure from CARB certification overhead. Commercial utility buyers exhibit highest price sensitivity through total cost of ownership evaluations, whereas desert racing enthusiasts accept substantial premiums for competition-grade suspension systems.
Supply Chain Analysis
Neodymium permanent magnet supply rests on Chinese rare earth processing facilities, with Australian and Chilean lithium extraction feeding cathode material production. Chromoly steel tubing draws from Japanese and South Korean specialty steel mills, while forged aluminum suspension components concentrate in German and Austrian automotive supplier networks. Single-source vulnerability in rare earth element refining exposes OEMs to export restriction risks from concentrated processing jurisdictions. Distribution runs through Minneapolis-St. Paul and Perth distribution hubs serving North American and Australasian dealer networks respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA Tier 4 compliance costs in the United States and state subsidy availability under China's dual carbon goals, with manufacturing footprint selection determining competitive unit economics.
For Market Incumbents: Deepen backward integration into lithium-ion pack assembly and sealed drivetrain validation capabilities to defend against emerging electric specialists. Secure ISO 6469-3 certification moats for architectures above 400V before regulatory deadlines compress. Add welded tubular frame capacity in Minnesota and Ontario clusters to constrain qualified supplier bottlenecks during demand surges. For New Entrants and Emerging Players: Capture armored UTV procurement white space in Saudi and UAE military modernization programs through local assembly partnerships satisfying SFDA content requirements. Target Australian cattle station fleet electrification pilots where state subsidies offset lithium cost exposure. Pursue telemetry-integrated subscription services for Texas and Arizona commercial operators as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with sealed drivetrain validation specialists and ISO 6469-3 compliance consultancies serving first-mover electric platform launches. Long-term viability favors acquisition targets with captive welding certifications and chromoly fabrication expertise across the 5-10 year electrification transition. Watch EPA enforcement intensity and Chinese rare earth export licensing as inflection indicators for supply cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | SFDA content requirements in Saudi Arabia and UAE defense procurement create mandatory partnership structures for foreign suppliers. |
| Battery Supply Agreement | Long-term lithium carbonate offtake contracts with Australian and Chilean extractors stabilize electric platform cost structures. |
| Certification Investment | ISO 6469-3 safety validation for architectures above 400V establishes competitive moats against late electric entrants. |
| Telemetry Platform Launch | FCC-authorized GPS and two-way radio integration enables subscription revenue streams from commercial ranch and rental fleets. |
| Suspension Technology Acquisition | Active damping calibration specialists in Bavaria compress development timelines for premium recreational segment positioning. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with UTV platform engineers, commercial ranch procurement managers, Middle Eastern defense contracting officers, and EPA certification consultants with secondary validation. Regulatory filings from EPA, CARB, and KBA shaped compliance cost modeling, while production databases and customs records informed capacity and trade flow analysis. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates across vehicle type, fuel category, and end-use segmentation.
Segment-weighting approaches distributed value and volume across UTV, SUV, ATV, and dirt bike architectures, with fuel type stratification between electric, gasoline, hybrid, and diesel powertrains. Performance feature tiers and market segment applications provided cross-cutting analytical dimensions. CAGRs derived from installed base replacement cycles, electrification penetration assumptions, and defense procurement pipeline visibility across the projection horizon. Military modernization program announcements and ranch utility fleet telemetry adoption curves served as industry-specific forecast inputs.
Raw material price volatility, regulatory enforcement intensity shifts, and charging infrastructure deployment pace are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about lithium-ion energy density improvement trajectories and rare earth supply chain stability that warrant ongoing watch. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Off-Highway Vehicle Engine Market