
 Automotive Data Logger Market | 2026-2036
Automotive Data Logger Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Data Logger Market Analysis
The embedded software engineering labor pool is bifurcating between legacy CAN protocol specialists and AI validation engineers, constraining how quickly Tier-1 suppliers can scale next-generation logging platforms. Robert Bosch GmbH leverages its Stuttgart-based R&D footprint to sustain deep integration with European OEM validation pipelines. National Instruments anchors North American demand through PXI-based test systems that dominate powertrain calibration labs. Continental AG competes by extending its logging hardware into full-stack ADAS data recording solutions.
An automotive data logger is a ruggedized electronic device that captures, timestamps, and stores vehicle bus data from CAN, LIN, FlexRay, and Ethernet networks at sampling rates exceeding 10 kHz per channel, serving the core purpose of validating powertrain performance, emissions compliance, and autonomous system behavior before production release. CAN Bus interfaces still dominate installed volume, though modular logger architectures are gaining fastest as OEMs demand reconfigurable channel counts across BEV and ICE test fleets. Fleet Management Solutions applications carry concentrated margin pools because operators pay premiums for real-time driver behavior analytics and predictive maintenance integration.
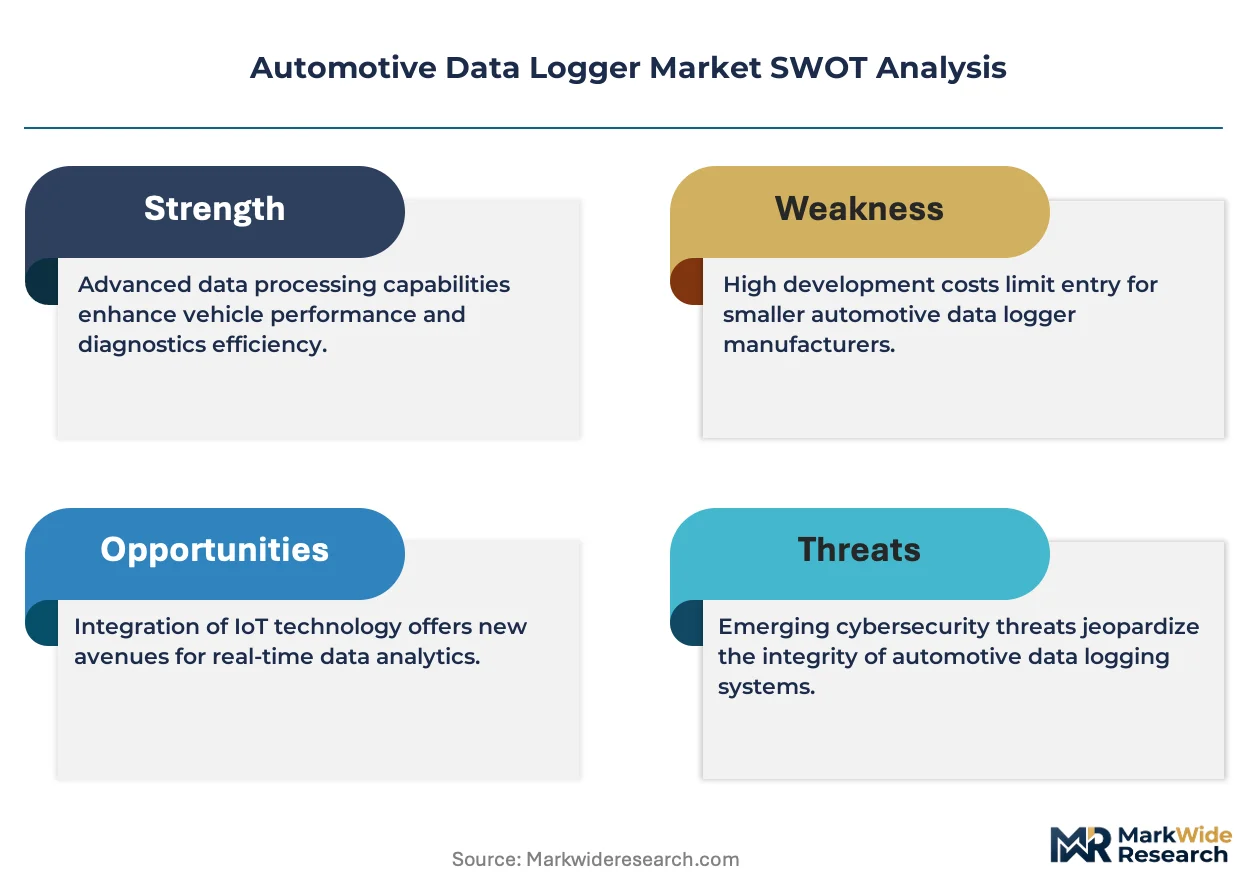
NHTSA mandates Event Data Recorder survivability standards, while UNECE WP.29 and ISO 26262 together force encryption, tamper-proofing, and functional safety certification into every logger sold for production-vehicle integration. The EU AI Act and GDPR add data governance layers that reshape how cross-border test fleets manage driver biometric logging. Stakeholders must monitor whether emerging software-defined vehicle architectures eliminate standalone hardware loggers or simply displace their form factors into zonal compute gateways.
Market Dynamics
The automotive data logger market is pivoting around the collision of zonal electronic architectures with legacy CAN-based validation workflows, forcing Tier-1 suppliers to reengineer hardware form factors while maintaining backward compatibility with existing test fleet infrastructure.
Growth Catalysts
- UNECE WP.29 Cybersecurity Mandates:The regulation forces production-vehicle data recorders to embed tamper-proof encryption and secure boot protocols, expanding hardware content per unit across European OEM fleets.
- Autonomous Validation Pipelines:ADAS development programs in Germany, Japan, and the United States now require continuous multi-sensor logging at terabyte-per-hour scales, pulling demand for high-channel-count modular systems.
- BEV Powertrain Calibration:Electric vehicle motor controllers generate transient load profiles that exceed legacy logger sampling capabilities, necessitating Ethernet-based acquisition hardware with sub-millisecond timestamping.
Market Restraints
- Semiconductor Supply Concentration:Automotive-grade FPGA and high-speed ADC sourcing clusters in Taiwan create vulnerability for logger manufacturers dependent on 10+ Gbps data throughput chips.
- ISO 26262 Functional Safety Certification:The ASIL-D compliance timeline adds 14-18 months to new product introductions, compressing effective revenue windows for hardware generations.
- Software-Defined Vehicle Substitution:Centralized zonal compute gateways with native logging capabilities threaten standalone hardware demand in next-generation vehicle platforms.
Strategic Opportunities
- India Test Fleet Expansion:Domestic OEMs and global validation centers are establishing hot-weather proving grounds in Rajasthan and Tamil Nadu, creating demand for ruggedized loggers rated to 85°C ambient operation.
- EU AI Act Data Governance:The framework mandates auditable biometric data handling for driver monitoring systems, opening specialized logging segments for privacy-compliant edge processing hardware.
- Edge-AI Logger Convergence:Integration of on-device inference engines with raw data acquisition enables real-time anomaly flagging, reducing cloud transfer costs for fleet operators running predictive maintenance programs.
Industry Challenges
- Embedded AI Validation Skill Scarcity:The labor pool bifurcation between legacy CAN protocol engineers and machine-learning pipeline specialists constrains how quickly suppliers can staff next-generation platform development.
- Multi-Protocol Integration Complexity:Simultaneous logging across CAN-FD, Automotive Ethernet, and LIN buses requires sophisticated timestamp synchronization that strains firmware engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Data Logger Market |
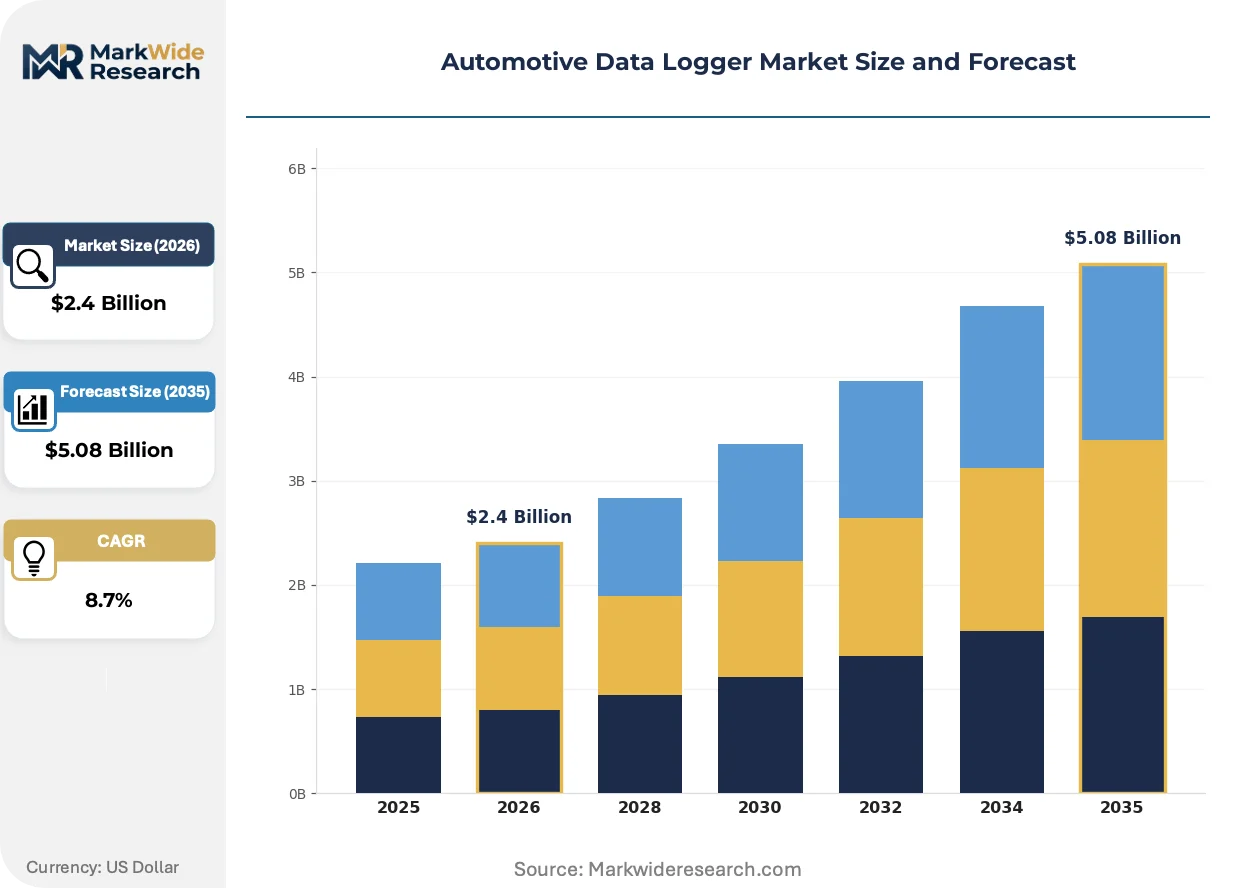
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Board Loggers, Off-Board Loggers, Handheld Loggers, Modular Loggers Application: Vehicle Performance Testing, Emissions Monitoring, Driver Behavior Analysis, Fleet Management Solutions Technology: GPS, Bluetooth, CAN Bus, Wi-Fi End User: OEMs, Aftermarket Retailers, Fleet Operators, Research Institutions |
| Companies Covered | National Instruments, TTTech Auto AG, Robert Bosch GmbH, Ipetronik GmbH & Co. KG, Intrepid Control Systems, Vector Informatik GmbH, Racelogic Ltd, Aptiv PLC, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Data Logger Market Emerging Trajectories
Automotive data logging is fragmenting into two divergent technical paths: centralized high-throughput acquisition for autonomous development and distributed edge-computing nodes for production vehicle monitoring, with hardware architectures splitting accordingly.
Ethernet-based logging backbones are supplanting traditional CAN-centric architectures in new vehicle platforms. The technology enables 10 Gbps sustained throughput for camera and lidar raw data streams. German and Japanese OEM validation centers are adopting these systems fastest for Level 3+ ADAS programs. The shift is compressing demand for legacy CAN-FD-only hardware while expanding modular chassis that accept mixed-protocol daughtercards.
NHTSA's Event Data Recorder survivability standards are tightening physical robustness requirements for production-integrated loggers. The rules mandate 30-second fire immunity and crash-impact tolerance that exceed consumer electronics specifications. Suppliers serving the US market are responding with metal-housing designs and solid-state storage arrays that eliminate mechanical failure points.
Fleet operators are unbundling data analytics from hardware procurement, purchasing logger hardware outright while subscribing to cloud-based interpretation platforms. The pattern disrupts traditional bundled-service contracts dominant in commercial vehicle telematics. North American trucking and last-mile delivery verticals exhibit this behavior most prominently, pressuring suppliers to decouple software revenue from hardware margins.
Automotive Data Logger Market Segmentation
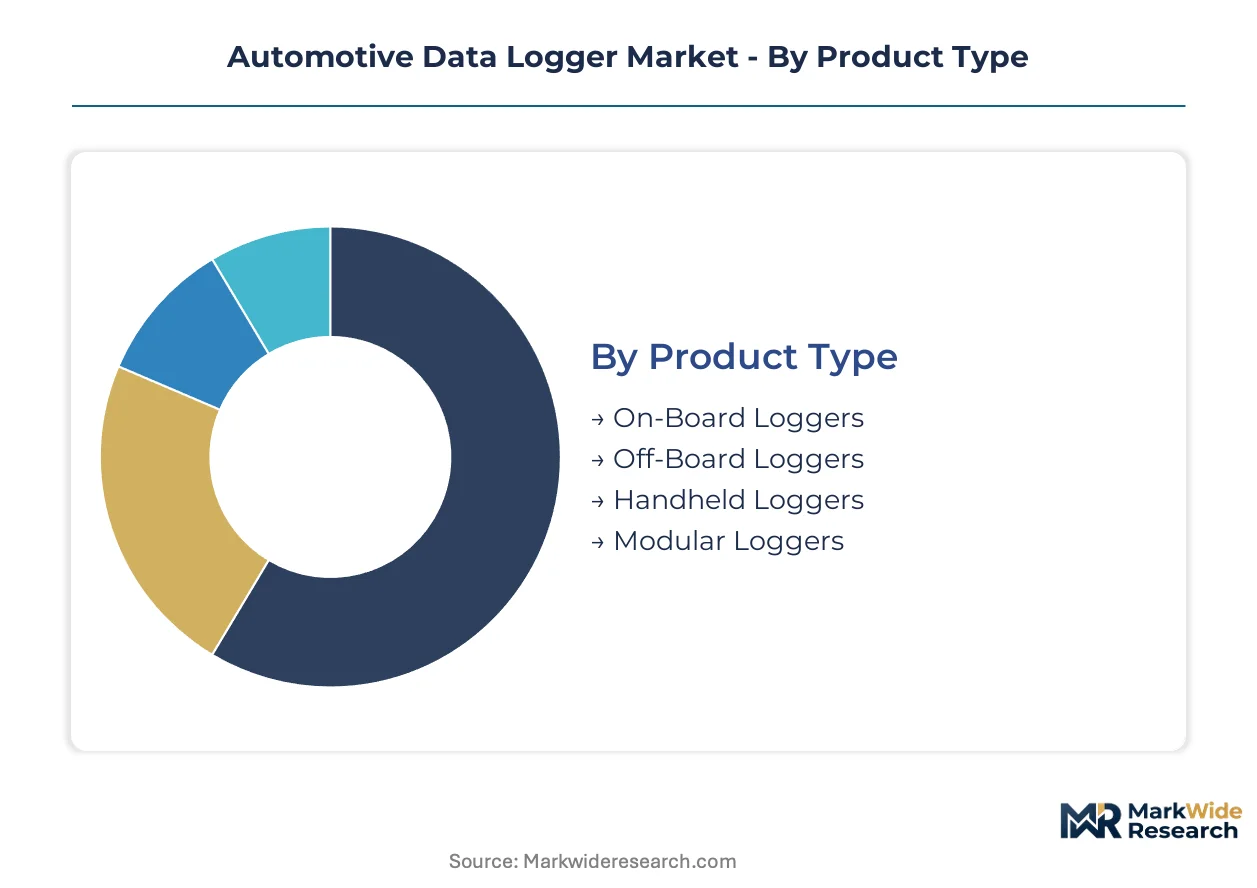
Automotive data logger segmentation reveals how hardware form factors, connectivity protocols, and customer procurement patterns split margin pools across radically different use cases from ADAS validation to commercial fleet telematics. Understanding these fracture lines exposes where suppliers can defend pricing power versus where commoditization pressures dominate.
Product Type:
Margin concentration sits with modular architectures that command premiums for reconfigurable channel counts across mixed BEV-ICE test fleets, while handheld units face relentless price compression from Asian electronics assemblers.
- On-Board Loggers:Permanently installed units integrate directly into vehicle electrical architectures for continuous production-vehicle monitoring. German OEMs embed these for UNECE WP.29 cybersecurity compliance validation, driving ASIL-D certified hardware demand.
- Off-Board Loggers:Portable acquisition systems connect via diagnostic ports for intermittent testing protocols. North American powertrain calibration labs favor these for emissions certification cycles where temporary instrumentation avoids homologation complexity.
- Handheld Loggers:Compact single-channel devices service roadside diagnostics and small repair operations. Price points below $500 dominate developing market aftermarket channels where feature depth matters less than physical durability.
- Modular Loggers:Chassis-based systems accept swappable daughtercards for mixed-protocol acquisition. Japanese Tier-1 suppliers specify these for Level 3+ ADAS programs requiring simultaneous CAN-FD, Automotive Ethernet, and camera interface logging.
The dominant share belongs to On-Board Loggers, while Modular Loggers are gaining share fastest as validation complexity multiplies across zonal electronic architectures.
Application:
Application segmentation tracks how regulatory enforcement intensity and data monetization potential split demand between compliance-mandated testing and discretionary fleet analytics investments.
- Vehicle Performance Testing:Powertrain and chassis validation protocols generate sustained demand from Stuttgart and Detroit engineering centers. NHTSA crash-data mandates force survivability specifications that eliminate consumer-grade hardware from consideration.
- Emissions Monitoring:Regulatory compliance logging for EPA and Euro 7 standards requires calibrated measurement chains traceable to national standards bodies. Hardware margins compress where certification is the sole purchase driver rather than engineering optimization.
- Driver Behavior Analysis:Insurance telematics and safety scoring applications concentrate in North American commercial auto fleets. GDPR and EU AI Act constraints limit biometric data logging in European deployments, fragmenting addressable market geography.
- Fleet Management Solutions:Integrated predictive maintenance and route optimization platforms command recurring software subscriptions. Last-mile delivery operators in the United States pay premiums for real-time anomaly flagging that reduces vehicle downtime.
Fleet Management Solutions capture the steepest expansion trajectory as operators unbundle analytics from hardware procurement, while Emissions Monitoring faces margin pressure from regulatory standardization of required feature sets.
Technology:
Technology segmentation exposes how protocol transition timelines and semiconductor sourcing constraints reshape competitive positioning across connectivity standards.
- GPS:Satellite positioning modules provide geospatial timestamping for correlation with mapping and traffic data. Accuracy demands for autonomous validation push dual-band receiver adoption in German and Japanese test fleets.
- Bluetooth:Short-range wireless enables smartphone pairing for configuration and data offload. Consumer-grade chipset availability from Taiwanese suppliers compresses hardware margins despite volume scale.
- CAN Bus:Controller Area Network interfaces remain the installed base majority for legacy vehicle compatibility. CAN-FD extensions double data rates while preserving physical layer investments, extending protocol relevance through the decade.
- Wi-Fi:High-throughput wireless backhaul supports over-the-air data extraction from test vehicles without physical retrieval. 802.11ax adoption in United States proving grounds reduces fleet downtime between validation cycles.
CAN Bus retains volume leadership, though Wi-Fi is climbing the fastest as terabyte-scale ADAS datasets render manual data retrieval economically unviable.
End User:
End user segmentation maps how procurement authority, technical specification depth, and supplier relationship duration fragment addressable demand across the value chain.
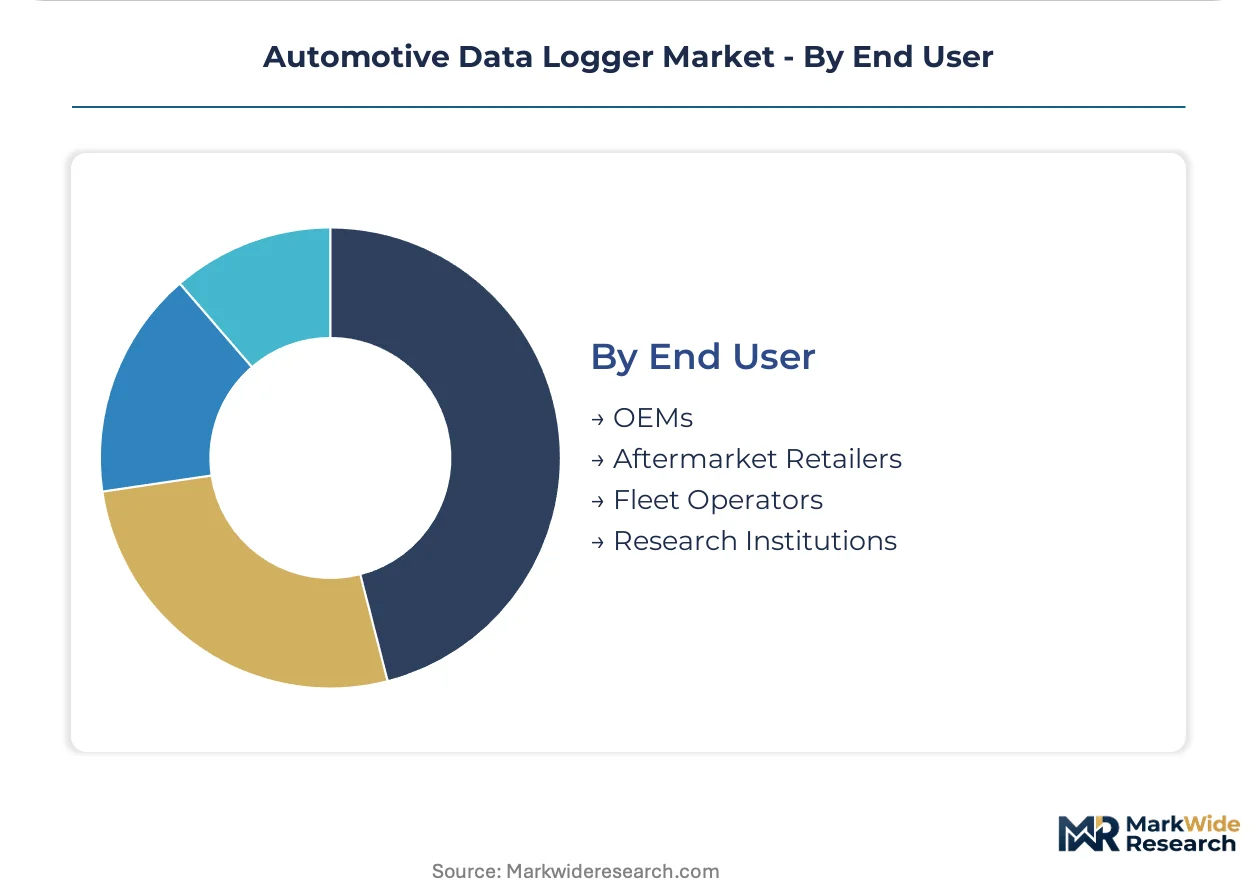
- OEMs:Original equipment manufacturers specify loggers for pre-production validation and production-vehicle integration. Long development cycles and deep supplier integration protect incumbents with proven ASIL-D certification track records.
- Aftermarket Retailers:Distributors and service chains procure hardware for diagnostic and retrofit applications. Price sensitivity and minimal technical support requirements favor simplified product portfolios with broad vehicle compatibility.
- Fleet Operators:Commercial vehicle owners purchase logging systems for asset tracking and maintenance optimization. Total cost of ownership calculations dominate procurement, privileging vendors with cloud analytics integration over pure hardware suppliers.
- Research Institutions:Universities and national laboratories acquire specialized instrumentation for fundamental automotive research. Small order quantities and custom protocol requirements strain standard product economics, often necessitating direct engineering engagement.
OEMs command the dominant procurement volume, while Fleet Operators are expanding most quickly as predictive maintenance ROI visibility improves across trucking and delivery verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA crash-data mandates and UNECE WP.29 cybersecurity rules anchor demand concentration in three advanced automotive testing economies. Regulatory enforcement intensity and validation infrastructure investment determine regional procurement patterns.
United States
Powertrain calibration labs in Detroit and Silicon Valley ADAS development centers drive hardware demand. NHTSA Event Data Recorder survivability standards mandate 30-second fire immunity and crash-impact tolerance that eliminate consumer-grade hardware. Austin and Ann Arbor engineering clusters concentrate Level 3+ autonomous validation programs requiring terabyte-per-hour logging capacity.
Germany
Stuttgart-based OEM validation pipelines and Munich engineering centers sustain embedded logging system procurement. UNECE WP.29 forces tamper-proof encryption and secure boot protocols into production-vehicle data recorders. Ingolstadt and Wolfsburg testing facilities specify ASIL-D certified hardware for cybersecurity compliance validation across European fleets.
Japan
Tier-1 suppliers in Nagoya and Tokyo specify modular chassis systems for mixed-protocol ADAS acquisition. METI industrial standards and JIS certification requirements shape hardware specifications for domestic OEM integration. Toyota City and Hiroshima validation centers drive demand for reconfigurable channel counts across BEV and ICE test fleets.
India
Domestic OEMs and global validation centers establish hot-weather proving grounds in Rajasthan and Tamil Nadu. BIS automotive electronics standards and PLI scheme incentives attract hardware manufacturing investment. Chennai and Pune engineering clusters create demand for ruggedized loggers rated to 85°C ambient operation in tropical testing conditions.
South Korea
Seoul Capital Area battery and motor controller development programs generate transient load profiling requirements. MFDS-equivalent automotive safety frameworks and KATRI certification protocols govern production-vehicle integration standards. Hwaseong and Ulsan validation facilities specify Ethernet-based acquisition hardware with sub-millisecond timestamping for BEV powertrain calibration.
Automotive Data Logger Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting ASIL-D certification track records and deep OEM validation pipeline integration. Consolidation pressures favor incumbents with proven functional safety documentation, while modular architecture demand creates openings for protocol-specialist challengers. Strategic archetypes include integrated automotive electronics conglomerates, test-and-measurement platform vendors, and embedded software engineering specialists. Dominant competitive moves center on backward integration into FPGA and high-speed ADC sourcing, plus geographic expansion into India hot-weather proving grounds.
Within the integrated tier, Robert Bosch GmbH and Continental AG exemplify European-based automotive electronics conglomerates with deep OEM validation relationships. National Instruments represents the test-and-measurement platform archetype, anchoring North American demand through PXI-based systems. These three occupy positions defined by certification depth and regional engineering cluster proximity rather than interchangeable hardware specifications.
| Leading Market Players |
|---|
| National Instruments |
| TTTech Auto AG |
| Robert Bosch GmbH |
| Ipetronik GmbH & Co. KG |
| Intrepid Control Systems |
| Vector Informatik GmbH |
| Racelogic Ltd |
| Aptiv PLC |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month ASIL-D certification timelines compress hardware generation revenue windows and force tiered pricing stratification across premium ASIL-D certified, standard ISO-compliant, and economy-grade aftermarket tiers. This lead-time concentration hands pricing power to incumbents with pre-certified platforms while squeezing margins for challengers bearing new product introduction costs.
Pricing Analysis
German and Japanese OEM validation centers pay 40-60% premiums over North American aftermarket channels for identical hardware specifications, reflecting ASIL-D certification depth and embedded software integration. Pricing stratifies across premium ASIL-D certified, standard ISO-compliant, and economy-grade aftermarket tiers. Cost compression in handheld diagnostics intensifies because Asian electronics assemblers flood developing market channels with sub-$500 units. Fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations privileging predictive maintenance ROI over upfront hardware spend.
Supply Chain Analysis
Strategic stockpiling of automotive-grade FPGAs and high-speed ADCs dominates procurement behavior among Tier-1 suppliers, displacing just-in-time norms that proved fragile during recent semiconductor shortages. Taiwan, South Korea, and the United States anchor supply for 10+ Gbps data throughput chips. Logger manufacturing draws from automotive-grade FPGA, high-speed ADC, and solid-state storage arrays. Single-source vulnerability concentrates in Taiwanese foundry capacity for specialized acquisition silicon. Distribution runs through direct OEM specification channels for on-board units and aftermarket distributor networks for portable diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive data logging is transitioning toward platform economics where zonal gateway architectures threaten standalone hardware incumbents, and interoperability with OEM validation pipelines determines competitive survival.
For Market Incumbents: Consolidate backward integration into FPGA and high-speed ADC sourcing to secure 10+ Gbps silicon allocation against fabless challengers. Deepen certification moats by accelerating ASIL-D documentation for next-generation Ethernet-based architectures before software-defined vehicle substitution accelerates.
For New Entrants and Emerging Players: Differentiate on edge-AI inference integration for real-time anomaly flagging in fleet management applications. Target India's hot-weather proving ground expansion with ruggedized 85°C-rated hardware, leveraging PLI scheme manufacturing incentives and domestic OEM validation center buildouts.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because UNECE WP.29 and NHTSA mandates embed hardware requirements that resist software substitution. Acquisition candidates with proven ASIL-D track records and embedded OEM validation relationships command defensive positioning. Watch for inflection when zonal compute gateway native logging capabilities cross 50% penetration in new vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Compresses 14-18 month compliance timelines to defend pricing power against uncertified challengers. |
| Ethernet Backbone Migration | Enables 10 Gbps camera and lidar data throughput for German and Japanese Level 3+ ADAS programs. |
| India Manufacturing Footprint | Captures PLI scheme incentives and hot-weather proving ground demand in Rajasthan and Tamil Nadu. |
| Edge-AI Logger Convergence | Integrates on-device inference engines to reduce cloud transfer costs for predictive maintenance operators. |
| Cybersecurity Protocol Embedding | Satisfies UNECE WP.29 tamper-proof encryption mandates for European OEM fleet compliance. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and fleet operator maintenance directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, vehicle production databases, IHS Markit registration data, and customs/trade flow records. Bottom-up channel checks triangulated against top-down OEM spending estimates.
Segmentation dimensions modeled span product type, connectivity protocol, application use case, and end-user procurement authority across the projection horizon. CAGRs derived from shipment volume trajectories by hardware form factor, weighted by regional regulatory enforcement intensity. Industry-specific forecast inputs incorporated NHTSA EDR mandate compliance deadlines and UNECE WP.29 cybersecurity implementation timelines.
Material uncertainties — semiconductor supply disruption, software-defined vehicle substitution velocity, and EU AI Act biometric data handling rulemaking — sit outside the modeled envelope. Forecasts reflect documented assumptions about zonal architecture penetration rates and certification timeline stability. Revision becomes warranted when standalone logger displacement by gateway-native solutions crosses critical adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market