
 Virtual Machine Backup and Recovery Market | 2026-2036
Virtual Machine Backup and Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Machine Backup and Recovery Market Intelligence
Healthcare provider adoption is expanding as hospitals virtualize critical imaging and electronic health record systems. Veeam Software leverages channel partnerships to dominate mid-market deployments across clinical networks. IBM Corporation anchors enterprise accounts with mainframe-integrated recovery orchestration. Commvault Systems Inc differentiates through metallic SaaS delivery and cross-cloud portability.
Virtual Machine Backup and Recovery encompasses software, services, and infrastructure that capture point-in-time copies of VM states—including memory, disk, and configuration files—to enable restoration after deletion, corruption, or ransomware encryption. Solutions typically support agentless hypervisor-level capture at 15-minute intervals for VMware vSphere and Microsoft Hyper-V environments, with recovery time objectives ranging from seconds to hours depending on tier. Cloud-based deployment is capturing the fastest growth as organizations abandon tape rotation for immutable object storage in AWS S3, Azure Blob, and Google Cloud. Continuous data protection commands premium pricing due to near-zero recovery point objectives, while snapshot backup remains mature and margin-compressed in commodity hosting environments. Large enterprises drive solution offering demand for disaster recovery as a service with orchestrated failover, though SMB appetite for bundled backup and archiving solutions is accelerating.
HIPAA Security Rule mandates healthcare entities implement data backup plans with retrievable exact copies, while GDPR Article 32 requires restoration of personal data availability in a timely manner. ISO 27001 and NIST SP 800-53 further shape product certification requirements for federal and financial buyers. Stakeholders must evaluate immutability guarantees and air-gapped recovery architectures as ransomware operators increasingly target backup repositories themselves.
Market Dynamics
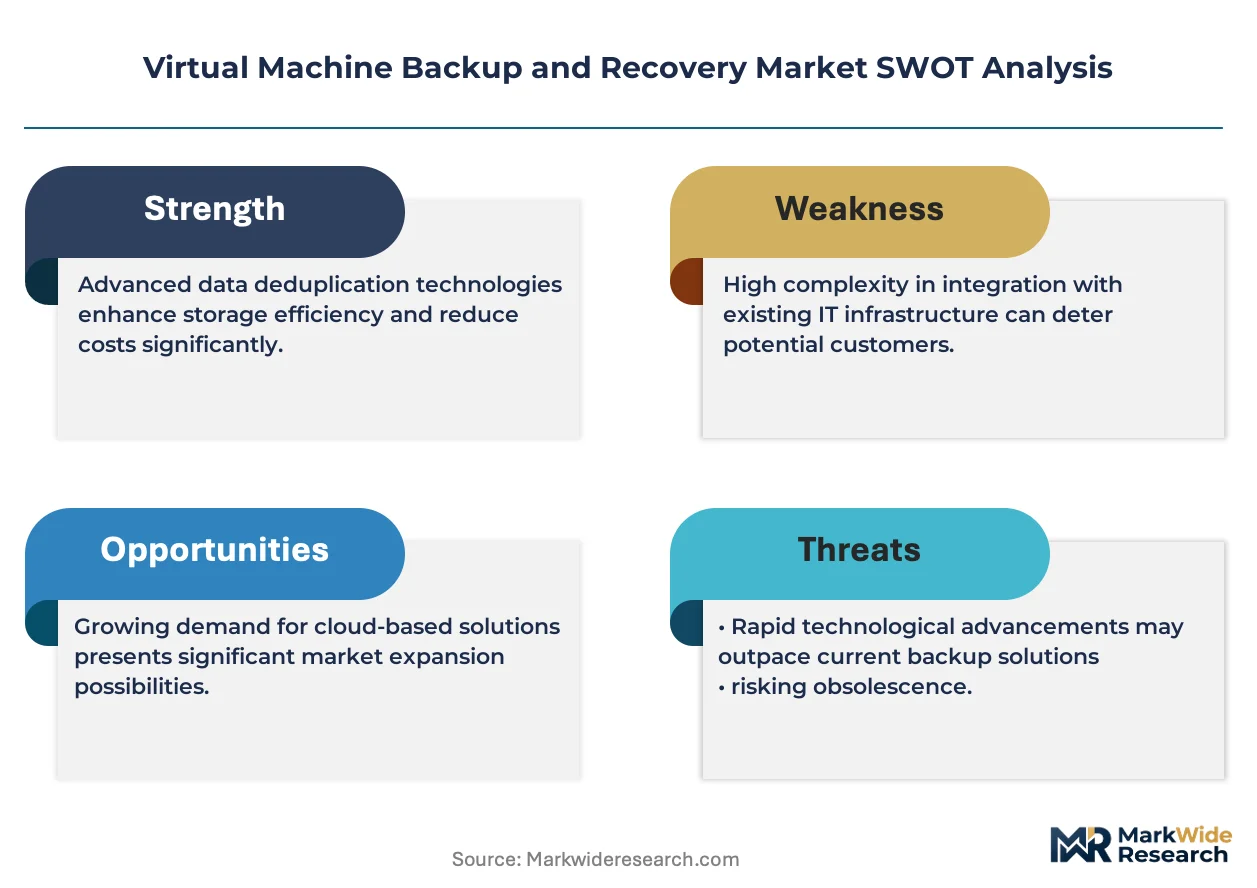
Ransomware operators now target backup repositories directly, forcing vendors to engineer immutable architectures and air-gapped recovery vaults as core product requirements rather than premium add-ons.
Growth Catalysts
- GDPR Article 32 mandates:European healthcare providers must restore personal data availability within strict timeframes, driving investment in continuous data protection with near-zero recovery point objectives.
- Agentless hypervisor capture:VMware vSphere and Microsoft Hyper-V environments now support 15-minute snapshot intervals without guest OS agents, reducing operational overhead for clinical IT teams.
- Cloud object storage economics:AWS S3, Azure Blob, and Google Cloud immutable tiers displace tape rotation with lower total cost of ownership and faster retrieval for tier-1 workloads.
Market Restraints
- Backup repository targeting:Ransomware gangs specifically hunt backup metadata stores, forcing redundant infrastructure spend that compresses solution margins.
- Hypervisor licensing concentration:VMware's pricing power in enterprise virtualization creates vendor lock-in that limits buyer negotiating leverage on bundled backup offerings.
- Skill scarcity in recovery orchestration:Enterprises lack sufficient staff fluent in cross-cloud failover automation, delaying disaster recovery as a service adoption.
Strategic Opportunities
- Metallic SaaS delivery models:Commvault's cloud-native architecture demonstrates how subscription portability across AWS, Azure, and Google Cloud captures mid-market buyers abandoning perpetual licenses.
- ISO 27001 certification gaps:Federal and financial buyers require validated immutability guarantees that smaller vendors struggle to document, creating acquisition targets for compliant platforms.
- India's hospital digitization:The country's National Digital Health Mission drives virtualization of imaging and electronic health records in tier-2 and tier-3 cities with limited legacy tape infrastructure.
Industry Challenges
- Cross-cloud metadata portability:VM configuration files, memory states, and disk snapshots use proprietary formats that resist seamless migration between hypervisor ecosystems.
- Recovery time objective verification:Buyers demand proof of seconds-to-hours restoration capabilities, yet live disaster testing disrupts production systems and risks data corruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Machine Backup and Recovery Market |
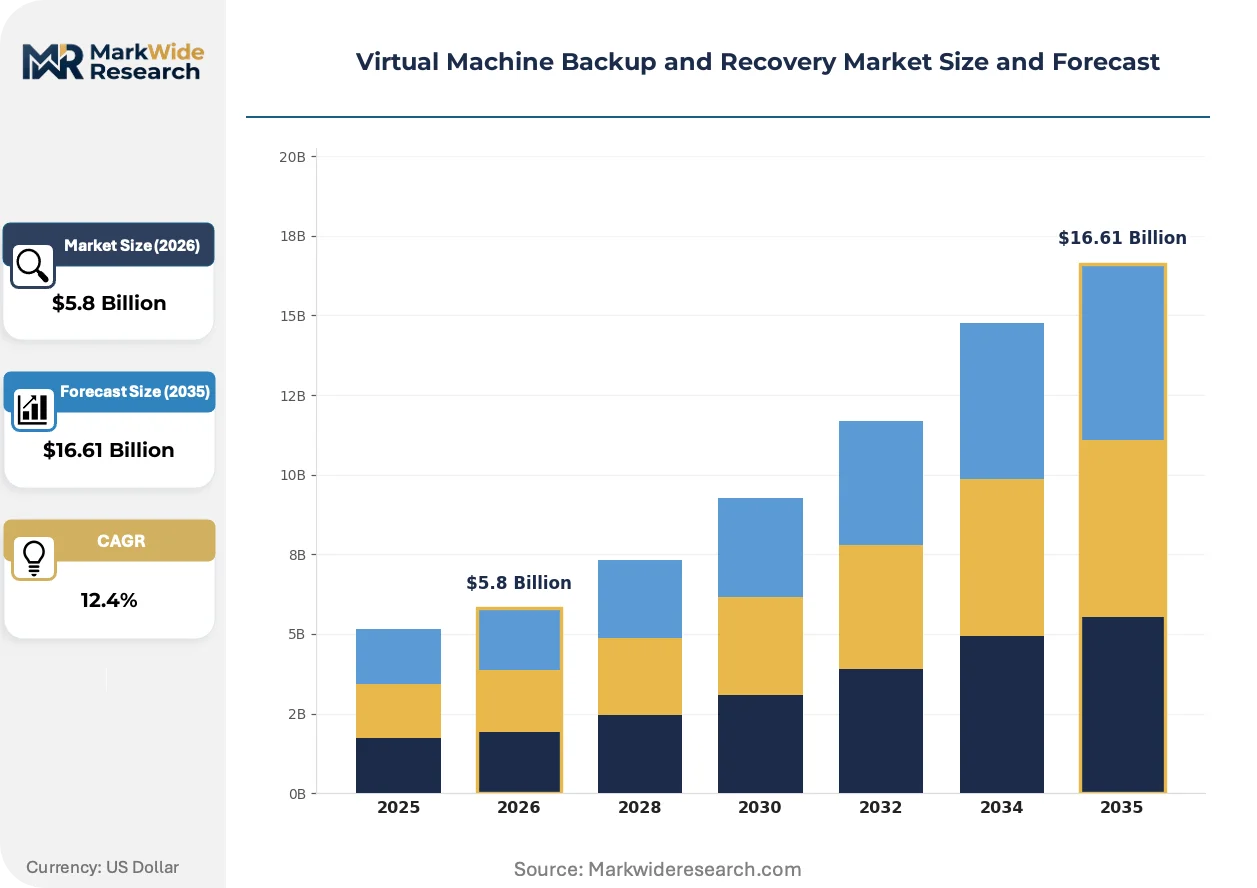
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $16.61 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Service Backup Type: Full Backup, Incremental Backup, Differential Backup, Continuous Data Protection, Snapshot Backup End User: SMBs, Large Enterprises, Government Agencies, Educational Institutions, Financial Organizations Solution Offering: Backup Software, Recovery Software, Disaster Recovery as a Service, Archiving Solutions, Monitoring Tools |
| Companies Covered | Veritas Technologies LLC, IBM Corporation, Veeam Software, Zerto, Inc., Vembu Technologies, Commvault Systems Inc, Acronis International GmbH, Quest Software Inc., VMware, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Machine Backup and Recovery Market Strategic Shifts & Innovations
Immutable object storage architectures are displacing tape-based rotation as the default protection tier, while continuous data protection compresses acceptable recovery windows from hours to seconds.
Kubernetes-native backup is unifying container and virtual machine protection under single control planes. Platform engineering teams in financial services and SaaS providers adopt this convergence to eliminate separate tooling for stateful containers and traditional VMs. The approach is unifying backup policy management and reducing operational sprawl that previously required distinct teams and budgets.
HIPAA Security Rule enforcement has intensified around data backup plan documentation. The Department of Health and Human Services Office for Civil Rights now audits exact copy retrievability during investigations, compelling hospitals to demonstrate restoration procedures rather than merely attest to their existence. United States healthcare providers respond by deploying orchestrated recovery testing that validates recovery time objectives without disrupting clinical operations.
Hospital procurement committees now bundle backup with cyber insurance requirements. Risk officers in United States health systems specify immutable storage and isolated recovery environments as policy prerequisites, shifting vendor selection criteria from technical specifications to risk transfer validation. This behavioral pivot favors vendors with documented ransomware recovery case studies over those with superior feature matrices alone.
Virtual Machine Backup and Recovery Market Segmentation
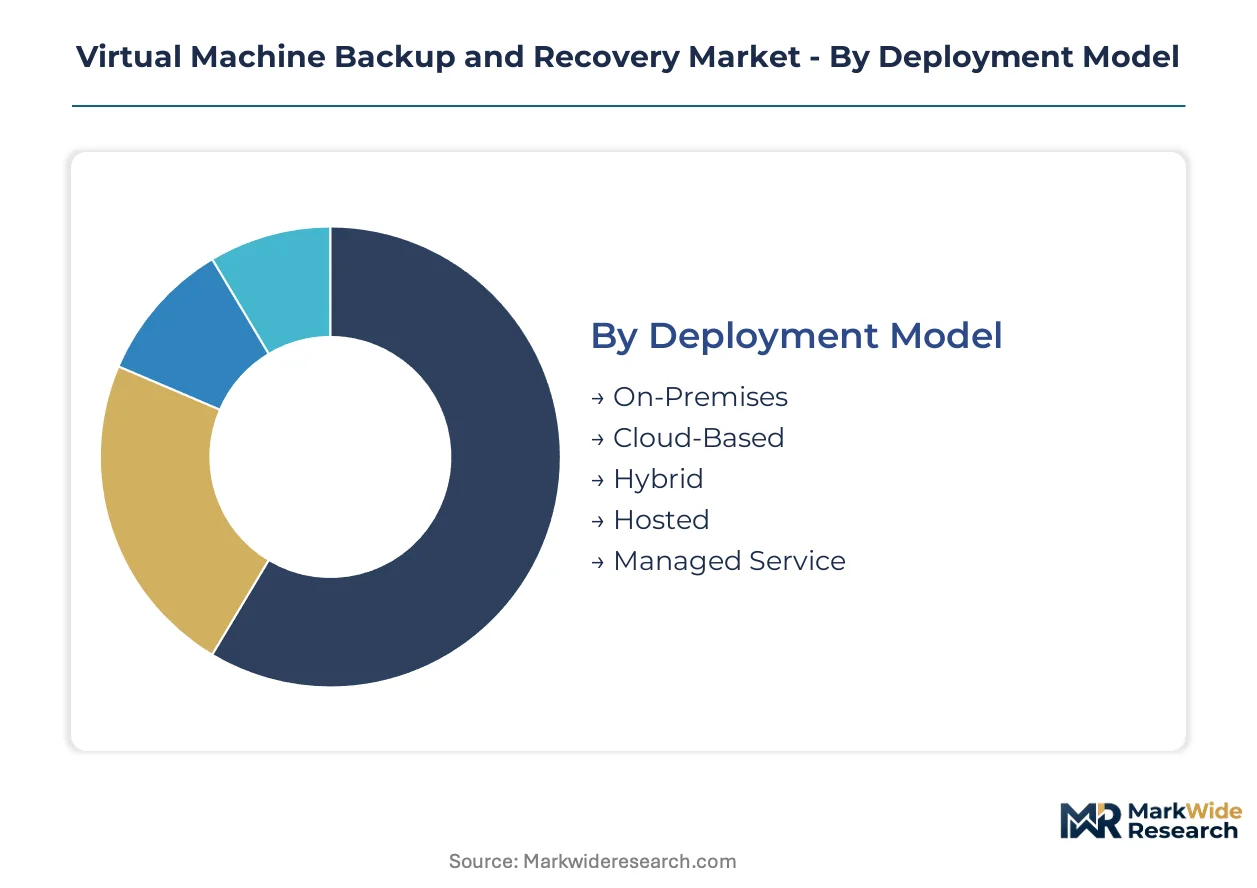
VM backup and recovery segmentation reveals divergent capital requirements across deployment architectures and buyer sophistication tiers. Procurement committees weight total cost of ownership against recovery time objectives when mapping segments to organizational risk profiles.
Deployment Model:
Capital intensity varies dramatically across deployment architectures, with infrastructure ownership obligations determining upfront investment thresholds.
- On-Premises:Organizations retain full hardware ownership including storage arrays, compute nodes, and dedicated network fabric for backup traffic isolation. United States healthcare providers favor this model for HIPAA-controlled environments where data sovereignty overrides cloud economics.
- Cloud-Based:Consumption pricing eliminates capital expenditure while introducing egress cost volatility. AWS S3, Azure Blob, and Google Cloud immutable tiers attract mid-market buyers abandoning tape rotation for operational expenditure models.
- Hybrid:Combines local snapshot retention with cloud archival tiers, demanding dual infrastructure competency and orchestration tooling. Financial organizations in Frankfurt and Singapore deploy this architecture to satisfy data residency mandates while leveraging cloud scale.
- Hosted:Third-party data centers provide dedicated backup infrastructure without shared-tenant risks. European manufacturers prefer this model for ISO 27001-certified environments avoiding hyperscaler concentration.
- Managed Service:Outsourced operations transfer staffing burdens to specialized providers. Australian healthcare networks adopt this segment to address recovery orchestration skill scarcity without internal hiring.
On-Premises absorbs the bulk of installed capacity; Cloud-Based is expanding most quickly.
Backup Type:
Recovery point objective requirements stratify buyer investment across protection granularity tiers.
- Full Backup:Captures complete VM states including memory, disk, and configuration files at scheduled intervals. Mature commodity hosting environments deploy this approach where hourly recovery windows suffice.
- Incremental Backup:Records only changed data blocks since last backup, reducing storage consumption and network transfer. Large enterprises with petabyte-scale VM estates standardize on this method for daily operational protection.
- Differential Backup:Accumulates changes since last full backup, balancing restore simplicity against growing backup windows. Educational institutions with limited IT staffing favor this approach for streamlined recovery procedures.
- Continuous Data Protection:Journal-based capture enables point-in-time recovery to any second, commanding premium pricing for near-zero recovery point objectives. United States hospitals protecting electronic health record systems drive demand for this segment despite operational complexity.
- Snapshot Backup:Hypervisor-native point-in-time copies execute at 15-minute intervals without guest OS agents. VMware vSphere and Microsoft Hyper-V environments standardize on this method for tier-1 workload protection.
Snapshot Backup dominates transaction volume; Continuous Data Protection commands the steepest expansion trajectory.
End User:
Organizational scale dictates procurement authority and solution complexity tolerance.
- SMBs:Bundled backup and archiving solutions with simplified policy management address limited technical staffing. India's tier-2 and tier-3 hospital digitization under the National Digital Health Mission accelerates adoption in this segment.
- Large Enterprises:Disaster recovery as a service with orchestrated failover across multiple sites satisfies stringent business continuity requirements. United States financial services firms lead investment in cross-cloud automation capabilities.
- Government Agencies:FedRAMP and NIST SP 800-53 compliance mandates shape vendor selection around documented immutability guarantees. Federal buyers prioritize air-gapped recovery architectures against nation-state threat models.
- Educational Institutions:Constrained budgets favor perpetual license models over subscription portability despite higher lifecycle costs. Research universities with heterogeneous VM estates require cross-hypervisor compatibility.
- Financial Organizations:Regulatory pressure from SEC cybersecurity disclosure rules drives investment in recovery time objective verification. Risk officers specify immutable storage as cyber insurance prerequisites.
Large Enterprises concentrate vendor revenue; SMBs are climbing the fastest as cloud delivery democratizes enterprise-grade capabilities.
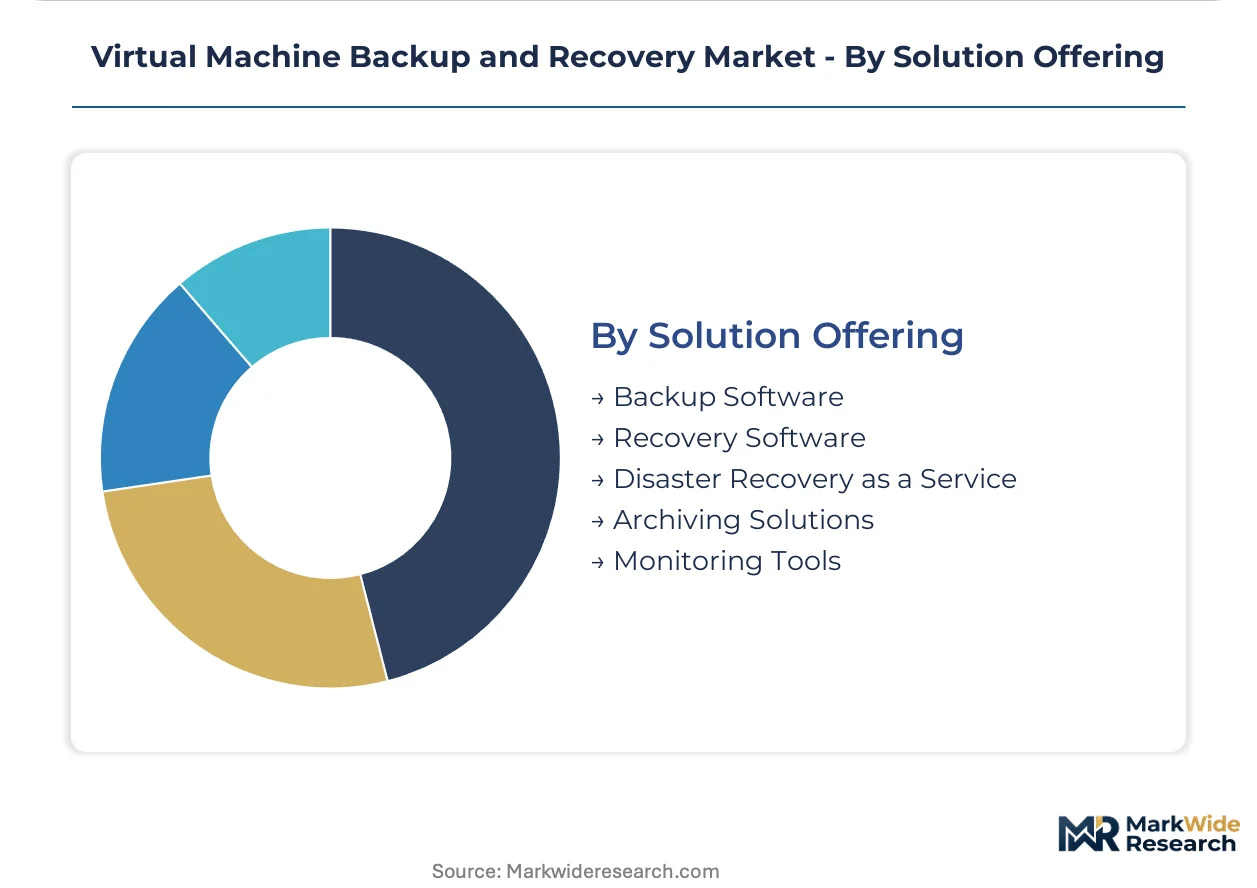
Solution Offering:
Product packaging determines margin structure and customer lifetime value.
- Backup Software:Agentless hypervisor-level capture tools with policy-driven scheduling and compression. VMware's pricing power in enterprise virtualization creates vendor lock-in that limits buyer negotiating leverage on bundled offerings.
- Recovery Software:Granular file-level and full-VM restoration with automated testing validation. GDPR Article 32 mandates for timely personal data restoration drive European healthcare provider investment in this segment.
- Disaster Recovery as a Service:Orchestrated failover with runbook automation and network reconfiguration. Skill scarcity in recovery orchestration delays adoption despite strong enterprise appetite.
- Archiving Solutions:Long-term retention with legal hold and e-discovery integration for compliance workflows. Financial organizations facing SEC record-keeping requirements standardize on this capability.
- Monitoring Tools:Real-time backup job visibility with anomaly detection for ransomware early warning. Ransomware operators targeting backup repositories directly elevates this from operational convenience to security necessity.
Backup Software retains the largest installed base; Disaster Recovery as a Service is gaining share fastest as orchestration capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and United Kingdom, while healthcare digitization and cloud infrastructure investment drive consumption across Germany, India, and Japan. Production of backup solutions clusters around established enterprise software hubs, with demand diffusion following data center buildouts and regulatory enforcement patterns.
United States
Enterprise cloud migration and ransomware defense investments propel solution demand across Fortune 500 accounts. HIPAA Security Rule enforcement by the Department of Health and Human Services Office for Civil Rights mandates documented data backup plans with exact copy retrievability. Dallas-Fort Worth and Northern Virginia data center corridors host concentrated deployments of immutable object storage architectures for healthcare networks.
Germany
Automotive manufacturers and industrial Mittelstand firms virtualize production systems, requiring orchestrated recovery capabilities. GDPR Article 32 imposes strict personal data restoration timelines, compelling investment in continuous data protection with near-zero recovery point objectives. Frankfurt's financial services cluster drives hybrid deployment adoption to satisfy data residency mandates while leveraging cloud scale.
India
The National Digital Health Mission accelerates hospital digitization in tier-2 and tier-3 cities with limited legacy tape infrastructure. The country's central bank guidelines on cyber resilience shape financial sector procurement criteria around backup immutability. Bengaluru's technology corridor and Hyderabad's pharmaceutical manufacturing belt generate concentrated demand for agentless hypervisor capture solutions.
Japan
Financial services firms and automotive suppliers lead virtualization of mission-critical systems amid escalating ransomware threats. METI cybersecurity frameworks emphasize business continuity planning with validated recovery time objectives. Tokyo and Osaka metropolitan areas concentrate enterprise deployments, while regional manufacturing hubs adopt managed service models to address skill scarcity in recovery orchestration.
United Kingdom
Cloud-native SaaS providers and fintech startups drive subscription-based backup adoption over perpetual licenses. GDPR compliance requirements intersect with Financial Conduct Authority operational resilience rules for financial services. London's insurance market and Edinburgh's banking cluster specify immutable storage and isolated recovery environments as cyber insurance prerequisites.
Virtual Machine Backup and Recovery Market Key Industry Players
Top-tier vendors anchor enterprise accounts with integrated recovery orchestration, while mid-market specialists compete on subscription portability and channel density. The vendor base arranges across three distinct tiers: legacy infrastructure providers with mainframe integration capabilities, cloud-native platforms emphasizing SaaS delivery, and hypervisor-integrated offerings bundled with virtualization licensing. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into Kubernetes-native protection.
Within the cloud-native tier, Commvault Systems Inc and Veeam Software exemplify divergent route-to-market strategies, with the former emphasizing metallic SaaS delivery and the latter leveraging channel partnerships for clinical network penetration. IBM Corporation occupies a position representing legacy enterprise integration, anchoring accounts requiring mainframe-connected recovery workflows. Zerto, Inc. and Vembu Technologies sit within the specialist segment, with the Israel-based Zerto and India-anchored Vembu representing geographic diversification in engineering talent and customer support proximity.
| Leading Market Players |
|---|
| Veritas Technologies LLC |
| IBM Corporation |
| Veeam Software |
| Zerto, Inc. |
| Vembu Technologies |
| Commvault Systems Inc |
| Acronis International GmbH |
| Quest Software Inc. |
| VMware, Inc. |
| Others |
Cost & Logistics Intelligence
Backward integration into immutable object storage infrastructure anchors pricing power for vendors controlling their own cloud-native architectures, while hyperscaler-dependent competitors absorb egress cost volatility that compresses margins and limits rate-setting flexibility.
Pricing Analysis
Short lead-time delivery of continuous data protection capabilities commands premium subscription rates, while standard snapshot backup offerings face price erosion from commodity hosting competition. Three-tier pricing structure across premium, standard, and economy levels segments buyers by recovery point objective requirements, with HIPAA-mandated healthcare providers showing lowest price sensitivity due to regulatory compliance imperatives. Cost compression in the standard tier intensifies because VMware's bundled backup offerings leverage hypervisor licensing concentration. SMB buyers in India's tier-2 cities exhibit highest price sensitivity, prioritizing operational expenditure models over perpetual licenses.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler concentration in the United States, Ireland, and Singapore for immutable object storage infrastructure. Software development draws from engineering talent pools in Bengaluru, Tel Aviv, and the Research Triangle Park corridor. Supply chain risk centers on regulatory restriction: GDPR data residency mandates and FedRAMP certification requirements fragment cloud infrastructure deployment patterns. Distribution runs through channel partnerships for mid-market penetration and direct enterprise sales for orchestrated disaster recovery deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained recovery orchestration talent props pricing for vendors with proven cross-cloud automation capabilities, as skill scarcity delays disaster recovery as a service adoption despite enterprise appetite.
For Market Incumbents: To counter ransomware operators targeting backup metadata stores, engineer air-gapped recovery vaults as core product architecture rather than premium add-ons. Invest in ISO 27001 certification documentation to satisfy federal and financial buyer procurement requirements. Acquire Kubernetes-native backup specialists to unify container and VM protection under single control planes. For New Entrants and Emerging Players: Kubernetes-native backup unification represents the most penetrable white-space target, as platform engineering teams seek to eliminate separate tooling for stateful containers and traditional VMs. India's tier-2 and tier-3 hospital digitization under the National Digital Health Mission offers geographic entry with limited legacy tape infrastructure competition. Pursue metallic SaaS delivery models with subscription portability across AWS, Azure, and Google Cloud to capture mid-market buyers abandoning perpetual licenses. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation by legacy infrastructure providers seeking cloud-native capabilities. Long-term viability favors vendors with documented ransomware recovery case studies over feature-matrix superiority alone. Watch for inflection signals in cyber insurance policy language: when risk officers specify immutable storage as standard prerequisites, compliant platforms will command acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Architecture Engineering | Air-gapped recovery vaults satisfy HIPAA Security Rule exact-copy retrievability mandates for hospital networks. |
| Kubernetes-Native Backup Development | Unified container and VM protection eliminates operational sprawl for financial services platform engineering teams. |
| ISO 27001 Certification Investment | Validated immutability guarantees unlock federal and financial buyer segments with documented compliance requirements. |
| Channel Partnership Expansion | Clinical network penetration through VARs addresses mid-market healthcare providers with limited internal IT staffing. |
| Metallic SaaS Delivery Model | Subscription portability across hyperscalers captures buyers abandoning perpetual licenses for operational expenditure flexibility. |
Research Approach
SEC 10-K filings, hyperscaler capex disclosures, and hospital procurement databases formed the secondary backbone, supplemented by primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across VMware vSphere and Microsoft Hyper-V environments. Bottom-up sizing of VM backup deployment counts triangulated against top-down cloud storage revenue attribution to produce segment-level demand estimates.
Historical trendline analysis of cloud migration patterns and ransomware incident frequency informed the analytical framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, backup type granularity, and regional regulatory cluster. CAGRs were derived from curve-fitting observed adoption velocities against infrastructure investment cycles, with continuous data protection penetration and Kubernetes-native backup unification serving as key technology diffusion inputs.
Several conditions sit outside the modeled scope, including nation-state cyberattack escalation beyond current ransomware patterns and hyperscaler pricing regime shifts affecting egress economics. Forecasts reflect assumptions about regulatory enforcement continuity and cloud infrastructure availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Hard Disk Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Brazil Data Center Storage Market