
 Cloud Native Storage Market | 2026-2036
Cloud Native Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Native Storage Market Analysis
The gap between cloud-native and legacy storage architectures is narrowing as Kubernetes persistent volumes become the default abstraction for stateful container workloads. Amazon Web Services, Inc. leverages its S3 and EBS portfolio to dominate enterprise object and block storage migrations. Microsoft Corporation anchors hybrid scenarios through Azure Stack HCI integration with AKS persistent storage classes. Google LLC specializes in high-throughput file systems for AI training pipelines via its Cloud Filestore service.
Cloud native storage encompasses software-defined data persistence layers designed for container orchestration platforms, typically exposing APIs compatible with the Container Storage Interface specification for dynamic volume provisioning across clusters. These systems automate storage class selection, snapshot operations, and cross-zone replication to maintain application availability during node failures. Object storage leads technology adoption for unstructured data lakes and backup archives, while block storage commands premium positioning for database workloads requiring low-latency IOPS. Distributed file systems represent the fastest-expanding technology segment as generative AI training clusters demand parallel access to massive datasets across thousands of compute nodes.
FedRAMP authorization requirements shape procurement decisions for U.S. federal cloud storage contracts, while ISO 27001 certification governs data security expectations for European enterprise buyers. The EU AI Act introduces additional data governance obligations for storage systems processing training datasets for high-risk artificial intelligence applications. Enterprises must evaluate vendor CSI driver maturity, snapshot consistency guarantees, and cross-cloud portability before committing to platform-specific persistent storage architectures.
Market Dynamics
Kubernetes persistent volume abstraction is compressing the traditional storage procurement cycle, forcing infrastructure buyers to reevaluate SAN and NAS refresh timelines against software-defined alternatives.
Growth Catalysts
- FedRAMP Authorization:U.S. federal procurement mandates for sovereign cloud infrastructure accelerate vendor qualification cycles and expand addressable contract volume for compliant storage providers.
- Containerized Financial Workloads:Real-time analytics pipelines in banking and capital markets demand dynamic volume provisioning that legacy arrays cannot match.
- CSI Specification Maturity:The Container Storage Interface standard enables portable storage classes across multi-cloud deployments, reducing platform lock-in risk for enterprise buyers.
Market Restraints
- Silicon Supply Concentration:NAND flash fabrication concentrates in Taiwan and South Korea, exposing storage hardware margins to geopolitical disruption and foundry allocation constraints.
- EU AI Act Data Governance:Training dataset provenance requirements impose audit overhead on storage systems serving high-risk AI applications, extending sales cycles.
- Latency Floor in Object Stores:S3-compatible APIs cannot satisfy sub-millisecond database workloads, preserving niche demand for proprietary block arrays.
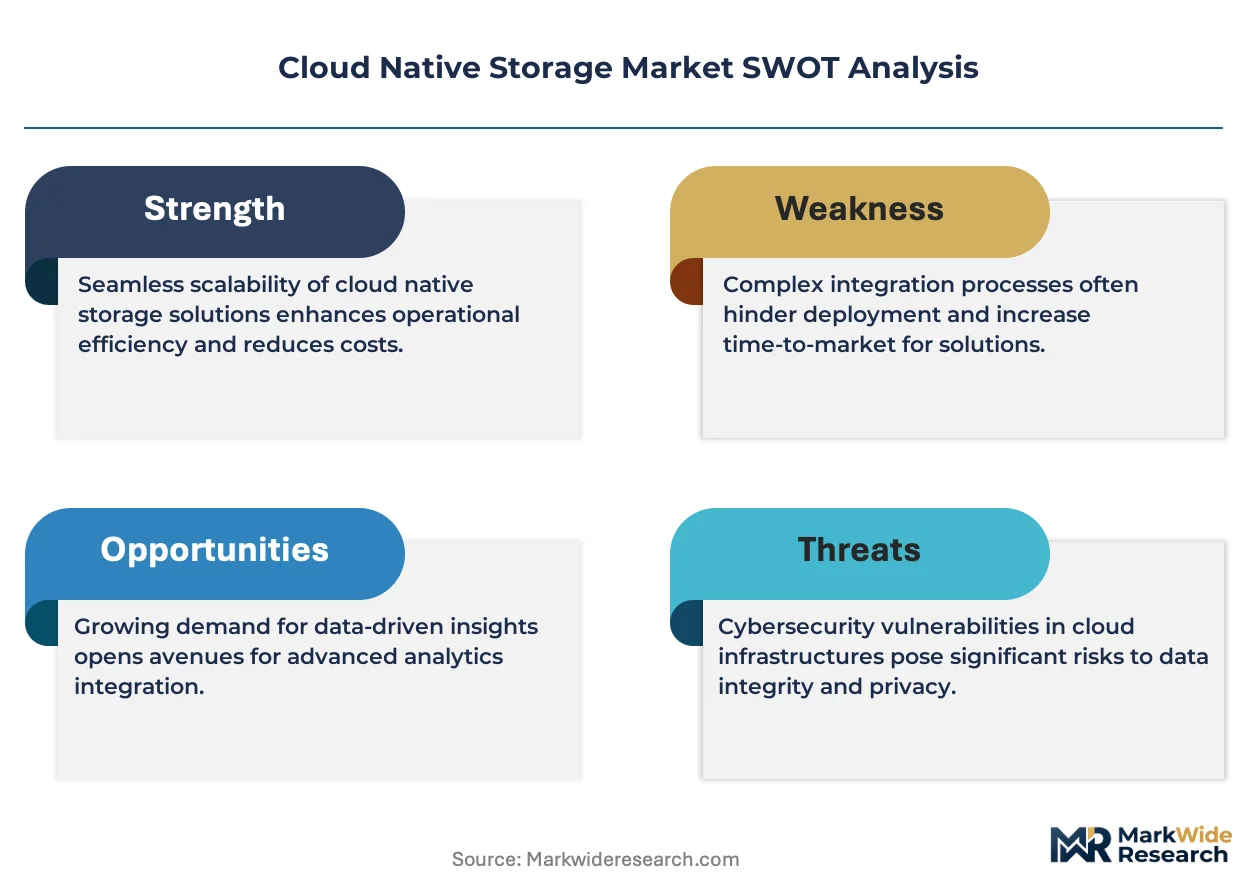
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor and server manufacturing create localized assembly opportunities for CSI driver-enabled storage appliances.
- AI Training Cluster File Systems:Parallel access architectures for generative AI workloads represent unmet demand as GPU clusters scale beyond single-node NVMe capacity.
- Edge-Native Persistence:5G MEC deployments require lightweight volume orchestration at cell tower density, opening distribution partnerships with telecom infrastructure vendors.
Industry Challenges
- Kubernetes Storage Architecture Expertise:Enterprise IT organizations lack sufficient Site Reliability Engineers capable of tuning storage classes for workload-specific performance profiles.
- Cross-Cloud Snapshot Consistency:Application-consistent backup across heterogeneous CSI implementations demands vendor-specific tooling that fragments operational playbooks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Native Storage Market |
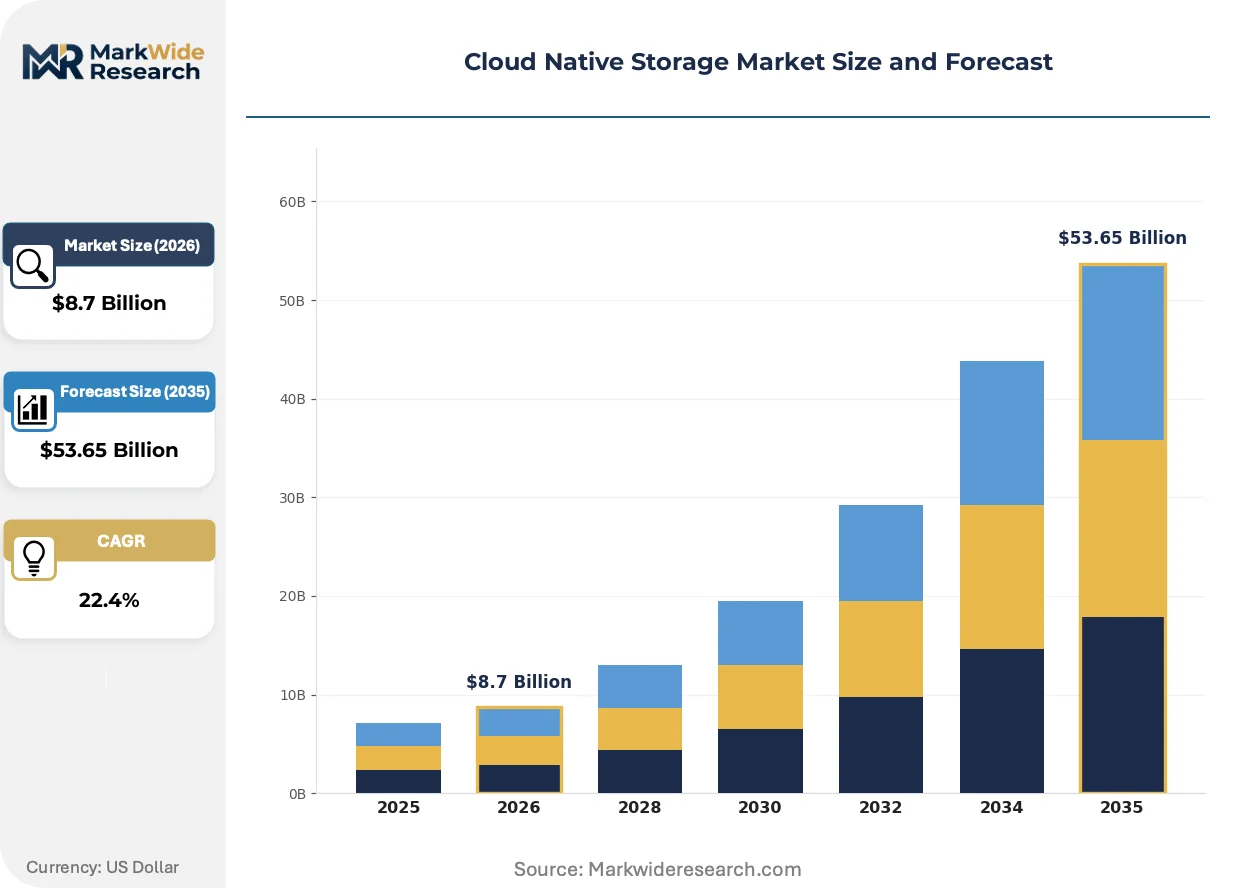
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: Block Storage, Object Storage, File Storage, Distributed File Systems End User: SMEs, Large Enterprises, Startups, Managed Service Providers Service Type: Backup & Recovery, Data Management, Disaster Recovery, Data Migration |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Alibaba Group Holding Limited, Huawei Technologies Co., Ltd., Citrix Systems, Inc., Rackspace Technology, Inc., Splunk, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Native Storage Market Emerging Trajectories
Storage abstraction layers are decoupling data persistence from physical infrastructure ownership, enabling consumption models that mirror compute elasticity rather than hardware depreciation cycles.
Erasure-coded object storage is migrating from archival cold tiers to active analytics workloads as query engines optimize for S3-select operations. Retail and media buyers now tier warm data directly into object pools, bypassing file system translation layers entirely. This compression of the storage hierarchy eliminates forklift migrations between performance tiers.
The EU AI Act mandates training dataset lineage documentation for high-risk artificial intelligence deployments. Storage vendors must embed immutable audit logs and cryptographic provenance chains into their metadata layers. European enterprise buyers now prioritize ISO 27001-certified object stores with native compliance tagging over generic hyperscaler offerings.
Enterprise procurement teams now require storage-as-code capabilities, rejecting GUI-driven provisioning in favor of Terraform and Ansible module integration. Systems integrators and value-added distributors lose margin to direct API consumption. This pattern concentrates in the United States, where DevOps maturity outpaces European and Asian enterprise adoption curves.
Cloud Native Storage Market Segmentation
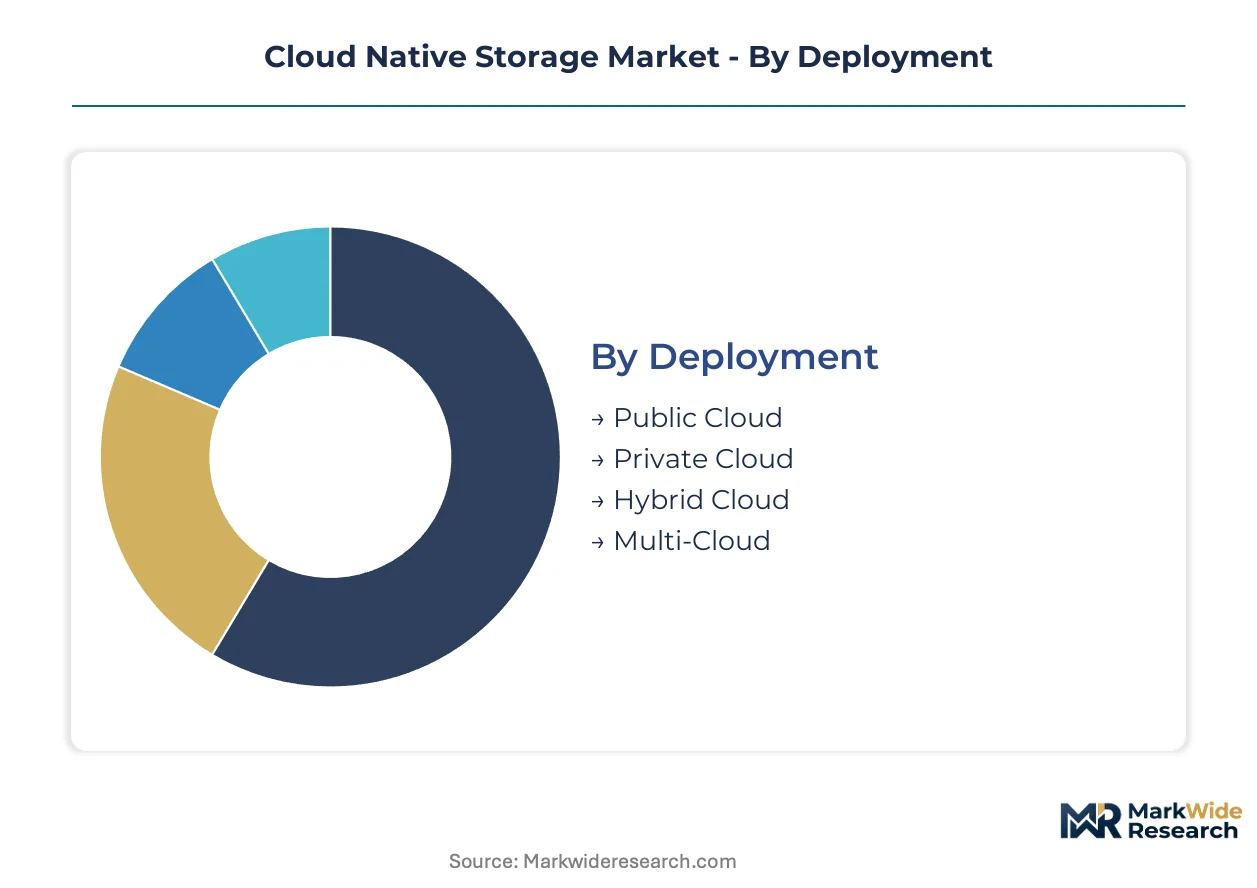
Cloud native storage procurement patterns diverge sharply across deployment models and workload architectures. Technology selection increasingly correlates with data gravity locations rather than legacy performance tiering.
Deployment:
Mature hyperscaler deployments coexist with emerging sovereign and edge-native configurations as data residency requirements proliferate.
- Public Cloud:Hyperscaler-managed persistent volumes dominate containerized workload migrations. Financial services firms in the United States concentrate procurement here for FedRAMP-authorized elastic block storage.
- Private Cloud:On-premises Kubernetes clusters with software-defined storage layers address latency-sensitive database workloads. German automotive manufacturers favor this model for industrial data sovereignty under GDPR.
- Hybrid Cloud:Unified storage classes span on-premises and hyperscaler infrastructure through consistent CSI implementations. Azure Stack HCI integration exemplifies this pattern for Microsoft-centric enterprises.
- Multi-Cloud:Portability-focused architectures avoid vendor-specific persistent volume lock-in. DevOps teams in India leverage this approach to arbitrage spot compute pricing across AWS, Azure, and GCP.
Public Cloud retains volume leadership; Multi-Cloud holds the steepest expansion curve.
Technology:
Cost tiering separates commodity object stores from premium block arrays and emerging parallel file systems.
- Block Storage:Low-latency IOPS provisioning for transactional databases and stateful microservices. PostgreSQL and MySQL operators in capital markets demand sub-millisecond response guarantees.
- Object Storage:Erasure-coded persistence for unstructured data lakes and backup archives. S3-compatible APIs now serve active analytics queries via select operations, displacing file translations.
- File Storage:POSIX-compliant shared volumes for legacy application lift-and-shift. NFS and SMB protocols persist in healthcare imaging and media rendering pipelines.
- Distributed File Systems:Parallel access architectures scale across thousands of GPU nodes for generative AI training. Lustre and WEKA implementations climb fastest as model parameter counts explode.
Object Storage retains volume leadership; Distributed File Systems hold the steepest expansion curve.
End User:
Customer type determines procurement sophistication and storage-as-code maturity thresholds.
- SMEs:Managed Kubernetes services with preconfigured storage classes reduce operational burden. Terraform module adoption lags behind larger counterparts.
- Large Enterprises:Dedicated Site Reliability Engineering teams tune CSI drivers for workload-specific performance profiles. FedRAMP and ISO 27001 compliance gate vendor selection.
- Startups:Cloud-native by default, these buyers prioritize API-driven provisioning and consumption-based pricing. European AI startups navigate EU AI Act training dataset lineage requirements.
- Managed Service Providers:Multi-tenant storage orchestration platforms aggregate demand across client portfolios. Indian MSPs leverage PLI scheme incentives for localized appliance assembly.
Large Enterprises retain volume leadership; Managed Service Providers hold the steepest expansion curve.
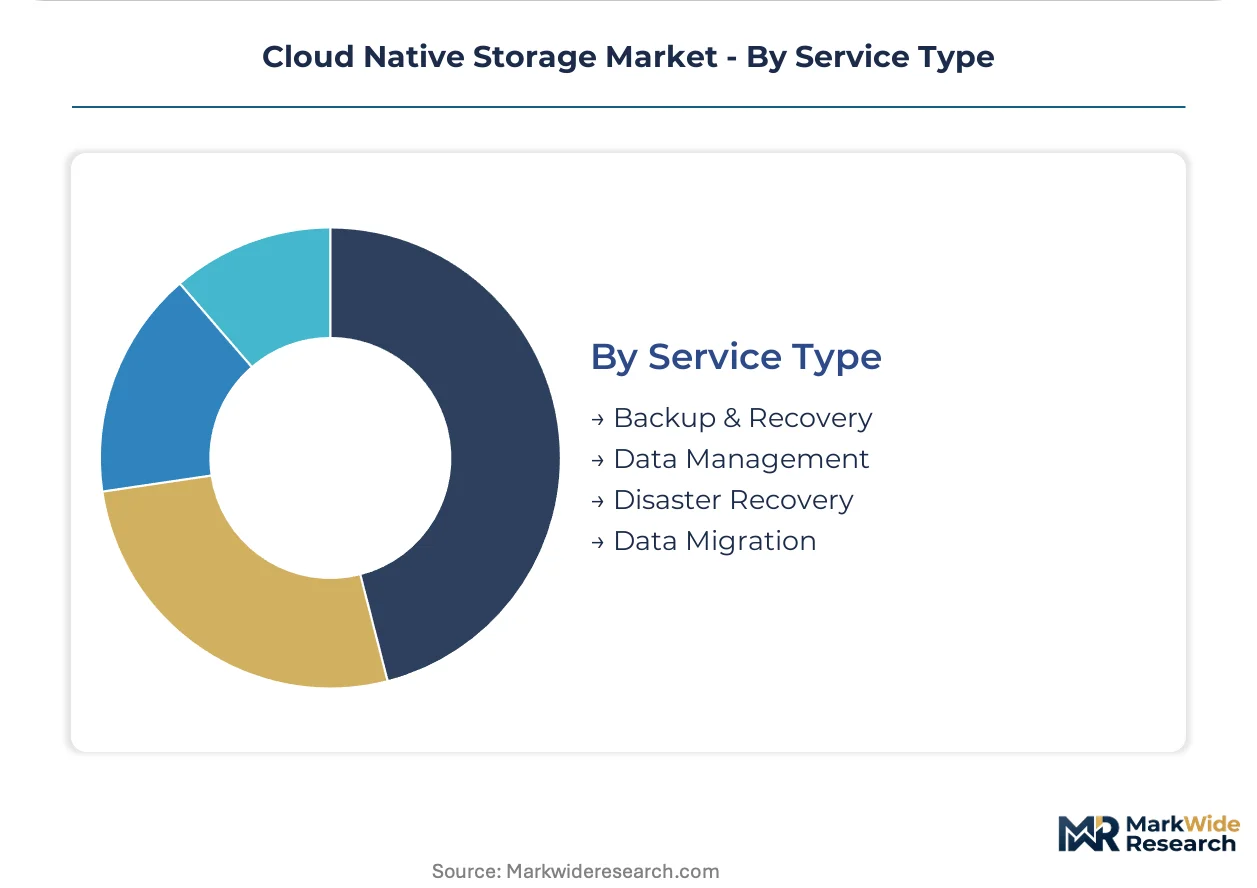
Service Type:
Application focus separates infrastructure-centric offerings from data governance and mobility services.
- Backup & Recovery:Application-consistent snapshots across heterogeneous CSI implementations demand vendor-specific tooling. Cross-cloud portability remains operationally fragmented.
- Data Management:Metadata-driven tiering and lifecycle policies automate cost optimization. Immutable audit logs satisfy EU AI Act provenance mandates for high-risk AI training data.
- Disaster Recovery:Cross-zone replication maintains availability during node failures. Synchronous replication for databases preserves RPO zero guarantees.
- Data Migration:CSI-agnostic volume portability reduces platform lock-in risk. Lift-and-shift operations accelerate legacy SAN and NAS displacement timelines.
Backup & Recovery retains volume leadership; Data Management holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud native storage infrastructure flows disproportionately toward economies with dense hyperscaler footprints and stringent data sovereignty mandates. Import dependency for NAND flash components shapes procurement strategies in markets lacking domestic semiconductor fabrication.
United States
FedRAMP-authorized elastic block storage dominates federal procurement pipelines. The Securities and Exchange Commission enforces data retention rules that accelerate CSI-compliant backup architecture deployments. Northern Virginia's Ashburn data center cluster hosts the densest concentration of Kubernetes-native persistent volume provisioning worldwide.
Germany
Automotive manufacturers demand on-premises software-defined storage layers for industrial data sovereignty. GDPR enforcement through the Federal Commissioner for Data Protection elevates ISO 27001 certification to a baseline vendor requirement. Bavaria's Munich-Stuttgart corridor anchors private cloud Kubernetes clusters serving precision engineering workloads.
China
Domestic cloud providers displace foreign hyperscalers in state-controlled sectors under MIIT localization directives. Dual carbon goals impose energy efficiency standards on data center storage infrastructure procurement. The Yangtze River Delta's Shanghai-Suzhou zone concentrates GPU training cluster deployments driving parallel file system demand.
India
Managed service providers aggregate multi-tenant storage demand across client portfolios at scale. The PLI scheme for semiconductor manufacturing creates localized assembly opportunities for CSI-enabled storage appliances. Karnataka's Bengaluru tech corridor hosts the highest density of DevOps teams arbitraging spot compute pricing across AWS, Azure, and GCP.
United Kingdom
Financial services firms in the City of London mandate cross-zone replication for disaster recovery compliance. The Financial Conduct Authority's operational resilience rules extend to cloud storage availability guarantees. The London-Southeast corridor dominates hybrid cloud Kubernetes deployments bridging on-premises and hyperscaler infrastructure.
Cloud Native Storage Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Hyperscalers leverage infrastructure scale to bundle storage with compute at marginal cost. Specialized software vendors compete on CSI driver maturity and snapshot consistency guarantees. Systems integrators face margin compression as enterprise buyers adopt direct API consumption. Dominant competitive moves include strategic partnerships with Kubernetes distribution vendors and geographic expansion through sovereign cloud certifications.
Among hyperscaler-based providers, Amazon Web Services, Inc., Microsoft Corporation, and Google LLC exemplify the scale-driven archetype. AWS represents the infrastructure-bundling model through S3 and EBS portfolio integration. Microsoft Corporation occupies a hybrid-cloud position via Azure Stack HCI persistence layers. Google LLC anchors high-throughput specialization for AI training pipelines. These three entities collectively define procurement benchmarks for enterprise container storage abstraction.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Alibaba Group Holding Limited |
| Huawei Technologies Co., Ltd. |
| Citrix Systems, Inc. |
| Rackspace Technology, Inc. |
| Splunk, Inc. |
| Others |
Supply Flow & Price Mechanics
Taiwanese NAND flash fabrication concentration exposes storage hardware margins to geopolitical disruption while simultaneously compressing pricing spreads between premium CSI-enabled arrays and commodity object storage tiers. This single-source dependency for critical controller silicon forces buyers into longer contract commitments that lock in tier boundaries.
Pricing Analysis
The generational pricing gap between NVMe-oF-enabled persistent volumes and legacy SATA-based CSI implementations spans three distinct performance tiers. Three-tier pricing structure across premium NVMe, standard SSD, and economy HDD-backed storage classes reflects IOPS guarantees and snapshot consistency SLAs rather than raw capacity. Cost compression in the economy tier is intensifying because hyperscalers bundle block storage at marginal compute rates. Managed service providers exhibit the highest price sensitivity, while capital markets database operators accept premium positioning for sub-millisecond latency guarantees.
Supply Chain Analysis
Contract manufacturing for CSI-enabled storage controllers concentrates at Foxconn and Pegatron facilities in Taiwan and Mexico. Component sourcing draws from South Korean NAND fabs, Japanese controller ASIC designers, and Malaysian PCB assembly operations. Single-source vulnerability in Taiwan Strait logistics corridors threatens just-in-time delivery windows for enterprise array refreshes. Distribution runs through value-added distributors and direct hyperscaler API consumption, with the latter gaining share in DevOps-mature accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud native storage represents an early-cycle infrastructure expansion where Kubernetes persistent volume penetration in legacy enterprise data centers remains below saturation thresholds. Containerized workload migration from SAN and NAS architectures provides the primary adoption tailwind.
For Market Incumbents: Harden CSI driver certification portfolios against emerging software-defined storage vendors by embedding immutable audit logging for EU AI Act compliance. Prioritize backward integration into NAND flash controller design to offset foundry allocation constraints. Defensive patent positioning around cross-cloud snapshot consistency APIs preserves margin in multi-cloud deployments.
For New Entrants and Emerging Players: Establish a beachhead in Indian MSP aggregation platforms where PLI scheme incentives lower appliance assembly costs. Target edge-native persistence for 5G MEC deployments at cell tower density, bypassing hyperscaler-dominated core markets. Lead with Terraform-native provisioning modules that bypass GUI-driven incumbent workflows.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated software vendors with mature CSI implementations over pure-play hardware OEMs. Long-term viability hinges on cross-cloud portability rather than single-platform optimization. Monitor FedRAMP authorization queue velocity as an inflection indicator for federal contract flow.
| Strategic Initiative | Industry Significance |
|---|---|
| CSI Driver Certification Expansion | FedRAMP and ISO 27001 credentials unlock sovereign cloud procurement pipelines in the United States and Germany. |
| Strategic Partnership with Kubernetes Distributors | Red Hat OpenShift and VMware Tanzu integration embeds persistent storage classes into platform-default configurations. |
| Acquisition of Specialist Firm | Parallel file system expertise accelerates AI training cluster positioning against Lustre and WEKA implementations. |
| Geographic Expansion | Indian PLI scheme localization reduces landed cost for MSP appliance assembly serving South Asian demand. |
| Platform Integration | Azure Stack HCI persistence layer anchoring captures hybrid cloud Kubernetes migrations in Microsoft-centric enterprises. |
Methodological Framework
Cross-validation between primary field interviews with storage architects and secondary validation through hyperscaler capex disclosures anchors the qualitative findings. Platform engineers, IT procurement officers, CSI driver maintainers, and DevOps team leads provided operational perspective on persistent volume provisioning patterns. SEC filings, Kubernetes community contribution metrics, and FedRAMP authorization databases supplied quantitative benchmarks. Bottom-up cluster deployment estimates and top-down infrastructure spend analysis were reconciled through iterative triangulation.
Calibration against historical adoption curves for software-defined storage and container orchestration platforms shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, storage technology tier, end-user scale, and service type, with regional regulatory intensity as an overlay factor. CAGRs were derived from elasticity-adjusted penetration rates and infrastructure replacement cycle timing. GPU cluster scaling trajectories and FedRAMP authorization pipeline velocity served as industry-specific forecast inputs.
Stress conditions across NAND flash supply disruption, Kubernetes version deprecation cycles, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding CSI specification maturity and hyperscaler pricing discipline. Quarterly review of FedRAMP authorization queue depth, GPU cluster deployment announcements, and PLI scheme incentive allocation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Storage in Big Data Market