
 Cloud Object Storage Solutions Market | 2026-2036
Cloud Object Storage Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Object Storage Solutions Market Outlook
The pool of certified cloud infrastructure architects is collapsing across North America and Western Europe, constraining enterprise migration timelines and inflating implementation costs. Amazon Web Services leverages its pioneering S3 protocol ecosystem to dominate object storage primitives. Microsoft Azure anchors hybrid deployments through deep Active Directory integration. Google Cloud specializes in analytics-optimized storage tiers for media and AI workloads.
Cloud object storage denotes a flat-address data architecture where discrete units called objects combine raw data, metadata, and unique identifiers within a single namespace, typically accessed via RESTful APIs over HTTP. This design eliminates hierarchical file system limitations and enables exabyte-scale horizontal scaling across distributed server clusters. Public cloud deployment captures the dominant revenue share as hyperscalers amortize infrastructure across millions of tenants. Hybrid cloud configurations represent the fastest-expanding segment as regulated industries demand on-premises sovereignty with burst elasticity. Media hosting and content delivery services concentrate margin pools where low-latency edge replication commands premium pricing.
FDA 21 CFR Part 11, HIPAA Security Rule, and EU GDPR shape healthcare and cross-border data governance requirements, compelling vendors to certify encryption, audit logging, and geographic data residency controls. The SEC's cybersecurity disclosure rules for public companies further tighten accountability for stored financial records. Stakeholders must evaluate sovereign cloud certifications and data localization statutes before committing to multi-tenancy architectures.
Market Dynamics
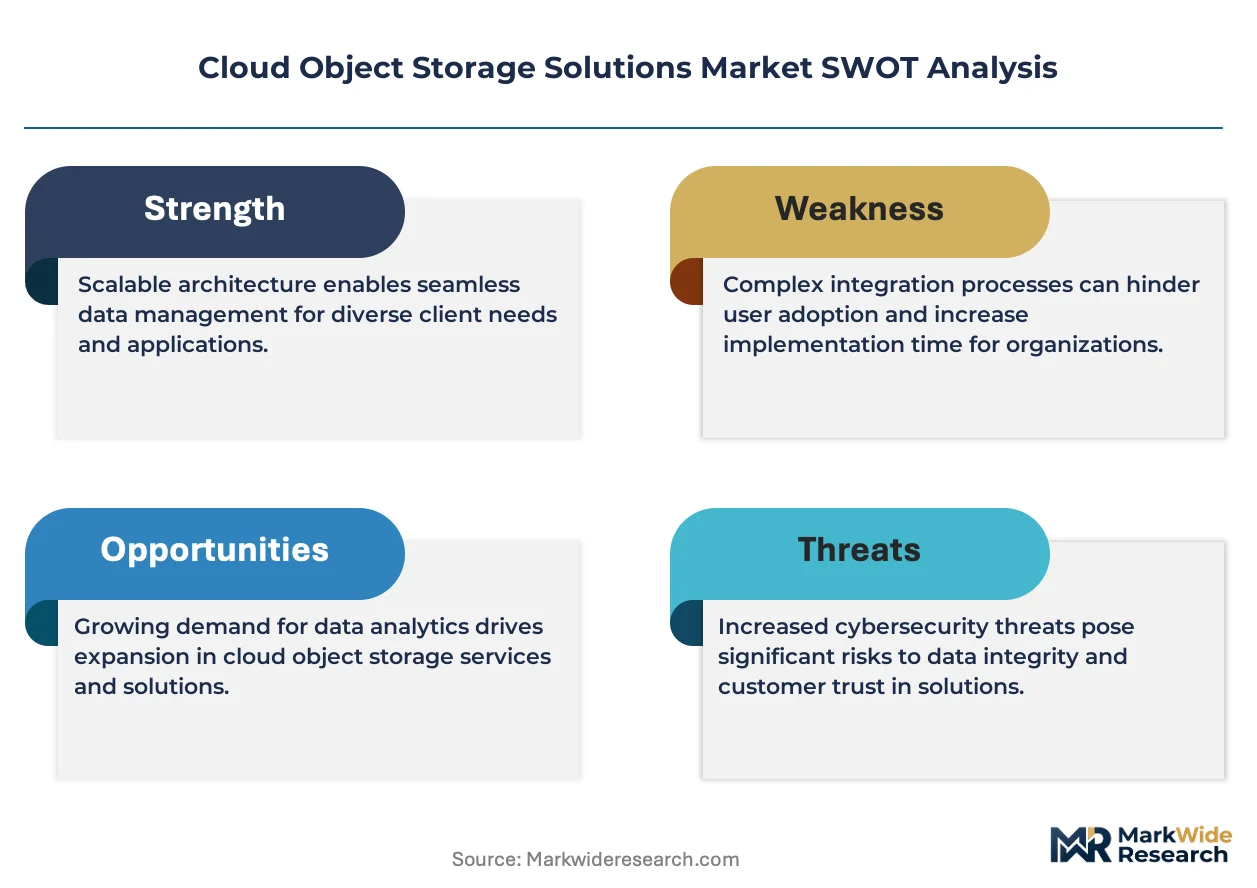
Enterprise data sovereignty mandates are fragmenting cloud infrastructure procurement, compelling vendors to deploy region-locked storage clusters that sacrifice economies of scale for compliance assurance.
Growth Catalysts
- EU AI Act data residency rules:Healthcare providers in Germany and France must localize AI training datasets, accelerating sovereign cloud deployments for imaging archives.
- Media streaming bit-rate escalation:4K and 8K content pipelines demand exabyte-scale object storage with edge replication, pulling investment into low-latency tiered architectures.
- SEC cybersecurity disclosure mandates:Public companies face audit-ready logging requirements, expanding demand for immutable object storage with cryptographic verification chains.
Market Restraints
- Certified architect scarcity:The collapsing pool of cloud infrastructure specialists in North America and Western Europe inflates implementation timelines and labor costs.
- Encryption key management complexity:Customer-managed keys for HIPAA and GDPR compliance introduce operational friction that slows enterprise migration velocity.
- On-premises hardware refresh cycles:Hybrid cloud deployments require synchronized capital expenditure across server, networking, and storage layers.
Strategic Opportunities
- India's data localization framework:The country's digital sovereignty push creates demand for in-country object storage infrastructure serving financial services and government sectors.
- AI-optimized storage tier convergence:GPU-direct storage protocols merged with object APIs enable high-throughput model training without file system translation overhead.
- Carbon-aware workload scheduling:Renewable-energy-matched storage operations attract sustainability-mandated enterprises in Nordic markets.
Industry Challenges
- Multi-cloud orchestration expertise gap:Enterprises lack personnel capable of managing data placement policies across heterogeneous storage APIs.
- Legacy tape archive integration:Cold data migration from robotic tape libraries to object storage requires custom middleware development.
- Cross-border litigation discovery:Conflicting GDPR right-to-erasure and US legal hold requirements complicate global data governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Object Storage Solutions Market |
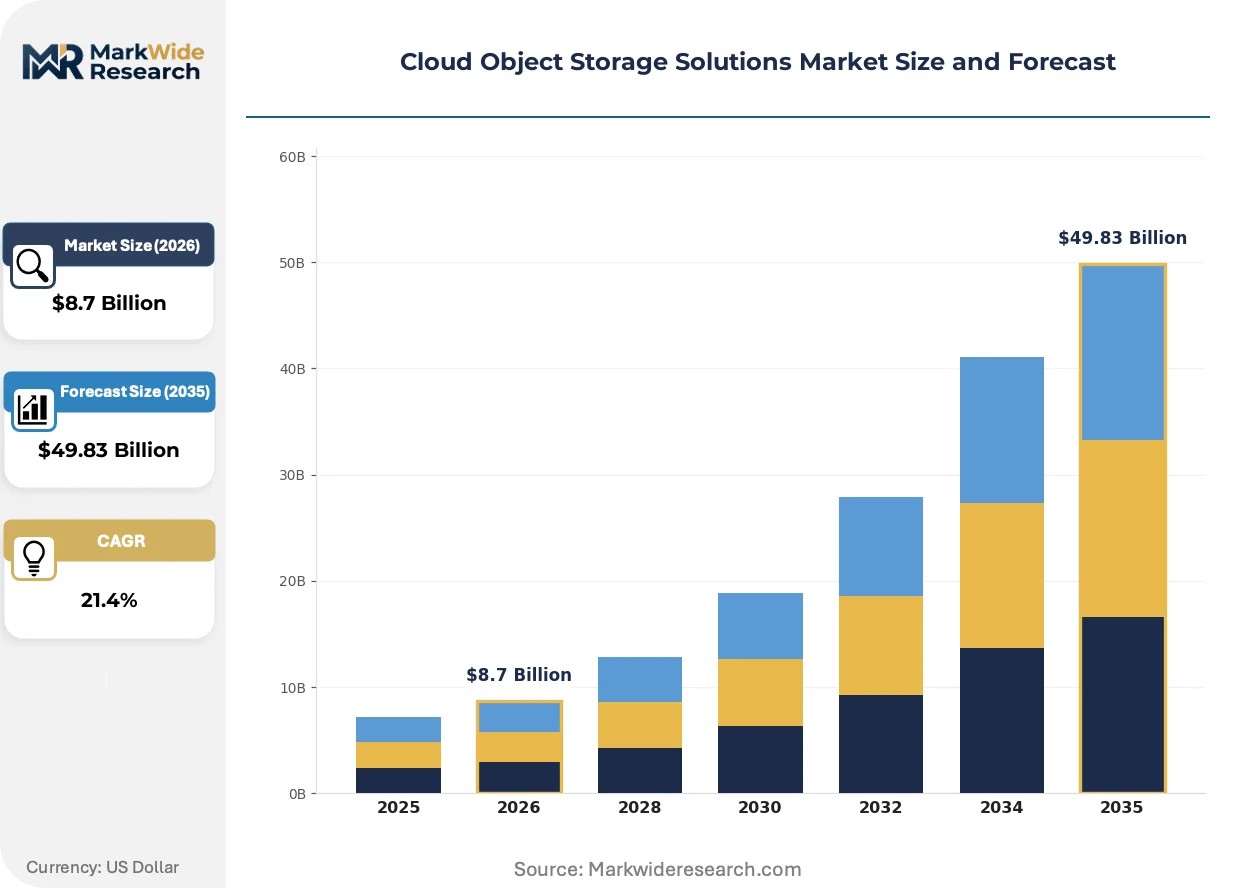
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $49.83 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Backup Solutions, Data Archiving, Content Delivery, Media Hosting End User: E-Commerce, Media & Entertainment, Healthcare, Government Integration Level: API Integration, SaaS Compatibility, On-Premises Sync, Third-Party Tools |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Cloud, Oracle Cloud, Alibaba Cloud, Hewlett Packard Enterprise, NetApp, Wasabi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Object Storage Solutions Market Strategic Shifts
Storage architectures are pivoting from capacity-centric designs to compliance-embedded systems where data placement logic encodes regulatory boundaries. This shift redefines vendor competitive advantage around certification depth rather than raw price-per-gigabyte.
Immutable object storage with write-once-read-many enforcement is displacing traditional backup software stacks in regulated industries. Financial services firms in Switzerland and asset managers in Luxembourg are adopting these architectures for ransomware resilience. The technology is displacing three-tier backup infrastructure by collapsing primary, secondary, and archival tiers into a single namespace with policy-driven lifecycle automation.
The EU AI Act's training data documentation requirements are forcing storage vendors to embed lineage tracking and provenance logging at the object metadata layer. This compels engineering investment in cryptographic attestation chains. Healthcare AI developers in France and diagnostic imaging consortiums in Germany face the steepest compliance ramps, driving early adoption of certified sovereign storage clusters.
Consumption-based billing for egress and API operations is compressing procurement cycles from annual capacity planning to monthly workload optimization. Media production houses and gaming studios in California are unbundling storage from compute commitments, selecting providers through benchmark-driven competitive trials. This pattern is most visible in creative industries where unpredictable burst workloads resist traditional reserved-capacity models.
Cloud Object Storage Solutions Market Segmentation
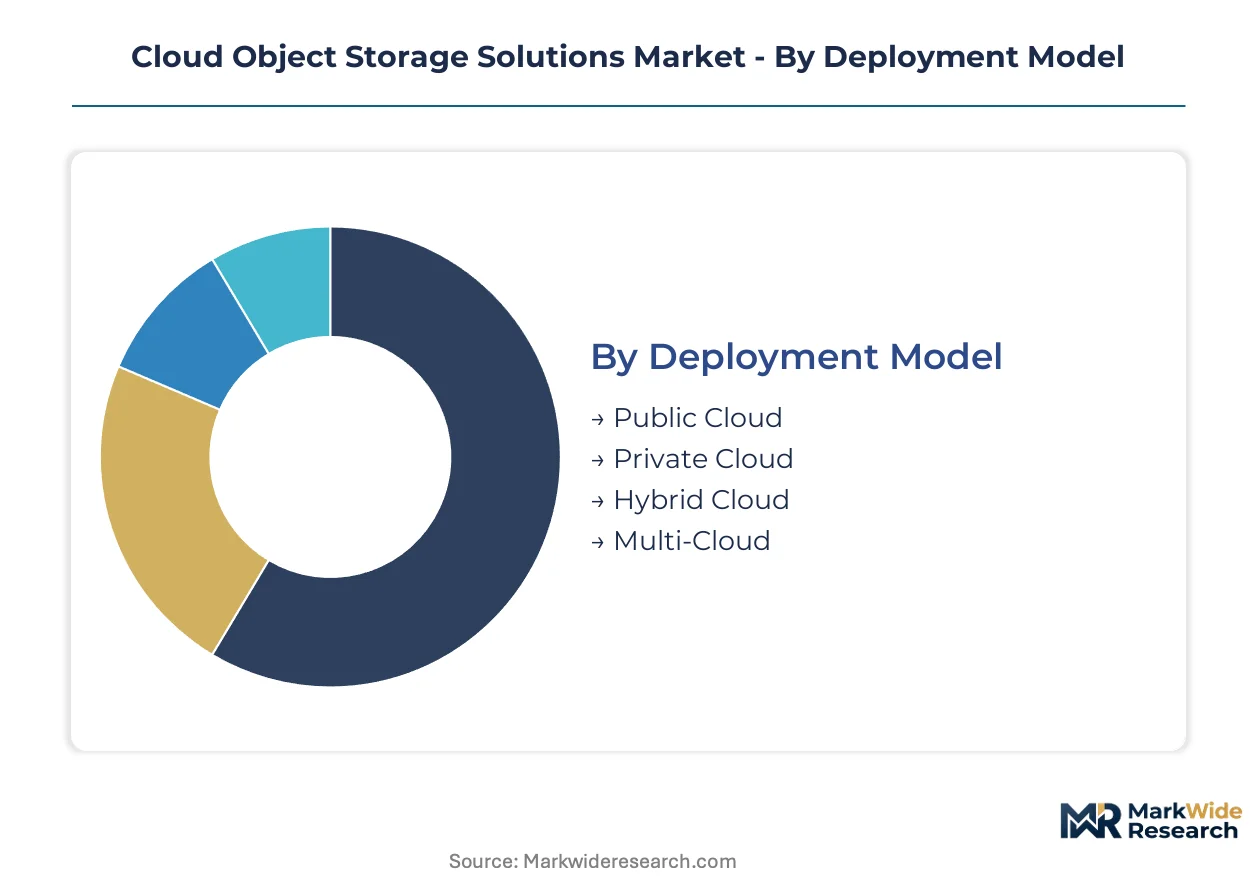
Cloud object storage procurement fragments across four critical dimensions: deployment sovereignty, service specialization, vertical compliance requirements, and integration architecture. Each axis carries distinct margin profiles and vendor competitive dynamics.
Deployment Model:
Margin pools concentrate where regulatory friction forces premium pricing for sovereignty guarantees.
- Public Cloud:Hyperscalers amortize infrastructure across millions of tenants, delivering the lowest unit economics. Healthcare providers in Germany and France are migrating imaging archives here despite GDPR residency requirements, driven by burst elasticity needs for AI training pipelines.
- Hybrid Cloud:Regulated industries demand on-premises sovereignty with cloud burst capacity, commanding 40-60% pricing premiums over pure public deployments. Financial services firms in Switzerland and asset managers in Luxembourg anchor this segment for ransomware resilience through immutable storage tiers.
- Private Cloud:Single-tenant dedicated infrastructure serves defense contractors and intelligence agencies with air-gapped security requirements.
- Multi-Cloud:Orchestration across heterogeneous APIs mitigates vendor lock-in for enterprises with geographic dispersion mandates.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest.
Service Type:
Application-specific workloads reshape vendor specialization and pricing power.
- Content Delivery:Low-latency edge replication commands premium pricing from media streaming platforms. 4K and 8K bit-rate escalation in California production houses pulls investment into tiered architectures with geographic proximity optimization.
- Media Hosting:Unpredictable burst workloads resist reserved-capacity models, driving consumption-based billing adoption. Gaming studios benchmark providers through competitive trials rather than annual commitments.
- Backup Solutions:Immutable write-once-read-many enforcement displaces three-tier backup infrastructure in regulated sectors.
- Data Archiving:Long-term retention for compliance faces migration friction from legacy tape libraries requiring custom middleware.
Content Delivery captures the highest margin concentration, with Media Hosting expanding most quickly as creative industries unbundle storage from compute.
End User:
Vertical compliance requirements segment pricing tiers by certification depth rather than raw capacity.
- Healthcare:FDA 21 CFR Part 11 and HIPAA Security Rule mandates compel encryption, audit logging, and geographic residency controls. German diagnostic imaging consortiums face steep EU AI Act compliance ramps for training data documentation.
- Government:Sovereign cloud certifications and data localization statutes dominate procurement criteria. India's digital sovereignty push creates demand for in-country infrastructure serving financial services and public sectors.
- Media & Entertainment:Burst workload unpredictability favors unbundled procurement with benchmark-driven provider selection.
- E-Commerce:Transaction volume scaling demands API-optimized storage with low-latency consistency guarantees.
Healthcare holds the largest revenue pool, while Government is climbing the fastest on sovereignty mandate acceleration.
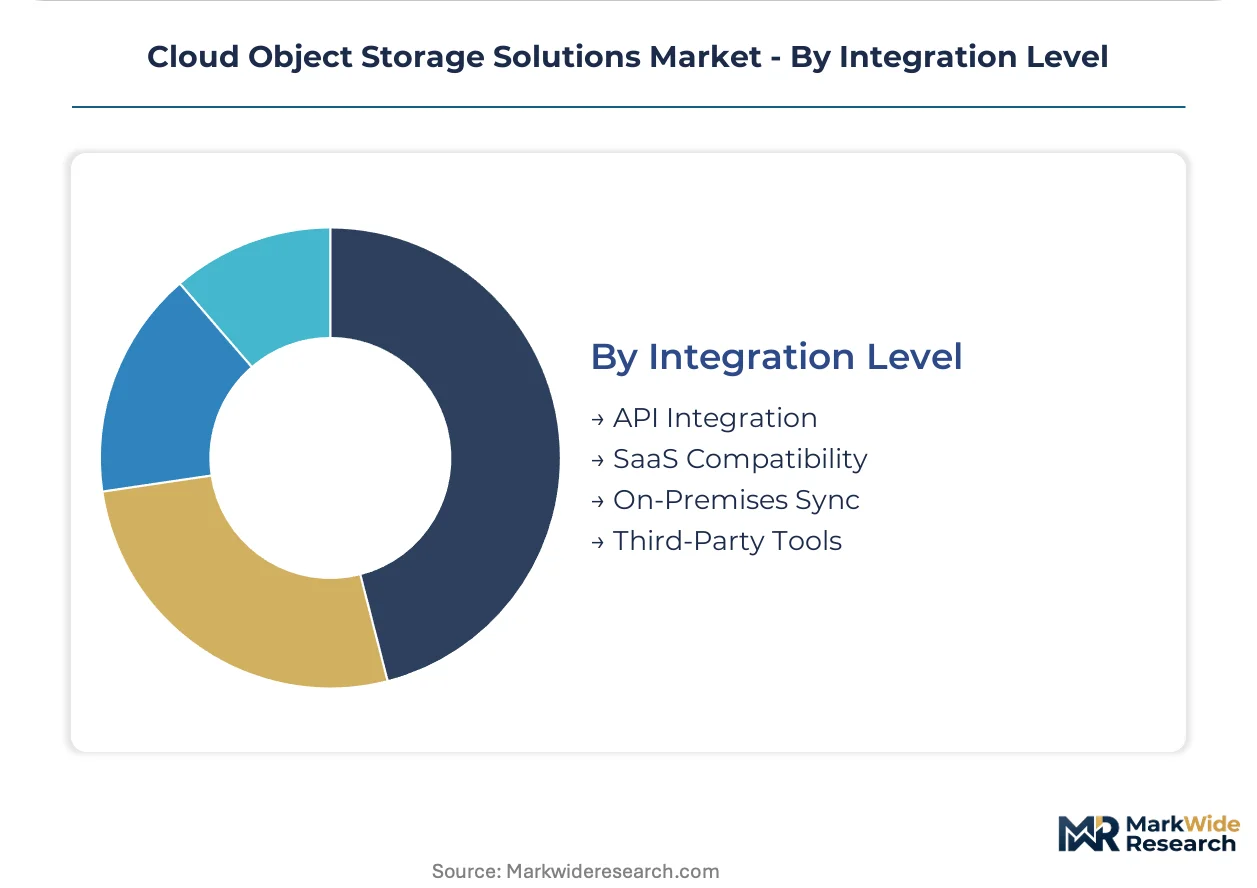
Integration Level:
Technical architecture choices determine migration velocity and operational friction.
- API Integration:RESTful HTTP access enables exabyte-scale horizontal scaling across distributed clusters. GPU-direct storage protocols merged with object APIs now enable high-throughput AI model training without file system translation overhead.
- SaaS Compatibility:Native integration with productivity and analytics platforms accelerates enterprise adoption timelines.
- On-Premises Sync:Hybrid configurations require synchronized capital expenditure across server, networking, and storage layers.
- Third-Party Tools:Custom middleware development bridges legacy tape archive migrations and multi-cloud orchestration gaps.
API Integration dominates deployment preferences, with SaaS Compatibility gaining share fastest as enterprises prioritize native platform connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German healthcare providers deploy sovereign storage clusters for AI training datasets under EU AI Act mandates, while California media studios prioritize burst-elasticity pricing over data residency controls.
United States
SEC cybersecurity disclosure rules compel public companies to adopt immutable object storage with cryptographic verification chains. Financial services firms in New York and asset managers in Connecticut anchor demand for audit-ready logging architectures. Media production houses in Los Angeles benchmark providers through competitive trials for 4K and 8K content pipelines.
Germany
Diagnostic imaging consortiums in Bavaria face steep compliance ramps for EU AI Act training data documentation requirements. GDPR residency controls accelerate sovereign cloud deployments for healthcare AI developers. Frankfurt's financial district drives demand for ransomware-resilient immutable storage tiers.
France
CNIL enforcement actions tighten geographic data residency specifications for cross-border healthcare archives. AI developers in Paris medical research clusters adopt certified sovereign storage for imaging dataset localization. The Île-de-France region concentrates procurement for compliance-embedded storage architectures.
United Kingdom
Post-Brexit data adequacy negotiations fragment cloud procurement toward UK-resident storage clusters. London's asset management sector demands immutable archives for SEC-aligned disclosure mandates. Cambridge AI research groups require lineage-tracking metadata layers for training data provenance.
India
RBI data localization directives and the country's digital sovereignty framework create demand for in-country object storage infrastructure. Financial services firms in Mumbai and government agencies in Delhi-NCR prioritize localized storage clusters. Karnataka's technology corridor drives adoption for sovereign cloud certifications.
Cloud Object Storage Solutions Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in cloud object storage. Hyperscalers amortize infrastructure across millions of tenants, delivering lowest unit economics through scale. Independent software vendors and regional cloud operators occupy mid-market positions with compliance-focused specialization. Dominant competitive moves include sovereign cloud certification investments and GPU-direct storage protocol development for AI workloads.
Within the hyperscaler tier, Amazon Web Services exemplifies scale-driven infrastructure amortization, while Microsoft Azure anchors hybrid deployment architectures through enterprise directory integration. Wasabi Technologies occupies a position among cost-optimized specialists challenging incumbent pricing models for media archiving workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Cloud |
| Oracle Cloud |
| Alibaba Cloud |
| Hewlett Packard Enterprise |
| NetApp |
| Wasabi Technologies |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day provisioning cycles for sovereign cloud infrastructure anchor pricing power to regional certification depth rather than raw capacity scale. This lead-time band concentrates margin capture with vendors holding EU AI Act and GDPR attestations, while hyperscalers amortize standardized tiers across millions of tenants.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement, with annual reserved capacity commitments commanding 25-40% discounts against consumption-based spot pricing. Price differentiation rests on certification grade—sovereign cloud attestations for EU AI Act compliance extract 40-60% premiums over standard tiers—and volume scale, where petabyte-scale anchors secure custom rate cards. Pricing pressure stems from Wasabi Technologies and cost-optimized specialists undercutting incumbent storage rates for media archiving workloads. Gaming studios and California production houses exhibit highest price sensitivity, benchmarking providers through competitive trials rather than multi-year commitments.
Supply Chain Analysis
Ninety-day lead times for GPU-direct storage hardware concentrate supply chain risk in Taiwan, South Korea, and the United States, where NVIDIA and AMD accelerator fabrication anchors. Raw material dependencies span advanced memory modules, high-bandwidth interconnects, and specialized cooling substrates. Single-source vulnerability in sovereign cloud certification auditing—where only three accredited bodies serve EU healthcare deployments—creates procurement chokepoints. Distribution runs through hyperscaler direct sales for public cloud, systems integrators for hybrid configurations, and regional operators for private sovereign clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat. Switching costs compound as enterprises embed compliance documentation and lineage tracking into operational workflows, raising exit barriers.
For Market Incumbents: Compound certification depth through EU AI Act sovereign cloud attestations and GPU-direct storage protocol development. Threats from Wasabi Technologies and cost-optimized specialists intensify margin pressure in media archiving tiers. Capacity addition in Germany and France secures healthcare AI training dataset localization mandates. Channel control through systems integrator certification programs reinforces hybrid deployment capture.
For New Entrants and Emerging Players: Carbon-aware workload scheduling gaps expose under-served Nordic sustainability-mandated enterprises. India's data localization framework presents the most penetrable geography, with RBI directives forcing in-country infrastructure buildout. Go-to-market through sovereign cloud certification partnerships with Mumbai financial services firms accelerates reference architecture validation.
For Investors and Strategic Acquirers: Carve-out targets emerge from hyperscaler cloud divisions seeking compliance-specialist tuck-ins for EU healthcare verticals. Long-term viability centers on AI-optimized storage tier convergence and immutable archive displacement of legacy backup stacks. Watch for SEC cybersecurity disclosure enforcement acceleration as inflection signal for immutable object storage demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | EU AI Act mandates force German healthcare providers toward attested storage clusters. |
| GPU-Direct Storage Protocol Development | High-throughput AI model training without file system translation overhead attracts Paris research clusters. |
| Immutable Archive Tier Launch | Write-once-read-many enforcement displaces three-tier backup in Swiss financial services. |
| Carbon-Aware Workload Scheduling | Renewable-energy-matched operations capture Nordic sustainability-mandated enterprise procurement. |
| Regional Edge Replication Expansion | Low-latency tiered architectures command premium pricing from California 4K and 8K production houses. |
Study Parameters
The analysis maps public cloud, hybrid cloud, private cloud, and multi-cloud deployment models, each validated through cloud infrastructure architects, healthcare IT procurement officers, financial services compliance leads, and media production technology directors. Primary interviews with hyperscaler solution engineers and sovereign cloud operators combined with secondary validation against SEC cybersecurity disclosure filings, EU AI Act regulatory texts, GDPR enforcement actions, and hyperscaler capex disclosures. Bottom-up sizing across storage capacity tiers and top-down triangulation against aggregate infrastructure spending anchored volume estimates.
Consistency checks against external benchmarks validated projections across the modeling period. Segmentation dimensions modeled include deployment sovereignty, service specialization, vertical compliance requirements, and integration architecture complexity. CAGRs derived from regression analysis of historical capacity deployment patterns and forward-looking regulatory mandate timelines. Industry-specific inputs incorporated GPU-direct storage adoption curves and immutable archive displacement rates in regulated sectors.
Underlying assumptions cover sustained EU AI Act enforcement intensity, continued SEC cybersecurity disclosure rule expansion, and stable hyperscaler infrastructure amortization efficiency, with deviation risk concentrated in sovereign cloud certification body capacity constraints and cross-border data adequacy negotiation outcomes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Cloud Storage Market