
 Thailand Data Center Storage Market | 2026-2036
Thailand Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Storage Market Insights
Direct sales channels between storage vendors and Thai enterprise buyers is narrowing as local systems integrators consolidate procurement relationships. Dell Inc. leverages its established server-storage bundling to dominate mid-market deployments across Bangkok and Eastern Economic Corridor zones. Huawei Technologies Co., Ltd. competes aggressively on all-flash array pricing while navigating national security screening protocols. Western Digital Corporation anchors the hard disk drive supply tier for hyperscale builds, sustaining volume through captive manufacturing relationships.
Data center storage encompasses electromechanical and solid-state devices engineered for persistent digital retention, with capacities spanning terabyte-scale HDDs to petabyte-class NVMe flash arrays operating at sub-millisecond latency. These systems serve as the foundational substrate for enterprise databases, virtualization platforms, and cloud-native workloads across Thailand's digitizing economy. Cloud Storage deployments are expanding fastest among Thai enterprises pursuing hybrid infrastructure models, while Storage Area Network retains the largest installed base in legacy financial data halls. SSD technology commands premium positioning for latency-sensitive workloads, whereas HDD sustains cost-archival dominance in government and telecom backup tiers.
Thailand's Personal Data Protection Act and NBTC telecommunications licensing framework impose data sovereignty and encryption standards that filter vendor eligibility and product certification requirements. BIS-equivalent testing protocols for electromagnetic compatibility add compliance layers to imported storage hardware. Stakeholders must weigh localization mandates against total cost of ownership as Thai regulators tighten cross-border data flow restrictions.
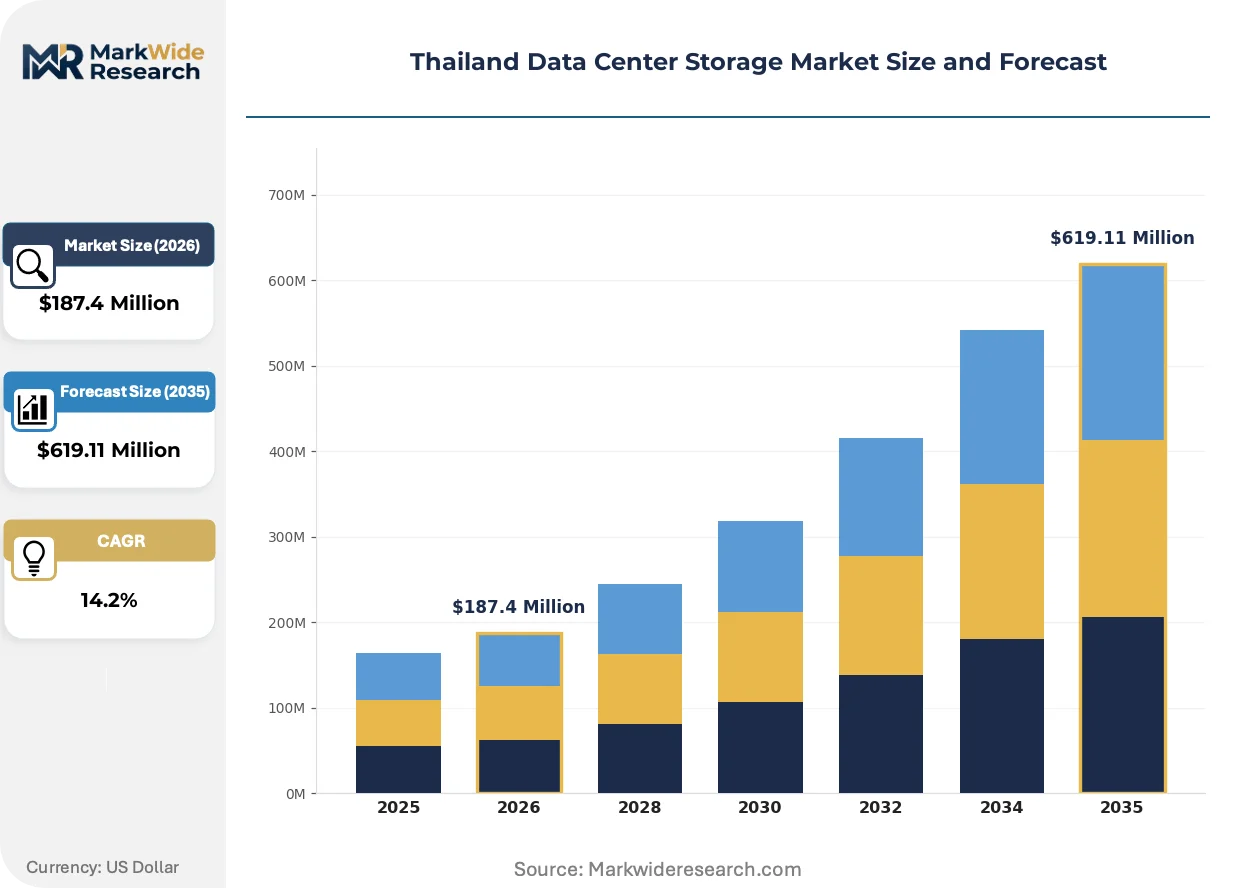
Market Dynamics
Thai financial institutions are consolidating data center footprints while simultaneously expanding storage capacity for real-time transaction processing, creating bifurcated demand between hyperscale consolidation and edge-distributed retention nodes.
Growth Catalysts
- PDPA Compliance Mandates:Thailand's Personal Data Protection Act requires encrypted, sovereign data retention, forcing enterprise upgrades to certified storage systems with hardware-level encryption capabilities.
- Banking Digitalization:Thai banks are deploying petabyte-scale all-flash arrays to support instant payment platforms and mobile banking transaction logs with sub-millisecond query response.
- Eastern Economic Corridor Buildouts:Government incentives for data center zones in Chonburi and Rayong provinces are attracting hyperscale operators requiring massive HDD and SSD procurement.
Market Restraints
- NAND Flash Supply Concentration:Thailand relies on imported flash memory from concentrated East Asian foundry sources, exposing procurement to geopolitical supply disruptions and freight cost volatility.
- NBTC Licensing Friction:Telecommunications storage equipment approvals under National Broadcasting and Telecommunications Commission protocols add 4-6 month certification delays for non-domestic vendors.
- Magnetic Tape Substitution:Cold archival tiers in government and telecom sectors are migrating to tape libraries for exabyte-scale retention, compressing addressable HDD volume in price-sensitive segments.
Strategic Opportunities
- Chiang Mai-Phuket Secondary Hubs:Disaster recovery and latency-sensitive edge deployments are creating storage demand outside Bangkok's saturated primary market.
- AI/ML Training Clusters:Convergence of GPU compute infrastructure with high-throughput NVMe storage is opening specialized deployment opportunities for low-latitude inference workloads.
- BOI Incentive Alignment:Thailand's Board of Investment tax holidays for data center construction are accelerating greenfield builds requiring full storage stack provisioning.
Industry Challenges
- Enterprise Storage Architecture Expertise:Thai systems integrators face acute shortages of certified engineers for NVMe-over-Fabrics and software-defined storage deployment.
- Legacy SAN Integration Complexity:Financial institutions running 15-year-old Fibre Channel infrastructure require costly bridge architectures to adopt modern flash arrays without forklift replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Storage Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Cloud Storage Technology: SAN, NAS, SSD, HDD End User: BFSI, Government, Healthcare, Telecom Deployment: On-Premise, Off-Premise, Hybrid, Colocation |
| Companies Covered | Huawei Technologies Co., Ltd., NetApp, Inc., Dell Inc., Lenovo Group Ltd., Hewlett Packard Enterprise Co., Seagate Technology LLC, Western Digital Corporation, Kingston Technology Company Inc., Fujitsu Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Storage Market Trends and Innovations
Storage architectures across Thailand are fragmenting between performance-optimized flash tiers for transactional workloads and capacity-optimized object storage for unstructured data lakes, with software abstraction layers unifying heterogeneous hardware.
Computational storage drives with embedded processing capability are digitizing data reduction and encryption operations at the device level. Thai cloud service providers are piloting these drives in video analytics and genomics pipelines to minimize host CPU overhead. This compression of processing latency is digitizing the economics of edge deployments previously constrained by backhaul bandwidth costs.
Thailand's Personal Data Protection Act enforcement guidelines are mandating data residency attestations and breach notification protocols with 72-hour windows. Storage vendors must now embed immutable snapshot capabilities and geo-fencing controls as standard features rather than premium add-ons. Financial services and healthcare verticals are driving compliance-certified product development roadmaps.
Enterprise buyers in Bangkok are consolidating procurement through managed service contracts that bundle storage hardware, maintenance, and capacity scaling into per-terabyte monthly fees. Systems integrators are displacing direct vendor relationships as the primary contracting interface. This preference for operational expenditure treatment is most visible among mid-market enterprises lacking dedicated storage administration functions.
Thailand Data Center Storage Market Segmentation
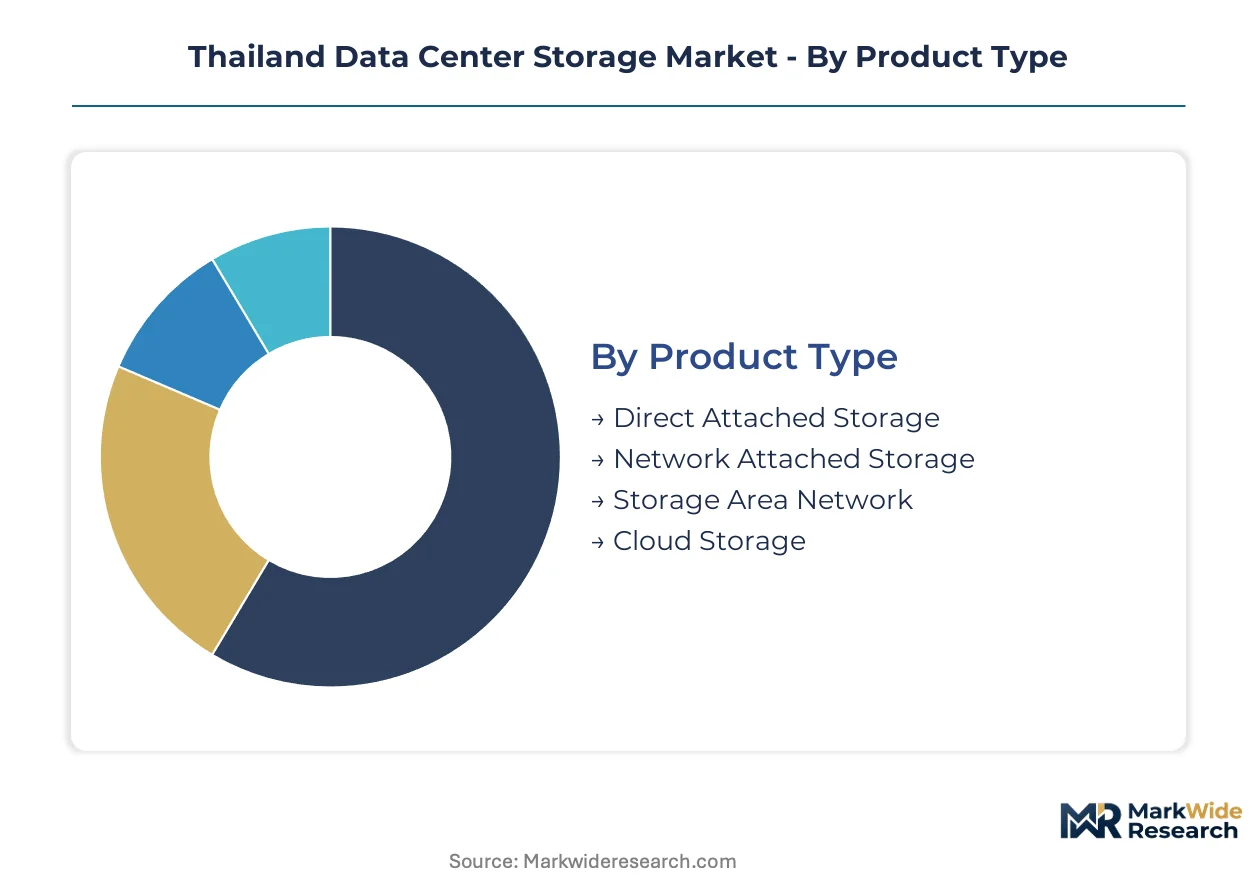
Thailand's data center storage procurement patterns fragment sharply across infrastructure architectures and sovereignty requirements. Understanding these segment boundaries illuminates where PDPA compliance costs concentrate and which technology transitions offer the steepest growth trajectories.
Product Type:
Cost tier differentiation separates commodity retention from premium performance tiers across Thai enterprise procurement.
- Storage Area Network:Fibre Channel and iSCSI fabrics interconnect block-level storage arrays to host servers with dedicated high-bandwidth paths. Bangkok's financial institutions maintain extensive SAN footprints for core banking databases, though legacy Fibre Channel infrastructure creates costly bridge requirements for flash array adoption.
- Cloud Storage:Object and file services delivered over IP networks enable elastic capacity scaling without capital deployment. Thai enterprises pursuing hybrid infrastructure models are expanding cloud storage fastest, driven by Board of Investment tax incentives for greenfield data center construction.
- Direct Attached Storage:Internal server drives and external JBOD enclosures serve single-host workloads with minimal latency overhead.
- Network Attached Storage:File-level protocols support departmental document repositories and media workflows.
Storage Area Network commands the established base. The steepest expansion runs through Cloud Storage.
Technology:
Application workload characteristics determine whether latency sensitivity or cost-per-gigabyte governs technology selection.
- SSD:NAND flash arrays deliver sub-millisecond access times for transactional databases and real-time analytics. Thai banks deploy petabyte-scale all-flash configurations for instant payment platforms, absorbing premium pricing to meet query response requirements.
- HDD:Magnetic spinning media retains cost dominance for sequential access and archival retention tiers. Hyperscale operators in Chonburi and Rayong provinces sustain substantial HDD procurement volumes for capacity-optimized object stores.
- SAN:Block-level network architectures persist in consolidated enterprise data halls.
- NAS:File-serving protocols support unstructured data growth in content and media verticals.
HDD retains the volume base. SSD climbs the fastest as financial services modernize transaction infrastructure.
End User:
Customer type determines compliance stringency, procurement scale, and technology refresh cycles.
- BFSI:Banking, financial services and insurance institutions operate under strictest PDPA encryption mandates and real-time transaction requirements. This vertical drives certified storage system upgrades with hardware-level encryption and immutable snapshot capabilities.
- Government:State agencies manage sovereign data with residency attestations and extended retention periods. Cold archival tiers in this segment face magnetic tape substitution pressure for exabyte-scale retention economics.
- Healthcare:Medical record digitization creates expanding storage demand with breach notification protocol requirements.
- Telecom:Network operators balance subscriber data retention against NBTC licensing friction for equipment approvals.
BFSI commands the premium technology base. Healthcare gains share fastest as digitization accelerates.
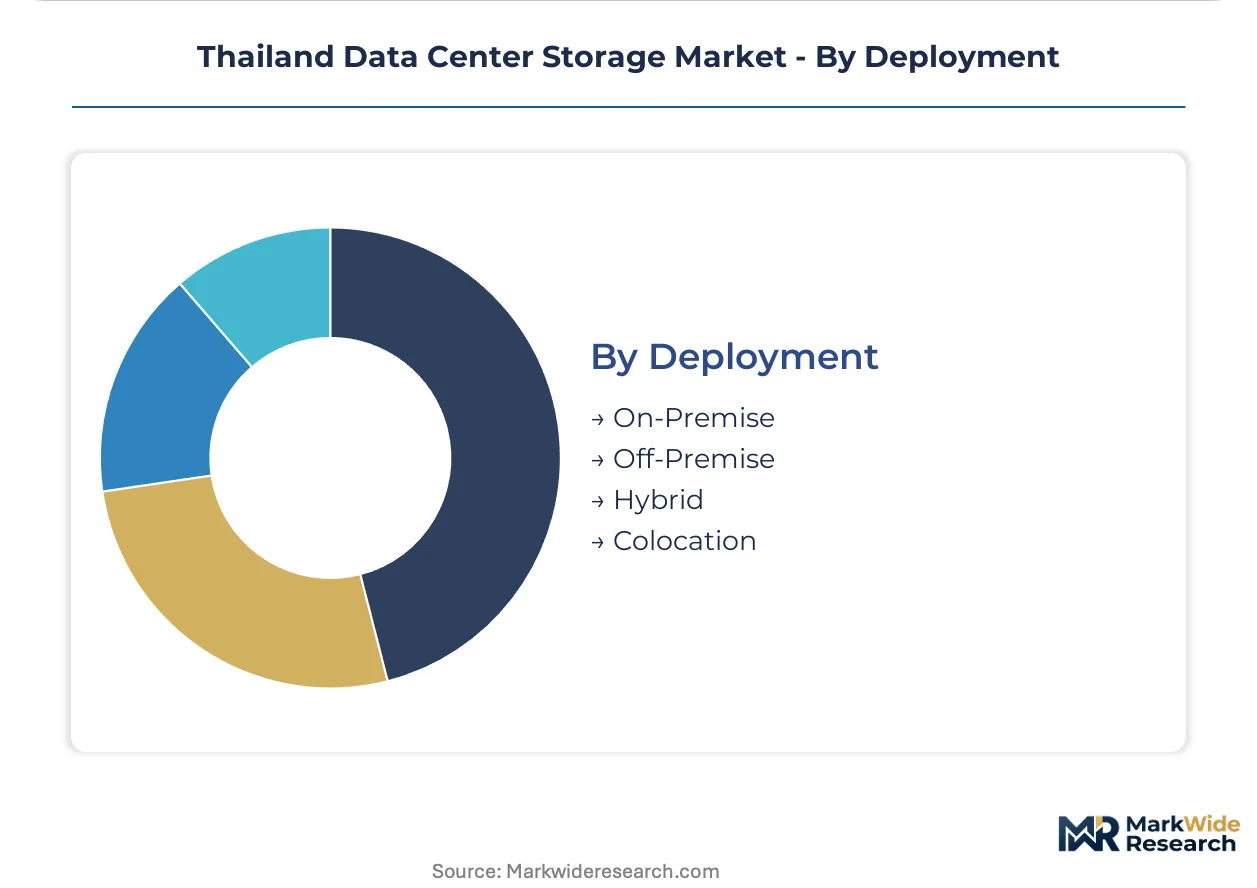
Deployment:
Volume concentration and margin structure vary dramatically by physical infrastructure control model.
- Hybrid:Orchestrated on-premise and off-premise capacity pools enable workload portability with data sovereignty guardrails. Thai enterprises lacking dedicated storage administration increasingly prefer operational expenditure treatment through managed hybrid contracts.
- Colocation:Leased data center space with tenant-managed storage hardware reduces capital facility investment. Eastern Economic Corridor buildouts in Chonburi and Rayong are expanding colocation supply with full storage stack provisioning requirements.
- On-Premise:Enterprise-owned facilities retain control for strictest compliance scenarios.
- Off-Premise:Fully outsourced capacity suits mid-market buyers consolidating procurement through systems integrators.
On-Premise retains the installed base. Hybrid deployment expands most quickly as sovereignty requirements complicate pure cloud strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Economic Corridor's high-voltage transmission backbone and submarine cable landings at Laem Chabang port anchor Thailand's data center storage expansion, channeling investment toward Chonburi and Rayong provinces.
Bangkok Metropolitan Area
Hyperscale facilities cluster along the Bang Na-Trat corridor and Ratchada-Ladprao districts, absorbing premium all-flash arrays for financial services. Thailand's Personal Data Protection Act mandates encrypted sovereign retention, forcing enterprise upgrades to certified systems. The Thailand Board of Investment tax holidays accelerate greenfield builds requiring full storage stack provisioning.
Eastern Economic Corridor
Chonburi and Rayong provinces attract cloud operators pursuing disaster recovery and latency-sensitive edge deployments. Government incentives for data center zones drive massive HDD and SSD procurement for capacity-optimized object stores. Huawei Technologies Co., Ltd. and Western Digital Corporation sustain volume through manufacturing relationships near these clusters.
Chiang Mai
Northern Thailand's secondary hub emerges for disaster recovery workloads seeking geographic separation from Bangkok's seismic and flood risks. The National Broadcasting and Telecommunications Commission licensing framework adds certification delays for imported equipment. Local systems integrators consolidate procurement relationships for mid-market enterprises lacking dedicated storage administration.
Phuket
Southern Thailand's island province develops edge storage nodes for tourism and maritime logistics digitization. Cross-border data flow restrictions under PDPA enforcement complicate pure cloud strategies, favoring hybrid deployment models. Dell Inc. leverages server-storage bundling to dominate these deployments.
Rayong
Industrial estates near Map Ta Phut harbor combine petrochemical infrastructure with data center construction, exploiting existing power substations. Magnetic tape substitution pressure in government archival tiers compresses addressable HDD volume. AI/ML training clusters converge GPU compute with high-throughput NVMe storage for low-latitude inference workloads.
Thailand Data Center Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying raw capacity. Thai enterprise procurement narrows toward bundled solutions as direct vendor relationships give way to systems integrator consolidation. Three archetypes dominate: server-storage bundlers, all-flash array specialists, and HDD volume suppliers. Competitive moves center on strategic partnerships with local integrators and geographic expansion into Eastern Economic Corridor zones.
Among China-based platform vendors, Huawei Technologies Co., Ltd. occupies a position exemplifying aggressive flash pricing within national security screening constraints. Dell Inc. anchors the server-storage bundling archetype across Bangkok and Eastern Economic Corridor deployments. Western Digital Corporation sits within the component supply tier, representing captive manufacturing relationships that sustain hyperscale build volumes.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| NetApp, Inc. |
| Dell Inc. |
| Lenovo Group Ltd. |
| Hewlett Packard Enterprise Co. |
| Seagate Technology LLC |
| Western Digital Corporation |
| Kingston Technology Company Inc. |
| Fujitsu Limited |
| Others |
Pricing and Supply Chain Analysis
NAND flash foundry concentration in South Korea and Taiwan concentrates margin capture upstream, leaving Thai systems integrators and hyperscale operators to compete on procurement scale and certification bundling rather than component sourcing leverage. Storage vendors serving Bangkok's financial institutions must absorb PDPA compliance costs into hardware-level encryption premiums while defending position against tape library substitution in archival tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Thai enterprise procurement, with all-flash NVMe arrays commanding certification-grade premiums for BFSI workloads while HDD-based object storage competes on petabyte-scale volume discounts. Price differentiation rests on hardware encryption certification status and after-sales service bundling rather than raw capacity metrics. Cost compression in mid-market SAN replacements is intensifying because legacy Fibre Channel bridge requirements add integration overhead. Government and telecom archival buyers exhibit highest price sensitivity, whereas banking technology officers prioritize query latency guarantees over per-terabyte procurement economics.
Supply Chain Analysis
Contract manufacturing for storage enclosures and controller boards concentrates in China, Thailand, and Malaysia, with Western Digital and Seagate maintaining captive disk assembly facilities near Eastern Economic Corridor demand clusters. NAND flash wafers draw from South Korean and Taiwanese foundries, while HDD platters and spindle motors source from Japanese and Malaysian precision component suppliers. Single-source vulnerability in advanced NAND process nodes exposes procurement to geopolitical freight disruptions. Distribution runs through Bangkok-based systems integrators who consolidate direct vendor relationships and bundle hardware with managed capacity scaling contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic tape library substitution in exabyte-scale government archival tiers threatens incumbent HDD suppliers, forcing storage vendors to defend replacement revenue through compliance-certified flash tiering and edge deployment diversification.
For Market Incumbents: Build switching-cost moats around legacy SAN integration expertise to capture bridge architecture deployments as Thai banks modernize 15-year-old Fibre Channel infrastructure without forklift replacement. Deepen backward integration into Thailand-based enclosure assembly to reduce NBTC certification delays and capture Board of Investment tax holiday benefits. Defend against tape library substitution by embedding immutable snapshot capabilities as standard features rather than premium add-ons. For New Entrants and Emerging Players: Mid-market enterprises in Chiang Mai and Phuket lacking dedicated storage administration functions represent the most penetrable entry point for managed hybrid cloud contracts with per-terabyte operational expenditure treatment. AI/ML training clusters converging GPU infrastructure with NVMe storage for low-latitude inference workloads offer specialized deployment opportunities outside Bangkok's saturated primary market. Lead with systems integrator partnerships rather than direct vendor relationships to bypass entrenched procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional systems integrators who have consolidated Bangkok enterprise procurement relationships and now bundle hardware, maintenance, and capacity scaling into single-source contracts. Long-term viability hinges on exposure to PDPA compliance upgrade cycles rather than pure capacity growth. Monitor NBTC certification backlog durations as an inflection indicator for vendor eligibility friction and localization mandate tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Level Encryption Certification | PDPA compliance mandates force enterprise upgrades to certified storage systems with sovereign data retention capabilities. |
| Systems Integrator Partnership Expansion | Direct vendor relationships narrow as Bangkok-based integrators consolidate procurement and bundle managed services. |
| Eastern Economic Corridor Manufacturing Localization | Board of Investment tax holidays accelerate greenfield builds requiring captive assembly relationships near Chonburi demand. |
| Immutable Snapshot Feature Standardization | 72-hour breach notification protocols under PDPA enforcement embed geo-fencing controls as baseline requirements. |
| Edge Storage Node Deployment | Chiang Mai-Phuket secondary hubs create disaster recovery demand outside Bangkok's seismic and flood risk concentration. |
Research Methodology
Cross-validation between primary interviews with data center infrastructure directors, storage procurement officers at Thai banks, systems integrator technical leads, and NBTC regulatory affairs specialists anchors the qualitative findings against secondary sources including Board of Investment incentive disclosures, PDPA enforcement guidelines, hyperscaler capex announcements, and customs import records for storage hardware categories. Bottom-up capacity installation tracking triangulates against top-down vendor shipment estimates to constrain projection variance.
Calibration against historical adoption curves for flash storage in ASEAN financial services markets shapes the analytical framework across the analysis window, with segmentation modeling across deployment architecture, technology tier, end-use vertical, and geographic hub. CAGRs derive from fitted growth curves applied to certified product upgrade cycles and greenfield data center construction pipelines. Forecast inputs incorporate NBTC certification delay distributions and PDPA compliance cost pass-through assumptions.
Practitioners should monitor NAND flash supply concentration disruptions, NBTC licensing friction escalations, and tape library substitution acceleration in government archival tiers for early signals of forecast revision. Quarterly review of hyperscale procurement announcements, systems integrator consolidation activity, and regulatory enforcement guideline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Multi Cloud Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Belgium Data Center Storage Market