
 Scale-Out NAS Market | 2026-2036
Scale-Out NAS Market Size, Share, and Industry Trends Forecast 2026-2036
Scale-Out NAS Market Outlook
Enterprise-grade NVMe performance tiers are rotating toward the center of procurement decisions as latency-sensitive AI training workloads displace cold-archive use cases. Dell Technologies leverages its server-to-storage integration to anchor large federal and healthcare contracts. NetApp competes through cloud-connected fabric architectures that bridge on-premises estates with AWS and Azure. Huawei Technologies dominates in Asia-Pacific carrier deployments where 5G content delivery networks require elastic file services.
Scale-out network-attached storage distributes data across clustered nodes with shared-nothing architectures, typically scaling from hundreds of terabytes to exabyte ranges while maintaining single-namespace access through protocols such as NFSv4.2 or SMB 3.1.1 with RDMA acceleration. Its primary commercial purpose is to provide concurrent low-latency file access for thousands of clients without the throughput bottlenecks of traditional monolithic NAS controllers. Hybrid deployment models now capture the widest margin pools as enterprises retain hot data on-premises while tiering archive workloads to object-backed cloud gateways. Object storage technology is displacing legacy NFS in video surveillance and medical imaging pipelines where immutable retention and S3-compatible APIs simplify compliance. Media and entertainment end users sustain the highest capacity growth rates as streaming platforms expand original content libraries across multiple geographic production hubs.
FCC guidelines on broadcast media retention and HIPAA security rules for healthcare data at rest directly shape encryption, audit logging, and geographic replication requirements in U.S. deployments. ISO 27001 and NIST SP 800-53 frameworks further constrain vendor qualification timelines for federal and defense-adjacent buyers. The EU AI Act and GDPR cross-border transfer mechanisms are forcing European enterprises to evaluate residency-guaranteed scale-out NAS architectures with certified EU data boundary compliance. Stakeholders must monitor whether emerging sovereign cloud mandates fragment vendor certification paths or consolidate procurement around hyperscaler-affiliated storage platforms.
Market Dynamics
NVMe-over-Fabrics integration is compressing latency thresholds below 100 microseconds, forcing incumbent vendors to redesign controller architectures or cede high-performance workloads to software-defined alternatives.
Growth Catalysts
- FCC broadcast retention mandates:Media studios in the United States must archive uncompressed 4K and 8K footage for multi-year periods, driving petabyte-scale NAS procurement with immutable snapshot capabilities.
- Healthcare AI training pipelines:Radiology departments and pharmaceutical researchers require concurrent low-latency access to billion-image datasets, rotating storage budgets toward clustered file systems with GPU-direct connectivity.
- Hyperscaler co-location buildouts:Federal data sovereignty requirements and classified workload processing are concentrating demand in Virginia, Texas, and Arizona data center corridors.
Market Restraints
- Flash memory supply concentration:NAND fabrication capacity concentrates in South Korea and Taiwan, exposing procurement teams to die shortage risks and volatile contract pricing.
- NIST SP 800-53 compliance timelines:Federal buyers face 12-18 month vendor qualification cycles that delay deployment and freeze competitive entry for emerging suppliers.
- Object storage substitution:S3-compatible archival tiers with erasure coding are capturing cold-data workloads previously assigned to scale-out NAS namespaces.
Strategic Opportunities
- EU AI Act data residency requirements:Certified EU data boundary compliance creates procurement preference for European-hosted scale-out NAS architectures with localized encryption key management.
- 5G content delivery network buildouts:Asia-Pacific carrier deployments require elastic file services at network edge nodes, opening tier-2 city markets previously served by centralized storage.
- NVMe-TCP and RDMA convergence:Hybrid transport protocols enable RoCE v2 deployment over standard Ethernet switches, reducing specialized InfiniBand infrastructure costs for mid-market enterprises.
Industry Challenges
- Distributed systems engineering talent scarcity:Vendors and enterprise IT organizations compete for kernel-level NFS and SMB protocol developers capable of debugging clustered namespace consistency.
- Legacy POSIX application integration:Financial services and engineering workflows built on decades-old file system semantics resist migration to object-backed namespaces without extensive application refactoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scale-Out NAS Market |
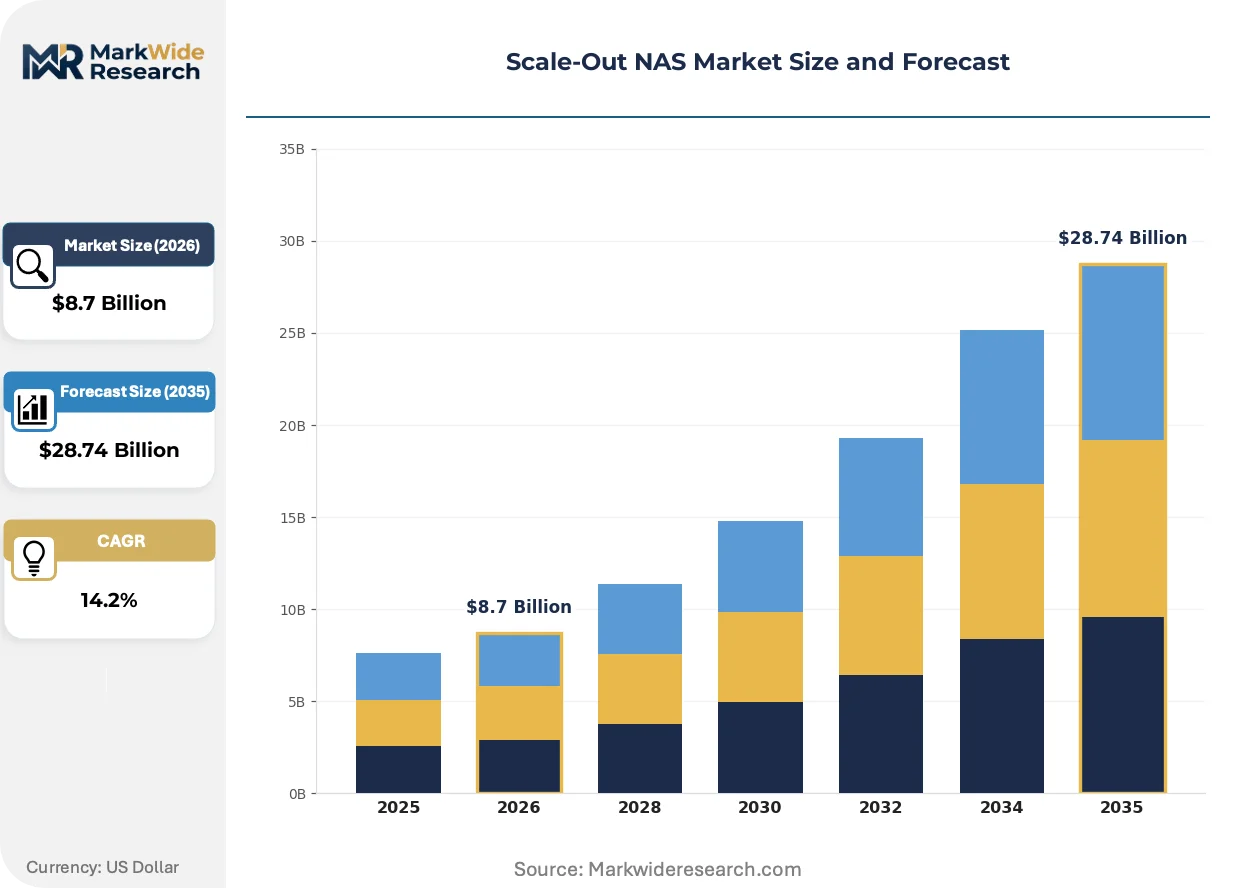
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Media & Entertainment, Healthcare, Telecommunications, Manufacturing Technology: NFS, SMB, Object Storage, File System Solution: Backup & Recovery, Archiving, Content Distribution, Data Management |
| Companies Covered | Hewlett Packard Enterprise, Huawei Technologies, Dell Technologies, Scality, Quantum Corporation, NetApp, Pure Storage, Nasuni Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scale-Out NAS Market Strategic Shifts
Storage class memory and computational storage drives are collapsing the traditional separation between compute and persistence layers, forcing architecture decisions that favor disaggregated composable infrastructure over fixed appliance form factors.
NVMe-over-TCP controller software is bifurcating the performance-tier market into two distinct procurement tracks: latency-optimized deployments using RoCE v2 for AI training clusters, and throughput-optimized configurations using standard TCP for media rendering farms. Post-production studios in Los Angeles and London are adopting the latter to avoid InfiniBand skill requirements. This bifurcation is compressing mid-range unified storage margins as buyers self-segment into specialized tiers.
GDPR Article 44 cross-border transfer mechanisms and the EU AI Act risk classification framework are mandating data localization for high-risk AI training datasets. European enterprises must now certify that model training data never leaves EU jurisdictional boundaries. Healthcare and automotive AI developers in Germany and France are responding by procuring residency-guaranteed scale-out NAS with hardware-rooted encryption.
Consumption-based financing models are displacing traditional three-year capital lease structures for storage infrastructure. Enterprise buyers in the United States now prefer utility billing tied to actual capacity utilization rather than pre-provisioned raw terabytes. This shift is most visible among SaaS platform operators in Seattle and San Francisco who match storage opex to subscription revenue streams.
Scale-Out NAS Market Segmentation
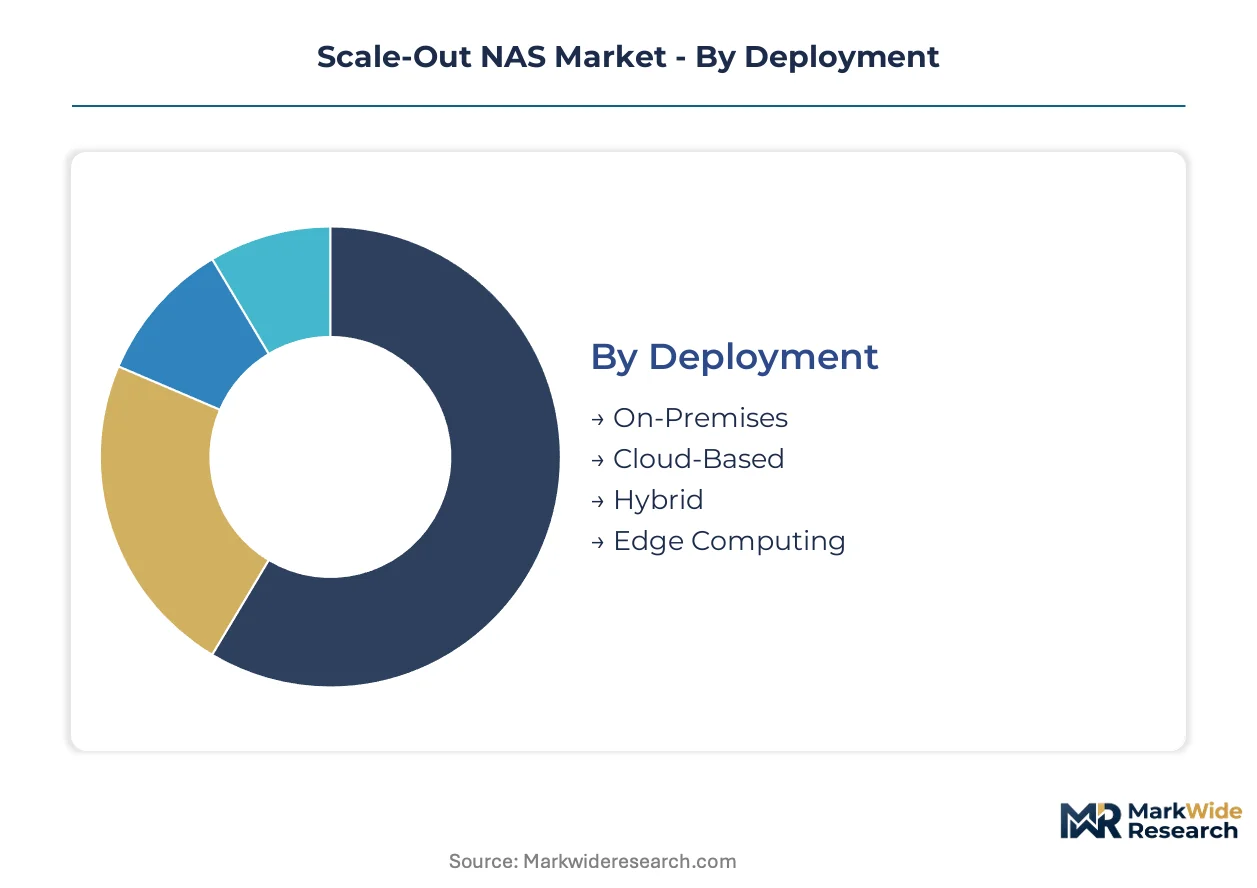
Scale-out NAS procurement patterns diverge sharply across deployment models and workload types. Channel mix varies from direct enterprise sales for on-premises clusters to utility billing for cloud-backed tiers, with hybrid architectures capturing the widest margin pools.
Deployment:
Channel strategy bifurcates between capital-intensive direct sales for on-premises infrastructure and recurring-revenue models for cloud-backed deployments.
- On-Premises:Petabyte-scale clusters with NVMe-over-Fabrics backbones serve latency-sensitive AI training and 4K/8K post-production workflows. Healthcare systems in the United States anchor procurement here due to HIPAA data-at-rest requirements and 12-18 month NIST SP 800-53 qualification cycles that freeze cloud migration timelines.
- Hybrid:Hot data resides on-premises while archive tiers flow to S3-compatible cloud gateways, matching storage opex to subscription revenue streams. SaaS operators in Seattle and San Francisco prefer utility billing tied to actual utilization rather than pre-provisioned raw capacity.
- Cloud-Based:Fully managed namespace services eliminate capital expenditure for mid-market enterprises lacking distributed systems engineering talent.
- Edge Computing:Elastic file services at 5G network edge nodes serve Asia-Pacific carrier deployments in tier-2 cities previously centralized.
On-Premises dominates installed base. Hybrid is where expansion concentrates.
End User:
Application intensity determines performance tier selection and procurement authority concentration.
- Media & Entertainment:Uncompressed 4K and 8K footage pipelines drive petabyte-scale procurement with immutable snapshot capabilities. Los Angeles and London post-production studios adopt NVMe-over-TCP configurations using standard Ethernet to avoid InfiniBand skill barriers.
- Healthcare:Radiology departments require concurrent low-latency access to billion-image datasets with GPU-direct connectivity. FCC broadcast retention mandates and HIPAA security rules shape encryption, audit logging, and geographic replication requirements.
- Telecommunications:5G content delivery networks in Asia-Pacific require elastic file services at distributed edge nodes.
- Manufacturing:Engineering workflows built on decades-old POSIX semantics resist migration to object-backed namespaces without extensive application refactoring.
Media & Entertainment commands the steepest capacity expansion trajectory. Healthcare rotates budgets fastest toward performance tiers.
Technology:
Protocol selection governs latency thresholds and interoperability with legacy application stacks.
- NFS:Version 4.2 with RDMA acceleration maintains single-namespace access across clustered nodes scaling to exabyte ranges. Kernel-level protocol expertise scarcity constrains vendor development timelines and enterprise debugging capacity.
- SMB:Version 3.1.1 with RDMA serves Windows-centric enterprise environments requiring concurrent access for thousands of clients.
- Object Storage:S3-compatible APIs displace legacy file systems in video surveillance and medical imaging pipelines where immutable retention simplifies compliance.
- File System:Proprietary clustered architectures compete with software-defined alternatives in high-performance workloads.
NFS anchors enterprise interoperability. Object Storage is climbing the fastest as archival workloads migrate to erasure-coded tiers.
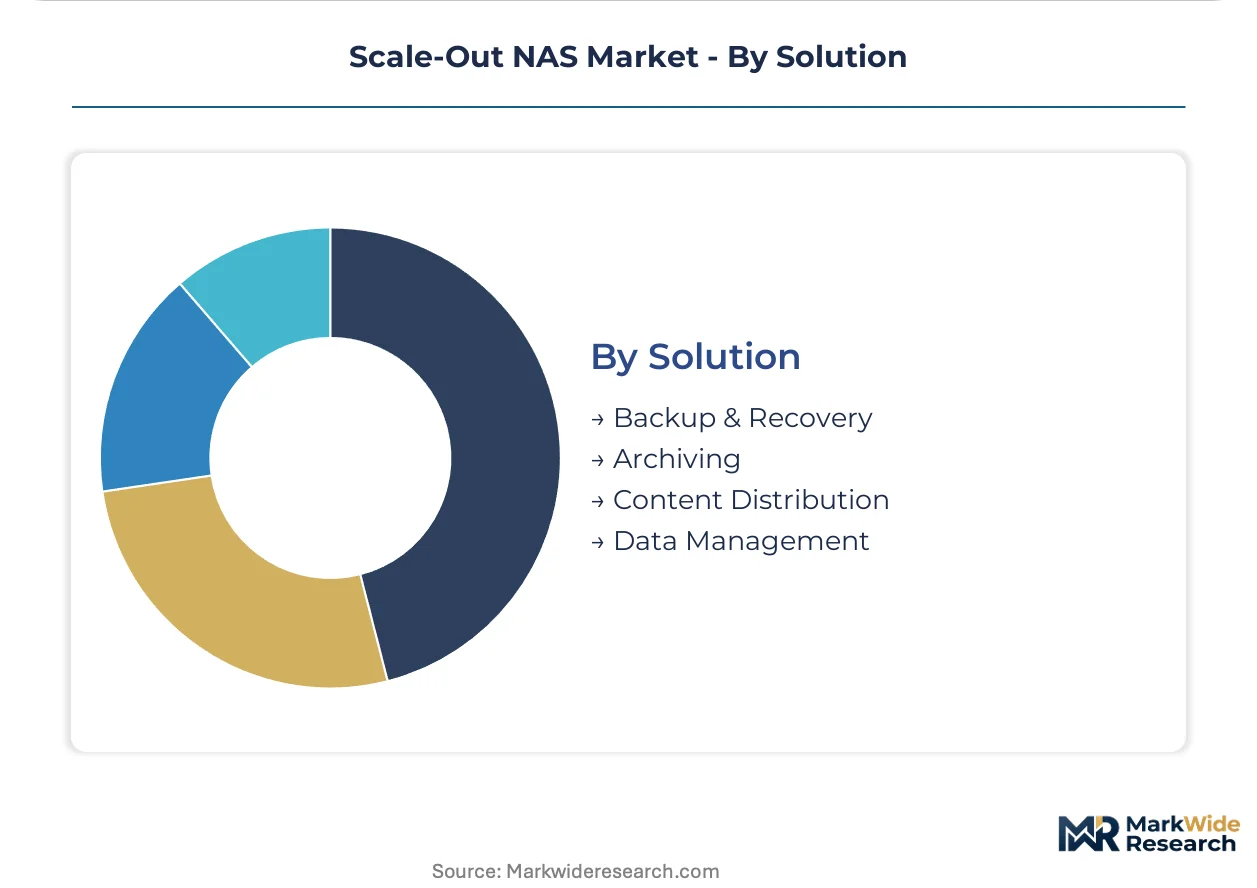
Solution:
Value capture shifts from capacity provisioning toward data lifecycle orchestration and compliance automation.
- Backup & Recovery:Immutable snapshot capabilities satisfy FCC broadcast retention mandates for multi-year archive periods.
- Archiving:S3-compatible cold tiers with geographic replication address GDPR Article 44 cross-border transfer constraints and EU AI Act data residency requirements.
- Content Distribution:Elastic file services at network edge nodes enable 5G carrier deployments requiring low-latency delivery to geographically dispersed production hubs.
- Data Management:Hardware-rooted encryption and localized key management certify EU data boundary compliance for high-risk AI training datasets in Germany and France.
Archiving represents the largest addressable volume pool. Data Management is gaining share fastest as residency mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across procurement contexts: federal buyers prioritize NIST compliance timelines over unit economics, while SaaS operators in Seattle and San Francisco aggressively optimize storage opex against subscription revenue streams.
United States
Hyperscaler co-location buildouts and federal data sovereignty requirements concentrate demand in Virginia, Texas, and Arizona data center corridors. FCC broadcast retention mandates and HIPAA security rules shape encryption, audit logging, and geographic replication requirements. Los Angeles post-production studios adopt NVMe-over-TCP configurations using standard Ethernet to avoid InfiniBand skill barriers.
Germany
Healthcare and automotive AI developers procure residency-guaranteed scale-out NAS with hardware-rooted encryption for high-risk training datasets. GDPR Article 44 cross-border transfer mechanisms and the EU AI Act risk classification framework mandate data localization. Munich and Stuttgart industrial clusters drive procurement for manufacturing workflows built on decades-old POSIX semantics.
China
5G content delivery network buildouts require elastic file services at network edge nodes in tier-2 cities previously served by centralized storage. National data sovereignty regulations and MIIT cloud service licensing constrain foreign vendor participation. Beijing and Shanghai anchor hyperscaler infrastructure expansion for domestic streaming platforms.
Japan
Radiology departments and pharmaceutical researchers require concurrent low-latency access to billion-image datasets with GPU-direct connectivity. METI industrial digitalization initiatives accelerate storage procurement for smart factory deployments. Tokyo and Osaka metropolitan areas concentrate healthcare AI training pipeline investments.
South Korea
NAND fabrication capacity concentration exposes procurement teams to die shortage risks and volatile contract pricing. MFDS medical device data regulations and national AI development strategies shape enterprise storage requirements. Seoul Capital Area and Busan-Ulsan corridor anchor media streaming platform infrastructure expansion.
Scale-Out NAS Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the scale-out NAS market. Incumbent infrastructure vendors anchor federal and healthcare contracts through server-to-storage integration, while software-defined alternatives capture mid-market share with utility billing models. Three strategic archetypes dominate: integrated infrastructure conglomerates, cloud-native storage specialists, and regional carrier-focused suppliers. Competitive moves concentrate on NVMe-over-Fabrics architecture redesigns and consumption-based financing model expansion.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify archetypes leveraging server-to-storage integration to anchor large federal contracts. Huawei Technologies occupies a position within the Asia-Pacific carrier-focused supplier archetype, where 5G content delivery network requirements create procurement preference for elastic file services. NetApp sits within the cloud-connected fabric architecture tier, bridging on-premises estates with hyperscaler environments.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Huawei Technologies |
| Dell Technologies |
| Scality |
| Quantum Corporation |
| NetApp |
| Pure Storage |
| Nasuni Corporation |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Petabyte-scale NAND fabrication economies in South Korea and Taiwan compress unit costs for flash-based controllers while simultaneously concentrating supply-side pricing power among three dominant memory suppliers. This scale dynamic creates asymmetric procurement leverage where hyperscaler buyers extract volume discounts while mid-market enterprises absorb spot-price volatility.
Pricing Analysis
NIST SP 800-53 dictates the pricing tier structure across federal and healthcare deployments, where 12-18 month vendor qualification cycles create certification-premium capture for pre-approved suppliers. Three-tier pricing structure across NVMe performance, hybrid flash-disk, and archive tiers segments buyers by latency sensitivity rather than raw capacity. Cost compression in mid-range unified storage is intensifying because NVMe-over-TCP adoption collapses specialized InfiniBand infrastructure requirements. SaaS operators in Seattle and San Francisco exhibit highest price sensitivity through utility-billing demands, while federal buyers prioritize compliance timelines over unit economics.
Supply Chain Analysis
South Korea and Taiwan anchor NAND wafer fabrication and controller ASIC production, with China mounting domestic capacity expansion through MIIT-licensed facilities. Scale-out NAS manufacturing draws from flash memory dies, RoCE-capable Ethernet switches, and specialized FPGA-based protocol acceleration cards. Single-source vulnerability concentrates in advanced node NAND where three suppliers control fabrication capacity. Distribution runs through direct enterprise sales for petabyte-scale clusters and channel partners for mid-market edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scale-out NAS market functions as a defensive-moat arena where NIST SP 800-53 qualification entrenchment creates 12-18 month switching costs that freeze competitive entry for emerging suppliers.
For Market Incumbents: Compound server-to-storage integration advantages by embedding GPU-direct connectivity into federal healthcare contracts before software-defined alternatives achieve protocol parity. Extend certification moats through accelerated EU data boundary compliance investments, as GDPR Article 44 and EU AI Act mandates reshape procurement preference toward residency-guaranteed architectures. Prioritize consumption-based financing model expansion to match SaaS operator opex preferences in Seattle and San Francisco. For New Entrants and Emerging Players: FedRAMP authorization fast-track represents the most penetrable regulatory wedge for cloud-native storage specialists targeting federal-adjacent workloads bypassing legacy NIST qualification freezes. Target mid-market media rendering farms in Los Angeles adopting NVMe-over-TCP over standard Ethernet to avoid InfiniBand skill barriers. Lead with utility-billing models that align storage costs to subscription revenue streams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid deployment specialists bridging on-premises hot tiers with S3-compatible cloud gateways, as consumption-based financing displaces capital lease structures. Long-term viability centers on vendors controlling kernel-level NFSv4.2 protocol expertise where distributed systems engineering talent scarcity constrains competitive replication. Watch for NVMe-over-Fabrics latency threshold compression below 100 microseconds as inflection signal for software-defined displacement of incumbent controller architectures.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-over-Fabrics Architecture Redesign | Compresses latency below 100 microseconds for AI training workloads in Virginia federal corridors. |
| EU Data Boundary Certification | Captures GDPR Article 44 procurement preference from German automotive AI developers. |
| Consumption-Based Financing Expansion | Aligns storage opex to SaaS subscription revenue streams in Seattle and San Francisco. |
| GPU-Direct Connectivity Integration | Locks radiology departments into billion-image dataset pipelines with HIPAA-compliant encryption. |
| 5G Edge Node Deployment | Opens tier-2 city markets across Asia-Pacific carrier networks previously centralized. |
Study Parameters
A standing panel of storage procurement officers at hyperscale SaaS operators, federal IT directors managing NIST SP 800-53 qualification cycles, post-production technical directors in Los Angeles and London, and distributed systems engineers at cloud-native storage vendors provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, FCC broadcast retention guideline updates, and EU AI Act regulatory text. Bottom-up deployment model sizing and top-down market aggregation triangulated volume estimates across the analysis window.
External benchmark consistency checks validated outputs against hyperscaler infrastructure expansion disclosures and carrier 5G edge deployment announcements. The analytical framework modeled deployment architecture, end-user vertical, protocol technology, and solution type across the projection horizon, with CAGRs derived from fitted growth curves calibrated to historical capacity expansion patterns. Industry-specific inputs included NAND supply elasticity parameters and federal qualification timeline distributions.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscaler co-location buildouts and stable NIST SP 800-53 framework continuity; material deviation in flash memory supply concentration or EU regulatory enforcement intensity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Storage Software Market