
 Copy Data Management Software Market | 2026-2036
Copy Data Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Copy Data Management Software Market Outlook
North American cloud infrastructure expansion is tilting vendor investment toward hybrid architectures. Cohesity leverages converged data management platforms to sustain R&D intensity across enterprise workloads. Rubrik anchors its position through immutable backup layers that dominate SaaS-delivered protection. Dell Technologies extends hardware-software integration to control channel access for on-premise deployments.
Copy data management software creates virtualized, deduplicated data copies across production and non-production environments, typically reducing physical storage footprints through pointer-based replication while maintaining referential integrity for test, backup, and analytics operations. The technology serves primary industrial purposes in minimizing storage capital expenditure and accelerating DevOps pipeline velocity. Cloud-based deployment captures the fastest structural expansion as enterprises exit owned data center obligations, while data security solutions command premium margin pools amid ransomware frequency. Large enterprises occupy the dominant demand tier, though healthcare end users generate disproportionate compliance-driven urgency under HIPAA and state privacy mandates.
ISO 27001 certification, GDPR data minimization principles, and SEC cybersecurity disclosure rules collectively elevate software procurement standards and compress vendor qualification timelines. HIPAA enforcement by the US Department of Health and Human Services directly shapes healthcare segment product roadmaps and encryption requirements. Stakeholders must monitor evolving SEC incident reporting obligations and cross-border data localization statutes to align architecture decisions with jurisdictional compliance exposure.

Market Dynamics
Cloud repatriation and sovereign data mandates are fragmenting enterprise storage architectures, forcing vendors to engineer portable data planes that traverse hyperscaler boundaries without violating residency requirements.
Growth Catalysts
- GDPR Article 17 erasure mandates:Financial services firms in Germany and France require automated copy lifecycle management to demonstrate compliant deletion across distributed environments.
- Container-native backup architectures:Kubernetes-orchestrated workloads in DevOps pipelines demand immutable snapshot integration that legacy tools cannot provision.
- Japan's METI data free flow with trust initiative:Cross-border enterprise operations in Tokyo and Osaka are accelerating procurement of jurisdictional-aware copy management platforms.
Market Restraints
- Hyperscaler storage API volatility:Amazon S3 and Azure Blob breaking changes force quarterly engineering sprints that compress vendor R&D bandwidth for feature differentiation.
- Silicon Valley talent concentration:Platform engineering expertise clusters within a 50-mile radius, inflating compensation benchmarks and constraining vendor scaling velocity.
- Quantum encryption uncertainty:NIST post-quantum cryptography standards remain draft-phase, freezing long-term encryption roadmaps and procurement confidence.
Strategic Opportunities
- India's Digital Personal Data Protection Act:Localized copy vault requirements create first-mover advantages for vendors establishing Mumbai and Bangalore data center partnerships.
- AI training data pipeline integration:Synthetic data generation tools are converging with copy management platforms to provision compliant, deduplicated datasets for model development.
- Healthcare SaaS channel expansion:Epic and Cerner marketplace integrations offer embedded distribution paths that bypass traditional enterprise sales cycles.
Industry Challenges
- Immutable backup certification timelines:SEC cybersecurity disclosure rules demand attestation documentation that most vendors cannot generate without six-month compliance engineering investments.
- Mainframe tape integration complexity:Fortune 500 enterprises in the United States retain decades of COBOL-era backup protocols that resist API abstraction without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copy Data Management Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government, Healthcare Solution: Data Backup, Data Security, Data Archiving, Data Integration Use Case: Disaster Recovery, Analytics, Test/Data Copy, Compliance |
| Companies Covered | Cohesity, Commvault Systems, Rubrik, Actifio, Catalogic Software, Delphix, IBM, Hitachi Vantara, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copy Data Management Software Market Strategic Shifts
Immutable storage architectures and zero-trust data access models are redefining how enterprises classify copy sensitivity tiers, compressing the window between breach detection and forensic recovery.
Air-gapped immutable snapshots are migrating from ransomware recovery insurance to continuous compliance verification. Healthcare providers under HIPAA enforcement pressure now deploy these architectures as default configurations rather than premium add-ons. The structural consequence is collapsing pricing power for vendors without native immutability at the storage layer.
EU AI Act training data provenance requirements are mandating lineage tracking across derivative copies used in model development. German automotive manufacturers and French pharmaceutical firms must now demonstrate complete audit trails from production databases to synthetic training sets. This is compressing procurement cycles toward platforms with built-in metadata inheritance rather than bolt-on compliance modules.
Consumption-based licensing is displacing perpetual seat agreements in enterprise software procurement. Large financial services buyers in New York and London now negotiate copy volume tiers with automatic bursting provisions for quarter-end reporting spikes. This behavioral shift is most visible among hedge funds and private equity firms where data velocity fluctuates with deal flow intensity.
Copy Data Management Software Market Segmentation
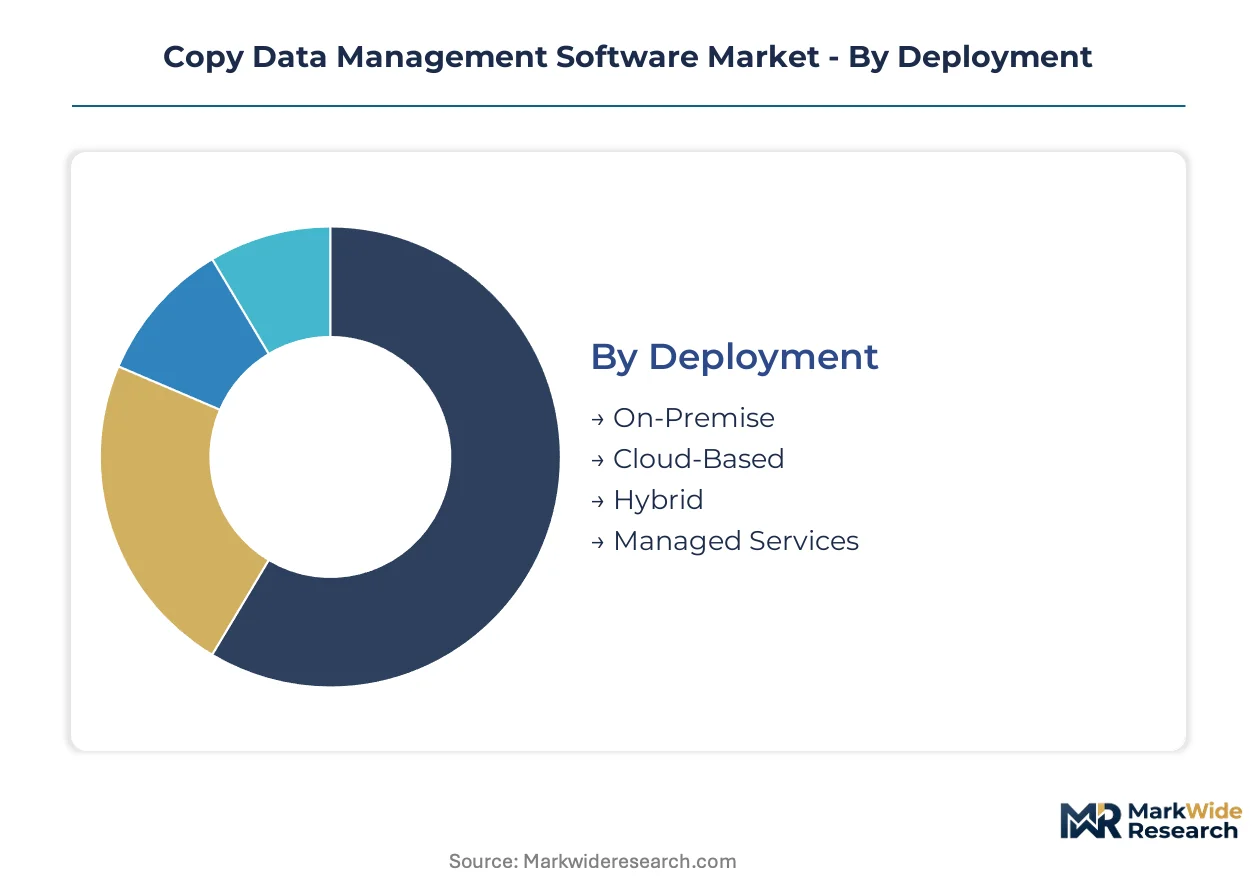
Segmentation in copy data management software reveals how procurement priorities diverge across infrastructure maturity, organizational scale, and regulatory exposure. Vendors must architect modular platforms that traverse deployment modes without fragmenting operational consistency.
Deployment:
Mature on-premise installations coexist with emerging cloud-native architectures as enterprises navigate hybrid complexity.
- On-Premise:Hardware-integrated deployments persist in United States financial services and German automotive manufacturing where data residency mandates override cloud migration timelines. Legacy SAN and NAS integration requirements sustain vendor engineering investment in tape abstraction layers and mainframe connectivity protocols.
- Cloud-Based:Consumption-metered SaaS delivery dominates new procurement in United Kingdom hedge funds and Singapore fintech startups seeking elastic capacity for quarter-end reporting spikes. Hyperscaler API dependencies force vendors into quarterly compatibility sprints that compress feature differentiation bandwidth.
- Hybrid:Policy-orchestrated data planes span owned data centers and AWS or Azure regions, enabling Japanese manufacturers to satisfy METI data free flow with trust requirements while retaining on-premise latency-sensitive workloads.
- Managed Services:Outsourced operational responsibility appeals to Australian mining operators and Canadian energy utilities lacking internal platform engineering expertise.
On-Premise handles the majority of throughput; Cloud-Based is expanding most quickly on share.
End User:
Customer scale determines pricing architecture and sales cycle complexity across the deployment base.
- Large Enterprises:Fortune 500 manufacturers in Germany and pharmaceutical conglomerates in Switzerland negotiate enterprise-wide copy volume tiers with automatic bursting provisions. Procurement teams demand ISO 27001 certification and immutable backup attestation documentation that compresses vendor qualification timelines.
- SMEs:Mid-market professional services firms in France and Netherlands logistics operators adopt standardized SaaS packages with limited customization. Price sensitivity concentrates demand on consumption-based licensing without perpetual seat commitments.
- Government:Federal agencies in United States and national research institutes in Japan require air-gapped architectures with FedRAMP or equivalent sovereign certification.
- Healthcare:Hospital networks under HIPAA and emerging state privacy mandates generate compliance-driven urgency for encrypted copy lifecycle management with automated erasure capabilities.
Large Enterprises contribute the dominant revenue pool; Healthcare is climbing the fastest on growth trajectory.
Solution:
Functional modules align with distinct operational risk profiles and margin structures.
- Data Security:Immutable snapshot layers and zero-trust access controls command premium pricing from United States healthcare providers facing ransomware frequency. EU AI Act training data provenance requirements are mandating lineage tracking across derivative copies in German automotive AI development pipelines.
- Data Backup:Foundation copy virtualization with deduplication and pointer-based replication remains the volume driver across all deployment modes and customer tiers.
- Data Archiving:Long-term retention with automated tiering to cold storage serves Japanese financial institutions under FIEA record-keeping obligations.
- Data Integration:API-driven pipeline connectivity for DevOps and analytics workloads attracts technology-forward buyers in Netherlands and Sweden.
Data Backup anchors the revenue base; Data Security is gaining share fastest.
Use Case:
Operational purpose dictates technical specification and procurement urgency.
- Compliance:GDPR Article 17 erasure mandates and SEC cybersecurity disclosure rules drive automated copy lifecycle management adoption in Germany and United States financial services. Documentation requirements for immutable backup certification compress vendor engineering roadmaps.
- Disaster Recovery:RTO and RPO specifications determine replication topology and geographic distribution strategies for business-critical systems.
- Analytics:Synthetic data generation convergence with copy management platforms provisions compliant datasets for AI model development in French pharmaceutical research.
- Test/Data Copy:DevOps pipeline velocity acceleration through rapid provisioning of referentially intact non-production environments serves Kubernetes-orchestrated workloads.
Disaster Recovery handles the majority of deployment volume; Compliance is expanding most steeply on growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering resources cluster disproportionately within the United States, Germany, and Japan, where enterprise procurement density justifies localized data center partnerships and compliance engineering investments. This concentration shapes feature roadmaps and certification priorities across the competitive set.
United States
SEC cybersecurity disclosure rules and HIPAA enforcement by the Department of Health and Human Services drive automated copy lifecycle management adoption among New York financial services firms and Boston healthcare networks. Fortune 500 manufacturers in the Midwest retain mainframe tape protocols that resist API abstraction. Silicon Valley engineering talent pools sustain R&D velocity for converged data management platforms.
Germany
GDPR Article 17 erasure mandates and EU AI Act training data provenance requirements shape procurement among Frankfurt banking consortia and Stuttgart automotive manufacturers. The country's national data protection authority enforces strict data minimization principles. Bavarian industrial clusters demand jurisdictional-aware copy management for cross-border operations.
Japan
METI data free flow with trust initiative accelerates adoption of portable data planes among Tokyo financial institutions and Osaka manufacturing headquarters. FIEA record-keeping obligations sustain long-term retention requirements. Nagoya industrial corridors require hybrid architectures satisfying both latency-sensitive workloads and cross-border compliance.
United Kingdom
Consumption-metered SaaS delivery dominates new procurement among London hedge funds seeking elastic capacity for quarter-end reporting spikes. The Information Commissioner's Office enforces GDPR-aligned data protection standards. Scottish financial services clusters increasingly favor cloud-native architectures over legacy on-premise commitments.
India
The Digital Personal Data Protection Act creates localized copy vault requirements among Mumbai banking headquarters and Bangalore technology parks. The country's central bank mandates data localization for financial institutions. Hyderabad and Chennai data center partnerships offer first-mover positioning for vendors establishing sovereign infrastructure.
Copy Data Management Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in backup virtualization and security modules. The vendor set arranges into three layers: converged data management platforms, immutable backup specialists, and hardware-integrated legacy providers. Consolidation pressure intensifies as enterprise buyers demand unified control planes across hybrid deployments. Dominant competitive moves include strategic partnerships with hyperscalers and embedded distribution through healthcare SaaS marketplaces.
Among platform-centric providers, Cohesity and Rubrik exemplify the converged architecture archetype, while Dell Technologies anchors the hardware-integrated legacy tier. IBM occupies a position spanning both platform and component domains through its hybrid cloud data services portfolio. These three represent distinct strategic postures: cloud-native software delivery, immutable-first security positioning, and channel-controlled on-premise integration.
| Leading Market Players |
|---|
| Cohesity |
| Commvault Systems |
| Rubrik |
| Actifio |
| Catalogic Software |
| Delphix |
| IBM |
| Hitachi Vantara |
| Dell Technologies |
| Others |
Value Chain & Pricing Dynamics
Hyperscaler API volatility as a single-source dependency determines both pricing tier spreads and supply chain shape in copy data management software. Vendors absorbing quarterly engineering sprints for Amazon S3 and Azure Blob compatibility pass cost premiums through to enterprise buyers while compressing margin buffers for feature differentiation.
Pricing Analysis
SEC cybersecurity disclosure rules dictate the pricing tier structure across the copy data management software market. Three-tier pricing structure across premium, standard, and economy levels separates vendors with native immutable backup certification from those requiring six-month compliance engineering investments. Price differentiation centers on ISO 27001 attestation documentation and automated erasure capabilities for GDPR Article 17 mandates. Cost compression in the standard tier is intensifying because hyperscaler API changes force perpetual re-engineering. Healthcare providers under HIPAA enforcement pressure exhibit the least price sensitivity, while mid-market professional services firms in France and the Netherlands drive procurement toward consumption-based licensing without perpetual commitments.
Supply Chain Analysis
Platform engineering expertise clusters within Silicon Valley, Seattle, and Bangalore, constraining vendor scaling velocity. Software development draws from hyperscaler infrastructure in the United States, Germany, and Japan, with cloud-native architectures tethered to AWS, Azure, and GCP data center partnerships. Raw material dependencies center on semiconductor components for on-premise hardware-integrated deployments, encryption chipsets for immutable storage layers, and API access licenses for hyperscaler integration. Single-source vulnerability concentrates in the 50-mile Silicon Valley talent radius, inflating compensation benchmarks. Distribution runs through direct enterprise sales teams, healthcare SaaS marketplaces, and channel partners for on-premise installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of platform engineers with Kubernetes-orchestrated workload expertise constrains vendor roadmaps and compresses qualification timelines for enterprise procurement. This capability gap shapes competitive positioning across converged data management platforms.
For Market Incumbents: Insulate margin position by deepening captive supply of container-native backup engineering talent in Bangalore and Singapore, bypassing Silicon Valley compensation inflation. Accelerate FedRAMP and sovereign certification pipelines to preempt regulatory qualification barriers. Prioritize immutable backup attestation documentation generation to compress six-month compliance engineering investments into automated audit trails. For New Entrants and Emerging Players: India's Digital Personal Data Protection Act creates localized copy vault requirements among Mumbai banking headquarters and Bangalore technology parks where hyperscaler incumbents lack sovereign infrastructure partnerships. Target healthcare SaaS channel expansion through Epic and Cerner marketplace integrations, bypassing traditional enterprise sales cycles. Lead with consumption-metered SaaS delivery to capture mid-market price sensitivity in the United Kingdom and Singapore. For Investors and Strategic Acquirers: EU AI Act training data provenance requirements reshape the acquisition landscape toward platforms with built-in metadata inheritance rather than bolt-on compliance modules. Long-term viability hinges on jurisdictional-aware copy management capabilities spanning METI data free flow with trust requirements and GDPR Article 17 erasure mandates. Target acquisition archetypes: converged data management platforms with hybrid orchestration engines. Monitor NIST post-quantum cryptography standard finalization as inflection indicator for encryption roadmap confidence.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies control planes across hybrid deployments for Japanese manufacturers under METI requirements. |
| Geographic Expansion | Establishes Mumbai and Bangalore data center partnerships for India's Digital Personal Data Protection Act compliance. |
| Strategic Partnership | Embeds distribution through Epic and Cerner marketplaces, bypassing traditional healthcare enterprise sales cycles. |
| Acquisition of Specialist Firm | Consolidates immutable backup certification capabilities to compress SEC cybersecurity disclosure attestation timelines. |
| Product Launch | Introduces synthetic data generation convergence for EU AI Act training data provenance in German automotive AI pipelines. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with platform engineers, IT procurement officers, healthcare CIOs, and compliance officers; and secondary validation through SEC cybersecurity disclosure filings, HIPAA enforcement actions by the Department of Health and Human Services, GDPR Article 17 guidance documents, and METI data free flow with trust initiative publications. Bottom-up sizing traversed deployment mode, organization scale, vertical, and regional adoption pattern. Top-down triangulation anchored against hyperscaler capex disclosures and enterprise software procurement databases.
Forecast inputs considered consumption-based licensing displacement of perpetual agreements, container-native backup architecture penetration, and AI training data pipeline integration velocity across the projection horizon. Segmentation dimensions modeled deployment mode, end user scale, solution type, and use case purpose. CAGRs derived from elasticity-adjusted demand curves and vendor R&D intensity benchmarks. Industry-specific inputs included ransomware frequency trajectories and cross-border data localization statute proliferation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native entrants with sovereign infrastructure partnerships would shift outcomes. Quarterly review of NIST post-quantum cryptography standard progression, hyperscaler API change frequency, and SEC incident reporting obligation enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Hong Kong Data Center Storage Market