
 Nigeria Data Center Storage Market | 2026-2036
Nigeria Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Data Center Storage Market Insights
Enterprise buyers in banking and telecommunications are collapsing legacy tape-based archiving commitments in favor of flash and software-defined platforms. Dell Inc. leverages its PowerStore line to anchor high-performance workloads in Lagos financial districts. Huawei Technologies Co. Ltd competes aggressively on price-performance for government and carrier-neutral facilities. Hewlett Packard Enterprise differentiates through GreenLake as-a-service contracts that reduce capital intensity for mid-tier colocation tenants.
Nigeria data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention, typically specified by IOPS density, latency thresholds, and endurance ratings measured in drive writes per day. These systems serve Nigeria's commercial and institutional need for transactional integrity, regulatory compliance, and business continuity across unreliable grid environments. Cloud Storage is capturing the fastest expansion as hyperscale providers establish local regions, while Network Attached Storage retains dominance among small and medium enterprises prioritizing capital preservation. NVMe protocols are displacing SAS in performance-tier procurement, particularly within BFSI and IT Services verticals where real-time analytics workloads proliferate.
The National Information Technology Development Agency enforces data sovereignty and local hosting mandates that shape procurement patterns for foreign cloud operators. The Central Bank of Nigeria's risk management guidelines and the Nigeria Data Protection Regulation impose encryption, access control, and audit trail standards that elevate certified storage architecture requirements. Stakeholders must monitor grid reliability investments and diesel cost trajectories, as backup power economics will determine whether on-premises deployment or colocation absorption proves sustainable for capacity planning.
Market Dynamics
NVMe protocol adoption is compressing storage refresh cycles across Nigerian banking and fintech verticals, forcing infrastructure planners to re-evaluate capital allocation between on-premises arrays and colocated flash deployments.
Growth Catalysts
- Nigeria Data Protection Regulation:The NDPR mandates local data residency for personal information processing, compelling foreign cloud operators to provision certified storage within Lagos and Abuja facilities.
- Mobile money transaction logging:Fintech operators including OPay and PalmPay are expanding petabyte-scale storage procurement to meet Central Bank of Nigeria audit trail requirements for real-time settlement records.
- Submarine cable landings:MainOne and Equiano cable terminations in Lagos are reducing latency to European cloud regions, accelerating hybrid storage architecture adoption among enterprise buyers.
Market Restraints
- Diesel generator dependency:Grid unreliability forces 18-24 hour daily generator runtime at Lagos facilities, inflating total cost of ownership for high-density flash arrays by 34-40% versus grid-stable comparators.
- Import tariff structure:Nigeria Customs Service applies 20% duty on enterprise storage hardware, compressing vendor margins and limiting price competitiveness of tier-one arrays against refurbished alternatives.
- Foreign exchange volatility:Naira depreciation against USD denominates 85% of storage procurement contracts, creating working capital strain for mid-tier colocation tenants with local-currency revenue streams.
Strategic Opportunities
- Kano and Port Harcourt metro expansion:Carrier-neutral facilities in these secondary cities remain underserved for tier-III certified storage, offering first-mover positioning before submarine cable extensions arrive.
- Software-defined storage convergence:SUSE Enterprise Storage and Ceph deployments on commodity hardware are enabling Nigerian system integrators to bypass branded array premiums while maintaining NDPR compliance.
- Central Bank IT governance directives:CBN's risk-based cybersecurity framework is mandating encrypted-at-rest storage for all deposit money banks, creating certified architecture upgrade mandates across 184 licensed institutions.
Industry Challenges
- Certified technician scarcity:NITDA-authorized storage architects number fewer than 400 nationally, creating deployment bottlenecks for flash array rollouts requiring vendor-specific accreditation.
- Legacy SAN integration complexity:Fibre Channel fabrics from 2012-2016 procurement waves resist seamless NVMe-oF migration, forcing forklift replacements rather than phased upgrades at tier-two banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Data Center Storage Market |
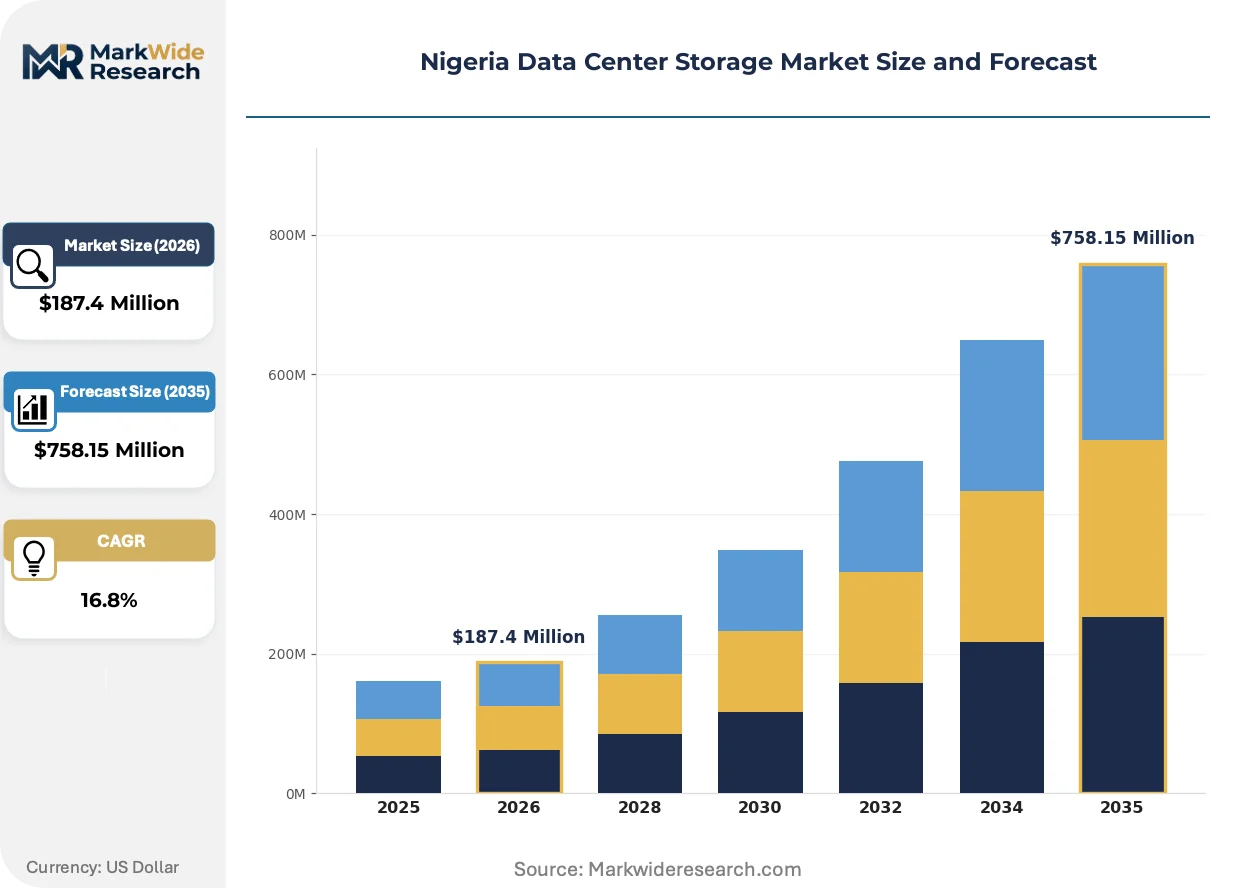
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Cloud Storage End User: Telecommunications, IT Services, BFSI, Healthcare Technology: SAS, SATA, NVMe, Fibre Channel Deployment: On-Premises, Hybrid, Colocation, Managed Services |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, Lenovo Group Limited, Oracle Corporation, Huawei Technologies Co. Ltd, SMART Modular Technologies Inc., QSAN Technology Inc., ADATA Technology Co. Ltd, Fujitsu Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Data Center Storage Market Trends and Innovations
Storage architecture in Nigeria is pivoting from capacity-centric procurement to performance-density optimization, driven by real-time analytics workloads and regulatory compression requirements that reward IOPS-per-watt efficiency over raw terabyte economics.
QLC NAND flash is miniaturizing cost-per-gigabyte thresholds for read-intensive workloads. Nigerian colocation providers are deploying QLC-based all-flash arrays for backup and archival tiers previously served by nearline disk. This technology is miniaturizing the price gap between flash and mechanical storage, enabling hyperscale-style density in 500kVA-constrained Lagos facilities where rack power limits previously favored hybrid configurations.
The Central Bank of Nigeria's risk management guidelines are tightening encryption and access control mandates for financial institutions. These directives require FIPS 140-2 Level 3 certified key management for all customer transaction storage. Deposit money banks are responding by retiring software-encrypted arrays in favor of self-encrypting drives with hardware root-of-trust, prioritizing vendors with local certification support presence in Lagos.
Consumption-based capacity contracts are displacing traditional capital purchase models among mid-market enterprises. HPE GreenLake and Dell APEX as-a-service offerings allow Nigerian firms to match storage payments to actual utilization, preserving foreign exchange for core operations. This shift is most visible in the telecommunications vertical, where MTN and Airtel are absorbing capacity from vendor-managed utility models rather than owning depreciating assets across 37 edge PoPs nationwide.
Nigeria Data Center Storage Market Segmentation
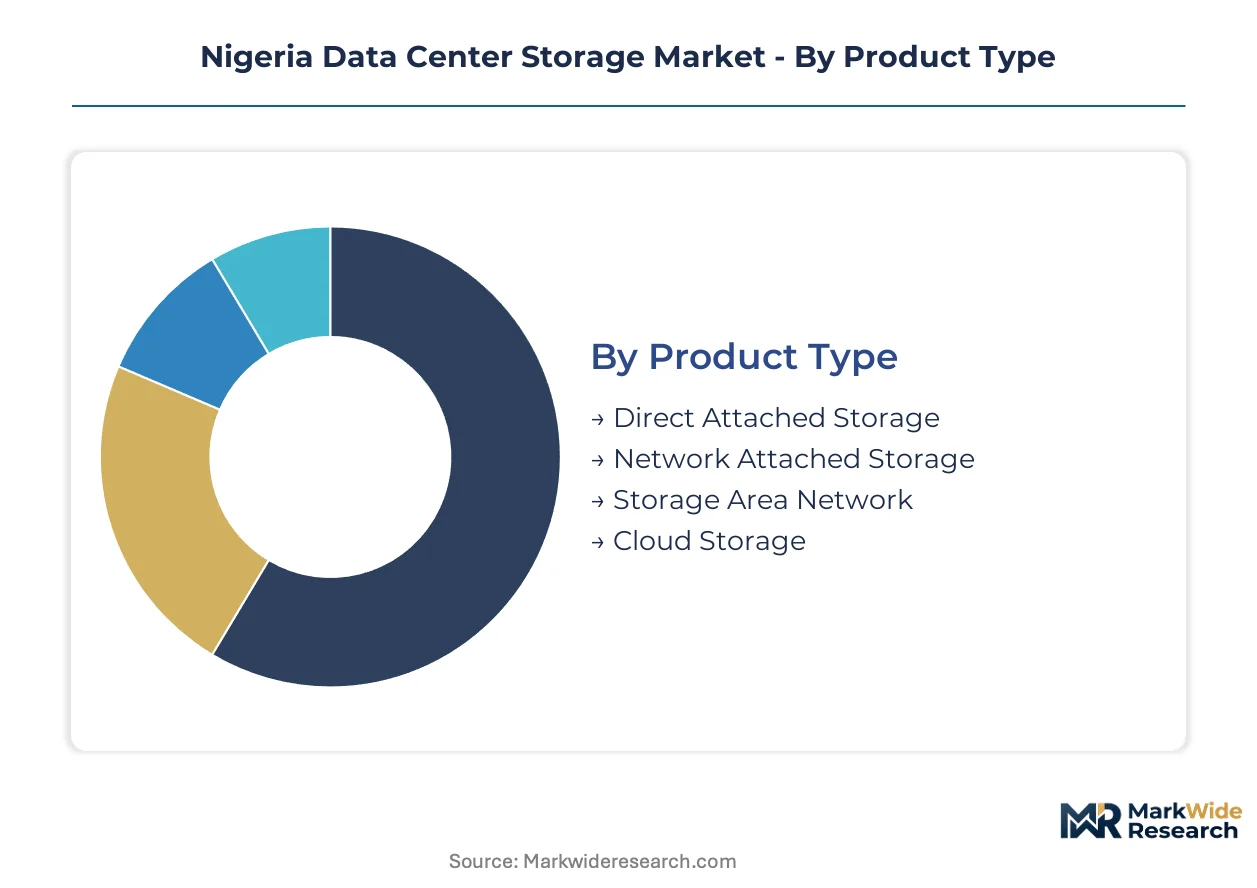
Segmentation reveals how procurement patterns in Nigeria diverge across compliance regimes, power economics, and workload latency requirements. Buyers optimize storage architecture against NDPR data residency mandates, diesel-dependent total cost of ownership, and submarine cable proximity in Lagos versus secondary metros.
Product Type:
The National Data Protection Regulation imposes distinct certification burdens on each architecture tier, with local residency requirements favoring certain deployment modes over others.
- Direct Attached Storage:Block-level storage directly connected to individual servers via PCIe or internal bus architectures. Nigerian tier-two banks in Kano deploy DAS for isolated transaction logging to satisfy Central Bank audit trail mandates without network exposure risks.
- Network Attached Storage:File-level storage accessed over standard Ethernet protocols, typically deployed with NFS or SMB implementations. NAS dominates procurement among Lagos small and medium enterprises prioritizing capital preservation and simplified administration over performance density.
- Storage Area Network:Dedicated Fibre Channel or iSCSI fabrics providing block-level access across consolidated pools. SAN installations concentrate in Lagos Island financial districts where legacy Fibre Channel investments from 2012-2016 procurement waves resist forklift replacement.
- Cloud Storage:Hyperscale object and block services delivered from local availability zones or edge points of presence. Cloud Storage is expanding most quickly as MainOne and Equiano cable landings reduce latency to European regions, accelerating hybrid architecture adoption among fintech operators.
Network Attached Storage handles the majority of throughput among capital-constrained buyers; Cloud Storage is the fastest mover on share.
End User:
Vertical-specific compliance deadlines and transaction volume profiles create divergent procurement rhythms across Nigerian institutional buyers.
- Telecommunications:MTN and Airtel operate 37 edge PoPs nationwide requiring distributed storage for subscriber data and billing records. These operators absorb capacity through HPE GreenLake utility models to preserve foreign exchange for core network investments.
- IT Services:System integrators and managed service providers provision multi-tenant infrastructure for enterprise clients. IT Services verticals are driving software-defined storage adoption on commodity hardware to bypass branded array premiums while maintaining NDPR compliance.
- BFSI:Deposit money banks face encrypted-at-rest mandates under Central Bank risk management guidelines. BFSI procurement concentrates on self-encrypting drives with FIPS 140-2 Level 3 certification, prioritizing vendors with Lagos-based certification support.
- Healthcare:Teaching hospitals and diagnostic chains store imaging archives and patient records under emerging data protection obligations. Healthcare storage demand remains nascent compared to financial verticals, with most facilities relying on hybrid cloud for disaster recovery.
BFSI commands the densest performance-tier procurement; IT Services is climbing the fastest as systems integrators consolidate multi-tenant infrastructure.
Technology:
Protocol selection determines power consumption, latency floors, and integration complexity against Nigeria's constrained grid environments and legacy Fibre Channel investments.
- SAS:Serial Attached SCSI protocol delivering 12Gbps throughput on dual-ported drives. SAS persists in nearline tier deployments at Lagos colocation facilities where rack power limits previously favored hybrid configurations over all-flash density.
- SATA:Lower-cost serial interface prioritizing capacity economics over IOPS performance. SATA dominates cold storage and backup tiers among mid-tier enterprises with limited capital allocation for performance optimization.
- NVMe:Non-Volatile Memory Express protocol over PCIe fabrics, delivering sub-100 microsecond latency. NVMe is displacing SAS in BFSI and IT Services verticals where real-time analytics workloads proliferate and diesel generator runtime costs reward IOPS-per-watt efficiency.
- Fibre Channel:Dedicated storage networking protocol operating at 32Gbps in current-generation switches. Fibre Channel fabrics from 2012-2016 procurement waves resist seamless NVMe-oF migration, forcing phased retirement timelines at tier-two banks.
NVMe captures the steepest expansion trajectory; Fibre Channel retains installed base dominance in legacy SAN environments.
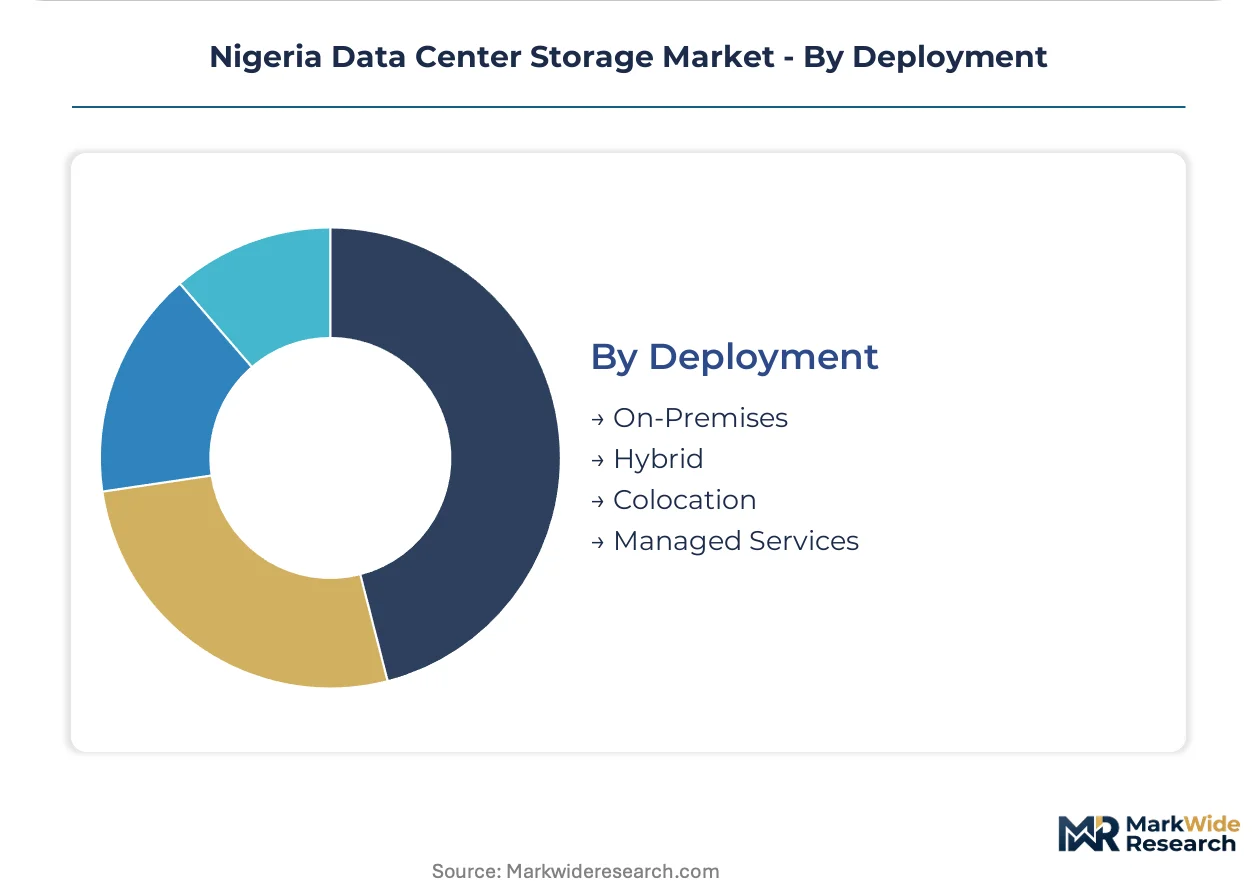
Deployment:
Power reliability and foreign exchange exposure shape whether Nigerian enterprises absorb capacity through ownership, colocation, or utility consumption models.
- On-Premises:Customer-owned and operated storage infrastructure within corporate facilities. On-Premises deployment faces 34-40% total cost of ownership inflation from diesel generator dependency at Lagos facilities with 18-24 hour daily runtime requirements.
- Hybrid:Architectures combining local performance tiers with cloud capacity for burst and archival workloads. Hybrid configurations accelerate as Equiano cable latency reductions enable seamless tiering between Lagos edge and European hyperscale regions.
- Colocation:Leased space in carrier-neutral or wholesale data centers with customer-managed storage. Colocation absorption concentrates in Lagos Mainland and Lekki corridors where submarine cable landings and certified facility density cluster.
- Managed Services:Fully outsourced storage operations including hardware, software, and administration. Managed Services is gaining traction among mid-tier enterprises seeking to transfer diesel cost volatility and certified technician scarcity risks to specialist operators.
Colocation handles the majority of new capacity absorption; Managed Services is expanding most quickly as buyers seek to offload operational risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MainOne and Equiano submarine cable landings in Lagos anchor Nigeria's data center storage expansion, reducing latency to European cloud regions and concentrating certified facility investments along the Lekki corridor.
Lagos State
OPay and PalmPay drive petabyte-scale procurement for Central Bank transaction logging mandates. The National Information Technology Development Agency enforces data sovereignty compliance for all foreign cloud operators hosting personal data. Ikeja and Lekki districts cluster tier-III facilities where Dell PowerStore and Huawei arrays compete for fintech workloads.
Abuja
Federal government data localization requirements generate demand for encrypted storage architectures. The Nigeria Data Protection Regulation mandates certified hosting for ministries processing citizen biometric records. Jabi and Central Business District zones attract carrier-neutral developments targeting diplomatic and regulatory institution procurement.
Kano
Tier-two banks deploy Direct Attached Storage for isolated transaction logging under Central Bank audit trail rules. The national grid's unreliability forces diesel-dependent total cost of ownership calculations at 34-40% premiums versus southern comparators. Bompai Road financial district remains underserved for tier-III certified capacity.
Port Harcourt
Oil and gas operators require disaster recovery infrastructure for upstream operational data. The Nigerian National Petroleum Corporation's digital transformation programs stimulate hybrid cloud procurement. Trans Amadi industrial zone hosts emerging colocation facilities awaiting submarine cable extensions.
South-East Region
Onitsha and Aba manufacturing clusters generate nascent demand for edge storage supporting IoT and inventory systems. The region lacks submarine cable proximity, limiting hybrid architecture adoption versus Lagos-based alternatives. Local system integrators deploy software-defined storage on commodity hardware to bypass branded array premiums.
Nigeria Data Center Storage Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and foreign exchange hedging capabilities. The vendor base stratifies into three tiers: multinational incumbents with Lagos certification support, Chinese price-competitive challengers, and regional system integrators deploying open-source software-defined platforms. Dominant competitive moves include as-a-service contract structuring to reduce capital intensity and strategic partnerships with diesel generator operators to guarantee power resilience.
Within the multinational tier, Dell Inc. and Hewlett Packard Enterprise occupy positions anchored by utility consumption models. Huawei Technologies Co. Ltd exemplifies price-performance competition for government and carrier-neutral facilities. These three companies represent divergent approaches to Nigeria's foreign exchange volatility and certified technician scarcity constraints.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| Lenovo Group Limited |
| Oracle Corporation |
| Huawei Technologies Co. Ltd |
| SMART Modular Technologies Inc. |
| QSAN Technology Inc. |
| ADATA Technology Co. Ltd |
| Fujitsu Limited |
| Others |
Pricing and Supply Chain Analysis
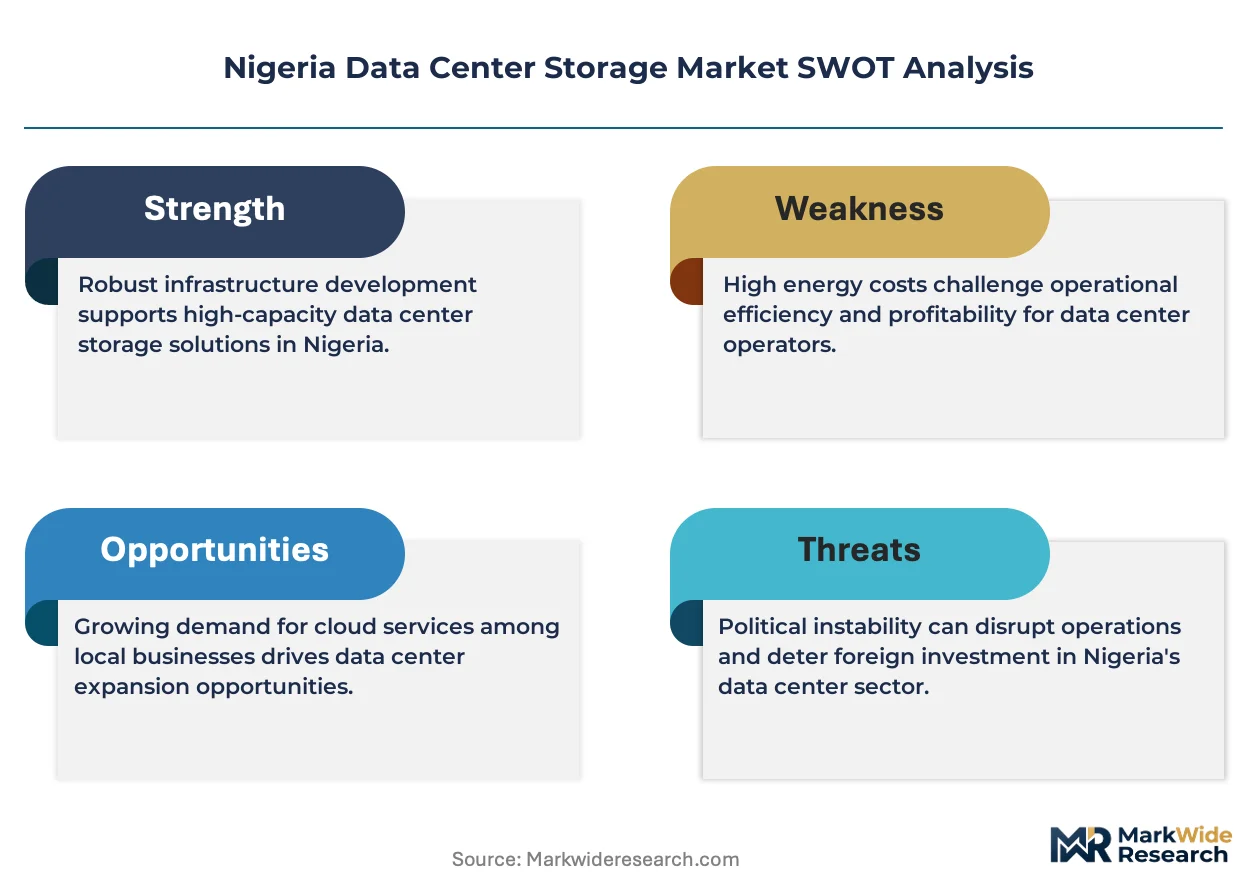
NITDA certification requirements for data residency compliance gate both vendor qualification and price tiering simultaneously, compressing margins for uncertified hardware while elevating premiums for architectures with Lagos-based support infrastructure. Foreign exchange volatility denominates procurement contracts in USD, forcing local-currency revenue streams into hedging costs that reshape total cost of ownership calculations across deployment modes.
Pricing Analysis
Volume-discount tiering structures separate petabyte-scale fintech deployments from mid-tier colocation commitments, with OPay and PalmPay extracting steep concessions unavailable to capital-constrained SMEs. Three-tier pricing stratifies across FIPS 140-2 Level 3 certified arrays, NDPR-compliant standard configurations, and refurbished economy alternatives. Pricing pressure stems from Huawei's aggressive price-performance positioning in government tenders. SMEs exhibit highest price sensitivity; tier-one banks prioritize certification over unit cost.
Supply Chain Analysis
Inventory lead times stretch 16-22 weeks for NVMe flash modules as Nigerian distributors buffer against naira depreciation and customs clearance delays. Manufacturing concentrates in China, South Korea, and Taiwan for NAND fabrication, with assembly operations in Malaysia and Vietnam feeding Lagos distribution channels. Supply chain risk centers on single-source vulnerability for enterprise-grade controllers. Distribution runs through Lagos-based system integrators with NITDA authorization rather than direct vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud storage substitution threatens on-premises array incumbents as MainOne latency reductions enable seamless hybrid tiering, forcing defensive repositioning around compliance-certified local capacity.
For Market Incumbents: Shield installed base relationships by embedding diesel-resilience guarantees into managed service contracts, offsetting the 34-40% total cost of ownership premium that cloud alternatives exploit. Deepen backward integration into Lagos certification training pipelines to address the sub-400 NITDA-authorized architect bottleneck constraining competitor deployment velocity. For New Entrants and Emerging Players: Software-defined storage deployment expertise represents the most penetrable service-layer gap, as Dell and HPE prioritize branded array margins over commodity-hardware Ceph integrations. Target Kano and Port Harcourt metro expansions with NDPR-compliant SUSE Enterprise Storage bundles, bypassing the Lekki corridor's saturated competitive intensity through first-mover positioning ahead of submarine cable extensions. For Investors and Strategic Acquirers: Central Bank encrypted-at-rest mandates for 184 deposit money banks reshape the acquisition landscape toward certified architecture specialists with Lagos support presence. Five-to-ten year viability favors vertically integrated operators controlling both hardware procurement and diesel-generator power resilience. Watch CBN risk management guideline enforcement velocity as the inflection signal determining upgrade mandate compliance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Support Localization | NITDA-authorized training pipelines in Lagos reduce deployment bottlenecks for flash array rollouts. |
| As-a-Service Contract Structuring | HPE GreenLake utility models preserve foreign exchange for MTN and Airtel core network investments. |
| Secondary Metro Facility Development | Carrier-neutral tier-III capacity in Kano captures first-mover positioning before cable landings arrive. |
| Software-Defined Storage Convergence | Ceph deployments on commodity hardware bypass branded premiums while maintaining NDPR compliance. |
| Diesel Resilience Partnerships | Generator operator alliances guarantee power continuity for high-density flash arrays in grid-unreliable environments. |
Research Methodology
A spread of perspectives from data center infrastructure planners, NITDA compliance officers, fintech CTOs, and colocation facility operators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against Central Bank directives, NDPR enforcement notices, and submarine cable operator technical specifications. Customs and trade data, hyperscaler capex disclosures, and vendor certification records anchored bottom-up and top-down triangulation across the analysis window.
Segmentation dimensions modeled include deployment mode, protocol technology, end-user vertical, and product architecture type across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating diesel cost trajectories and foreign exchange volatility assumptions. Forecast inputs weighted submarine cable latency improvements against grid reliability investment timelines.
Forecasts assume regulatory continuity in NDPR enforcement and CBN risk management frameworks; material policy shifts would require re-modeling. Revision becomes warranted when naira depreciation velocity or diesel subsidy removal crosses thresholds altering total cost of ownership parity between on-premises and cloud alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
United States Data Center Storage Market