
 Hard Disk Market | 2026-2036
Hard Disk Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Disk Market Intelligence
Glass substrate material is hardening as the dominant platter medium, replacing aluminum alloys in high-capacity drives due to superior thermal stability and thinner form factors. Seagate Technology leverages its integrated media operations to control cost structures across enterprise segments. Western Digital sustains competitive pressure through vertical alignment with flash memory portfolios. Toshiba anchors supply continuity for nearline storage deployments in Asian manufacturing corridors.
A hard disk drive is an electromechanical data storage device that uses magnetically coated rigid platters spinning at speeds typically between 5,400 and 15,000 revolutions per minute, with read/write heads floating nanometers above the surface on an air bearing. Its primary commercial purpose is persistent, high-volume, random-access data retention at lower cost per terabyte than solid-state alternatives. Enterprise HDD and surveillance HDD represent the most durable margin pools, with the former capturing value from 24/7 operational reliability requirements and the latter expanding alongside IP camera network densification. Desktop HDD persists as a mature, contracting segment as personal computing shifts toward solid-state boot drives, while external HDD occupies a niche in consumer backup and creative professional workflows.
FCC equipment authorization rules govern electromagnetic emissions for drives sold into US computing systems, while EU RoHS and REACH frameworks restrict hazardous substances in platter coatings and actuator assemblies. China's GB standards and MIIT certification requirements shape market access for foreign suppliers serving domestic server builders. Japan's METI energy efficiency guidelines influence spindle motor designs and idle power specifications. Stakeholders must monitor how energy-assisted magnetic recording transitions from development to volume production, as this technology choice will determine which manufacturers retain cost competitiveness in the highest-density tiers.
Market Dynamics
Heat-assisted magnetic recording is compressing areal density roadmaps and forcing manufacturers to retool fabrication lines before competing solid-state alternatives capture enterprise workloads.
Growth Catalysts
- Data Center Buildouts:Cloud service providers in China are expanding server farms under MIIT certification requirements, pulling nearline HDD volumes upward.
- REACH Compliance:EU restrictions on hazardous platter coatings are accelerating glass substrate adoption across European server OEM supply chains.
- Surveillance Network Densification:IP camera deployments in manufacturing corridors are sustaining demand for high-write-endurance surveillance HDD tiers.
Market Restraints
- Flash Memory Cost Curves:NAND price declines are compressing HDD addressable markets in consumer boot-drive segments.
- Spindle Motor Supply Concentration:Japanese and Taiwanese precision motor suppliers create single-source vulnerability for high-RPM enterprise drives.
- GB Standard Friction:China's mandatory testing protocols delay foreign supplier qualification timelines for domestic server bids.
Strategic Opportunities
- Chilled Storage Tiers:Archive and cold-data applications in North American hyperscale facilities favor high-capacity helium-sealed drives over tape libraries.
- Dual Carbon Alignment:China's national emissions targets are incentivizing energy-efficient spindle designs through preferential procurement scoring.
- AI Training Data Lakes:Machine learning pipelines are generating petabyte-scale sequential write workloads that favor HDD economics over all-flash arrays.
Industry Challenges
- Cleanroom Talent Scarcity:Substrate polishing and thin-film deposition expertise concentrates in aging workforces across Japanese and Korean manufacturing hubs.
- Legacy Array Integration:Enterprise storage managers face firmware compatibility gaps when mixing energy-assisted recording drives with existing RAID controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Disk Market |
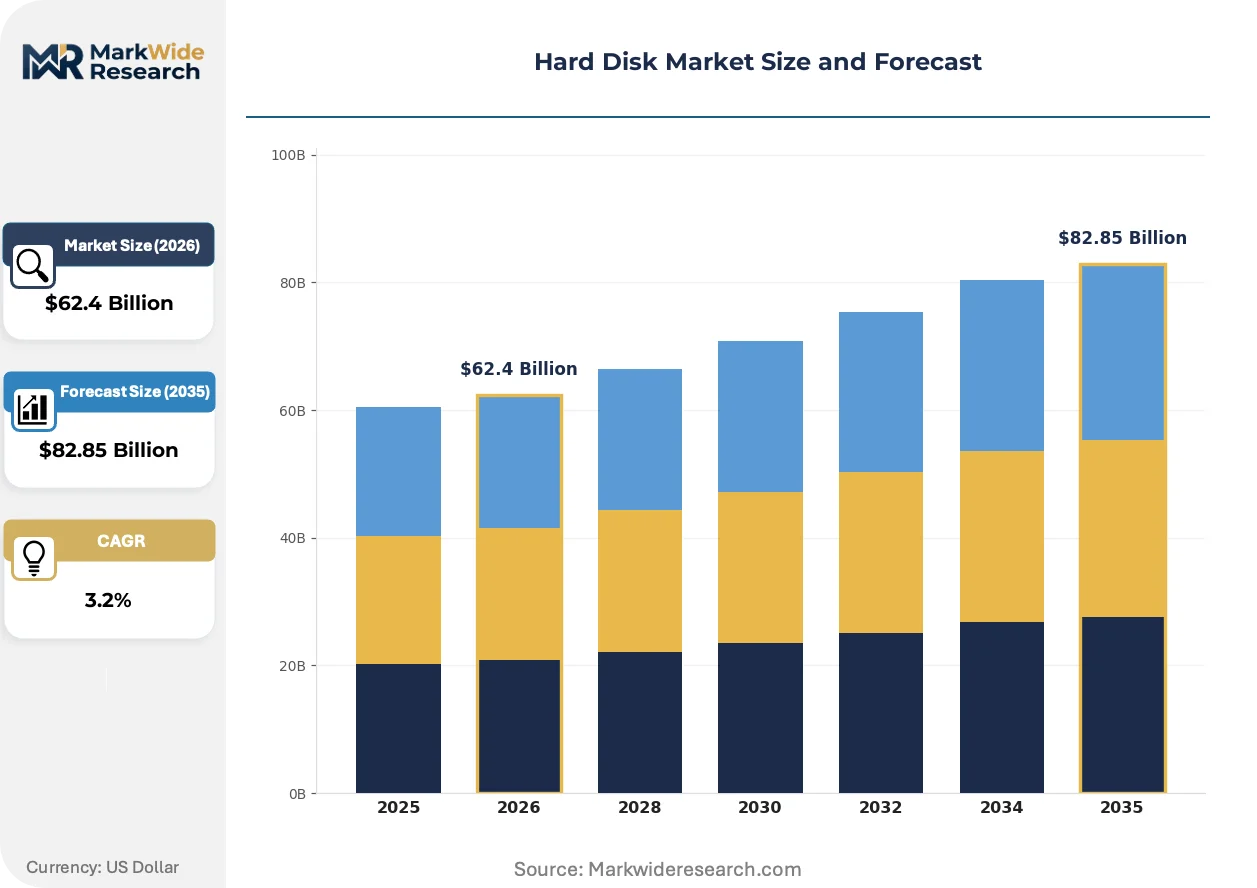
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $82.85 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop HDD, Laptop HDD, External HDD, Enterprise HDD, Surveillance HDD Technology: Perpendicular Magnetic Recording, Shingled Magnetic Recording, Heat-Assisted Magnetic Recording, Energy-Assisted Magnetic Recording Application: Data Centers, Cloud Storage Providers, Video Surveillance Systems, Personal Computing, Gaming Systems End User: Original Equipment Manufacturers, Data Storage Service Providers, Small and Medium Enterprises, Research Institutions |
| Companies Covered | Hitachi Global Storage Technologies, Intel Corporation, Western Digital, SK Hynix, Micron Technology, Seagate Technology, Samsung Electronics, Kioxia Holdings, Toshiba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Disk Market Strategic Shifts & Innovations
Recording physics breakthroughs and energy-efficiency mandates are rewriting product roadmaps faster than procurement cycles can absorb, creating temporary mismatches between supply capabilities and buyer specifications.
Heat-assisted magnetic recording employs a laser-diode-integrated head to transiently heat platter surfaces during writes, enabling smaller magnetic grains without thermal instability. Hyperscale operators in the United States are qualifying HAMR-based nearline drives for 24/7 archive tiers. This technology is decentralizing areal density leadership away from traditional perpendicular magnetic recording incumbents toward suppliers with integrated laser fabrication capabilities.
EU F-Gas Regulation is phasing down hydrofluorocarbon use in precision manufacturing cleanrooms, forcing HDD component suppliers to retool etching and deposition processes. The industrial consequence is extended qualification timelines for new substrate materials. European server OEMs are responding by dual-sourcing glass media from Asian suppliers with alternative chemistries.
Hyperscale buyers are consolidating storage procurement under direct supplier contracts, bypassing traditional distributor channels for high-volume nearline orders. Value-added resellers serving mid-market enterprises are losing HDD attach rates to manufacturer-direct programs. This channel compression is most visible in North American and Chinese cloud-adjacent data center construction corridors.
Hard Disk Market Segmentation
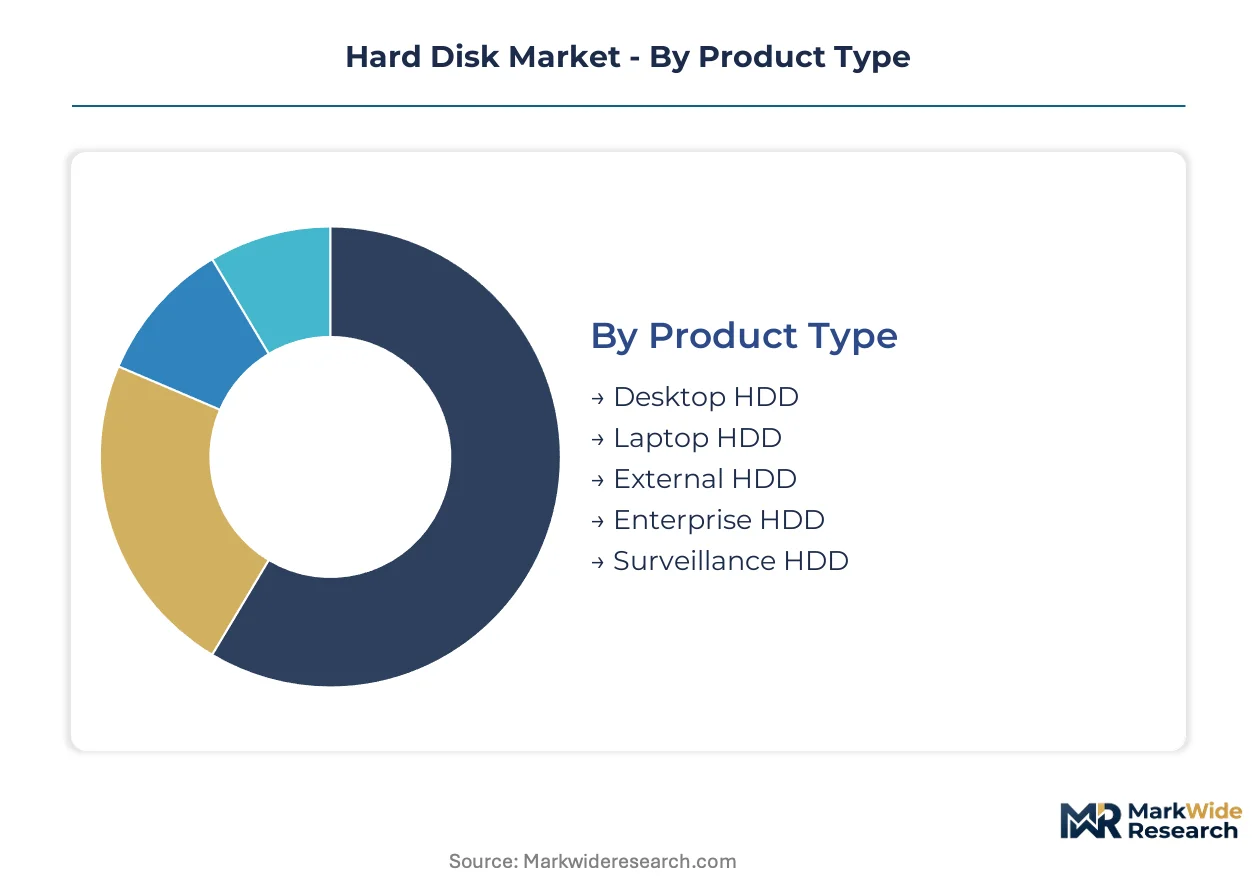
Hard disk segmentation reveals how manufacturers balance standardized volume production against specialized configurations for mission-critical environments. Product architecture, recording physics, deployment context, and procurement relationships each create distinct margin tiers and competitive barriers.
Product Type:
Standardization dominates consumer-grade formats while enterprise variants demand extensive customization for thermal envelopes and vibration tolerance.
- Enterprise HDD:These units deploy helium-sealed enclosures with dual-stage actuators and vibration compensation for 24/7 rack-mounted operation. Hyperscale facilities in the United States and China specify these drives for warm-tier storage under direct procurement contracts. Reliability premiums sustain manufacturer margins despite NAND competition.
- Surveillance HDD:Optimized for high-write endurance and sequential streaming from multi-camera arrays, these drives tolerate wider temperature swings than standard nearline products. Manufacturing corridors across Asia deploy these in IP camera networks where 90-day retention cycles are mandatory. Firmware tuning for write-heavy workloads differentiates suppliers.
- Desktop HDD:Mature segment facing displacement as solid-state boot drives capture consumer preference. Remaining demand concentrates in budget system builders and secondary storage applications.
- External HDD:Portable and desktop-class enclosures serving creative professionals and consumer backup workflows. USB interface standardization limits differentiation to industrial design and bundled software.
- Laptop HDD:Thin form factors for legacy mobile systems. Volumes contract as ultrabook and tablet architectures eliminate mechanical storage entirely.
Leading the category by volume: Desktop HDD. Growing fastest: Enterprise HDD.
Technology:
Cost tiers separate legacy recording methods from energy-assisted architectures requiring capital-intensive fabrication retooling.
- Heat-Assisted Magnetic Recording:Laser-integrated heads transiently heat media during writes, enabling magnetic grains below thermal stability limits without demagnetization. Seagate Technology has qualified these drives for hyperscale archive tiers. The technology shifts areal density leadership toward suppliers with captive laser diode fabrication.
- Perpendicular Magnetic Recording:Established technology with mature tooling and qualified supply chains. Remains cost-competitive for capacity tiers below energy-assisted thresholds.
- Shingled Magnetic Recording:Overlapping write tracks boost areal density but impose sequential-write constraints unsuitable for random-access workloads. Cold storage and backup applications absorb these drives where write patterns are predictable.
- Energy-Assisted Magnetic Recording:Umbrella category including microwave-assisted and other emerging thermal or field-assisted methods. Development-stage technologies competing for roadmap positioning beyond HAMR.
Highest volume production: Perpendicular Magnetic Recording. Steepest expansion trajectory: Heat-Assisted Magnetic Recording.
Application:
Customer type determines whether procurement flows through distributor channels or direct manufacturer relationships.
- Data Centers:Colocation and enterprise facilities specifying drives for primary and secondary storage tiers. Power consumption and failure rate guarantees drive supplier selection.
- Cloud Storage Providers:Hyperscale operators qualifying drives through extended burn-in protocols before volume deployment. Direct contracts displace traditional distribution.
- Video Surveillance Systems:Security integrators and municipal operators deploying multi-petabyte arrays. Retention regulations and camera count growth sustain demand.
- Personal Computing:Declining segment as retail channels shift attach rates toward solid-state alternatives.
- Gaming Systems:Console manufacturers and PC builders specifying high-capacity drives for local game libraries. Solid-state expansion cards capture premium tier.
Dominant procurement volume: Data Centers. Gaining share fastest: Cloud Storage Providers.
End User:
Supply relationships range from arm's-length component sales to deeply integrated co-development partnerships.
- Data Storage Service Providers:Cloud and managed storage operators with direct supplier engineering engagement. These buyers influence product roadmaps through volume commitments and qualification feedback.
- Original Equipment Manufacturers:Server and storage array builders integrating drives into branded systems. Procurement leverage varies with scale and vertical integration.
- Small and Medium Enterprises:Mid-market buyers purchasing through value-added resellers. Channel compression erodes attach rates as manufacturer-direct programs expand.
- Research Institutions:Specialized requirements for high-performance computing and archival scientific data. Volumes limited but specifications often preview enterprise features.
Largest procurement scale: Data Storage Service Providers. Fastest relationship restructuring: Small and Medium Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center construction in China is pulling disproportionate HDD volumes, while regulatory friction and energy mandates are reshaping procurement patterns across Germany, Japan, and the United States.
China
MIIT certification requirements for domestic server deployments are accelerating nearline HDD absorption by cloud service providers in Beijing and Shanghai. The country's dual carbon goals are incentivizing energy-efficient spindle designs through preferential procurement scoring. Yangtze River Delta manufacturing corridors host expanding glass substrate polishing facilities serving regional drive assembly.
United States
FCC equipment authorization rules govern electromagnetic emissions for drives sold into hyperscale facilities across Virginia, Texas, and Oregon. Hyperscale operators are consolidating storage procurement under direct supplier contracts, bypassing traditional distributor channels. Northern Virginia's data center cluster represents the densest concentration of HAMR qualification activity.
Germany
EU F-Gas Regulation is phasing down hydrofluorocarbon use in precision manufacturing cleanrooms, forcing component suppliers to retool etching processes. REACH restrictions on hazardous platter coatings are accelerating glass substrate adoption across European server OEM supply chains. Bavaria's industrial automation sector sustains demand for high-reliability enterprise drives.
Japan
METI energy efficiency guidelines influence spindle motor designs and idle power specifications for drives deployed in domestic and export markets. Japanese precision motor suppliers maintain critical positions in high-RPM enterprise drive supply chains. Tokyo-Osaka manufacturing corridors concentrate substrate polishing expertise and thin-film deposition capabilities.
South Korea
Memory semiconductor specialists are extending flash memory cost curves that compress HDD addressable markets in consumer segments. The country's national emissions targets are reshaping industrial procurement criteria for storage infrastructure. Seoul Capital Area data center operators are qualifying helium-sealed drives for warm-tier storage deployments.
Hard Disk Market Key Industry Players
Technology licensing dominates the current landscape as manufacturers seek captive laser diode fabrication capabilities for energy-assisted recording transitions. The vendor base concentrates around three integrated specialists with in-house media operations, mid-scale fabricators dependent on external substrate supply, and memory-diversified conglomerates with flash-HDD portfolio breadth. Strategic archetypes separate integrated recording head manufacturers from substrate-dependent assemblers and memory-captive diversifiers. Competitive moves center on fabrication line retooling for HAMR volume production and direct procurement contract capture with hyperscale operators.
Within the integrated specialist tier, Seagate Technology and Western Digital exemplify manufacturers with captive media operations controlling cost structures across enterprise segments. Toshiba occupies a position anchoring supply continuity for nearline storage deployments in Asian manufacturing corridors. Samsung Electronics represents the memory-diversified archetype, extending competitive pressure through portfolio alignment with flash memory economics.
| Leading Market Players |
|---|
| Hitachi Global Storage Technologies |
| Intel Corporation |
| Western Digital |
| SK Hynix |
| Micron Technology |
| Seagate Technology |
| Samsung Electronics |
| Kioxia Holdings |
| Toshiba |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud operators consolidating procurement under direct manufacturer contracts have compressed distributor margins and shifted pricing power toward volume-tiered contract structures. This buyer concentration rewards suppliers with captive laser diode fabrication and helium-sealed enclosure capabilities while penalizing assemblers dependent on external substrate sourcing.
Pricing Analysis
High-volume nearline drives for data center deployment capture thin margins at massive scale, while enterprise HDD with vibration compensation and dual-stage actuators sustain premium pricing through reliability guarantees. Price differentiation rests on certification tier—MIIT-qualified drives for Chinese domestic server bids command premiums over standard FCC-authorized units—and helium-sealed versus air-filled enclosure technology. Cost compression in consumer desktop tiers is intensifying because NAND flash price declines erode addressable HDD volumes. Small and medium enterprises purchasing through value-added resellers exhibit highest price sensitivity, whereas hyperscale operators with direct engineering engagement prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
China's GB standards and domestic-content preferences for government server procurement are reshaping sourcing patterns toward Yangtze River Delta glass substrate polishing facilities. Manufacturing concentrates in China, Japan, and Thailand, with Japanese precision motor suppliers maintaining critical positions in high-RPM spindle production. Raw material dependencies include rare-earth magnets for voice coil motors, chemically strengthened glass substrates, and laser diodes for HAMR heads. Single-source vulnerability in Japanese and Taiwanese spindle motor suppliers creates structural risk for enterprise drive output. Distribution runs through manufacturer-direct programs for hyperscale buyers, while mid-market enterprises rely on eroding value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hard disk market is becoming a vertical-integration race, with laser diode fabrication and captive media operations determining which manufacturers retain cost competitiveness as energy-assisted recording transitions to volume production.
For Market Incumbents: Lock in hyperscale direct procurement relationships through extended burn-in qualification programs and roadmap co-development partnerships. Secure captive supply of laser diodes and glass substrates to defend against flash memory cost curves compressing HDD addressable markets. Prioritize helium-sealed enclosure capacity additions in Thailand and China to satisfy MIIT-certified domestic server demand. For New Entrants and Emerging Players: Enter via specialized surveillance HDD firmware tuning for Asian manufacturing corridor IP camera networks, where 90-day retention mandates sustain niche demand. Target cold-storage archive tiers in North American hyperscale facilities where sequential-write-optimized shingled magnetic recording drives face limited NAND competition. Pursue white-label supply agreements with security integrators lacking direct manufacturer access. For Investors and Strategic Acquirers: The window for entry favors substrate polishing and thin-film deposition specialists with aging workforce expertise in Japanese and Korean manufacturing hubs. Long-term viability hinges on energy-assisted recording technology transitions, making integrated laser fabrication capabilities the critical acquisition target archetype. Watch HAMR qualification completion rates at hyperscale facilities as the inflection indicator for technology leadership consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| HAMR Volume Production Retooling | Seagate Technology's integrated laser diode fabrication shifts areal density leadership away from PMR incumbents. |
| Helium-Sealed Enclosure Expansion | Western Digital's vertical alignment with flash memory portfolios pressures pure-play HDD suppliers. |
| Direct Procurement Program Capture | Hyperscale operators in Virginia and Shanghai bypass distributors, compressing value-added reseller attach rates. |
| Glass Substrate Supply Diversification | EU F-Gas Regulation forces European server OEMs toward Asian suppliers with alternative chemistries. |
| MIIT Certification Qualification | China's mandatory testing protocols delay foreign supplier timelines, favoring domestic assembly partnerships. |
Research Approach
SEC 10-K filings, MIIT equipment certification databases, and hyperscaler capital expenditure disclosures formed the secondary backbone for volume and value estimation. Primary interviews with data center procurement officers, storage array firmware engineers, and glass substrate plant managers validated supply chain assumptions. Bottom-up triangulation against top-down macroeconomic drivers ensured segmentation coherence across enterprise, surveillance, and consumer HDD tiers.
Bottom-up modeling of unit shipments by recording technology and enclosure type combined with top-down macroeconomic absorption rates across the projection horizon. Segmentation dimensions included product architecture, application context, and procurement relationship type. CAGRs derived from elasticity analysis of cloud infrastructure investment cycles and NAND flash substitution patterns. Industry-specific inputs incorporated spindle motor supplier capacity constraints and cleanroom talent availability in Japanese manufacturing corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt NAND price decline scenarios or HAMR yield shortfalls. Forecasts reflect assumptions about energy-assisted recording transition timing and hyperscale qualification protocols. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market