
 Brazil Data Center Storage Market | 2026-2036
Brazil Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Storage Market Insights
LGPD enforcement is decoupling data residency requirements from legacy cross-border hosting arrangements. Ascenty leverages its vertically integrated campus design to control power and connectivity costs across São Paulo and Rio de Janeiro. Scala Data Centers anchors its expansion strategy in secondary Brazilian cities where land and energy costs undercut metro premiums. Equinix competes through interconnection density that appeals to multinational enterprises requiring low-latency links to Miami and Buenos Aires.
Brazil data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention at enterprise scale, typically operating across temperature ranges of 0°C to 60°C and latency thresholds below 10 milliseconds for tier-one workloads. These systems serve financial transaction logging, healthcare imaging archives, and e-commerce transaction databases that must remain accessible under LGPD-mandated retention schedules. SSD deployments command premium positioning due to performance density requirements in São Paulo's hyperscale corridors, while hybrid storage configurations occupy the mid-market where BFSI clients balance hot-tier speed against cold-archive economy. Tape storage persists in regulated backup and disaster recovery segments where air-gapped immutability satisfies ANPD audit protocols for sensitive personal data.
ANPD, the national data protection authority, shapes procurement standards through enforcement actions that mandate encryption and access logging for all personal data repositories. BIS-equivalent telecommunications certification from Anatel governs storage hardware interconnect standards, while central bank circulars from Banco do Brasil impose retention granularity on financial institutions. Stakeholders must monitor how LGPD secondary regulations on cross-border data flows redirect hyperscaler buildout decisions between domestic expansion and regional hub strategies.
Market Dynamics
LGPD enforcement is compressing cross-border hosting arrangements and forcing domestic storage capacity expansion across Brazilian financial and healthcare sectors. This regulatory pressure is accelerating capital deployment into São Paulo state hyperscale corridors while reshaping procurement criteria for data residency compliance.
Growth Catalysts
- Central Bank Digital Compliance:Banco do Brasil circulars mandate granular transaction retention, forcing Brazilian banks to expand electromechanical and solid-state storage infrastructure for audit-ready logging systems.
- Healthcare Imaging Archive Expansion:Diagnostic networks across Minas Gerais and Rio de Janeiro are deploying petabyte-scale storage for DICOM-compliant radiology retention under LGPD-mandated schedules.
- NVMe-over-Fabric Adoption:Flash storage protocols are reducing latency thresholds below 10 milliseconds for tier-one financial workloads in São Paulo's hyperscale facilities.
Market Restraints
- Import Tariff Structure:Anatel certification requirements and BIS-equivalent telecommunications levies inflate solid-state drive landed costs for non-local assembly configurations.
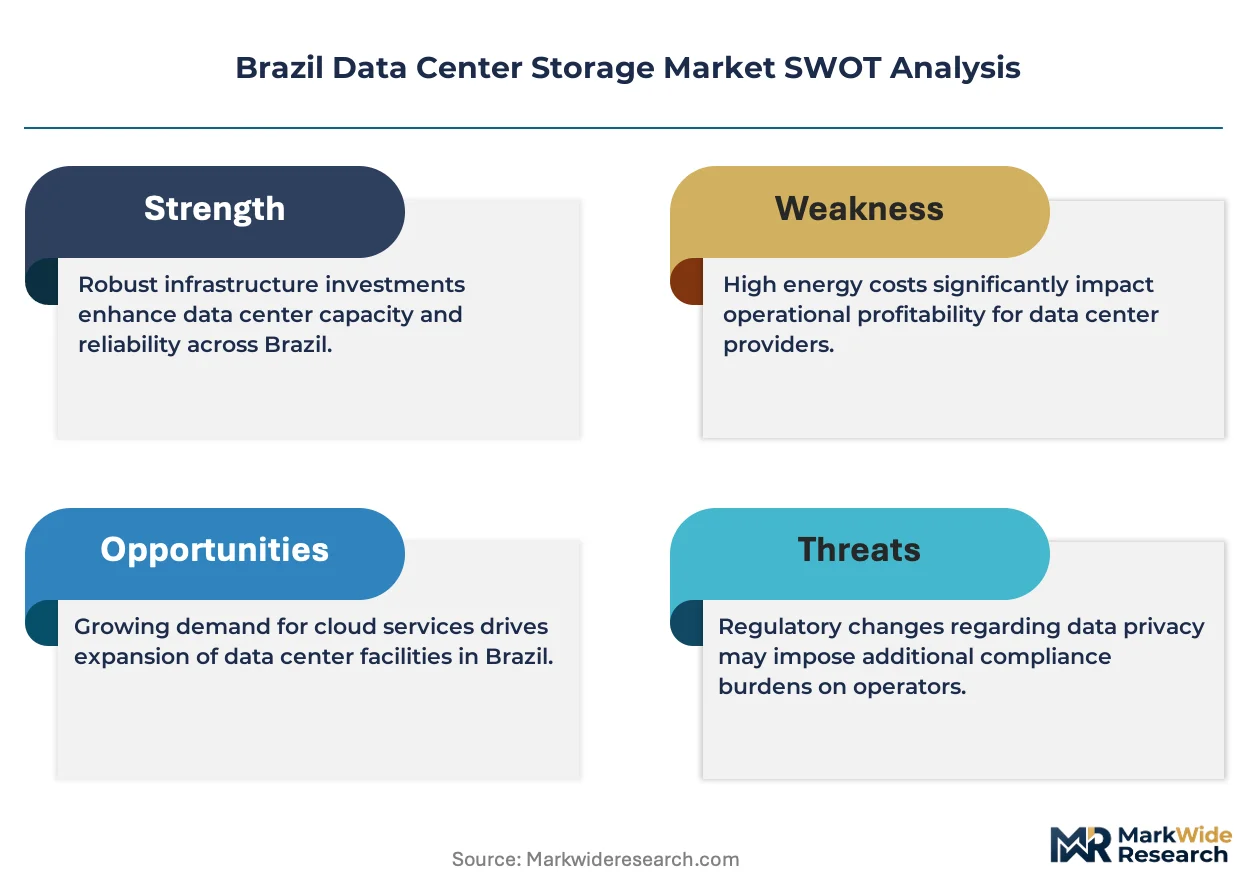
- Grid Power Concentration:Over 60 percent of certified data center capacity clusters in São Paulo state, creating single-region exposure to transmission constraints and energy price volatility.
- Tape Archive Persistence:Air-gapped magnetic storage retains cost advantages for ANPD audit protocols, slowing all-flash displacement in regulated backup segments.
Strategic Opportunities
- Secondary City Expansion:Scala Data Centers and competitors are anchoring buildouts in Campinas and Curitiba where land and energy costs undercut metro premiums by 30-40 percent.
- Edge Computing Convergence:5G network densification is integrating micro data centers with distributed storage nodes for low-latency IoT processing in industrial zones.
- State Tax Incentive Zones:São Paulo's ICMS reduction programs for technology infrastructure are redirecting hyperscaler investment toward certified campus developments.
Industry Challenges
- ANPD Certification Timelines:Encryption and access logging compliance reviews for personal data repositories extend procurement cycles by 4-6 months for BFSI clients.
- Legacy System Integration:Hybrid storage configurations face protocol translation complexity when bridging mainframe transaction logs with modern object storage architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Storage Market |
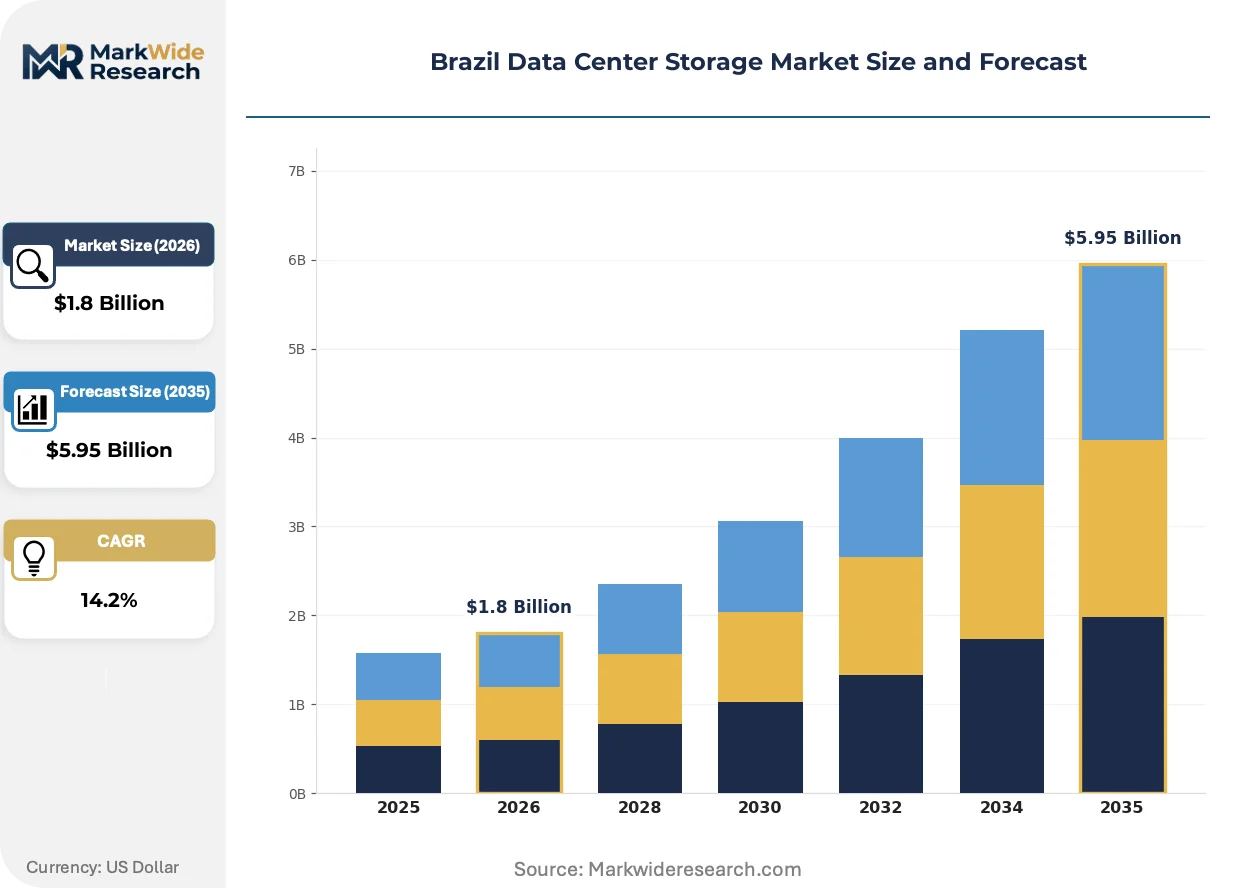
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SSD, HDD, Hybrid Storage, Tape Storage Service Type: Managed Services, Cloud Storage, Backup Solutions, Disaster Recovery End User: Telecommunications, BFSI, Healthcare, E-Commerce Deployment: On-Premises, Off-Premises, Hybrid, Colocation |
| Companies Covered | Ascenty, Equinix, Scala Data Centers, ODATA, Elea Data Centers, Cirion Technologies, Angola Cable, Amazon Web Services, Microsoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Storage Market Trends and Innovations
Computational storage architectures and regulatory automation are compressing traditional hardware refresh cycles while elevating software-defined management platforms. These shifts are reconfiguring vendor competitive positioning around firmware capabilities rather than raw capacity metrics.
Computational storage drives with embedded processing capabilities are integrating analytics functions directly at the data layer, eliminating host CPU bottlenecks for real-time fraud detection workloads. Brazilian card payment processors are adopting these architectures to meet sub-50-millisecond authorization requirements. The technology is integrating encryption and compression pipelines that previously required separate appliance layers, collapsing rack space requirements in São Paulo financial corridors.
ANPD secondary regulations on cross-border data flows are mandating technical safeguards for international transfers, including encryption standards and breach notification protocols. These rules are disqualifying legacy hosting arrangements that lack domestic redundancy. Financial institutions in Rio de Janeiro are responding by contracting exclusively with providers offering certified LGPD compliance attestations and in-country backup replication.
Consumption-based storage procurement is replacing traditional capital-heavy acquisition models among mid-market enterprises. Pay-per-terabyte arrangements with local cloud service providers are displacing three-year hardware depreciation cycles for e-commerce and logistics firms. This pattern is most visible in São Paulo state where fiber connectivity density enables real-time tiering between on-premise and hosted infrastructure.
Brazil Data Center Storage Market Segmentation
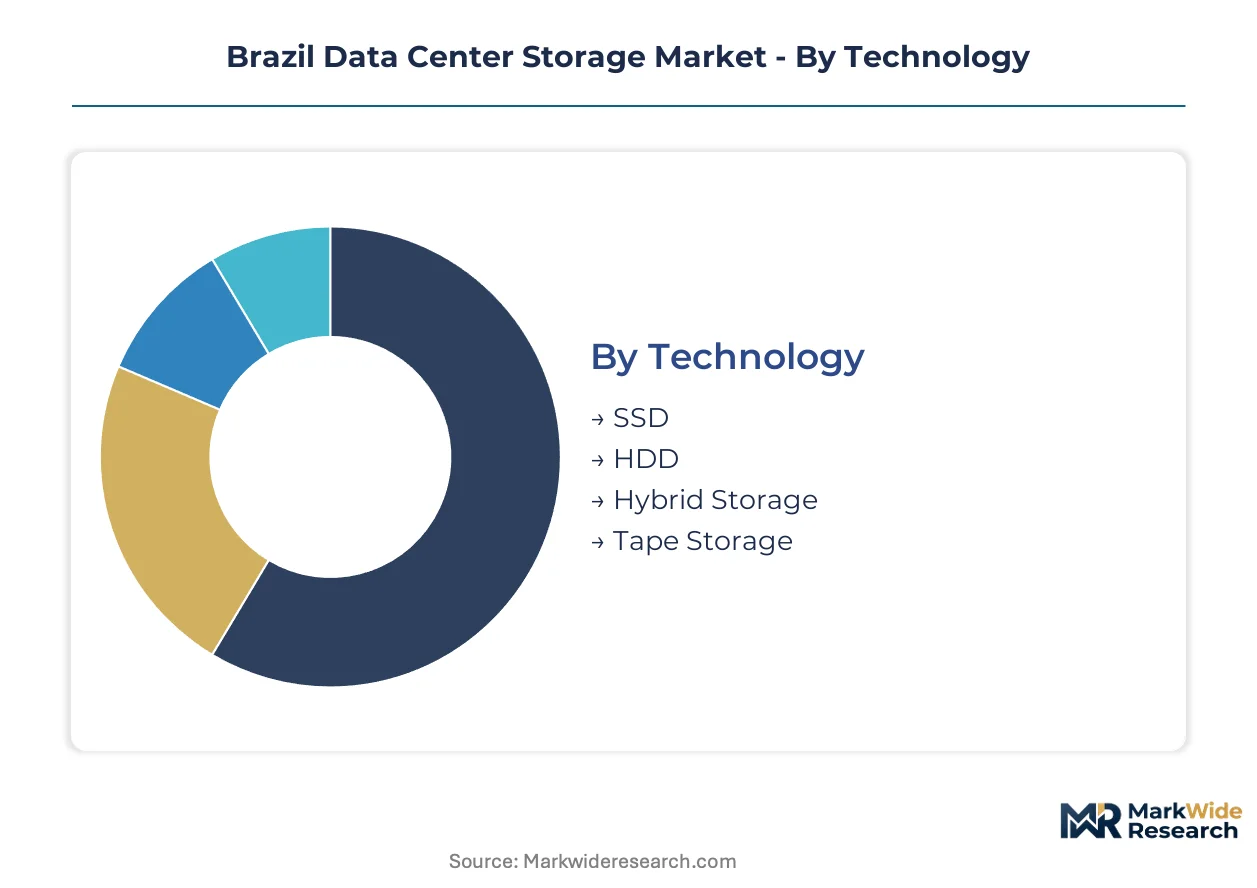
Brazil's data center storage market fragments across technology generations, service models, and deployment architectures that reflect divergent compliance burdens and performance requirements. Understanding these segment boundaries clarifies where capital concentrates versus where margin compression threatens incumbent positioning.
Technology:
Customization intensity spans from commodity electromechanical platforms to firmware-differentiated solid-state systems, with hybrid configurations occupying the configurable middle ground.
- SSD:Flash-based persistent storage leveraging NVMe protocols achieves sub-10-millisecond latency for tier-one financial workloads. São Paulo hyperscale corridors absorb dominant share as Banco do Brasil circulars mandate granular transaction logging with audit-ready retrieval speeds.
- HDD:Electromechanical rotating media delivers cost-efficient capacity for warm-tier data lakes and sequential access patterns. Secondary city expansions in Campinas and Curitiba favor these deployments where land and energy cost advantages stretch depreciation schedules.
- Hybrid Storage:Tiered architectures automatically migrate data between flash and disk layers based on access frequency. Mid-market BFSI clients deploy these systems to balance LGPD-mandated retention against capital constraints.
- Tape Storage:Magnetic linear formats provide air-gapped immutability for ANPD audit protocols. Healthcare imaging archives across Minas Gerais rely on these systems for disaster recovery compliance.
Leading the category by volume: HDD. Growing fastest: SSD.
Service Type:
Margin profiles diverge sharply between capital-intensive infrastructure ownership and recurring revenue service wrappers that monetize operational expertise.
- Managed Services:Third-party operational control over storage infrastructure including provisioning, monitoring, and firmware maintenance. Brazilian banks outsource these functions to compress ANPD certification timelines that otherwise extend procurement cycles.
- Cloud Storage:Consumption-based capacity with pay-per-terabyte economics displacing three-year hardware depreciation. E-commerce platforms in São Paulo state leverage fiber connectivity density for real-time tiering between on-premise and hosted infrastructure.
- Backup Solutions:Point-in-time replication systems ensuring recoverability under LGPD retention schedules. Diagnostic networks across Rio de Janeiro deploy petabyte-scale configurations for DICOM-compliant radiology archives.
- Disaster Recovery:Geographically separated redundancy with automated failover orchestration. Financial institutions contract exclusively with providers offering certified LGPD compliance attestations and in-country backup replication.
Cloud storage commands the steepest expansion trajectory as consumption models displace capital-heavy acquisition.
End User:
Regulatory exposure intensity shapes procurement sophistication, with centrally supervised sectors demanding encrypted, logged, and auditable retention architectures.
- Telecommunications:Network equipment providers and mobile operators storing subscriber metadata and traffic logs under Anatel certification requirements. 5G densification drives distributed storage node deployment for low-latency IoT processing.
- BFSI:Banks, insurers, and payment processors subject to Banco do Brasil circulars mandating granular transaction retention. Card payment processors adopt computational storage drives with embedded processing to meet sub-50-millisecond authorization requirements.
- Healthcare:Hospital networks and diagnostic imaging centers managing DICOM archives under LGPD-mandated schedules. ANPD enforcement actions mandate encryption and access logging for all personal data repositories.
- E-Commerce:Online retail platforms and logistics firms handling consumer transaction histories and behavioral data. Pay-per-terabyte arrangements displace owned infrastructure as these firms prioritize working capital flexibility.
BFSI generates the highest revenue concentration. Healthcare climbs fastest as imaging archive expansion accelerates.
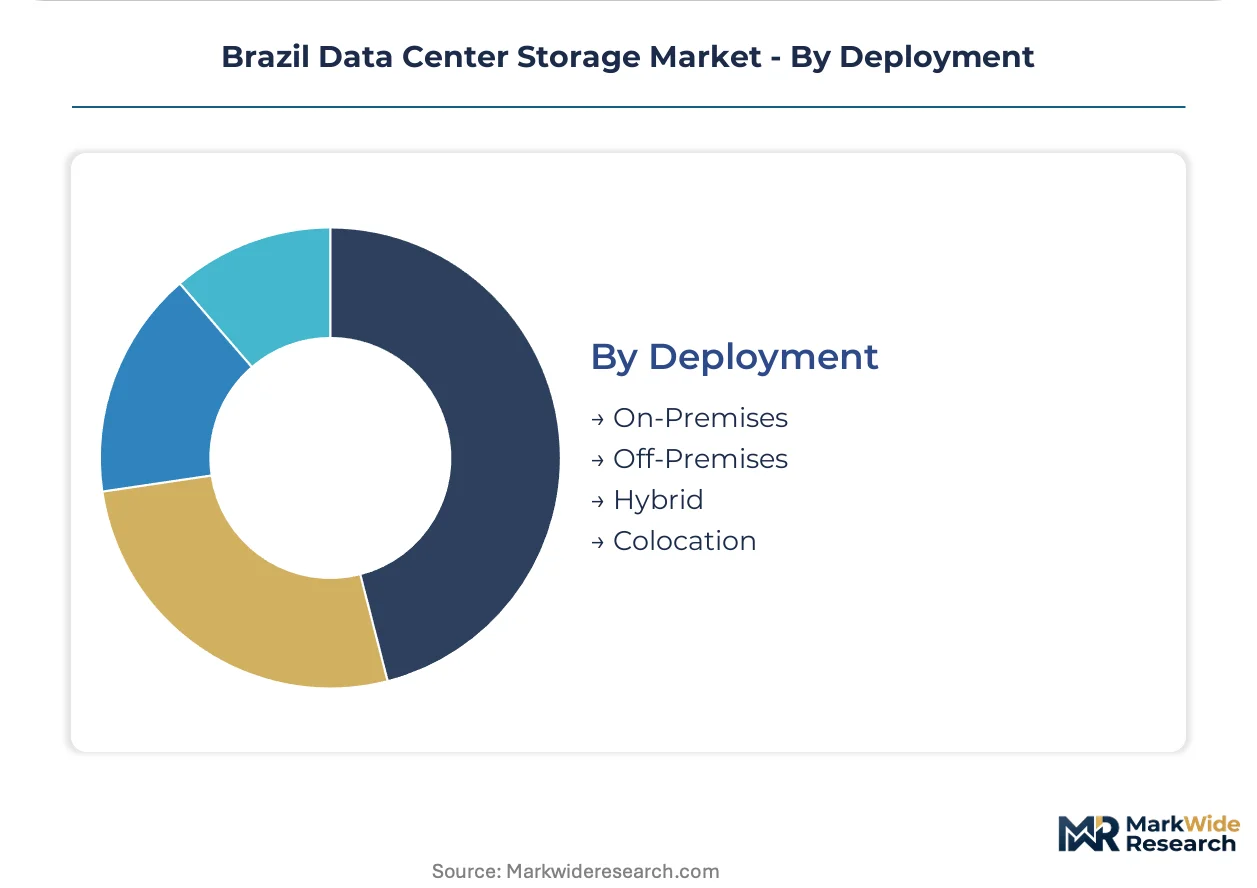
Deployment:
Control spectrum ranges from full captive ownership to shared facility economics, with hybrid architectures capturing organizations navigating LGPD residency ambiguity.
- On-Premises:Captive data center facilities with direct hardware ownership and operational control. Large banks maintain these deployments for core banking systems requiring air-gapped security.
- Off-Premises:Third-party hosted capacity without physical infrastructure ownership. Cloud service providers concentrate investment in São Paulo state due to fiber connectivity density and ICMS tax incentive zones.
- Hybrid:Orchestrated workloads spanning owned and hosted infrastructure with policy-driven data placement. This architecture addresses LGPD enforcement that compresses cross-border hosting arrangements while preserving cloud elasticity.
- Colocation:Leased space within multi-tenant facilities where clients supply hardware and providers deliver power, cooling, and connectivity. Ascenty and Scala Data Centers compete for these deployments across São Paulo and secondary cities.
Colocation leads by installed base. Hybrid deployment gains share fastest as residency compliance reshapes hosting decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in São Paulo state where over sixty percent of certified data center capacity clusters, driven by fiber density and ICMS tax incentives that redirect hyperscaler investment toward certified campus developments.
São Paulo
Financial institutions and cloud service providers dominate procurement as Banco do Brasil circulars mandate granular transaction retention with audit-ready retrieval speeds. ANPD enforcement actions mandate encryption and access logging for all personal data repositories. The state capital anchors hyperscale corridors where Ascenty and Equinix compete through interconnection density appealing to multinational enterprises requiring low-latency links to Miami and Buenos Aires.
Rio de Janeiro
Diagnostic imaging networks deploy petabyte-scale storage for DICOM-compliant radiology retention under LGPD-mandated schedules. Healthcare providers contract exclusively with suppliers offering certified LGPD compliance attestations and in-country backup replication. The metropolitan area serves as a secondary hub where Elea Data Centers and Cirion Technologies target regulated backup and disaster recovery segments.
Minas Gerais
Healthcare imaging archive expansion accelerates across hospital networks managing DICOM archives under LGPD-mandated schedules. Tape storage persists in regulated backup segments where air-gapped immutability satisfies ANPD audit protocols for sensitive personal data. Belo Horizonte functions as a tertiary node where land and energy costs undercut metro premiums by thirty to forty percent.
Paraná
Curitiba attracts secondary city expansion strategies where Scala Data Centers anchors buildouts leveraging land and energy cost advantages. Edge computing convergence with 5G network densification integrates micro data centers with distributed storage nodes for low-latency IoT processing in industrial zones. State-level ICMS reduction programs for technology infrastructure compete with São Paulo incentives.
Brazil Data Center Storage Market Competitive Landscape
Brazilian operators anchor one tier; multinational cloud hyperscalers hold another through differentiated service models. The vendor base separates into vertically integrated campus developers, interconnection-focused platform operators, and consumption-based cloud providers. Three archetypes dominate: facility owners controlling power and connectivity costs, network-dense operators serving low-latency requirements, and scale-driven hyperscalers monetizing elastic capacity. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping positioning.
Within the vertically integrated tier, Ascenty exemplifies campus developers controlling power and connectivity costs across São Paulo and Rio de Janeiro. Equinix occupies a position among interconnection-focused platform operators competing through density that appeals to multinational enterprises. Scala Data Centers represents secondary city specialists anchoring expansion in Campinas and Curitiba where land and energy costs undercut metro premiums.
| Leading Market Players |
|---|
| Ascenty |
| Equinix |
| Scala Data Centers |
| ODATA |
| Elea Data Centers |
| Cirion Technologies |
| Angola Cable |
| Amazon Web Services |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
NVMe-over-Fabric protocol migration simultaneously compresses storage latency economics and concentrates procurement leverage among São Paulo hyperscale operators capable of absorbing premium flash infrastructure at scale. This technology transition rewards vertically integrated campus developers while squeezing margin structures for distributors dependent on legacy HDD inventory turnover.
Pricing Analysis
Volume-vs-margin splits sharply across deployment tiers. Three-tier pricing structure across premium NVMe flash, standard SATA SSD, and economy HDD levels reflects certification grade and performance density requirements. Cost compression in electromechanical tiers is intensifying because secondary city expansions in Campinas and Curitiba stretch depreciation schedules. Mid-market BFSI clients exhibit highest price sensitivity as they balance LGPD-mandated retention against capital constraints, while hyperscale cloud providers demonstrate lowest sensitivity due to consumption-based procurement models.
Supply Chain Analysis
Single-source vulnerability sits with NAND flash wafer fabrication concentrated in South Korea, Taiwan, and USA. Controller silicon and enterprise-grade capacitors draw from these same geographies, creating stacked dependency. Tariff exposure through Anatel certification levies inflates landed costs for non-local assembly configurations. Distribution runs through authorized Brazilian systems integrators holding Anatel telecommunications certification, with direct OEM relationships reserved for hyperscale volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ANPD enforcement actions create a barrier-to-entry moat for players holding certified LGPD attestations. The regulation's encryption and access logging mandates extend procurement cycles, freezing out undercapitalized competitors.
For Market Incumbents: Deepen backward integration into power and connectivity infrastructure to control operational cost bases across São Paulo and Rio de Janeiro campuses. Expand certified capacity in secondary cities where land and energy cost advantages stretch depreciation schedules against emerging colocation competitors. Prioritize firmware differentiation over raw capacity metrics as computational storage architectures compress hardware refresh cycles.
For New Entrants and Emerging Players: Cloud marketplace routes through AWS, Azure, and Google Cloud partner programs offer lowest-friction customer acquisition for consumption-based storage services. Target healthcare imaging archives in Minas Gerais and Rio de Janeiro where DICOM-compliant retention requirements outstrip existing supplier capacity. Position around ANPD certification acceleration services that compress 4-6 month procurement timelines for BFSI clients.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of vertically integrated campus developers with certified LGPD compliance and São Paulo state tax incentive zone positioning. Long-term viability hinges on secondary city expansion capabilities and interconnection density to Miami and Buenos Aires. Monitor ANPD secondary regulation timing on cross-border data flows as the critical inflection signal redirecting domestic versus regional hub investment.
| Strategic Initiative | Industry Significance |
|---|---|
| LGPD Certification Acceleration | Compresses 4-6 month procurement cycles for BFSI clients facing ANPD enforcement deadlines. |
| Secondary City Campus Expansion | Captures 30-40 percent land and energy cost advantages in Campinas and Curitiba versus São Paulo metro premiums. |
| NVMe-over-Fabric Deployment | Achieves sub-10-millisecond latency for tier-one financial workloads mandated by Banco do Brasil circulars. |
| Computational Storage Integration | Collapses rack space requirements in São Paulo financial corridors through embedded encryption and compression pipelines. |
| Interconnection Density Buildout | Enables low-latency links to Miami and Buenos Aires for multinational enterprise requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center infrastructure executives, ANPD compliance officers, BFSI procurement leads, and cloud platform engineers combined with ANPD enforcement action records, Banco do Brasil circulars, Anatel certification databases, and hyperscaler capex disclosures. Bottom-up storage capacity deployment estimates triangulated against top-down market value reconstructions.
Granularity-level modeling segmented the market by technology generation, service model, end-user vertical, and deployment architecture across the analysis window. Technology splits captured SSD, HDD, hybrid, and tape storage configurations. Service models distinguished managed services, cloud storage, backup solutions, and disaster recovery. End-user verticals tracked telecommunications, BFSI, healthcare, and e-commerce. Deployment architectures separated on-premises, off-premises, hybrid, and colocation. CAGRs derived from installed base evolution and unit economics trajectories, with NVMe adoption curves and LGPD compliance investment cycles as industry-specific forecast inputs.
The model holds under steady ANPD enforcement intensity and continued ICMS tax incentive program stability; deviation in central bank circular timing or federal tax policy would shift capacity expansion trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Media and Entertainment Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Storage Software Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Cloud Block Storage Market