
 Global Personal Cloud Storage Market | 2026-2036
Global Personal Cloud Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Cloud Storage Market Foresight
Asset-light subscription financing is narrowing the capital barrier for mid-tier entrants in personal cloud storage. Microsoft leverages its enterprise software ecosystem to sustain cross-sell momentum into consumer tiers. Google anchors its position through tight integration with mobile operating systems and productivity suites. Apple differentiates via hardware-software bundling that controls churn across its installed base.
Personal cloud storage denotes networked data repositories enabling individuals to upload, synchronize, and retrieve files across devices via internet protocols, typically employing object storage architectures with erasure coding for redundancy and AES-256 encryption for data protection. The public cloud deployment model dominates volume due to zero infrastructure requirements for users, while hybrid configurations capture margin pools from privacy-sensitive freelancers and remote workers seeking local encryption with remote backup. Pricing tiers stratify sharply: freemium layers drive acquisition, premium subscriptions extract value from power users, and pay-as-you-go models serve episodic demand from content creators managing large media libraries.
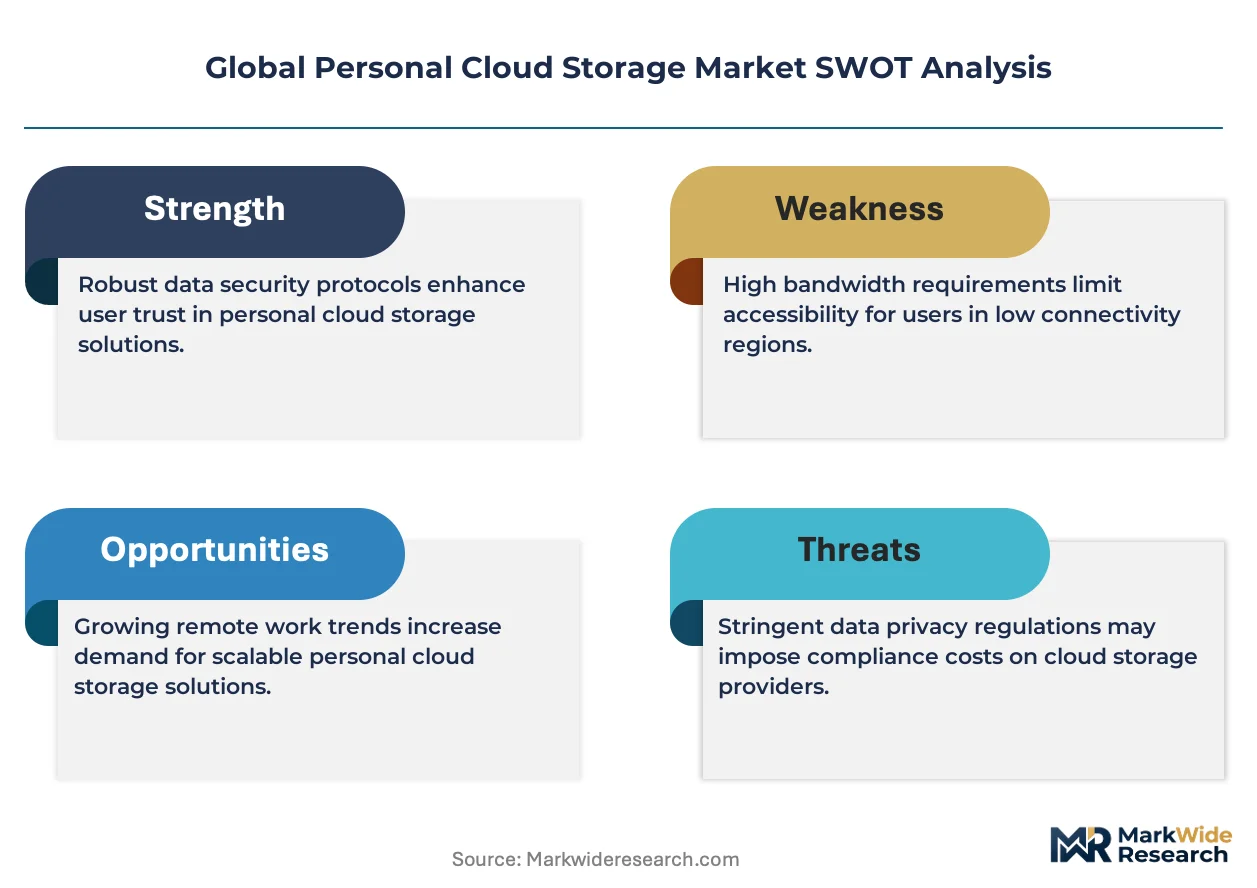
GDPR in Europe, the EU AI Act's data governance provisions, and state-level privacy statutes in the United States are reshaping where providers locate infrastructure and how they architect consent management. Japan's METI guidelines on cloud data handling and China's GB standards for cross-border data transfer add compliance complexity for multinational operators. Stakeholders must monitor divergence between regional data localization mandates and the operational economics of centralized infrastructure.
Market Dynamics
Freelancer adoption of hybrid storage architectures is compressing margins for pure-play public cloud providers while forcing infrastructure localization to satisfy data sovereignty mandates across multiple jurisdictions.
Growth Catalysts
- GDPR Article 44 Cross-Border Transfer Rules:European freelancers are migrating toward EU-located servers, creating demand for regional data center capacity and local encryption key management.
- Content Creator Vertical:Video production workflows now require multi-terabyte synchronization, pulling power users toward premium subscription tiers with expanded object storage quotas.
- Erasure Coding Redundancy:Distributed storage architectures reduce per-gigabyte infrastructure costs, enabling freemium models that accelerate user acquisition in price-sensitive segments.
Market Restraints
- Electricity Cost Volatility:Data center cooling and compute power consumption expose providers to regional energy price spikes, particularly in Germany and Japan where grid stress intensifies.
- Concentrated Hyperscaler Dominance:Three operators control the majority of object storage infrastructure, limiting price competition and creating single-point-of-failure risks for downstream resellers.
- AES-256 Encryption Overhead:Client-side encryption protocols increase latency for real-time synchronization, degrading user experience in markets with limited bandwidth infrastructure.
Strategic Opportunities
- India's Data Protection Bill Compliance Gap:Local providers can capture SME and freelancer segments before multinational entrants complete infrastructure localization.
- Edge-Cloud Convergence:Integration of 5G mobile edge computing with central repositories enables low-latency media editing for remote video production teams.
- Japan METI Cloud Security Guidelines:Certification alignment creates preferential procurement status for financial services freelancers handling client documentation.
Industry Challenges
- Zero-Knowledge Architecture Talent Scarcity:Cryptographic engineering expertise for client-side key management remains concentrated in Silicon Valley and Tel Aviv hiring markets.
- Multi-Jurisdiction Consent Orchestration:Simultaneous compliance with GDPR, state-level US privacy statutes, and China's GB standards requires redundant legal engineering functions.
Report Scope
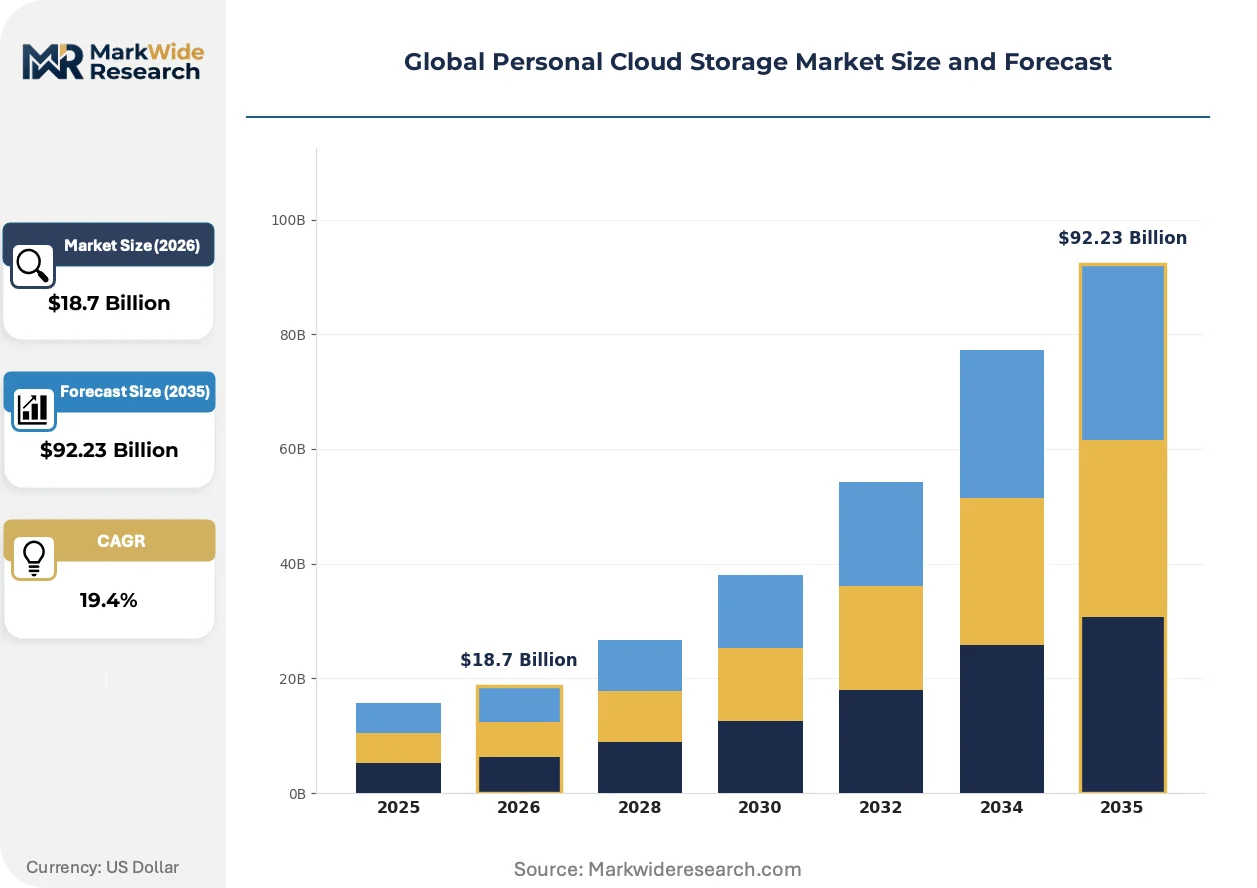
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Cloud Storage Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Storage Capacity: Under 100 GB, 100 GB to 1 TB, 1 TB to 5 TB, Above 5 TB End User: Individual Consumers, Freelancers, Content Creators, Students, Remote Workers Pricing Tier: Freemium, Basic, Premium, Enterprise, Pay-as-you-go |
| Companies Covered | Dropbox, Alibaba Cloud, Microsoft, Huawei Technologies, Tencent Cloud, Google, Apple, IBM, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Cloud Storage Market Shifts & Advancements
Decentralized storage protocols and sovereign cloud architectures are fragmenting what was a centralized public cloud monopoly, creating new competitive axes around data residency and cryptographic control.
Object storage with client-side encryption and distributed erasure coding is rendering obsolete traditional at-rest encryption models that exposed keys to provider infrastructure. Privacy-sensitive freelancers in Germany and legal services verticals are adopting these architectures fastest, migrating away from centralized key management. The shift is compressing margins for providers unable to offer zero-knowledge guarantees while rewarding specialized infrastructure operators.
The EU AI Act's data governance provisions now classify training data provenance as a high-risk activity, forcing personal cloud providers to implement automated data lineage tracking. Cloud operators must document whether user-stored content feeds foundation model training, creating compliance engineering costs that favor larger platforms. Freelancers in creative industries are responding by selecting certified non-training repositories, segmenting the market by AI-data policy.
Subscription fatigue among remote workers is shortening evaluation cycles and increasing churn sensitivity to pricing transparency. Annual billing commitments are losing ground to monthly flexibility with clear downgrade paths, particularly among episodic content creators. This pattern concentrates in the United States where credit-card subscription density has peaked and cancellation friction generates reputational damage on social platforms.
Global Personal Cloud Storage Market Segmentation
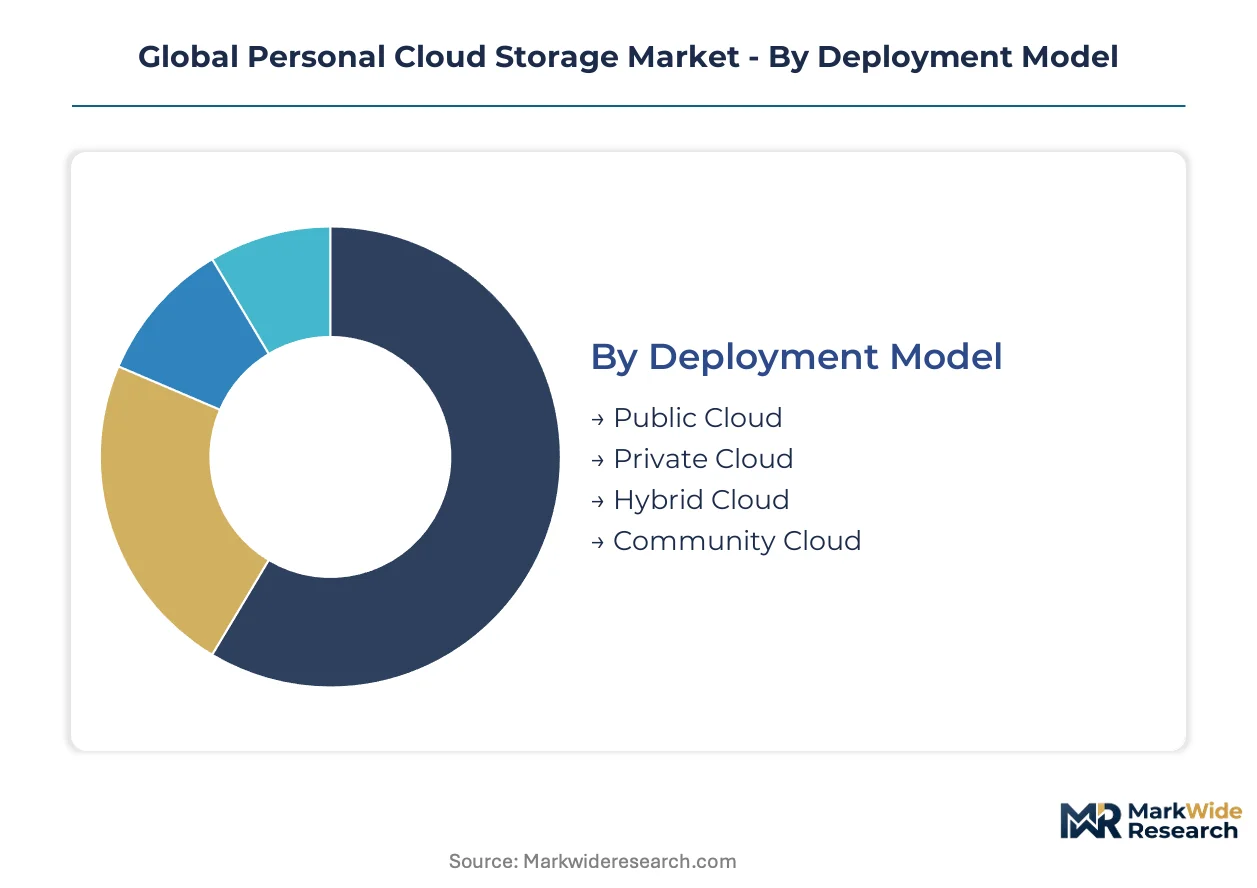
Personal cloud storage segmentation reveals how infrastructure choices, capacity needs, and user economics fragment the competitive landscape. Providers must align deployment architectures and pricing mechanics with distinct technical requirements across freelancer workflows and consumer behaviors.
Deployment Model:
After-sales service intensity varies sharply across deployment architectures, with hybrid and private configurations demanding sustained technical support for encryption key management and cross-border compliance.
- Public Cloud:Zero-infrastructure object storage with provider-managed AES-256 encryption and automated erasure coding. Demand concentrates among price-sensitive students and casual consumers in India and Brazil where bandwidth costs dominate vendor selection.
- Hybrid Cloud:Local encryption appliances paired with remote backup repositories enabling data sovereignty compliance. Freelancers in Germany and Japan drive adoption as GDPR and METI guidelines force jurisdictional control over client files.
- Private Cloud:Dedicated infrastructure with single-tenant isolation for legal and financial services freelancers handling sensitive documentation.
- Community Cloud:Shared infrastructure among affiliated organizations with common compliance requirements, serving university researcher cohorts and creative collective memberships.
By volume, Public Cloud leads. By growth pace, Hybrid Cloud is ahead.
Storage Capacity:
Capacity tiers map directly to monetization depth, with upper thresholds determining whether users convert to premium subscriptions or remain within freemium constraints.
- Under 100 GB:Entry-tier object storage for document synchronization and mobile photo backup. Students and casual consumers in Southeast Asian markets cluster here, constrained by smartphone storage economics and metered data plans.
- 100 GB to 1 TB:Standard tier supporting high-resolution photography libraries and professional document archives. Remote workers across Spain and Italy represent the core demographic, balancing cost against collaboration requirements.
- 1 TB to 5 TB:Power-user tier for 4K video project repositories and RAW image workflows. Content creators in Los Angeles and London drive demand, pulled by multi-device editing synchronization and client delivery requirements.
- Above 5 TB:Enterprise-grade object storage with custom erasure coding configurations for production studios and independent filmmakers managing feature-length deliverables.
By user count, Under 100 GB dominates. By revenue per account, Above 5 TB generates the highest returns.
End User:
User type segmentation determines feature prioritization, with professional segments demanding API access and version control while consumer segments prioritize frictionless mobile interfaces.
- Individual Consumers:Personal photo and document archiving with family sharing permissions. Retention challenges intensify as subscription fatigue peaks in United States credit-card markets with high cancellation velocity.
- Freelancers:Client file management with audit trails and jurisdiction-selective storage for contract compliance. German legal and Japanese financial services verticals show steepest expansion trajectory as data localization mandates tighten.
- Content Creators:Multi-terabyte media libraries with frame-accurate preview and proxy generation for remote collaboration pipelines.
- Students:Collaborative document editing with institutional licensing discounts and plagiarism-checking integrations.
- Remote Workers:Enterprise-secured personal partitions with single sign-on and centralized IT policy enforcement.
Freelancers and Content Creators together command premium pricing power, while Individual Consumers anchor volume scale.
Pricing Tier:
Pricing architecture separates acquisition mechanics from retention economics, with tier boundaries calibrated to storage thresholds that trigger upgrade decisions.
- Freemium:Capacity-limited entry tier with referral-based expansion bonuses and advertising-supported bandwidth. Serves as the primary funnel for emerging market user acquisition in Nigeria and Indonesia.
- Basic:Annual subscription with modest storage expansion and priority support queue positioning. Captures cost-conscious remote workers seeking reliability without collaboration features.
- Premium:Expanded quotas with client-side encryption options and advanced sharing controls. Freelancers in France and Netherlands migrate here as CNIL guidance tightens on provider-accessible keys.
- Enterprise:Custom contracts with SLA guarantees, dedicated support channels, and compliance certification documentation for regulated industry freelancers.
- Pay-as-you-go:Episodic billing for burst capacity during production cycles, favored by event videographers and seasonal content creators managing irregular project volumes.
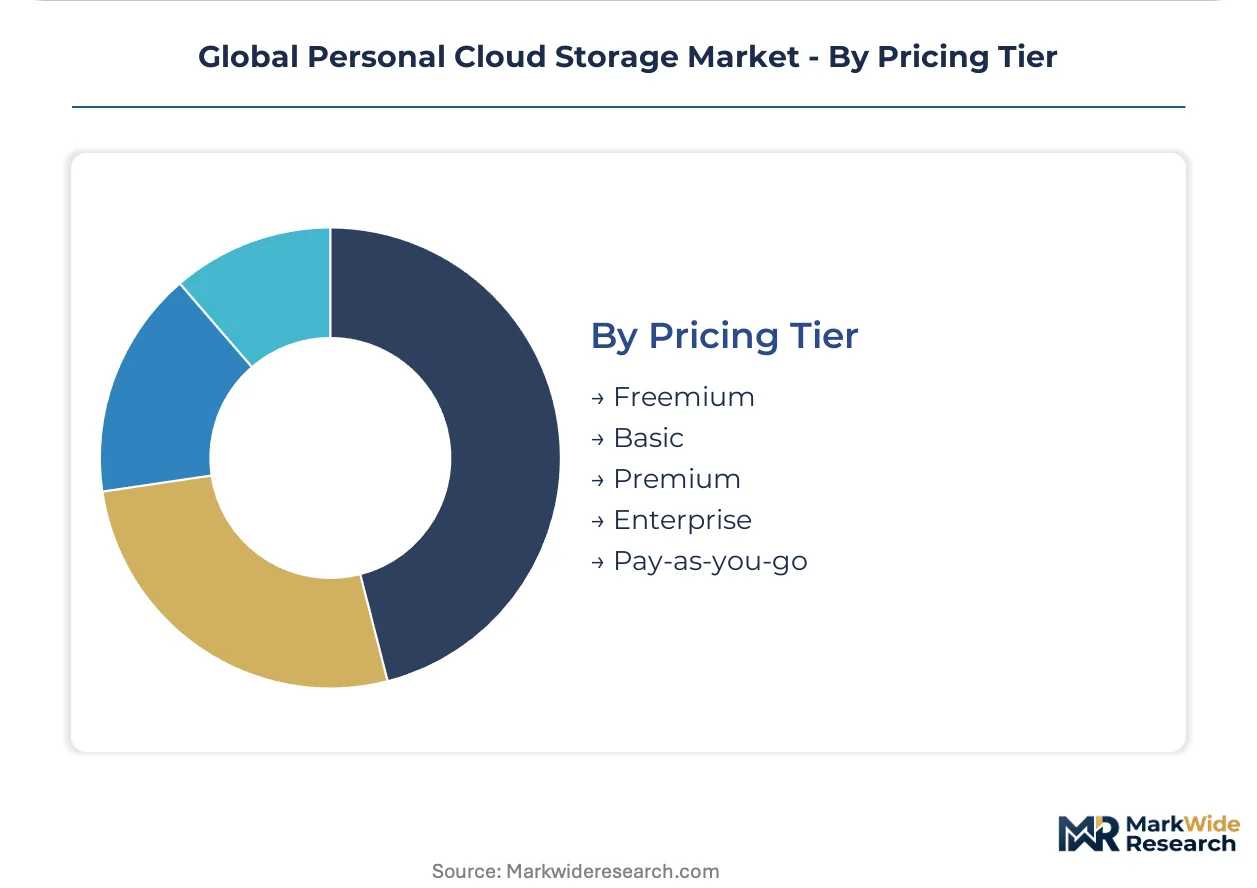
Freemium and Basic tiers combined represent the largest installed base, though Premium and Enterprise tiers generate disproportionate profit contribution per account.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in cloud services, exporting infrastructure and software to European and Asian markets while importing localized data center hardware from Taiwan and South Korea. Germany and Japan maintain near-balanced positions, exporting compliance-engineered storage architectures while importing hyperscaler capacity from US-based operators.
United States
Remote work infrastructure and content creation economies in Los Angeles and New York drive premium-tier subscriptions. The FTC and state-level privacy statutes in California and Virginia reshape consent management architectures. Seattle and San Francisco Bay Area clusters concentrate engineering talent for zero-knowledge encryption development.
Germany
GDPR Article 44 cross-border transfer rules compel freelancers toward EU-located servers with local encryption key management. The BSI and CNIL guidance tighten requirements on provider-accessible keys. Berlin and Munich host the densest concentrations of legal services freelancers adopting hybrid storage for client file compliance.
Japan
METI guidelines on cloud data handling create preferential procurement status for certified providers serving financial services freelancers. The Personal Information Protection Commission enforces strict data handling protocols. Tokyo and Osaka clusters lead adoption of edge-cloud convergence for low-latency media workflows.
India
The Data Protection Bill compliance gap allows local providers to capture SME and freelancer segments before multinational entrants complete infrastructure localization. MeitY and RBI guidelines shape data localization requirements. Bengaluru and Hyderabad clusters concentrate domestic cloud engineering and data center construction.
United Kingdom
Post-Brexit divergence from EU data adequacy decisions forces UK freelancers to maintain dual-compliance architectures. The Information Commissioner's Office and UK GDPR provisions create overlapping regulatory obligations. London's creative industries drive demand for multi-terabyte synchronization in video production verticals.
Global Personal Cloud Storage Market Competitive Landscape
On the supply side, the industry is consolidating around three hyperscalers controlling object storage infrastructure while specialized operators fragment across compliance-sensitive niches. Tier-one players leverage enterprise software ecosystems for cross-sell momentum into consumer tiers. Mid-tier entrants compete through asset-light subscription financing and regional data sovereignty positioning. Dominant competitive moves include strategic partnerships for edge-cloud convergence and portfolio diversification into zero-knowledge architectures.
Within the hyperscaler tier, Microsoft and Google exemplify divergent ecosystem strategies, while Dropbox occupies a position representing the pure-play consumer synchronization archetype. Microsoft leverages its productivity suite integration for retention, Google anchors through mobile operating system tie-ins, and Dropbox exemplifies the freemium acquisition model targeting price-sensitive segments. These three represent the competitive axes—enterprise cross-sell, platform integration, and standalone specialization—that structure vendor positioning across deployment models.
| Leading Market Players |
|---|
| Dropbox |
| Alibaba Cloud |
| Microsoft |
| Huawei Technologies |
| Tencent Cloud |
| Apple |
| IBM |
| Amazon Web Services |
| Others |
Supply & Pricing Matrix
Single-source dependency on Taiwan-manufactured NAND flash memory determines both tier spreads in storage pricing and the geographic shape of infrastructure deployment. Cloud providers pass through silicon cost volatility into premium subscription markups while sourcing erasure coding appliances from South Korean and Chinese assembly networks.
Pricing Analysis
Content creators and video production freelancers anchor subscription pricing across three capacity tiers. Pricing stratifies across premium zero-knowledge tiers, standard encrypted object storage, and economy freemium layers differentiated by API access and client-side key control. Cost compression in the standard tier is intensifying because hyperscaler volume discounts squeeze mid-market providers. Students and casual consumers in Southeast Asian markets exhibit highest price sensitivity, while German legal services freelancers show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for encryption hardware and data center cooling components. Infrastructure assembly concentrates in Taiwan, South Korea, and Malaysia for server-grade storage arrays. Raw material dependencies span rare earth elements for magnetic drives, high-purity silicon for NAND fabrication, and liquid cooling fluids for thermal management. Single-source vulnerability persists in advanced lithography equipment. Distribution runs through hyperscaler direct procurement channels and regional value-added resellers serving compliance-sensitive freelancers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-knowledge architecture adoption represents a high-growth disruption as GDPR Article 44 and Japan METI guidelines force cryptographic control into procurement specifications.
For Market Incumbents: Build ecosystem lock-in moats through productivity suite integration and mobile operating system tie-ins. Defend against specialized zero-knowledge entrants by certifying EU-located infrastructure for data sovereignty compliance. Invest in client-side encryption R&D to preserve margin in the freelancer segment. For New Entrants and Emerging Players: Build out regional data center capacity in India before the Data Protection Bill compliance window closes. Target SME freelancers in Bengaluru and Hyderabad with localized encryption key management. Pursue METI certification as a go-to-market differentiator for financial services verticals. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized infrastructure operators with jurisdictional compliance capabilities. Long-term viability hinges on geographic diversification of server footprints and cryptographic engineering talent acquisition. Watch for divergence between EU AI Act data governance enforcement and hyperscaler training data policies as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Architecture Certification | CNIL and BSI guidance on provider-accessible keys creates procurement preference for certified platforms. |
| EU Data Center Localization | GDPR Article 44 cross-border transfer rules force infrastructure investment in Frankfurt and Amsterdam clusters. |
| Edge-Cloud Convergence Partnership | 5G mobile edge computing integration enables low-latency workflows for Tokyo and Osaka video production teams. |
| Freelancer Vertical API Development | Audit trail and jurisdiction-selective storage features capture German legal services procurement budgets. |
| Pay-as-You-Go Billing Infrastructure | Episodic billing mechanics reduce churn among Los Angeles event videographers with irregular project volumes. |
Research Methodology
A spread of perspectives from cloud infrastructure architects, data protection officers, freelance platform operators, and hyperscaler procurement leads converged on the working assumptions. Primary interviews with CTOs at mid-tier storage providers and compliance consultants in Berlin and Tokyo were cross-checked against secondary sources including SEC capex disclosures, EU regulatory filings, and hyperscaler data center expansion announcements. Bottom-up capacity modeling and top-down demand segmentation were triangulated to validate volume estimates.
Demand-supply balance across deployment models, capacity tiers, and end-user segments structured the analytical framework throughout the projection horizon. Modeled dimensions included public-hybrid-private deployment architectures, storage capacity thresholds, and freelancer versus consumer adoption patterns. CAGRs were derived from installed base growth rates and premium tier conversion assumptions. Forecast inputs incorporated electricity cost trajectories in Germany and Japan alongside bandwidth infrastructure buildout timelines in India.
Stress conditions across energy price volatility, regulatory enforcement divergence, and NAND flash supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about data sovereignty mandate adoption curves and zero-knowledge architecture penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market