
 Cloud Storage Gateways Market | 2026-2036
Cloud Storage Gateways Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Storage Gateways Market Analysis
Market Context
The capital-intensity divergence between hyperscale infrastructure operators and specialized gateway vendors is unwinding competitive dynamics across the sector. Amazon Web Services leverages its cloud-native integration stack to dominate enterprise deployments, while NetApp sustains hardware-software hybrid relevance through on-premises appliance partnerships. CTERA Networks specializes in edge-to-cloud file services for distributed workforces, occupying a niche between commodity storage and full cloud migration.
Technical Definition and Segments
Cloud storage gateways are network appliances or software instances that translate between standard on-premises storage protocols such as NFS, SMB, or iSCSI and cloud object storage APIs, enabling seamless tiering of data to public or private cloud backends without application modification. Hybrid deployment configurations command the largest revenue share as enterprises retain hot data locally while archiving cold tiers to AWS or Azure. Object storage technology underpins the fastest expansion within the technology dimension, displacing traditional NAS filers in analytics and backup workloads. Disaster recovery services generate premium margins compared to basic data backup offerings, reflecting the operational criticality of near-zero recovery point objectives.
Regulatory Outlook
FCC guidelines on data transmission security and NIST SP 800-53 controls shape federal procurement specifications for gateway encryption and access logging in United States deployments. HIPAA mandates for healthcare entities and SEC recordkeeping rules for financial firms directly determine retention architecture and audit trail capabilities vendors must embed. Stakeholders should monitor evolving state-level privacy statutes and cross-border data flow restrictions that could fragment gateway deployment standards across jurisdictions.
Market Dynamics
Hybrid cloud data gravity is forcing enterprises to rearchitect storage tiering strategies, as latency-sensitive workloads resist full public cloud migration while compliance mandates demand local data residency for regulated datasets.
Growth Catalysts
- NIST SP 800-53 encryption mandates:Federal agencies in the United States must deploy FIPS 140-2 validated gateway appliances, creating standardized procurement pipelines that accelerate vendor certification investments.
- Healthcare data fragmentation:Hospital systems managing petabyte-scale imaging archives require seamless tiering between on-premises PACS storage and cloud object repositories without reconfiguring radiology workstations.
- Industrial IoT sensor proliferation:Manufacturing facilities in Germany generate continuous telemetry streams that exceed local NAS capacity, necessitating edge gateways that buffer and compress data before cloud transmission.
Market Restraints
- Bandwidth cost volatility:Egress fees from hyperscale cloud providers consume 15-30% of total gateway ownership costs, making multi-cloud strategies financially punitive for data-intensive workloads.
- Appliance supply concentration:Specialized hardware components for high-throughput encryption engines source predominantly from Taiwanese semiconductor fabricators, exposing deployment timelines to geopolitical trade friction.
- Protocol translation limitations:Legacy mainframe storage environments using IBM z/OS datasets lack native object API mapping, forcing expensive custom gateway development for financial services retention compliance.
Strategic Opportunities
- Edge computing convergence:Kubernetes-native gateway containers deployed on factory-floor servers enable real-time analytics preprocessing before cloud archival, reducing transmission volumes.
- India data localization mandates:RBI guidelines requiring financial transaction records remain within national borders create demand for domestic cloud gateway deployments that federate with global cloud control planes.
- EU CSRD sustainability reporting:Corporate disclosure requirements for IT carbon footprints incentivize gateway solutions that optimize storage tiering for energy efficiency metrics alongside cost.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Enterprise IT teams lack personnel fluent in AWS, Azure, and Google Cloud API variations simultaneously, complicating unified gateway policy management.
- Legacy NAS integration complexity:Decades-old Windows file server environments with complex ACL inheritance structures resist clean migration to cloud identity models without permission reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Storage Gateways Market |
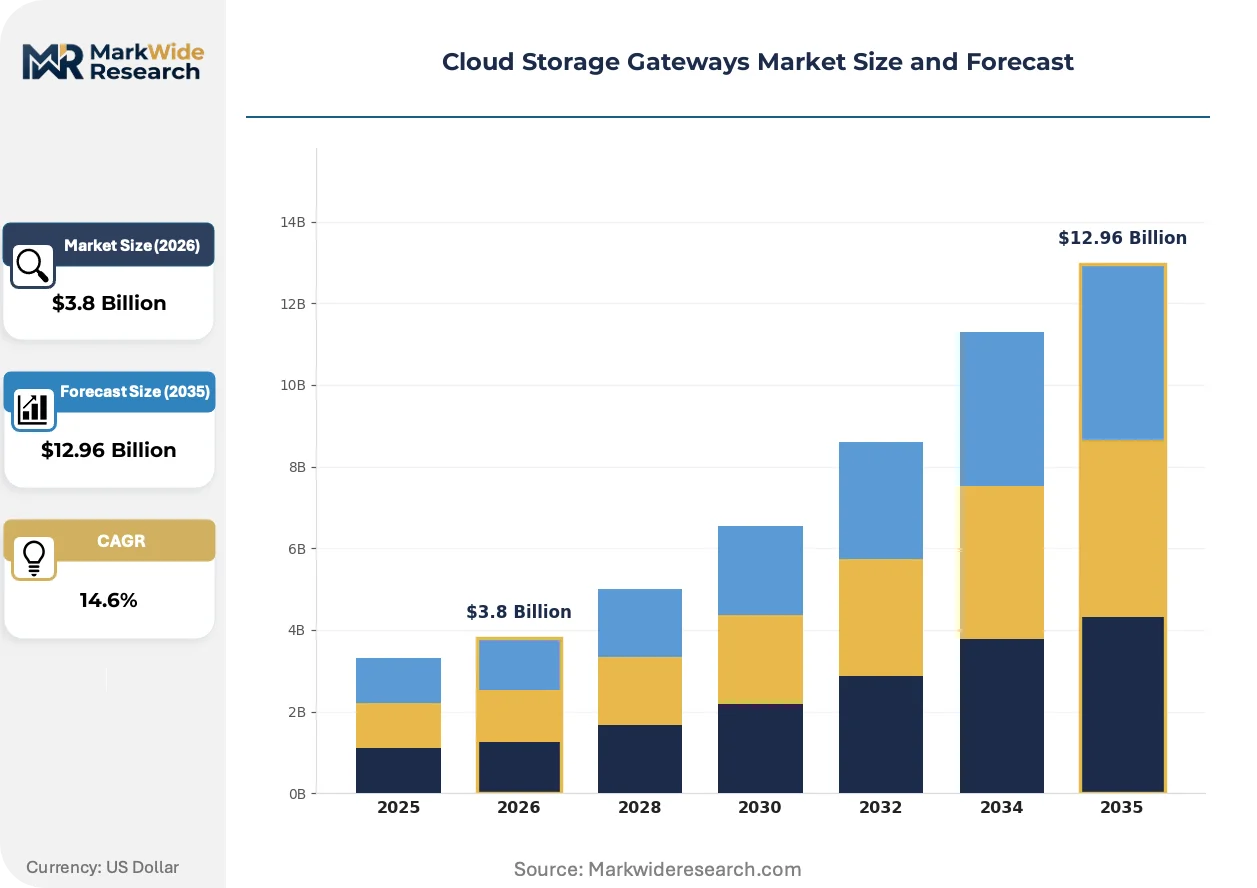
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Hybrid, Multi-Cloud, Private Cloud End User: Large Enterprises, SMEs, Government, Educational Institutions Service Type: Managed Services, Professional Services, Data Backup, Disaster Recovery Technology: NAS, SAN, Object Storage, File Storage |
| Companies Covered | Amazon Web Services, Microsoft Corporation, CTERA Networks, NetApp, Nasuni Corporation, Riverbed Technology, Dell EMC, Google LLC, Panzura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Storage Gateways Market Emerging Trajectories
Software-defined storage controllers are supplanting purpose-built hardware appliances, collapsing the distinction between gateway functionality and hyperconverged infrastructure management planes.
Immutable object storage with WORM (Write Once Read Many) capabilities is displacing tape-based long-term archival in financial services and healthcare compliance frameworks. Regional banks in the United States are adopting S3 Object Lock configurations to satisfy SEC 17a-4 recordkeeping requirements without maintaining physical tape libraries. This shift compresses recovery time objectives from days to minutes while eliminating media degradation risks.
GDPR Article 44 cross-border transfer mechanisms are compelling European enterprises to deploy gateway appliances with data residency enforcement at the packet-inspection layer. German automotive manufacturers now require gateways that block automatic cloud tiering if geolocation tagging detects potential third-country transfer. Vendors are embedding legal hold workflows directly into storage policy engines to preempt regulatory exposure.
Consumption-based financing models for gateway infrastructure are disrupting traditional capital expenditure procurement cycles in midmarket enterprises. Managed service providers in the United Kingdom bundle appliance hardware, cloud egress, and support into per-terabyte monthly subscriptions. This unbundles vendor relationships from long-term depreciation schedules and accelerates refresh cycles for encryption-hardened hardware generations.
Cloud Storage Gateways Market Segmentation
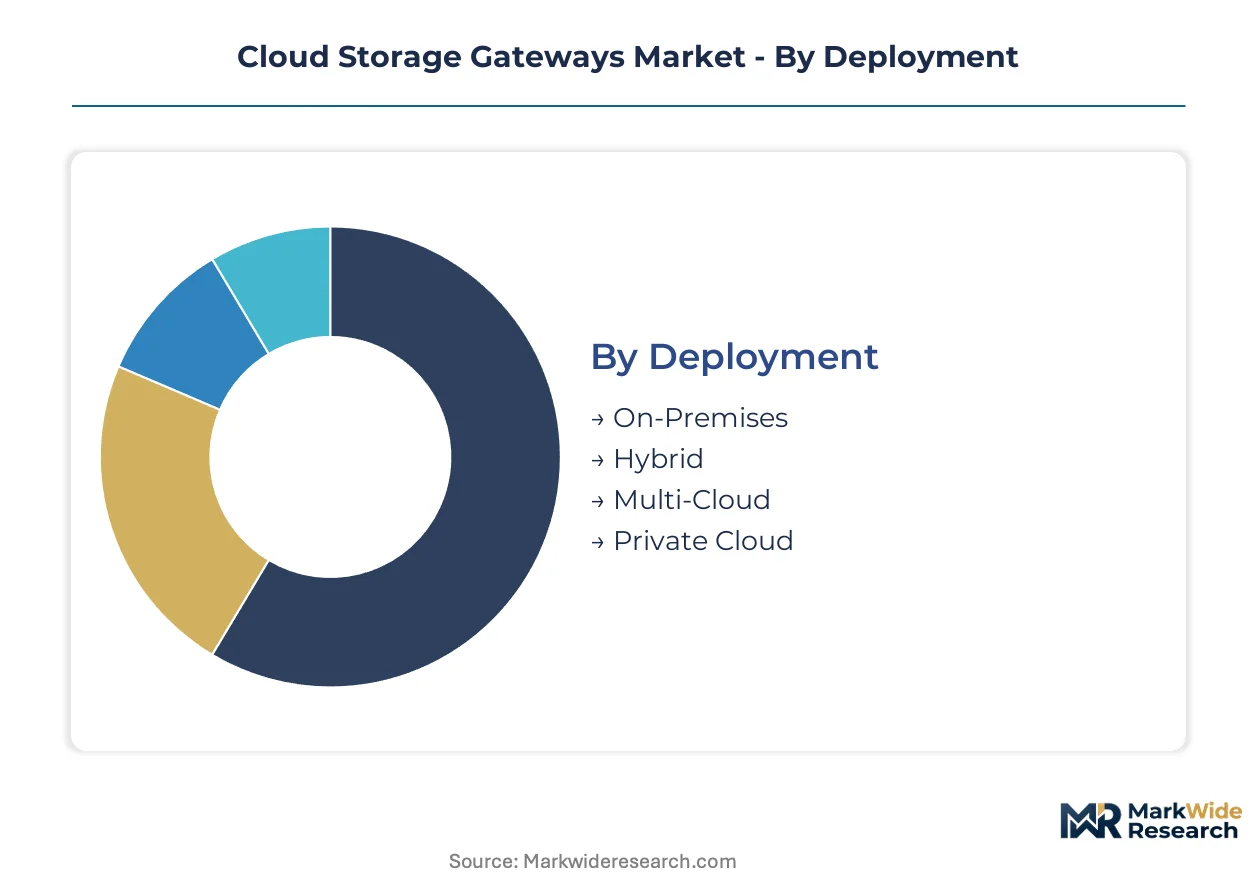
Cloud storage gateway architectures diverge sharply across deployment models and operational scale, with procurement patterns split between domestic data sovereignty mandates and export-oriented hybrid configurations. Understanding segment boundaries clarifies where vendor specialization yields pricing power versus commodity competition.
Deployment:
Domestic regulatory compliance favors on-premises and private cloud configurations, while export-led demand concentrates in multi-cloud and hybrid tiers serving distributed multinational operations.
- On-Premises:Physical appliances residing entirely within enterprise data centers process sensitive workloads under direct administrative control. German automotive manufacturers and United States defense contractors deploy these configurations to satisfy data residency requirements without external network exposure.
- Hybrid:Split architectures retain hot data on local storage while tiering cold archives to AWS or Azure. Healthcare systems in the United States managing petabyte-scale imaging archives rely on this model to balance radiologist workstation latency against cloud economics.
- Multi-Cloud:Gateways federating across two or more hyperscale providers reduce vendor lock-in for data-intensive enterprises. Financial services firms in Singapore and Switzerland use these configurations to arbitrage egress pricing and satisfy divergent regulatory jurisdictions.
- Private Cloud:Dedicated gateway instances running on sovereign cloud infrastructure serve government and regulated industries. India's banking sector deploys these under RBI data localization mandates requiring transaction records remain within national borders.
Hybrid configurations command the established base. The steepest expansion runs through multi-cloud deployments.
End User:
Cost tiering separates capital-rich institutional buyers from price-sensitive midmarket adopters, with procurement sophistication varying across public and private sector procurement channels.
- Large Enterprises:Global 2000 organizations operate dedicated gateway infrastructure with in-house DevOps teams managing policy orchestration. These buyers negotiate enterprise licensing agreements spanning three-to-five year horizons with embedded hardware refresh clauses.
- SMEs:Midmarket firms consume gateway functionality through managed service providers rather than direct appliance procurement. United Kingdom and Australian markets show particular concentration here, where per-terabyte subscription models displace capital expenditure cycles.
- Government:Federal agencies require FIPS 140-2 validated encryption and NIST SP 800-53 compliant access logging. United States and Canadian procurement specifications explicitly exclude non-validated vendors from contract eligibility.
- Educational Institutions:Universities and research consortia leverage gateway tiering for grant-funded dataset archival with unpredictable access patterns. European Research Council-funded projects in Germany and France represent significant demand concentration.
Large enterprises anchor revenue concentration. SMEs are climbing the fastest as consumption-based financing democratizes access.
Service Type:
Margin structure stratifies sharply between operational continuity services commanding premium pricing and commoditized data protection offerings.
- Managed Services:Third-party providers assume full operational responsibility for gateway infrastructure including patching, capacity planning, and incident response. These engagements typically span multi-year terms with SLA-backed availability guarantees.
- Professional Services:Implementation and migration consulting addresses legacy NAS integration complexity. Demand concentrates in financial services modernizing decades-old IBM z/OS environments for cloud object compatibility.
- Data Backup:Scheduled replication to cloud object storage represents the most mature and price-compressed service tier. Manufacturing facilities in Germany use these for IoT telemetry archival exceeding local NAS capacity.
- Disaster Recovery:Near-zero recovery point objectives with automated failover orchestration generate 40-60% margin premiums over basic backup. United States regional banks adopting S3 Object Lock configurations for SEC 17a-4 compliance drive specialized demand.
Data backup commands the established base. Disaster recovery is gaining share fastest on operational criticality premiums.
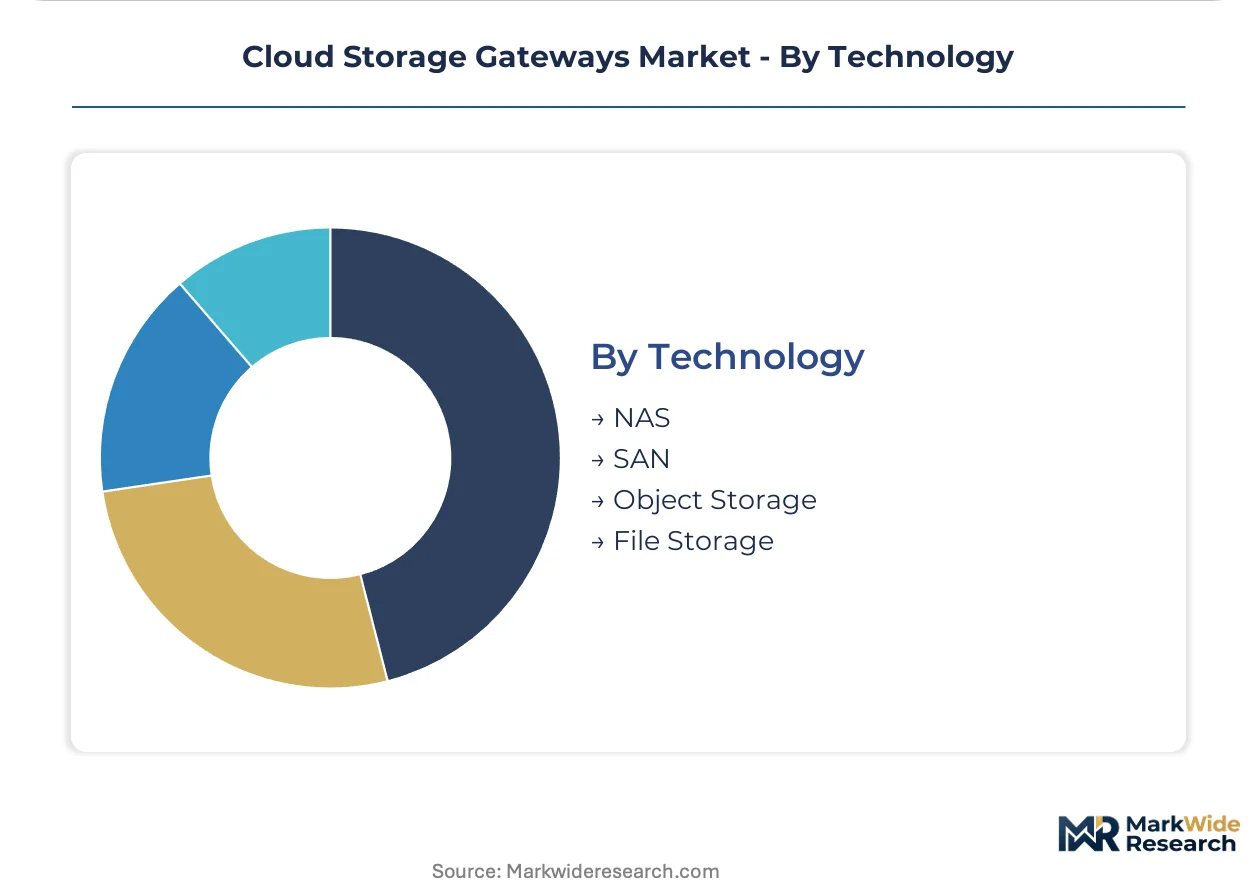
Technology:
Storage protocol maturity creates divergent growth trajectories, with legacy file systems yielding to object-native architectures in analytics and AI/ML workloads.
- NAS:Network-attached storage gateways translate NFS and SMB protocols to cloud APIs without application modification. Windows file server environments with complex ACL inheritance structures remain dependent on this technology.
- SAN:Block-level iSCSI and Fibre Channel gateways serve database and virtualization workloads requiring raw device mapping. Financial transaction processing systems in Singapore and Tokyo maintain SAN dependency for latency-sensitive operations.
- Object Storage:Native S3-compatible APIs displace traditional filers in backup, analytics, and long-term archival. Immutable WORM configurations satisfy healthcare HIPAA mandates and SEC recordkeeping rules without physical tape infrastructure.
- File Storage:Cloud-native parallel file systems serve high-performance computing and media rendering workflows. Research institutions in Switzerland and the Netherlands deploy these for genomics and climate simulation datasets.
NAS retains the established base. Object storage is expanding most quickly on analytics and compliance workload migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand composition varies sharply across geographies. United States healthcare systems prioritize hybrid architectures for HIPAA-compliant imaging archives. German industrial manufacturers emphasize local data residency alongside cloud scalability. Financial hubs in Singapore and Switzerland arbitrage multi-cloud configurations to satisfy divergent regulatory jurisdictions.
United States
Federal agencies drive FIPS 140-2 validated gateway procurement under NIST SP 800-53 encryption mandates. Healthcare providers manage petabyte-scale PACS storage tiering between on-premises systems and cloud object repositories. Regional banks in the Southeast adopt S3 Object Lock configurations to satisfy SEC 17a-4 recordkeeping requirements without physical tape infrastructure.
Germany
Automotive manufacturers generate continuous IoT telemetry streams exceeding local NAS capacity, necessitating edge gateways with packet-level geolocation enforcement. GDPR Article 44 cross-border transfer mechanisms compel data residency controls at the inspection layer. Industrial clusters in Bavaria and Baden-Württemberg deploy appliances that block automatic cloud tiering if third-country transfer is detected.
India
RBI data localization guidelines require financial transaction records remain within national borders, creating demand for domestic gateway deployments. Banking sector procurement favors private cloud configurations that federate with global control planes. Mumbai and Bangalore technology corridors concentrate managed service provider activity for midmarket subscription models.
Singapore
Financial services firms arbitrage egress pricing across AWS, Azure, and Google Cloud through multi-cloud gateway configurations. Monetary Authority of Singapore cybersecurity guidelines shape encryption and access logging specifications. The city-state's wealth management sector drives premium disaster recovery deployments with near-zero recovery point objectives.
Switzerland
Private banking and pharmaceutical research institutions demand sovereign cloud gateway instances with audit trail capabilities exceeding standard commercial offerings. FINMA recordkeeping rules intersect with EU CSRD sustainability reporting requirements. Geneva and Basel clusters concentrate deployments optimizing storage tiering for both compliance and energy efficiency metrics.
Cloud Storage Gateways Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud operators leveraging native integration stacks against hardware-software hybrid vendors sustaining appliance relevance. The structure rewards vertical integration into encryption engines and cloud API orchestration layers. Three archetypes dominate: cloud-native platform operators, legacy storage hardware incumbents, and edge-to-cloud specialists. Competitive moves concentrate on strategic partnerships with semiconductor fabricators and geographic expansion through managed service provider channels.
Among cloud-native platform operators, Amazon Web Services and Microsoft Corporation anchor the integrated tier with cloud control plane dominance. CTERA Networks occupies a specialist position between commodity storage and full cloud migration, exemplifying the edge-to-cloud archetype for distributed workforce deployments. These three represent the competitive vectors shaping procurement standards across federal, healthcare, and industrial verticals.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| CTERA Networks |
| NetApp |
| Nasuni Corporation |
| Riverbed Technology |
| Dell EMC |
| Google LLC |
| Panzura |
| Others |
Supply Flow & Price Mechanics
FIPS 140-2 validation requirements simultaneously gate vendor qualification for United States federal procurement and stratify pricing tiers between certified and non-certified gateway appliances. This certification regime creates dual barriers: supply-side fabrication partnerships must embed validated encryption engines, while buyer budgets diverge sharply between compliance-mandated premiums and cost-optimized commercial deployments.
Pricing Analysis
Long-term enterprise licensing agreements spanning three-to-five years dominate procurement for Global 2000 organizations, while managed service providers in the United Kingdom and Australia push per-terabyte subscription models into midmarket accounts. Price differentiation hinges on FIPS 140-2 certification tier and embedded hardware refresh clauses, with uncertified commercial appliances facing cost compression from software-defined alternatives. Government and healthcare buyers exhibit lowest price sensitivity due to compliance mandates, whereas manufacturing SMEs in Germany prioritize economy-tier configurations for IoT telemetry buffering.
Supply Chain Analysis
Taiwanese semiconductor fabrication for high-throughput encryption engines creates a chokepoint exposing gateway deployment timelines to geopolitical trade friction. Specialized ASIC production draws from Taiwan, South Korea, and United States foundries, with flash memory components and network interface controllers anchoring secondary dependencies. Single-source vulnerability concentrates in advanced node fabrication for FIPS-validated security processors. Distribution runs through direct enterprise sales for large accounts and managed service provider channels for subscription-based consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-cloud API orchestration expertise scarcity constrains enterprise IT teams from unifying gateway policy management across hyperscale environments. This capability gap fragments procurement decisions and creates openings for vendors that abstract complexity through unified control planes.
For Market Incumbents: Fortify encryption hardware partnerships with Taiwanese foundries to secure FIPS 140-2 validated component supply against trade policy volatility. Deepen backward integration into cloud API abstraction layers to defend margin position against software-defined challengers collapsing appliance distinctions. For New Entrants and Emerging Players: Anchor in India's domestic banking sector under RBI data localization mandates, where private cloud gateway deployments federating with global control planes remain underpenetrated. Target midmarket manufacturing facilities in Germany through edge-to-cloud Kubernetes-native containers that preprocess IoT telemetry before cloud transmission. For Investors and Strategic Acquirers: NIST SP 800-53 revision cycles reshapes the acquisition landscape by periodically recertifying vendor eligibility for federal procurement pipelines. Long-term viability favors targets with embedded FIPS validation capabilities and managed service provider channel density. Monitor state-level privacy statute proliferation as signal for geographic fragmentation in gateway deployment standards.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Semiconductor Fabricator | Secures FIPS 140-2 validated encryption engine supply for federal procurement eligibility. |
| Acquisition of Edge-to-Cloud Specialist | Extends Kubernetes-native gateway containers into manufacturing IoT telemetry preprocessing. |
| Geographic Expansion via Managed Service Provider Channel | Accelerates per-terabyte subscription penetration in United Kingdom and Australian midmarkets. |
| Platform Integration with Hyperscaler Control Planes | Unifies multi-cloud policy orchestration for enterprises lacking AWS-Azure-Google fluency. |
| Product Launch of Immutable WORM-Enabled Object Gateway | Displaces tape infrastructure for United States regional banks under SEC 17a-4 recordkeeping rules. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC filings, and customs trade data covering encryption appliance imports. Interviews with enterprise storage architects, federal procurement officers, healthcare IT directors, and managed service provider executives informed demand-side validation. Secondary sources include NIST certification databases, RBI regulatory circulars, and German automotive supplier filings. Bottom-up unit economics triangulate against top-down addressable market sizing across deployment models and service tiers.
Segmentation dimensions modeled span on-premises, hybrid, multi-cloud, and private cloud deployments; large enterprise, SME, government, and educational end users; managed services, professional services, data backup, and disaster recovery service types; plus NAS, SAN, object storage, and file storage technologies. CAGRs derive from regression analysis of historical adoption curves against regulatory inflection timing and hyperscale infrastructure expansion rates. Forecast inputs incorporate healthcare PACS archive growth trajectories and industrial IoT sensor deployment densities.
Decision-makers should treat outputs as directional under assumptions of sustained NIST framework stability and continued hyperscale cloud egress pricing structures; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU cross-border data flow restrictions and state-level United States privacy statutes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Hard Disk Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Consumer Network Attached Storage Market